
 Myocarditis Disease Market | 2026-2036
Myocarditis Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Myocarditis Disease Market Foresight
Biologic immunosuppressants are recalibrating treatment economics away from generic corticosteroid regimens in fulminant myocarditis. Novartis AG leverages its established immunology pipeline to anchor development of targeted interleukin inhibitors for autoimmune-driven cardiac inflammation. Pfizer Inc. competes through sustained investment in mRNA therapeutic platforms applicable to viral myocarditis etiologies. Cardiol Therapeutics specializes in cannabidiol-based cardioprotective formulations, occupying a distinct niche in acute-stage management protocols.
Myocarditis denotes inflammatory infiltration of the myocardium, typically characterized by lymphocytic infiltrate, myocyte necrosis, and elevated troponin biomarkers, with primary clinical purpose of restoring cardiac contractility and preventing progression to dilated cardiomyopathy. Monoclonal antibodies represent the fastest-growing treatment type as payers expand coverage for IL-1 and IL-6 pathway inhibitors refractory to standard care. MRI-based diagnosis commands premium reimbursement due to tissue characterization sequences that distinguish acute edema from chronic fibrosis, while home care segments gain traction through remote cardiac monitoring integration.
FDA orphan drug designation and EMA PRIME eligibility shape development timelines by granting protocol assistance and fee waivers for rare cardiovascular indications. Japan's PMDA Sakigake framework accelerates domestic review of novel immunomodulators, creating parallel track opportunities for sponsors with Asian regulatory strategy. Stakeholders must monitor evolving biomarker-based diagnostic criteria that could redefine addressable patient populations and reshape trial endpoint requirements.
Market Dynamics
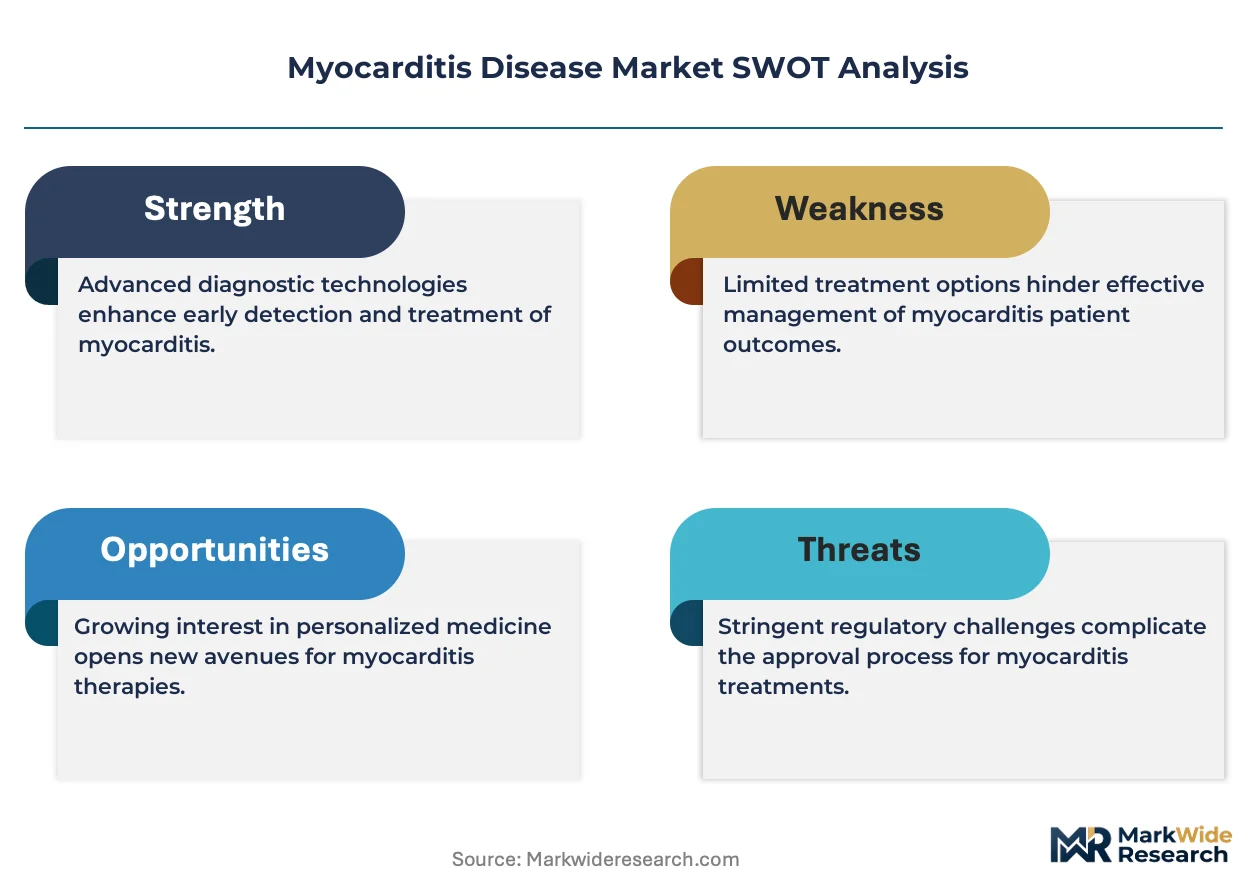
FDA orphan drug designation and EMA PRIME eligibility are compressing development timelines for rare cardiovascular therapies, redirecting capital toward targeted biologics and away from broad-spectrum immunosuppressants.
Growth Catalysts
- Accelerated regulatory pathways:FDA orphan drug designation grants protocol assistance and fee waivers for rare cardiovascular indications, shortening time-to-market for novel immunomodulators.
- Cardiac MRI infrastructure expansion:Hospital systems in the United States, Germany, and Japan are deploying tissue characterization sequences that distinguish acute edema from chronic fibrosis, enabling earlier therapeutic intervention.
- Biologics pipeline maturation:Interleukin-1 and interleukin-6 pathway inhibitors are securing expanded payer coverage for refractory cases previously managed with corticosteroid regimens alone.
Market Restraints
- Diagnostic cost concentration:Cardiac MRI protocols require substantial capital investment in magnet systems and specialized radiologist training, limiting deployment to tertiary centers.
- Biomarker validation gaps:Troponin elevation lacks specificity for myocarditis versus acute coronary syndrome, creating diagnostic uncertainty that delays targeted therapy initiation.
- Reimbursement heterogeneity:Payer coverage for IL-1 and IL-6 inhibitors varies across national health systems, fragmenting addressable patient populations.
Strategic Opportunities
- Remote cardiac monitoring integration:Home care segments are incorporating wearable ECG and implantable loop recorders to track post-acute recovery, creating subscription revenue streams.
- Japan's PMDA Sakigake framework:This accelerated review pathway for novel immunomodulators enables parallel Asian regulatory strategies for sponsors with domestic development programs.
- Cannabidiol cardioprotection protocols:Acute-stage management represents an underserved niche distinct from chronic immunosuppression, with distinct clinical endpoints and reimbursement pathways.
Industry Challenges
- Cardiac immunology specialist scarcity:Hospital systems face recruitment constraints for clinicians trained at the intersection of cardiology and rheumatology, limiting department expansion velocity.
- Trial endpoint standardization:Evolving biomarker-based diagnostic criteria threaten to redefine addressable populations mid-study, requiring adaptive protocol designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myocarditis Disease Market |
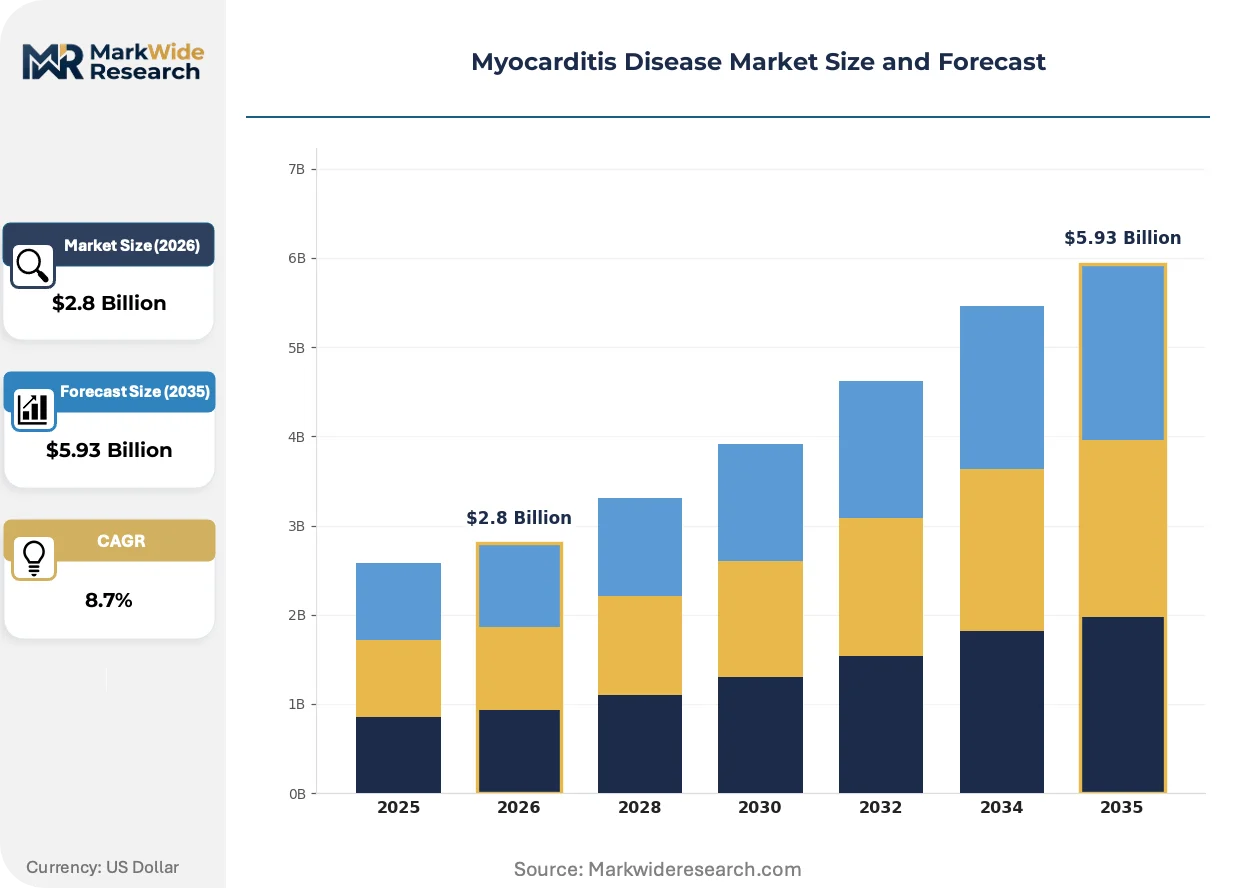
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Antivirals, Corticosteroids, Immunosuppressants, Monoclonal Antibodies End User: Hospitals, Clinics, Research Institutes, Home Care Diagnosis Method: Electrocardiogram, Echocardiogram, MRI, Biopsy Stage of Disease: Acute, Chronic, Fulminant, Recurrent |
| Companies Covered | Evotec AG, Novartis AG, Cardiol Therapeutics, Pfizer Inc., F. Hoffmann-La Roche Ltd., Cantargia AB, Swedish Orphan Biovitrum AB, ARMO Biosciences, CEL-SCI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myocarditis Disease Market Shifts & Advancements
Monoclonal antibody platforms are displacing small-molecule immunosuppressants across autoimmune-driven cardiac inflammation, while regulatory frameworks and care delivery models undergo parallel restructuring.
Cardiac MRI with T2 mapping and extracellular volume quantification is rewriting diagnostic economics by enabling non-invasive tissue characterization that previously required endomyocardial biopsy. Tertiary cardiac centers in Germany and Japan are adopting these sequences as standard-of-care for suspected acute myocarditis. The technology is compressing the diagnostic pathway from days to hours, accelerating therapeutic decision-making and reducing hospital length-of-stay.
EMA's PRIME eligibility criteria for rare cardiovascular diseases are tightening evidentiary standards for breakthrough therapy designation, requiring sponsors to demonstrate mechanistic biomarker correlation earlier in development. This regulatory pressure is forcing biologics developers to integrate companion diagnostic strategies into Phase II protocols. Autoimmune myocarditis indications are experiencing the most pronounced timeline compression as sponsors compete for priority review vouchers.
Payer contracts for biologic immunosuppressants are migrating toward outcomes-based arrangements that tie reimbursement to six-month freedom from recurrent hospitalization. Hospital systems in the United States are negotiating these value-based agreements with specialty pharmacy administrators, displacing traditional fee-for-service infusion reimbursement. This shift is most advanced in integrated delivery networks with captive specialty pharmacy capabilities and longitudinal EHR tracking infrastructure.
Myocarditis Disease Market Segmentation
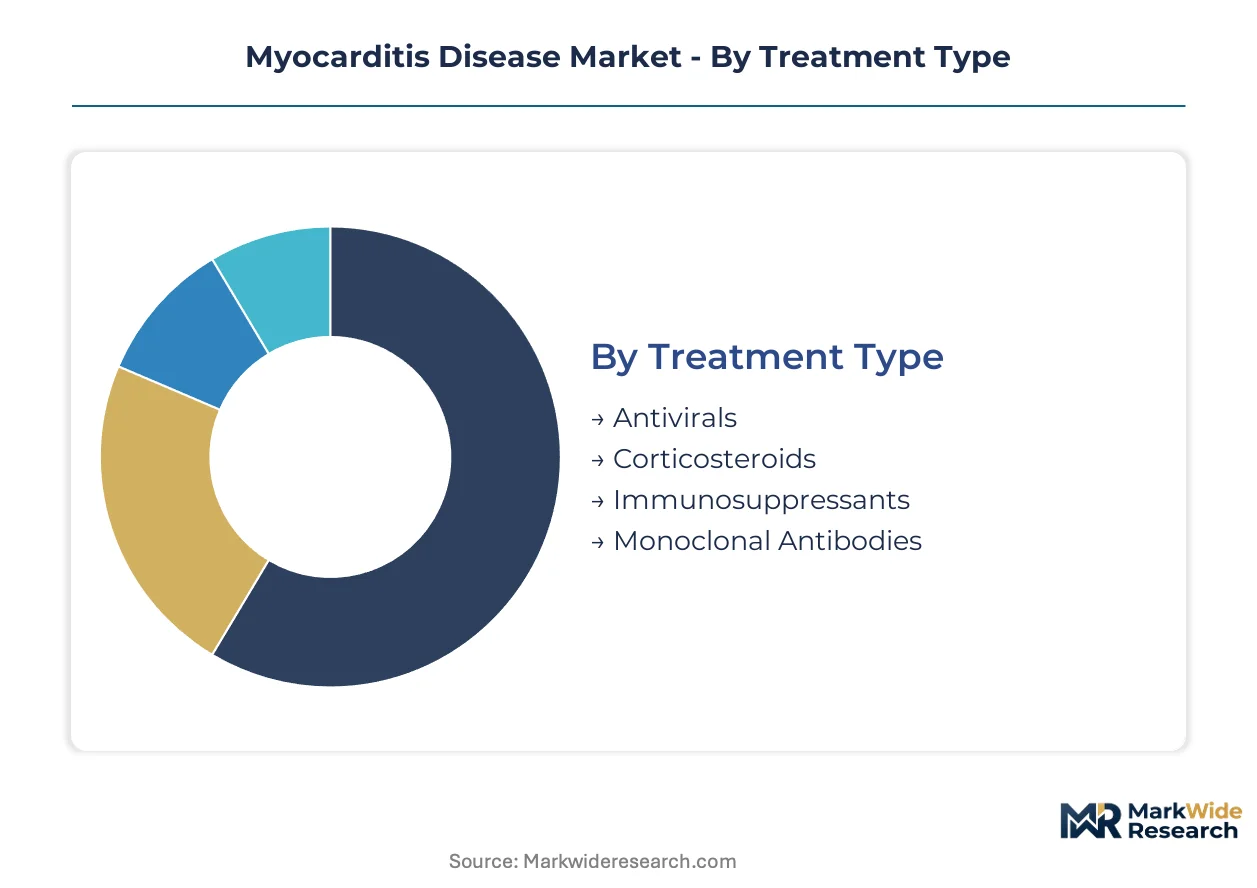
Treatment modality selection in myocarditis care hinges on etiological stratification between viral, autoimmune, and fulminant presentations. Diagnostic pathway economics further fragment the market, with imaging infrastructure availability determining patient routing across acute and chronic management settings.
Treatment Type:
Supply concentration tilts toward biologics developers with established immunology manufacturing footprints, while generic corticosteroid producers compete on hospital formulary access.
- Monoclonal Antibodies:Engineered proteins targeting IL-1β and IL-6 cytokine pathways demonstrate superior efficacy in corticosteroid-refractory autoimmune myocarditis. Demand clusters in tertiary cardiac centers within the United States and Germany where payer coverage for biologics has expanded. Supply constraints persist due to cold-chain distribution requirements and infusion center capacity.
- Immunosuppressants:Calcineurin inhibitors and mycophenolate mofetil form the backbone of maintenance therapy for chronic autoimmune presentations. Volume concentrates in Japan's hospital networks where PMDA Sakigake-accelerated immunomodulators have shortened approval timelines. Generic price erosion pressures originator manufacturers to defend position through combination protocols.
- Corticosteroids:High-dose methylprednisolone remains first-line for acute inflammatory suppression due to rapid availability and low cost. Standardized across emergency departments regardless of etiological confirmation.
- Antivirals:Direct-acting agents target viral persistence in suspected post-infectious cases, though diagnostic uncertainty limits addressable populations. Development concentrates in mRNA platform sponsors with respiratory virus pipeline assets.
Today's leader: Immunosuppressants. Tomorrow's challenger: Monoclonal Antibodies.
End User:
Patient acuity and reimbursement economics stratify service delivery across institutional settings, with diagnostic capability and therapeutic intensity determining site-of-care allocation.
- Hospitals:Tertiary cardiac centers command premium case volumes through integrated MRI-biopsy pathways and extracorporeal membrane oxygenation backup for fulminant presentations. Capital intensity in magnet systems and specialist staffing creates regional supply concentration. United States academic medical centers and German university hospitals anchor global treatment protocol development.
- Home Care:Remote cardiac monitoring and subcutaneous biologic administration are shifting stable chronic patients away from infusion centers. Wearable ECG integration with specialty pharmacy platforms enables longitudinal tracking. Growth trajectory steepest in integrated US delivery networks with captive remote monitoring infrastructure.
- Clinics:Community cardiology practices handle stable follow-up and diagnostic triage, referring complex cases to tertiary centers. Reimbursement limitations on advanced imaging constrain service expansion.
- Research Institutes:Academic centers with dedicated cardiac immunology departments drive biomarker validation and adaptive trial design for rare disease indications.
Hospitals retain procedure intensity. Home Care captures volume expansion.
Diagnosis Method:
Capital deployment in imaging infrastructure is recalibrating diagnostic economics away from invasive tissue sampling toward non-invasive tissue characterization.
- MRI:T2 mapping and extracellular volume quantification enable non-invasive distinction between acute edema and chronic fibrosis. Deployment concentrates in German and Japanese tertiary centers where standardized protocols have compressed diagnostic pathways from days to hours. Magnet system costs and specialized radiologist training limit geographic penetration.
- Biopsy:Endomyocardial sampling remains gold standard for definitive histological classification but carries procedural risk and sampling error. Volume declining as non-invasive alternatives achieve payer acceptance for initial diagnosis.
- Echocardiogram:Transthoracic imaging provides rapid functional assessment and wall motion abnormality detection across all care settings. Universal availability supports frontline screening.
- Electrocardiogram:Twelve-lead and continuous monitoring detect arrhythmia and conduction abnormalities suggestive of myocardial involvement. Lowest-cost entry point for diagnostic suspicion.
MRI commands premium positioning. Echocardiogram defends access breadth.
Stage of Disease:
Clinical urgency and mortality risk stratify therapeutic investment, with fulminant presentations justifying highest-cost interventions despite smaller addressable populations.
- Fulminant:Rapid-onset hemodynamic collapse requiring mechanical circulatory support and emergent immunosuppression. Case volume smallest but per-patient expenditure highest due to intensive care and device utilization. Concentrated in specialized cardiac surgical centers.
- Acute:Symptomatic presentation with elevated biomarkers and imaging abnormalities drives the majority of hospital admissions and MRI utilization. Represents primary target for novel therapeutic trials.
- Chronic:Persistent inflammation or established fibrosis requiring long-term immunomodulation and heart failure management. Largest addressable population for maintenance biologics.
- Recurrent:Relapsing-remitting course in autoimmune subsets necessitates repeated intervention and drives demand for definitive ablative or transplant evaluation.
Acute stage anchors revenue concentration. Fulminant stage justifies premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts academic medical centers anchor advanced cardiac immunology infrastructure in the United States. Germany's university hospital networks deploy tissue characterization MRI protocols that compress diagnostic timelines. Japan's PMDA Sakigake framework accelerates novel immunomodulator access for domestic patients.
United States
Tertiary cardiac centers in Boston and Cleveland drive MRI-based diagnosis adoption for acute myocarditis presentations. FDA orphan drug designation grants protocol assistance and fee waivers for rare cardiovascular indications, shortening development timelines for targeted biologics. Integrated delivery networks in California and Texas negotiate outcomes-based payer contracts tying reimbursement to six-month hospitalization avoidance.
Germany
University hospitals in Munich and Heidelberg standardize T2 mapping sequences for non-invasive tissue characterization. EMA PRIME eligibility criteria tighten evidentiary standards for breakthrough therapy designation in rare cardiovascular diseases. The Baden-Württemberg medical technology corridor concentrates magnet system manufacturing and specialized radiologist training programs.
Japan
PMDA's Sakigake framework accelerates domestic review of IL-1 and IL-6 pathway inhibitors for autoimmune-driven cardiac inflammation. Tokyo and Osaka academic centers anchor cardiac immunology department expansion with combined cardiology-rheumatology staffing models. Biologics cold-chain distribution networks concentrate in the Kanto region to serve metropolitan infusion centers.
United Kingdom
London teaching hospitals pioneer biomarker-based diagnostic criteria validation for adaptive trial designs. NHS England coverage determinations for biologic immunosuppressants vary by integrated care system, fragmenting addressable patient populations. The Cambridge-Oxford biomedical cluster supports companion diagnostic development for Phase II cardiovascular protocols.
Switzerland
Basel and Zurich pharmaceutical research centers leverage established immunology manufacturing footprints for cardiac indication expansion. Swissmedic coordinates with EMA on parallel review pathways for rare disease therapies. The country's specialty pharmacy infrastructure supports subcutaneous biologic administration for stable chronic patients transitioning to home care.
Myocarditis Disease Market Competitive Landscape
Strategic partnerships dominate the current landscape as biologics developers integrate companion diagnostic capabilities into Phase II protocols. The market structures around three tiers: established immunology majors with cardiovascular pipeline extensions, rare disease specialists leveraging accelerated regulatory pathways, and emerging platform technology sponsors. Consolidation pressures intensify as payer outcomes-based contracts favor integrated delivery networks with captive specialty pharmacy capabilities. Portfolio diversification into autoimmune cardiac indications and geographic expansion into Asian regulatory frameworks represent the dominant competitive vectors.
Within the immunology-major tier, Novartis AG and Pfizer Inc. exemplify divergent platform strategies. Novartis leverages its Basel-based manufacturing infrastructure and established interleukin inhibitor portfolio to anchor autoimmune myocarditis development. Pfizer occupies a position defined by mRNA therapeutic platform investment applicable to viral etiologies. Cardiol Therapeutics represents the specialized-niche archetype, with its cannabidiol-based cardioprotection focus distinguishing acute-stage protocols from chronic immunosuppression approaches.
| Leading Market Players |
|---|
| Evotec AG |
| Novartis AG |
| Cardiol Therapeutics |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd. |
| Cantargia AB |
| Swedish Orphan Biovitrum AB |
| ARMO Biosciences |
| CEL-SCI Corporation |
| Others |
Supply & Pricing Matrix
Cardiac immunology specialist scarcity in the United States and Germany widens pricing-tier spreads between tertiary academic centers and community cardiology practices, as labor-cost differentials in magnet-system operation and interleukin-inhibitor infusion administration stratify reimbursement rates across institutional tiers.
Pricing Analysis
Input-cost pass-through from biologics cold-chain logistics and MRI magnet maintenance contracts shapes a three-tier pricing structure across premium, standard, and economy levels in myocarditis care. Premium tiers concentrate in Boston and Cleveland academic medical centers where FDA orphan drug designation enables value-based contracts tied to six-month hospitalization avoidance, while standard tiers dominate German university hospitals with EMA PRIME eligibility protocols, and economy tiers persist in corticosteroid-first emergency departments. Price differentiation hinges on tissue-characterization MRI availability and biologics infusion center certification. Pricing pressure stems from generic immunosuppressant erosion in Japan's PMDA Sakigake-accelerated market. Community cardiology clinics exhibit highest price sensitivity due to reimbursement limitations on advanced imaging.
Supply Chain Analysis
Dual-sourcing requirements for IL-1β and IL-6 pathway inhibitors mandate multi-supplier qualification across United States, Switzerland, and Japan biologics manufacturing networks, compressing procurement timelines for hospital systems. Raw material dependencies center on monoclonal antibody cell lines, specialized MRI contrast agents, and cannabidiol API feedstocks. Supply chain risk concentrates in single-source vulnerability for cardiac MRI magnet systems produced by limited German and Japanese equipment manufacturers. Distribution runs through captive specialty pharmacy platforms in integrated US delivery networks and regional cold-chain hubs serving metropolitan infusion centers in the Kanto region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in myocarditis therapeutics rests on biologics outcomes-based contract penetration and diagnostic imaging standardization that shifts volume from high-cost biopsy pathways to repeatable MRI protocols.
For Market Incumbents: Cement formulary dominance through backward integration into companion diagnostic development and cardiac MRI software analytics, defending against mRNA platform sponsors encroaching on viral etiology segments. Priority capacity addition targets Switzerland's specialty pharmacy infrastructure for subcutaneous biologic administration. FDA protocol assistance for rare cardiovascular indications remains the critical regulatory lever to extend development timelines against emerging interleukin inhibitor competitors. For New Entrants and Emerging Players: Enter via acute-stage cardioprotection protocols distinct from chronic immunosuppression, where cannabidiol-based formulations face limited incumbent saturation. White-space concentrates in home care remote monitoring integration with wearable ECG platforms, particularly in Texas and California integrated delivery networks. Go-to-market positioning should emphasize subscription revenue models for post-acute recovery tracking rather than per-dose therapeutic competition. For Investors and Strategic Acquirers: Large-cap immunology majors with cardiovascular pipeline extensions are the most active acquirer in this space, consolidating rare disease specialists with EMA PRIME eligibility and adaptive trial capabilities. Long-term viability over the 5-10 year window hinges on biomarker-based diagnostic criteria standardization that redefines addressable populations. Acquisition target archetype: Phase II biologics developers with mechanistic correlation data and parallel Asian regulatory strategies. Signal to watch: PMDA Sakigake approval velocity for novel immunomodulators as inflection indicator for competitive timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA orphan drug designation shortens time-to-market for rare cardiovascular indications with protocol assistance. |
| Manufacturing Scale-Up | Biologics cold-chain expansion in the Kanto region serves metropolitan Tokyo and Osaka infusion centers. |
| Pipeline Diversification | Interleukin-1 and interleukin-6 pathway inhibitors secure expanded payer coverage for refractory autoimmune cases. |
| Hospital System Partnership | Tertiary cardiac centers in Munich and Heidelberg anchor MRI-based diagnostic protocol standardization. |
| Reimbursement Strategy | Outcomes-based contracts in US integrated delivery networks tie biologic immunosuppressant payment to hospitalization avoidance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down therapeutic-class revenue triangulation anchored market sizing across the analysis window.
Segment-weighting approaches distributed value across treatment type, end user, diagnosis method, and disease stage dimensions, with regional regulatory clusters capturing FDA, EMA, and PMDA pathway differentiation. CAGRs were derived from epidemiological trend extrapolation, biologics pipeline maturation curves, and imaging infrastructure deployment schedules. Forecast inputs incorporated cardiac MRI adoption velocity in German university hospitals and PMDA Sakigake review timeline compression for novel immunomodulators.
Inputs from clinical trial registries and payer coverage determinations were available through the study window; gaps in real-world evidence for cannabidiol cardioprotocols introduce uncertainty bands around acute-stage market penetration assumptions. Deviation in biomarker-based diagnostic criteria validation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Cardio-Selective Beta Blockers Market
Cardiovascular
Cardiac Safety Services Market
Cardiovascular
Global Cardiac Tamponade Market
Cardiovascular
Vasculitis Market
Cardiovascular
Cardiometabolic Disease Market
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Fractional Flow Reserve Market
Cardiovascular
Cardiovascular Clinical Trials Market
Cardiovascular
Prinzmetal Angina Therapeutics Market
Cardiovascular
Chronic Heart Failure Market
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Aortic Coarctation Market