
 Sleep Apnea Diagnostic Systems Market | 2026-2036
Sleep Apnea Diagnostic Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Apnea Diagnostic Systems Market Outlook
Direct-to-patient distribution is tilting toward home sleep test devices as insurers tighten pre-authorization requirements for in-lab polysomnography. ResMed Inc. leverages its connected care platform to sustain recurring revenue streams beyond device sales. Koninklijke Philips N.V. anchors its position through hospital sleep lab partnerships across Western Europe and North America. Fisher & Paykel Healthcare Corporation Limited competes on humidification-integrated diagnostic accessories that improve patient compliance during multi-night home studies.
Sleep apnea diagnostic systems encompass devices and software platforms that detect, quantify, and classify breathing disturbances during sleep through airflow, respiratory effort, oxygen saturation, and electrophysiological signal acquisition, typically sampling at 200-512 Hz for EEG channels and employing thermocouple or nasal pressure transducers for airflow measurement. These systems serve primarily to stratify disease severity via the apnea-hypopnea index and guide therapeutic intervention selection. Polysomnography devices retain the highest margin pool in hospital and accredited sleep center settings where comprehensive neurophysiological monitoring justifies premium reimbursement, while home sleep test devices represent the fastest-expanding segment as portable peripheral arterial tone and peripheral capillary oxygen saturation technologies achieve diagnostic parity for uncomplicated obstructive sleep apnea. Wearable technology is displacing traditional cable-tethered diagnostics in consumer-accessible channels, though diagnostic software and remote monitoring solutions increasingly determine long-term account stickiness through cloud-based interpretation workflows.
FDA premarket notification requirements under 21 CFR 892 classify sleep diagnostic devices according to intended use complexity, with home test devices subject to streamlined 510(k) pathways compared to full polysomnography systems requiring more substantial equivalence demonstrations. The Centers for Medicare & Medicaid Services national coverage determinations for sleep testing directly shape provider capital expenditure cycles by specifying which device categories qualify for reimbursement under which clinical indications. Stakeholders must monitor evolving FDA guidance on artificial-enabled diagnostic algorithms and state-level scope-of-practice expansions that could shift interpretation authority from board-certified sleep physicians to advanced practice providers.
Market Dynamics
Reimbursement compression from Medicare and commercial payers is restructuring capital deployment across sleep medicine, forcing providers to prioritize lower-cost diagnostic modalities and cloud-connected platforms that extend patient monitoring beyond single-night studies.
Growth Catalysts
- Portable monitoring technologies:Peripheral arterial tone and oximetry sensors now achieve diagnostic equivalence to polysomnography for uncomplicated obstructive sleep apnea, expanding eligible patient populations.
- CMS national coverage determinations:Medicare reimbursement pathways for home sleep testing devices accelerate provider adoption by reducing out-of-pocket exposure for Medicare Advantage enrollees.
- Sleep clinic network consolidation:Integrated health systems in the United States are centralizing diagnostic services under value-based contracts that reward throughput efficiency.
Market Restraints
- Semiconductor component volatility:Discrete analog-to-digital converters and MEMS pressure sensors face allocation constraints that extend device manufacturing lead times.
- Interpretation workforce concentration:Board-certified sleep physicians cluster in metropolitan corridors, creating diagnostic bottlenecks for rural and exurban patient populations.
- Polysomnography reimbursement erosion:Pre-authorization requirements from commercial payers reduce in-lab study volumes and compress hospital sleep center margins.
Strategic Opportunities
- Artificial intelligence-enabled scoring:FDA draft guidance on machine-learning diagnostic algorithms creates pathways for automated event detection that reduces interpretation labor costs.
- Direct-to-consumer channels:Wearable manufacturers bypass traditional clinical distribution by partnering with telehealth platforms for asynchronous physician review.
- India outpatient expansion:Diagnostic infrastructure investment in tier-2 cities addresses untreated prevalence in a geography with limited sleep medicine specialist density.
Industry Challenges
- Algorithm validation timelines:FDA premarket notification requirements for AI-enabled devices demand extensive clinical equivalence studies that extend development cycles.
- Legacy system interoperability:Hospital information system integration with cloud-based sleep platforms requires custom HL7 interface development that strains IT resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Apnea Diagnostic Systems Market |
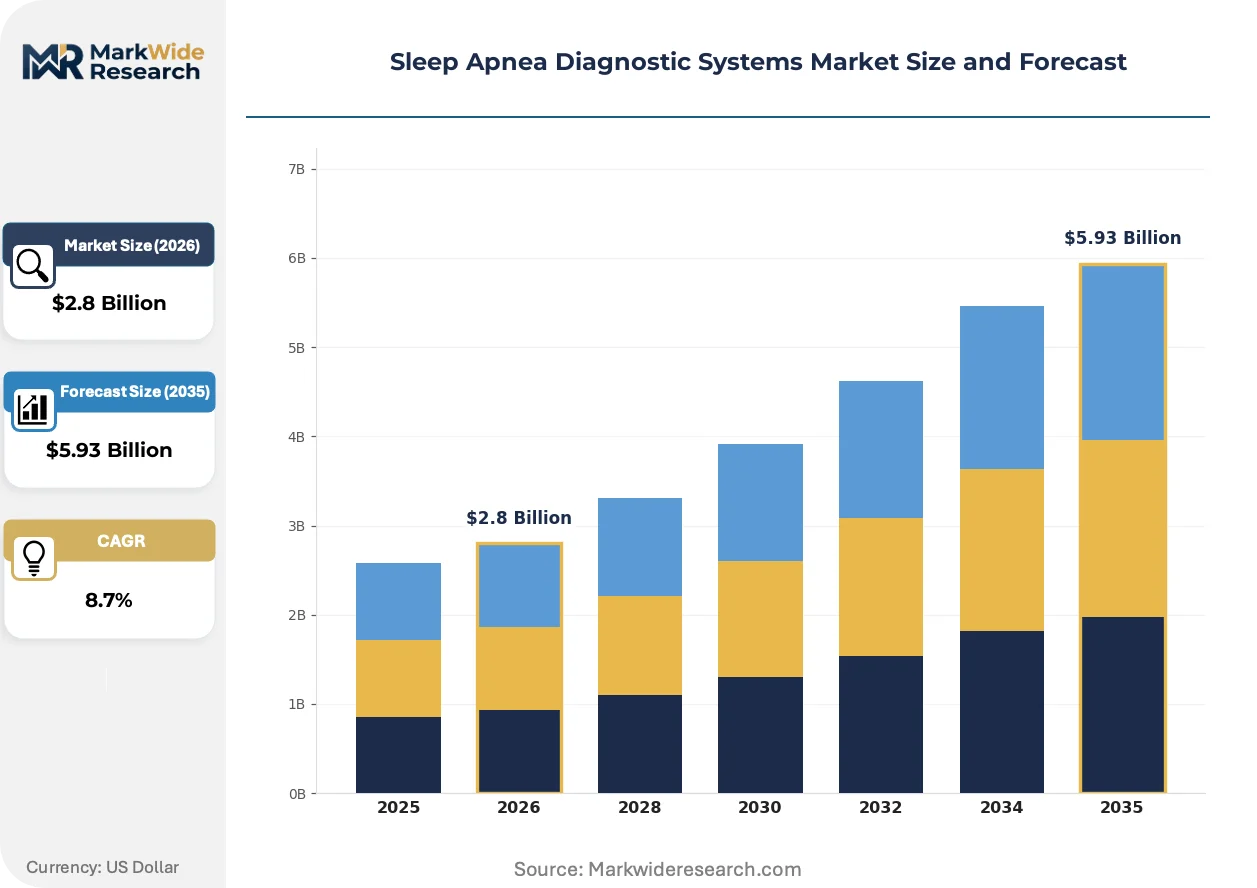
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Sleep Test Devices, Polysomnography Devices, Oximeters, Actigraphy Systems End User: Hospitals, Sleep Clinics, Homecare Settings, Diagnostic Laboratories Technology: Wearable Technology, Continuous Positive Airway Pressure, Diagnostic Software, Remote Monitoring Solutions Application: Diagnosis, Patient Monitoring, Treatment Assessment, Data Analysis |
| Companies Covered | ResMed Inc., Koninklijke Philips N.V., Fisher & Paykel Healthcare Corporation Limited, Compumedics Limited, Natus Medical Incorporated, BMC Medical Co., Ltd., Itamar Medical Ltd., SOMNOmedics GmbH, Drive DeVilbiss Healthcare, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Apnea Diagnostic Systems Market Strategic Shifts
Diagnostic modality boundaries are dissolving as wearable form factors achieve clinical-grade signal fidelity, while reimbursement policy and procurement logic simultaneously favor decentralized patient acquisition over facility-based testing.
Wireless patch-based electrocardiogram and respiratory inductance plethysmography systems are collapsing the distinction between home sleep tests and comprehensive polysomnography by capturing sleep staging data without scalp electrode attachment. Academic medical centers in the United States and Germany are piloting these platforms for multi-night longitudinal studies. The technology is collapsing capital requirements for diagnostic service expansion by eliminating dedicated sleep laboratory infrastructure.
The FDA's evolving guidance on software-as-a-medical-device classification is reshaping product development roadmaps for diagnostic algorithms that operate on consumer wearables. Manufacturers must demonstrate clinical validation across diverse demographic cohorts to support 510(k) clearance. Home sleep test device categories face heightened scrutiny regarding autonomous diagnostic output versus physician-over-interpretation requirements.
Hospital purchasing committees now bundle diagnostic device procurement with multi-year remote monitoring subscriptions that transfer interpretation liability to vendor platforms. Sleep clinic chains in the United States are displacing capital purchase models with per-test fee structures that align vendor incentives with patient throughput targets. This restructuring concentrates vendor selection authority within health system supply chain functions rather than individual physician preference.
Sleep Apnea Diagnostic Systems Market Segmentation
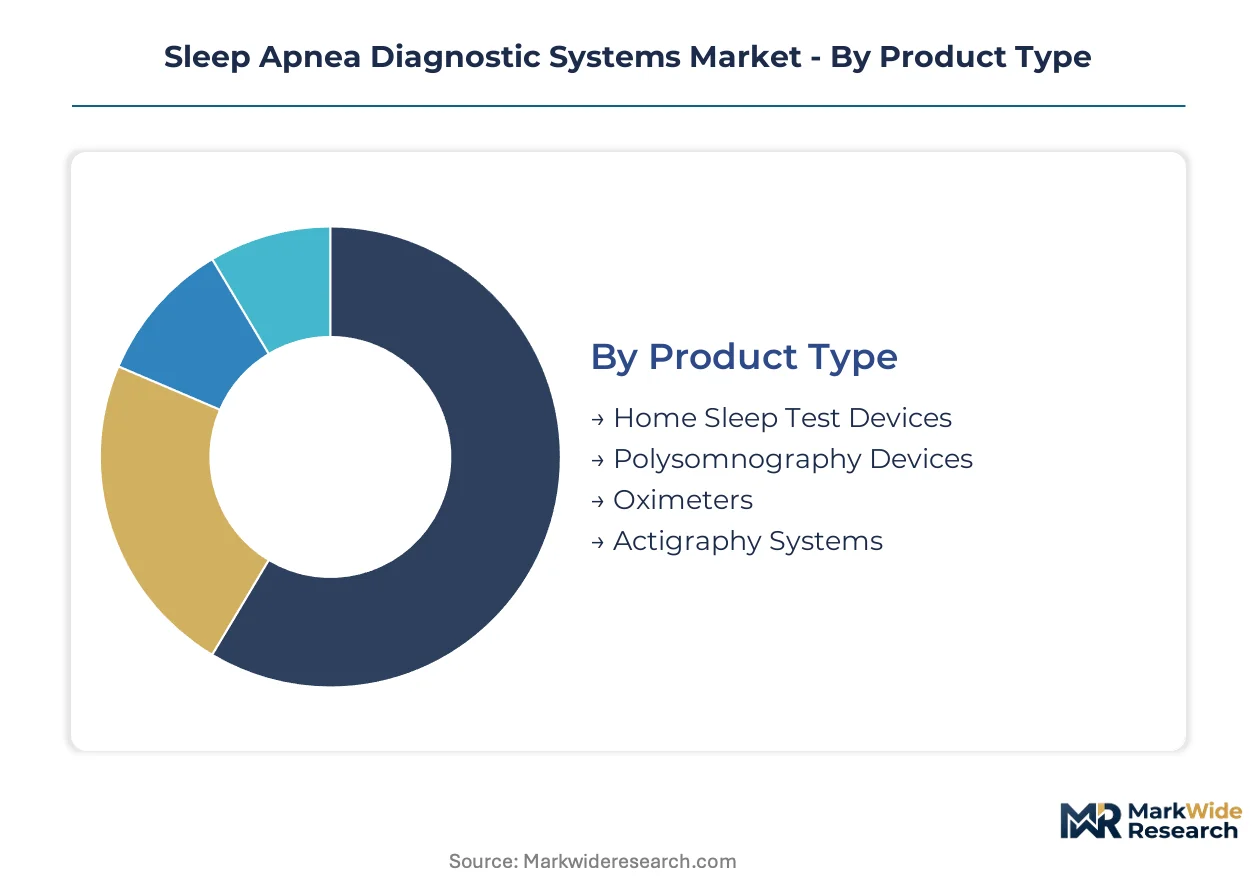
Sleep apnea diagnostic systems fragment across four critical dimensions that determine procurement patterns, reimbursement pathways, and vendor profitability. Product type selection dictates capital intensity and service revenue potential, while end-user concentration shapes distribution architecture and regulatory compliance burdens.
Product Type:
After-sales-service intensity varies sharply across device categories, with cloud-connected platforms generating recurring subscription revenue and standalone hardware requiring minimal ongoing vendor engagement.
- Home Sleep Test Devices:Portable peripheral arterial tone and oximetry sensors achieve diagnostic equivalence to polysomnography for uncomplicated obstructive sleep apnea. Demand concentrates among integrated health networks in the United States seeking to reduce per-test costs under value-based contracts while expanding patient access beyond metropolitan corridors.
- Polysomnography Devices:Comprehensive neurophysiological monitoring systems sample EEG channels at 200-512 Hz and employ thermocouple or nasal pressure transducers for airflow measurement. Hospital sleep centers in Germany and Japan retain these systems for complex cases requiring sleep staging differentiation, though pre-authorization requirements from commercial payers compress utilization rates.
- Oximeters:Peripheral capillary oxygen saturation monitors serve as standalone screening tools or integrated components within multi-parameter diagnostic arrays.
- Actigraphy Systems:Wrist-worn accelerometer-based devices quantify sleep-wake patterns through movement detection algorithms.
By volume, Home Sleep Test Devices lead. By growth pace, Polysomnography Devices are expanding most quickly as academic medical centers pilot wireless patch-based alternatives.
End User:
Procurement authority concentrates differently across settings, with hospital purchasing committees bundling multi-year remote monitoring subscriptions while homecare channels favor direct-to-patient distribution models.
- Hospitals:Accredited sleep centers within tertiary care institutions justify premium reimbursement through comprehensive neurophysiological monitoring. These facilities in the United States and Switzerland face margin pressure from Medicare reimbursement compression and extended interpretation workforce bottlenecks.
- Sleep Clinics:Dedicated diagnostic facilities centralize interpretation expertise and maintain physician oversight of multi-night home studies. Chains across the United States are displacing capital purchase models with per-test fee structures that align vendor incentives with throughput targets.
- Homecare Settings:Direct-to-patient distribution channels bypass traditional clinical infrastructure through telehealth platform partnerships for asynchronous physician review.
- Diagnostic Laboratories:Centralized interpretation hubs process data streams from distributed acquisition devices, leveraging cloud-based scoring algorithms to reduce labor costs.
By installed base, Hospitals dominate. By expansion trajectory, Homecare Settings are climbing the fastest as wearable manufacturers penetrate consumer-accessible channels.
Technology:
Margin structures diverge across technology categories, with software platforms capturing recurring revenue and hardware components facing semiconductor allocation constraints that extend manufacturing lead times.
- Wearable Technology:Wireless patch-based electrocardiogram and respiratory inductance plethysmography systems capture sleep staging data without scalp electrode attachment. Academic medical centers in Germany and the United States pilot these platforms for longitudinal multi-night studies that collapse capital requirements for diagnostic service expansion.
- Continuous Positive Airway Pressure:Therapeutic devices with embedded diagnostic capabilities enable treatment verification and compliance monitoring within single hardware deployments.
- Diagnostic Software:Cloud-based interpretation workflows determine long-term account stickiness through automated event detection algorithms that reduce scoring labor costs.
- Remote Monitoring Solutions:Vendor platforms assume interpretation liability under multi-year subscription arrangements that transfer operational risk from provider to supplier.
By revenue concentration, Diagnostic Software leads. By adoption velocity, Wearable Technology is gaining share fastest as FDA guidance on software-as-a-medical-device classification clarifies clearance pathways.
Application:
Workflow integration requirements vary by application, with diagnosis demanding regulatory clearance for autonomous output while treatment assessment maintains physician-over-interpretation safeguards.
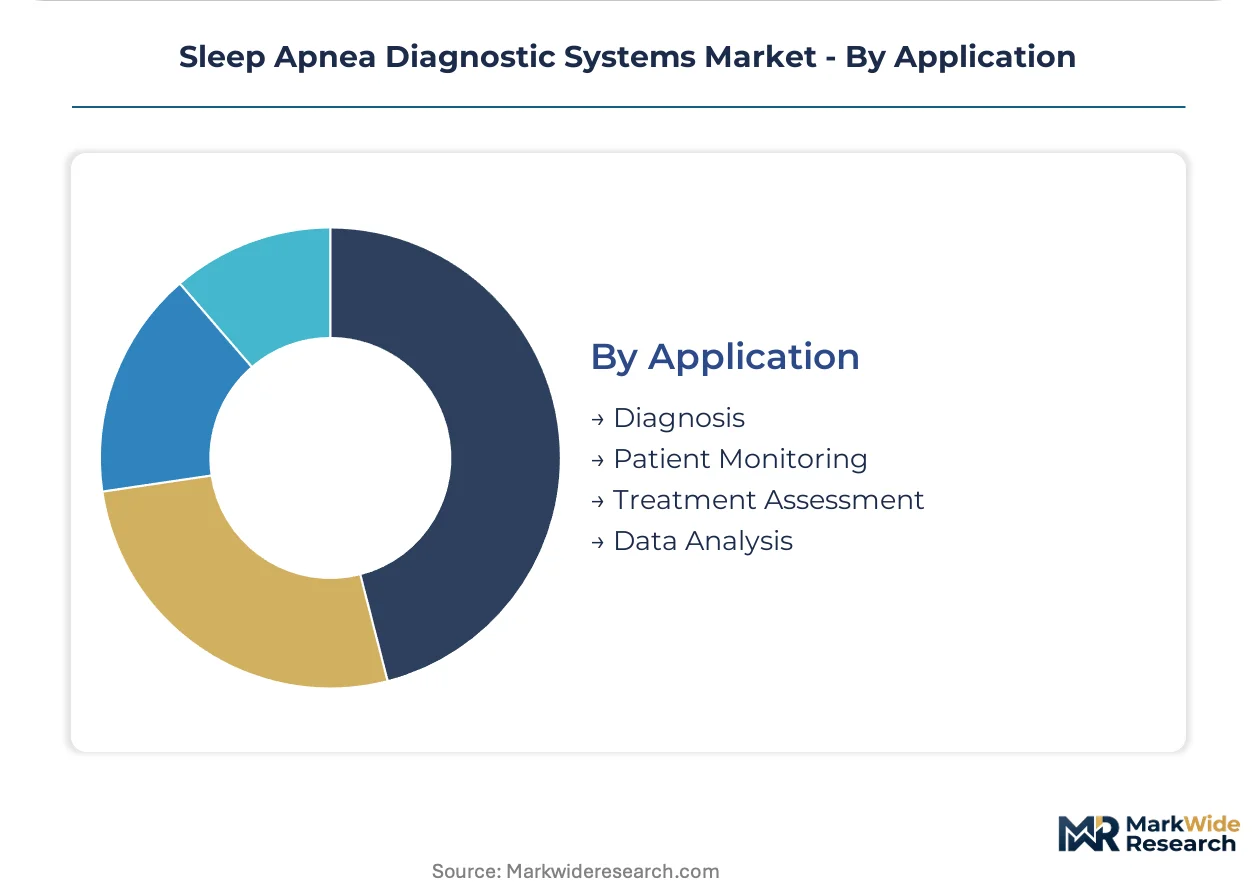
- Diagnosis:Initial disease stratification via apnea-hypopnea index quantification requires FDA premarket notification under 21 CFR 892, with home test devices subject to streamlined 510(k) pathways compared to full polysomnography systems.
- Patient Monitoring:Longitudinal tracking of therapy adherence and symptom progression extends patient engagement beyond single-night studies through connected care platforms.
- Treatment Assessment:Verification of therapeutic efficacy following intervention selection generates repeat utilization of diagnostic infrastructure.
- Data Analysis:Population-level aggregation of de-identified sleep study outputs supports algorithm training and clinical research initiatives.
By procedure volume, Diagnosis leads. By platform investment, Data Analysis is expanding most quickly as artificial intelligence-enabled scoring attracts development resources.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement pathways for home sleep testing accelerate provider adoption across multiple geographies, while national regulators streamline clearance frameworks for wearable diagnostic technologies.
United States
Integrated health networks consolidate sleep medicine services under value-based care contracts that reward throughput efficiency. The FDA's 510(k) premarket notification requirements under 21 CFR 892 classify devices by intended use complexity, streamlining pathways for home test technologies. Sleep clinic chains in Texas and Florida displace capital purchase models with per-test fee structures.
Germany
Academic medical centers pilot wireless patch-based electrocardiogram systems for multi-night longitudinal studies. The EU Medical Device Regulation (MDR) mandates clinical equivalence demonstrations for diagnostic software platforms. Hospital sleep centers in Bavaria and North Rhine-Westphalia retain comprehensive polysomnography systems for complex cases requiring sleep staging differentiation.
Japan
Aging demographics drive diagnostic infrastructure investment for untreated sleep apnea prevalence. The Ministry of Economy, Trade and Industry (METI) promotes connected care platform adoption through reimbursement harmonization initiatives. Sleep laboratories in Tokyo and Osaka face interpretation workforce concentration challenges that create diagnostic bottlenecks for rural patient populations.
India
Outpatient diagnostic expansion in tier-2 cities addresses untreated disease prevalence with limited specialist density. The Central Drugs Standard Control Organization (CDSCO) regulates device import and local manufacturing compliance for sleep diagnostic technologies. Diagnostic infrastructure investment concentrates in Maharashtra and Karnataka where private hospital networks build sleep medicine capacity.
Switzerland
Hospital sleep centers justify premium reimbursement through comprehensive neurophysiological monitoring capabilities. Swissmedic maintains stringent clinical validation requirements for autonomous diagnostic algorithms. Sleep medicine services cluster in Zurich and Geneva where tertiary care institutions anchor regional diagnostic networks.
Sleep Apnea Diagnostic Systems Market Competitive Environment
On the supply side, the industry is consolidating around integrated platform providers that bundle hardware with recurring software subscriptions. Tier-one participants leverage connected care infrastructure to sustain revenue beyond device sales, while mid-scale specialists compete on humidification-integrated accessories and regional service density. Strategic moves concentrate on multi-year remote monitoring subscriptions that transfer interpretation liability to vendor platforms, and per-test fee structures that align supplier incentives with patient throughput targets.
Within the integrated platform tier, ResMed Inc. and Koninklijke Philips N.V. exemplify archetypes that anchor hospital sleep lab partnerships across Western Europe and North America. Fisher & Paykel Healthcare Corporation Limited occupies a position among specialists competing on diagnostic accessories that improve patient compliance during multi-night home studies. These three entities represent distinct strategic postures: connected care platform dominance, hospital channel anchoring, and accessory-integrated compliance optimization.
| Leading Market Players |
|---|
| ResMed Inc. |
| Koninklijke Philips N.V. |
| Fisher & Paykel Healthcare Corporation Limited |
| Compumedics Limited |
| Natus Medical Incorporated |
| BMC Medical Co., Ltd. |
| Itamar Medical Ltd. |
| SOMNOmedics GmbH |
| Drive DeVilbiss Healthcare, Inc. |
| Others |
Value Chain & Pricing Dynamics
Semiconductor component volatility for discrete analog-to-digital converters and MEMS pressure sensors determines both the spread between premium polysomnography systems and economy home sleep test tiers and the geographic configuration of device manufacturing networks. FDA 510(k) clearance timelines and CMS reimbursement eligibility criteria further stratify pricing power across vendor categories.
Pricing Analysis
Certification level (FDA-grade versus CE-marked versus non-regulated consumer wearables) creates the primary spread across pricing tiers. The dominant pricing structure combines per-unit device sales with recurring SaaS subscriptions for cloud-based interpretation platforms. Price differentiation rests on after-sales service intensity and diagnostic algorithm autonomy, with premium tiers bundling multi-year remote monitoring liabilities. Cost compression in the polysomnography segment is intensifying because commercial payer pre-authorization requirements reduce in-lab study volumes. Hospital purchasing committees demonstrate lowest price sensitivity due to bundled procurement authority, while independent sleep clinics exhibit highest sensitivity under per-test fee structures.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for sensor-dependent device categories. Manufacturing concentrates in the United States, Germany, and China, with final assembly often shifting to Mexico or Eastern Europe to mitigate customs exposure. Raw material dependencies center on silicon wafers for signal processing chips, lithium polymer cells for portable power, and medical-grade polymers for patient-contact housings. Single-source vulnerability for specialized ADC components extends procurement lead times during allocation periods. Distribution runs through hospital supply chain functions, GPO contracts, and direct-to-patient telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sleep apnea diagnostic systems occupy an early-cycle expansion phase as home sleep test technologies achieve diagnostic parity with polysomnography for uncomplicated obstructive sleep apnea, opening addressable populations previously excluded by facility access constraints.
For Market Incumbents: Insulate recurring revenue streams by deepening software platform stickiness through AI-enabled scoring algorithms that reduce interpretation labor costs. Anchor hospital system partnerships with multi-year remote monitoring subscriptions that transfer clinical liability. Defend against wearable manufacturer encroachment by accelerating FDA clearance for autonomous diagnostic outputs.
For New Entrants and Emerging Players: Pursue white-space opportunities in tier-2 Indian cities where outpatient diagnostic infrastructure expansion outpaces specialist density. Target direct-to-consumer channels through telehealth platform partnerships that bypass traditional clinical distribution. Leverage asynchronous physician review models to penetrate price-sensitive homecare settings.
For Investors and Strategic Acquirers: FDA draft guidance on machine-learning diagnostic algorithms reshapes the acquisition landscape by clarifying regulatory pathways for automated event detection. Long-term viability centers on platforms combining hardware with recurring software revenue rather than standalone device manufacturers. Monitor state-level scope-of-practice expansions as the signal indicating interpretation authority shifts from board-certified sleep physicians to advanced practice providers.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for AI-Enabled Scoring | Automated event detection algorithms reduce labor costs for interpretation bottlenecks. |
| Hospital System Partnership | Bundled procurement with GPO contracts secures multi-year remote monitoring subscriptions. |
| Software Companion Development | Cloud-based interpretation workflows determine long-term account stickiness beyond hardware. |
| Reimbursement Strategy | CMS national coverage determinations directly shape provider capital expenditure cycles. |
| CE Marking Pathway | EU MDR compliance opens Western European academic medical center pilot programs. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, CMS national coverage determination archives, and hospital procurement contract registries. Primary interviews engaged sleep medicine physicians, biomedical engineers at hospital purchasing committees, GPO contracts managers, and regulatory affairs leads at diagnostic device manufacturers. Secondary validation drew from SEC filings of publicly traded device manufacturers, CDSCO import compliance records, and METI connected care platform adoption reports. Bottom-up triangulation across installed base estimates and top-down reconciliation against reimbursement claim volumes anchor quantitative outputs.
Forecast inputs span product type segmentation across home sleep test devices, polysomnography systems, and wearable technologies; end-user concentration across hospitals, sleep clinics, and homecare settings; and technology categories including diagnostic software and remote monitoring solutions. CAGRs derive from regression analysis of historical reimbursement claim growth and equipment procurement cycles. Industry-specific inputs incorporate FDA guidance evolution on software-as-a-medical-device classification and state-level scope-of-practice regulatory shifts.
Sensitivities concentrate around semiconductor allocation constraints extending manufacturing lead times, reimbursement compression from Medicare and commercial payers, and algorithm validation timelines for AI-enabled devices. Forecasts reflect assumptions regarding regulatory clearance pathway stability and payer policy continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Non-Hospital-Based Point-Of-Care Diagnostic Products Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
Breath Samplers Market
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market
Diagnostic Devices
Europe Breath Analyzer Market
Diagnostic Devices
Amniotic Fluid Detection Market
Diagnostic Devices
Diagnostic Ophthalmic Devices Market
Diagnostic Devices
Blood Testing Devices Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
Electrochemical Biosensors Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
Global DNA Test Kit Market
Diagnostic Devices
Hemoglobin Testing Devices Market
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
Point of Care Diagnostics Market