
 US Cancer Contrast Media Market | 2026-2036
US Cancer Contrast Media Market Size, Share, and Industry Trends Forecast 2026-2036
US Cancer Contrast Media Market Insights
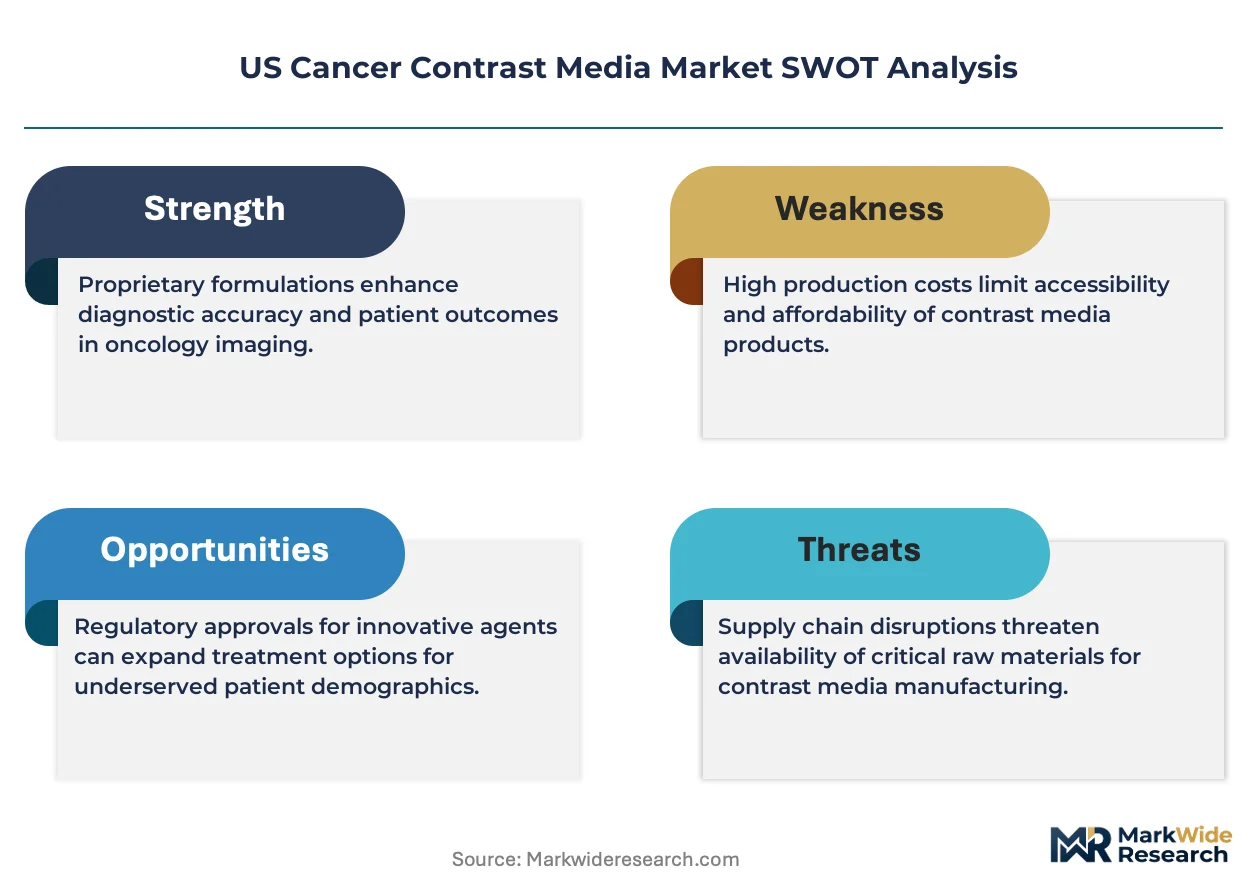
The FDA's strengthened gadolinium retention warnings is recalibrating formulation priorities across the industry. Bayer AG leverages its macrocyclic gadolinium portfolio to sustain clinical preference in high-volume MRI suites. GE HealthCare anchors its position through integrated scanner-contrast bundling with hospital procurement teams. Lantheus competes via radiopharmaceutical adjacencies that extend its oncology imaging footprint beyond traditional contrast agents.
Cancer contrast media comprise diagnostic agents engineered to alter tissue signal characteristics during radiologic examination, with iodine-based formulations containing 300-400 mg iodine per mL for CT attenuation and gadolinium chelates providing paramagnetic T1 shortening at 0.1-0.3 mmol/kg dosing for MRI. Their primary purpose is to differentiate malignant from benign tissue through altered vascularity, capillary permeability, or cellular uptake patterns. Gadolinium-based agents dominate current revenue pools due to MRI's superior soft-tissue resolution in brain and liver oncology protocols, while iodine-based segments retain substantial volume in CT-guided biopsy and staging procedures where speed and cost efficiency matter. Microbubble ultrasound contrast occupies a narrower but expanding niche in hepatocellular carcinoma characterization, where real-time perfusion assessment guides treatment selection.
FDA oversight through its Center for Drug Evaluation and Research governs new molecular entity approvals and post-market pharmacovigilance for retention risks, while USP Chapter 797 and ASHP guidelines shape sterile compounding standards in hospital radiology pharmacies. The Nuclear Regulatory Commission and state radiation control programs layer additional requirements on radioactive contrast adjuncts used in PET-CT fusion studies. Stakeholders must monitor pending FDA guidance on gadolinium-based agent class labeling revisions and their downstream impact on formulary positioning.
Market Dynamics
FDA's intensified gadolinium retention surveillance is restructuring formulation priorities across the US cancer contrast media landscape. Macrocyclic chelate chemistry investments now dominate R&D allocation as manufacturers preempt regulatory reclassification risks.
Growth Catalysts
- Integrated Delivery Network Consolidation:Hospital system mergers in California and Texas are standardizing contrast procurement across multi-site imaging networks, concentrating volume pull toward preferred suppliers.
- MRI Protocol Expansion:Liver-specific hepatobiliary agents are penetrating staging workflows for metastatic colorectal cancer, extending gadolinium-based revenue pools beyond traditional neurological applications.
- USP Chapter 797 Enforcement:Stricter sterile compounding standards in hospital radiology pharmacies are disqualifying small compounders, advantaging manufacturers with validated aseptic manufacturing infrastructure.
Market Restraints
- Gadolinium Supply Concentration:Rare earth processing for paramagnetic cores depends on a limited supplier base concentrated in specific mining jurisdictions, creating input vulnerability.
- CT Attenuation Cost Compression:Iodine-based formulations face reimbursement pressure as Medicare Physician Fee Schedule adjustments compress technical component payments.
- Macrocyclic Premium Economics:Linear-to-macrocyclic formulation transitions impose 40-60% raw material cost premiums without commensurate reimbursement uplift.
Strategic Opportunities
- Microbubble Ultrasound Adjacency:Real-time perfusion imaging for hepatocellular carcinoma characterization represents underdeveloped white space outside saturated CT and MRI channels.
- Texas Hub Expansion:MD Anderson and Houston Methodist's imaging center buildouts create concentrated demand nodes for high-throughput contrast delivery systems.
- AI-Enhanced Dosing Protocols:Machine learning integration with PACS systems enables personalized contrast volume optimization, differentiating vendor relationships beyond commodity supply.
Industry Challenges
- Radiopharmacist Talent Scarcity:USP 797 compliance requires specialized sterile compounding expertise that academic programs are not producing at replacement rates.
- Scanner-Contrast Integration Complexity:Vendor-neutral contrast delivery systems must interface with proprietary MRI injector protocols from GE HealthCare, Siemens Healthineers, and Philips platforms.
- Gadolinium Retention Litigation Exposure:Product liability frameworks around NSF and Gd deposition create unpredictable reserve requirements for underwriters and manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cancer Contrast Media Market |
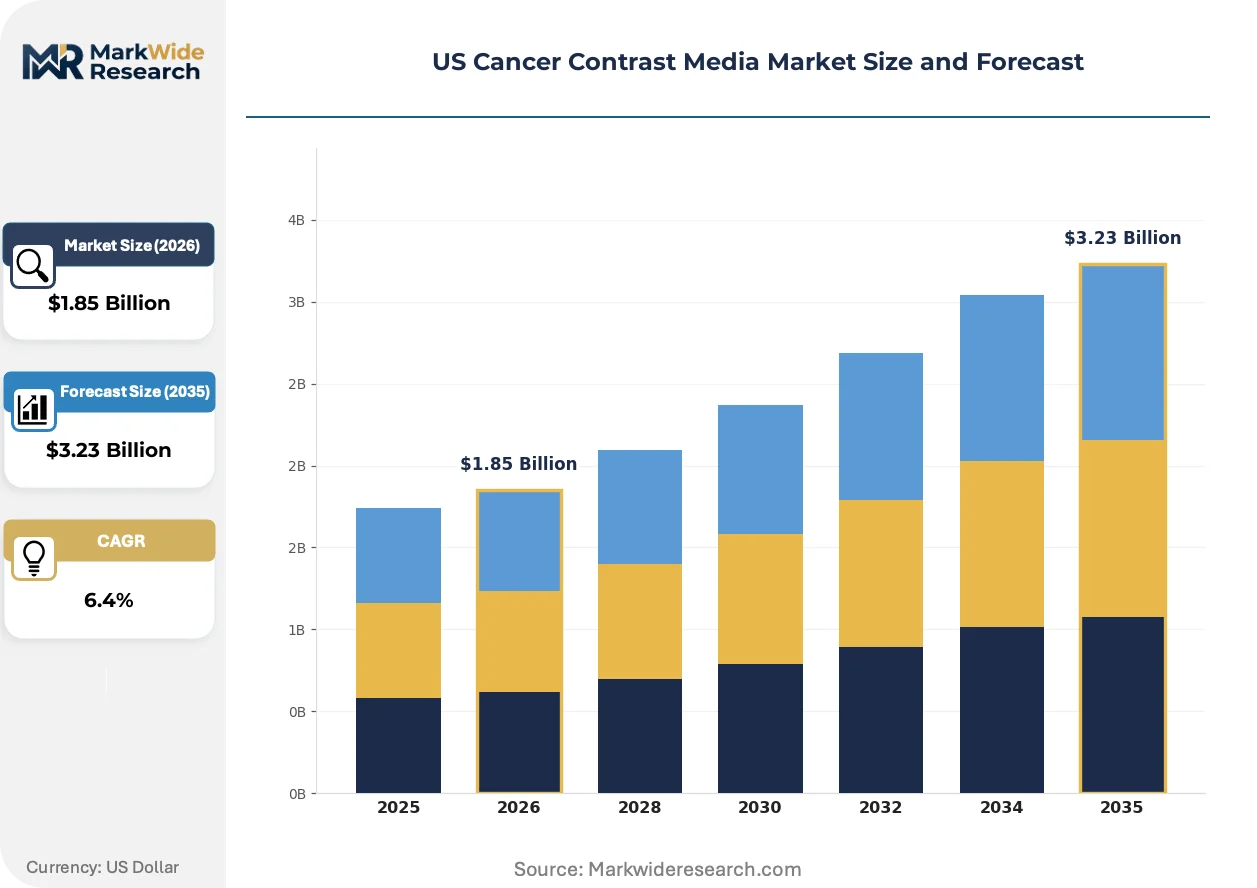
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gadolinium-Based, Iodine-Based, Microbubble, Ultrasound Contrast Agents Application: Diagnostic Imaging, Radiation Therapy, Preoperative Assessment, Therapeutic Monitoring End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics Delivery Mode: Injectable, Oral, Intravenous, Intratumoral |
| Companies Covered | Bayer AG, Bracco, Guerbet, GE HealthCare, Lantheus, IMAX Diagnostic Imaging, Cardinal Health, Trivitron Healthcare, Telix Pharmaceuticals Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cancer Contrast Media Market Trends and Innovations
Artificial intelligence integration is compressing contrast dosing optimization timelines while macrocyclic formulation chemistry is displacing linear chelates from high-volume hospital formularies. Procurement centralization within integrated delivery networks is simultaneously reshaping vendor selection criteria.
Macrocyclic gadolinium chelate chemistry is overtaking linear formulations in high-volume US hospital MRI suites. Academic medical centers and NCI-designated cancer centers are completing formulary conversions within 18-24 month windows. This transition is compressing revenue pools for legacy linear agents while expanding margin structures for manufacturers with validated macrocyclic portfolios.
FDA's 2023 class labeling revision for gadolinium-based contrast agents is mandating retention risk disclosure across all approved formulations. The industrial consequence is accelerated clinical preference for macrocyclic agents in pediatric and renally impaired populations. Pediatric oncology centers and transplant hepatology units are now requiring macrocyclic exclusivity in contrast procurement specifications.
Hospital procurement departments are consolidating contrast purchasing through integrated delivery network headquarters rather than individual facility autonomy. Radiology service line administrators are ceding vendor selection authority to system-level supply chain executives. This concentration is most visible in California's Kaiser Permanente and Sutter Health networks, where single-source contracts now span 15-40 imaging centers simultaneously.
US Cancer Contrast Media Market Segmentation
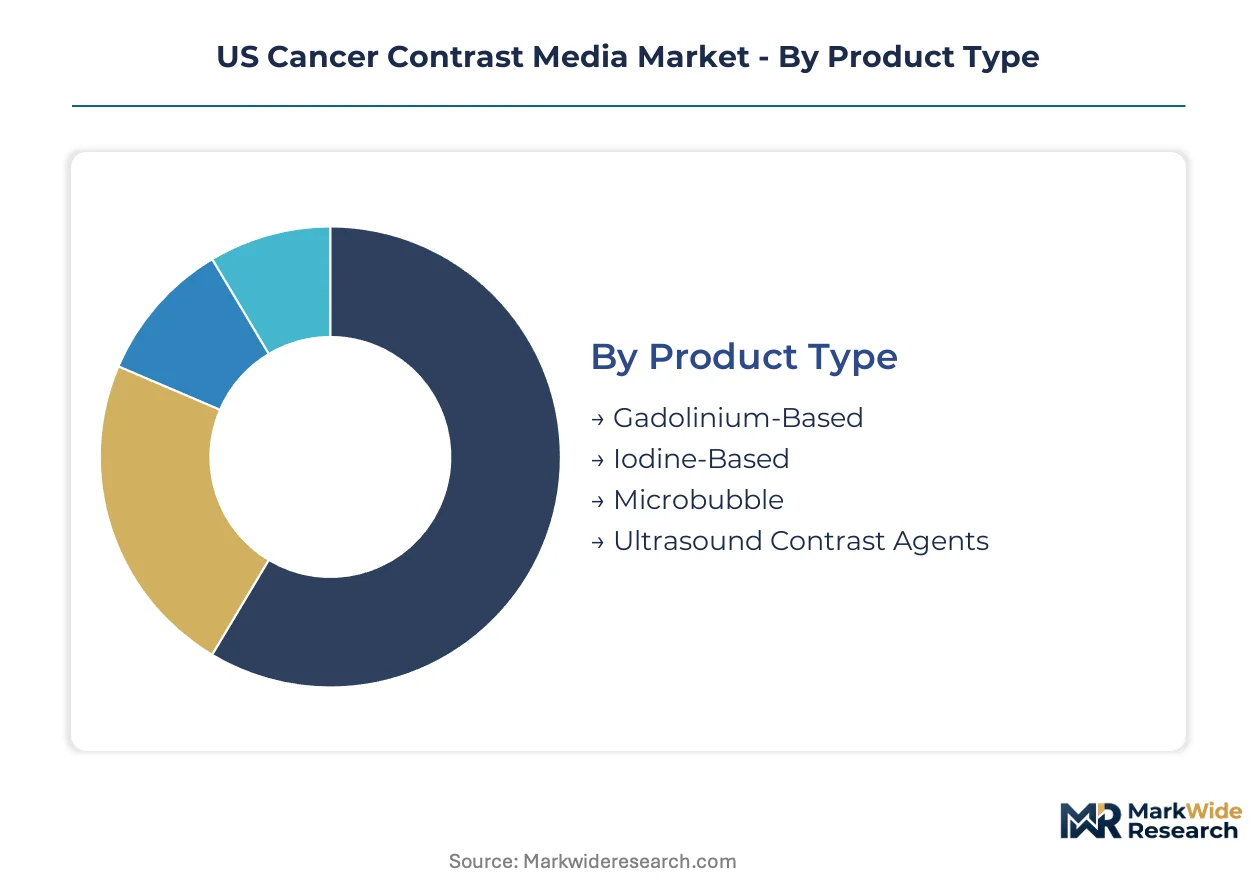
Segmentation in the US cancer contrast media market reveals how capital deployment, regulatory exposure, and procurement concentration fragment commercial opportunity. Manufacturers must align R&D and sales resources against segments where hospital system consolidation and FDA safety mandates are reshaping volume flows.
Product Type:
Capital intensity varies sharply across chemistry platforms, with macrocyclic gadolinium chelates demanding the most substantial upfront manufacturing investment for validated aseptic production and regulatory compliance infrastructure.
- Gadolinium-Based:Macrocyclic chelates provide paramagnetic T1 shortening at 0.1-0.3 mmol/kg dosing for MRI protocols. Demand concentrates in California and Texas integrated delivery networks where high-throughput imaging centers prioritize retention-risk mitigation. FDA's strengthened gadolinium retention warnings are accelerating formulary conversions toward macrocyclic exclusivity in pediatric and renally impaired populations.
- Iodine-Based:Formulations containing 300-400 mg iodine per mL deliver CT attenuation for rapid staging and biopsy guidance. Medicare Physician Fee Schedule compression on technical component payments is squeezing margin structures in outpatient settings, though volume persists in emergency oncology workflows where speed dominates.
- Microbubble:Ultrasound contrast agents enable real-time perfusion assessment for hepatocellular carcinoma characterization. Academic medical centers in Texas are piloting expanded protocols.
- Ultrasound Contrast Agents:Specialized microsphere formulations support contrast-enhanced ultrasound outside traditional CT and MRI channels. Niche adoption limits near-term infrastructure investment.
Most installed capacity flows through Gadolinium-Based segments. Expansion is steepest in Microbubble applications.
Application:
Procurement patterns diverge by clinical setting, with hospital radiology departments commanding volume through integrated delivery network contracts while outpatient sites face reimbursement asymmetries.
- Diagnostic Imaging:MRI and CT protocols for tumor detection, staging, and surveillance constitute the foundational revenue pool. Kaiser Permanente and Sutter Health in California are consolidating contrast procurement across 15-40 imaging centers simultaneously through system-level supply chain authority.
- Radiation Therapy:Contrast-enhanced simulation for treatment planning requires precise vascular mapping. MD Anderson's imaging center buildouts in Texas are creating concentrated demand nodes for high-throughput delivery systems.
- Preoperative Assessment:Surgical planning workflows leverage contrast delineation of tumor margins and vascular involvement. Volume correlates with NCI-designated cancer center surgical caseloads.
- Therapeutic Monitoring:Response assessment protocols track treatment efficacy through serial imaging. USP Chapter 797 compliance requirements are disqualifying small compounders from hospital radiology pharmacy supply.
Diagnostic Imaging absorbs the majority of current contrast volume. Therapeutic Monitoring is climbing the fastest as immunotherapy protocols demand more frequent serial assessment.
End User:
Customer scale determines contract structure, with multi-site health systems extracting pricing leverage unavailable to standalone facilities.
- Hospitals:Academic medical centers and NCI-designated cancer centers complete macrocyclic formulary conversions within 18-24 month windows. Radiology service line administrators are ceding vendor selection authority to system-level supply chain executives.
- Diagnostic Centers:Independent imaging facilities face technical component reimbursement compression under Medicare adjustments. Cost efficiency pressures favor iodine-based CT protocols over MRI where clinically equivalent.
- Research Institutions:Early-phase trials and imaging biomarker development create demand for specialized formulations. Radiopharmacist talent scarcity limits USP 797 compliance capacity.
- Outpatient Clinics:Community oncology practices rely on referral network imaging rather than in-house contrast administration. Volume fragmentation constrains procurement leverage.
Hospitals command the largest share of contrast procurement volume. Research Institutions are expanding most quickly as pharmaceutical sponsors integrate imaging endpoints into oncology trials.
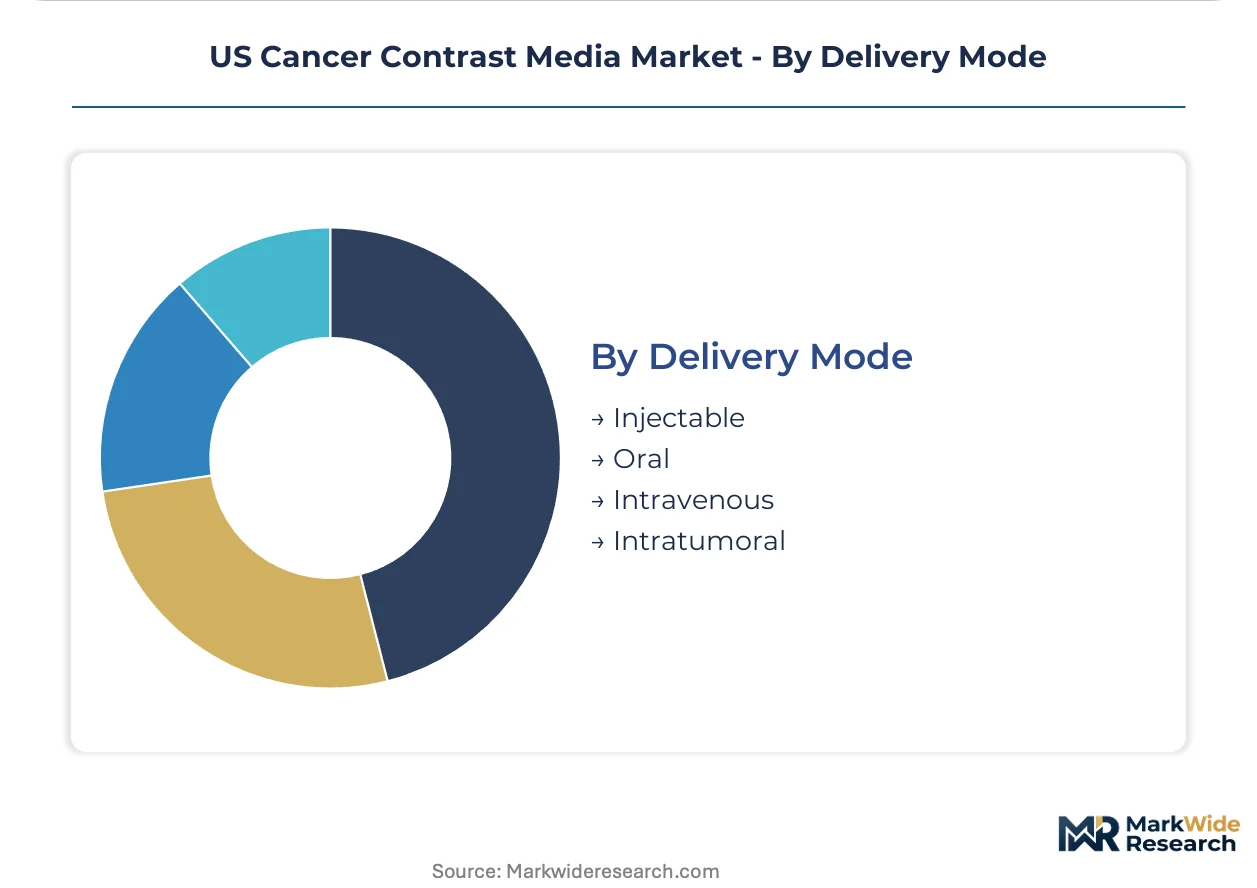
Delivery Mode:
Route of administration shapes manufacturing complexity, with intravenous formulations requiring the most stringent sterile validation.
- Injectable:Subcutaneous and intramuscular routes serve specialized lymphatic mapping procedures. Limited oncology application relative to vascular routes.
- Oral:Iodine-based solutions for CT enterography and gastrointestinal tract opacification. Barium alternatives occupy declining share as CT colonography protocols shift.
- Intravenous:Bolus and power injector delivery dominate MRI and CT contrast administration. Scanner-contrast integration complexity requires vendor-neutral systems to interface with proprietary MRI injector protocols from GE HealthCare, Siemens Healthineers, and Philips platforms.
- Intratumoral:Direct injection for locoregional therapy guidance and interventional oncology procedures. Emerging application in ablation margin assessment.
Intravenous delivery channels the preponderance of installed base utilization. Intratumoral administration is gaining share fastest as interventional oncology expands within multidisciplinary cancer centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiopharmacist talent clusters anchor geographic demand concentration, with sterile compounding expertise concentrating in states hosting NCI-designated cancer centers and academic medical institutions. These workforce pools determine where USP Chapter 797-compliant contrast manufacturing and administration infrastructure scales fastest.
California
Kaiser Permanente and Sutter Health operate integrated delivery networks spanning 15-40 imaging centers each, consolidating contrast procurement through system-level supply chain executives. FDA's 2023 gadolinium retention labeling revision accelerates macrocyclic formulary conversions at Stanford Medicine and UCSF Helen Diller Family Comprehensive Cancer Center. The San Francisco Bay Area and Los Angeles County host the densest concentrations of pediatric oncology centers requiring macrocyclic exclusivity.
Texas
MD Anderson Cancer Center and Houston Methodist are completing imaging center buildouts that create concentrated demand nodes for high-throughput contrast delivery systems. The state's radiation control programs layer additional requirements on radioactive contrast adjuncts used in PET-CT fusion studies. The Texas Medical Center in Houston anchors the southern region's largest radiopharmacist employment cluster.
New York Metro
Memorial Sloan Kettering Cancer Center and NYU Langone Health drive demand for hepatobiliary agents in metastatic colorectal cancer staging workflows. New York State's Department of Health enforces stricter sterile compounding standards beyond federal USP Chapter 797 baselines. The Manhattan-Brooklyn corridor concentrates research institution procurement for early-phase trial imaging biomarker development.
Greater Boston
Dana-Farber Cancer Institute and Massachusetts General Hospital prioritize AI-enhanced dosing protocol integration with PACS systems for personalized contrast volume optimization. Massachusetts Board of Registration in Pharmacy maintains separate licensure requirements for nuclear pharmacy specialists. The Longwood Medical and Academic Area represents the Northeast's densest cluster of NCI-designated comprehensive cancer centers.
Midwest
Mayo Clinic in Rochester and Cleveland Clinic anchor demand for microbubble ultrasound contrast in hepatocellular carcinoma characterization protocols. State radiation control programs in Minnesota and Ohio impose additional layer requirements on radioactive contrast adjuncts. The Chicago-Minneapolis corridor maintains secondary radiopharmacist training pipelines through University of Wisconsin and University of Michigan academic programs.
US Cancer Contrast Media Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the US cancer contrast media landscape, with integrated pharmaceutical conglomerates operating validated aseptic manufacturing infrastructure while specialized radiopharmaceutical firms pursue portfolio adjacencies. The market structure concentrates around three strategic archetypes: diversified healthcare conglomerates with scanner-contrast bundling capabilities, pure-play contrast manufacturers with macrocyclic chemistry specialization, and radiopharmaceutical specialists extending into oncology imaging. Dominant competitive moves include integrated delivery network contract consolidation and macrocyclic formulation R&D prioritization to preempt FDA reclassification risks.
Within the diversified healthcare conglomerate tier, Bayer AG and GE HealthCare exemplify capital-intensive players leveraging hospital procurement relationships. Bracco occupies a position among European-origin manufacturers with established US distribution infrastructure. These three entities anchor the premium tier where scanner-contrast bundling and validated aseptic manufacturing capabilities determine integrated delivery network contract outcomes.
| Leading Market Players |
|---|
| Bayer AG |
| Bracco |
| Guerbet |
| GE HealthCare |
| Lantheus |
| IMAX Diagnostic Imaging |
| Cardinal Health |
| Trivitron Healthcare |
| Telix Pharmaceuticals Limited |
| Others |
Pricing and Supply Chain Analysis
FDA's 2023 gadolinium retention labeling revision gates qualified supply access for macrocyclic chelate manufacturers while simultaneously enabling premium-tier pricing power for validated aseptic producers serving pediatric oncology centers and NCI-designated cancer centers.
Pricing Analysis
Scanner-contrast bundling versus unbundled pharmaceutical procurement splits the market into two distinct pricing regimes. Three-tier pricing structure across premium macrocyclic, standard linear gadolinium, and economy iodine-based levels differentiates offerings, with FDA safety tier and volume scale driving spreads. Cost compression in iodine-based CT segments is intensifying because Medicare Physician Fee Schedule adjustments squeeze technical component payments. Diagnostic centers exhibit the highest price sensitivity, while academic medical centers prioritize retention-risk mitigation over unit cost.
Supply Chain Analysis
Reverse-logistics flows for expired contrast agents and recalled lots require specialized hazardous waste handling, with manufacturers bearing cradle-to-grave stewardship obligations under EPA Resource Conservation and Recovery Act provisions. Rare earth processing for paramagnetic cores draws from China, Estonia, and Malaysia, creating geographic concentration risk. Gadolinium oxide, chelating ligands, and sterile packaging materials anchor input dependencies. Single-source vulnerability in rare earth refining threatens supply continuity. Distribution runs through integrated delivery network headquarters rather than individual facility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential as macrocyclic formulation transitions command premium pricing without proportional cost escalation, while sterile manufacturing scale economies compress per-unit production expenses.
For Market Incumbents: Hedge against FDA reclassification risk by accelerating macrocyclic R&D allocation and securing validated aseptic manufacturing capacity expansions in Texas and California. Scanner-contrast bundling agreements with GE HealthCare, Siemens Healthineers, and Philips platforms represent the critical channel control lever for defending formulary position against radiopharmaceutical specialists.
For New Entrants and Emerging Players: Direct-to-hospital procurement platforms bypass traditional distributor markups and enable competitive positioning in microbubble ultrasound contrast, the most penetrable white space outside saturated CT and MRI channels. Texas Medical Center imaging center buildouts and hepatocellular carcinoma characterization protocols offer concentrated entry points.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play contrast manufacturers lacking macrocyclic portfolios, as FDA safety mandates relegate linear chelate specialists to terminal decline. Long-term viability hinges on aseptic manufacturing infrastructure and integrated delivery network contract density. Radiopharmacist employment growth rates signal inflection timing for USP Chapter 797 compliance capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Macrocyclic Portfolio Conversion | FDA retention warnings accelerate formulary exclusivity at pediatric oncology centers. |
| Integrated Delivery Network Contract Consolidation | Kaiser Permanente and Sutter Health procurement centralization demands system-level vendor relationships. |
| AI-Enhanced Dosing Protocol Development | Machine learning integration with PACS systems differentiates vendor relationships beyond commodity supply. |
| Microbubble Ultrasound Infrastructure Investment | MD Anderson hepatocellular carcinoma protocols create real-time perfusion imaging demand nodes. |
| Radiopharmacist Workforce Expansion | USP Chapter 797 compliance requirements outpace academic program output, constraining sterile compounding capacity. |
Research Methodology
Direct dialogue with hospital procurement executives, radiology service line administrators, radiopharmacists, GPO contracts managers, and FDA regulatory affairs specialists grounded qualitative findings. Secondary validation drew from FDA Center for Drug Evaluation and Research filings, USP Chapter 797 guidance documents, CMS Medicare Physician Fee Schedule archives, and hospital formulary databases. Bottom-up volume modeling and top-down market sizing triangulated against integrated delivery network contract disclosures.
Top-down macroeconomic framing anchored demand projections while bottom-up facility-level analysis calibrated regional concentration patterns across the analysis window. Segmentation dimensions spanned chemistry platform, application protocol, end-user scale, and delivery mode. CAGRs derived from procedure volume trajectories, pricing trend synthesis, and formulary conversion velocity assumptions. Forecast inputs incorporated MRI scanner installation pipelines and immunotherapy protocol expansion rates.
The model assumes a particular technology adoption path; alternative pathways for AI-enhanced dosing optimization or microbubble ultrasound protocol expansion would alter the outlook. Forecasts incorporate assumptions regarding FDA regulatory trajectory, rare earth supply continuity, and integrated delivery network consolidation velocity. Practitioners should monitor radiopharmacist licensing data, macrocyclic formulary conversion timelines, and gadolinium retention litigation dockets for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Pressure Ulcer Relief Products Market
Diagnostic and Therapeutic Devices
Therapeutic Bed Market
Diagnostic and Therapeutic Devices
RF Microneedling Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Microneedle Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Global Needle Free Injection Systems Market
Diagnostic and Therapeutic Devices
Dissolving Microneedles Market
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market
Diagnostic and Therapeutic Devices
Middle-East and Africa Stroke Diagnosis and Treatment Market