
 Pediatric Nasal Cannula Market | 2026-2036
Pediatric Nasal Cannula Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Nasal Cannula Market Analytics
REACH compliance is restructuring the cost-of-entry calculus for European manufacturers seeking to supply silicone-based pediatric nasal cannulas. Fisher & Paykel Healthcare Limited leverages its vertically integrated manufacturing in New Zealand to sustain cost advantages across high-flow product lines. Teleflex Incorporated anchors its competitive position through specialized distribution networks in North American pediatric hospitals. Salter Labs differentiates via decades-long brand recognition in homecare oxygen delivery channels.
A pediatric nasal cannula is a flexible tube assembly designed to deliver supplemental oxygen or blended gas directly into a child's nasal passages, typically constructed from medical-grade polymers with prong spacing calibrated to infant and toddler anatomical dimensions. The device serves as the primary non-invasive interface for low-flow and high-flow respiratory support in patients from premature neonates through adolescent populations. Soft cannula configurations command the dominant volume share due to skin-friendly polymer formulations that reduce nasal septum irritation during extended wear periods. High-flow cannula segments are expanding fastest as heated and humidified oxygen delivery protocols gain traction in pediatric intensive care units. Material selection increasingly gravitates toward silicone alternatives as clinicians prioritize biocompatibility and durability over lower-cost polyvinyl chloride options.
FDA 510(k) clearance pathways govern device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for pediatric-specific respiratory accessories. ISO 10993 biocompatibility testing standards shape material selection decisions across all major supply regions, effectively filtering out substandard polymer formulations. Stakeholders must monitor evolving reimbursement codes for home-based pediatric oxygen therapy, as payor policy shifts will determine whether high-flow devices penetrate residential care settings or remain concentrated in institutional environments.
Market Dynamics
The pediatric nasal cannula market is restructuring around heated high-flow oxygen delivery protocols that demand precision-engineered interfaces capable of sustaining 8 liters per minute flow rates without mucosal injury. Material biocompatibility testing under ISO 10993 now filters supplier bases as aggressively as clinical efficacy data.
Growth Catalysts
- Neonatal ICU expansion:Pediatric hospitals across the United States are scaling dedicated respiratory therapy units for premature infant populations. Facility construction is accelerating demand for anatomically calibrated cannula systems.
- REACH material compliance:European chemical safety frameworks are mandating silicone alternatives to polyvinyl chloride in prolonged-use devices. Manufacturers with certified polymer supply chains gain accelerated market access.
- Home oxygen therapy reimbursement:Medicaid and private payors in Germany are expanding coverage for pediatric high-flow systems outside institutional settings. Residential care channels are opening to specialized device categories previously restricted to hospitals.
Market Restraints
- Medical-grade silicone supply concentration:Raw material production clusters in Southeast Asian chemical processing zones. Geopolitical friction or shipping disruption propagates directly into device manufacturing lead times.
- EU MDR clinical evidence requirements:Pediatric-specific respiratory accessories now demand extended clinical trial documentation. Smaller manufacturers face capital barriers to sustained regulatory compliance.
- Reusable interface competition:Disinfectable nasal prong systems for adolescent populations threaten single-use volume in developed markets. Cost-conscious procurement committees are piloting sterilization protocols.
Strategic Opportunities
- Indian pediatric homecare penetration:Respiratory specialist networks in Mumbai and Delhi are establishing oxygen therapy rental models for middle-income families. Device-as-a-service structures bypass upfront capital constraints.
- Integrated humidification-cannula systems:Convergence of heated breathing circuits with disposable interfaces is collapsing component count. Manufacturers with thermal control IP can capture value previously distributed across suppliers.
- Japan's aging pediatric infrastructure:METI incentives for neonatal device localization are creating joint-venture pathways. Domestic production certification accelerates hospital procurement cycles.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies require 14-18 month completion timelines. Product development pipelines stall awaiting third-party laboratory capacity.
- Pediatric anatomical modeling expertise:Computational fluid dynamics simulation for infant nasal cavity geometries demands rare cross-training between biomedical engineers and neonatologists. Talent scarcity compresses R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Nasal Cannula Market |
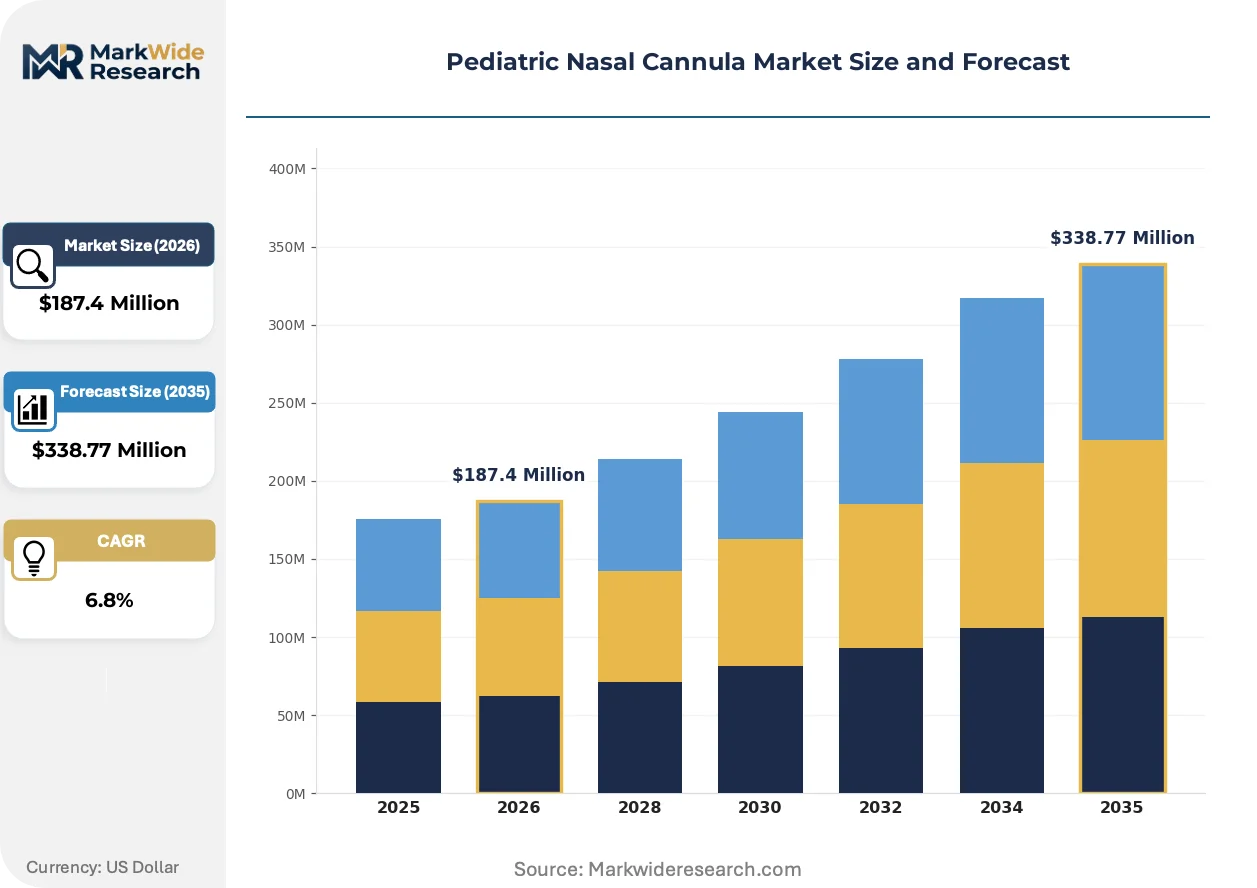
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Cannula, Standard Cannula, High-Flow Cannula, Ultra-Soft Cannula Material: Polyvinyl Chloride, Silicone, Polyethylene, Rubber End User: Pediatric Hospitals, Clinics, Homecare, Emergency Services Application: Oxygen Therapy, Respiratory Support, Sleep Apnea, Asthma Treatment |
| Companies Covered | Fisher & Paykel Healthcare Limited, Teleflex Incorporated, DeVilbiss Healthcare LLC, Besmed Health Business Corp., Flexicare Medical Limited, Salter Labs, Asid Bonz GmbH, Medin Medical Innovations GmbH, GaleMed Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Nasal Cannula Market Evolving Landscape
Silicone polymer formulations are displacing legacy materials as the dominant interface technology, while regulatory frameworks on both sides of the Atlantic tighten evidence requirements for pediatric-specific claims. Distribution channels are fragmenting between institutional procurement consortia and direct-to-homecare logistics networks.
Heated humidification circuits integrated directly into high-flow nasal cannula assemblies are expanding into standard-of-care protocols for bronchiolitis and respiratory syncytial virus management. Pediatric intensive care units in the United States and Germany are adopting these systems at replacement-cycle velocity. The technology is expanding into homecare settings as portable power and thermal control miniaturization collapses the infrastructure requirements for residential deployment.
EU Medical Device Regulation Article 61 now mandates clinical investigation for all class IIa pediatric respiratory accessories, including nasal cannulas previously cleared through equivalence pathways. Manufacturers must generate original safety and performance data rather than referencing predicate devices. Smaller European specialists are responding through consortia arrangements that pool clinical trial costs across non-competing product categories.
Hospital procurement committees are consolidating oxygen therapy purchasing across neonatal, pediatric, and adult service lines under single-source contracts with volume-tier pricing. Traditional distributor relationships in North American academic medical centers are giving way to direct manufacturer agreements with integrated logistics guarantees. This consolidation is most visible in the United States, where health system mergers have created multi-hospital networks with standardized device formularies and centralized inventory management.
Pediatric Nasal Cannula Market Segmentation
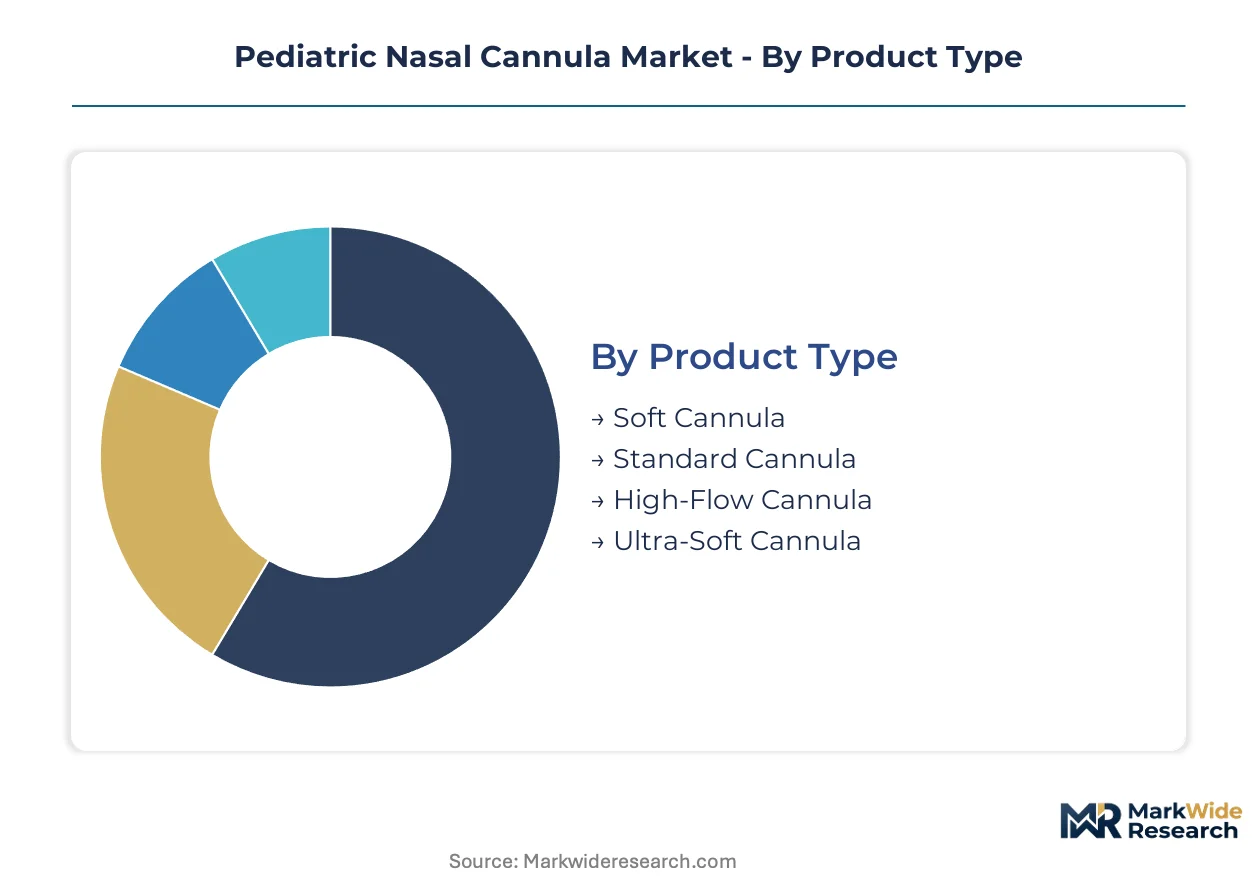
Pediatric nasal cannula procurement patterns diverge sharply across clinical settings, with material selection and flow specifications driving replacement cycles that range from single-use disposables to multi-year capital equipment investments. Understanding these segment boundaries clarifies where manufacturers must configure distinct supply chain and regulatory compliance strategies.
Product Type:
Upgrade cycles in pediatric oxygen delivery are compressing as heated humidification protocols displace legacy low-flow systems in neonatal intensive care units.
- Soft Cannula:Skin-friendly polymer formulations with calibrated prong spacing reduce nasal septum irritation during extended wear periods. Demand concentrates in United States pediatric hospitals scaling dedicated respiratory therapy units for premature infant populations, where clinician preference for biocompatible interfaces drives procurement decisions.
- High-Flow Cannula:Precision-engineered interfaces sustain 8 liters per minute flow rates without mucosal injury through integrated heated breathing circuits. German pediatric intensive care units are adopting these systems at replacement-cycle velocity as Medicaid and private payors expand coverage for residential deployment.
- Standard Cannula:Conventional polymer construction serves cost-sensitive procurement committees in emerging market clinics.
- Ultra-Soft Cannula:Advanced silicone layering targets adolescent populations with heightened skin sensitivity requirements.
Volume placements concentrate in Soft Cannula configurations; the faster expansion belongs to High-Flow Cannula segments.
Material:
Cost tier stratification in raw material sourcing is restructuring competitive positioning as REACH compliance mandates elevate silicone alternatives above commodity polymers.
- Silicone:Medical-grade formulations deliver superior biocompatibility and durability for prolonged-use devices. Production clusters in Southeast Asian chemical processing zones create supply vulnerability, yet European manufacturers with certified polymer supply chains gain accelerated market access under tightening ECHA frameworks.
- Polyvinyl Chloride:Lower-cost option facing displacement as FDA device classification requirements tighten material safety standards for pediatric respiratory accessories. United States hospital procurement committees are phasing PVC from neonatal-specific formularies.
- Polyethylene:Intermediate cost-performance profile serves standard-flow applications in budget-constrained clinical environments.
- Rubber:Legacy material retaining niche presence in emergency services rapid-deployment kits where sterilization cycles are impractical.
Silicone commands premium positioning in developed markets; polyethylene maintains volume leadership in cost-optimized procurement segments.
End User:
Customer type fragmentation is accelerating as home oxygen therapy reimbursement reforms open residential channels previously restricted to institutional settings.
- Pediatric Hospitals:Primary demand concentration for anatomically calibrated cannula systems with ISO 10993 biocompatibility certification. Facility construction across United States academic medical centers is accelerating demand for high-flow configurations with integrated humidification.
- Homecare:Fastest-expanding channel as portable power and thermal control miniaturization collapses infrastructure requirements. Respiratory specialist networks in Mumbai and Delhi are establishing oxygen therapy rental models for middle-income families.
- Clinics:Outpatient settings prioritize standard cannula configurations with simplified inventory management.
- Emergency Services:Pre-hospital care demands ruggedized disposable interfaces with rapid application protocols.
Pediatric Hospitals dominate absolute volume; Homecare is climbing the fastest as reimbursement boundaries shift.
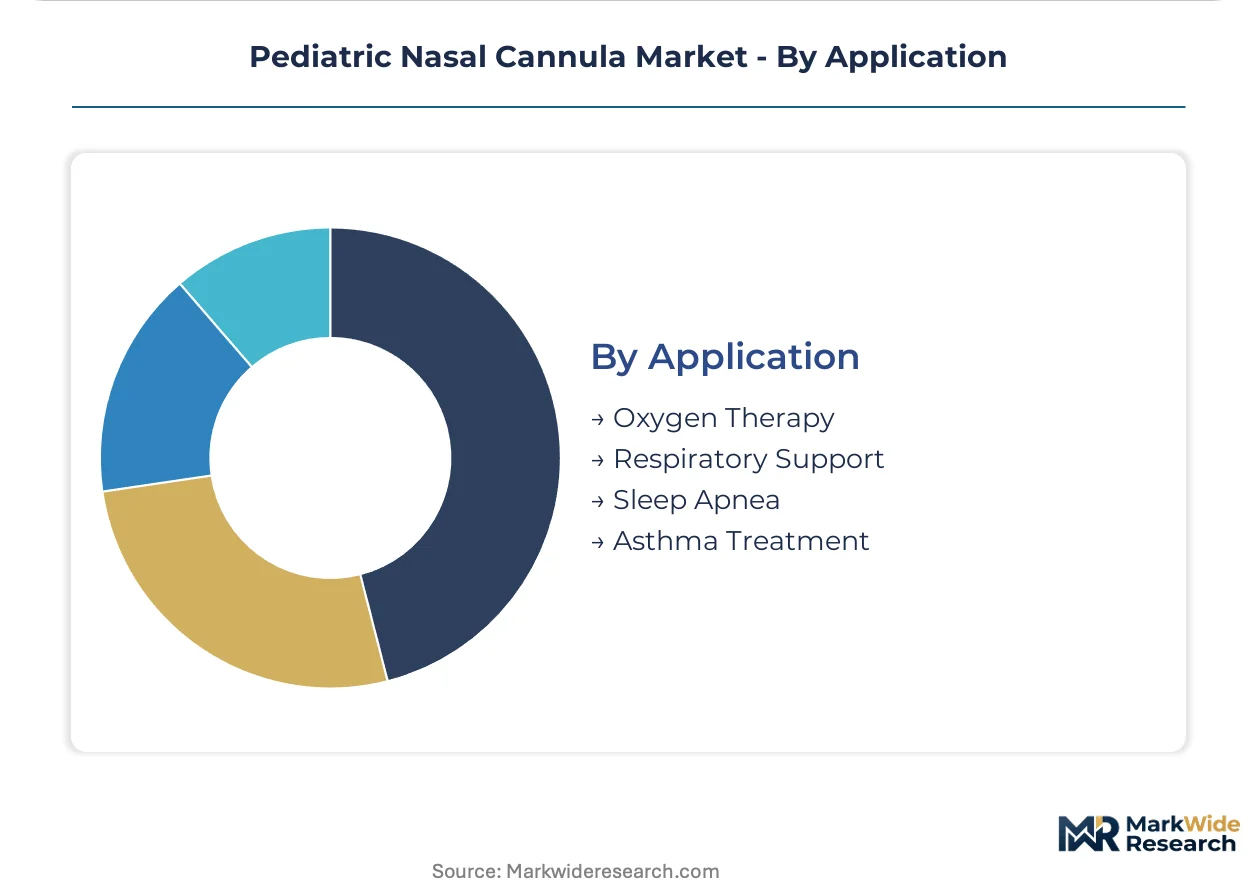
Application:
Application-specific performance requirements are forcing material and design specialization as heated high-flow protocols expand beyond traditional oxygen therapy indications.
- Oxygen Therapy:Core indication spanning low-flow supplemental delivery through high-flow heated systems. United States and Germany are standardizing heated humidification circuits for bronchiolitis and respiratory syncytial virus management.
- Respiratory Support:Critical care applications demand precision-engineered interfaces capable of sustaining elevated flow rates without mucosal injury. EU MDR Article 61 now mandates clinical investigation for class IIa pediatric respiratory accessories in this category.
- Sleep Apnea:Emerging application requiring ultra-soft configurations for nocturnal compliance in adolescent populations.
- Asthma Treatment:Acute exacerbation management drives demand for rapid-deployment standard cannula systems in emergency services.
Oxygen Therapy retains the largest installed base; Respiratory Support is gaining share fastest as ICU protocols advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Southeast Asian chemical processing corridors concentrate medical-grade silicone supply chains that feed device manufacturing clusters worldwide.
United States
Pediatric hospitals are scaling dedicated respiratory therapy units for premature infant populations, with academic medical centers in Boston and Philadelphia driving procurement of heated humidification systems. FDA 510(k) clearance pathways govern device commercialization while tightening material safety standards reshape neonatal-specific formularies. The Southeast health corridor spanning Florida and Georgia anchors multi-hospital network consolidation with standardized device formularies.
Germany
Medicaid and private payors are expanding coverage for pediatric high-flow systems outside institutional settings, opening residential care channels. REACH compliance mandates are elevating silicone alternatives above commodity polymers for prolonged-use devices. The Baden-Württemberg medical technology cluster around Stuttgart hosts specialists in precision-engineered respiratory interfaces.
China
Domestic production certification under NMPA frameworks is accelerating hospital procurement cycles for localized neonatal device manufacturing. Middle-income families in Shanghai and Beijing are accessing oxygen therapy through emerging rental service models. The Yangtze River Delta chemical processing zones supply raw material inputs despite geopolitical friction risks.
India
Respiratory specialist networks in Mumbai and Delhi are establishing device-as-a-service structures that bypass upfront capital constraints for middle-income families. CDSCO regulatory pathways are streamlining import substitution for pediatric respiratory accessories. The Maharashtra pharmaceutical manufacturing belt is incubating contract fabrication capabilities for international OEMs.
Japan
METI incentives for neonatal device localization are creating joint-venture pathways that accelerate hospital procurement cycles. The Kanto region around Tokyo concentrates demand from aging pediatric infrastructure requiring replacement-cycle investment. Domestic production certification is collapsing traditional import dependency for critical care respiratory interfaces.
Pediatric Nasal Cannula Market Competitive Landscape
United States producers anchor the premium-tier supply base; German and New Zealand specialists hold differentiated positions in heated humidification technology. The vendor base fragments across three strategic tiers: multinational respiratory conglomerates with vertically integrated manufacturing, regional specialists with certified polymer supply chains, and contract fabricators serving private-label demand. Consolidation pressures are intensifying as hospital procurement committees consolidate oxygen therapy purchasing under single-source contracts with volume-tier pricing, while REACH compliance and EU MDR clinical evidence requirements filter out capital-constrained smaller manufacturers.
Within the multinational tier, Fisher & Paykel Healthcare Limited and Teleflex Incorporated exemplify divergent geographic anchoring strategies, with the former representing vertically integrated manufacturing advantages and the latter illustrating specialized distribution network positioning. Salter Labs occupies a position within the brand-recognition archetype for homecare oxygen delivery channels. These three entities collectively represent the competitive fault lines between manufacturing control, distribution access, and channel-specific reputation that structure procurement decisions across institutional and residential settings.
| Leading Market Players |
|---|
| Fisher & Paykel Healthcare Limited |
| Teleflex Incorporated |
| DeVilbiss Healthcare LLC |
| Besmed Health Business Corp. |
| Flexicare Medical Limited |
| Salter Labs |
| Asid Bonz GmbH |
| Medin Medical Innovations GmbH |
| GaleMed Corporation |
| Others |
Value Network & Pricing Analysis
Medical-grade silicone feedstock indices in Southeast Asian chemical processing corridors cascade through device manufacturing tiers, compressing margins for polyvinyl chloride-dependent suppliers while rewarding REACH-certified European manufacturers with pricing power in institutional procurement channels.
Pricing Analysis
Lead-time-driven pricing stratification separates emergency stock replenishment premiums from scheduled contract volumes in pediatric hospital procurement. Three-tier pricing structure across premium silicone, intermediate polyethylene, and economy PVC levels reflects ISO 10993 certification grades and thermal control integration depth. Pricing pressure stems from reusable interface pilots in adolescent care segments. Cost-conscious procurement committees in emerging market clinics exhibit highest price sensitivity; United States academic medical centers with consolidated GPO contracts demonstrate lowest.
Supply Chain Analysis
Dual-sourcing mandates from United States pediatric hospital networks and German procurement consortia require qualified silicone suppliers in Malaysia, Thailand, and Vietnam alongside secondary polymer streams. Raw material flows draw from Southeast Asian chemical zones for medical-grade silicone, Yangtze River Delta for precision-molded components, and Baden-Württemberg for thermal control subassemblies. Single-source vulnerability concentrates in heated humidification circuit foundries. Distribution runs through specialized respiratory device distributors and direct manufacturer agreements with multi-hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pediatric nasal cannula market is accelerating into a vertical-integration race as manufacturers pursue captive control over medical-grade silicone polymerization to secure REACH compliance and compress raw material lead times.
For Market Incumbents: Hedge silicone supply exposure through backward integration into certified polymer production or long-term offtake agreements with Southeast Asian chemical processors. Reinforce hospital system partnerships against emerging device-as-a-service rental models in Indian metropolitan markets. Prioritize thermal control IP development to capture value from integrated humidification-cannula convergence. For New Entrants and Emerging Players: Begin with homecare oxygen therapy channels in Mumbai and Delhi where rental service structures bypass upfront capital barriers for middle-income families. Target CDSCO streamlined pathways for import substitution in Maharashtra's pharmaceutical manufacturing belt. Pursue joint-venture localization under Japan METI incentives to accelerate domestic production certification cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European specialists with EU MDR clinical evidence packages but constrained capital for scaled manufacturing in the current regulatory environment. Long-term viability hinges on consolidation resilience across the projection horizon as hospital procurement committees centralize oxygen therapy purchasing. Watch for FDA material safety standard tightening as inflection signal for silicone displacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Polymerization | Captive supply of REACH-certified medical-grade polymer secures European market access against ECHA enforcement waves. |
| Integrated Humidification-Cannula System Development | Thermal control IP capture collapses component count and displaces separate heated circuit suppliers in pediatric ICUs. |
| Device-as-a-Service Rental Model Deployment | Respiratory specialist networks in Indian metropolitan markets bypass upfront capital constraints for middle-income family access. |
| EU MDR Article 61 Clinical Investigation Completion | Original safety data generation replaces equivalence pathways and filters capital-constrained competitors from class IIa pediatric accessories. |
| Joint-Venture Localization under METI Incentives | Domestic production certification in Japan's Kanto region collapses import dependency for critical care respiratory interfaces. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR clinical investigation filings, and REACH compliance certification rates anchored the trend analysis, supplemented by interviews with neonatologists, biomedical engineers, hospital GPO contracts managers, and respiratory device procurement leads. Secondary validation drew from FDA 510(k) databases, EUDAMED device registrations, ISO 10993 biocompatibility test reports, and hospital procurement database extracts. Bottom-up volume triangulation across product type, material, and end-user segments converged with top-down market sizing.
Segment-weighting approaches distributed value and volume across soft cannula, high-flow cannula, standard cannula, and ultra-soft cannula configurations, with material-grade stratification between silicone, polyvinyl chloride, polyethylene, and rubber tiers. End-user segmentation captured pediatric hospitals, homecare, clinics, and emergency services channels. CAGRs were derived from replacement-cycle velocity analysis in neonatal intensive care units and reimbursement policy trajectory modeling for residential oxygen therapy deployment. Forecast inputs incorporated heated humidification protocol adoption curves and regulatory compliance cost escalation pathways.
Silicone feedstock price volatility, EU MDR clinical evidence requirement enforcement intensity, and homecare reimbursement policy reversals are the dominant revision risks to the outlook. Deviation in FDA material safety standard tightening velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Global Pediatric Clinical Trials Market
Pediatrics
Autism Service Platform Market
Pediatrics
Pediatric Tube Feeding Market
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Pediatric Home Healthcare Market
Pediatrics
Paediatric Spasticity Treatment Market
Pediatrics
Pediatric Dental Market
Pediatrics
Global Pediatric Neuroblastoma Treatment Market
Pediatrics
Global Pediatric Radiology Market
Pediatrics
Global Pediatric Home Healthcare Services Market
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Pediatric Brain Tumor Market