
 Bronchial Biopsy Devices Market | 2026-2036
Bronchial Biopsy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Bronchial Biopsy Devices Market Analytics
The single-use specification tier is collapsing the installed base of reusable bronchial biopsy instruments in tertiary care settings. Medtronic leverages its integrated respiratory diagnostics platform to sustain procedure volume capture across North American hospital networks. Olympus Corporation anchors its competitive stance through proprietary imaging channels that pair with captive biopsy tool sets. Boston Scientific Corporation differentiates via catheter-based delivery systems that navigate tortuous airway anatomy.
Bronchial biopsy devices comprise instruments designed to extract tissue specimens from the tracheobronchial tree through flexible or rigid bronchoscopic channels, typically incorporating stainless steel forceps jaws with electrocautery compatibility or cryogenic probes operating at minus 40 to minus 70 degrees Celsius for transbronchial sampling. These devices serve the primary purpose of obtaining histopathological and molecular diagnostic material to confirm malignancy, characterize interstitial lung disease, or identify infectious pathogens. Flexible bronchoscope-compatible forceps retain the dominant volume position due to procedural familiarity and capital equipment ubiquity, while cryobiopsy devices represent the fastest-expanding category as interventional pulmonologists adopt larger specimen protocols for diffuse parenchymal disease. Molecular diagnostics integration within tissue sampling workflows is concentrating margin pools in academic medical centers with on-site pathology laboratories.
The FDA regulates bronchial biopsy devices under Class II medical device controls with 510(k) premarket notification requirements, while the EU Medical Device Regulation mandates notified body conformity assessment and post-market surveillance through EUDAMED. The EPA's reprocessing guidance for semi-critical bronchoscopes indirectly shapes single-use biopsy tool demand by elevating sterilization validation burdens. Stakeholders must monitor reimbursement alignment between tissue acquisition procedures and downstream genomic testing codes.
Market Dynamics
Single-use bronchial biopsy instruments are displacing reusable forceps in tertiary hospitals as sterilization validation costs escalate and infection control protocols tighten. This substitution wave is compressing capital equipment cycles while fragmenting procurement decisions across pulmonology departments and central supply chains.
Growth Catalysts
- EU MDR post-market surveillance mandates:The EU Medical Device Regulation's EUDAMED reporting requirements are accelerating hospital transitions to single-use biopsy tools with established traceability records.
- Cryobiopsy protocol adoption:Interventional pulmonology societies in Germany and the United States are endorsing larger specimen retrieval methods for diffuse parenchymal disease characterization.
- Molecular diagnostics integration:Academic medical centers with on-site pathology laboratories are bundling tissue acquisition with genomic testing workflows, concentrating procedure volumes.
Market Restraints
- Stainless steel supply concentration:Forceps jaw manufacturing depends on specialized German and Japanese metallurgical suppliers with limited surge capacity.
- 510(k) pathway friction:The FDA's updated substantial equivalence criteria for electrocautery-compatible accessories are extending clearance timelines for novel device submissions.
- Capital equipment lock-in:Rigid bronchoscope installed bases in Eastern European public hospitals create technical barriers to flexible catheter adoption.
Strategic Opportunities
- India's CDSCO streamlined Class B approvals:The national regulator's risk-based classification reforms are reducing entry barriers for cryobiopsy device manufacturers.
- Community hospital outpatient bronchoscopy:Ambulatory surgical centers in the United States are expanding screening programs outside traditional academic networks.
- Artificial intelligence-histopathology convergence:Real-time specimen adequacy assessment tools are enabling point-of-care diagnostic confirmation during biopsy procedures.
Industry Challenges
- Interventional pulmonology fellowship scarcity:Advanced bronchoscopy training programs in the United States and Germany are producing insufficient specialists to match screening program expansion.
- Reimbursement code misalignment:Tissue acquisition procedures and downstream genomic testing codes lack coordination across Medicare, commercial payers, and hospital billing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bronchial Biopsy Devices Market |
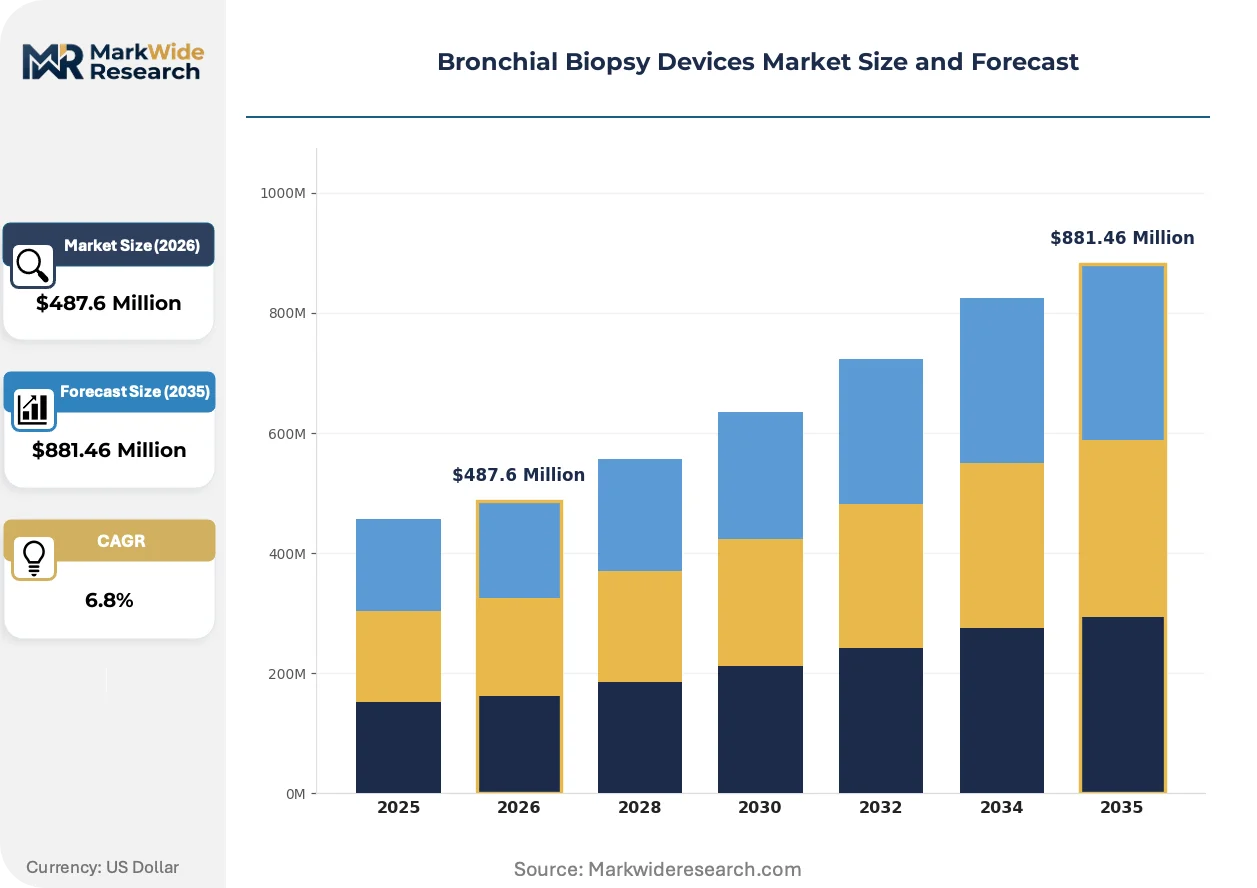
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Flexible Bronchoscope, Endobronchial Biopsy Forceps, Transbronchial Needle, Cryobiopsy Device Application: Lung Cancer Diagnosis, Infection Detection, Inflammatory Disease Analysis, Tissue Sampling End User: Hospitals, Diagnostic Laboratories, Outpatient Clinics, Research Institutions Technology: Image-guided Biopsy, Robotic-assisted Biopsy, Manual Biopsy, Molecular Diagnostics |
| Companies Covered | Medtronic, Olympus Corporation, Boston Scientific Corporation, CONMED Corporation, Becton, Dickinson and Company, Cook Medical, Argon Medical Devices, Johnson & Johnson, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bronchial Biopsy Devices Market Evolving Landscape
Technological differentiation is bifurcating the competitive landscape between imaging-integrated platforms and standalone disposable instruments. Three convergent forces are reshaping how tissue sampling devices are designed, regulated, and procured across hospital systems.
Cryogenic probe technology is bifurcating the specimen quality debate in interstitial lung disease diagnosis. Academic medical centers in Germany and the United States are adopting minus 70 degrees Celsius protocols for larger tissue samples. This thermal approach is compressing the market position of traditional forceps in diffuse parenchymal disease applications.
The FDA's updated 510(k) pathway for reusable endoscopic accessories is elevating sterilization validation documentation requirements. Device manufacturers face expanded biocompatibility testing for electrocautery-compatible components. United States-based pulmonology departments are responding by accelerating single-use substitution cycles to bypass reprocessing liability exposure.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases. Third-party reprocessors and independent service organizations are capturing maintenance revenue previously retained by original equipment manufacturers. This disintermediation is most visible in United States health systems with centralized supply chain governance and multi-hospital network contracts.
Bronchial Biopsy Devices Market Segmentation
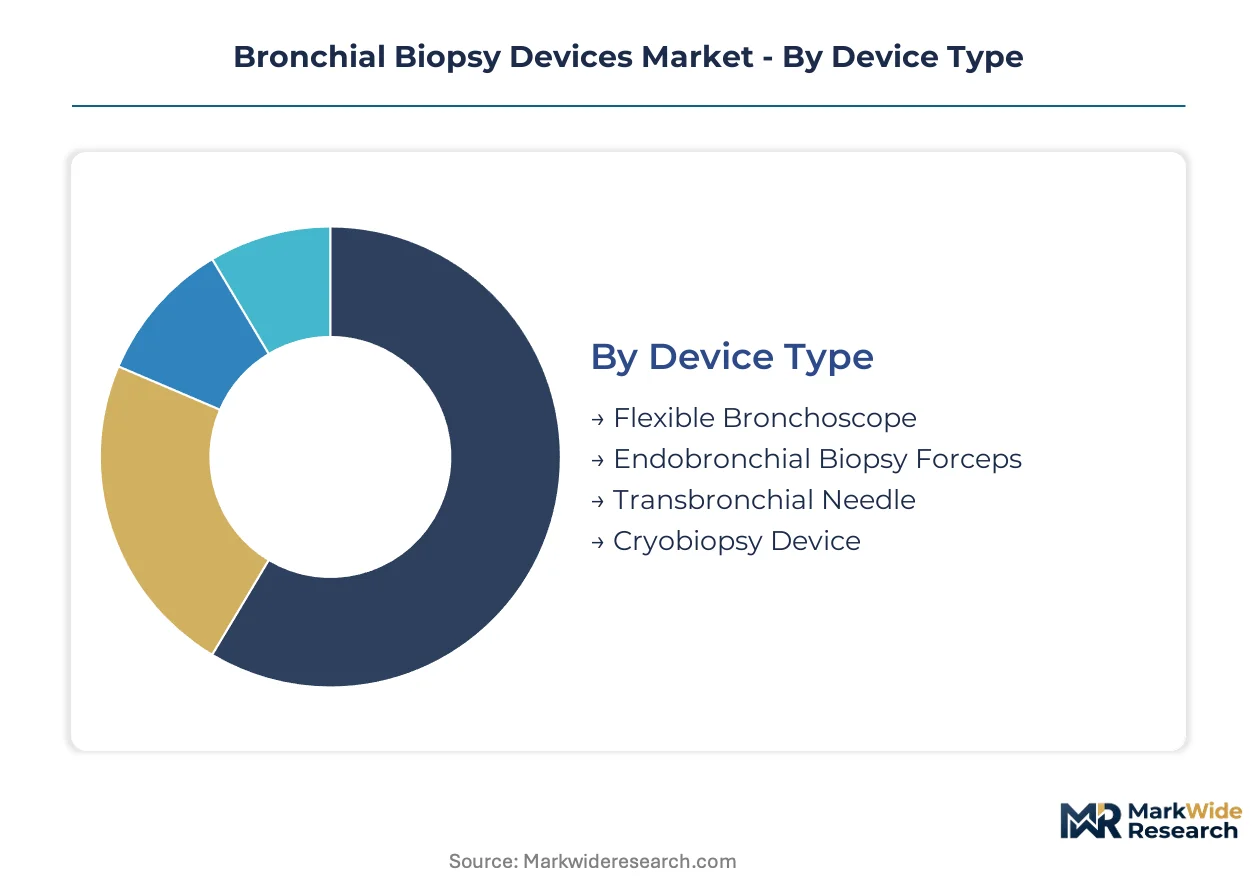
Device categorization in bronchial biopsy instruments tracks how procedural settings shape procurement patterns across tertiary hospitals and ambulatory networks. Segment boundaries reflect competing pressures between capital equipment longevity and single-use infection control protocols.
Device Type:
Domestic manufacturing clusters in Germany and Japan anchor forceps production, while cryobiopsy device assembly concentrates in United States and Swiss contract facilities serving export markets.
- Flexible Bronchoscope:Fiberoptic or video-based insertion platforms with working channels accommodating 2.0-2.8mm instruments. Demand clusters in United States academic medical centers upgrading from fiberoptic to digital video systems.
- Endobronchial Biopsy Forceps:Stainless steel jaw instruments with cupped or alligator configurations for mucosal sampling. German hospital procurement committees are mandating single-use specifications to satisfy EU MDR traceability requirements.
- Transbronchial Needle:21-22 gauge aspiration devices for mediastinal lymph node sampling via bronchial wall puncture.
- Cryobiopsy Device:Probe systems using compressed gas or Joule-Thomson expansion for transbronchial lung biopsy.
Endobronchial biopsy forceps command the established base. The steepest expansion runs through cryobiopsy devices.
Application:
Procedure reimbursement alignment varies sharply across diagnostic categories, with cancer staging protocols commanding premium tissue acquisition workflows.
- Lung Cancer Diagnosis:Staging and histopathological confirmation of primary or metastatic pulmonary malignancies. United States hospital networks bundle these procedures with PET-CT navigation and on-site cytology evaluation.
- Infection Detection:Pathogen identification in immunocompromised hosts or treatment-resistant pneumonia. Diagnostic laboratories in India are expanding TB molecular testing capacity using bronchial wash and biopsy specimens.
- Inflammatory Disease Analysis:Interstitial lung disease characterization through histopathological pattern recognition.
- Tissue Sampling:General specimen acquisition for unspecified diagnostic workups or research biobanking.
Lung cancer diagnosis captures the revenue concentration. Infection detection applications are climbing fastest in high-TB-burden geographies.
End User:
Capital equipment purchasing authority fragments differently across facility types, with centralized supply chains dominating multi-hospital systems.
- Hospitals:Inpatient and outpatient bronchoscopy suites with integrated pathology and imaging infrastructure. German tertiary centers are consolidating interventional pulmonology services into dedicated thoracic procedure units.
- Diagnostic Laboratories:Independent reference labs processing externally collected specimens. United States commercial labs are building direct-to-physician bronchoscopy partnerships to secure tissue volumes.
- Outpatient Clinics:Ambulatory surgical centers performing screening bronchoscopies without overnight admission.
- Research Institutions:Academic biobanks and clinical trial networks requiring standardized tissue collection protocols.
Hospitals retain the installed base dominance. Outpatient clinics represent the steepest volume trajectory as screening decentralizes.
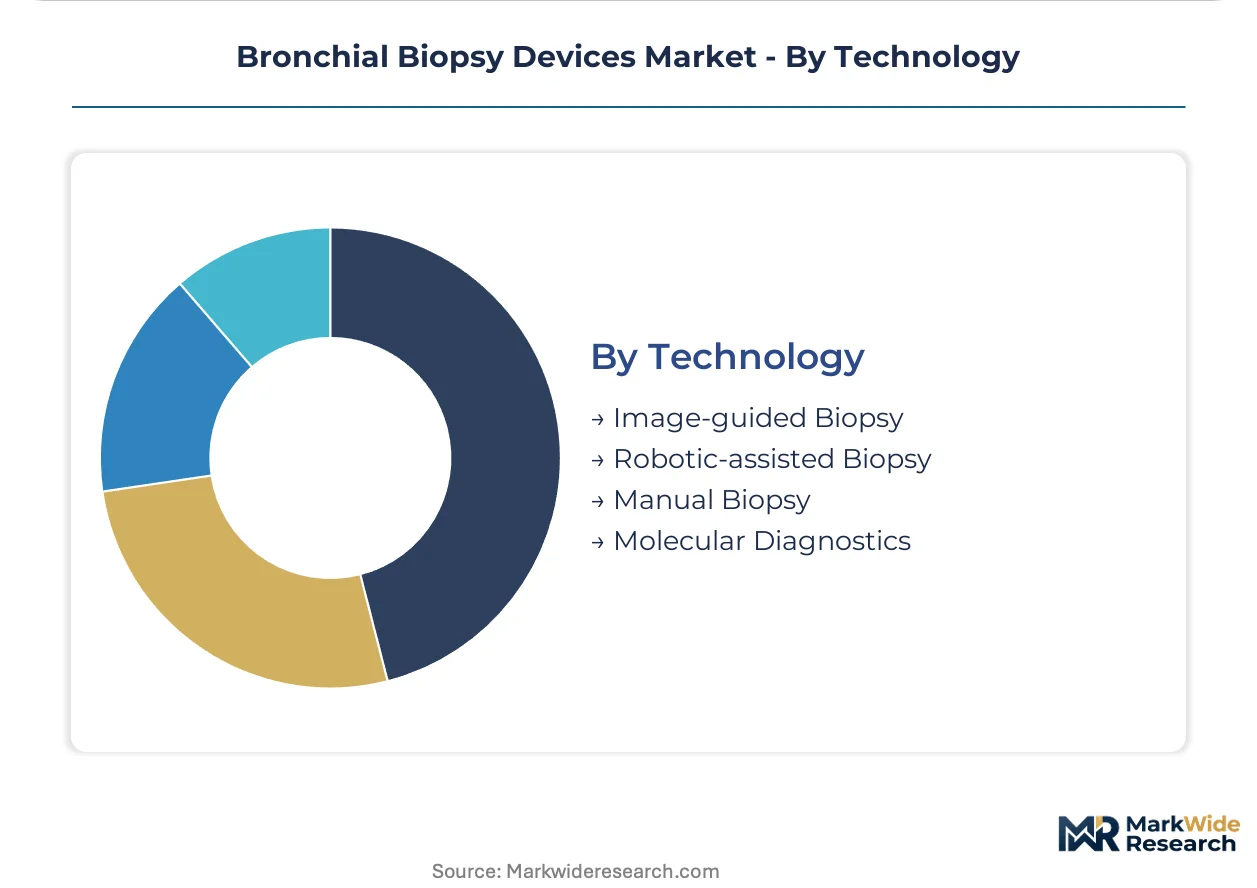
Technology:
Regulatory clearance pathways diverge sharply between hardware-based and software-integrated biopsy modalities.
- Image-guided Biopsy:Electromagnetic navigation or cone-beam CT overlay for peripheral lesion targeting. United States academic centers are pairing these systems with robotic bronchoscope platforms to reduce fluoroscopy exposure.
- Robotic-assisted Biopsy:Articulated catheter systems with remote operator control for peripheral nodule access. Japanese regulatory approvals for these systems are proceeding through PMDA's novel device review track.
- Manual Biopsy:Conventional operator-directed instrument manipulation without computational guidance.
- Molecular Diagnostics:Integrated genomic testing workflows from tissue acquisition to variant reporting.
Manual biopsy holds the procedure volume base. Robotic-assisted platforms are gaining share fastest among early-adopter health systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a persistent trade surplus in precision-engineered biopsy forceps components, while the United States and Japan remain net importers of finished cryobiopsy systems despite strong domestic R&D bases. Import dependency concentrates in specialized metallurgical feedstocks and electrocautery-compatible instrument coatings.
United States
Hospital-based screening program expansion drives demand for single-use bronchial biopsy instruments across academic medical centers. The FDA's updated 510(k) pathway for reusable endoscopic accessories accelerates device substitution cycles. Boston Scientific Corporation anchors interventional pulmonology supply chains through catheter-based delivery platforms.
Germany
National lung cancer screening guidelines mandate tissue confirmation protocols, concentrating procurement authority in tertiary thoracic procedure units. The EU Medical Device Regulation's EUDAMED reporting requirements elevate traceability standards for biopsy tool suppliers. Baden-Württemberg manufacturing clusters specialize in stainless steel forceps jaw production for export markets.
Japan
PMDA's novel device review track processes regulatory approvals for robotic-assisted bronchoscope platforms. Aging demographics expand early-stage lung cancer detection programs in metropolitan hospital networks. Tokyo-based academic centers pioneer electromagnetic navigation integration with flexible biopsy systems.
India
TB molecular testing capacity expansion drives bronchial specimen acquisition demand in diagnostic laboratories. CDSCO's streamlined Class B approval reforms reduce entry barriers for cryobiopsy device manufacturers. Maharashtra and Gujarat host emerging domestic assembly operations serving South Asian export markets.
Switzerland
Swissmedic conformity assessment procedures align with EU MDR standards for cross-border device distribution. Precision manufacturing clusters in the Basel region supply cryogenic probe components to German and United States OEMs. Research institutions standardize tissue collection protocols for pan-European clinical trial networks.
Bronchial Biopsy Devices Market Competitive Landscape
Listed leaders compete with private specialists across capital equipment financing and disposable instrument procurement channels. The vendor base organizes into three tiers: integrated respiratory diagnostics platforms, standalone imaging system manufacturers, and catheter-based navigation specialists. Strategic moves concentrate on service contract unbundling and third-party reprocessor partnerships.
Among United States-based multinationals, Medtronic, Boston Scientific Corporation, and Stryker Corporation exemplify divergent competitive archetypes. Medtronic occupies a position as an integrated platform provider spanning capital equipment through consumables. Boston Scientific Corporation represents catheter-based navigation specialization for tortuous airway anatomy. Stryker Corporation anchors the orthopedic-interventional crossover segment with hospital supply chain leverage.
| Leading Market Players |
|---|
| Medtronic |
| Olympus Corporation |
| Boston Scientific Corporation |
| CONMED Corporation |
| Becton, Dickinson and Company |
| Cook Medical |
| Argon Medical Devices |
| Johnson & Johnson |
| Stryker Corporation |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day forceps jaw lead times from Baden-Württemberg metallurgical suppliers concentrate pricing power with German component manufacturers, while United States hospital procurement committees exploit single-use substitution trends to compress OEM margins through competitive bidding.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for stainless steel forceps assemblies, with price differentiation resting on ISO 13485 certification tier and after-sales service bundling. Cost compression in standard-grade disposable instruments is intensifying because third-party reprocessors are capturing maintenance revenue previously retained by original equipment manufacturers. Academic medical centers with integrated pathology laboratories show the least price sensitivity due to bundled genomic testing workflows, while community hospital outpatient clinics face acute margin pressure from centralized GPO contracting.
Supply Chain Analysis
Germany and Japan anchor precision-engineered forceps jaw production, while United States and Swiss contract facilities concentrate cryobiopsy device assembly for export markets. Manufacturing draws from specialized German and Japanese metallurgical feedstocks, electrocautery-compatible instrument coatings, and compressed gas cryogenic systems. Single-source vulnerability in stainless steel supply creates exposure to surge capacity constraints. Distribution runs through hospital supply chain governance structures and multi-hospital network contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bronchial Biopsy Devices Market is recovering from sterilization validation cost inflation as single-use substitution cycles accelerate procedure volume expansion.
For Market Incumbents: Shield installed base positions through backward integration into stainless steel component manufacturing and captive supply of electrocautery-compatible coatings. Consolidate service contract revenue by acquiring independent service organizations before third-party reprocessors capture maintenance streams. The EU MDR's EUDAMED traceability mandates favor incumbents with established quality management systems. For New Entrants and Emerging Players: Third-party reprocessor service gaps in United States health systems with centralized supply chain governance offer immediate white-space capture. Target India's CDSCO streamlined Class B approval pathway for cryobiopsy device market entry, where TB molecular testing capacity expansion drives specimen acquisition demand. A direct-to-laboratory go-to-market angle bypasses entrenched hospital procurement committees. For Investors and Strategic Acquirers: Long-term, this sits as a diagnostics-platform consolidation play because molecular diagnostics integration concentrates margin pools in academic medical centers with on-site pathology laboratories. Acquisition targets should display vertical integration into proprietary imaging channels or catheter-based navigation specialization. Watch interventional pulmonology fellowship graduation rates as the inflection signal for procedure volume sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment accelerates single-use device substitution across German hospital networks. |
| Hospital System Partnership | Bundled tissue acquisition with genomic testing workflows concentrates procedure volumes in academic centers. |
| Software Companion Development | Real-time specimen adequacy assessment tools enable point-of-care diagnostic confirmation during biopsy. |
| Reimbursement Strategy | Alignment between tissue acquisition procedures and downstream genomic testing codes unlocks commercial payer coverage. |
| Backward Integration | In-house production of stainless steel forceps jaws mitigates supply concentration risk from German metallurgical suppliers. |
Research Methodology
Initial hypotheses were tested against primary input from interventional pulmonologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR EUDAMED surveillance data, CMS Medicare reimbursement codes, and hospital procurement databases. Bottom-up procedure volume estimates were cross-checked with top-down capital equipment shipment analysis.
Variance in projected values decomposes across device type, application category, end-user facility tier, and technology modality segmentation dimensions. CAGRs were derived from modeled adoption curves for cryobiopsy protocols and single-use substitution rates, calibrated against interventional pulmonology fellowship training capacity and national lung cancer screening guideline implementation timelines.
Forecasts assume regulatory continuity in FDA Class II controls and EU MDR post-market surveillance regimes; material policy shifts in sterilization validation requirements or reimbursement code bundling would require re-modeling. Recalibration cycles align with material shifts in screening program expansion, molecular diagnostics integration, and supply chain concentration events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Calprotectin Serum Immunoassay Market
Diagnostic Devices
Diagnostic Ophthalmic Devices Market
Diagnostic Devices
Animal Pregnancy Test Kits Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
Procalcitonin Antibody Market
Diagnostic Devices
Thrombus Precursor Protein Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Non-Hospital-Based Point-Of-Care Diagnostic Products Market
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Navigated Biopsy Needles Market
Diagnostic Devices
Pulmonary Function Testing Devices Market
Diagnostic Devices
Breathalyzers Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
Breath Samplers Market
Diagnostic Devices
Companion Diagnostics Market