
 Global Breath Analyzer Market | 2026-2036
Global Breath Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Breath Analyzer Market Foresight
Aftermarket calibration and certification services is reconfiguring profit pools away from hardware sales across the breath analyzer value chain. Drägerwerk AG & Co. KGaA leverages its German manufacturing base to dominate evidential-grade systems for law enforcement. Lifeloc Technologies, Inc. specializes in portable workplace testing units with rapid response protocols. Intoximeters, Inc. anchors its position through long-term service contracts with US state police laboratories.
A breath analyzer measures volatile compounds in exhaled breath through sensor-based detection systems, typically employing fuel cell or infrared spectroscopy technologies with detection thresholds measured in parts per thousand for blood alcohol concentration equivalence. These devices serve law enforcement evidentiary testing, occupational safety compliance, and clinical metabolic screening applications. Fuel cell sensor technology leads in accuracy-sensitive segments where evidential standards apply, while semiconductor sensor designs occupy cost-driven personal monitoring applications. Portable form factors represent the fastest-expanding category as workplace testing decentralizes beyond fixed-site installations.
FDA 510(k) clearance requirements shape US market access for clinical and law enforcement devices, while EU Green Deal sustainability mandates and REACH substance restrictions influence material selection for European manufacturers. Germany's KBA and France's ANSM apply additional national performance certifications that fragment compliance pathways. Stakeholders must monitor evolving sensor accuracy standards and cross-jurisdictional certification reciprocity as procurement specifications tighten across government agencies and occupational health services.
Market Dynamics
Fuel cell sensor miniaturization is compressing device footprints while tightening accuracy tolerances, forcing manufacturers to reconfigure production lines around precision electrochemical assembly rather than semiconductor batch processing.
Growth Catalysts
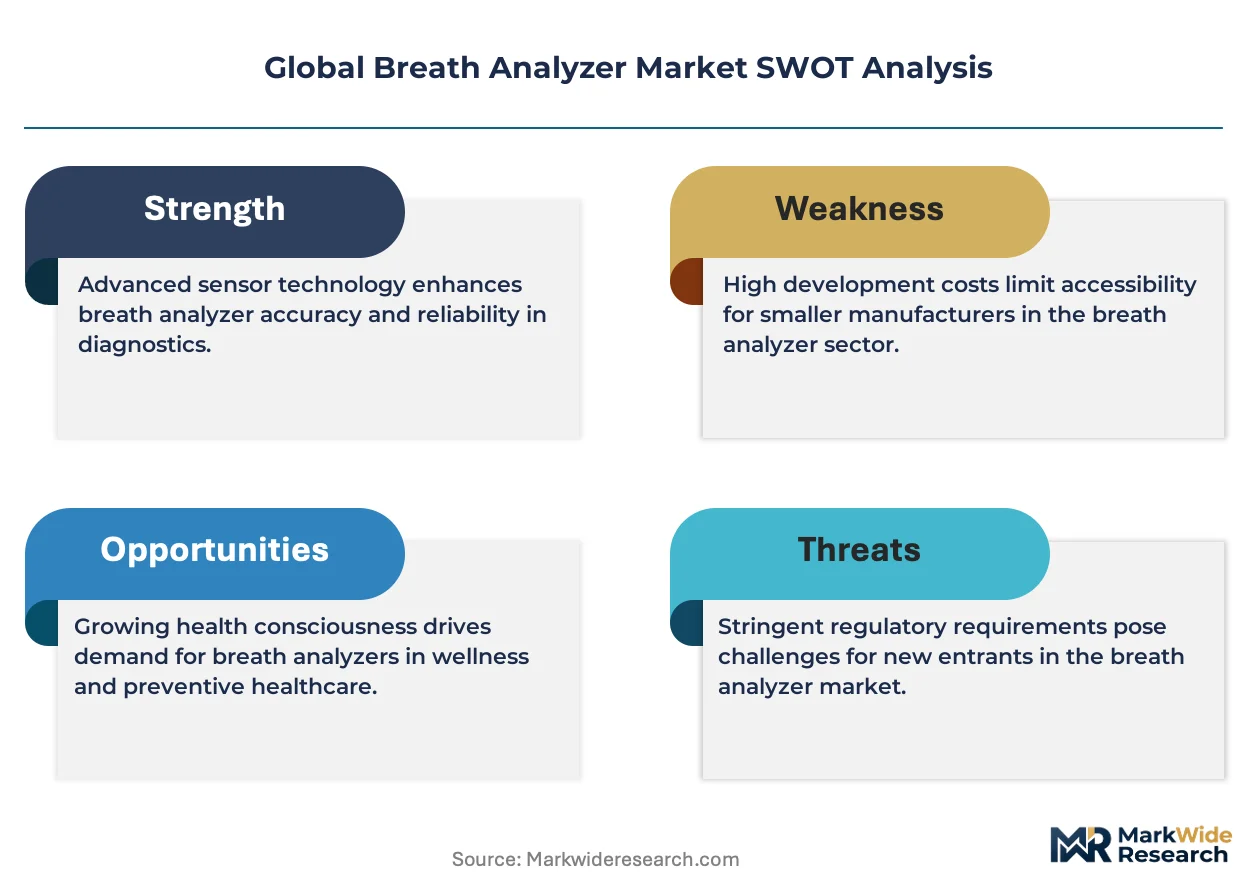
- OSHA workplace testing mandates:US Department of Labor rules for commercial transportation and hazardous materials handling are expanding mandatory screening protocols across logistics fleets and industrial facilities.
- Fuel cell accuracy thresholds:Evidential-grade detection precision measured in parts per thousand is displacing semiconductor sensors in law enforcement procurement specifications.
- German federal police standards:KBA certification requirements for roadside testing devices are creating reference specifications that neighboring European enforcement agencies adopt.
Market Restraints
- Platinum catalyst cost volatility:Fuel cell electrodes depend on platinum group metal prices that fluctuate with South African mining output and automotive catalytic converter demand.
- Calibration infrastructure concentration:Certified reference gas suppliers cluster in Germany and the United States, creating cross-border logistics dependencies for device maintenance.
- Semiconductor sensor accuracy ceiling:Metal oxide detection platforms cannot achieve evidential-grade precision required for criminal prosecution, limiting their addressable market to personal monitoring.
Strategic Opportunities
- India commercial vehicle screening:Motor Vehicles Act amendments and state-level transport enforcement expansion are opening fleet-installed breathalyzer mandates.
- Clinical metabolic screening convergence:Integration of volatile organic compound detection with diabetes monitoring and respiratory diagnostics is creating hospital laboratory demand.
- EU Green Deal material compliance:REACH substance restrictions and battery directive requirements are favoring manufacturers with established European supply chain auditing.
Industry Challenges
- FDA 510(k) clearance timelines:Clinical and law enforcement device categories face 12-18 month regulatory review cycles that delay product launches and compress revenue recognition windows.
- Electrochemical engineer scarcity:Fuel cell design expertise concentrates in automotive and aerospace sectors, forcing breathalyzer manufacturers to compete for specialized talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Breath Analyzer Market |
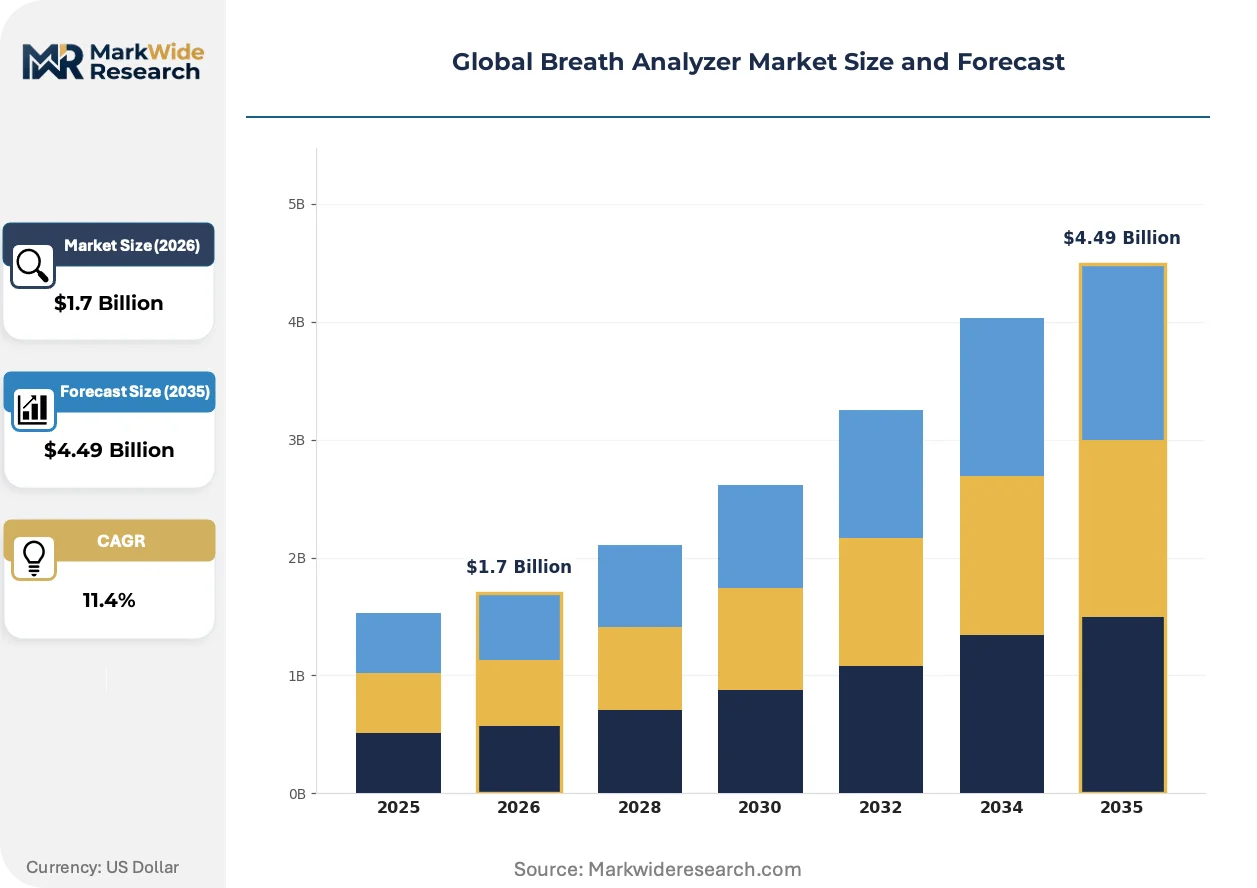
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Desktop, Wearable, Disposable Technology: Infrared Spectroscopy, Semiconductor Sensor, Fuel Cell Sensor, Electrochemical Sensor Application: Law Enforcement, Workplace Testing, Clinical Diagnostics, Personal Monitoring End User: Government Agencies, Occupational Health Services, Medical Facilities, Individual Consumers |
| Companies Covered | Drägerwerk AG & Co. KGaA, Lifeloc Technologies, Inc., Intoximeters, Inc., Alcohol Countermeasure Systems Corp., BACtrack, Quest Products, Inc., Lion Laboratories, Bedfont Scientific Ltd., AK GlobalTech Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Breath Analyzer Market Shifts & Advancements
Connected device architectures and cloud-based calibration management are transforming breath analyzers from standalone instruments into integrated compliance platforms, altering how buyers evaluate total cost of ownership.
Photonic integrated circuits are digitizing infrared spectroscopy detection, enabling multi-compound analysis beyond ethanol in compact form factors. Occupational health services in German industrial clusters are piloting these systems for simultaneous alcohol and drug screening. The technology is digitizing compliance workflows by embedding automated chain-of-custody documentation directly into sensor output streams.
EU MDR classification expansion is redefining clinical breath analyzers as Class IIa medical devices, triggering quality management system audits and post-market surveillance obligations. Manufacturers serving hospital laboratories must now maintain clinical evidence portfolios that parallel pharmaceutical device requirements. French ANSM has issued supplementary guidance on metabolic screening claims that exceeds baseline EU harmonized standards.
Aftermarket service unbundling is separating hardware procurement from calibration certification contracts, particularly in North American workplace testing programs. Third-party service providers now compete directly with original equipment manufacturers for recurring revenue streams. This shift is most visible in US logistics fleets where procurement departments negotiate multi-year calibration agreements independent of initial device purchases.
Global Breath Analyzer Market Segmentation
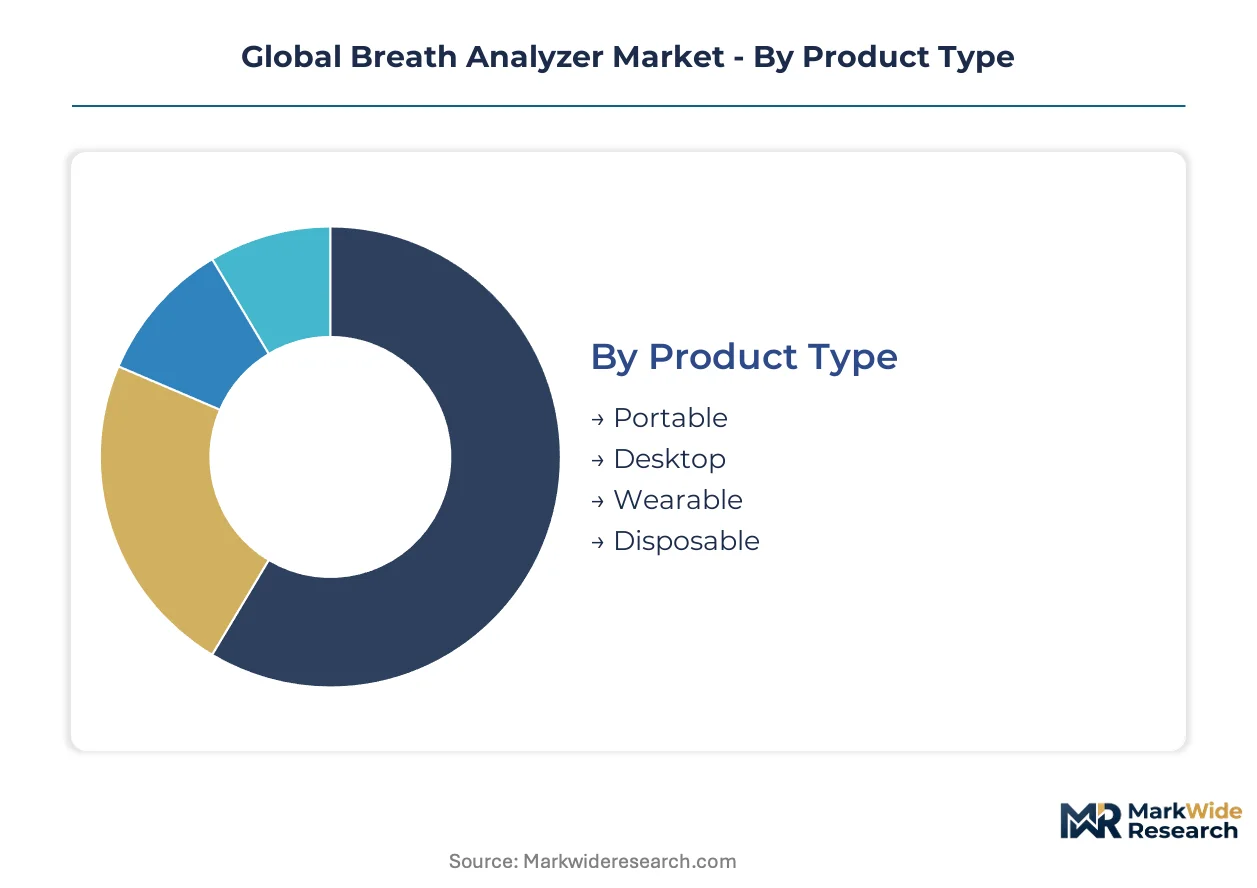
Segmentation in the breath analyzer market determines service contract structures and calibration frequency requirements. Procurement specifications diverge sharply across law enforcement, workplace, and clinical settings, with each vertical imposing distinct accuracy thresholds and maintenance protocols.
Product Type:
After-sales service intensity varies dramatically by form factor, with portable units demanding field calibration networks and desktop systems requiring laboratory-grade maintenance infrastructure.
- Portable:Handheld devices with fuel cell or semiconductor sensors dominate roadside testing and logistics fleet screening. German federal police procurement and US OSHA workplace mandates are compressing device footprints while expanding deployment volumes across enforcement and occupational health settings.
- Desktop:Stationary instruments with infrared spectroscopy or fuel cell technology anchor evidential-grade testing in police laboratories and hospital facilities. These systems command premium pricing tied to KBA certification and FDA 510(k) clearance pathways, with multi-year service contracts representing substantial recurring revenue.
- Wearable:Continuous monitoring bracelets and personal devices integrate semiconductor or electrochemical sensors for probation programs and personal health tracking.
- Disposable:Single-use breathalyzer units with chemical reaction indicators serve event-based screening and emergency response applications.
Desktop holds the largest share; momentum sits with portable.
Technology:
Cost tier stratification separates precision electrochemical platforms from commodity semiconductor alternatives, with platinum catalyst expenses and calibration complexity driving total cost of ownership divergence.
- Fuel Cell Sensor:Electrochemical detection using platinum catalysts achieves parts-per-thousand accuracy for evidential standards. German KBA certification and US state police laboratory procurement concentrate demand in this segment, though South African platinum price volatility constrains margin stability.
- Infrared Spectroscopy:Photonic integrated circuits enable multi-compound detection beyond ethanol in compact footprints. Pilot deployments in German industrial clusters for simultaneous alcohol and drug screening are validating clinical metabolic screening claims.
- Semiconductor Sensor:Metal oxide detection platforms occupy personal monitoring and preliminary screening where evidential precision is not required.
- Electrochemical Sensor:Amperometric detection methods serve clinical diagnostics and specialized metabolic screening with intermediate accuracy positioning.
Fuel cell sensor holds the largest share; infrared spectroscopy is climbing the fastest.
Application:
Customer type determines procurement authority structure, with government tenders, occupational health contracts, hospital purchasing committees, and direct-to-consumer channels operating on entirely different decision cycles.
- Law Enforcement:Evidential-grade testing for criminal prosecution requires KBA, FDA 510(k), or equivalent national certifications. German federal police standards and US state laboratory contracts anchor this segment with stringent chain-of-custody documentation requirements.
- Workplace Testing:OSHA mandates for commercial transportation and hazardous materials handling are expanding mandatory screening across US logistics fleets and industrial facilities, with aftermarket calibration unbundling reshaping vendor relationships.
- Clinical Diagnostics:EU MDR Class IIa classification and French ANSM supplementary guidance impose quality management system obligations for hospital laboratory deployment.
- Personal Monitoring:Consumer-grade devices for voluntary alcohol tracking occupy price-sensitive segments with minimal regulatory oversight.
Law enforcement holds the largest share; workplace testing is gaining share fastest.
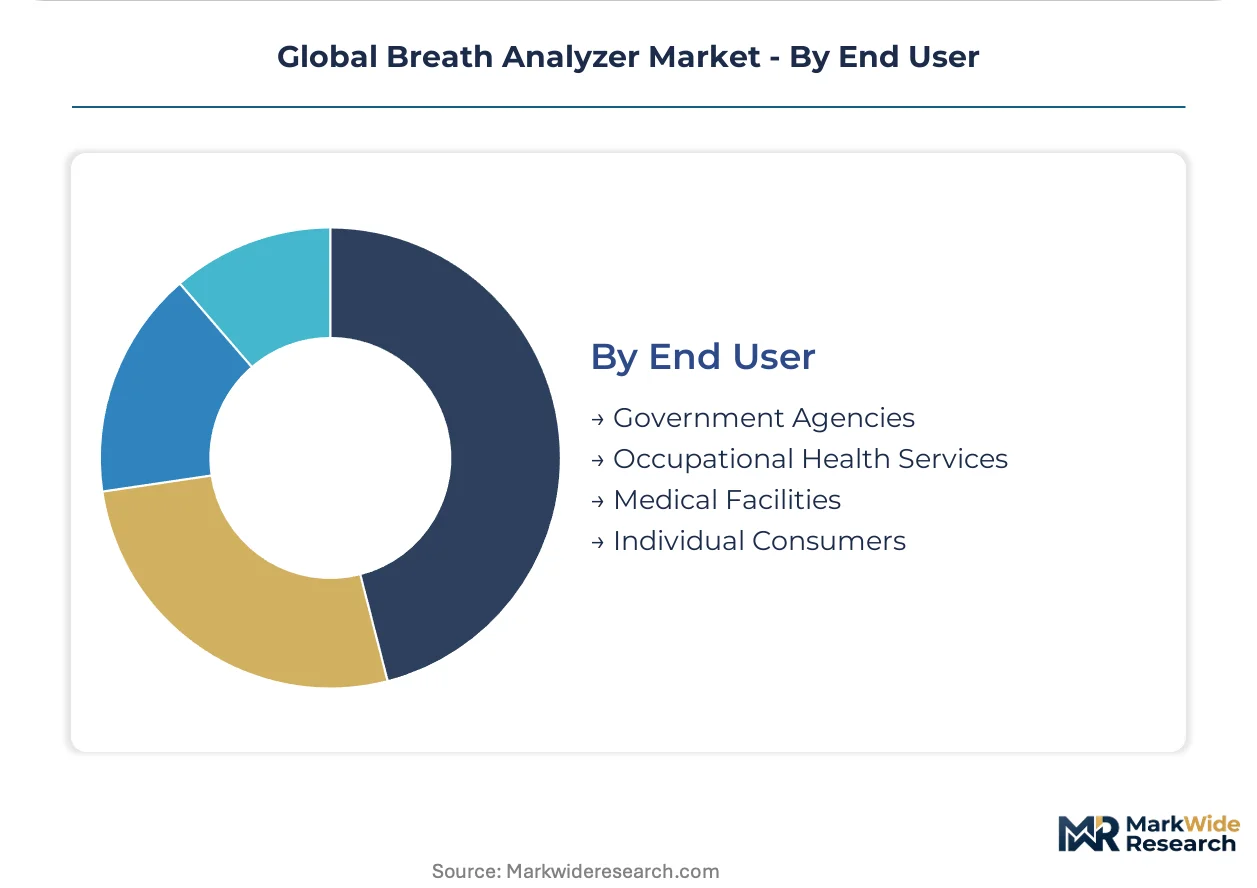
End User:
Volume concentration versus margin protection trade-offs differentiate segments, with government tenders prioritizing total cost of ownership and medical facilities emphasizing clinical evidence portfolios.
- Government Agencies:Federal and state police laboratories, transport authorities, and correctional facilities procure through multi-year framework agreements with embedded service provisions. German KBA certification serves as reference standard for cross-border European procurement.
- Occupational Health Services:Third-party workplace testing providers and corporate medical departments are decoupling hardware procurement from calibration contracts, particularly in North American logistics fleets.
- Medical Facilities:Hospital laboratories and diabetes clinics are piloting volatile organic compound detection for metabolic screening convergence, triggering EU MDR compliance investments.
- Individual Consumers:Direct-to-end-user sales through retail and e-commerce channels concentrate in semiconductor-based personal monitoring devices.
Government agencies hold the largest share; occupational health services show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Workplace testing programs in the United States tolerate premium hardware costs for evidential-grade accuracy, while personal monitoring demand in emerging markets gravitates toward semiconductor-based alternatives.
United States
OSHA workplace testing mandates for commercial transportation fleets are expanding mandatory screening protocols across logistics networks. FDA 510(k) clearance requirements shape market access for clinical and law enforcement devices, creating 12-18 month regulatory review cycles. California and Texas industrial corridors are piloting connected device architectures with cloud-based calibration management.
Germany
Federal police standards mandate evidential-grade devices with KBA certification for roadside testing. EU Green Deal sustainability mandates and REACH substance restrictions influence material selection for domestic manufacturers. The Ruhr industrial cluster hosts precision electrochemical assembly operations serving cross-border European procurement.
India
Motor Vehicles Act amendments and state-level transport enforcement expansion are opening fleet-installed breathalyzer mandates. BIS certification requirements apply to imported devices, while CDSCO oversight governs clinical metabolic screening applications. Maharashtra and Gujarat transport authorities are scaling roadside testing infrastructure.
China
Commercial vehicle safety regulations are tightening screening requirements for long-haul trucking fleets. NMPA medical device classification applies to clinical diagnostics segments. The Yangtze River Delta manufacturing base produces semiconductor sensor components for cost-driven personal monitoring exports.
United Kingdom
Police and Crime Commissioner procurement frameworks govern law enforcement device acquisition with emphasis on total cost of ownership. MHRA regulations align with EU MDR standards for clinical breath analyzers. Greater London occupational health services are unbundling hardware procurement from calibration certification contracts.
Global Breath Analyzer Market Competitive Landscape
Evidential-grade specialists and workplace testing providers split the market between accuracy-sensitive and volume-driven segments. The vendor base concentrates around precision electrochemical expertise and regulatory certification capabilities. German manufacturing heritage and US logistics fleet relationships define the two dominant strategic archetypes. Competitive moves center on aftermarket service unbundling and multi-year calibration agreement capture.
Within the evidential-grade tier, Drägerwerk AG & Co. KGaA anchors German manufacturing-based supply for law enforcement procurement. Lifeloc Technologies, Inc. and Intoximeters, Inc. occupy positions in North American workplace testing and state police laboratory service contracts respectively. These three exemplify how regulatory certification depth and geographic manufacturing concentration determine competitive positioning.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| Lifeloc Technologies, Inc. |
| Intoximeters, Inc. |
| Alcohol Countermeasure Systems Corp. |
| BACtrack |
| Quest Products, Inc. |
| Lion Laboratories |
| Bedfont Scientific Ltd. |
| AK GlobalTech Corp. |
| Others |
Supply & Pricing Matrix
The Ruhr industrial cluster anchors precision electrochemical assembly capacity for fuel cell sensor production, concentrating manufacturing expertise that translates into pricing power for evidential-grade device tiers. German KBA certification requirements and South African platinum price volatility feed directly into cost structures, compressing margins for manufacturers lacking captive calibration infrastructure or long-term service contract anchoring.
Pricing Analysis
Aftermarket calibration and certification contracts now drive lifetime value beyond hardware margins, with multi-year service agreements representing recurring revenue streams that OEMs and third-party providers contest. Three-tier pricing structure across evidential-grade, workplace-standard, and personal-monitoring levels separates KBA-certified systems from OSHA-compliant units and semiconductor-based consumer devices. Pricing pressure stems from platinum catalyst cost volatility and unbundled procurement patterns in North American logistics fleets. Government tenders show lowest price sensitivity due to total-cost-of-ownership frameworks, while individual consumer segments gravitate toward economy-tier semiconductor alternatives.
Supply Chain Analysis
Export-control restrictions on precision electrochemical manufacturing equipment limit technology transfer to emerging production hubs, constraining capacity expansion outside established bases. Component supply concentrates in Germany, the United States, and China, with fuel cell electrodes drawing from South African platinum group metal output and photonic integrated circuits sourcing from Taiwanese semiconductor foundries. Single-source vulnerability runs through certified reference gas suppliers clustered in Germany and the United States. Distribution runs through direct government procurement frameworks, occupational health service contracts, and hospital purchasing committees with diverging certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fuel cell design expertise concentrates in automotive and aerospace sectors, forcing breathalyzer manufacturers to compete for electrochemical engineering talent that determines product accuracy thresholds. This capability scarcity rewards incumbents with established training pipelines and university research partnerships.
For Market Incumbents: Insulate service contract portfolios from third-party calibration competitors by embedding cloud-based calibration management into device architectures. Acquire or partner with certified reference gas suppliers to reduce cross-border logistics dependencies. Vertical integration into precision electrochemical assembly protects margin stability against South African platinum price volatility. For New Entrants and Emerging Players: Establish a beachhead in Indian commercial vehicle screening by securing BIS certification ahead of Motor Vehicles Act enforcement scaling. Target occupational health services in Greater London where procurement unbundling creates vendor-switching opportunities. Lead with connected device architectures that automate chain-of-custody documentation for buyers prioritizing compliance workflow efficiency. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with FDA 510(k) clearance depth and KBA certification reciprocity across European procurement frameworks. Long-term viability hinges on fuel cell miniaturization R&D pipelines and clinical metabolic screening convergence capabilities. Watch for EU MDR Class IIa quality management system audit failures as consolidation triggers among underprepared hospital laboratory suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Fuel Cell Miniaturization R&D | Compresses device footprints for portable deployment while tightening KBA accuracy tolerances. |
| Cloud-Based Calibration Platform | Transforms hardware vendors into recurring-revenue compliance platforms for OSHA-mandated fleets. |
| EU MDR Class IIa Certification Investment | Unlocks hospital laboratory procurement governed by French ANSM supplementary guidance. |
| Indian BIS Certification Pathway | Secures market access ahead of Maharashtra and Gujarat transport enforcement scaling. |
| Photonic Integrated Circuit Integration | Enables multi-compound detection beyond ethanol for German industrial cluster pilots. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with electrochemical engineers, occupational health procurement officers, FDA regulatory consultants, and German KBA certification auditors; and secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation, BIS certification registries, and OSHA workplace testing mandate filings. Bottom-up segment sizing across portable, desktop, wearable, and disposable form factors triangulated against top-down market value estimates.
Forecast inputs incorporated fuel cell sensor deployment trajectories in US logistics fleets, KBA certification adoption patterns across European enforcement agencies, and clinical metabolic screening pilot expansion in German Ruhr industrial clusters. Segmentation modeling spanned product type, sensor technology, application vertical, and end-user procurement authority. CAGRs were derived from installation base growth, replacement cycle compression, and aftermarket service revenue maturation across the projection horizon.
Stress conditions across platinum price volatility bands, FDA 510(k) clearance timeline extensions, and EU REACH substance restriction scope expansions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OSHA mandate enforcement intensity and German federal police procurement continuity. Material shifts in fuel cell accuracy standard reciprocity between FDA and KBA frameworks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Amniotic Fluid Detection Market
Diagnostic Devices
Europe Breath Analyzer Market
Diagnostic Devices
Lung Biopsy Systems Market
Diagnostic Devices
GCC Breath Analyzer Market
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
PCR and Real-Time PCR Molecular Diagnostics Market
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
Blood Testing Devices Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
Non-Invasive Biosensors Market
Diagnostic Devices
Counterfeit Drug Detection Device Market
Diagnostic Devices
ENT Diagnostic Devices Market
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
Europe Point of Care Diagnostics Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market