
 Digital Diagnostic Audiometer Market | 2026-2036
Digital Diagnostic Audiometer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Diagnostic Audiometer Market Insights
Hospitals and audiology clinics are realigning procurement priorities toward computer-based platforms with integrated electronic health record connectivity. William Demant leverages its vertical integration into transducer manufacturing to control component quality across its diagnostic portfolio. Amplivox sustains brand recognition in occupational health channels through calibrated portable systems that meet workplace screening protocols. Grason-Stadler differentiates via specialized pediatric assessment modules that support conditioned play audiometry in clinical environments.
A digital diagnostic audiometer is an electroacoustic instrument that generates calibrated pure tones, speech signals, and immittance measurements at specified frequencies and intensity levels to quantify hearing threshold and middle-ear function. The device serves ENT specialists, audiologists, and occupational health technicians in diagnosing sensorineural, conductive, and mixed hearing pathologies. Standalone audiometers retain dominance in hospital settings where dedicated sound booths and permanent installations support comprehensive diagnostic workflows. Portable audiometers represent the fastest-expanding segment as home healthcare providers and mobile occupational screening services prioritize field-deployable units with battery-operated pure tone and speech capabilities.
The US OSHA mandates baseline and annual audiometric testing for workers exposed to noise levels exceeding 85 dB, directly shaping employer purchasing patterns for compliant screening equipment. The EU MDR and CE marking requirements govern clinical diagnostic audiometers marketed across member states, raising documentation and quality management burdens for manufacturers. Stakeholders must monitor evolving reimbursement codes for tele-audiology services, as remote testing authorization could redirect capital toward cloud-integrated platforms and away from traditional booth-dependent configurations.
Market Dynamics
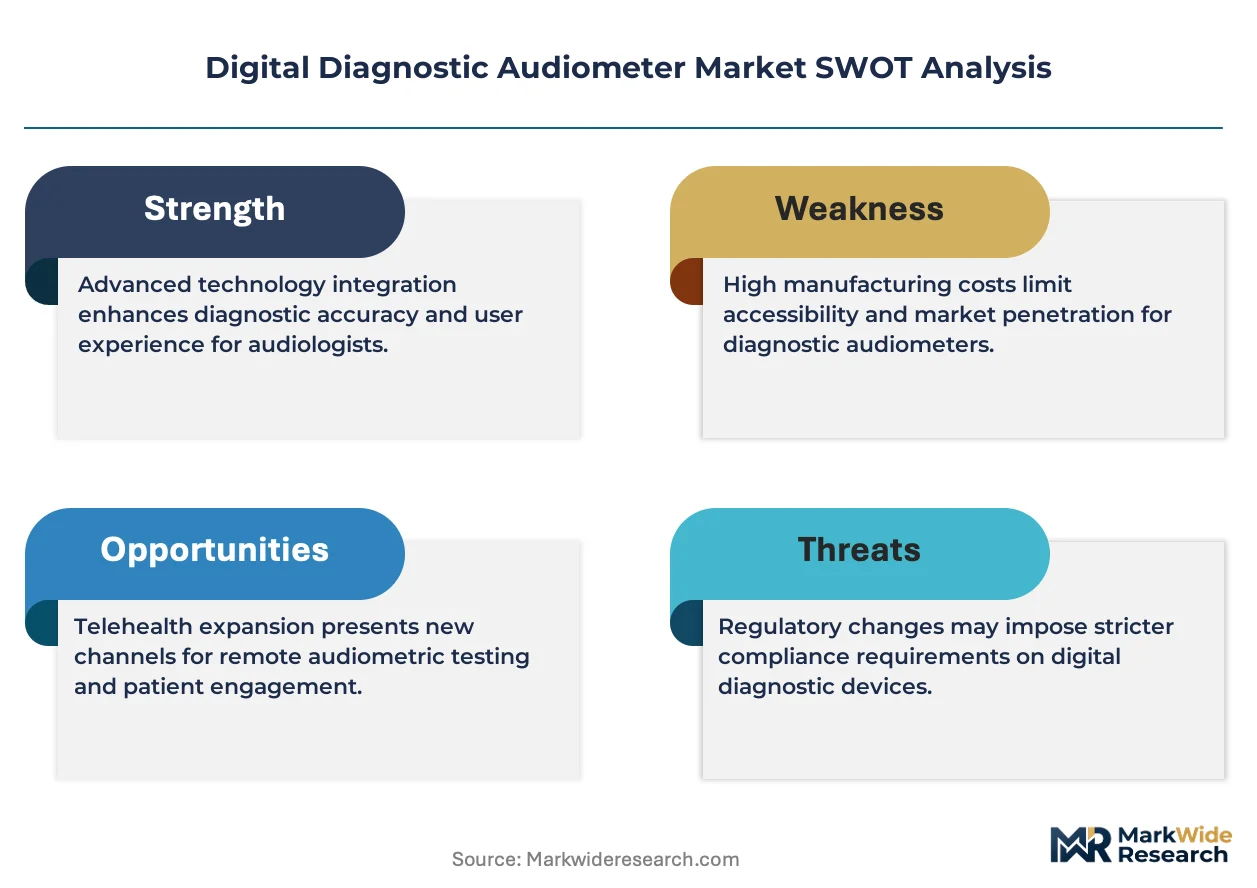
Occupational noise mandates are compressing replacement cycles for screening equipment while tele-audiology reimbursement approvals redirect hospital capital toward cloud-integrated platforms. The tension between booth-dependent diagnostic fidelity and portable field deployment is forcing manufacturers to recalibrate hardware-software architectures.
Growth Catalysts
- OSHA Hearing Conservation Amendments:US employers exposed to 85 dB thresholds must maintain annual audiometric testing records, sustaining baseline procurement volumes for calibrated screening units.
- EU Physical Agents Directive Enforcement:Member state labor inspectorates are intensifying workplace noise assessments, compelling manufacturing facilities to upgrade from analog to digital audiometric systems.
- Pediatric Early Intervention Mandates:Universal newborn hearing screening programs in Germany and France are expanding diagnostic referral volumes, driving demand for conditioned play audiometry modules.
Market Restraints
- Transducer Supply Concentration:Precision electroacoustic transducer manufacturing concentrates among German and Japanese component specialists, exposing OEMs to single-source bottlenecks.
- MDR Documentation Burden:EU MDR technical file requirements and notified body backlogs are extending CE marking timelines by 12-18 months for new diagnostic audiometer submissions.
- Smartphone-Based Screening Substitution:FDA-cleared mobile hearing test applications are capturing price-sensitive occupational screening segments, compressing margins for entry-level portable audiometers.
Strategic Opportunities
- Home Healthcare Penetration:Remote patient monitoring reimbursement codes in the US are creating viable economics for mail-deployed audiometer kits with cloud-based audiologist review.
- AI-Assisted Threshold Detection:Machine learning algorithms for automated Hughson-Westlake procedure execution are converging with tablet-based platforms to reduce technician training requirements.
- India Occupational Health Expansion:Factory Act amendments and state-level ESI hospital network growth are opening procurement channels for mid-range diagnostic units in Maharashtra and Tamil Nadu.
Industry Challenges
- Audiologist Workforce Constraints:Clinical training program bottlenecks in the US and UK are limiting the technician pool available to operate expanded screening programs.
- EHR Integration Complexity:Proprietary data formats from legacy audiometers resist seamless interoperability with Epic and Cerner systems, forcing costly middleware development.
- Calibration Certification Backlogs:Accredited acoustic calibration laboratory capacity shortages are delaying annual certification renewals required for OSHA-compliant testing programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Diagnostic Audiometer Market |
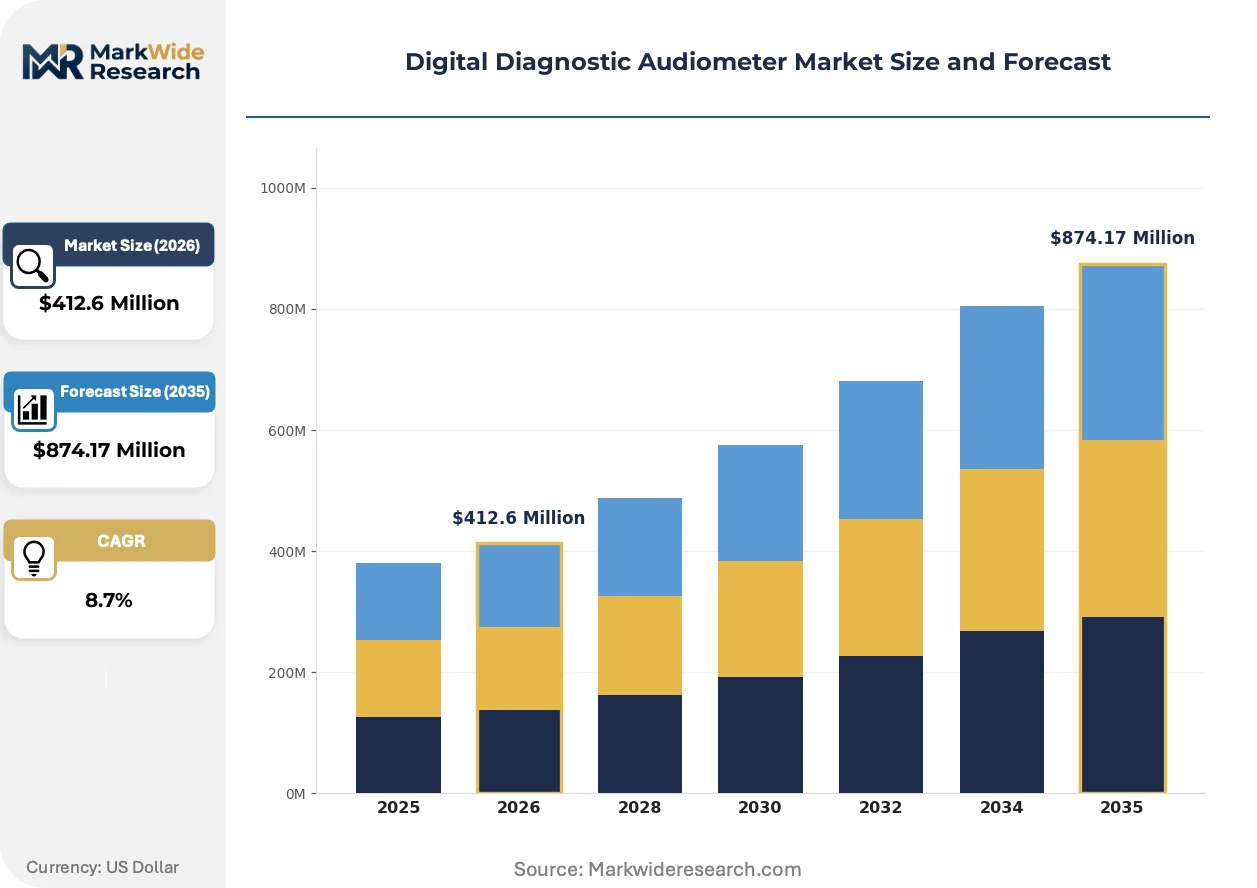
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Audiometers, Standalone Audiometers, Computer-Based Audiometers, Digital Screening Devices End User: Hospitals, Audiology Clinics, Research Facilities, Home Healthcare Providers Technology: Pure Tone Audiometry, Speech Audiometry, Immittance Audiometry, Otoacoustic Emissions Application: Pediatrics, Geriatrics, Occupational Health, General Health Screening |
| Companies Covered | William Demant, Amplivox, Natus Medical, Inventis, Benson Medical Instruments, Otometrics, Grason-Stadler, MAICO Diagnostics, Interacoustics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Diagnostic Audiometer Market Trends and Innovations
Diagnostic audiology is transitioning from isolated booth-based instruments to networked platforms capable of remote operation and automated reporting. This shift is compressing hardware replacement cycles while elevating software and connectivity to primary purchase criteria.
Bone conduction audiometry is converging with wireless transducer technology to eliminate cumbersome headband cabling. Pediatric clinics and mobile screening services are adopting these untethered systems to improve patient compliance during extended test sessions. The structural consequence is a reallocation of R&D expenditure from analog signal processing toward RF engineering and miniaturized power management.
The EU MDR's post-market surveillance requirements are mandating systematic clinical follow-up data collection for Class IIa diagnostic devices. Manufacturers must now maintain vigilance systems tracking device performance across installed bases. Audiology clinics in Germany and the Netherlands are responding by demanding extended service contracts that bundle regulatory documentation support with hardware maintenance.
Hospital purchasing committees are consolidating vendor relationships to reduce contract management overhead, favoring suppliers offering multi-modality diagnostic platforms. This concentration is displacing standalone audiometer specialists from large health system RFPs. The shift is most visible in US integrated delivery networks where procurement authority has centralized from individual ENT departments to system-wide value analysis committees.
Digital Diagnostic Audiometer Market Segmentation
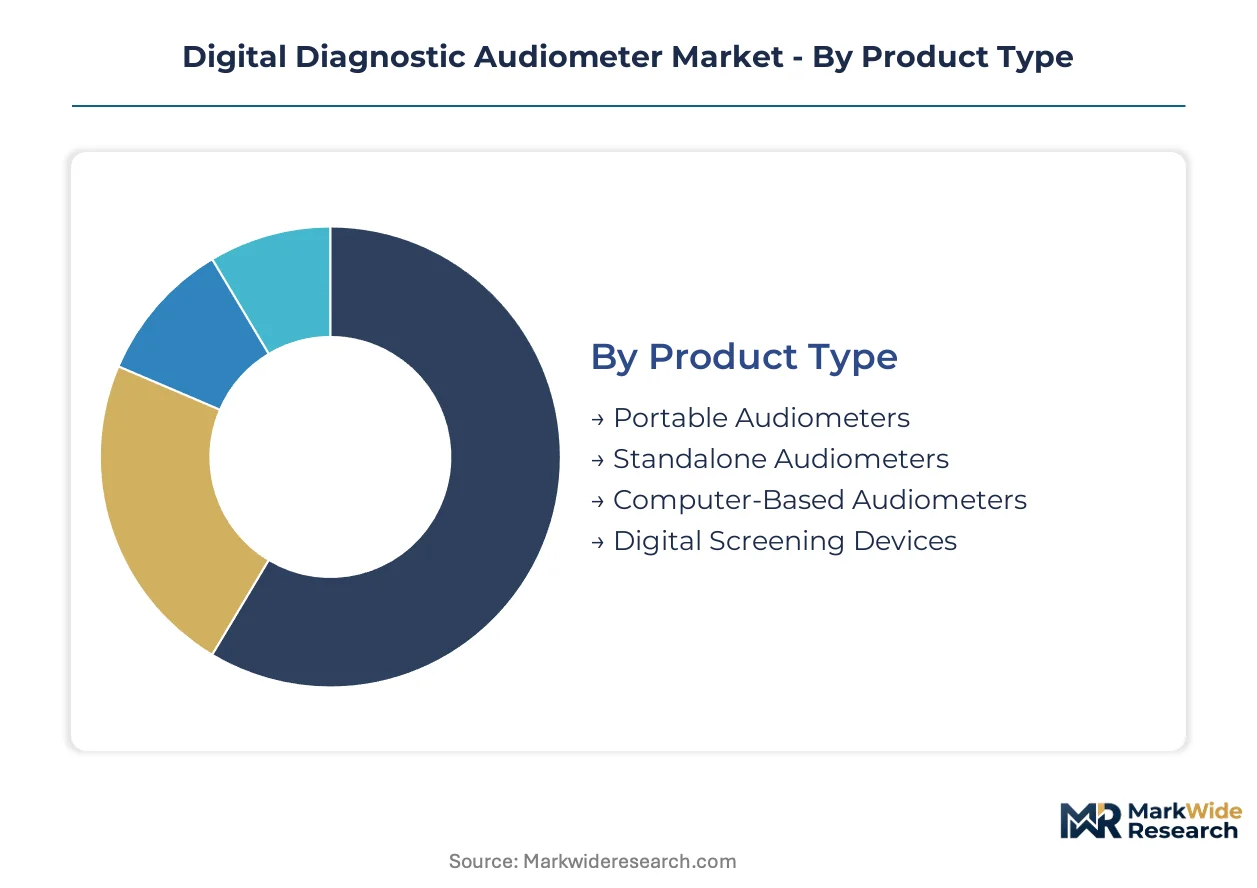
Segmentation in the digital diagnostic audiometer market reveals divergent regulatory pathways and procurement economics across hardware configurations and clinical settings. Certification requirements from FDA and EU MDR create tiered barriers that reshape competitive dynamics within each category.
Product Type:
CE marking under EU MDR Class IIa applies universally, though portable and screening devices face streamlined technical documentation compared to comprehensive diagnostic platforms requiring extensive clinical evidence.
- Portable Audiometers:Battery-operated units with calibrated pure tone and speech capabilities designed for field deployment. Demand concentrates in mobile occupational screening services across Germany and US manufacturing corridors, where OSHA compliance mandates sustain fleet procurement cycles despite smartphone-based substitution pressure.
- Standalone Audiometers:Booth-dependent systems with dedicated sound isolation and permanent installation requirements. Hospital ENT departments in France and the Netherlands prioritize these configurations for diagnostic fidelity, though capital constraints are redirecting some procurement toward computer-based alternatives.
- Computer-Based Audiometers:Software-driven platforms leveraging PC or tablet hardware with modular transducer connectivity.
- Digital Screening Devices:Simplified threshold detection instruments for high-volume workplace testing protocols.
Standalone audiometers sit at the top of the volume ranking, with portable audiometers climbing the fastest.
End User:
Procurement authority varies sharply across customer types, with hospital value analysis committees demanding multi-modality platforms while occupational health buyers prioritize calibrated portability and audit-ready documentation.
- Hospitals:Integrated delivery networks with centralized purchasing authority. German university hospitals and US academic medical centers are consolidating vendor relationships toward suppliers offering EHR-integrated diagnostic suites, displacing standalone audiometer specialists from large system RFPs.
- Audiology Clinics:Independent and chain-affiliated diagnostic centers performing threshold assessments and hearing aid fittings. Dense clinic networks in Germany's statutory insurance system sustain recurring equipment refresh cycles, with pediatric specialists demanding conditioned play audiometry modules.
- Research Facilities:Academic and commercial laboratories conducting longitudinal hearing studies and device validation.
- Home Healthcare Providers:Remote patient monitoring services and mail-deployed screening programs.
Hospitals command the largest installed base, though home healthcare providers are gaining share fastest as reimbursement codes for tele-audiology mature.
Technology:
Margin structures diverge by measurement modality, with immittance and otoacoustic emissions requiring specialized probe assemblies and transducer calibration protocols that elevate service contract attach rates.
- Pure Tone Audiometry:Threshold detection via air and bone conduction at standardized frequencies. Remains the foundational protocol across all clinical settings, with wireless bone conduction transducers eliminating headband cabling to improve pediatric compliance in French and Dutch clinics.
- Speech Audiometry:Word recognition and speech-in-noise testing using recorded or live voice materials. Occupational health programs in US manufacturing and construction sectors mandate annual speech discrimination testing alongside pure tone thresholds per OSHA hearing conservation amendments.
- Immittance Audiometry:Middle-ear function assessment through tympanometry and acoustic reflex measurement.
- Otoacoustic Emissions:Objective cochlear response detection for newborn screening and malingering assessment.
Pure tone audiometry retains dominant volume position, while otoacoustic emissions demonstrates steepest expansion trajectory driven by universal newborn hearing program mandates.
Application:
Reimbursement coding and regulatory surveillance intensity vary by patient population, with pediatric applications demanding specialized protocols and occupational health subject to inspectorate audit requirements.
- Pediatrics:Assessment protocols adapted for non-verbal patients including conditioned play audiometry and visual reinforcement orientation. German and French universal newborn screening programs are expanding diagnostic referral volumes, with specialized modules from Grason-Stadler and competitors capturing clinic preference.
- Occupational Health:Workplace compliance testing for noise-exposed employees. US OSHA and EU Physical Agents Directive enforcement are compressing replacement cycles for screening equipment, with manufacturing facilities in Maharashtra and Tamil Nadu opening new procurement channels as India's Factory Act amendments expand coverage.
- Geriatrics:Age-related hearing loss assessment in senior care and community health settings.
- General Health Screening:Routine auditory evaluation in primary care and wellness programs.
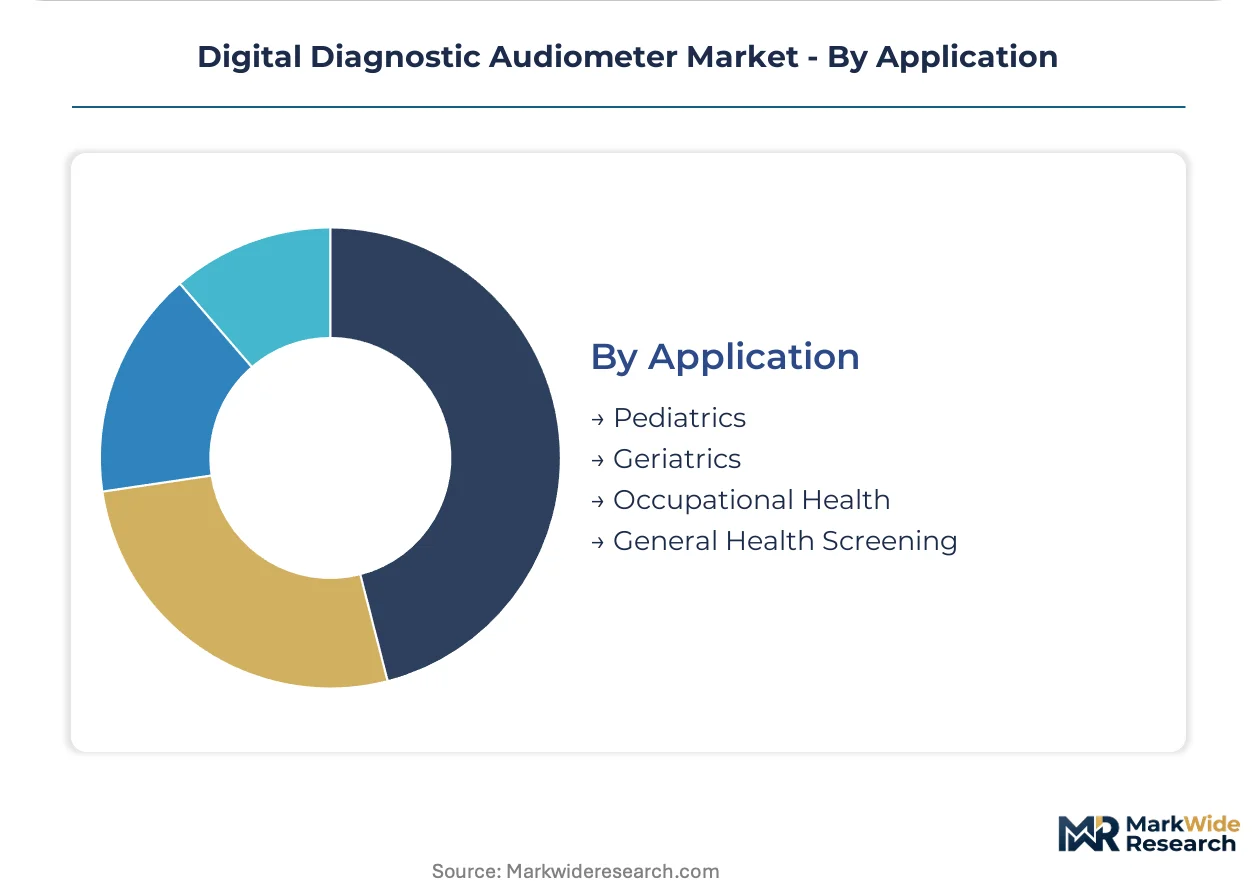
Occupational health leads by volume, with pediatrics expanding most quickly amid early intervention mandate proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate assembly to jurisdictions with streamlined medical device certification timelines, compressing time-to-market for EU-bound exports while US OSHA compliance mandates sustain premium pricing in North American procurement channels.
United States
Hospital value analysis committees and occupational health purchasing managers drive divergent demand patterns. OSHA mandates annual audiometric testing for noise-exposed workers above 85 dB, sustaining fleet procurement for manufacturing facilities. The Detroit automotive corridor and Houston petrochemical belt concentrate replacement cycles for screening equipment as employers face inspectorate audit pressure.
Germany
Statutory insurance mandates and dense audiology clinic networks sustain the densest installed base in Europe. EU MDR Class IIa certification requirements and notified body backlogs are extending CE marking timelines, favoring incumbent suppliers with established technical files. The Ruhr industrial belt and Bavarian manufacturing zones compress replacement cycles for workplace screening protocols.
China
NMPA regulatory pathways and domestic hospital procurement centralization are elevating compliance costs for imported diagnostic platforms. Provincial health commissions in Jiangsu and Guangdong are expanding ENT department capital budgets, though price-sensitive tender processes favor locally assembled units. The Yangtze River Delta concentrates contract manufacturing for transducer components.
India
Factory Act amendments and ESI hospital network expansion are opening procurement channels in Maharashtra and Tamil Nadu. CDSCO medical device rules and state-level occupational health inspectorates are mandating baseline audiometric testing in textile and heavy engineering facilities. The Pune-Nashik industrial corridor sustains demand for mid-range portable screening units.
Japan
PMDA quality management requirements and aging demographics are elevating diagnostic audiology service volumes. Prefecture-level occupational health centers in Osaka and Nagoya maintain calibrated equipment fleets for manufacturing sector compliance. METI industrial health guidelines are tightening noise exposure assessment protocols in automotive and electronics assembly plants.
Digital Diagnostic Audiometer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital procurement committees consolidating vendor relationships toward multi-modality platform suppliers while occupational health buyers prioritize calibrated portability and audit-ready documentation. The structure concentrates around three archetypes: vertically integrated hearing healthcare conglomerates, specialized diagnostic instrument manufacturers, and regional contract assemblers serving price-sensitive tenders. Dominant competitive moves include backward integration into transducer manufacturing to control component quality, and geographic expansion through distributor partnerships in emerging occupational health markets.
Among European-origin specialists, William Demant and Amplivox occupy positions exemplifying contrasting strategic archetypes. William Demant represents the hearing healthcare conglomerate model with captive supply chain control over electroacoustic components. Amplivox exemplifies the portable-focused specialist archetype sustaining brand recognition in occupational health channels. Grason-Stadler anchors the pediatric diagnostic segment, representing specialized clinical module development. These three entities collectively illustrate the tiered competitive structure where vertical integration depth, application specialization, and channel focus determine procurement access.
| Leading Market Players |
|---|
| William Demant |
| Amplivox |
| Natus Medical |
| Inventis |
| Benson Medical Instruments |
| Otometrics |
| Grason-Stadler |
| MAICO Diagnostics |
| Interacoustics |
| Others |
Pricing and Supply Chain Analysis
Wireless bone conduction transducer miniaturization is simultaneously elevating R&D cost structures and concentrating component sourcing among German and Japanese electroacoustic specialists, creating asymmetric pricing power for suppliers of precision-calibrated assemblies.
Pricing Analysis
Distributor margins in occupational health channels absorb 15-25% of end-equipment value, compressing OEM profitability on entry-level portable units. Three-tier pricing structure across premium diagnostic, standard clinical, and economy screening levels reflects CE marking tier and calibration certification depth. Price erosion runs through economy screening tiers as FDA-cleared smartphone applications capture price-sensitive workplace testing demand. Occupational health buyers in US manufacturing corridors exhibit highest price sensitivity, while German university hospitals prioritize diagnostic fidelity over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle comprehensive diagnostic platform demand, while distributor networks serve fragmented audiology clinic procurement. Precision electroacoustic transducer manufacturing concentrates in Germany and Japan, with final assembly distributed across China, Denmark, and the United States. Component supply draws from specialized ceramic substrate suppliers in Bavaria and precision coil winders in Osaka. Single-source vulnerability in bone conduction oscillator supply exposes OEMs to 12-18 month qualification timelines for alternative sources.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital diagnostic audiometer market functions as a stable compounder, with regulatory mandates for occupational noise exposure testing creating predictable replacement cycle demand across industrial economies.
For Market Incumbents: Hedge transducer supply exposure through dual-source qualification programs with Japanese ceramic substrate suppliers and German precision coil specialists. Backward integration into transducer manufacturing anchors component quality control against single-source bottlenecks. CE marking technical file maintenance absorbs disproportionate regulatory resources under EU MDR notified body backlogs. For New Entrants and Emerging Players: AI-assisted Hughson-Westlake automation offers a technology-first wedge into technician-constrained US occupational health markets. Home healthcare tele-audiology reimbursement codes in Medicare Advantage plans represent the most penetrable white-space target. Direct-to-employer sales models bypass entrenched distributor relationships in manufacturing belt procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among portable-focused specialists lacking multi-modality platform breadth. Long-term viability framing centers on software-integrated diagnostic suites with recurring service contract attach rates. Watch FDA tele-audiology reimbursement rulemaking as the signal indicating capital reallocation timing toward cloud-integrated platforms.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa technical files require 12-18 month notified body engagement timelines. |
| Hospital System Partnership | Integrated delivery network consolidation favors multi-modality diagnostic suite suppliers. |
| Software Companion Development | Cloud-integrated platforms with EHR interoperability capture value analysis committee preference. |
| Reimbursement Strategy | Tele-audiology CPT code expansion redirects capital toward remote testing authorization. |
| Backward Integration | In-house transducer production insulates against German-Japanese component supply concentration. |
Research Methodology
Bottom-up audiology clinic procurement modeling reconciled against top-down transducer manufacturing tracking forms the analytical core of this study. Primary interviews with hospital biomedical engineers, occupational health technicians, audiology clinic directors, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body registrations, and OSHA compliance audit databases. Triangulation across these sources calibrated installed base estimates and replacement cycle assumptions.
Historical trendline analysis of pure tone audiometer shipments across product type, end user, and technology segments established baseline growth patterns. Segmentation dimensions modeled include hardware configuration, clinical setting, measurement modality, and patient application across the projection horizon. CAGRs derived from weighted average of segment-level growth rates incorporate regulatory mandate enforcement timelines and reimbursement code expansion scenarios.
The model holds under stable regulatory enforcement intensity; deviation in EU MDR notified body capacity or OSHA inspection priority shifts would alter replacement cycle timing. Forecasts reflect assumptions regarding tele-audiology reimbursement maturation and transducer supply chain stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
Portable Diagnostic Devices Market
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
GCC Breath Analyzer Market
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
Biopsy Devices Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Hemoglobin Testing Devices Market
Diagnostic Devices
US Point of Care Diagnostics Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market
Diagnostic Devices
MRI Compatible Biopsy Devices Market
Diagnostic Devices
Urine Analyzers Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Global Breast Lesion Localization Methods Market
Diagnostic Devices
Hearing Screening Diagnostic Devices Market