
 Pulmonary Function Testing Devices Market | 2026-2036
Pulmonary Function Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pulmonary Function Testing Devices Market Analysis
Modular bundling of spirometry hardware with cloud-based data management platforms is hardening as the dominant procurement configuration. Vyaire Medical leverages its integrated respiratory care portfolio to sustain hospital system contracts across North America. COSMED Srl anchors its position through precision calibration technology for sports and clinical pulmonary diagnostics. ndd Medical Technologies specializes in portable ultrasonic spirometry, differentiating its product line for point-of-care and home monitoring channels.
Pulmonary Function Testing Devices comprise instruments that quantify lung mechanics, volumes, and gas exchange through forced expiratory maneuvers, body plethysmography, or inert gas dilution, typically resolving airflow rates to within 50 milliliters and detecting obstructive or restrictive patterns critical to respiratory disease management. Spirometers occupy the largest installed base among product types due to standardized COPD and asthma screening protocols, while portable technology configurations are expanding fastest as home care reimbursement frameworks mature. Gas diffusion test devices command premium positioning within hospital pulmonary laboratories where interstitial lung disease workups require carbon monoxide uptake precision.
The FDA regulates these devices under 21 CFR Part 874 diagnostic device classifications, while the European Medical Device Regulation mandates clinical evidence for spirometry systems marketed under CE marking. The EPA's ambient air quality standards indirectly shape demand by elevating public health surveillance requirements that feed into respiratory diagnostic volumes. Stakeholders must weigh the pace of portable device validation against stationary system replacement cycles as reimbursement pathways fragment across clinical and non-clinical settings.
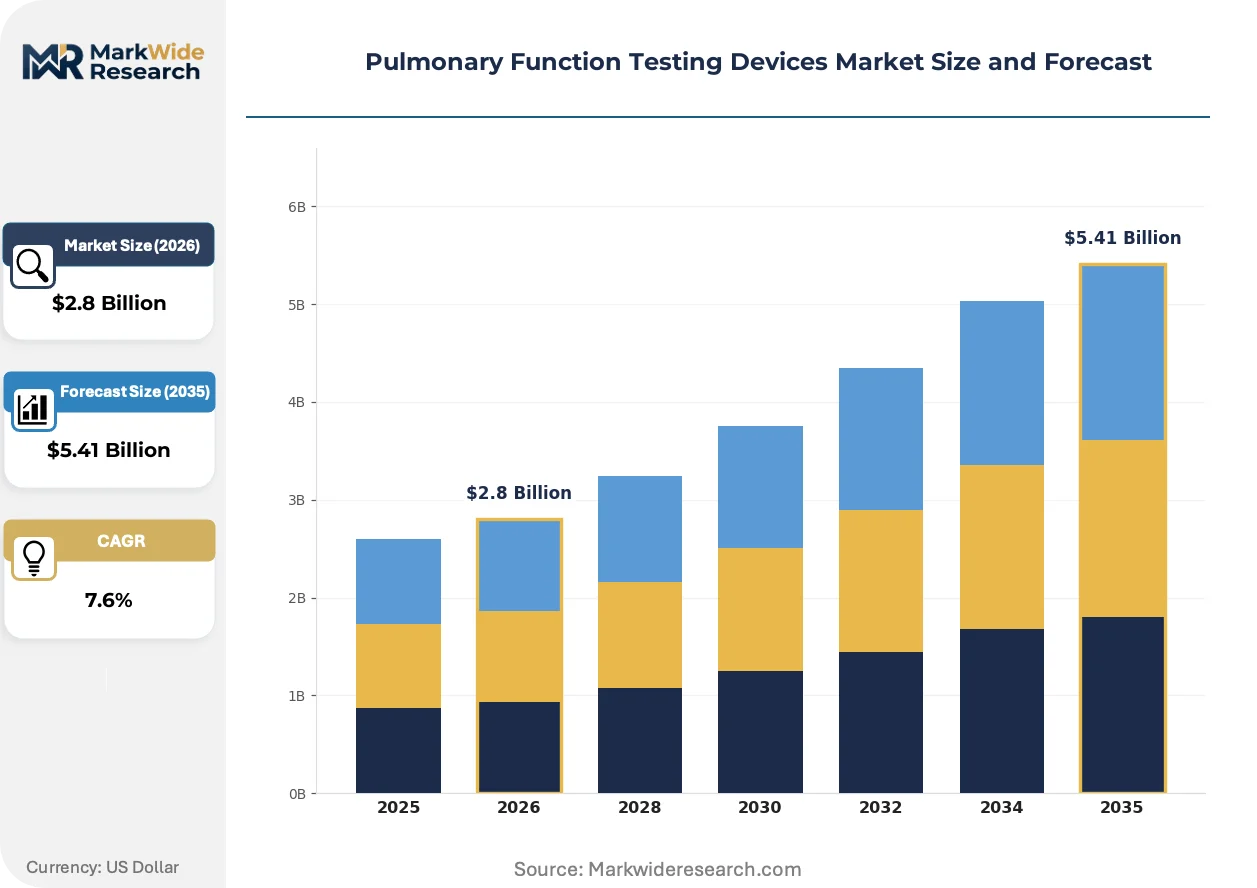
Market Dynamics
Cloud-based data management platforms are hardening procurement configurations across hospital systems, compressing standalone hardware margins while elevating bundled service contracts as the dominant commercial format.
Growth Catalysts
- Home care reimbursement frameworks:CMS and private payers in the United States are expanding remote patient monitoring codes, accelerating portable spirometer deployment for COPD management outside clinical settings.
- FDA 510(k) clearance pathway:Streamlined premarket notification for novel spirometry systems reduces regulatory friction, enabling faster technology entry for ultrasonic and oscillometric devices.
- Aging demographics in Germany and Japan:Elevated chronic respiratory disease prevalence drives equipment replacement cycles in hospital pulmonary laboratories and diagnostic centers.
Market Restraints
- Precision sensor supply concentration:Ultrasonic flow sensor manufacturing clusters in East Asia create vulnerability to geopolitical disruption and shipping volatility.
- Calibration infrastructure costs:Body plethysmography systems require climate-controlled laboratory environments and certified biomedical engineering staff, limiting deployment to tertiary care centers.
- CE marking clinical evidence requirements:The European Medical Device Regulation mandates expanded clinical validation for software-as-medical-device spirometry platforms, extending time-to-market.
Strategic Opportunities
- Telemedicine integration in rural United States:Federally Qualified Health Centers seek FDA-cleared portable devices with synchronous data transmission to offset pulmonologist shortages.
- Artificial intelligence pattern recognition:Machine learning algorithms for automated obstructive-restrictive classification are integrating with cloud spirometry platforms to reduce interpreter dependency.
- Sports medicine expansion:Elite athletic programs in Australia and professional cycling teams in Europe are adopting precision gas diffusion testing for performance optimization protocols.
Industry Challenges
- Biomedical engineering talent scarcity:Hospital systems struggle to recruit technicians certified in both respiratory physiology and networked device cybersecurity.
- Legacy EMR integration complexity:Proprietary data formats from incumbent spirometry vendors resist seamless interoperability with Epic and Cerner deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulmonary Function Testing Devices Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirometers, Peak Flow Meters, Lung Volume Measurement Devices, Gas Diffusion Test Devices End User: Hospitals, Clinics, Home Care, Research Laboratories Technology: Digital, Analog, Portable, Stationary Application: Chronic Obstructive Pulmonary Disease, Asthma, Interstitial Lung Disease, Others |
| Companies Covered | Schiller AG, CHEST M.I., Inc, Vyaire Medical, Inc, Ganshorn Medizin Electronic, Morgan Scientific Inc., MGC Diagnostics Corporation, ndd Medical Technologies, KoKo PFT, COSMED Srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulmonary Function Testing Devices Market Emerging Trajectories
Ultrasonic flow measurement is displacing traditional pneumotachograph technology across point-of-care configurations, while artificial intelligence and remote monitoring architectures reshape how respiratory diagnostics are delivered and reimbursed.
Ultrasonic spirometry is integrating precision time-of-flight sensors that eliminate moving parts and reduce calibration frequency. Ambulatory surgery centers and urgent care chains are adopting these devices at accelerating pace to support same-day respiratory assessment protocols. The technology is integrating with tablet-based interfaces that compress training requirements and expand operator pools beyond specialized pulmonary technicians.
The European Medical Device Regulation's software classification guidance is redefining clinical evidence requirements for algorithm-driven diagnostic interpretation. Manufacturers must now submit prospective validation studies for AI-enhanced pattern recognition features. Cloud-native spirometry platforms marketed under CE marking are most affected, with several vendors restructuring quality management systems to address notified body scrutiny.
Subscription-based device provisioning is displacing capital purchase models among independent physician practices and smaller hospital networks. Device-as-a-service contracts bundle hardware, calibration, software updates, and predictive maintenance into per-test or monthly fee structures. This shift is most visible in the United States, where reimbursement compression and interest rate sensitivity are driving preference for operational expenditure over capital deployment.
Pulmonary Function Testing Devices Market Segmentation
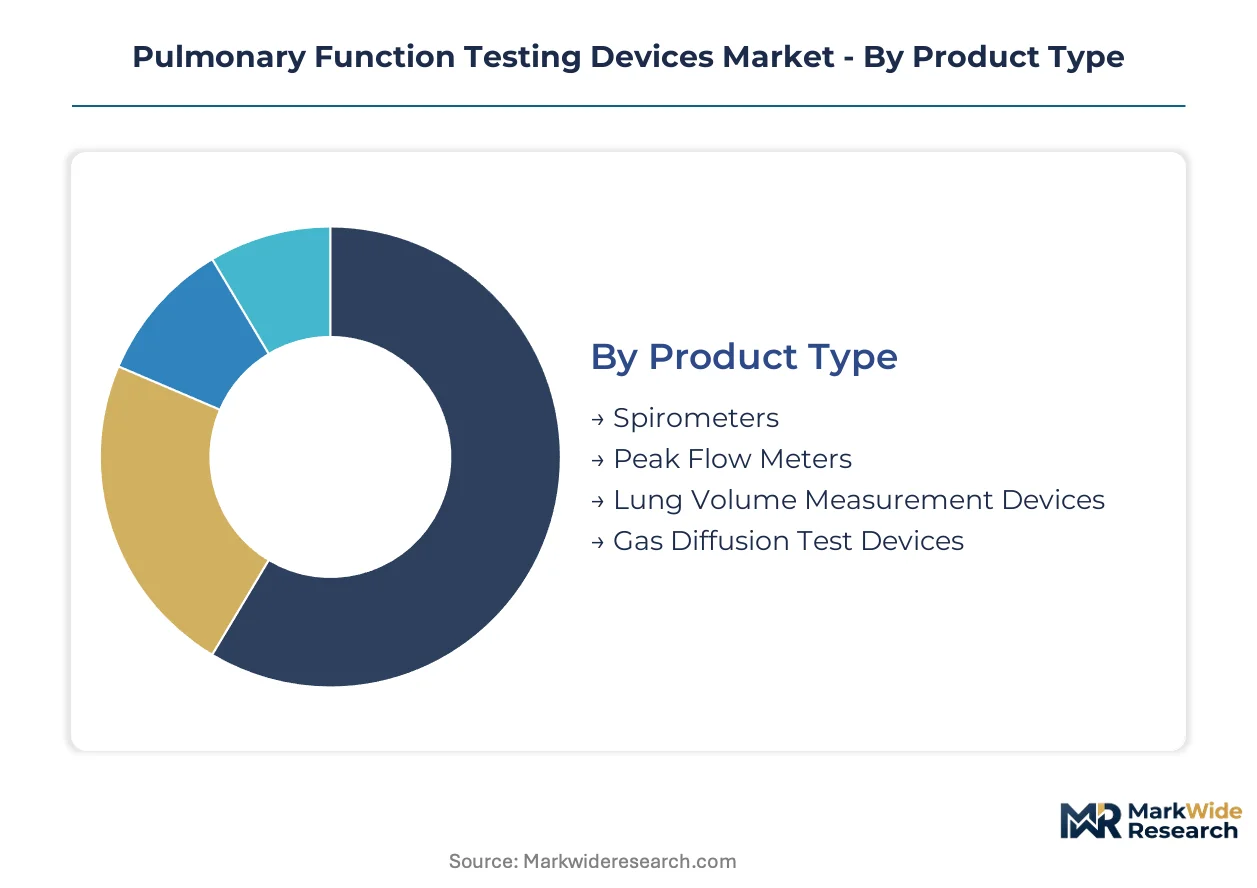
Equipment replacement cycles and reimbursement pathway maturation create divergent growth trajectories across pulmonary function testing configurations. Segment-specific procurement patterns determine whether vendors capture value through capital sales or recurring service contracts.
Product Type:
Upgrade cycles vary sharply by measurement complexity and calibration infrastructure requirements, with simpler devices turning over faster than laboratory-grade systems.
- Spirometers:Forced expiratory maneuver instruments resolve airflow rates to within 50 milliliters using pneumotachograph or ultrasonic flow sensors. Hospital pulmonary laboratories in the United States and Germany drive replacement demand as COPD screening protocols expand and aging equipment exceeds calibration tolerance windows.
- Gas Diffusion Test Devices:Carbon monoxide uptake measurement systems require climate-controlled environments and certified biomedical engineering staff for DLCO precision. Tertiary care centers in Japan concentrate procurement for interstitial lung disease workups where diagnostic accuracy commands premium positioning.
- Peak Flow Meters:Handheld expiratory flow monitors serve asthma management protocols with minimal training requirements.
- Lung Volume Measurement Devices:Body plethysmography and inert gas dilution systems quantify functional residual capacity and total lung capacity.
Volume placements concentrate in Spirometers; the faster expansion belongs to Gas Diffusion Test Devices.
End User:
Reimbursement fragmentation across clinical and non-clinical settings reshapes how vendors structure pricing and service bundling.
- Hospitals:Integrated delivery networks negotiate enterprise contracts combining stationary laboratory systems with cloud-based data management platforms. Pulmonary laboratories in the United States anchor procurement volume as health systems consolidate respiratory diagnostic capabilities under single vendor relationships.
- Home Care:Remote patient monitoring code expansion from CMS and private payers accelerates portable device deployment for COPD management outside clinical settings. The segment gains share fastest as patients and payers favor operational expenditure models over capital deployment.
- Clinics:Ambulatory surgery centers and urgent care chains adopt tablet-interfaced spirometry for same-day respiratory assessment protocols.
- Research Laboratories:Academic medical centers and contract research organizations source precision-calibrated systems for clinical trial endpoints.
Procurement volume tilts toward Hospitals; Home Care climbs the fastest as reimbursement frameworks mature.
Technology:
Sensor architecture and connectivity specifications determine deployment feasibility across point-of-care versus laboratory environments.
- Portable:Battery-powered ultrasonic and oscillometric configurations eliminate moving parts and reduce calibration frequency. Federally Qualified Health Centers in rural United States target these devices to offset pulmonologist shortages through synchronous telemedicine transmission.
- Digital:Cloud-native platforms with artificial intelligence pattern recognition integrate automated obstructive-restrictive classification to reduce interpreter dependency. The European Medical Device Regulation's software classification guidance imposes expanded clinical validation requirements that extend time-to-market for algorithm-driven features.
- Analog:Mechanical pneumotachograph systems persist in resource-constrained settings with limited technical support infrastructure.
- Stationary:Hardwired laboratory configurations anchor body plethysmography and gas diffusion testing in tertiary pulmonary centers.
Installed base dominance rests with Stationary systems; Portable configurations expand most quickly.
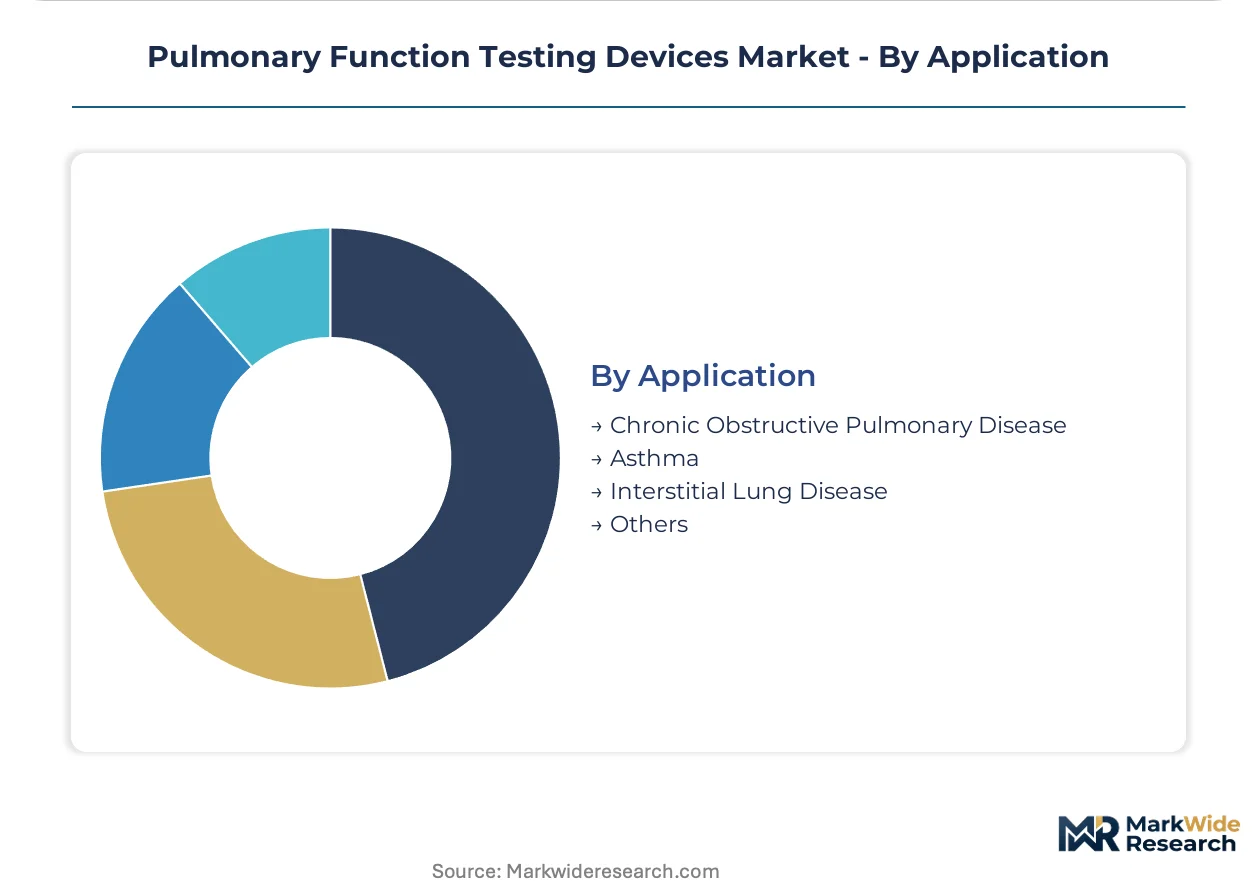
Application:
Disease prevalence patterns and screening protocol standardization determine addressable market depth by clinical indication.
- Chronic Obstructive Pulmonary Disease:Standardized spirometry protocols for diagnosis and severity classification drive the largest installed base of testing devices. Medicare's annual wellness visit requirements in the United States and Japan's aging demographic profile sustain equipment utilization rates.
- Asthma:Peak expiratory flow monitoring and bronchodilator response testing concentrate demand in pediatric and allergy specialist practices. The segment shows steep expansion as home-based monitoring programs reduce emergency department utilization.
- Interstitial Lung Disease:DLCO precision requirements limit testing to specialized pulmonary laboratories with gas diffusion capabilities.
- Others:Pre-operative assessment, occupational health surveillance, and sports medicine applications round out clinical utilization.
Testing volume concentrates in Chronic Obstructive Pulmonary Disease; Asthma demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of ultrasonic flow sensors and precision calibration components clusters in East Asia, while diagnostic utilization concentrates in aging Western markets where reimbursement frameworks drive equipment procurement cycles.
United States
Medicare's expansion of remote patient monitoring reimbursement codes accelerates portable spirometer deployment for COPD management outside hospital settings. The FDA's 510(k) clearance pathway streamlines premarket notification for novel spirometry systems. Federally Qualified Health Centers in rural Texas and the Mountain West target tablet-interfaced devices to offset pulmonologist shortages through synchronous telemedicine transmission.
Germany
Aging demographics and elevated chronic respiratory disease prevalence sustain equipment replacement cycles in hospital pulmonary laboratories and diagnostic centers. The European Medical Device Regulation mandates expanded clinical evidence for CE-marked spirometry platforms, extending time-to-market for algorithm-driven features. Medical technology clusters in Baden-Württemberg and Bavaria concentrate precision manufacturing capabilities for body plethysmography systems.
Japan
Interstitial lung disease workups requiring DLCO precision concentrate procurement in tertiary care centers across Kanto and Kansai regions. METI standards for medical device software classification align with PMDA guidance on AI-enhanced diagnostic interpretation. Tokyo-based academic medical centers anchor demand for gas diffusion test devices where diagnostic accuracy commands premium positioning.
China
Domestic production of portable diagnostic devices scales to serve county-level hospital networks under national respiratory disease screening mandates. NMPA regulatory pathways for innovative medical devices accelerate market entry for ultrasonic spirometry configurations. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta concentrate flow sensor component supply for both domestic consumption and export markets.
Australia
Elite athletic programs and professional sports medicine institutes drive adoption of precision gas diffusion testing for performance optimization protocols. The TGA's medical device framework governs software-as-medical-device classifications for cloud-native spirometry platforms. Sports medicine research centers in Victoria and New South Wales anchor specialized procurement for research-calibrated pulmonary diagnostic systems.
Pulmonary Function Testing Devices Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement configurations that favor bundled service contracts over standalone hardware sales. Market structure tilts toward consolidation as integrated delivery networks negotiate enterprise-wide vendor relationships. Three archetypes dominate: diversified respiratory care portfolios, precision calibration technology specialists, and portable point-of-care innovators. Competitive moves concentrate on cloud platform integration and subscription-based device provisioning models.
Among diversified portfolio companies, Vyaire Medical, Inc. represents the integrated respiratory care archetype, while COSMED Srl exemplifies precision calibration specialization for clinical and sports applications. ndd Medical Technologies occupies a position within the portable diagnostic segment, anchoring the point-of-care and home monitoring configuration tier.
| Leading Market Players |
|---|
| Schiller AG |
| CHEST M.I., Inc |
| Vyaire Medical, Inc |
| Ganshorn Medizin Electronic |
| Morgan Scientific Inc. |
| MGC Diagnostics Corporation |
| ndd Medical Technologies |
| KoKo PFT |
| COSMED Srl |
| Others |
Supply Flow & Price Mechanics
Hospital system procurement consolidation into bundled cloud-platform contracts is compressing standalone hardware margins and forcing manufacturers to absorb calibration service costs into subscription pricing. This demand-side restructuring concentrates pricing power among integrated delivery networks while fragmenting supplier negotiating leverage.
Pricing Analysis
Margin tightening in portable device tiers reflects CMS reimbursement compression and interest rate sensitivity driving preference for operational expenditure models. Three-tier pricing structure across premium laboratory systems, mid-range clinic configurations, and economy home-care units stratifies by calibration precision and software integration depth. Cost-down pressure on stationary systems accelerates as cloud-native competitors displace legacy pneumotachograph vendors through subscription bundling. Independent physician practices exhibit highest price sensitivity; tertiary academic medical centers prioritize diagnostic accuracy over unit cost.
Supply Chain Analysis
CE marking and FDA 510(k) certification gating concentrates qualified component supply in Germany, Japan, and the United States where precision calibration infrastructure meets regulatory documentation standards. Ultrasonic flow sensors draw from East Asian manufacturing clusters while gas diffusion measurement assemblies source from Swiss and Italian precision instrumentation specialists. Single-source vulnerability in time-of-flight sensor supply creates exposure to geopolitical disruption and shipping volatility. Distribution runs through hospital system GPO contracts and direct manufacturer relationships with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultrasonic spirometry is displacing traditional pneumotachograph technology across point-of-care configurations, creating asymmetric transition risks for legacy equipment portfolios.
For Market Incumbents: Anchor enterprise contracts through backward integration into cloud data management platforms and predictive maintenance services. Vyaire Medical's integrated respiratory care portfolio demonstrates how hospital system relationships resist disintermediation by point-of-care specialists. Defensive certification investment in FDA software-as-medical-device pathways offsets emerging AI-native competitors. For New Entrants and Emerging Players: AI-enhanced pattern recognition algorithms for automated obstructive-restrictive classification offer technology-first wedge positioning against interpreter-dependent incumbents. Federally Qualified Health Centers in rural United States represent the most penetrable segment given pulmonologist shortages and synchronous telemedicine transmission requirements. Tablet-interfaced portable configurations with minimal training requirements enable rapid operator pool expansion beyond specialized pulmonary technicians. For Investors and Strategic Acquirers: The window for entry favors portable diagnostic specialists with validated AI software modules and established CMS reimbursement codes. Long-term viability hinges on consolidation resilience as integrated delivery networks narrow vendor panels to three or fewer enterprise relationships. Watch for FDA software classification guidance expansion as inflection indicator for algorithm-driven feature time-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | European Medical Device Regulation clinical evidence requirements extend time-to-market for cloud-native platforms. |
| Hospital System Partnership | Integrated delivery network enterprise contracts bundle stationary laboratory systems with data management services. |
| Software Companion Development | AI pattern recognition modules reduce interpreter dependency and expand operator pools beyond pulmonary technicians. |
| Reimbursement Strategy | CMS remote patient monitoring code expansion accelerates portable spirometer deployment for COPD home management. |
| FDA Submission | 510(k) clearance pathway streamlines premarket notification for ultrasonic and oscillometric device configurations. |
Methodological Framework
Independent corroboration across hospital purchasing committee interviews, biomedical engineer surveys, and GPO contract databases underwrites the qualitative findings. Primary fieldwork engaged pulmonary laboratory directors, respiratory care department heads, and medical device procurement specialists across tertiary care centers in the United States, Germany, and Japan. Secondary validation drew from FDA 510(k) filings, CE marking notified body documentation, CMS Medicare reimbursement data, and hospital equipment procurement records. Bottom-up unit placement estimates triangulate against top-down spending analysis across the forecast period.
Comparable-period anchoring to historical replacement cycle data and reimbursement pathway maturation timelines structures the projection horizon. Segmentation modeling spans product type, end-user configuration, technology architecture, and application indication dimensions. CAGRs derive from equipment utilization rate trajectories and capital expenditure sensitivity analysis across hospital system, clinic, and home care settings. Forecast inputs incorporate aging demographic profiles, chronic respiratory disease prevalence indices, and regulatory approval velocity assumptions.
Several conditions sit outside the modeled scope, including unanticipated FDA software classification guidance revisions, geopolitical disruption to East Asian sensor supply, and radical reimbursement framework restructuring. Forecasts reflect documented assumptions regarding calibration infrastructure availability and telemedicine integration adoption curves. A model refresh is warranted upon material change in CMS remote patient monitoring code coverage or European Medical Device Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
ENT Diagnostic Devices Market
Diagnostic Devices
US Point of Care Diagnostics Market
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
Diagnostic Stopper Market
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
Electrochemical Biosensors Market
Diagnostic Devices
United States Biopsy Devices Market
Diagnostic Devices
Europe Point of Care Diagnostics Market
Diagnostic Devices
Companion Diagnostics Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
AI Portable Chest X-ray Triage Device Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
Skin Moisture Detectors Market
Diagnostic Devices
Calprotectin Serum Immunoassay Market
Diagnostic Devices
GCC Breath Analyzer Market