
 Global Dermatology Diagnostic Devices Market | 2026-2036
Global Dermatology Diagnostic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dermatology Diagnostic Devices Market Foresight
EU MDR is consolidating the cost-of-entry calculus for dermatology diagnostic device manufacturers seeking European market access. Canfield Scientific leverages its digital imaging heritage to sustain leadership in skin analysis systems across North American dermatology clinics. FotoFinder Systems GmbH anchors its competitive position through specialized dermoscopy platforms with integrated AI-based analysis capabilities.
Dermatology diagnostic devices encompass precision optical and electronic instruments engineered to detect, visualize, and quantify cutaneous pathologies at resolutions reaching cellular and subcellular levels, employing wavelengths from visible light through near-infrared spectra to generate actionable clinical data. These systems serve the primary commercial purpose of enabling early-stage disease identification, treatment monitoring, and procedural guidance in dermatological practice. Dermatoscopes and optical coherence tomography devices command established margin pools in skin cancer screening workflows, while AI-based analysis technology represents the fastest-expanding segment as machine learning algorithms gain regulatory clearance for autonomous lesion classification. Skin analyzers occupy a mature position in cosmetic center applications where non-diagnostic aesthetic assessment drives replacement cycles.
FDA clearance pathways and EU MDR conformity assessment procedures shape product development timelines and commercialization strategies for device manufacturers targeting major markets. Japan's PMDA maintains distinct clinical evidence requirements that influence trial design for companies including Carl Zeiss AG and Bruker Corporation seeking Asian market entry. Stakeholders must monitor evolving reimbursement codes for AI-augmented diagnostics as payer policies increasingly determine adoption velocity in institutional settings.
Market Dynamics
AI-augmented diagnostic platforms are compressing traditional dermoscopy workflows and forcing device manufacturers to rebuild software-hardware integration architectures around machine learning inference engines rather than standalone optical systems.
Growth Catalysts
- EU MDR certification pathways:The Medical Device Regulation's risk-based classification system for software-as-a-medical-device is creating clear commercialization roadmaps for AI-enabled lesion analysis tools across Germany, France, and Italy.
- Teledermatology networks:Remote consultation platforms in rural United States and Australian territories are driving hardware procurement for high-resolution image capture devices that integrate with cloud-based specialist review systems.
- Photonics manufacturing clusters:Precision optical component foundries concentrated in Stuttgart and Jena are reducing sensor costs for multispectral imaging modules used in next-generation skin analyzers.
Market Restraints
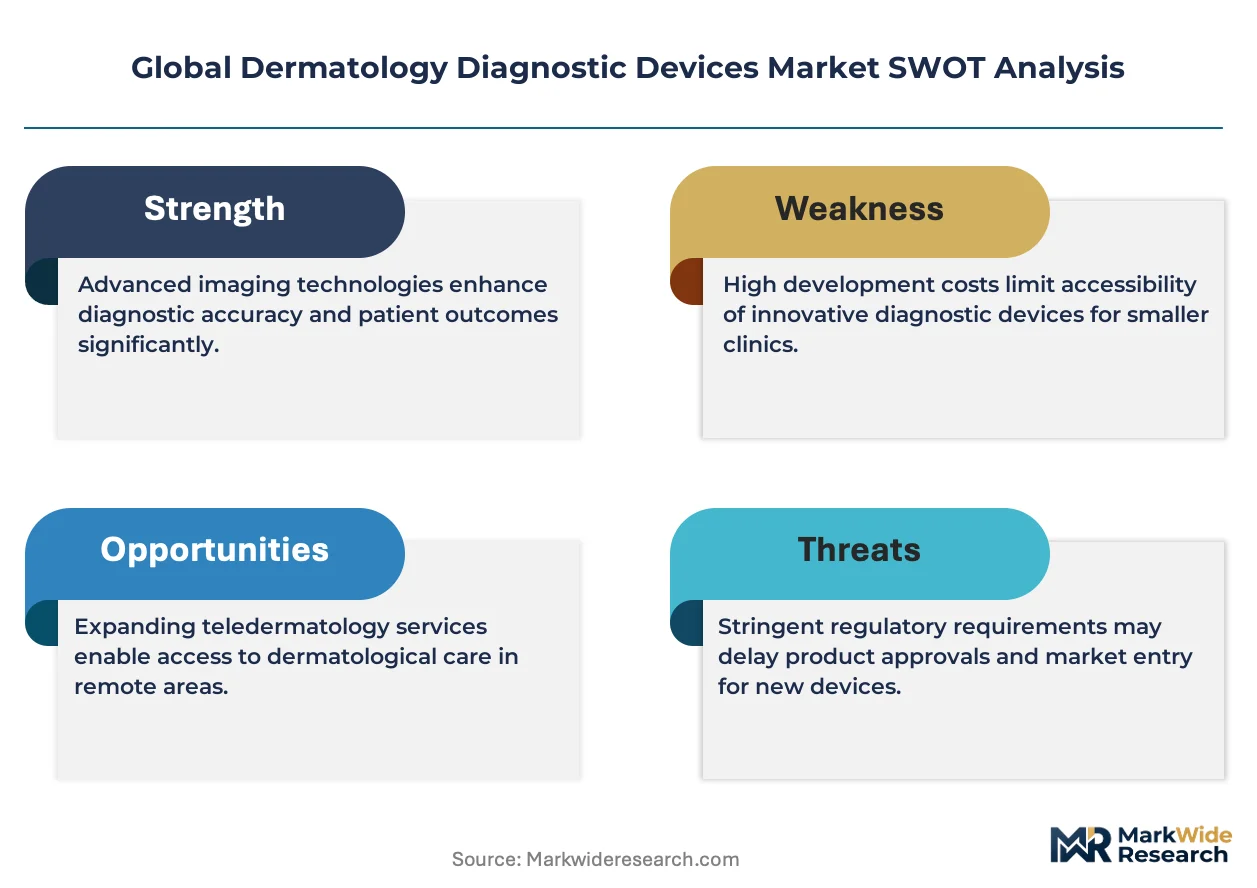
- EU MDR conformity assessment costs:The notified body capacity bottleneck extends technical documentation review timelines to 18-24 months for Class IIa dermatology devices seeking European market access.
- CMOS sensor supply concentration:Advanced image sensor fabrication depends on Taiwan Semiconductor Manufacturing and Samsung Foundry capacity allocation priorities affecting dermatoscope OEM delivery schedules.
- Reimbursement code fragmentation:Inconsistent CPT coding for AI-assisted diagnosis across US commercial payers and Medicare administrative contractors creates revenue recognition uncertainty for clinic purchasers.
Strategic Opportunities
- Brazil's SUS integration:The Unified Health System's expanding dermatology screening programs in São Paulo and Minas Gerais states represent untapped volume for portable dermoscopy devices with embedded connectivity.
- Multimodal imaging convergence:Combined optical coherence tomography and reflectance confocal microscopy systems are opening procedural guidance applications in Mohs surgery suites previously served by single-modality equipment.
- India's PLI scheme for medical electronics:Production-linked incentives for domestic manufacturing of diagnostic devices are attracting component suppliers to set up final assembly operations in Andhra Pradesh and Karnataka.
Industry Challenges
- Algorithm validation expertise:Clinical evidence generation for FDA 510(k) clearance of autonomous lesion classification requires dermatopathologist-annotated training datasets that exceed most device firms' in-house capabilities.
- Legacy PACS integration:Hospital IT departments face interoperability friction when connecting cloud-native AI diagnostic platforms to on-premise DICOM archives and electronic health record systems from entrenched vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dermatology Diagnostic Devices Market |
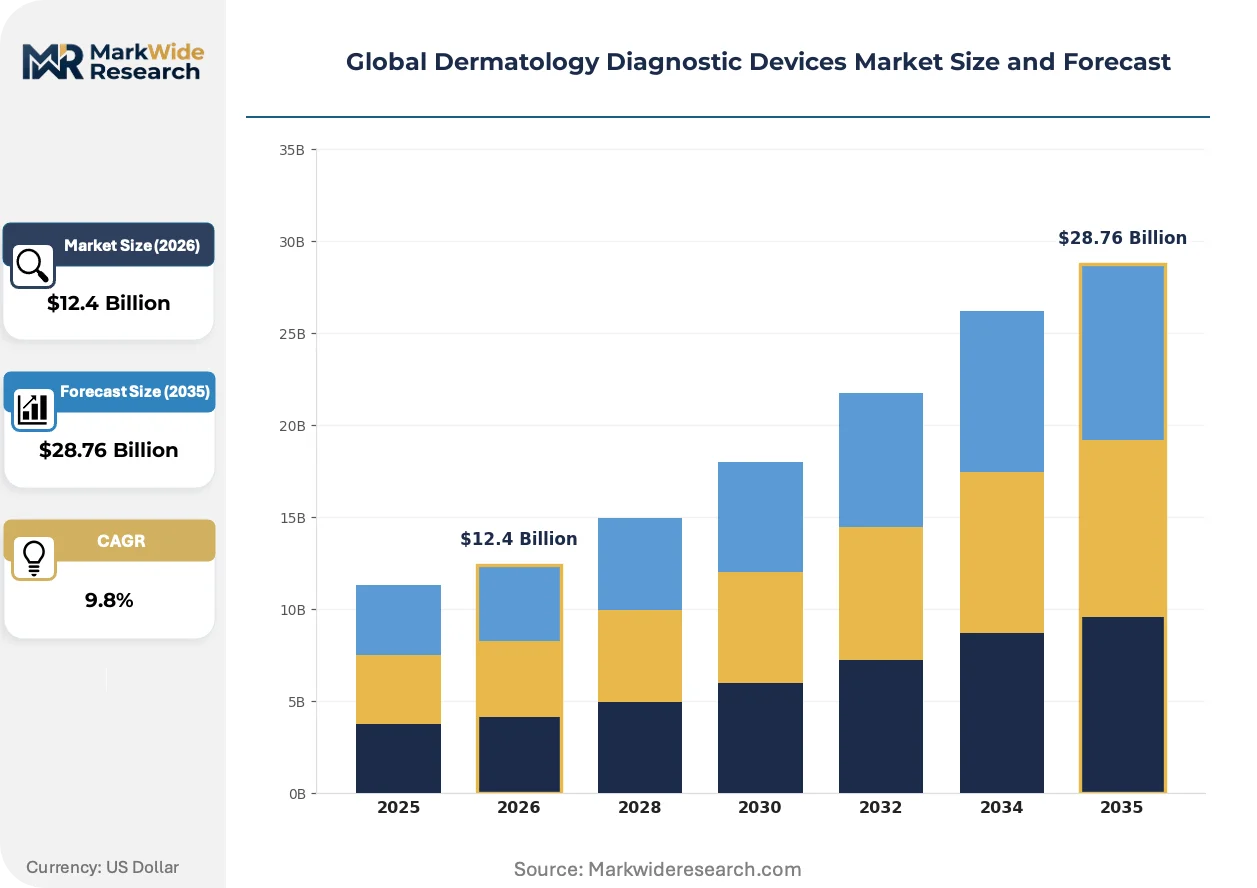
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.76 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dermatoscopes, Confocal Microscopes, Optical Coherence Tomography Devices, Ultrasound Devices, Skin Analyzers Technology: Digital Imaging, 3D Imaging, AI-Based Analysis, Multispectral Imaging, Laser Scanning Application: Skin Cancer Screening, Psoriasis Assessment, Atopic Dermatitis Monitoring, Acne Diagnosis, Pigmentation Evaluation End User: Dermatology Clinics, Research Institutions, Cosmetic Centers, Telemedicine Providers, Academic Hospitals |
| Companies Covered | HEINE Optotechnik GmbH & Co. KG, Canfield Scientific, FotoFinder Systems GmbH, Caliber Imaging & Diagnostics, Michelson Diagnostics Ltd., Carl Zeiss AG, Agfa-Gevaert Group, Bruker Corporation, STRATA Skin Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dermatology Diagnostic Devices Market Shifts & Advancements
Computational dermatology is shifting from assistive image enhancement toward autonomous diagnostic decision support, rewiring competitive advantage toward software architecture and regulatory science capabilities rather than pure optical engineering.
Multispectral imaging systems capturing wavelengths from 400nm through 1000nm are penetrating academic medical center dermatology departments in the United States and Germany. These platforms enable subsurface melanin and hemoglobin mapping beyond visible-light dermoscopy limitations. The technology is converging with convolutional neural network architectures trained on histopathology-correlated image banks, collapsing the traditional separation between screening and diagnostic modalities.
Japan's PMDA revised its guidance on machine learning-enabled medical devices in 2022, establishing distinct clinical trial requirements for locked-algorithm versus continuously learning AI systems. Manufacturers targeting Japanese market entry must now structure prospective validation studies with predetermined performance thresholds rather than retrospective database analyses. Domestic dermatology clinics in Tokyo and Osaka are prioritizing PMDA-cleared devices in procurement decisions, creating first-mover advantages for firms completing these evidentiary requirements.
Subscription-based equipment access models are displacing capital purchase arrangements in US dermatology group practices facing cash flow pressure from reimbursement compression. Device manufacturers including Canfield Scientific and FotoFinder Systems GmbH now offer per-scan pricing for AI analysis modules bundled with hardware leases. This shift concentrates most visibly in California and Texas multi-site dermatology platforms seeking to align diagnostic technology costs with patient visit volumes rather than fixed asset depreciation schedules.
Global Dermatology Diagnostic Devices Market Segmentation
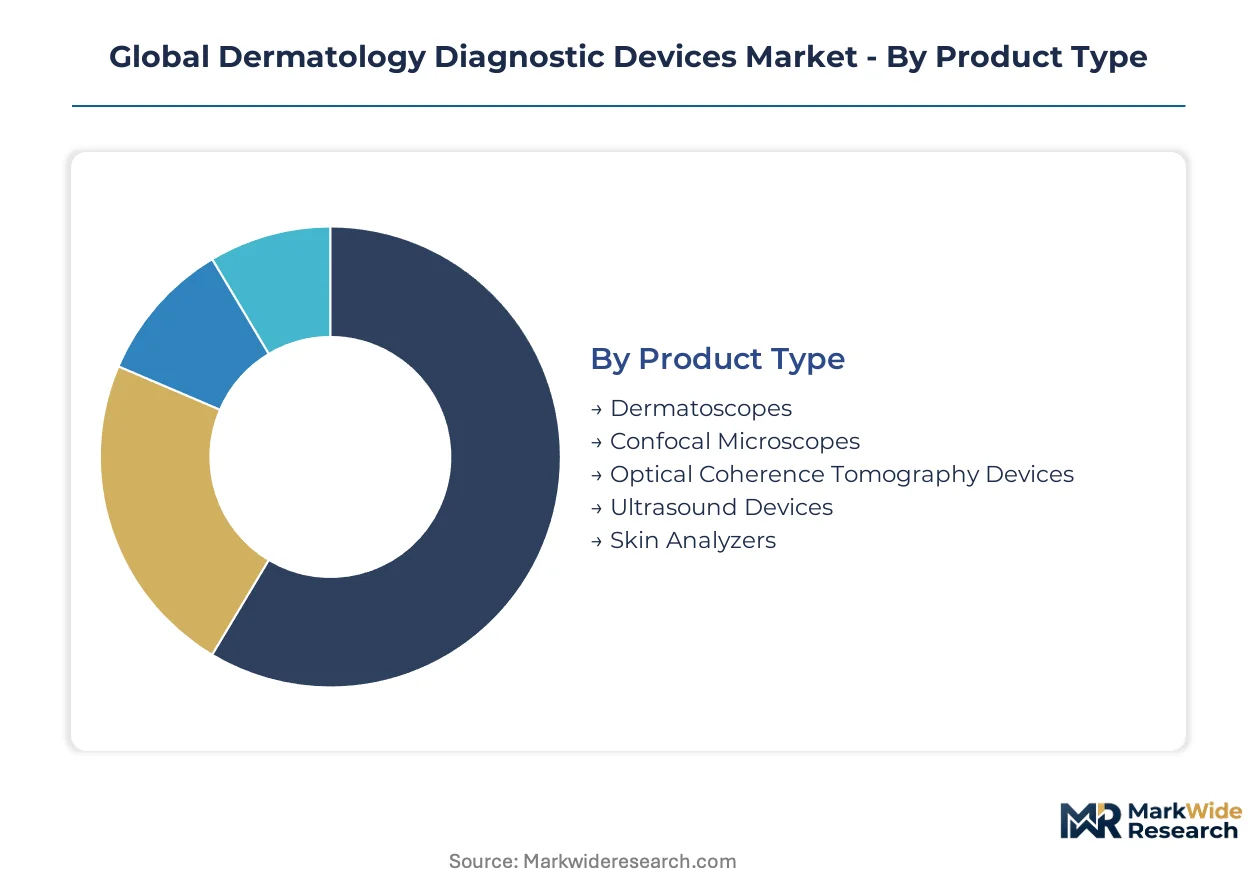
Dermatology diagnostic devices fragment across four critical dimensions that shape procurement patterns and vendor positioning. Product type determines capital intensity and replacement cycles. Technology selection increasingly hinges on AI integration depth rather than optical specifications alone. Application focus dictates reimbursement pathway complexity. End-user category determines whether sales cycles emphasize clinical workflow efficiency or research publication potential.
Product Type:
Capital allocation priorities in dermatology practices drive purchasing hierarchy across device categories, with screening volume and procedural reimbursement rates determining equipment mix.
- Dermatoscopes:Handheld and video-dermoscopy systems remain the foundational screening tool in melanoma detection protocols across United States outpatient clinics and German dermatology centers. Demand concentrates in high-throughput screening programs where portable units with integrated image archiving justify per-procedure cost recovery. FDA 510(k) clearance pathways for dermatoscope hardware are well-established, compressing vendor entry timelines relative to novel modalities.
- Optical Coherence Tomography Devices:Cross-sectional imaging systems capture micrometer-resolution subsurface tissue architecture using near-infrared interferometry, enabling non-invasive visualization of epidermal and dermal structures previously requiring biopsy. Adoption clusters in academic medical centers in Boston and Heidelberg where research funding subsidizes capital acquisition and Mohs surgery suites demand real-time margin assessment. Reimbursement coding for OCT-guided procedures remains fragmented across US Medicare administrative contractors.
- Confocal Microscopes:Reflectance confocal microscopy provides cellular-level resolution without tissue excision, serving specialized diagnostic confirmation roles.
- Ultrasound Devices:High-frequency ultrasound systems measure tumor thickness and monitor treatment response in inflammatory conditions.
- Skin Analyzers:Multispectral cosmetic assessment devices dominate aesthetic clinic workflows in Seoul and Dubai where non-diagnostic applications drive replacement demand.
Dermatoscopes lead on scale; optical coherence tomography devices lead on momentum.
Technology:
Software architecture capabilities now differentiate vendor competitiveness more decisively than optical engineering heritage, rewiring R&D investment priorities across the industry.
- AI-Based Analysis:Machine learning algorithms trained on dermatopathology-annotated image libraries enable autonomous lesion classification with sensitivity metrics approaching specialist dermatologist performance. Regulatory clearance under FDA's software-as-a-medical-device pathway and EU MDR's risk-based classification system is accelerating commercial deployment across North American and European markets. PMDA's 2022 guidance on locked-algorithm versus continuously learning systems is shaping trial design for Japanese market entry.
- Digital Imaging:High-resolution CMOS and CCD sensor platforms with standardized DICOM output remain the technical baseline for image capture workflows. Supply concentration at Taiwan Semiconductor Manufacturing and Samsung Foundry is creating delivery uncertainty for OEMs dependent on advanced sensor fabrication.
- Multispectral Imaging:Wavelength-selective systems capturing 400-1000nm spectra enable subsurface chromophore mapping beyond visible-light limitations.
- 3D Imaging:Stereoscopic and structured-light surface reconstruction supports cosmetic treatment planning and volumetric tracking.
- Laser Scanning:Confocal and optical coherence tomography modalities employ coherent light sources for depth-resolved tissue imaging.
Digital imaging leads on installed base; AI-based analysis climbs the fastest.
Application:
Clinical indication determines reimbursement code availability and thus equipment utilization economics, with oncology applications commanding premium positioning.
- Skin Cancer Screening:Melanoma and non-melanoma detection protocols drive the highest device utilization rates and justify capital investment in multi-modality imaging suites. Germany's statutory health insurance system reimburses dermoscopy examinations at rates supporting equipment amortization, while US commercial payer policies vary by state and plan type. Screening program expansion in Australia's rural territories is creating demand for portable devices with cloud connectivity.
- Psoriasis Assessment:Severity scoring and treatment response monitoring applications leverage standardized imaging protocols for clinical trial endpoints and biologic therapy management. Academic hospitals in Copenhagen and Rotterdam are deploying AI-augmented plaque segmentation tools for longitudinal outcome tracking.
- Atopic Dermatitis Monitoring:Eczema severity quantification supports pediatric and adult treatment optimization.
- Acne Diagnosis:Lesion counting and inflammation grading serve cosmetic and therapeutic indication workflows.
- Pigmentation Evaluation:Melasma and vitiligo assessment applications concentrate in aesthetic dermatology practices.
Skin cancer screening leads on revenue concentration; psoriasis assessment gains share fastest.
End User:
Procurement authority and budget source—clinical operating revenue versus research grants versus consumer-direct payment—create distinct sales motion requirements across customer categories.
- Dermatology Clinics:Private and group practice settings in Texas and California are shifting from capital purchase to subscription-based equipment access models that align diagnostic technology costs with patient visit volumes. Per-scan pricing for AI analysis modules bundled with hardware leases is displacing fixed asset depreciation schedules.
- Academic Hospitals:Research-active institutions in Boston, New York, and Munich prioritize devices supporting clinical trial endpoints and publication output, with procurement decisions influenced by principal investigator preferences and grant funding availability.
- Research Institutions:Dedicated dermatology research centers demand highest-resolution modalities for mechanistic studies.
- Cosmetic Centers:Aesthetic-focused practices in Seoul and Dubai drive skin analyzer replacement cycles where non-diagnostic applications predominate.
- Telemedicine Providers:Remote consultation platforms in rural United States and Australian territories require high-resolution image capture hardware integrated with cloud-based specialist review systems.
Dermatology clinics lead on volume; telemedicine providers show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized dermatopathologists and AI algorithm engineers concentrate in Boston, Heidelberg, and Tokyo, anchoring the geographic distribution of device development and clinical validation capacity across major markets.
United States
Teledermatology networks in rural Montana and Alaska drive procurement of portable dermoscopy hardware with cloud connectivity. FDA 510(k) clearance pathways for AI-augmented diagnostic software compress commercialization timelines relative to European counterparts. Dermatology group practices in Texas and California are shifting to subscription-based equipment access models that align technology costs with patient visit volumes.
Germany
Precision photonics manufacturing clusters in Stuttgart and Jena supply multispectral imaging sensors at declining unit costs for next-generation skin analyzers. EU MDR conformity assessment procedures extend technical documentation review timelines to 18-24 months for Class IIa devices. Statutory health insurance reimbursement rates for dermoscopy examinations support equipment amortization in outpatient dermatology centers across Bavaria and North Rhine-Westphalia.
Japan
Academic medical centers in Tokyo and Osaka prioritize PMDA-cleared devices in procurement decisions following the 2022 guidance on locked-algorithm versus continuously learning AI systems. Domestic manufacturers face distinct clinical trial requirements with predetermined performance thresholds rather than retrospective database analyses. Kanto region dermatology clinics are deploying multimodal imaging systems for melanoma screening protocols.
Australia
Rural territory screening programs in Queensland and Western Australia create demand for high-resolution image capture devices integrated with cloud-based specialist review systems. TGA regulatory frameworks align with FDA precedents for software-as-a-medical-device classification. Sydney and Melbourne academic hospitals are validating AI-based lesion classification algorithms for deployment in remote consultation workflows.
Brazil
Unified Health System dermatology screening expansion in São Paulo and Minas Gerais states represents volume opportunity for portable dermoscopy devices with embedded connectivity. ANVISA medical device registration procedures require in-country clinical evidence for novel diagnostic modalities. Domestic distributors in Southeast Brazil are building technical service capacity for AI-integrated imaging platforms.
Global Dermatology Diagnostic Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the dermatology diagnostic devices landscape. The vendor base separates into three strategic tiers: optical engineering heritage firms with multispectral imaging platforms, AI-native software developers seeking hardware partnerships, and aesthetic equipment manufacturers diversifying into clinical diagnostic applications. Dominant competitive moves include strategic partnerships between sensor fabricators and algorithm developers, plus geographic expansion through distributor relationships in underserved Latin American and Southeast Asian markets.
Within the optical engineering tier, Carl Zeiss AG and Bruker Corporation represent diversified conglomerates with precision instrumentation heritage extending into dermatology applications. Canfield Scientific and FotoFinder Systems GmbH exemplify focused specialists that have rebuilt competitive positioning around AI-integrated software architectures rather than standalone hardware specifications. These four companies occupy positions across the premium and mid-market segments, with geographic origins spanning German precision manufacturing clusters and North American digital health innovation corridors.
| Leading Market Players |
|---|
| HEINE Optotechnik GmbH & Co. KG |
| Canfield Scientific |
| FotoFinder Systems GmbH |
| Caliber Imaging & Diagnostics |
| Michelson Diagnostics Ltd. |
| Carl Zeiss AG |
| Agfa-Gevaert Group |
| Bruker Corporation |
| STRATA Skin Sciences |
| Others |
Supply & Pricing Matrix
Captive sensor fabrication in Taiwan and South Korea anchors both supply security and pricing power for dermatoscope OEMs, while EU MDR certification costs feed directly into premium tier positioning for AI-augmented platforms. Subscription-based equipment access models in US dermatology group practices are compressing upfront capital requirements and shifting margin capture toward recurring software revenue streams.
Pricing Analysis
Bundled service splits separate hardware lease arrangements from per-scan AI analysis fees across US dermatology group practices. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status and algorithm training dataset scale. Cost compression in mid-market dermatoscope tiers is intensifying because CMOS sensor supply concentration limits vendor negotiation leverage. Price-sensitive buyers cluster in Brazil's SUS procurement programs, while least-sensitive purchasers occupy academic medical centers in Boston and Heidelberg where research funding subsidizes capital acquisition.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gating restricts component sourcing to qualified optical foundries in Germany, Japan, and the United States. Advanced image sensor fabrication draws from Taiwan Semiconductor Manufacturing and Samsung Foundry capacity allocation priorities. Single-source vulnerability concentrates in specialized dermoscopy optics from Stuttgart precision manufacturing clusters. Distribution runs through authorized medical device distributors with in-country service capability for AI-integrated platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR certification timelines and FDA software-as-a-medical-device pathways create demand acceleration for cleared AI diagnostic platforms.
For Market Incumbents: Anticipate margin compression from AI-native software developers seeking hardware partnerships by deepening backward integration into multispectral sensor design and securing exclusive algorithm licensing arrangements. Prioritize EU MDR notified body relationship investment to compress 18-24 month conformity assessment timelines. Channel control through direct sales forces in Texas and California dermatology group practices remains essential.
For New Entrants and Emerging Players: Rural telemedicine providers in Australian territories and US frontier states represent underserved buyer archetypes with limited incumbent penetration. White-space targets include portable dermoscopy devices with embedded cloud connectivity for Brazil's SUS expansion and subscription-priced AI modules for mid-market dermatology clinics. Go-to-market angle should emphasize per-scan pricing alignment with patient visit volume variability.
For Investors and Strategic Acquirers: Roll-up economics work for AI-native diagnostic software specialists because EU MDR and FDA regulatory clearance scarcity creates durable competitive moats. Long-term viability framing favors platforms with locked-algorithm validation completing PMDA requirements for Japanese market entry. Acquisition target archetype includes dermatopathology-annotated training dataset owners. Signal to watch is reimbursement code consolidation for AI-assisted diagnosis across US Medicare administrative contractors.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates commercial deployment for AI lesion classification algorithms in US dermatology clinics. |
| CE Marking Pathway | Unlocks statutory health insurance reimbursement access across German outpatient dermatology centers. |
| Hospital System Partnership | Secures Mohs surgery suite placement for optical coherence tomography guidance applications. |
| Software Companion Development | Enables locked-algorithm PMDA clearance for Tokyo and Osaka academic medical center procurement. |
| Reimbursement Strategy | Resolves CPT coding fragmentation for AI-assisted diagnosis across US commercial payers. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with dermatology clinic directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers alongside secondary validation from FDA 510(k) filings, EU MDR technical documentation, CMS Medicare reimbursement databases, and PMDA medical device approval records. Bottom-up equipment shipment analysis triangulates against top-down healthcare expenditure allocation estimates.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, clinical application, and end-user category with regional regulatory cluster overlay. CAGRs derive from installed base growth, replacement cycle compression, and software attachment rate progression. Industry-specific forecast inputs incorporate teledermatology network expansion trajectories and AI algorithm regulatory clearance pipelines.
Underlying measurement precision varies by segment; AI-based analysis platforms carry tighter precision than mature skin analyzer categories due to visible regulatory milestone tracking. Forecasts reflect documented assumptions regarding reimbursement code evolution and notified body capacity expansion. A model refresh is warranted upon material change in FDA software-as-a-medical-device guidance or EU MDR delegated act revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
US Breath Analyzers Market
Diagnostic Devices
Calprotectin Serum Immunoassay Market
Diagnostic Devices
Europe Breath Analyzer Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Global DNA Test Kit Market
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Hearing Screening Diagnostic Devices Market
Diagnostic Devices
Automated Visual Field Analyzer Market
Diagnostic Devices
Amniotic Fluid Detection Market
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
Companion Diagnostics Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
Immunology-Oncology ELISA Kits Market
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
US Point of Care Diagnostics Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market