
 Corn Starch Market | 2026-2036
Corn Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Starch Market Intelligence
Food-grade specification upgrades is reorganizing procurement priorities across the corn starch value chain. Cargill Incorporated leverages its North American grain origination network to secure consistent raw material flows. Ingredion Incorporated differentiates through specialty modified starch portfolios tailored to bakery and dairy applications. Roquette Frères anchors European supply with pea and corn hybrid processing capabilities that extend its ingredient reach.
Corn starch is a carbohydrate polymer extracted from maize endosperm, typically containing twenty-five to twenty-eight percent amylose with the balance as amylopectin, produced through wet milling involving steeping, grinding, and multi-stage centrifugal separation; it functions primarily as a thickening agent, binder, and texturizer across industrial and consumer applications. Modified starch commands premium positioning due to enhanced freeze-thaw stability and shear resistance demanded by ready-meal manufacturers. Native corn starch retains volume leadership in paper and packaging applications where cost efficiency governs mill procurement decisions. Pharmaceutical formulations represent the fastest-growing application as tablet disintegrant specifications tighten.
FDA food additive regulations and GRAS self-affirmation pathways govern ingredient approval timelines in the United States, while REACH compliance and the EU Green Deal bioeconomy targets reshape European manufacturing investments. China's GB standards and dual carbon goals from MEE are redirecting industrial starch demand toward biodegradable material feedstocks. Stakeholders must monitor how divergent regional sustainability mandates recalibrate plant expansion timelines and certification requirements.
Market Dynamics
Clean-label formulation mandates across food and beverage manufacturing are compressing procurement timelines and forcing starch suppliers to accelerate native-to-modified conversion capabilities. Wet millers now face dual pressure from EU F-Gas solvent restrictions and China's biodegradable material quotas, reshaping capital allocation toward bioplastics feedstock production.
Growth Catalysts
- Bioplastics feedstock demand:China's MEE dual carbon goals redirect industrial starch volumes toward polylactic acid and polyhydroxyalkanoate precursors, creating dedicated supply streams from Shandong and Jilin processing clusters.
- REACH solvent compliance:EU Green Deal bioeconomy targets phase petroleum-derived solvents from extraction processes, advantaging corn ethanol-based purification systems in European wet milling operations.
- Pharmaceutical disintegrant specifications:Tightened tablet dissolution standards from FDA and EMA accelerate high-amylose starch qualification for generic drug manufacturers in North America and Western Europe.
Market Restraints
- Maize price volatility:Drought-induced yield compression in Argentina and Ukraine export corridors transmits directly to starch processor margins, with limited hedging instruments available for six-month forward contracts.
- Thailand supply concentration:Over sixty percent of tapioca starch substitution originates from Thai processing cooperatives, creating arbitrage pressure on corn starch pricing during El Niño crop cycles.
- Modified starch technical ceilings:Current cross-linking chemistries fail to deliver simultaneous acid stability and freeze-thaw performance demanded by retort pouch ready-meal manufacturers.
Strategic Opportunities
- India PLI scheme alignment:Production-linked incentives for biodegradable packaging create localized starch derivative demand from Maharashtra and Gujarat food exporters seeking EU market access.
- Cellular agriculture nutrient media:Precision fermentation startups require pharmaceutical-grade dextrose and maltodextrin streams, opening premium pricing tiers for corn wet millers with USP certification.
- Direct-to-bakery distribution platforms:Specialty ingredient e-procurement channels bypass traditional distributor markups for artisanal bread and pastry manufacturers in France, Italy, and Spain.
Industry Challenges
- Enzyme engineering talent scarcity:Wet milling optimization requires rare combinations of protein biochemistry and process engineering expertise concentrated at Iowa State University and Wageningen University pipelines.
- GRAS self-affirmation timeline compression:Novel modified starch variants face eighteen-to-twenty-four month FDA documentation cycles, delaying commercialization against faster European EFSA novel food pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Starch Market |
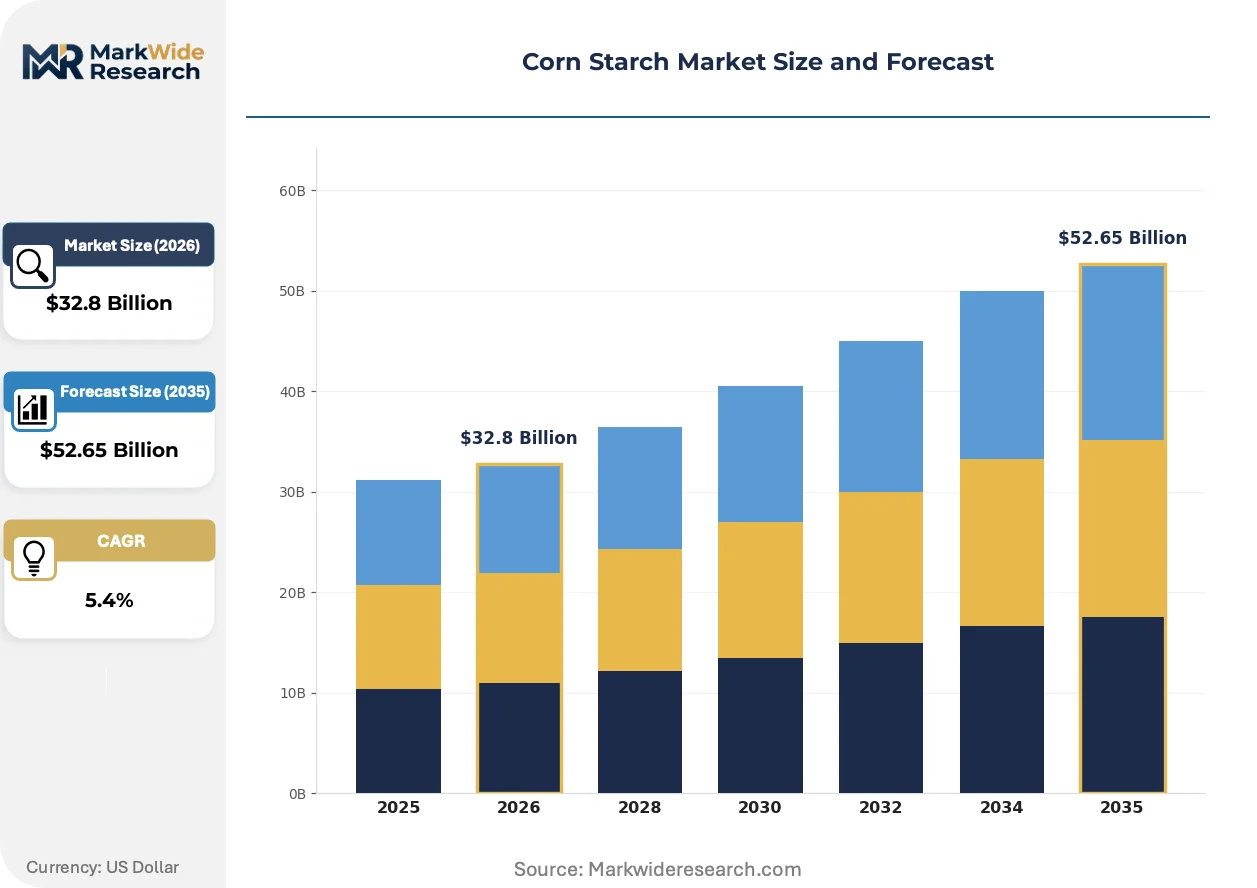
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Corn Starch, Modified Starch, Pregelatinized Starch, Acid-Thinned Starch, Cross-Linked Starch Application: Food & Beverage, Paper & Packaging, Textile Manufacturing, Pharmaceutical Formulations, Adhesives Production End User Industry: Confectionery Makers, Paper Mills, Textile Plants, Pharmaceutical Manufacturers, Glue Producers Packaging Type: Bulk Bags, Kraft Paper Bags, Polyethylene Bags, Valve Bags, Cardboard Boxes |
| Companies Covered | Tate & Lyle PLC, Tereos Starch & Sweeteners, Cargill Incorporated, AGRANA Beteiligungs-AG, Royal Avebe U.A., Archer Daniels Midland Company, Roquette Frères, Grain Processing Corporation, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Starch Market Strategic Shifts & Innovations
Biotechnology convergence with traditional wet milling is dissolving boundaries between commodity starch production and specialty ingredient manufacturing. Equipment miniaturization and continuous processing architectures are enabling distributed processing models that bypass historical scale advantages.
Membrane filtration technology is miniaturizing separation economics for small-batch modified starch production. Regional bakery cooperatives in Germany and the Netherlands now deploy skid-mounted ultrafiltration units for on-site glucose syrup conversion. This distributed architecture compresses logistics costs and enables just-in-time viscosity customization for artisanal bread lines.
EU F-Gas Regulation phase-down schedules force solvent recovery system retrofits across European wet milling facilities. Industrial starch processors in Belgium and France now invest in closed-loop hexane recovery to maintain extraction efficiency while eliminating vented emissions. Modified starch lines with solvent-free oxidation pathways gain competitive preference for sustainable sourcing certifications.
Clean-label procurement criteria now disqualify chemically modified starches from premium retail positioning. European ready-meal manufacturers specify physically treated starches for private-label lines, compressing demand for E1442 and E1422 food additives. Native starch blends with hydrocolloid synergists capture shelf-space in UK and Scandinavian supermarkets where ingredient panel simplicity drives repeat purchase.
Corn Starch Market Segmentation
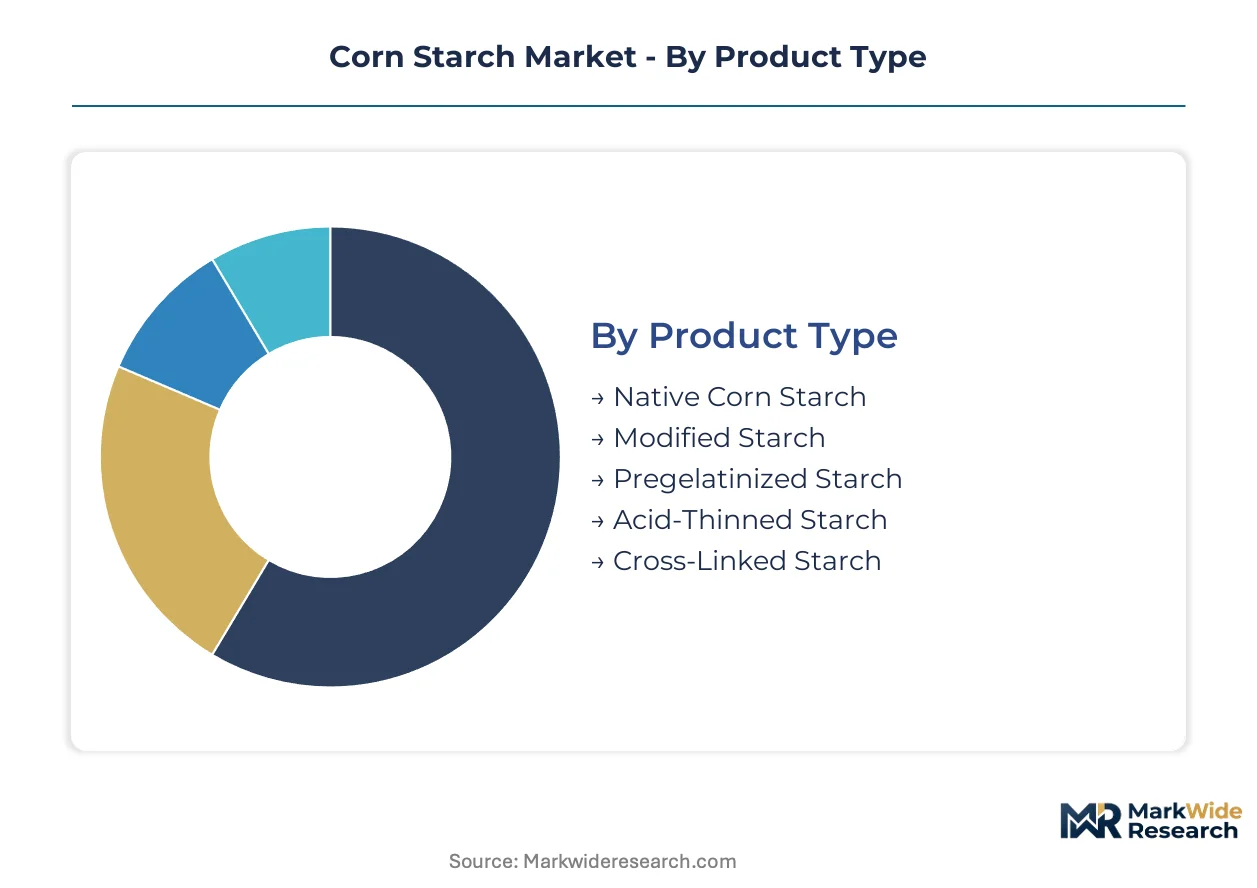
Corn starch procurement patterns diverge sharply across product specifications and end-use requirements. Wet millers must configure production lines around viscosity profiles, regulatory thresholds, and packaging formats that vary by customer scale and application sensitivity.
Product Type:
Substitution pressure from tapioca and potato starches hits hardest at the commodity end of the spectrum, forcing differentiation through functional performance rather than price alone.
- Native Corn Starch:Standard amylose-amylopectin composition (25-28% amylose) extracted through conventional wet milling without chemical alteration. Paper mills in the American Midwest and packaging converters across Germany and Belgium anchor procurement volumes here, though margin compression from Thai tapioca arbitrage limits pricing power during El Niño crop cycles.
- Modified Starch:Chemical or physical alteration delivers enhanced freeze-thaw stability, acid resistance, and shear tolerance for demanding food processing conditions. Ready-meal manufacturers in France and the United Kingdom specify hydroxypropylated and acetylated variants for retort pouch applications where EFSA additive regulations govern clean-label positioning.
- Pregelatinized Starch:Pre-cooked and dried to enable cold-water solubility for instant food formulations.
- Acid-Thinned Starch:Mild acid hydrolysis reduces molecular weight for low-viscosity film-forming in textile sizing and adhesive binders.
- Cross-Linked Starch:Di-starch phosphate and adipate cross-linking chemistry improves heat and acid stability for canning and pie filling applications.
Native corn starch retains volume leadership; modified starch holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity-grade volumes from pharmaceutical and specialty food segments commanding certification premiums.
- Food & Beverage:Thickening, gelling, and stabilizing functions across bakery, dairy, confectionery, and savory applications. Clean-label mandates from EU retailers and FSSAI formulation standards in India are compressing demand for chemically modified variants while amplifying native starch-hydrocolloid blend procurement.
- Pharmaceutical Formulations:Tablet disintegrants, binders, and excipients requiring USP-NF and EP compliance with specified particle size and moisture parameters. Generic drug manufacturers in North America and Western Europe are accelerating high-amylose starch qualification as FDA and EMA dissolution standards tighten for immediate-release formulations.
- Paper & Packaging:Surface sizing and coating binders where cost efficiency governs mill procurement decisions.
- Textile Manufacturing:Warp sizing and finishing applications competing with polyvinyl alcohol and synthetic polymer substitutes.
- Adhesives Production:Corrugated board bonding and wallpaper paste formulations sensitive to viscosity stability and gel temperature.
Paper and packaging commands the largest volume share; pharmaceutical applications are climbing the fastest.
End User Industry:
Customer type fragmentation creates divergent service requirements from technical specification support to logistics flexibility.
- Confectionery Makers:Gummy candy and jelly applications requiring specific gel strength and clarity profiles. European artisanal producers and industrial manufacturers in Maharashtra and Gujarat specify acid-thinned and oxidized starches for molded starch depositing processes.
- Pharmaceutical Manufacturers:cGMP-compliant facilities demanding batch documentation, stability data, and excipient certification. Contract development and manufacturing organizations across New Jersey, North Carolina, and Bavaria are consolidating supplier bases to reduce audit burden and secure dual-sourced amylose supply.
- Paper Mills:Integrated pulp and paper operations with captive starch processing or merchant supply contracts.
- Textile Plants:Denim finishing and yarn sizing operations in Turkey, Bangladesh, and Vietnam seeking desize efficiency.
- Glue Producers:Adhesive compounders blending starch with synthetic latex and dextrin for construction and consumer applications.
Paper mills retain volume leadership; pharmaceutical manufacturers hold the steepest expansion curve.
Packaging Type:
Supply concentration in flexible intermediate bulk container manufacturing shapes procurement economics for large-scale industrial buyers.
- Bulk Bags:One-tonne flexible intermediate bulk containers with lined woven polypropylene construction for automated handling systems. Wet millers in Iowa, Illinois, and Shandong deploy bulk bag loading for paper mill and adhesive producer customers with dedicated pneumatic conveying infrastructure.
- Kraft Paper Bags:Multi-wall paper construction with polyethylene moisture barriers for 25-50 kilogram food-grade shipments. European bakery and confectionery ingredient distributors specify heat-sealed valve configurations to prevent contamination during storage and transport.
- Polyethylene Bags:Food-grade linear low-density polyethylene for moisture-sensitive pregelatinized and modified starch variants.
- Valve Bags:Self-sealing paper or plastic construction for dust-free filling of fine-powder pharmaceutical and food grades.
- Cardboard Boxes:Corrugated fiberboard cases for retail-sized consumer packages and sample shipments.
Bulk bags retain volume leadership; valve bags hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina exports corn starch derivatives through Rosario port terminals to Brazilian food processors and European bioplastics manufacturers, creating price transmission corridors that amplify drought-induced volatility across Atlantic trade lanes.
United States
Iowa and Illinois wet milling clusters supply modified starch to ready-meal manufacturers in France and the United Kingdom. FDA GRAS self-affirmation pathways govern novel additive approvals, compressing commercialization timelines against European alternatives. Decatur and Cedar Rapids processing facilities anchor North American supply with integrated grain origination networks.
China
Shandong and Jilin provinces redirect industrial starch volumes toward polylactic acid feedstock production for domestic bioplastics quotas. MEE dual carbon goals and GB standards reshape manufacturing investments away from conventional food-grade output. Qingdao and Changchun processing clusters now dedicate separate lines to biodegradable material precursors.
Germany
Belgian and French wet millers serve German paper mills and adhesive compounders with modified starch variants. EU F-Gas Regulation phase-down schedules force solvent recovery retrofits across extraction facilities. Krefeld and Hamburg chemical parks host closed-loop hexane recovery systems that maintain efficiency while eliminating vented emissions.
India
Maharashtra and Gujarat food exporters seek EU market access through PLI scheme alignment for biodegradable packaging. FSSAI formulation standards compress demand for chemically modified variants while amplifying native starch-hydrocolloid blend procurement. Mumbai and Ahmedabad processing cooperatives now qualify for production-linked incentives targeting sustainable material feedstocks.
Belgium
Antwerp wet milling facilities supply pharmaceutical-grade excipients to contract manufacturers across New Jersey and Bavaria. REACH compliance and EU Green Deal bioeconomy targets phase petroleum-derived solvents from extraction processes. Port-based processing infrastructure enables just-in-time delivery to European generic drug manufacturers with tightened dissolution standards.
Corn Starch Market Key Industry Players
Listed leaders compete with private specialists across grain origination and specialty modification capabilities. The vendor base concentrates around integrated agribusiness conglomerates with captive wet milling capacity, while mid-scale European cooperatives defend niche positions in pharmaceutical-grade certification. Three archetypes dominate: North American grain-integrated processors, European pea-corn hybrid specialists, and Asian bioplastics-dedicated operators. Competitive moves center on backward integration into seed genetics and geographic expansion through port-proximate processing assets.
Among North American grain-integrated processors, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven supply security, while Ingredion Incorporated occupies a position within the specialty modification tier. European presence concentrates through Roquette Frères and AGRANA Beteiligungs-AG, representing hybrid processing capabilities that extend ingredient reach across bakery and dairy applications. Tate & Lyle PLC anchors British-listed positioning in clean-label formulation supply.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Tereos Starch & Sweeteners |
| Cargill Incorporated |
| AGRANA Beteiligungs-AG |
| Royal Avebe U.A. |
| Archer Daniels Midland Company |
| Roquette Frères |
| Grain Processing Corporation |
| Ingredion Incorporated |
| Others |
Cost & Logistics Intelligence
Sixty-day inventory cycles at European wet millers compress hedging windows for maize procurement, tethering margin stability to origination networks in Iowa and Illinois while amplifying price transmission from Black Sea yield volatility. This lead-time exposure concentrates pricing power among grain-integrated processors with captive elevator capacity, leaving toll-dependent operators exposed to Argentine drought premiums.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure spanning pharmaceutical-grade excipients, food-modified starches, and native paper-grade volumes. Price differentiation separates USP-certified pharmaceutical tiers from standard food-grade specifications, with geographic delivery cost layering premiums for EU F-Gas-compliant solvent recovery. Cost compression in commodity native starch intensifies because Thai tapioca arbitrage caps corn starch ceiling prices during El Niño cycles. Paper mills in the American Midwest exhibit highest price sensitivity, while pharmaceutical manufacturers absorb certification premiums for disintegrant-grade amylose supply.
Supply Chain Analysis
Strategic-stockpile preferences dominate among Chinese bioplastics processors building polylactic acid precursor reserves, while just-in-time inventory governs European ready-meal manufacturers with weekly viscosity specification adjustments. Geographic supply concentrates in the United States, China, and Belgium, with wet milling clusters anchored in Iowa, Shandong, and Antwerp port zones. Raw material flows draw from Argentine export corridors, Ukrainian maize harvests, and domestic US elevator networks. Single-source vulnerability concentrates in Thai tapioca substitution channels during climate-induced crop stress. Distribution runs through bulk flexible intermediate bulk containers for paper mill customers, valve bags for pharmaceutical compounders, and kraft paper multi-wall construction for European bakery distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corn starch market functions as a defensive-moat arena where regulatory entrenchment around FDA GRAS self-affirmation and REACH compliance creates multi-year certification barriers that protect qualified incumbent positions.
For Market Incumbents: Consolidate backward integration into seed genetics and elevator origination networks to neutralize Argentine price volatility exposure. Expand solvent-free oxidation capacity at Belgian and French facilities ahead of EU F-Gas phase-down deadlines. Defend against tapioca substitution threats by locking multi-year contracts with Midwest paper mills through volume commitment pricing. For New Entrants and Emerging Players: Anchor in India's Maharashtra and Gujarat processing corridors where PLI scheme alignment creates localized demand for biodegradable packaging feedstocks. Target pharmaceutical-grade excipient qualification for contract manufacturing organizations in Bavaria and New Jersey seeking dual-sourced amylose supply. Pursue direct-to-bakery e-procurement channels in France and Italy to bypass established distributor markups. For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates divesting non-core wet milling assets amid portfolio rationalization pressures. Five-to-ten-year viability centers on bioplastics feedstock pivot capacity and pharmaceutical certification depth. Monitor Shandong and Jilin provincial bioplastics quota enforcement as inflection signal for industrial starch demand redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Genetics | Cargill and ADM control proprietary high-amylose hybrids that lock processor margins against commodity volatility. |
| Solvent-Free Oxidation Capacity Expansion | Roquette's Belgian facilities gain REACH-compliant positioning for clean-label ready-meal manufacturer contracts. |
| Pharmaceutical USP Certification Investment | Grain Processing Corporation secures generic drug manufacturer audit consolidation in New Jersey corridors. |
| Bioplastics Feedstock Line Dedication | Shandong wet millers capture MEE dual carbon quota allocation for polylactic acid precursor supply. |
| Direct-to-Bakery E-Procurement Platform Launch | Specialty starch distributors bypass traditional channel markups for artisanal bread manufacturers in Spain. |
Research Approach
The analysis maps native starch, modified starch, pregelatinized variants, and pharmaceutical-grade excipients, each validated through wet mill operations directors, food manufacturer procurement leads, pharmaceutical contract manufacturing quality officers, and paper mill technical buyers. Primary fieldwork combined structured interviews across Iowa, Shandong, and Antwerp processing clusters with secondary validation from FDA GRAS notifications, EFSA additive registers, EU F-Gas implementation schedules, and customs trade flow databases. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates across the projection horizon.
Consistency checks against external benchmarks validated output integrity, with segmentation dimensions spanning product type, application sensitivity, end-user industry scale, and packaging format requirements. CAGRs derived from elasticity-adjusted demand curves incorporate maize price volatility bands, bioplastics policy quota trajectories, and pharmaceutical dissolution standard adoption curves across the modeling period.
Underlying assumptions cover sustained EU Green Deal bioeconomy investment levels and China's MEE dual carbon enforcement intensity, with deviation risk concentrated in El Niño-induced yield compression and GRAS affirmation timeline delays. Revision becomes warranted when tapioca substitution elasticity exceeds historical bounds or pharmaceutical excipient qualification backlogs extend beyond standard documentation cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Coconut Flour Market
Ingredients
Terminalia Extract Market
Ingredients
Collagen Casings Market
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
China Gelatin Market
Ingredients
North America Malt Ingredients Market
Ingredients
Alkalized Cocoa Powder Market
Ingredients
EPA and DHA Omega-3 Ingredient Market
Ingredients
Biotech Ingredients Market
Ingredients
Protein Ingredients Market
Ingredients
Coconut Oil Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
White Wheat Malt Market
Ingredients
Bertholletia Excelsa Seed Oil Market
Ingredients
Vegetable Extract Market