
 Protein Ingredients Market | 2026-2036
Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Ingredients Market Analysis
Specialty ingredient distribution is fragmenting as direct-to-manufacturer platforms erode traditional broker networks in the protein sector. ADM leverages its crushing and refining infrastructure to control supply from oilseed through isolate. Cargill sustains geographic dominance through soybean processing clusters across the American Midwest. Nestlé differentiates via proprietary extraction methods that preserve functional properties in plant-derived concentrates.
Protein ingredients comprise concentrated or isolated amino acid chains derived from animal, dairy, or plant biomass, typically standardized to protein content levels between 80% and 95% by weight through mechanical separation, enzymatic hydrolysis, or isoelectric precipitation. These inputs serve primarily as functional texturizers, emulsifiers, and nutritional fortifiers across formulated foods, clinical nutrition, and feed compounding. Whey protein occupies the premium tier in sports nutrition applications where rapid amino acid absorption commands price premiums over casein. Pea protein represents the fastest-expanding source category as beverage brands reformulate away from soy allergens and dairy derivatives. Soy protein maintains volume leadership in animal feed compounding where cost-per-unit-protein drives procurement decisions.
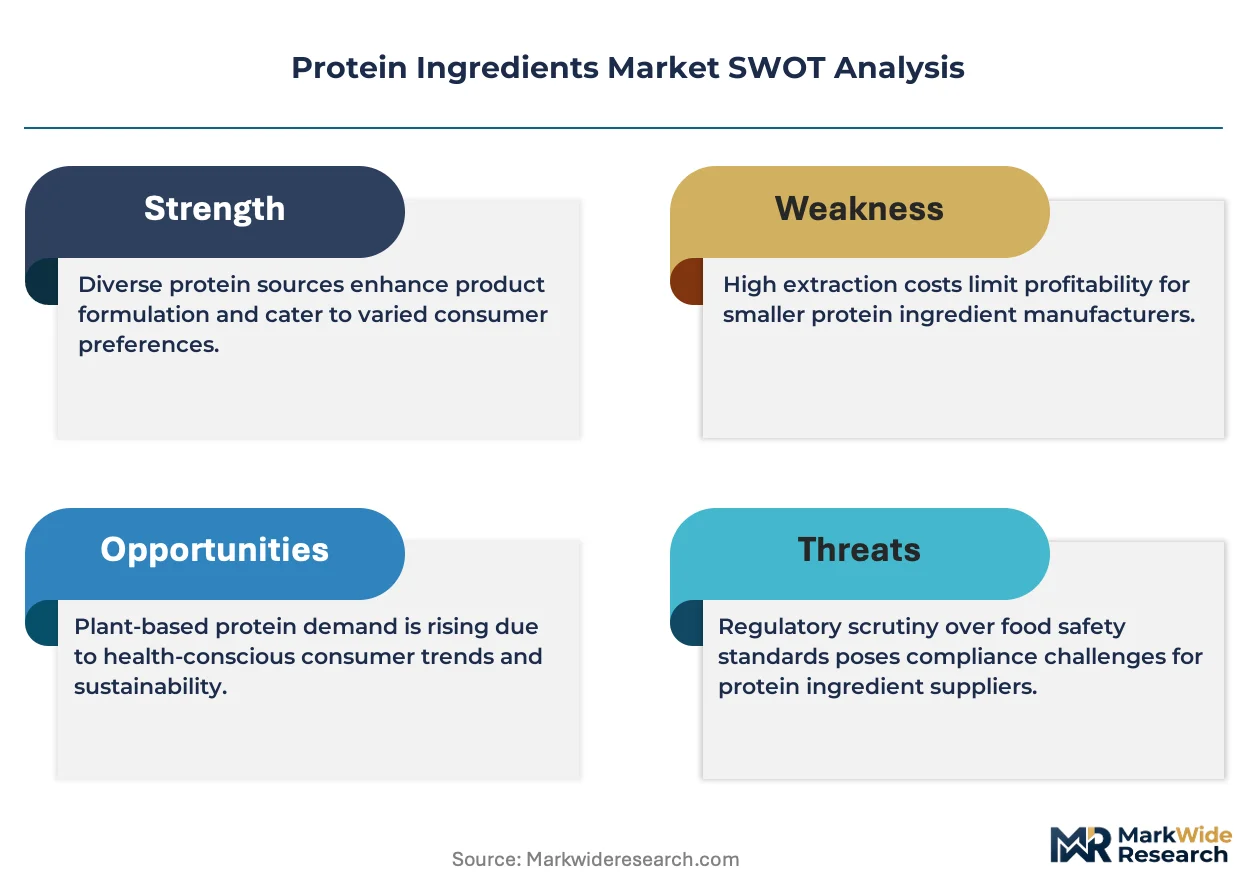
FDA protein labeling standards, EFSA novel food authorizations, and China's SAMR food fortification regulations collectively tighten purity thresholds and substantiation requirements for health claims. These frameworks elevate compliance costs for smaller isolate suppliers while advantaging integrated processors with in-house analytical laboratories. Stakeholders must monitor evolving thresholds for contaminant limits and label claim substantiation as regulatory divergence between jurisdictions complicates cross-border formulation strategies.
Market Dynamics
Direct-to-manufacturer procurement platforms are fragmenting specialty ingredient distribution networks, compressing traditional broker margins while accelerating isolate sourcing velocity for sports nutrition and clinical nutrition formulators.
Growth Catalysts
- FDA Protein Labeling Rules:Tightened purity verification requirements in the United States are elevating demand for certified analytical testing services and driving procurement toward integrated processors with in-house laboratory capabilities.
- Pea Protein Isolates:Beverage brands are accelerating reformulation away from soy allergens and dairy derivatives, with pea protein capturing the fastest-expanding source category position in functional beverage applications.
- China SAMR Fortification Mandates:Domestic food brands are expanding fortified product lines under stricter food fortification regulations, concentrating demand growth in protein concentrates for packaged goods and infant nutrition.
Market Restraints
- Input Cost Volatility:Yellow pea and fava bean prices fluctuate with Canadian and Australian harvest cycles, squeezing margin predictability for isolate suppliers dependent on pulse crop feedstocks.
- Supply Concentration Risk:Whey protein isolate production clusters in Wisconsin and Idaho create geographic vulnerability to dairy herd health disruptions and processing capacity constraints.
- Regulatory Friction:EFSA novel food authorization timelines for emerging protein sources extend 18-24 months, delaying European market entry for fermented and precision-fermentation derived ingredients.
Strategic Opportunities
- Precision Fermentation:Microbial protein production is converging with enzymatic hydrolysis capabilities, enabling animal-free whey and casein analogs for vegan-positioned sports nutrition brands.
- India FSSAI Expansion:Underpenetrated clinical nutrition and senior care segments present white space as India's food safety regulator streamlines protein fortification approvals for medical foods.
- Direct Platform Distribution:B2B ingredient marketplaces are displacing traditional broker networks, offering price transparency and sample fulfillment that accelerates formulation cycles for mid-sized manufacturers.
Industry Challenges
- Analytical Talent Scarcity:Protein characterization specialists with mass spectrometry and amino acid profiling expertise command premium compensation, constraining smaller isolate suppliers' quality assurance scaling.
- Certification Timeline Compression:Non-GMO Project and organic certifications require 12-18 month validation periods that misalign with beverage brand launch schedules, forcing expedited third-party auditing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Ingredients Market |
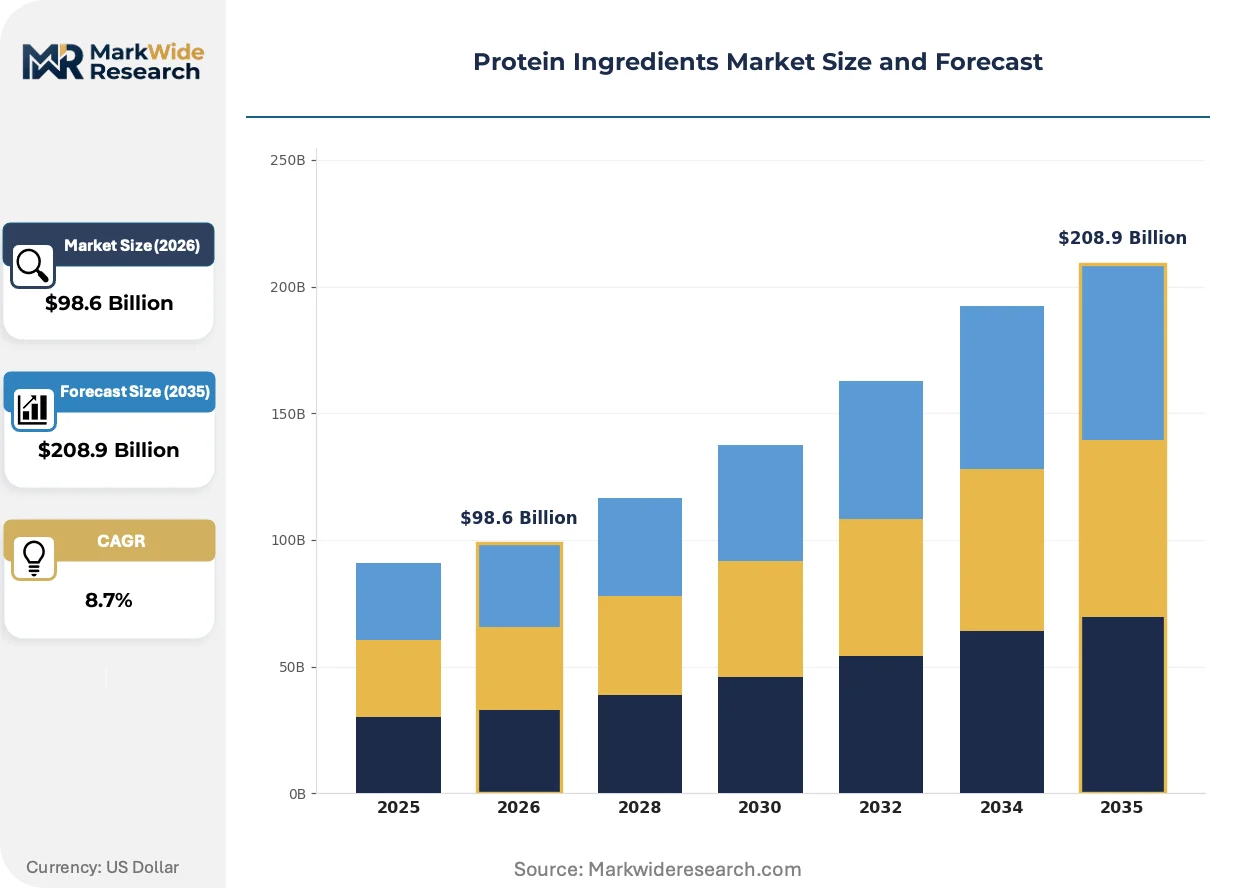
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein Application: Food & Beverages, Nutritional Supplements, Animal Feed, Pharmaceuticals Source: Dairy, Plant-Based, Egg, Animal End User: Athletes, Health-Conscious Consumers, Bodybuilders, Medical Patients |
| Companies Covered | Monde Nissin Corporation, The Hain Celestial Group, ADM (Archer Daniels Midland Company), Nestlé, Conagra Brands, Kellogg Company (Kellanova), Kraft Heinz, Cargill, Maple Leaf Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Ingredients Market Emerging Trajectories
Enzymatic processing advances and fermentation-derived alternatives are compressing traditional extraction economics while regulatory divergence between jurisdictions forces multi-standard compliance architectures.
Precision fermentation technology is hybridizing with conventional dairy processing infrastructure. Alternative protein startups are licensing this capability to retrofit idled whey processing facilities in the Netherlands and Denmark. This convergence is enabling functional whey protein analogs at price parity with commodity isolates within five years.
EFSA novel food authorization pathways are tightening substantiation requirements for bioactive peptide claims. Clinical trial data demands now exceed prior guidance thresholds, advantaging established players with dedicated regulatory affairs functions. Sports nutrition brands targeting European distribution are reformulating away from positionings that require health claim substantiation.
Formulation service unbundling is compressing traditional full-service distributor value propositions. Mid-sized food manufacturers in Germany and the United Kingdom are sourcing isolates directly while purchasing application technical support à la carte from independent food science consultancies. This bifurcation is visible most acutely in plant-based meat analog development programs.
Protein Ingredients Market Segmentation
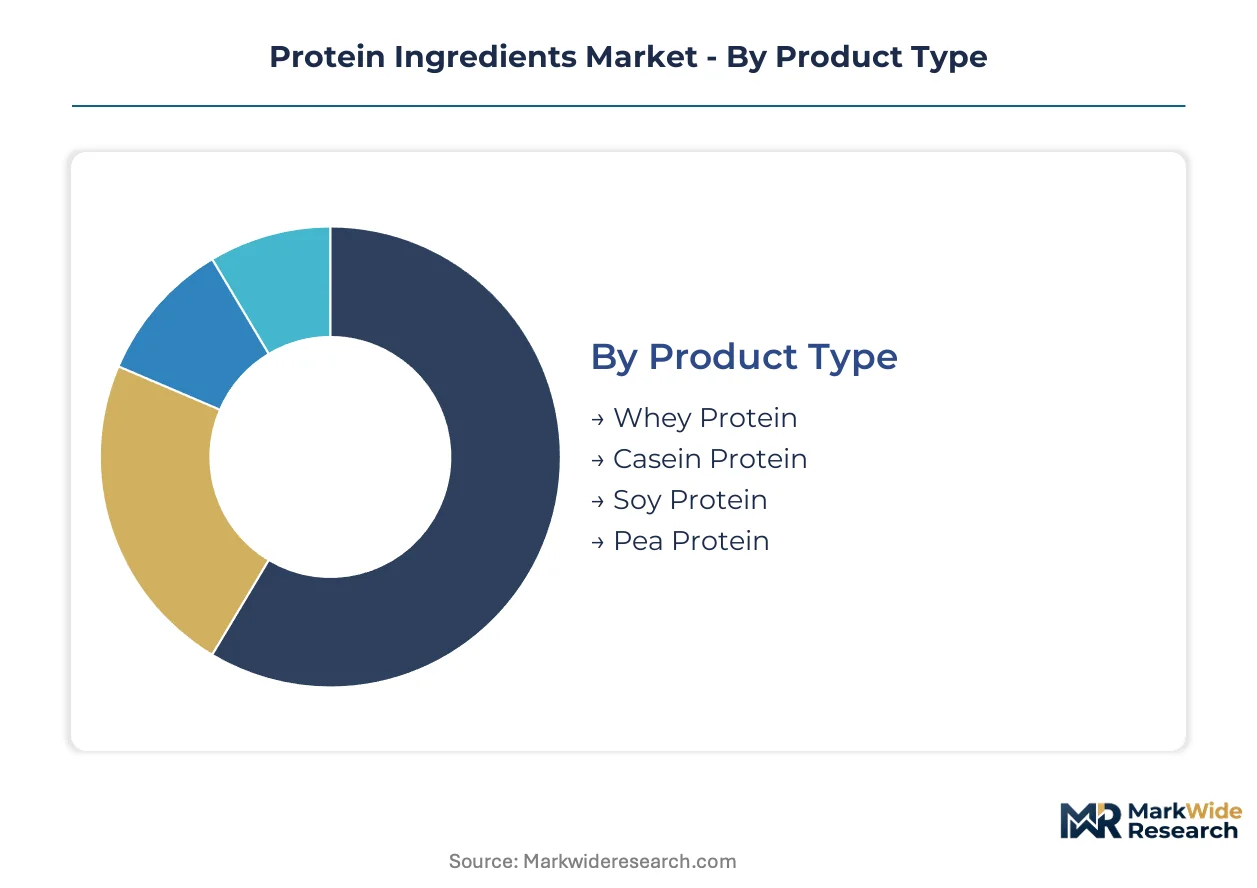
Protein ingredient procurement cycles vary dramatically by segment, with sports nutrition formulations turning over quarterly while pharmaceutical protein contracts lock in for multi-year supply agreements. Understanding these velocity differentials enables suppliers to align inventory positioning with demand predictability.
Product Type:
Whey protein isolate commands the shortest procurement cycles in sports nutrition, while casein contracts extend across annual planning horizons due to slower-moving clinical nutrition applications.
- Whey Protein:Rapid-digesting amino acid profiles with 90%+ protein concentration by weight dominate post-workout formulations. Demand concentrates in United States sports nutrition brands reformulating around FDA purity verification requirements. Procurement velocity accelerates as direct-to-manufacturer platforms compress traditional broker lead times.
- Pea Protein:Hypoallergenic isolates with 80-85% protein content serve beverage brands exiting soy and dairy derivatives. European formulators drive fastest category expansion as EFSA novel food pathways gradually clarify for emerging plant sources. Supply security hinges on Canadian yellow pea harvest reliability.
- Casein Protein:Slow-release micellar structures sustain overnight amino acid delivery for clinical nutrition and senior care segments.
- Soy Protein:Cost-optimized concentrates maintain feed compounding dominance where protein-per-dollar drives procurement decisions.
Soy protein anchors the volume base while pea protein gains share at the steepest rate.
Application:
Margin structures diverge sharply across applications, with pharmaceutical-grade isolates commanding five-fold premiums over feed-grade concentrates despite comparable input costs.
- Nutritional Supplements:Powder and ready-to-drink formats require instantized isolates with optimized dispersibility and minimal off-flavor carryover. United States sports nutrition manufacturers accelerate procurement through direct platforms, bypassing traditional distribution layers. China SAMR fortification mandates concentrate demand growth for packaged protein supplements.
- Food & Beverages:Functional texturization and emulsification properties drive specification requirements in plant-based meat analogs and dairy alternatives. German and United Kingdom mid-sized manufacturers unbundle formulation services, sourcing isolates directly while purchasing technical support independently.
- Pharmaceuticals:USP-grade purity with documented bioactivity substantiation serves enteral and parenteral nutrition applications.
- Animal Feed:Standardized protein content specifications prioritize cost efficiency over functional performance in livestock and aquaculture compounding.
Animal feed anchors the volume base while nutritional supplements expand most quickly.
Source:
Supply security timelines stretch longest for animal-derived proteins, where herd health and processing capacity constraints create eighteen-month visibility horizons versus six-month plant protein planning cycles.
- Dairy:Whey and casein fractions from cheese manufacturing co-products sustain established supply chains with proven analytical characterization. Wisconsin and Idaho processing clusters create geographic concentration risk for isolate availability. Precision fermentation startups are retrofitting idled European facilities to replicate dairy protein functionality without herd dependency.
- Plant-Based:Pea, fava, and rice protein concentrates serve allergen-free formulation requirements across beverage and bakery applications. Input cost volatility from Canadian and Australian pulse harvests squeezes margin predictability for dedicated isolate suppliers.
- Egg:Ovalbumin and lysozyme fractions retain niche positions in specialized nutritional and pharmaceutical applications.
- Animal:Collagen and gelatin derivatives from bovine and porcine sources serve connective tissue and encapsulation functions.
Dairy anchors the volume base while plant-based sources climb the fastest.
End User:
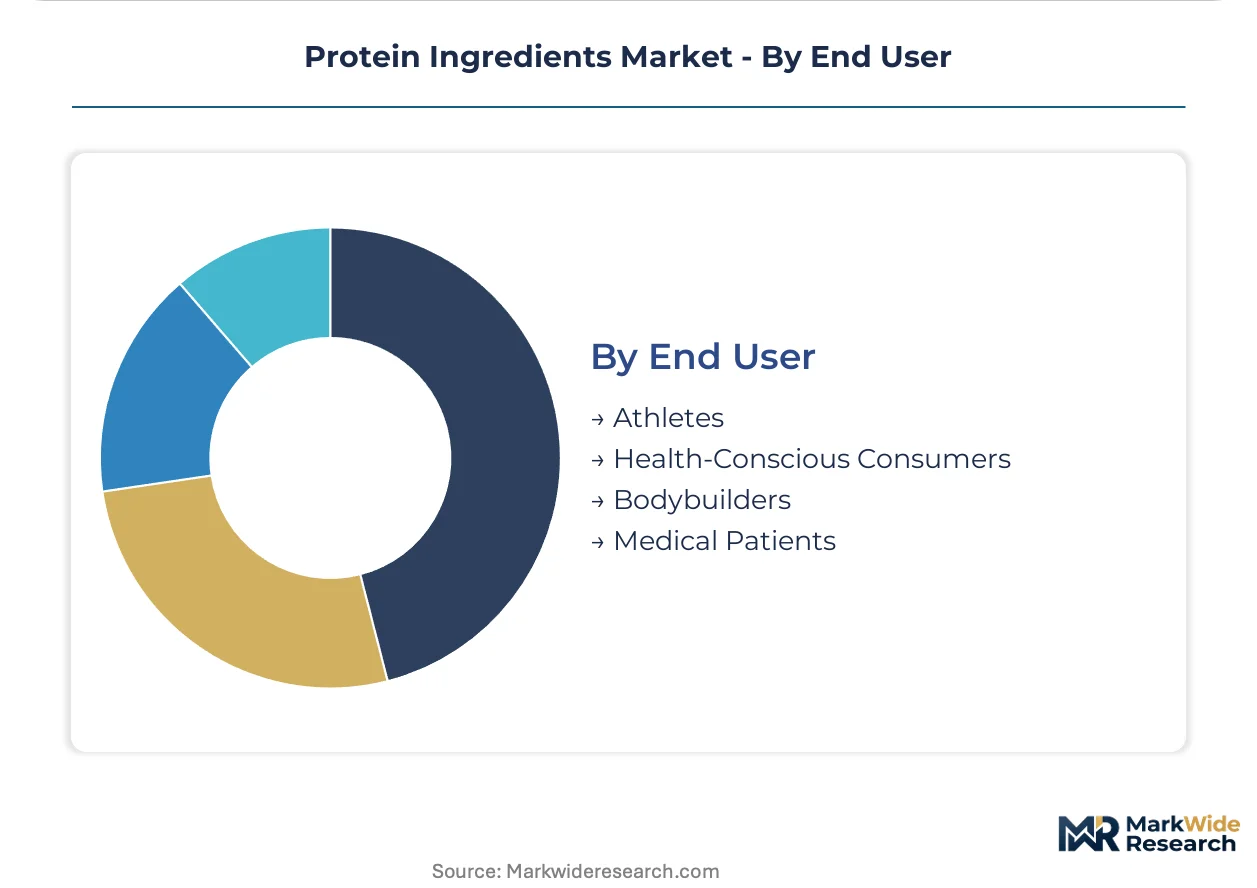
Specification complexity escalates from health-conscious consumers seeking basic fortification through medical patients requiring documented bioavailability data.
- Medical Patients:Clinical nutrition formulations demand batch-level amino acid profiling and contaminant documentation exceeding standard food-grade requirements. India FSSAI streamlining of medical food approvals creates white space expansion opportunity as underpenetrated senior care segments develop. Analytical talent scarcity constrains smaller suppliers' quality assurance scaling for this segment.
- Athletes:Rapid absorption kinetics and leucine content optimization drive premium positioning in pre- and post-workout applications. European brands reformulate away from health claim-dependent positionings as EFSA substantiation requirements tighten.
- Bodybuilders:High-dose protein delivery with minimal carbohydrate and fat content drives isolate preference over concentrate formats.
- Health-Conscious Consumers:Mainstream fortification applications accept broader protein source flexibility in exchange for cost accessibility.
Health-conscious consumers anchor the volume base while medical patients represent the fastest-expanding trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR fortification mandates in China are redirecting procurement flows toward certified isolate suppliers with in-house analytical capabilities. FDA labeling rule changes in the United States are elevating purity verification costs for cross-border exporters. EFSA novel food pathways in Europe are extending authorization timelines for emerging protein sources.
United States
Sports nutrition brands accelerate whey isolate procurement through direct-to-manufacturer platforms, bypassing traditional broker networks. FDA protein labeling rules tighten purity verification requirements, elevating demand for certified analytical testing services. Wisconsin and Idaho processing clusters concentrate whey protein isolate production, creating geographic vulnerability to dairy herd health disruptions.
China
Domestic food brands expand fortified product lines under stricter SAMR food fortification regulations, concentrating demand growth in protein concentrates. Beverage manufacturers reformulate away from soy allergens toward pea-derived alternatives. Yangtze River Delta processing hubs scale isolate production capacity to serve packaged goods and infant nutrition segments.
Germany
Mid-sized food manufacturers unbundle formulation services, sourcing isolates directly while purchasing technical support from independent consultancies. EFSA novel food authorization timelines extend 18-24 months for emerging protein sources, delaying market entry for fermented ingredients. Cologne-Düsseldorf industrial corridor anchors plant-based meat analog development programs.
India
Underpenetrated clinical nutrition and senior care segments present expansion opportunity as FSSAI streamlines protein fortification approvals for medical foods. Analytical talent scarcity constrains smaller suppliers' quality assurance scaling. Maharashtra and Gujarat processing clusters develop isolate capacity to serve domestic pharmaceutical-grade demand.
Netherlands
Precision fermentation startups license technology to retrofit idled whey processing facilities, enabling animal-free protein analogs. EFSA bioactive peptide claim substantiation requirements tighten, advantaging established players with dedicated regulatory affairs functions. Rotterdam-Antwerp port complex facilitates pulse crop import flows for isolate production.
Protein Ingredients Market Vendor Landscape
On the supply side, the industry is consolidating around integrated processors with captive crushing, refining, and analytical capabilities. Three strategic archetypes dominate: agribusiness conglomerates controlling oilseed-to-isolate supply chains, dairy cooperatives leveraging whey fractionation infrastructure, and alternative protein specialists deploying precision fermentation platforms. Competitive moves concentrate on backward integration into pulse crop origination and technology licensing partnerships for retrofitting idled dairy facilities.
Within the integrated processor tier, ADM and Cargill exemplify supply chain control through oilseed crushing and refining infrastructure. Nestlé occupies a position emphasizing proprietary extraction methods that preserve functional properties in plant-derived concentrates. These three anchors represent divergent competitive vectors: ADM and Cargill compete on feedstock security and geographic processing density, while Nestlé differentiates through formulation science and branded ingredient positioning.
| Leading Market Players |
|---|
| Monde Nissin Corporation |
| The Hain Celestial Group |
| ADM (Archer Daniels Midland Company) |
| Nestlé |
| Conagra Brands |
| Kellogg Company (Kellanova) |
| Kraft Heinz |
| Cargill |
| Maple Leaf Foods |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European precision fermentation facilities is driving contract manufacturers toward premium pricing postures while forcing sports nutrition brands to extend offtake commitments. This utilization squeeze rewards integrated processors with captive capacity and squeezes margin predictability for brands dependent on toll manufacturing arrangements.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade isolates from feed-grade concentrates and beverage-grade intermediates. Three-tier pricing stratification across premium, standard, and economy levels reflects certification grade and amino acid profiling depth. Cost compression in standard-tier plant proteins is intensifying as Canadian pulse crop volatility feeds into margin pressure. Animal feed compounders exhibit highest price sensitivity while clinical nutrition formulators absorb premiums for batch-level documentation.
Supply Chain Analysis
Extended payment terms from sports nutrition brands are forcing isolate suppliers to access supply-chain finance facilities, elevating working capital costs. Production gravity centers on the United States for whey isolates, China for soy concentrates, and Canada for pea protein extraction. Supply security draws from yellow pea harvests, dairy herd outputs, and oilseed crushing volumes. Single-source vulnerability concentrates in Wisconsin-Idaho dairy processing clusters. Distribution runs through direct-to-manufacturer platforms displacing traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized protein characterization capabilities are scarce assets that constrain quality assurance scaling and create acquisition premiums for laboratories with mass spectrometry proficiency.
For Market Incumbents: Entrench analytical capabilities through backward integration into certified testing laboratories or exclusive partnerships with academic research facilities. Defend against precision fermentation entrants by locking multi-year offtake agreements with beverage brands reformulating around FDA purity requirements. Prioritize capacity addition in Yangtze River Delta processing hubs to capture China SAMR fortification mandate demand. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated clinical nutrition segment where FSSAI streamlining creates regulatory clarity gaps that agile suppliers can exploit. Target medical-grade isolate contracts requiring amino acid profiling documentation that incumbent dairy cooperatives underserve. Deploy direct-platform distribution to bypass entrenched broker relationships and accelerate sample-to-contract velocity for mid-sized manufacturers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated processors with captive crushing, refining, and analytical capabilities that lock in multi-year pharmaceutical contracts. Long-term viability favors asset-light precision fermentation platforms licensing technology to retrofit idled European dairy facilities. Watch EFSA novel food authorization timeline compression as an inflection signal for European market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulse Crop Origination | ADM and Cargill secure Canadian yellow pea supply chains against harvest volatility. |
| Precision Fermentation Technology Licensing | Alternative protein startups retrofit idled whey facilities in the Netherlands and Denmark. |
| In-House Analytical Laboratory Investment | Integrated processors meet FDA protein labeling purity verification requirements. |
| Direct-to-Manufacturer Platform Launch | B2B marketplaces displace traditional broker networks with price transparency. |
| India FSSAI Medical Food Approval Pursuit | Suppliers capture white space in underpenetrated clinical nutrition segments. |
Methodological Framework
Desk research of FDA labeling guidance documents, EFSA novel food authorization databases, and SAMR fortification regulations preceded structured interviews with protein procurement managers at sports nutrition brands, quality assurance directors at isolate suppliers, regulatory affairs leads at precision fermentation startups, and commodity traders at agricultural processing conglomerates. Secondary validation drew from customs trade data, SEC filings of publicly traded ingredient processors, and industry association production statistics. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Assumptions held fixed include regulatory authorization timelines, pulse crop yield coefficients, and dairy herd productivity metrics; variables stress-tested included input cost volatility, certification adoption rates, and direct-platform penetration velocity. The analytical framework modeled protein ingredient demand across product type, application, source, and end user dimensions over the projection horizon. CAGRs were derived from segment-level demand elasticity coefficients and substitution rate assumptions for emerging protein sources.
Stress conditions across Canadian harvest variability, EFSA authorization delays, and precision fermentation scale-up timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Asia-Pacific Brewing Enzymes Market
Ingredients
Vitamin and Mineral Premixes Market
Ingredients
Africa Fats and Oil Market
Ingredients
Dill Seed Oil Market
Ingredients
Rose Extract Market
Ingredients
Australia Sodium Reduction Ingredients Market
Ingredients
Marine Hyaluronic Ingredients Market
Ingredients
Algae-Based Ingredients Market
Ingredients
Sunflower Lecithin Market
Ingredients
Africa Plant Protein Ingredients Market
Ingredients
Fluid Lecithin Market
Ingredients
Food Grade Hydrolyzed Casein Market
Ingredients
Bovine Gelatin Market
Ingredients
Citrus Fiber Market
Ingredients
Europe Gelatin Market