
 Europe Industrial Food and Beverages Filtration System Market | 2026-2036
Europe Industrial Food and Beverages Filtration System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Industrial Food and Beverages Filtration System Market Analytics
Small-batch beverage producers is collapsing the historical dominance of mass-market dairies in filtration procurement across Western Europe. Alfa Laval AB anchors its position through upstream control over membrane manufacturing in Sweden. GEA Group AG competes with integrated process engineering bundles that span filtration through packaging. Donaldson Company specializes in cartridge architectures optimized for high-viscosity juice applications in Southern Europe.
Europe industrial food and beverages filtration systems comprise pressure-driven separation equipment engineered to remove particulates, microorganisms, and dissolved solids from liquid food streams, with pore ratings spanning 0.1 micron for microfiltration to sub-nanometer precision for reverse osmosis. These systems serve primarily to extend shelf stability, recover valuable solids, and reduce thermal processing loads in commercial-scale production. Membrane filters and ultrafiltration technology lead installed capacity across the region, while reverse osmosis posts the fastest expansion in whey protein concentration and dealcoholization segments. Bag filters retain relevance in coarse pre-filtration stages where margin pools remain thin and replacement cycles drive recurring revenue.
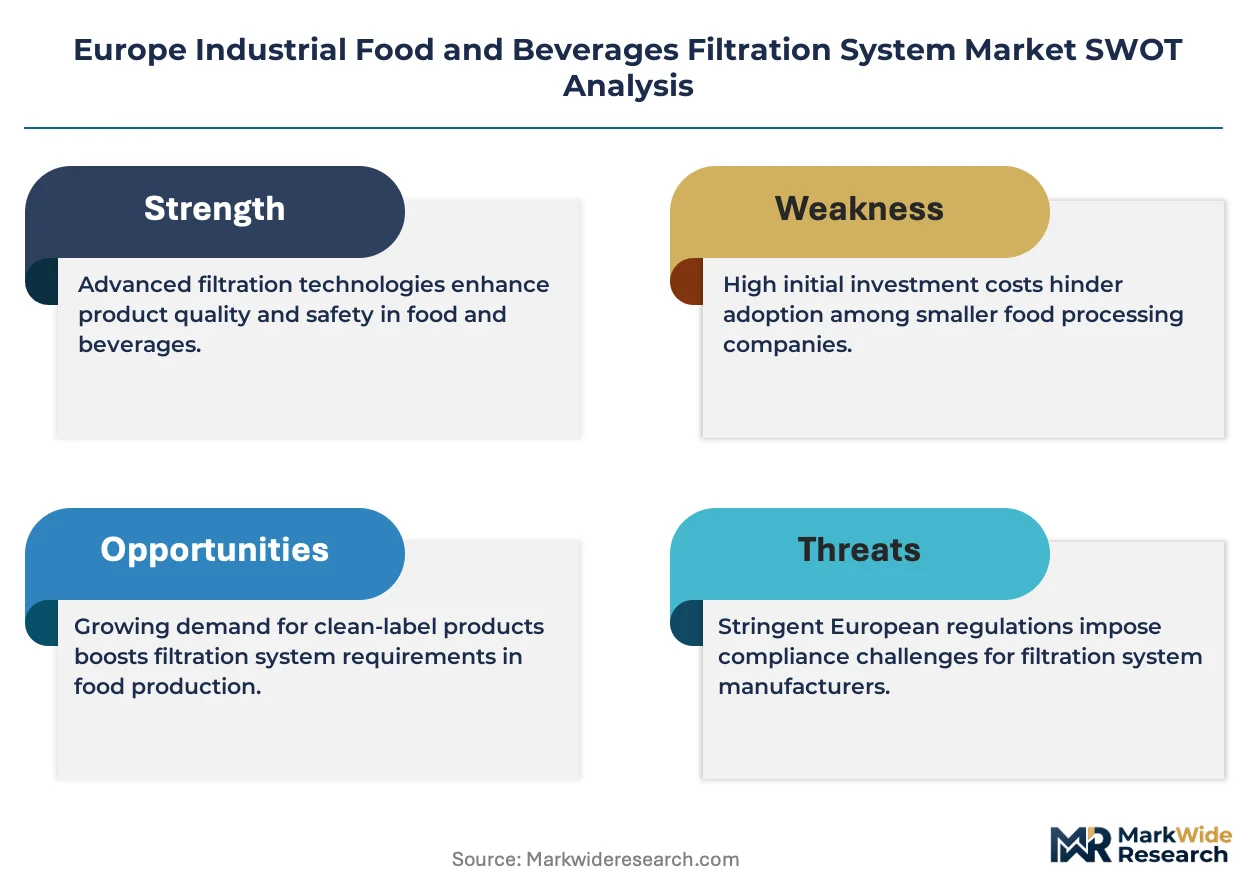
EMA food-contact material guidelines, REACH chemical safety thresholds, and EU Green Deal sustainability benchmarks collectively tighten compliance burdens for filtration media suppliers operating across the continent. EFSA migration limits on polymeric membranes directly shape product development timelines and raw material selection for equipment manufacturers. Stakeholders must monitor evolving F-Gas Regulation impacts on refrigeration-integrated filtration trains and assess whether CSRD disclosure requirements will redirect capital toward circular membrane regeneration services.
Market Dynamics
REACH chemical safety thresholds and EU Green Deal sustainability mandates are compressing procurement timelines across Europe's dairy and beverage corridors, forcing membrane system upgrades ahead of traditional replacement cycles.
Growth Catalysts
- REACH compliance deadlines:ECHA substance restrictions on legacy polymeric media are accelerating membrane replacement schedules in German and Dutch dairy processing clusters.
- Whey protein concentration:Ultrafiltration and reverse osmosis systems are capturing new installed base as protein recovery economics improve across Danish and Bavarian facilities.
- Dealcoholization segment:Low-alcohol beverage production lines in France and Spain are deploying nanofiltration trains to preserve flavor compounds while removing ethanol.
Market Restraints
- Specialized polymer supply:Food-grade polysulfone and polyethersulfone resin availability concentrates among a narrow supplier base in Germany and Belgium.
- Skilled technician scarcity:Membrane system commissioning and regeneration expertise pools thinly across Eastern European maintenance networks.
- Legacy thermal process substitution limits:High-temperature short-time pasteurization retains cost advantages in low-margin juice categories where membrane capex cannot amortize.
Strategic Opportunities
- Polish and Romanian dairy expansion:Greenfield processing facilities in these markets lack entrenched equipment relationships, opening membrane system specification battles.
- CSRD disclosure requirements:Corporate sustainability reporting mandates are elevating water recovery and chemical reduction metrics in equipment procurement scorecards.
- Membrane regeneration services:Circular economy business models are emerging as standalone revenue streams distinct from new system sales.
Industry Challenges
- EFSA migration testing timelines:Novel polymeric membrane materials face extended food-contact approval cycles that delay product launches by 18-24 months.
- Refrigeration-integrated filtration reconfiguration:F-Gas Regulation phase-downs are forcing simultaneous upgrades of cooling and filtration trains, compressing capex planning windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Industrial Food and Beverages Filtration System Market |
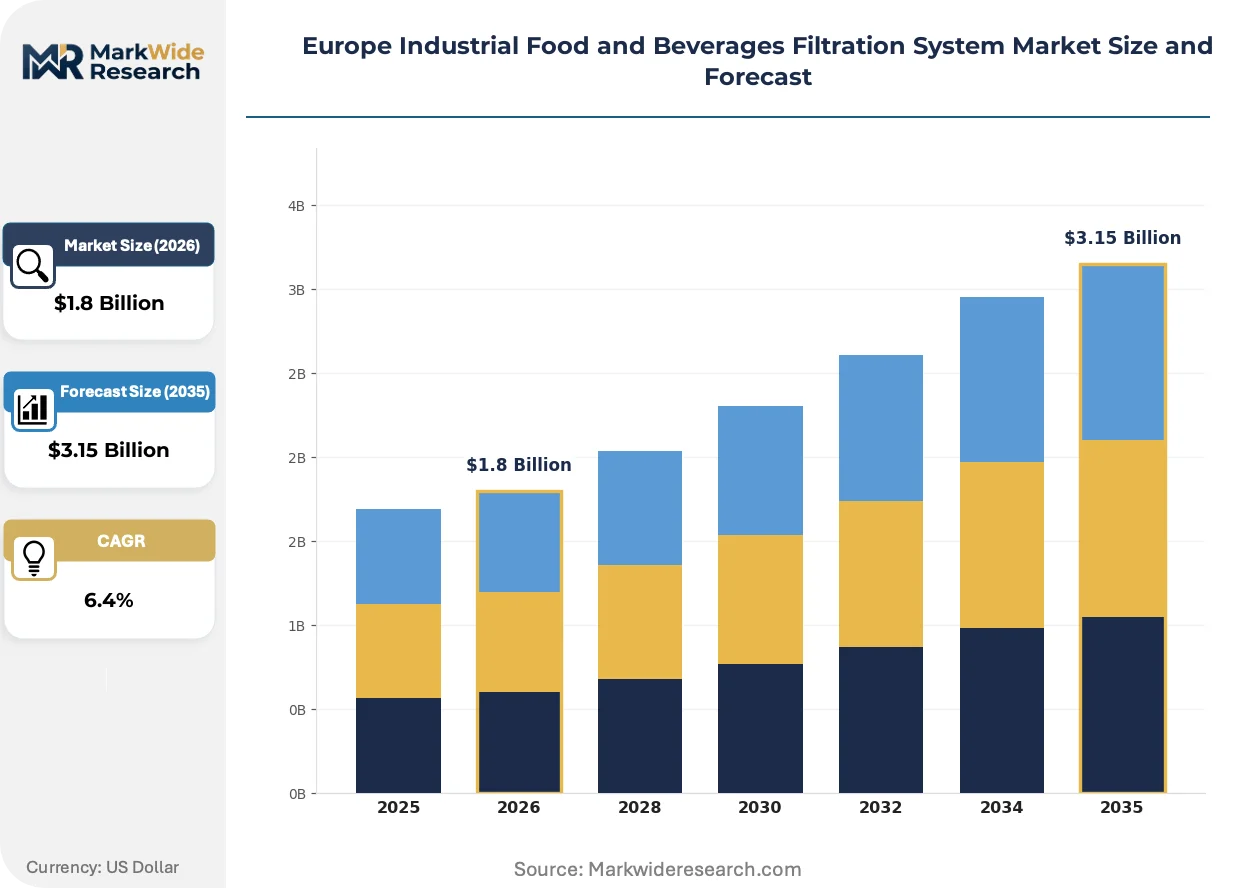
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filters, Cartridge Filters, Bag Filters, Plate Filters Application: Beverage Production, Dairy Processing, Oil Refining, Juice Processing Technology: Microfiltration, Ultrafiltration, Reverse Osmosis, Nanofiltration End User: Food Manufacturers, Beverage Companies, Chemical Processors, Pharmaceutical Firms |
| Companies Covered | Alfa Laval AB, GEA Group AG, Camfil AB, Krones AG, Donaldson Company, Parker Hannifin Corp., Eaton Corporation plc, 3M Co., Freudenberg and Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Industrial Food and Beverages Filtration System Market Evolving Landscape
Ceramic membrane architectures and intelligent process control systems are redrawing competitive boundaries between European equipment suppliers, while regulatory pressure on chemical intensity accelerates material substitution timelines.
Ceramic membranes constructed from aluminum oxide and titanium dioxide are penetrating high-temperature dairy applications previously reserved for polymeric systems. French and Italian cheese processors are retrofitting microfiltration lines with these inorganic media to eliminate chemical sanitization cycles. This substitution is decomposing the historical cost advantage of polyethersulfone membranes in thermally aggressive process streams.
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants are cascading into filtration system design requirements. Equipment manufacturers must now engineer membrane trains compatible with alternative cooling chemistries and lower operating temperatures. Southern European juice concentrate facilities face the steepest retrofit obligations as they simultaneously address energy efficiency and chemical migration compliance.
Beverage producers are unbundling aftermarket service contracts from initial equipment purchases, treating membrane replacement and regeneration as competitively tendered commodities. This disaggregation is compressing margin pools for integrated suppliers while creating entry points for specialized service providers. German craft breweries and Spanish cider houses are most aggressive in separating capital and operating expenditure decisions.
Europe Industrial Food and Beverages Filtration System Market Segmentation
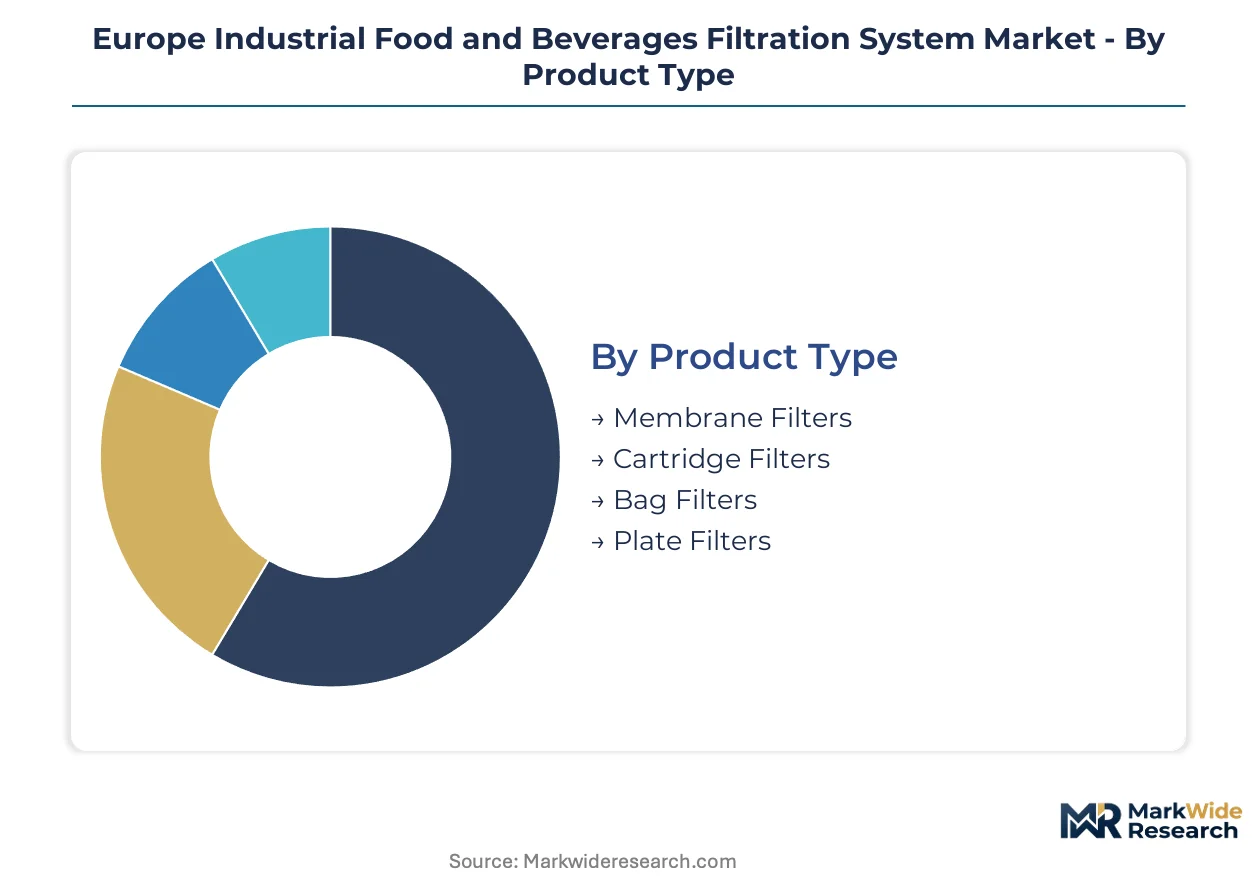
Filtration system procurement across Europe diverges sharply by product architecture and regulatory exposure. EFSA migration limits and REACH substance restrictions create tiered compliance burdens that reshape segment economics differently across dairy, beverage, and pharmaceutical end-uses.
Product Type:
REACH substance restrictions on polymeric media differentiate equipment categories by chemical intensity and replacement cycle economics.
- Membrane Filters:Polymeric and ceramic membranes engineered with pore ratings from 0.1 micron to sub-nanometer precision dominate whey protein concentration and dealcoholization lines. Bavarian and Danish dairy clusters drive specification upgrades as EFSA tightens food-contact migration thresholds for legacy polysulfone formulations.
- Cartridge Filters:Pleated polypropylene and cellulose architectures serve as final polishing stages in bottled water and premium juice applications. Southern European concentrate facilities prioritize cartridge systems with validated low-extractable profiles to satisfy EMA pharmaceutical-grade water standards.
- Bag Filters:Coarse particulate removal in pre-filtration trains where margin pools remain thin and replacement cycles drive recurring revenue.
- Plate Filters:Conventional stacked-sheet designs retain relevance in traditional cheese whey clarification and small-scale brewery operations across Belgium and the Netherlands.
Membrane filters handle the majority of throughput; cartridge filters are gaining share fastest on pharmaceutical and premium beverage co-specification.
Application:
Cost tier stratification separates capital-intensive membrane installations from lower-capex thermal process alternatives.
- Beverage Production:Craft breweries and low-alcohol lines in France and Spain deploy nanofiltration trains to preserve volatile flavor compounds while stripping ethanol. CSRD disclosure requirements elevate water recovery metrics in procurement scorecards for mid-size producers.
- Dairy Processing:Ultrafiltration and reverse osmosis systems capture new installed base as protein recovery economics improve across Danish and Bavarian facilities. ECHA substance restrictions accelerate membrane replacement schedules ahead of traditional cycles.
- Oil Refining:Edible oil degumming and dewaxing applications in the Netherlands and Germany utilize membrane clarification to reduce bleaching earth consumption.
- Juice Processing:High-viscosity concentrate facilities face steep retrofit obligations under F-Gas Regulation phase-downs, compressing capex planning windows for integrated cooling and filtration upgrades.
Dairy processing commands the largest equipment footprint; beverage production shows the steepest expansion trajectory on dealcoholization and craft segment growth.
Technology:
Volume concentration across installed base favors mature microfiltration while emerging applications pull toward higher-rejection membrane classes.
- Microfiltration:Ceramic aluminum oxide and titanium dioxide architectures penetrate high-temperature dairy applications previously reserved for polymeric systems. French and Italian cheese processors retrofit lines to eliminate chemical sanitization cycles.
- Ultrafiltration:Protein fractionation and enzyme recovery in whey processing across Denmark and the Netherlands. EFSA migration testing timelines for novel polymeric materials delay product launches.
- Reverse Osmosis:Whey protein concentration and dealcoholization segments in German and Spanish facilities. F-Gas Regulation restrictions cascade into system design requirements for alternative cooling chemistries.
- Nanofiltration:Selective ion removal and partial demineralization in specialized dairy ingredient production.
Microfiltration retains the deepest installed base; reverse osmosis climbs fastest on protein recovery and alcohol reduction applications.
End User:
Customer type determines service bundling preferences and aftermarket contract structures across the region.
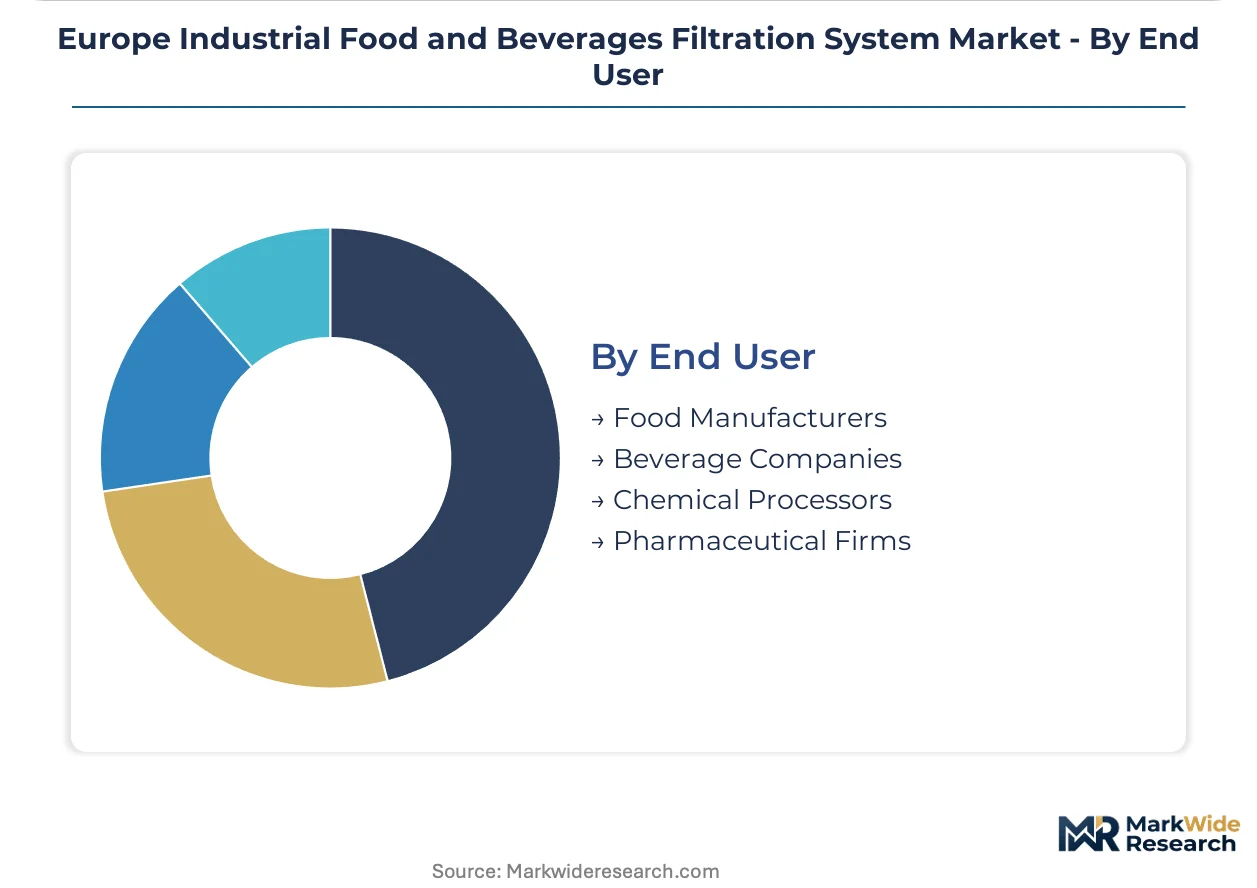
- Food Manufacturers:Dairy and ingredient processors across Bavaria, the Netherlands, and Denmark prioritize membrane regeneration services as standalone procurement categories separate from initial equipment purchases.
- Beverage Companies:German craft breweries and Spanish cider houses aggressively unbundle capital and operating expenditure decisions, treating membrane replacement as competitively tendered commodities.
- Chemical Processors:Food-grade chemical intermediates production with specialized polymer supply constraints concentrating among German and Belgian resin suppliers.
- Pharmaceutical Firms:EMA water-for-injection standards drive cartridge filter validation requirements in Irish and Swiss manufacturing clusters.
Food manufacturers represent the largest procurement volume; beverage companies are restructuring purchasing fastest toward disaggregated service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports membrane filtration systems to dairy processors across Denmark and the Netherlands, establishing the Rhine-Ruhr corridor as Europe's primary equipment manufacturing hub. This trade pattern concentrates technical expertise and polymer supply chains in Central Europe while driving specification standards for the broader regional market.
Germany
Bavarian dairy clusters and North Rhine-Westphalia chemical processors drive membrane system procurement for whey protein concentration and edible oil degumming. ECHA substance restrictions under REACH accelerate replacement schedules for legacy polysulfone media. Equipment fabricators in Cologne and Düsseldorf retrofit ceramic architectures into high-temperature cheese processing lines.
France
Dealcoholization demand from low-alcohol beverage producers in Champagne and Burgundy pulls nanofiltration capacity expansion. ANSM food-contact material guidelines tighten validation requirements for membrane migration testing. Lyon-based cheese processors deploy aluminum oxide microfiltration to eliminate chemical sanitization cycles in Comté and Roquefort production.
Netherlands
Whey fractionation facilities across Gelderland and Friesland upgrade ultrafiltration trains for protein recovery economics. EU Green Deal sustainability benchmarks elevate water recovery metrics in procurement scorecards for dairy cooperatives. Edible oil refineries in Rotterdam deploy membrane clarification to reduce bleaching earth consumption.
Denmark
Arla Foods and independent dairy processors concentrate ultrafiltration demand in Jutland for whey protein isolate production. CSRD disclosure requirements redirect capital toward circular membrane regeneration services. Aarhus technical institutes train commissioning specialists to address regional technician scarcity.
Spain
Cider houses in Asturias and low-alcohol wine producers in La Rioja aggressively unbundle capital and operating expenditure decisions for membrane replacement. F-Gas Regulation phase-downs force simultaneous upgrades of cooling and filtration trains in Valencia juice concentrate facilities. Barcelona equipment distributors compete on aftermarket service pricing.
Europe Industrial Food and Beverages Filtration System Market Competitive Landscape
Player mix skews toward integrated process engineering conglomerates with captive membrane manufacturing, creating a tiered structure where upstream material control separates premium-positioned suppliers from assembly-dependent competitors. Swedish and German engineering groups anchor the consolidated upper tier through backward integration into polymer resin supply. Mid-scale specialists compete on geographic proximity to dairy corridors. Dominant competitive moves include membrane regeneration service launches and ceramic architecture retrofits for high-temperature applications.
Among Nordic-based engineering groups, Alfa Laval AB exemplifies the vertically integrated archetype through upstream control over membrane manufacturing in Sweden. GEA Group AG represents the diversified process bundling model with integrated engineering spanning filtration through packaging stages. Donaldson Company occupies a position within cartridge architecture specialization for high-viscosity applications. These three anchors demonstrate how material control, process breadth, and application focus stratify competitive positioning across European procurement channels.
| Leading Market Players |
|---|
| Alfa Laval AB |
| GEA Group AG |
| Camfil AB |
| Krones AG |
| Donaldson Company |
| Parker Hannifin Corp. |
| Eaton Corporation plc |
| 3M Co. |
| Freudenberg and Co. KG |
| Others |
Value Network & Pricing Analysis
Ceramic membrane substitution for polymeric systems in French and Italian cheese processing simultaneously redraws supply geography toward German aluminum oxide feedstock producers and compresses pricing premiums previously commanded by polysulfone membrane manufacturers. This material transition feeds back into procurement patterns as Bavarian dairy clusters negotiate volume contracts that blend ceramic and polymer pricing benchmarks.
Pricing Analysis
Current-generation ceramic membrane systems command substantial premiums over prior-generation polyethersulfone architectures, while next-generation graphene-enhanced membranes remain pre-commercial. Pricing stratifies across premium, standard, and economy tiers based on EFSA migration certification status and REACH compliance verification depth. Cost compression in standard-tier polymeric membranes is intensifying because Chinese resin suppliers are expanding food-grade polysulfone capacity. German craft breweries exhibit highest price sensitivity due to unbundled procurement models, while Danish whey processors show lowest sensitivity given protein recovery economics.
Supply Chain Analysis
Germany and Belgium anchor food-grade polysulfone and polyethersulfone resin production for European membrane manufacturers. Equipment fabricators in Sweden and Germany draw from these polymer supply bases while sourcing ceramic aluminum oxide precursors from Austrian and Slovak specialty chemical producers. Single-source vulnerability concentrates in German resin suppliers serving REACH-compliant formulations. Distribution runs through direct OEM relationships with major dairy cooperatives and regional equipment distributors serving craft beverage segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EFSA food-contact approval cycles and REACH substance restrictions create 18-24 month barriers that protect validated membrane suppliers from rapid competitive displacement.
For Market Incumbents: Fortify position through captive membrane regeneration service networks in Denmark and the Netherlands, where CSRD disclosure requirements elevate circular economy metrics in procurement scorecards. Expand ceramic architecture production capacity to capture high-temperature dairy retrofit demand from French and Italian cheese processors threatened by chemical sanitization restrictions. For New Entrants and Emerging Players: Membrane regeneration service underperformance by integrated OEMs creates entry points for specialized Polish and Romanian maintenance providers. Target greenfield dairy facilities in these markets where equipment relationships remain unformed. Lead with aftermarket service pricing transparency to exploit unbundling trends among German craft breweries and Spanish cider houses. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors membrane technology specialists with validated EFSA portfolios over diversified engineering conglomerates. Five-to-ten year viability hinges on ceramic material transition execution and regeneration service scalability. Monitor F-Gas Regulation implementation pace as inflection indicator for simultaneous cooling-filtration retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Membrane Capacity Expansion | Captures high-temperature dairy retrofit demand from Roquefort and Comté producers eliminating chemical cycles. |
| Membrane Regeneration Service Launch | Addresses CSRD water recovery metrics for Danish Arla Foods and Dutch dairy cooperatives. |
| REACH-Compliant Resin Backward Integration | Secures supply of food-grade polysulfone against ECHA substance restriction timelines. |
| Polish Greenfield Equipment Specification | Exploits absence of entrenched supplier relationships in expanding dairy processing corridors. |
| F-Gas-Compatible System Redesign | Aligns filtration train engineering with EU refrigeration chemistry phase-down requirements. |
Research Methodology
Initial hypotheses were tested against primary input from membrane system commissioning engineers, dairy plant maintenance directors, beverage procurement managers, and EFSA regulatory affairs specialists and refined through secondary validation. Trade data from Eurostat customs records, ECHA substance restriction announcements, EFSA scientific opinions, and SEC filings of listed equipment manufacturers anchored quantitative sizing. Bottom-up installed base estimates triangulated against top-down procurement spend analysis.
Variance decomposition across product architecture, application segment, technology class, and end-user type shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-unit trends. Whey protein concentration economics and dealcoholization line deployment rates served as industry-specific forecast inputs alongside REACH compliance deadline impacts.
Forecasts assume regulatory continuity in EU Green Deal implementation and EFSA migration testing protocols; material policy shifts would require re-modeling. Specific risks include accelerated F-Gas Regulation phase-downs and novel polymeric material approval delays. Recalibration cycles align with material shifts in ECHA substance restriction schedules and CSRD disclosure requirement enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Small Continuous Fryer Market
Food Processing Equipment
Shawarma Grill Machine Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
Deep Fryer Machine Market
Food Processing Equipment
Automatic Fish Scaling Machine Market
Food Processing Equipment
Soda Production Machine Market
Food Processing Equipment
Freeze-Drying Equipment Market
Food Processing Equipment
Deep Fryer Oil Filtration Market
Food Processing Equipment
Food Extruder Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Food Extrusion Market
Food Processing Equipment
Tomato Processing Machine Market
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
Food Waste Disposal Equipment Market