
 Low-Odor Fish Protein Hydrolysates from Med Species Market | 2026-2036
Low-Odor Fish Protein Hydrolysates from Med Species Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Odor Fish Protein Hydrolysates from Med Species Market Insights
Norway's expanding enzymatic processing capacity is reshaping supply dynamics for Mediterranean-sourced raw material. Hofseth BioCare leverages its integrated trawler-to-hydrolysate model to control freshness at capture. Diana Aqua anchors European demand through specialized marine peptide extraction for premium aquafeed. Omega Protein dominates North American menhaden-derived supply chains, though its technical expertise extends toward odor-mitigated processing architectures.
Low-odor fish protein hydrolysates from med species represent enzymatically digested marine biomass with volatile amine content suppressed below human detection thresholds, typically achieving nitrogen solubility indices above 80% through controlled temperature-pH proteolysis. Powder formulations command the widest formulation flexibility across animal feed and nutraceutical matrices, while liquid concentrates capture margin pools in cosmetics where cold-process compatibility preserves bioactive peptide integrity. Functional foods represent the fastest-growing application channel as beverage manufacturers seek umami-enhancing protein fortification without fishy off-notes.
EFSA novel food authorization pathways govern ingredient entry into European nutraceutical applications, while FDA GRAS self-determination shapes US market access timelines for peptide-based functional ingredients. REACH compliance for processing aids and EU Green Deal carbon accounting requirements are forcing capital allocation toward energy-efficient enzymatic systems with solvent recovery. Stakeholders must monitor regulatory divergence between jurisdictions on marine allergen labeling thresholds and decide whether to pursue parallel compliance pathways or prioritize single-market dominance.
Market Dynamics
The EU's F-Gas Regulation and tightening emissions standards for food processing facilities are forcing capital reallocation toward closed-loop enzymatic systems with integrated odor recovery, compressing margins for conventional thermal processors while rewarding integrated trawler-to-hydrolysate operators with feedstock freshness control.
Growth Catalysts
- Clean-label pet food mandates:North American and European pet food manufacturers are accelerating procurement of low-odor marine ingredients to replace conventional fishmeal in premium formulations, creating pull-through demand for enzymatically processed Mediterranean biomass.
- EFSA novel food pathways:European nutraceutical applications are expanding as peptide-based functional ingredients secure regulatory authorization, opening formulation channels for umami-enhancing protein fortification without sensory off-notes.
- Enzymatic hydrolysis maturation:Controlled temperature-pH proteolysis achieving nitrogen solubility indices above 80% is displacing acid hydrolysis in commercial-scale installations, reducing volatile amine formation at source.
Market Restraints
- Raw material freshness dependency:Volatile amine suppression requires catch-to-processing intervals under 48 hours, constraining viable supply geography to Mediterranean coastal zones with established cold-chain infrastructure.
- Energy-intensive closed-loop recovery:Odor capture and solvent regeneration systems impose electricity costs 40-60% above conventional open-vessel processing, compressing returns for non-integrated operators.
- Plant protein substitution threat:Fermented pea and fava bean protein isolates are achieving comparable palatability enhancement in aquafeed trials at lower input cost volatility, threatening price-positioning for marine-derived alternatives.
Strategic Opportunities
- Cosmetics cold-process channel:Liquid concentrate formats preserving bioactive peptide integrity are capturing margin pools in European cosmetic formulations where thermal denaturation voids functional claims.
- Norway aquaculture nutrition cluster:Feed manufacturers in Bergen and Trondheim are actively sourcing palatability-enhancing alternatives to conventional fishmeal for Atlantic salmon diets, creating concentrated demand pull.
- EU Green Deal carbon accounting:Energy-efficient enzymatic systems with solvent recovery qualify for preferential financing under the European Investment Bank's circular bioeconomy facility, reducing effective capex burdens for compliant installations.
Industry Challenges
- REACH processing aid compliance:Enzyme stabilizers and pH adjustment chemicals require extensive dossier preparation for ECHA registration, extending facility commissioning timelines by 12-18 months.
- Marine allergen labeling divergence:EFSA and FDA maintain discordant thresholds for peptide-level fish protein labeling, forcing parallel compliance investments or single-market prioritization decisions.
- Peptide standardization protocols:Absence of harmonized analytical methods for molecular weight distribution and bioactivity markers complicates customer qualification and contract specification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Odor Fish Protein Hydrolysates from Med Species Market |
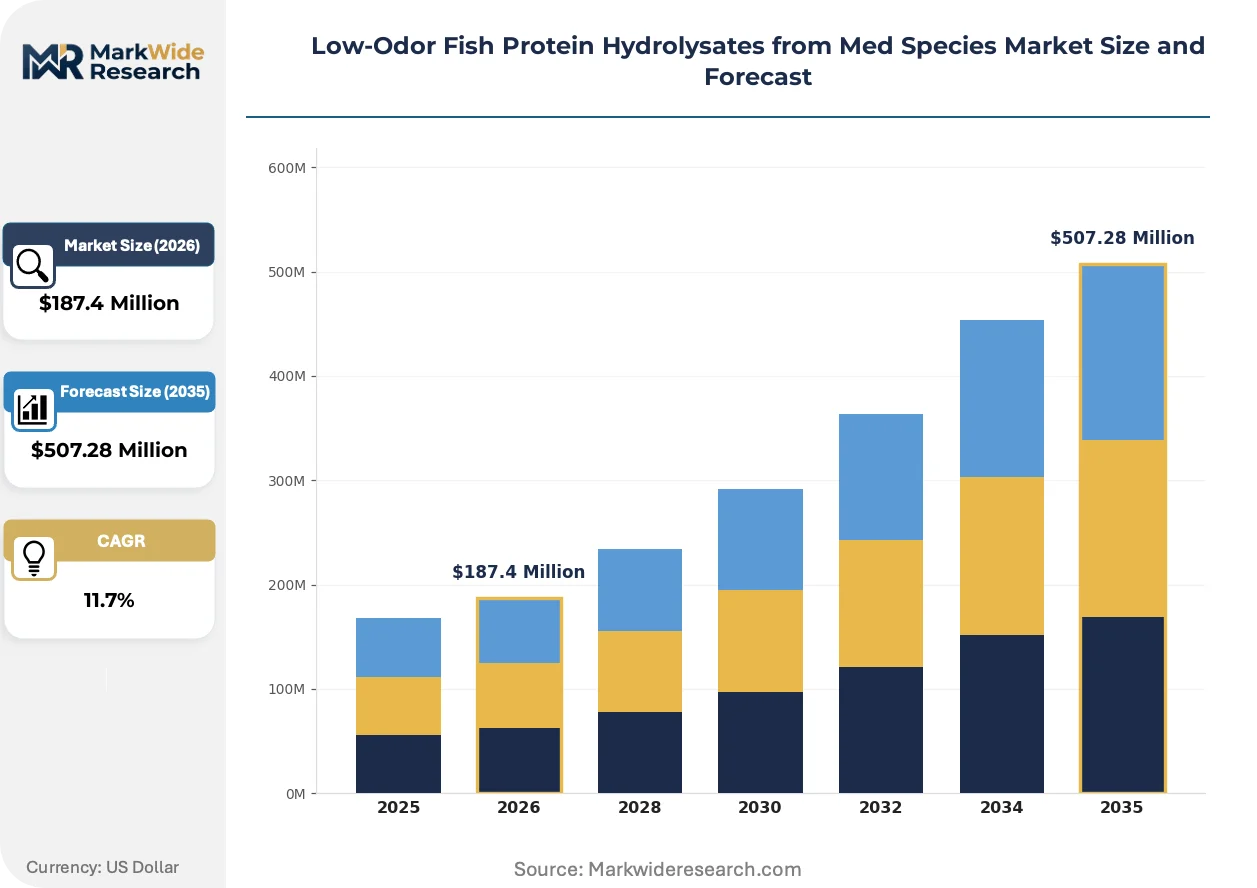
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Concentrate, Granules Application: Animal Feed, Nutraceuticals, Functional Foods, Cosmetics End User: Feed Manufacturers, Dietary Supplement Producers, Personal Care Brands, Contract Manufacturers Packaging Type: Bulk Bags, Plastic Drums, Multi-Layer Pouches, Fiber Drums |
| Companies Covered | Omega Protein, Diana Aqua, Hofseth BioCare, Bio-Marine Ingredients Ireland, Copalis Sea, Arla Foods Ingredients, Fonterra Co-operative Group, Kerry Group, DSM Nutritional Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Odor Fish Protein Hydrolysates from Med Species Market Trends and Innovations
Processing architectures are converging on integrated freshness preservation and volatile compound management, while downstream formulation demands are fragmenting across temperature-sensitive and shelf-stable application requirements.
Membrane filtration cascades for peptide fractionation are migrating from nutraceutical contract manufacturers to integrated marine protein processors. Premium aquafeed compounders in Norway and Scotland are specifying defined molecular weight cuts for palatability enhancement. This technology is migrating from batch diafiltration to continuous tangential flow systems, compressing unit costs and enabling scale-responsive supply contracts.
REACH compliance for processing aids and the EU Green Deal's embodied carbon reporting requirements are forcing disclosure of energy and solvent footprints across enzymatic hydrolysis operations. Facilities without heat recovery or solvent regeneration are facing exclusion from approved supplier lists of major European feed and food manufacturers. Norwegian processors are responding with third-verified lifecycle assessments and power purchase agreements for renewable electricity.
Beverage manufacturers are consolidating peptide procurement through direct partnerships with hydrolysate producers, bypassing traditional ingredient distributors. Functional food formulators in Germany and the Netherlands are specifying cold-process compatible liquid concentrates for ambient-stable protein fortification. This consolidation is most visible in the Benelux region, where clean-label beverage startups are vertically integrating into marine ingredient sourcing to secure supply priority and formulation co-development access.
Low-Odor Fish Protein Hydrolysates from Med Species Market Segmentation
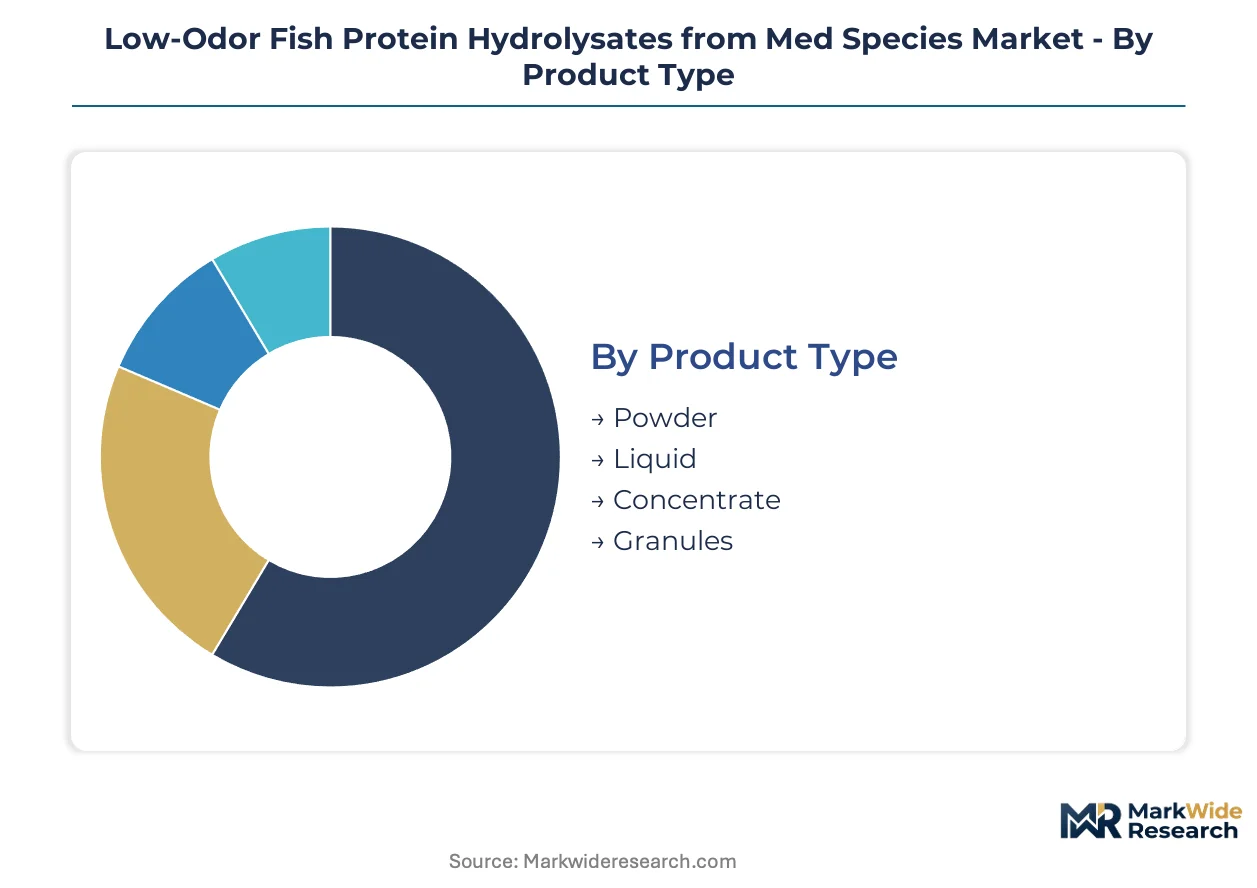
Segmentation in the low-odor fish protein hydrolysates market reveals how enzymatic processing capabilities align with divergent customer requirements across temperature sensitivity, regulatory exposure, and formulation integration complexity. Understanding these partitions exposes where margin pools concentrate and where capital deployment faces technical barriers.
Product Type:
Form factor determines shelf stability, reconstitution behavior, and downstream processing compatibility across feed, food, and cosmetic matrices.
- Powder:Spray-dried hydrolysates with moisture content below 5% achieve nitrogen solubility indices above 80% and blend readily into extruded aquafeed and dry pet food formulations. Norwegian feed compounders in Bergen specify powder grades for Atlantic salmon starter diets where palatability enhancement must survive pelleting temperatures.
- Liquid:Cold-processed concentrates preserve bioactive peptide integrity through minimal thermal exposure, enabling functional claims in European cosmetic applications where denaturation voids efficacy. Dutch beverage manufacturers source liquid formats for ambient-stable protein fortification without sensory off-notes.
- Concentrate:Intermediate viscosity grades bridge reconstitution speed and storage density for contract manufacturers serving multiple end-use channels.
- Granules:Agglomerated particles reduce dusting during bulk handling and improve flow properties for automated feed mill dosing systems.
Powder commands the established base. The steepest expansion runs through liquid formats preserving cold-chain peptide integrity.
Application:
End-use channels fragment by regulatory pathway complexity, temperature tolerance, and sensory threshold requirements.
- Functional Foods:Beverage and snack manufacturers in Germany and the Netherlands are consolidating peptide procurement through direct hydrolysate partnerships, bypassing distributors to secure formulation co-development access and supply priority for umami-enhancing fortification.
- Cosmetics:Cold-process compatibility preserves molecular weight distribution markers required for dermal penetration claims in European cosmetic regulation, with liquid concentrates capturing premium margin pools where thermal denaturation voids functional substantiation.
- Animal Feed:Norwegian aquaculture nutrition clusters specify defined molecular weight cuts for Atlantic salmon diet palatability enhancement.
- Nutraceuticals:EFSA novel food authorization pathways govern entry into European peptide-based supplements, extending qualification timelines against FDA GRAS self-determination in the US.
Animal feed anchors volume demand. Functional foods are climbing the fastest as clean-label beverage startups integrate backward into marine ingredient sourcing.
End User:
Customer type determines specification complexity, contract structure, and technical service intensity.
- Feed Manufacturers:Norwegian salmon feed compounders in Trondheim and Bergen specify peptide molecular weight distribution and volatile amine thresholds in supply agreements, requiring processors to maintain catch-to-hydrolysis intervals under 48 hours.
- Dietary Supplement Producers:EFSA novel food dossier requirements and FDA GRAS self-determination pathways create divergent compliance investments, forcing parallel market entry strategies or single-jurisdiction prioritization.
- Contract Manufacturers:Toll processors serving multiple brands demand flexible batch sizing and rapid specification switching across powder and liquid formats.
- Personal Care Brands:Cosmetic formulators require third-verified lifecycle assessments and renewable electricity documentation under EU Green Deal carbon accounting for approved supplier list inclusion.
Feed manufacturers command the established base. Dietary supplement producers show the steepest trajectory as peptide-based functional ingredients secure regulatory authorization.
Packaging Type:
Containment specifications track moisture sensitivity, handling automation, and regulatory migration limits.
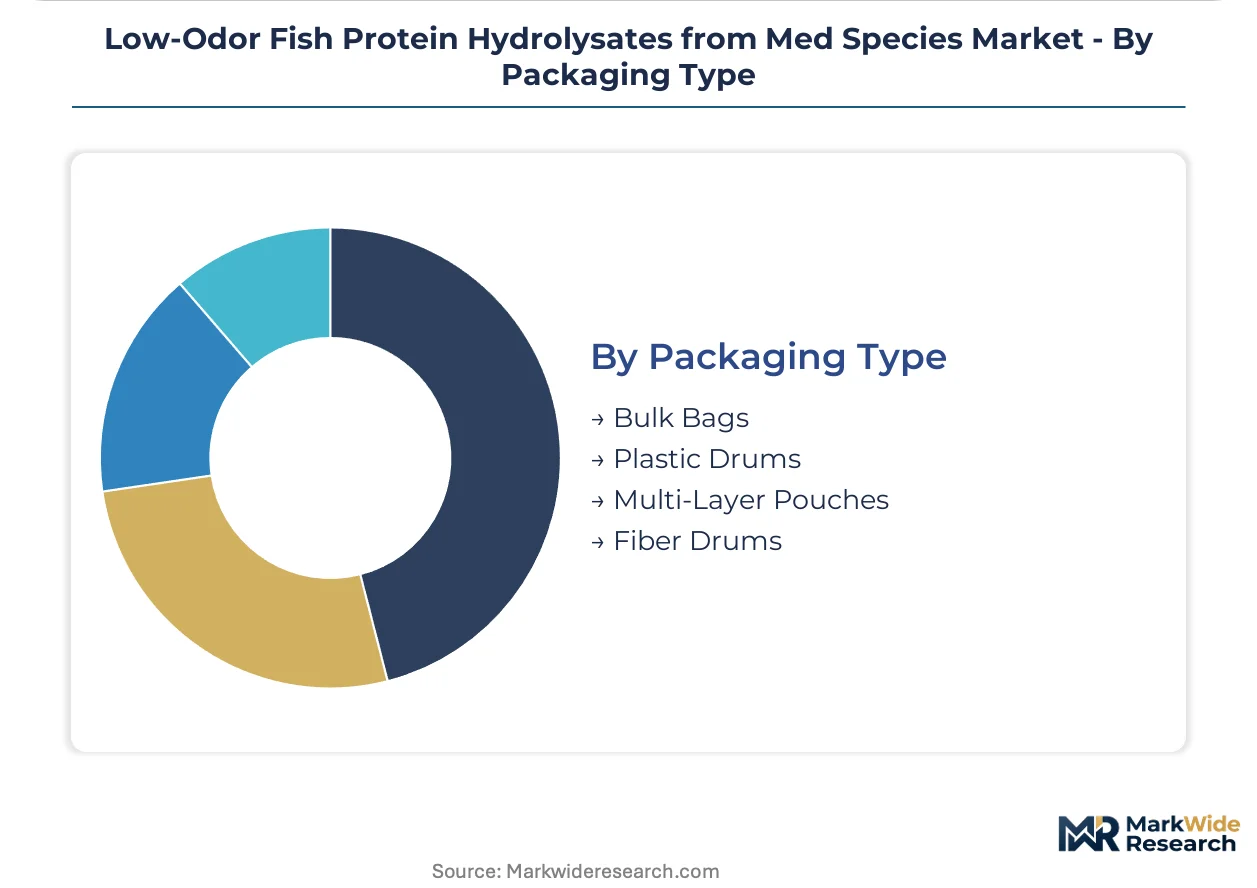
- Bulk Bags:Flexible intermediate bulk containers with laminated liners protect powder hydrolysates from moisture ingress during ocean freight from Mediterranean processing zones to Norwegian aquaculture clusters.
- Multi-Layer Pouches:High-barrier metallized films meet cosmetic and nutraceutical oxygen transmission requirements for peptide stability in extended distribution.
- Plastic Drums:Tight-head polyethylene containers suit liquid concentrate shipments requiring UN certification for marine pollutant classification.
- Fiber Drums:Recyclable Kraft-based containers align with EU circular economy packaging directives for institutional feed ingredient delivery.
Bulk bags command the established base. Multi-layer pouches are expanding most quickly as cosmetic and nutraceutical channels demand extended shelf stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Norwegian aquafeed compounders prioritize enzymatic freshness control for Atlantic salmon diets, while Dutch beverage manufacturers favor cold-process liquid concentrates for clean-label protein fortification. German cosmetic formulators demand third-verified lifecycle assessments under EU Green Deal carbon accounting.
Norway
Atlantic salmon feed manufacturers in Bergen and Trondheim specify peptide molecular weight distribution and volatile amine thresholds below human detection limits. The Norwegian Food Safety Authority enforces strict catch-to-processing traceability for marine ingredients. Hofseth BioCare anchors the aquaculture nutrition cluster through its integrated trawler-to-hydrolysate model controlling freshness at capture.
Germany
Functional food formulators in the Netherlands source cold-process compatible liquid concentrates for ambient-stable protein fortification without sensory off-notes. EFSA novel food authorization pathways govern entry into European nutraceutical applications. Beverage manufacturers in the Benelux region consolidate peptide procurement through direct hydrolysate partnerships bypassing traditional distributors.
France
Cosmetic brands specify liquid concentrate formats preserving bioactive peptide integrity for dermal penetration claims under European cosmetic regulation. REACH compliance for processing aids and EU Green Deal carbon accounting requirements force disclosure of energy and solvent footprints. Diana Aqua anchors specialized marine peptide extraction for premium aquafeed serving French and European markets.
United States
Pet food manufacturers accelerate procurement of low-odor marine ingredients to replace conventional fishmeal in premium formulations. FDA GRAS self-determination shapes market access timelines for peptide-based functional ingredients. Omega Protein dominates menhaden-derived supply chains with technical expertise extending toward odor-mitigated processing architectures.
Ireland
Dietary supplement producers navigate divergent EFSA and FDA allergen labeling thresholds forcing parallel compliance investments or single-market prioritization. The EU F-Gas Regulation pushes producers toward enzymatic hydrolysis methods with closed-loop odor recovery. Bio-Marine Ingredients Ireland occupies a position within the European enzymatic processing tier serving nutraceutical contract manufacturers.
Low-Odor Fish Protein Hydrolysates from Med Species Market Competitive Landscape
Capability concentration sits with integrated trawler-to-hydrolysate operators controlling freshness at capture; scale advantage sits with established marine protein processors with multi-species sourcing networks. The vendor base organizes around three strategic archetypes: freshness-integrated coastal processors, enzymatic technology licensors, and diversified nutrition ingredient platforms. Dominant competitive moves include backward integration into raw material sourcing and geographic expansion into Norwegian aquaculture nutrition clusters.
Within the integrated coastal processing tier, Hofseth BioCare exemplifies freshness control through capture-to-hydrolysate verticality. Diana Aqua occupies a position anchoring European demand for specialized marine peptide extraction. Omega Protein represents the scale-driven North American archetype with menhaden supply chain dominance extending toward odor-mitigated architectures.
| Leading Market Players |
|---|
| Omega Protein |
| Diana Aqua |
| Hofseth BioCare |
| Bio-Marine Ingredients Ireland |
| Copalis Sea |
| Arla Foods Ingredients |
| Fonterra Co-operative Group |
| Kerry Group |
| DSM Nutritional Products |
| Others |
Pricing and Supply Chain Analysis
Bergen's enzymatic processing cluster commands disproportionate pricing leverage through its captive trawler fleets and 48-hour catch-to-hydrolysis protocols, compressing margins for Mediterranean-dependent operators without equivalent freshness control. Norwegian feed compounders exploit this asymmetry to extract favorable long-term offtake terms while southern European processors absorb volatility from spot raw material markets.
Pricing Analysis
Long-term offtake contracts dominate procurement between Norwegian aquafeed compounders and integrated coastal processors, locking in volume commitments against freshness-guaranteed supply tiers. Price differentiation rests on nitrogen solubility index certification and volatile amine thresholds, with premium grades commanding substantial spreads over standard enzymatic hydrolysates. Cost compression in the spot-traded Mediterranean supply tier is intensifying because energy-intensive closed-loop odor recovery systems impose electricity burdens 40-60% above conventional open-vessel processing. Feed manufacturers exhibit the highest price sensitivity due to volume scale and substitution readiness, while cosmetic formulators show lowest sensitivity given peptide integrity requirements.
Supply Chain Analysis
Mediterranean coastal zones in Spain, Italy, and Greece anchor raw material supply through established cold-chain infrastructure supporting sub-48-hour catch-to-processing intervals. Enzymatic processors draw from sardine, anchovy, and mackerel landings, with protease enzymes and pH adjustment chemicals as critical processing inputs. Single-source vulnerability concentrates in specialized protease supply, where REACH registration timelines for enzyme stabilizers extend facility commissioning by 12-18 months. Distribution runs through flexible intermediate bulk containers with laminated liners protecting powder hydrolysates during ocean freight to Norwegian aquaculture clusters, supplemented by tight-head polyethylene drums for liquid concentrate shipments requiring UN certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among Norwegian aquafeed compounders and Benelux beverage manufacturers, who are bypassing traditional ingredient distributors to secure direct hydrolysate partnerships and formulation co-development access.
For Market Incumbents: Insulate margin pools by deepening backward integration into Mediterranean trawler operations and securing renewable electricity power purchase agreements that satisfy EU Green Deal carbon accounting for approved supplier list retention. Plant protein substitution in aquafeed trials poses the primary demand threat, requiring incumbents to invest in peptide molecular weight fractionation capabilities that fermented alternatives cannot replicate. For New Entrants and Emerging Players: Pursue the cosmetics cold-process channel in France and Germany, where liquid concentrate formats preserving bioactive peptide integrity capture premium margin pools and thermal denaturation voids incumbent functional claims. The most penetrable entry point lies in toll processing arrangements for contract manufacturers serving multiple personal care brands, leveraging existing REACH-registered enzyme stabilizer suppliers to compress commissioning timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated trawler-to-hydrolysate operators with demonstrated catch-to-processing traceability under EFSA and FDA parallel compliance pathways. Long-term viability hinges on enzymatic hydrolysis maturation displacing acid hydrolysis at commercial scale. The critical inflection signal to monitor is harmonized analytical method adoption for peptide molecular weight distribution and bioactivity markers, which would unlock contract specification standardization and customer qualification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trawler Operations | Captive supply of Mediterranean sardine and anchovy landings secures 48-hour freshness protocols against volatile amine formation. |
| Renewable Electricity Power Purchase Agreement | Third-verified lifecycle assessments qualify processors for European Investment Bank circular bioeconomy facility financing. |
| Membrane Filtration Cascade Investment | Continuous tangential flow systems enable defined molecular weight cuts specified by Norwegian salmon feed compounders. |
| EFSA Novel Food Dossier Preparation | Regulatory authorization unlocks European nutraceutical applications for peptide-based functional ingredients. |
| Direct Partnership with Beverage Manufacturers | Bypassing distributors secures supply priority and formulation co-development access in Benelux clean-label startups. |
Research Methodology
The analysis maps enzymatic processing technologies, peptide fractionation systems, and odor-mitigation architectures, each validated through procurement directors at Norwegian aquafeed compounders, regulatory affairs leads at hydrolysate processors, cosmetic formulators in France and Germany, and sustainability officers at European feed manufacturers. Primary interview findings triangulate against EFSA novel food authorization databases, REACH registration filings for enzyme stabilizers, EU Green Deal carbon accounting disclosures, customs records for Mediterranean marine protein trade flows, and SEC filings from publicly traded marine ingredient processors. Bottom-up capacity estimates and top-down demand projections reconcile through iterative stakeholder validation.
Assumptions around regulatory pathway timelines, enzymatic hydrolysis yield coefficients, and substitution elasticity between marine and plant proteins remained fixed across modeling scenarios, while raw material availability, energy cost trajectories, and carbon accounting stringency varied. The projection framework segments by product format, application channel, end-user archetype, and packaging specification, with CAGRs derived from elasticity-adjusted demand curves and capacity expansion announcements. Key inputs include nitrogen solubility index achievement rates, volatile amine suppression thresholds, and peptide molecular weight distribution specifications from contract manufacturer qualification protocols.
Sensitivities concentrate around EFSA-FDA regulatory divergence on marine allergen labeling thresholds, REACH processing aid registration delays, and plant protein substitution acceleration in aquafeed trials. Forecasts reflect documented assumptions without contingency for unannounced capacity additions or abrupt regulatory shifts. Cross-checking against European Investment Bank circular bioeconomy facility disbursement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Agar Agar Flakes Market
Ingredients
North America Agar Market
Ingredients
North America Cocoa Products Market
Ingredients
Fluid Lecithin Market
Ingredients
Protein Hydrolysate Market
Ingredients
Konjac Flour Market
Ingredients
Agar Market
Ingredients
Rice Starch Market
Ingredients
Volatile Fatty Acids Market
Ingredients
North America Gluten Free Flour Market
Ingredients
Fig Ingredient Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Borage Oil Market
Ingredients
North America Soybean Oil Market
Ingredients
Smoke Ingredients for Food Market
Ingredients
Omega Ingredients Market