
 Tapioca Starch Market | 2026-2036
Tapioca Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Tapioca Starch Market Analysis
REACH compliance is repositioning the cost-of-entry calculus for tapioca starch suppliers seeking European market access. Roquette Frères leverages its integrated pea-tapioca processing network to sustain margin stability across multiple geographies. Cargill, Incorporated anchors its competitive stance through deep backward integration into Southeast Asian cassava sourcing. Bangkok Starch Industrial Co., Ltd. dominates regional export channels with specialized modified starch production.
Tapioca starch is a carbohydrate extracted from cassava root (Manihot esculenta) containing 70-80% amylopectin and 17-23% amylose, produced through washing, grating, centrifugal separation, and spray-drying to achieve 10-13% moisture content for industrial use. The extracted powder functions as a thickening, gelling, and stabilizing agent across food processing, pharmaceutical excipient formulations, and biodegradable film manufacturing. Modified tapioca starch occupies the largest value share due to its tailored viscosity profiles and freeze-thaw stability demanded by processed food manufacturers. Native tapioca starch leads volume throughput in emerging markets where cost-sensitive bakery industries prioritize functional performance over premium positioning. Biodegradable plastics application represents the fastest-expanding demand pool as brand owners seek cassava-derived alternatives to petroleum-based polymers.
EU Green Deal sustainability criteria and EFSA food additive standards shape product certification requirements and import eligibility for tapioca starch entering European markets. FDA GRAS status and EPA biobased procurement preferences govern US market access and federal purchasing qualification for cassava-derived ingredients. Stakeholders must monitor evolving bioplastics certification schemes and carbon border adjustment mechanisms to align sourcing strategies with tightening environmental compliance thresholds.
Market Dynamics
The EU Green Deal is forcing tapioca starch suppliers to restructure sourcing networks as carbon border adjustments and REACH compliance recalibrate the cost-of-entry for Southeast Asian exporters seeking European market access.
Growth Catalysts
- Clean-label formulation mandates:Food and beverage manufacturers across Germany, France, and Italy are reformulating with tapioca starch to replace modified food starches and meet EFSA clean-label standards.
- REACH registration acceleration:European chemical regulations are compelling suppliers to invest in modified starch R&D facilities within EU borders to bypass import certification delays.
- Cassava cluster expansion:Processing capacity is concentrating in Thailand's Nakhon Ratchasima and Vietnam's Tay Ninh provinces, creating export hub economies of scale.
Market Restraints
- Cassava price volatility:Raw root costs fluctuate with Southeast Asian monsoon patterns and diesel prices for farm-to-factory transport.
- Single-origin concentration risk:Over 60% of global export-grade tapioca starch originates from Thai processing facilities, creating supply vulnerability during regional droughts.
- Modified starch technical ceiling:Freeze-thaw stability in high-acid food systems remains inferior to chemically modified corn and potato alternatives.
Strategic Opportunities
- Biodegradable film underpenetration:Japanese packaging converters are piloting cassava-derived thermoplastic starch to replace petroleum-based flexible films in convenience store chains.
- US biobased procurement preference:EPA federal purchasing guidelines are creating qualified supplier status for cassava starch meeting minimum biobased content thresholds.
- Pharmaceutical excipient convergence:Direct compression tableting and hot-melt extrusion technologies are opening high-margin drug delivery applications for pregelatinized tapioca grades.
Industry Challenges
- Modified starch process engineering talent gap:Southeast Asian facilities face shortages of chemical engineers trained in etherification and esterification reaction control.
- EFSA novel food authorization timelines:New modified starch variants for infant nutrition require 18-24 month safety assessment cycles before European commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tapioca Starch Market |
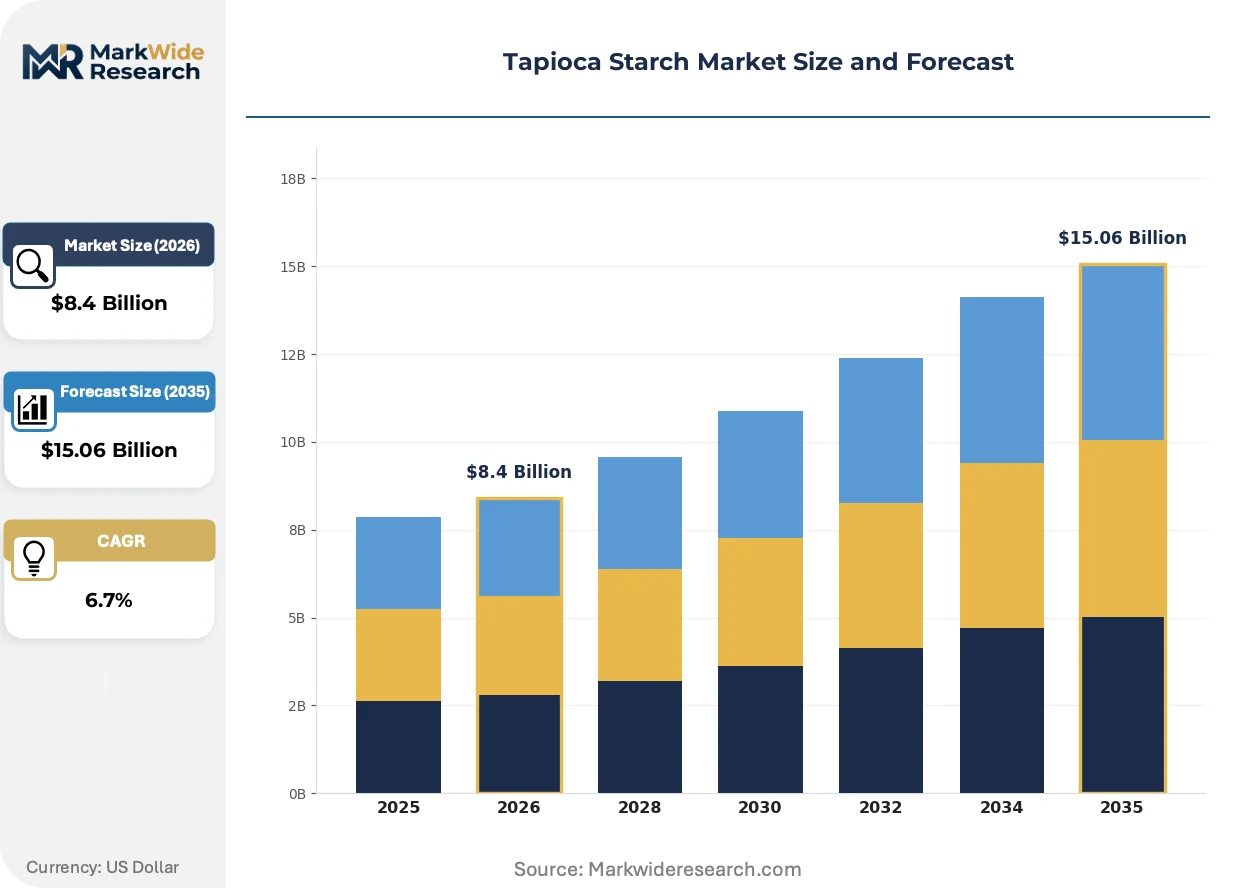
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Tapioca Starch, Native Tapioca Starch, Organic Tapioca Starch, Instant Tapioca Starch Application: Food & Beverage, Pharmaceuticals, Cosmetics, Biodegradable Plastics End User: Food Manufacturers, Bakery Industries, Pharmaceutical Companies, Personal Care Brands Distribution Channel: Online Retail, Wholesalers, Specialty Stores, Supermarkets |
| Companies Covered | Roquette Frères, AVEBE, Ingredion Incorporated, Thai Wah Public Company Limited, Archer Daniels Midland Company, Cargill, Incorporated, Emsland Group, Bangkok Starch Industrial Co., Ltd., Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tapioca Starch Market Emerging Trajectories
Automation and regulatory stringency are compressing traditional processing economics while opening premium positioning for certified-sustainable supply chains.
Enzymatic modification systems are automating viscosity tailoring in Thai and Vietnamese processing plants. Mid-size food manufacturers in Spain and Poland are adopting these precision-controlled starches for ready-meal sauces. This automation is compressing batch-to-batch variability and reducing quality-control labor costs by half.
REACH authorization requirements are tightening impurity thresholds for modified tapioca starch entering EU industrial applications. Chemical processors in Belgium and the Netherlands are demanding full substance volume tracking from cassava farm to final hydroxypropylated product. Modified starch grades for technical textiles and adhesives face the steepest compliance cost increases.
Brand-owner sustainability audits are displacing traditional commodity purchasing in European food manufacturing. Nestlé and Unilever procurement teams are requiring mass-balance certification and farm-level traceability for cassava starch in frozen dessert and sauce applications. This shift is most pronounced in German and Dutch manufacturing facilities where retail chains enforce packaging sustainability scorecards.
Tapioca Starch Market Segmentation
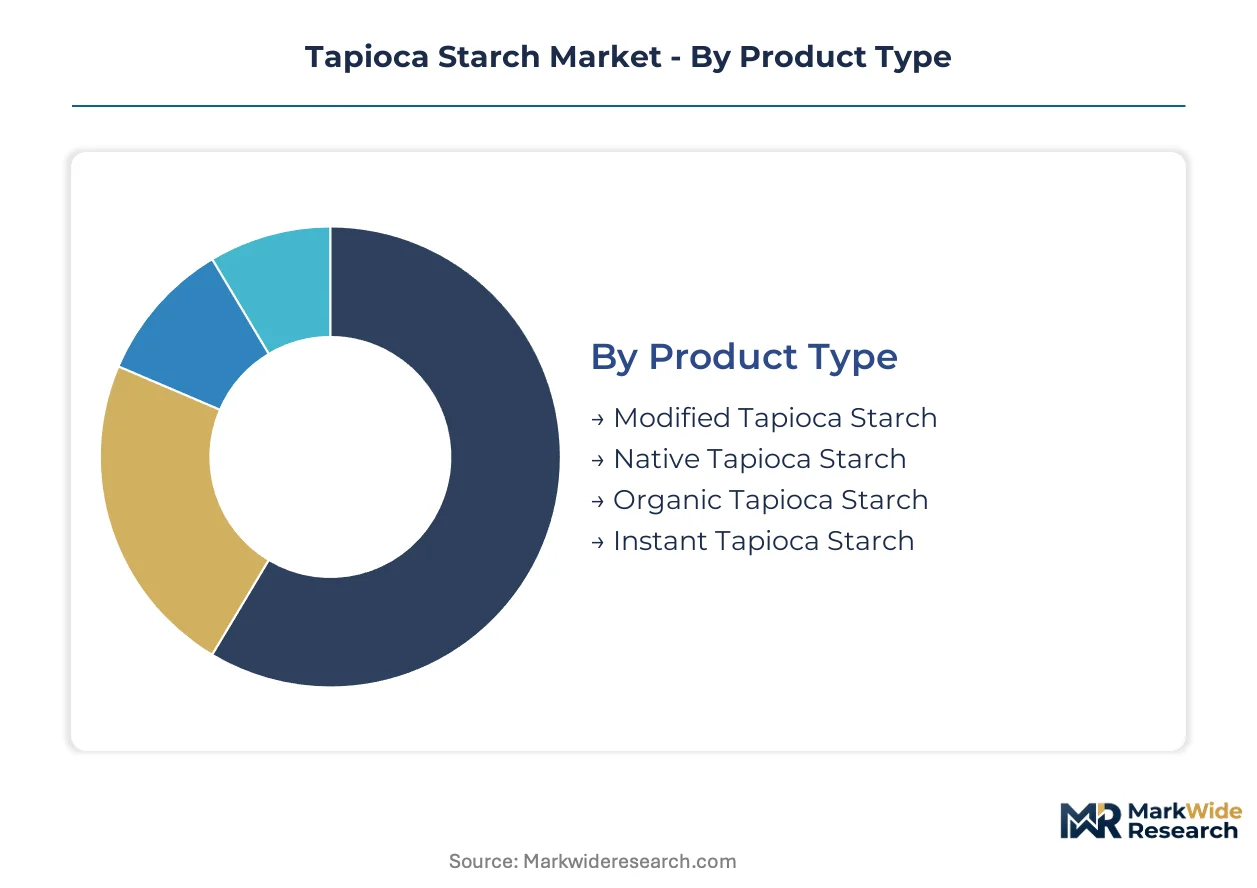
Product functionality and regulatory certification drive purchasing decisions across tapioca starch categories. Buyers prioritize viscosity stability, clean-label compliance, and supply chain traceability when selecting grades for specific applications.
Product Type:
Buyers select product types based on performance requirements versus cost sensitivity in their target applications.
- Modified Tapioca Starch:Chemically or physically altered to achieve specific viscosity profiles, freeze-thaw stability, and acid resistance. Demand concentrates in European processed food manufacturing where EFSA clean-label standards favor modified starches over synthetic thickeners. Modified grades command premium positioning due to tailored functionality in ready-meal sauces and frozen desserts.
- Native Tapioca Starch:Unmodified powder extracted through washing, grating, and spray-drying with 10-13% moisture content. Southeast Asian bakery industries in Thailand and Vietnam absorb volume throughput where cost-sensitive formulations prioritize basic thickening performance. Native starch serves as the reference price point for commodity purchasing decisions.
- Organic Tapioca Starch:Certified organic grades meeting EU organic regulation and USDA NOP standards for ingredient traceability.
- Instant Tapioca Starch:Pre-gelatinized powder dispersing in cold water for convenience food applications and quick-preparation bakery mixes.
Modified tapioca starch leads on scale; organic tapioca starch leads on momentum.
Application:
Application selection follows end-product regulatory requirements and performance specifications.
- Food & Beverage:Thickening, gelling, and stabilizing functions across sauces, soups, dairy alternatives, and baked goods. German and Italian food manufacturers drive adoption as clean-label reformulation accelerates. EFSA additive standards and retailer sustainability scorecards shape ingredient qualification timelines.
- Biodegradable Plastics:Cassava-derived thermoplastic starch replacing petroleum-based polymers in flexible packaging and disposable cutlery. Japanese packaging converters pilot film applications for convenience store chains seeking biobased alternatives. EPA federal purchasing preferences in the US create qualified supplier pathways for cassava starch meeting biobased content thresholds.
- Pharmaceuticals:Excipient functions in tablet binding, disintegration, and controlled-release formulations.
- Cosmetics:Powder bases and texture modifiers in personal care formulations requiring skin-safe carbohydrate sources.
Food and beverage leads on scale; biodegradable plastics leads on momentum.
End User:
End user procurement patterns reflect scale economies and formulation complexity requirements.
- Food Manufacturers:Large-scale processors of ready meals, sauces, and frozen desserts requiring consistent batch-to-batch viscosity. Nestlé and Unilever procurement teams enforce mass-balance certification and farm-level traceability for cassava starch in European manufacturing facilities. Sustainability audits displace traditional commodity purchasing in German and Dutch plants.
- Pharmaceutical Companies:Formulators of solid dosage forms and drug delivery systems demanding excipient purity and documentation.
- Bakery Industries:Producers of bread, pastries, and mixes seeking cost-effective texture modification.
- Personal Care Brands:Cosmetic formulators prioritizing natural ingredient positioning and skin compatibility claims.
Food manufacturers lead on scale; pharmaceutical companies leads on momentum.
Distribution Channel:
Channel selection balances order scale, technical service requirements, and geographic reach.
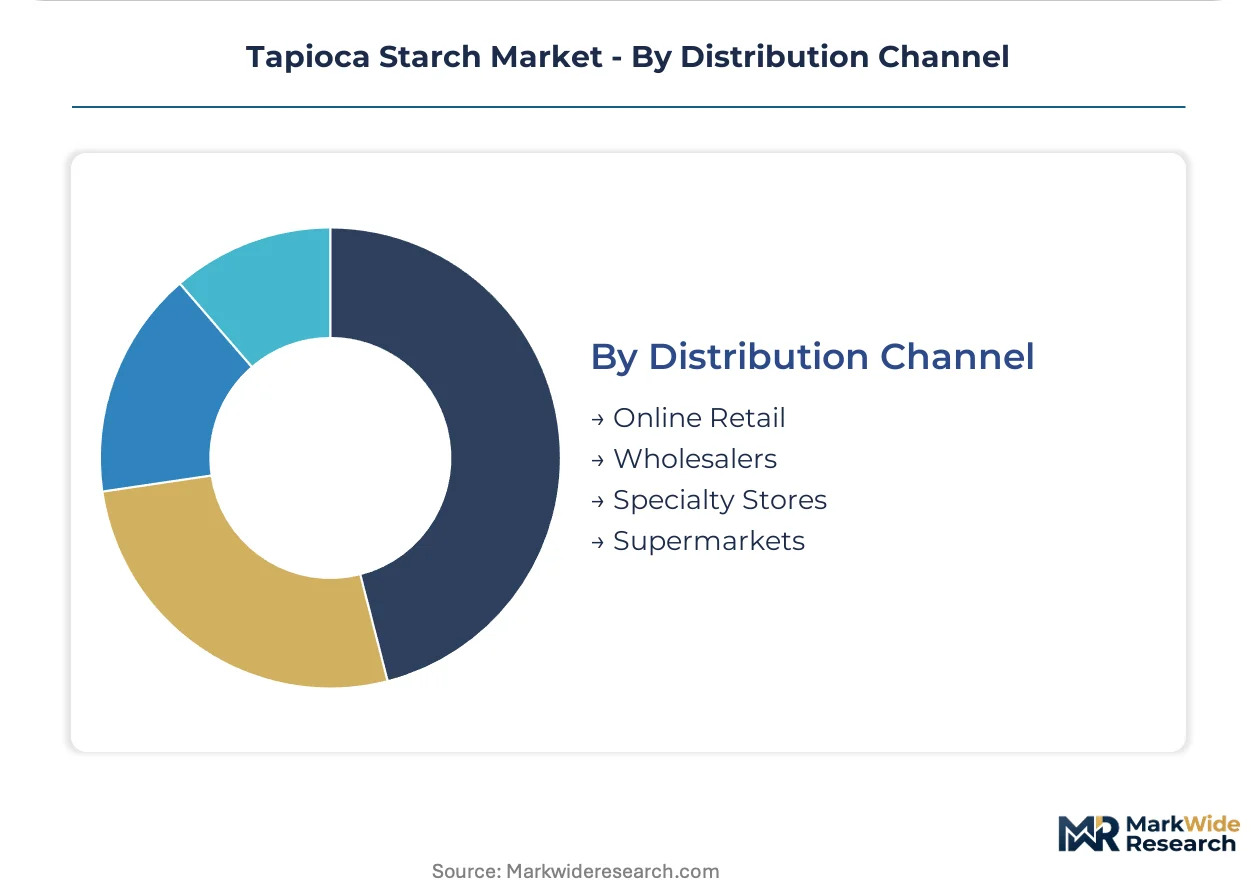
- Wholesalers:Bulk distributors serving mid-size food processors and regional bakery chains with standardized grades. Bangkok Starch Industrial Co. and comparable Thai exporters route containerized shipments through European and North American wholesale networks. REACH compliance documentation travels with bulk consignments to satisfy importer registration requirements.
- Online Retail:E-commerce platforms connecting small-scale buyers with specialty and organic grades.
- Specialty Stores:Ingredient suppliers serving artisan food producers and cosmetic formulators requiring technical consultation.
- Supermarkets:Consumer-packaged goods retail for home baking and small-scale food preparation.
Wholesalers lead on scale; online retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial tapioca starch production scaled in Southeast Asia during the mid-twentieth century as Thai and Vietnamese processors developed export-grade extraction infrastructure. European and North American markets now drive certification requirements while Asian clusters dominate volume throughput.
Thailand
Thai processors supply over sixty percent of global export-grade tapioca starch, with Nakhon Ratchasima province hosting the densest concentration of modified starch facilities. Bangkok Starch Industrial Co. anchors regional export channels through specialized production lines. REACH compliance documentation now accompanies all EU-bound shipments following carbon border adjustment implementation.
Vietnam
Tay Ninh province has emerged as the secondary processing hub where enzymatic modification systems are automating viscosity tailoring for mid-size European food manufacturers. Cassava root supply contracts now incorporate sustainability audit clauses demanded by German retail chains. The country's national food safety authority aligns export certification with EFSA additive standards to accelerate EU market access.
Germany
German food manufacturers in Bavaria and North Rhine-Westphalia are reformulating ready-meal sauces with tapioca starch to meet retailer clean-label scorecards. The country's federal chemical regulator enforces REACH authorization timelines that compel suppliers to invest in EU-based R&D facilities. Emsland Group exemplifies integrated processing operations that combine regional pea starch with imported cassava derivatives.
United States
EPA biobased procurement preferences are creating qualified supplier pathways for cassava starch meeting minimum content thresholds in federal purchasing. Midwestern food processors in Illinois and Ohio are qualifying Southeast Asian exporters for modified starch supply contracts. The FDA maintains GRAS status for cassava-derived ingredients while monitoring novel modification processes.
Japan
Japanese packaging converters in the Kanto region are piloting cassava-derived thermoplastic starch to replace petroleum-based flexible films in convenience store chains. METI industrial policy supports bioplastics certification schemes that align with corporate decarbonization commitments. Direct procurement relationships with Thai processors are bypassing traditional trading house intermediaries.
Tapioca Starch Market Vendor Landscape
The competitive structure tilts toward integrated agribusiness conglomerates with captive Southeast Asian sourcing networks. Market concentration remains moderate with distinct tiering between multinational ingredient suppliers and regional export specialists. Three archetypes dominate: European processors with diversified starch portfolios, Thai-Vietnamese export specialists with modified starch technical capabilities, and North American traders with biobased certification expertise. Capacity expansion in Vietnamese processing zones and strategic partnerships for pharmaceutical-grade production represent the dominant competitive moves.
Within the integrated processor tier, Roquette Frères and Cargill, Incorporated exemplify backward integration into cassava sourcing that sustains margin stability across multiple geographies. Bangkok Starch Industrial Co., Ltd. occupies a position among regional export specialists with concentrated modified starch production capabilities. These three companies represent the structural segmentation between diversified multinational operations and focused Southeast Asian processing hubs that define current competitive positioning.
| Leading Market Players |
|---|
| Roquette Frères |
| AVEBE |
| Ingredion Incorporated |
| Thai Wah Public Company Limited |
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Emsland Group |
| Bangkok Starch Industrial Co., Ltd. |
| Tate & Lyle PLC |
| Others |
Supply Flow & Price Mechanics
Chemical engineers trained in etherification and esterification reaction control cluster in Thailand's Nakhon Ratchasima province, and this workforce concentration compresses modified starch production costs sufficiently to sustain three-tier pricing spreads between premium REACH-certified grades and economy native starch offerings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies tapioca starch procurement by certification grade and modification complexity. Premium positioning attaches to REACH-registered modified grades with full substance volume tracking, while economy tiers serve Southeast Asian bakery industries prioritizing basic thickening performance. Cost compression in standard grades is intensifying because enzymatic modification automation in Vietnamese plants reduces batch-to-batch variability. Food manufacturers in Germany and the Netherlands exhibit the least price sensitivity due to sustainability audit mandates, whereas mid-size bakery industries in Thailand and Vietnam remain highly price-sensitive.
Supply Chain Analysis
Diesel costs for farm-to-factory root transport constitute a material input cost swing factor that Thai processors hedge through long-term cassava supply contracts. Production gravity centers on Thailand, Vietnam, and Cambodia, with raw material flows drawing from Southeast Asian cassava cultivation belts subject to monsoon-driven yield volatility. Single-origin concentration risk manifests in overreliance on Thai export-grade processing facilities during regional drought episodes. Distribution runs through containerized bulk shipments routed via Bangkok Starch Industrial Co. and comparable exporters to European and North American wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe exceed modification cost savings in Southeast Asia by margins that sustain qualified supplier premiums for integrated processors with captive Asian sourcing.
For Market Incumbents: Deepen backward integration into Vietnamese processing zones to diversify supply origination beyond Thailand's drought-exposed Nakhon Ratchasima corridor. Anchor margin stability through enzymatic modification automation investments that compress quality-control labor costs. Counter emerging bioplastics certification demands by pre-positioning mass-balance documentation systems ahead of EU carbon border adjustment enforcement.
For New Entrants and Emerging Players: Enter via pharmaceutical excipient applications where pregelatinized tapioca grades command qualified supplier premiums and EFSA novel food authorization timelines deter incumbent expansion. Target biodegradable plastics converters in Japan's Kanto region seeking cassava-derived thermoplastic starch alternatives to petroleum-based flexible films. Pursue direct procurement relationships with Thai processors that bypass traditional trading house intermediaries.
For Investors and Strategic Acquirers: European diversified starch processors are the most active acquirer in this space, seeking Southeast Asian modified starch capabilities to complete clean-label ingredient portfolios. Long-term viability hinges on sustainability certification infrastructure rather than commodity volume scale. Monitor EFSA novel food authorization pipeline velocity as the inflection signal for premium-grade market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cassava Sourcing | Cargill and Roquette Frères anchor margin stability through captive Southeast Asian root supply contracts. |
| Enzymatic Modification Automation | Vietnamese facilities in Tay Ninh province halve quality-control labor costs through precision-controlled viscosity tailoring. |
| REACH Registration Investment | Belgian and Dutch chemical processors demand full substance volume tracking from farm to hydroxypropylated product. |
| Pharmaceutical-Grade Capacity Expansion | Pregelatinized tapioca grades open high-margin drug delivery applications via direct compression tableting technology. |
| Bioplastics Certification Alignment | Japanese packaging converters pilot cassava-derived thermoplastic starch under METI-supported corporate decarbonization commitments. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with modified starch plant managers, procurement leads at European food manufacturers, distribution channel partners in Thai export networks, and technical R&D directors at enzymatic modification equipment suppliers with secondary validation against customs and trade data, SEC filings from listed agribusiness conglomerates, EFSA additive safety assessments, and REACH registration databases. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates.
Historical reference periods spanning pre- and post-EU Green Deal implementation anchored the forecast window to regulatory inflection points. The analytical framework segmented by product type, application, end user, and distribution channel across the projection horizon, with CAGRs derived from regression analysis of trade flow trajectories and capacity expansion announcements. Modeled inputs included cassava root yield volatility patterns, diesel price movements affecting farm-to-factory transport economics, and EFSA novel food authorization cycle durations.
The model holds under stable REACH authorization timelines and moderate monsoon variability; deviation in EU carbon border adjustment stringency or prolonged Southeast Asian drought would shift supply cost curves and qualified supplier premiums. Stakeholders should weight assumptions against their own operating context and sustainability certification readiness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
Non-PHO Emulsifiers Market
Food Additives and Ingredients
South Africa Food Emulsifiers Market
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
Wine Fining Agent Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Spain Food Acidulants Market
Food Additives and Ingredients
United States Food Additives Market
Food Additives and Ingredients
Canada Food Emulsifiers Market
Food Additives and Ingredients
North America Food Stabilizers Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
North America Food Starch Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
South Africa Food Additives Market