
 Alkalized Cocoa Powder Market | 2026-2036
Alkalized Cocoa Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Alkalized Cocoa Powder Market Analysis
Advanced alkalization process control is reshaping how cocoa processors standardize pH levels and color consistency across batches. Barry Callebaut leverages its integrated bean-to-powder infrastructure to secure supply continuity for industrial chocolate manufacturers. Cargill, Incorporated anchors its competitiveness through vertical ownership of West African sourcing networks and European processing assets. Olam Group differentiates via sustainability certification density across its alkalized cocoa supply chain.
Alkalized cocoa powder is cocoa solids treated with potassium carbonate to neutralize natural acidity, typically achieving pH levels between 6.5 and 7.5 while producing darker color and milder flavor profiles than natural cocoa. The Dutch-processed cocoa category dominates volume given its established preference among European confectioners for color stability in coated products. Bakery Products represents the fastest-growing end-use segment as clean-label dessert formulations require alkalized cocoa's consistent dispersibility and reduced bitterness. Bulk Packaging occupies the largest share within packaging type segments, reflecting the scale of industrial procurement by multinational food manufacturers.
EU EFSA cadmium limits and REACH chemical safety protocols govern alkalized cocoa import and processing standards across European member states. The FDA enforces strict food-grade specifications for alkalized cocoa entering US commercial channels, including heavy metal thresholds and labeling accuracy. Stakeholders must monitor evolving regulatory divergence between European and North American contaminant standards when configuring multi-destination production and compliance strategies.
Market Dynamics
EU EFSA cadmium thresholds are compressing supplier margins and forcing alkalization facility upgrades across European processing clusters, while Dutch-processed cocoa's color stability premium strengthens procurement concentration in the Netherlands.
Growth Catalysts
- REACH chemical safety protocols:These ECHA-enforced standards are accelerating facility modernization among European alkalized cocoa processors, creating compliant capacity expansion.
- Bakery Products segment:Clean-label dessert formulations require alkalized cocoa's consistent dispersibility, pulling volume from industrial chocolate manufacturers into premium baked goods.
- Amsterdam-Zaandam processing cluster:This Dutch harbor infrastructure concentration enables just-in-time alkalization services for German and Swiss confectioners facing tightened EU labeling windows.
Market Restraints
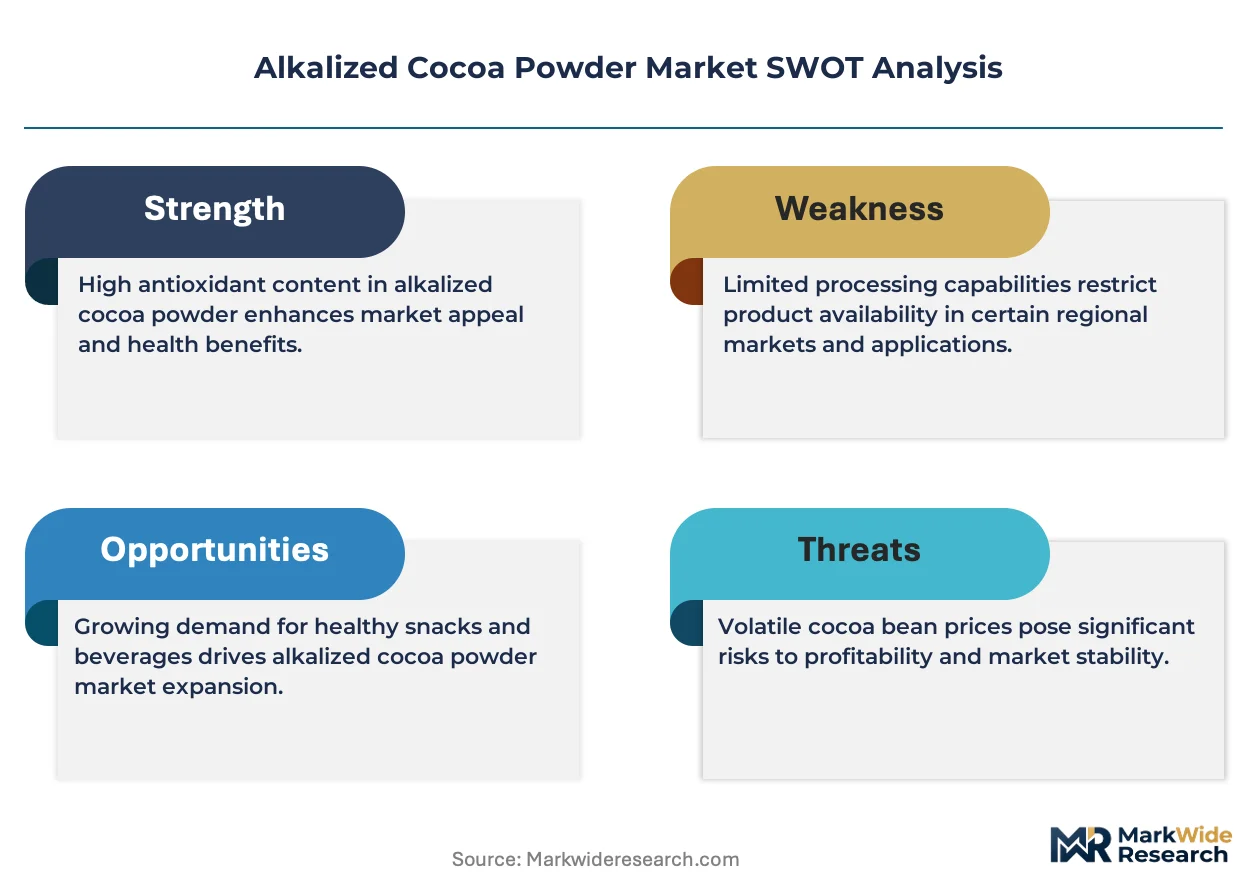
- Cocoa bean input volatility:West African supply disruptions transmit directly to alkalized cocoa powder cost structures, compressing processor margins during harvest shortfalls.
- Single-origin supply concentration:Heavy reliance on Côte d'Ivoire and Ghana bean sourcing creates geographic risk exposure for alkalization facilities without diversified procurement.
- Natural cocoa substitution:Some confectioners revert to natural cocoa powder in applications where color intensity requirements relax, threatening Dutch-processed volume in mid-tier segments.
Strategic Opportunities
- Sustainability certification density:Olam Group's certified supply chain model demonstrates margin capture potential through segregated alkalized cocoa streams for ESG-mandated buyers.
- India FSSAI alignment:Emerging market confectionery growth in India creates entry paths for alkalized cocoa meeting domestic food safety standards without full EU compliance costs.
- Precision alkalization control systems:Integration of inline pH monitoring with automated potassium carbonate dosing enables batch-to-batch consistency premiums in specialty chocolate applications.
Industry Challenges
- Alkalization chemist skill scarcity:Specialized expertise in pH-neutralization process control remains concentrated among veteran European technicians, constraining facility expansion timelines.
- Legacy equipment retrofit costs:Existing natural cocoa processing lines require substantial capital outlay for alkalization reactor installation and effluent handling upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkalized Cocoa Powder Market |
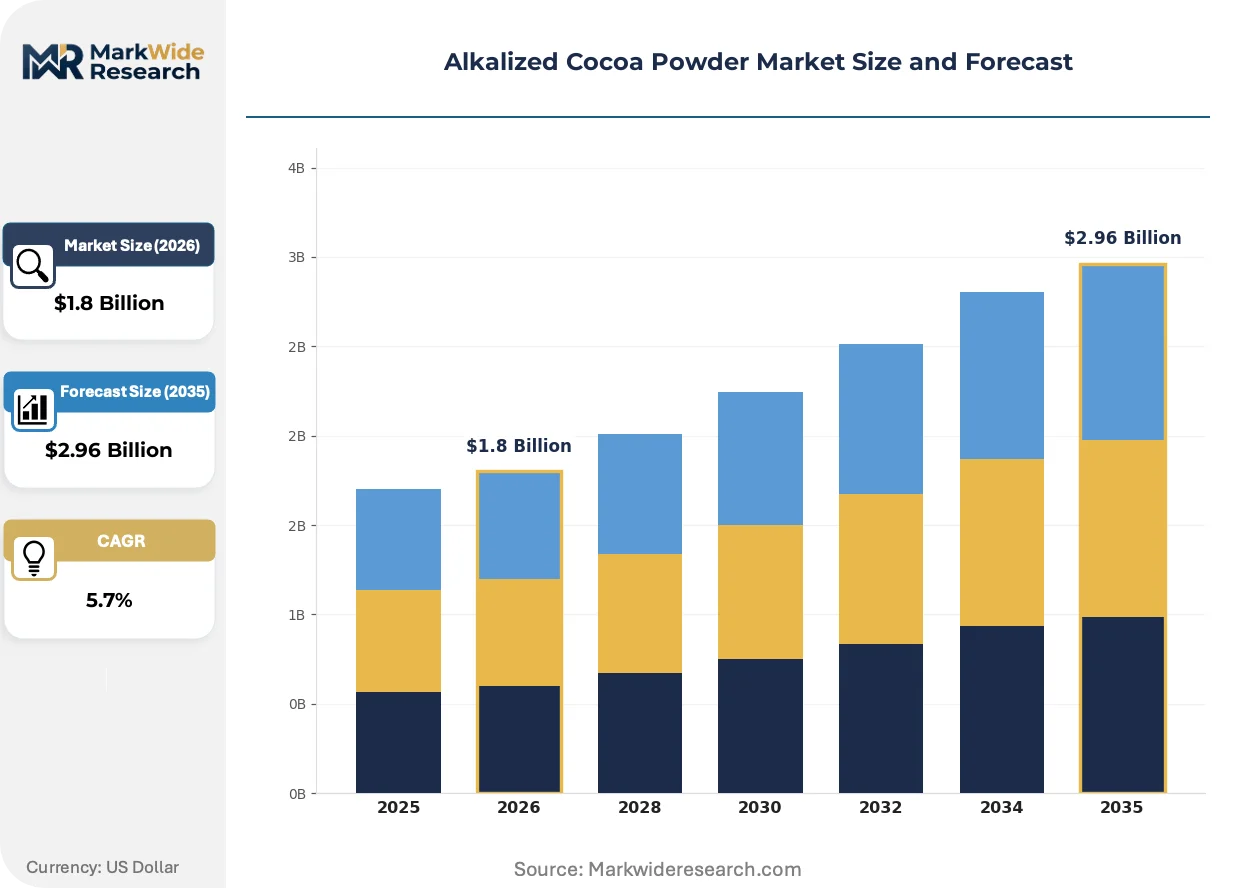
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Cocoa, Dutch-Processed Cocoa, Low-Fat Cocoa, High-Fat Cocoa End Use: Beverages, Bakery Products, Confectionery, Dairy Products Packaging Type: Bulk Packaging, Retail Packaging, Tins, Pouches Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale |
| Companies Covered | Barry Callebaut, Cargill, Incorporated, Olam Group, Blommer Chocolate Company, JB Foods Limited, ECOM Agroindustrial Corp. Limited, Moner Cocoa, Indcresa, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkalized Cocoa Powder Market Emerging Trajectories
Continuous alkalization reactor technology is compressing batch cycle times and standardizing color outputs, while regulatory divergence between EU and North American contaminant standards forces multi-destination producers into dual compliance architectures.
Membrane filtration systems for potassium carbonate recovery are rendering obsolete traditional single-use chemical approaches in alkalization facilities. Mid-sized European processors are retrofitting these systems to reduce input costs and effluent treatment burdens. The technology is enabling smaller batch runs with equivalent color consistency, compressing minimum efficient scale thresholds for specialty cocoa powder production.
EU EFSA cadmium maximum levels are forcing bean sourcing diversification away from high-cadmium origin zones. Processors must now segregate supply streams and implement origin-specific alkalization protocols to guarantee compliance. German and Swiss premium chocolate manufacturers are responding by tightening supplier qualification criteria and demanding batch-level heavy metal documentation.
Direct procurement relationships between alkalized cocoa processors and industrial bakery chains are displacing traditional distributor intermediaries. Large European bakery groups now negotiate volume commitments directly with Amsterdam and Zaandam facilities, securing color specification guarantees for coated product lines. This channel compression is most visible in the Netherlands, where harbor-proximate processing infrastructure supports just-in-time delivery windows for multinational food manufacturers.
Alkalized Cocoa Powder Market Segmentation
Alkalized cocoa powder segmentation reflects divergent technical specifications across pH-neutralization intensity, fat content, and downstream processing requirements. Product differentiation directly determines alkalization reactor configuration and potassium carbonate dosing protocols at processing facilities.
Product Type:
After-sales technical support intensity varies sharply across product categories, with Dutch-processed cocoa demanding sustained color calibration assistance while natural cocoa requires minimal post-sale intervention.
- Dutch-Processed Cocoa:Cocoa solids treated with potassium carbonate to achieve pH 6.5-7.5, producing darker color and milder flavor than natural variants. Demand concentrates among German and Swiss premium chocolate manufacturers facing EU EFSA cadmium labeling deadlines; color stability specifications drive long-term supply contracts with Amsterdam-Zaandam processors.
- Natural Cocoa:Untreated cocoa solids retaining natural acidity with pH 5.0-6.0, preserving sharper chocolate flavor profiles. Some mid-tier confectioners in the Netherlands revert to natural cocoa where color intensity requirements relax, threatening Dutch-processed volume in cost-sensitive applications.
- Low-Fat Cocoa:Defatted cocoa powder containing 10-12% cocoa butter, optimized for calorie-conscious formulations and clean-label dessert applications.
- High-Fat Cocoa:Cocoa powder retaining 20-24% cocoa butter content, delivering richer mouthfeel for premium confectionery and specialty chocolate coatings.
Dutch-Processed Cocoa holds the largest share; momentum sits with Low-Fat Cocoa as clean-label bakery formulations accelerate.
End Use:
Application-driven volume distribution reflects divergent dispersibility requirements and bitterness tolerance thresholds across food manufacturing segments.
- Bakery Products:Fastest-expanding application segment where alkalized cocoa's consistent dispersibility and reduced bitterness enable clean-label dessert formulations. Industrial bakery chains in the Netherlands now negotiate direct procurement with harbor-proximate processors, bypassing traditional distributors for color specification guarantees on coated product lines.
- Confectionery:Established demand anchor for Dutch-processed cocoa, with Swiss and German manufacturers tightening supplier qualification criteria and demanding batch-level heavy metal documentation under EU EFSA cadmium thresholds.
- Beverages:Instant drink mixes and chocolate beverages requiring rapid solubility without sedimentation; pH-neutralization improves suspension stability in hot and cold applications.
- Dairy Products:Ice cream, yogurt, and flavored milk applications where color consistency across production batches maintains brand recognition for multinational dairy processors.
Confectionery holds the largest share; Bakery Products are climbing the fastest as channel compression accelerates direct procurement relationships.
Packaging Type:
Scale economies and handling logistics determine packaging selection, with industrial procurement patterns favoring bulk formats while specialty applications require controlled-atmosphere retail containers.
- Bulk Packaging:Industrial-grade sacks and totes serving multinational food manufacturers with high-volume, continuous production lines. Amsterdam-Zaandam harbor infrastructure enables just-in-time bulk delivery to German and Swiss confectioners facing compressed EU labeling windows.
- Retail Packaging:Consumer-facing formats for artisanal bakeries and specialty food producers requiring smaller lot sizes with full traceability documentation.
- Tins:Airtight metal containers preserving aroma and preventing moisture absorption for premium culinary applications and gift markets.
- Pouches:Flexible laminated bags with resealable closures, gaining traction among mid-sized European processors for specialty cocoa powder production with reduced minimum efficient scale thresholds.
Bulk Packaging holds the largest share; Pouches show steepest expansion trajectory as membrane filtration technology compresses batch minimums.
Distribution Channel:
Channel structure reflects the displacement of intermediary layers as large buyers seek direct processor relationships for specification control and supply continuity.
- Wholesale:Traditional distributor networks serving regional bakeries and smaller confectioners without direct alkalized cocoa procurement capabilities.
- Online Retail:E-commerce platforms capturing artisanal and small-batch producers seeking certified sustainable cocoa with segregated supply chain documentation.
- Supermarkets:Mass-market retail for consumer-packaged cocoa powder, limited in alkalized cocoa given industrial concentration of Dutch-processed volumes.
- Specialty Stores:Gourmet food retailers catering to premium culinary applications and professional pastry chefs requiring specific pH and color specifications.
Wholesale holds the largest share; Online Retail gains share fastest as sustainability certification density becomes a searchable product attribute.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
West African bean flows into Amsterdam-Zaandam processing infrastructure supply German and Swiss confectioners facing compressed EU labeling deadlines for cadmium compliance.
Germany
Premium chocolate manufacturers in Cologne and Hamburg are expanding alkalized cocoa procurement volumes as EFSA cadmium thresholds tighten. The Federal Office of Consumer Protection and Food Safety enforces strict heavy metal documentation requirements. The Hamburg harbor processing corridor enables just-in-time delivery to industrial chocolate manufacturers.
Netherlands
Amsterdam and Zaandam harbor the world's largest cocoa alkalization infrastructure serving pan-European confectionery demand. REACH chemical safety protocols administered by ECHA mandate facility modernization investments. The Rotterdam-Amsterdam logistics cluster supports direct procurement relationships with multinational bakery chains.
Switzerland
Swiss chocolate manufacturers in Zurich and Vevey are tightening supplier qualification criteria under EU EFSA labeling convergence. Swissmedic coordinates with EU regulators on contaminant threshold alignment. The Lake Geneva processing corridor specializes in high-color-stability alkalized cocoa for premium coatings.
United States
Industrial chocolate manufacturers in Pennsylvania and Wisconsin are sourcing alkalized cocoa meeting FDA food-grade specifications for heavy metal thresholds. The FDA enforces strict labeling accuracy requirements for imported cocoa powder. The Port of Philadelphia serves as the primary entry point for Dutch-processed cocoa distribution to Midwest confectionery clusters.
India
Emerging confectionery manufacturers in Maharashtra and Gujarat are developing alkalized cocoa formulations aligned with FSSAI domestic standards. The Food Safety and Standards Authority of India is harmonizing contaminant protocols with international benchmarks. The Mumbai-JNPT logistics corridor enables cost-efficient import processing for industrial bakery expansion.
Alkalized Cocoa Powder Market Vendor Landscape
On the supply side, the industry is consolidating around integrated bean-to-powder processors with captive West African sourcing networks and European alkalization assets. Three strategic archetypes dominate: vertically integrated cocoa processors controlling origin sourcing, specialized alkalization service providers, and diversified agricultural conglomerates with sustainability certification density. Competitive intensity centers on M&A-driven processing capacity expansion and strategic partnerships securing origin supply continuity.
Within the integrated processing tier, Barry Callebaut and Cargill, Incorporated exemplify archetypes combining West African bean origination with European alkalization infrastructure. Olam Group occupies a distinct position emphasizing certified supply chain segregation for ESG-mandated buyers. These three anchors represent the competitive spectrum from integrated infrastructure control to sustainability-differentiated procurement models.
| Leading Market Players |
|---|
| Barry Callebaut |
| Cargill, Incorporated |
| Olam Group |
| Blommer Chocolate Company |
| JB Foods Limited |
| ECOM Agroindustrial Corp. Limited |
| Moner Cocoa |
| Indcresa |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
West African bean origination concentration in Côte d'Ivoire and Ghana funnels pricing power toward integrated processors with captive sourcing networks, while downstream margin pools concentrate among Amsterdam-Zaandam alkalization facilities serving premium chocolate manufacturers.
Pricing Analysis
Legacy batch-process alkalization equipment commands lower per-unit costs than continuous-reactor systems, while next-generation membrane filtration technology enables premium pricing for origin-segregated, certified cocoa streams. Three-tier pricing structure across premium, standard, and economy levels reflects certification density, fat content grade, and color stability guarantees. Cost compression in mid-tier natural cocoa substitution segments is intensifying because confectioners relax color specifications. Industrial bakery chains exhibit lowest price sensitivity due to just-in-time specification requirements, while regional distributors face highest sensitivity from channel compression.
Supply Chain Analysis
EU REACH chemical safety protocols and EFSA cadmium labeling requirements restrict bean flows from high-contaminant origin zones into European processing channels. Supply concentrates in Côte d'Ivoire, Ghana, and Ecuador for bean inputs, with Netherlands and Germany hosting downstream alkalization infrastructure. Potassium carbonate reagent supply, cocoa butter extraction capacity, and effluent treatment chemicals constitute critical input dependencies. Single-origin sourcing vulnerability threatens supply continuity during West African harvest disruptions. Distribution runs through direct procurement relationships between harbor-proximate processors and multinational food manufacturers, displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alkalized cocoa powder procurement is shifting toward platform-based direct relationships, with interoperability between processor alkalization systems and buyer specification databases becoming the ecosystem inflection point.
For Market Incumbents: Pre-empt natural cocoa substitution threats by embedding color calibration services into long-term supply contracts. Expand continuous alkalization reactor capacity in Amsterdam-Zaandam corridor to capture REACH compliance-driven facility consolidation. Secure backward integration into low-cadmium origin zones through offtake agreements with Ecuadorian and Brazilian bean suppliers. For New Entrants and Emerging Players: Pursue white-space opportunities in India FSSAI-aligned alkalized cocoa formulations for emerging confectionery manufacturers. Target membrane filtration retrofit services for mid-sized European processors seeking reduced minimum efficient scale thresholds. Lead with sustainability certification density as the go-to-market angle for ESG-mandated industrial bakery chains. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated processors with captive West African sourcing and European alkalization assets. Long-term viability hinges on regulatory compliance infrastructure amortization across multi-destination production. Watch for EU EFSA cadmium threshold enforcement acceleration as the inflection signal triggering processor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Alkalization Reactor Installation | Compresses batch cycle times for Amsterdam-Zaandam processors serving German confectioners. |
| Membrane Filtration Retrofit | Enables potassium carbonate recovery and smaller specialty batch runs for mid-tier facilities. |
| Low-Cadmium Origin Sourcing Agreement | Secures compliant bean streams for EU EFSA labeling requirements in Swiss chocolate manufacturing. |
| Direct Procurement Platform Development | Bypasses distributor intermediaries for industrial bakery chain color specification guarantees. |
| Sustainability Certification Segregation | Captures ESG-mandated buyer premiums through certified supply chain documentation density. |
Methodological Framework
Cross-validation between primary interviews with cocoa processing executives and secondary customs trade data anchors the qualitative findings. Plant managers at Dutch alkalization facilities, procurement leads at German confectionery manufacturers, sustainability certification officers, and technical R&D directors at potassium carbonate suppliers provided operational perspectives. Secondary validation drew from EU EFSA contaminant threshold documentation, REACH chemical safety protocol filings, FAO cocoa trade statistics, and SEC filings of publicly traded agricultural processors. Bottom-up volume estimates from alkalization facility capacity and top-down demand calibration from end-use consumption patterns were reconciled.
Calibration against historical pH-neutralization technology adoption curves and regulatory compliance cost trajectories shaped the analytical framework. Segmentation dimensions modeled include alkalization intensity tier, fat content grade, end-use application, packaging format, and regional regulatory cluster. CAGRs were derived from slope-consistent growth trajectory fitting across the projection horizon. Forecast inputs incorporated EU cadmium threshold enforcement timelines and continuous reactor technology penetration assumptions.
Sensitivities concentrate around West African supply disruption frequency, EU EFSA labeling deadline acceleration, and natural cocoa substitution elasticity in mid-tier confectionery. Forecasts reflect documented assumptions on regulatory convergence and technology adoption rates. Material shifts in origin-specific cadmium contamination patterns or REACH protocol amendments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Milk Protein Market
Ingredients
Middle East Feed Palatability Enhancers Market
Ingredients
Edible Peanut Oil and Soybean Oil Market
Ingredients
South America Agar Market
Ingredients
Modified Soya Flour Market
Ingredients
Cacao Bean Market
Ingredients
Pea Hull Fiber Market
Ingredients
GCC Bakery Ingredients Market
Ingredients
Safflower Oil Market
Ingredients
Orange Powder Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
Rice Starch Market
Ingredients
Indonesia Edible Oil Market
Ingredients
Plant Extracts Market
Ingredients
Citrus Fiber Market
Ingredients
Africa Fats and Oil Market