
 Vegetable Extract Market | 2026-2036
Vegetable Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Extract Market Analysis
Multi-source botanical procurement is repositioning how vegetable extract buyers manage supply risk and quality consistency. Naturex leverages its Mediterranean and South American cultivation partnerships to secure year-round raw material flows. Kalsec Inc. anchors its competitive stance through vertically integrated capsicum and carrot extract operations in the United States. Symrise AG differentiates via fermentation-derived and plant-based extract synergies that reduce solvent dependency.
Vegetable extracts comprise concentrated bioactive compounds—polyphenols, carotenoids, alkaloids, and essential oils—isolated from plant matrices through mechanical, thermal, or pressurized solvent techniques; supercritical CO2 extraction preserves thermolabile actives at temperatures below 40°C, yielding pharmaceutical-grade purity for sensitive applications. The food industry segment dominates volume consumption as clean-label coloring and flavoring replacements for synthetic additives gain formulation share, while supercritical fluid extraction commands premium positioning due to its absence of residual petrochemical solvents and compliance with organic certification standards. Powder and liquid forms split end-user preference by stability requirements and dosing flexibility in beverage versus tablet applications.
EFSA novel food assessments and EU REACH substance restrictions are elevating documentation burdens for non-European extract suppliers seeking market access. FDA GRAS self-affirmation and FSSAI ingredient licensing in India create parallel compliance tracks that shape regional competitive entry costs. Stakeholders must monitor evolving residue limits for ethylene oxide and glyphosate as regulatory arbitrage between jurisdictions becomes a decisive sourcing variable.
Market Dynamics
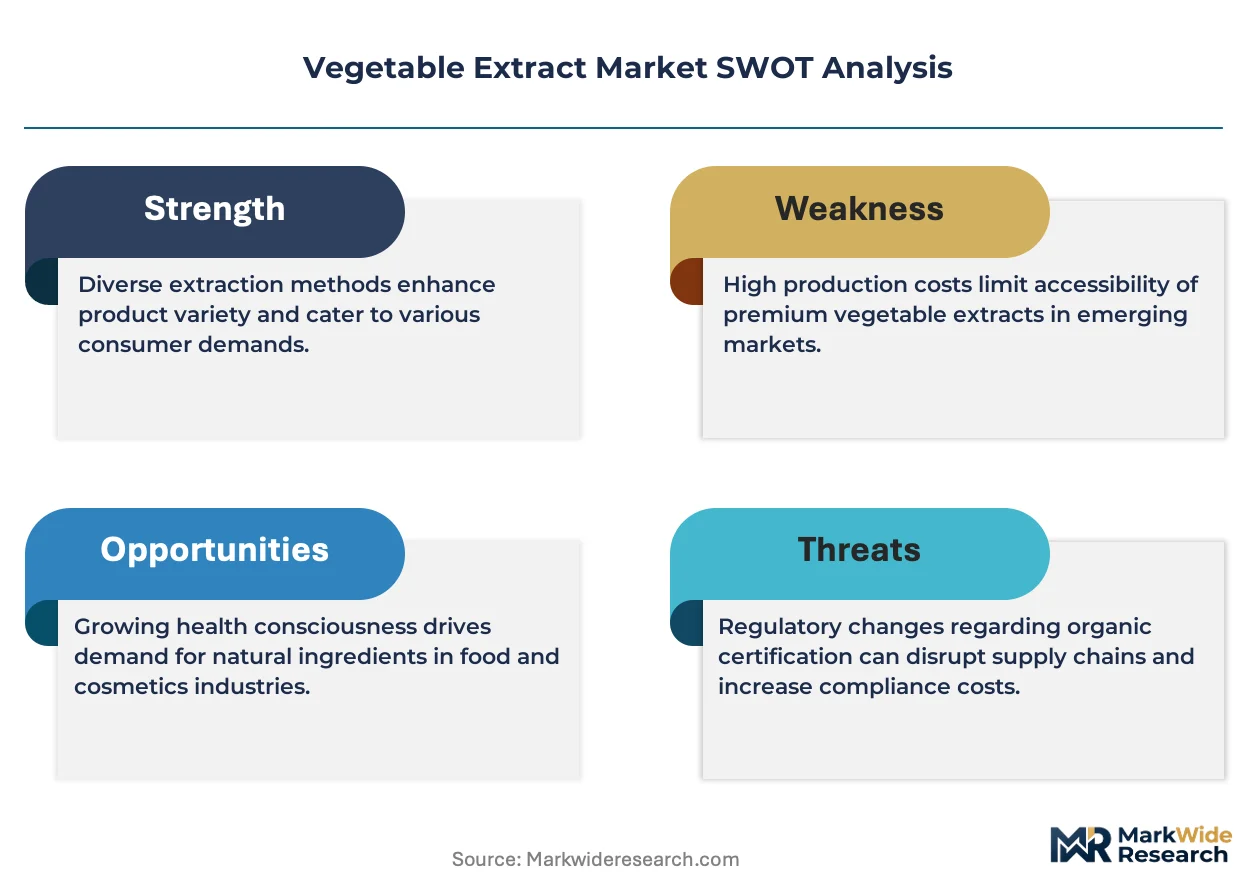
Clean-label formulation mandates from EU REACH and EFSA are compressing synthetic additive tolerance while elevating botanical extract procurement complexity for multinational food and nutraceutical manufacturers.
Growth Catalysts
- EFSA Novel Food Pathway:Standardized safety assessments for new botanical concentrates accelerate European market entry for validated extract suppliers.
- Supercritical CO2 Systems:Pharmaceutical-grade extraction without residual solvents satisfies organic certification thresholds for premium nutraceutical applications.
- India:FSSAI ingredient licensing reforms streamline import documentation for standardized vegetable concentrates entering domestic supplement manufacturing.
Market Restraints
- Raw Material Volatility:Climate-driven harvest fluctuations in Mediterranean capsicum and carrot growing regions destabilize year-round extract supply commitments.
- Regulatory Friction:Divergent residue limits for ethylene oxide and glyphosate between EU REACH, FDA GRAS, and FSSAI create compliance arbitrage costs for cross-border suppliers.
- Substitution Pressure:Synthetic carotenoid and polyphenol alternatives from petrochemical feedstocks undercut botanical extracts on price in cost-sensitive beverage applications.
Strategic Opportunities
- Fermentation-Derived Synergies:Bioprocessed bioactive precursors reduce solvent dependency while expanding yield consistency for thermolabile compound production.
- China:SAMR novel food regulations and dual carbon goals create preferential market access for low-carbon extraction technologies in domestic functional food formulations.
- Direct-to-Formulator Channels:Bypassing traditional ingredient distributors via certified digital procurement platforms reduces documentation lag for compliant extract sourcing.
Industry Challenges
- Analytical Chemist Shortage:Specialized chromatography and spectroscopy expertise for batch-to-batch phytochemical validation remains scarce across contract testing laboratories.
- Multi-Jurisdiction Certification Timelines:Parallel EU organic, USDA NOP, and India Organic filings extend product launch cycles by 18-24 months for new extract introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Extract Market |
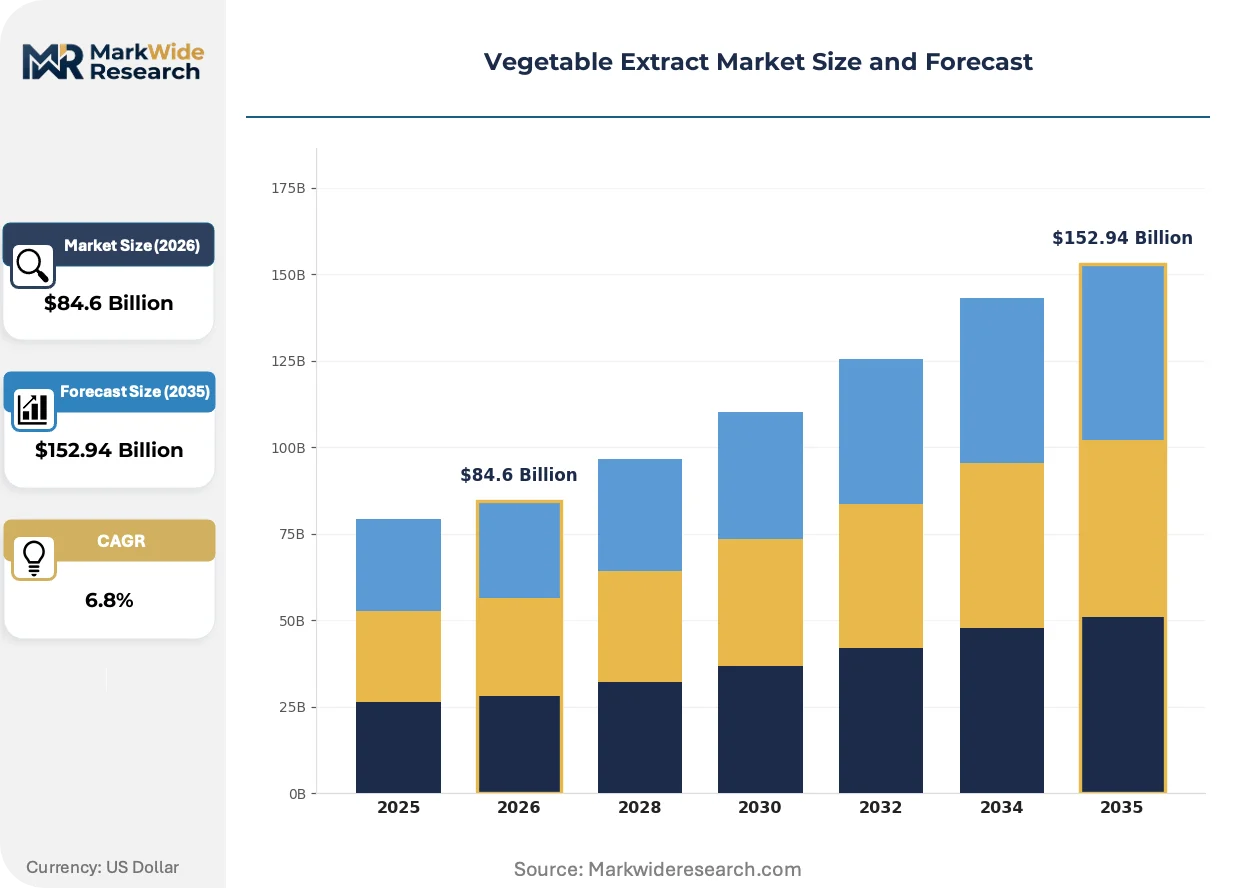
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extract, Fruit Extract, Leaf Extract, Root Extract End User: Food Industry, Nutraceuticals, Cosmetics, Pharmaceuticals Form: Liquid, Powder, Granule, Paste Extraction Method: Cold Pressing, Solvent Extraction, Steam Distillation, Supercritical Fluid Extraction |
| Companies Covered | Naturex, Kalsec Inc., Döhler GmbH, Martin Bauer Group, Symrise AG, Givaudan, Sensient Technologies Corporation, Archer Daniels Midland Company, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Extract Market Emerging Trajectories
Extraction technology convergence with precision fermentation and AI-driven phytochemical profiling is compressing development cycles while fragmenting competitive advantage sources across the supply base.
Supercritical CO2 extraction equipment is integrating with inline near-infrared spectroscopy for real-time active compound monitoring during botanical processing. Nutraceutical contract manufacturers in Germany and Switzerland are retrofitting existing pressurized systems with these sensor arrays to reduce batch rejection rates. The technology is integrating quality assurance directly into production workflows, collapsing the traditional separation between manufacturing and analytical validation.
EU REACH substance restrictions on residual petrochemical solvents are tightening purity documentation requirements for imported concentrates entering European food applications. Manufacturers must now submit full supply chain chemical inventories extending back to agricultural inputs. Small-scale South American and Asian extract suppliers face disproportionate compliance burdens, accelerating consolidation toward vertically integrated European and North American producers with captive cultivation networks.
Formulators are consolidating supplier relationships around regionally certified partners capable of delivering standardized phytochemical certificates with every lot. Beverage manufacturers in Germany and China now require dual-specification documentation covering both identity preservation and quantitative active profiling. This concentration is visible most acutely in clean-label coloring applications, where synthetic replacement projects demand guaranteed year-round chromatographic consistency that fragmented spot-market sourcing cannot reliably deliver.
Vegetable Extract Market Segmentation
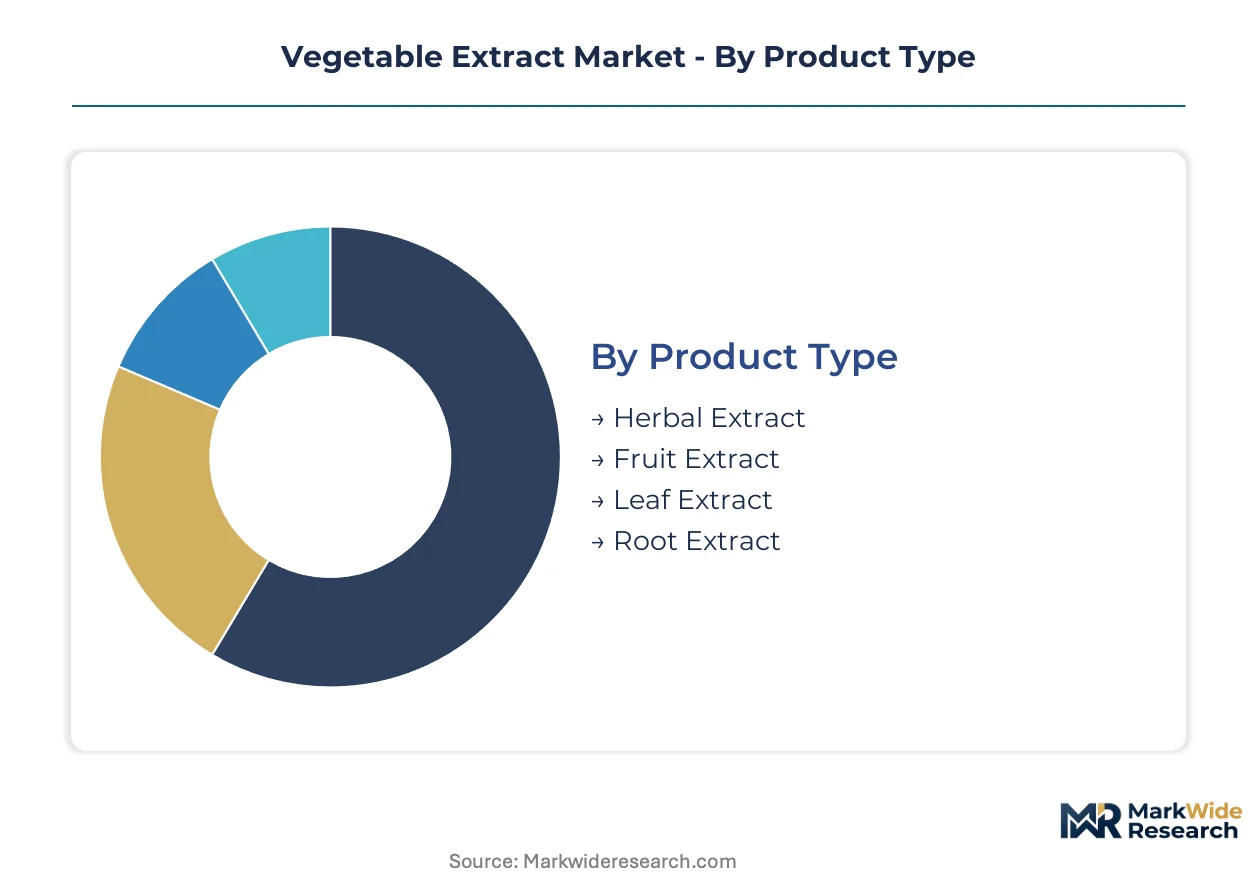
Vegetable extract procurement decisions hinge on how formulators balance stability requirements, regulatory compliance thresholds, and dosing precision across divergent end-use applications. Segmentation reveals where extraction technology investments concentrate versus where commodity sourcing suffices.
Product Type:
Standalone concentrates dominate high-value nutraceutical formulations, while embedded extracts integrate into multi-ingredient food matrices requiring less precise active standardization.
- Herbal Extract:Concentrated bioactive complexes—polyphenols, alkaloids, terpenoids—derived from medicinal plant species. Demand concentrates in German and Swiss nutraceutical manufacturing where EFSA novel food dossiers require validated phytochemical profiles for immune and adaptogenic positioning.
- Fruit Extract:Anthocyanin and flavonoid concentrates from berry and citrus matrices. Beverage formulators in China leverage these for clean-label coloring replacements, though climate volatility in Mediterranean growing regions constrains year-round supply security.
- Leaf Extract:Chlorophyll and catechin concentrates from tea, spinach, and nettle sources.
- Root Extract:Ginsenoside and withanolide concentrates from adaptogenic botanicals.
Volume placements concentrate in Herbal Extract; the faster expansion belongs to Fruit Extract.
End User:
Cost tier stratification separates premium pharmaceutical-grade specifications from economy food-grade tolerances, with nutraceuticals occupying the contested middle ground.
- Food Industry:Clean-label coloring and flavoring replacements for synthetic additives in beverages, confectionery, and prepared foods. German manufacturers now mandate dual-specification documentation covering identity preservation and quantitative active profiling for every lot.
- Nutraceuticals:Standardized botanical concentrates for dietary supplements and functional foods. India FSSAI ingredient licensing reforms streamline import documentation, accelerating domestic contract manufacturing expansion for export markets.
- Cosmetics:Antioxidant and soothing actives for topical formulations.
- Pharmaceuticals:API-grade extracts meeting pharmacopeial monograph standards.
Food Industry commands absolute volume; nutraceuticals are climbing the fastest on per-unit value expansion.
Form:
Application-driven selection favors liquids for beverage integration, powders for tablet compression, and granules for sachet dosing flexibility.
- Liquid:Ready-to-disperse concentrates with immediate bioavailability in beverage matrices. Chinese functional drink manufacturers prefer these for streamlined production workflows, though cold-chain logistics add cost complexity.
- Powder:Spray-dried or freeze-dried extracts with extended shelf stability. Nutraceutical tablet manufacturers in Germany specify powder forms for precise dose uniformity in high-speed compression equipment.
- Granule:Intermediate particle size for controlled dissolution in instant applications.
- Paste:High-viscosity concentrates for bakery and confectionery incorporation.
Powder dominates manufacturing throughput; liquid forms gain share fastest in ready-to-drink expansion.
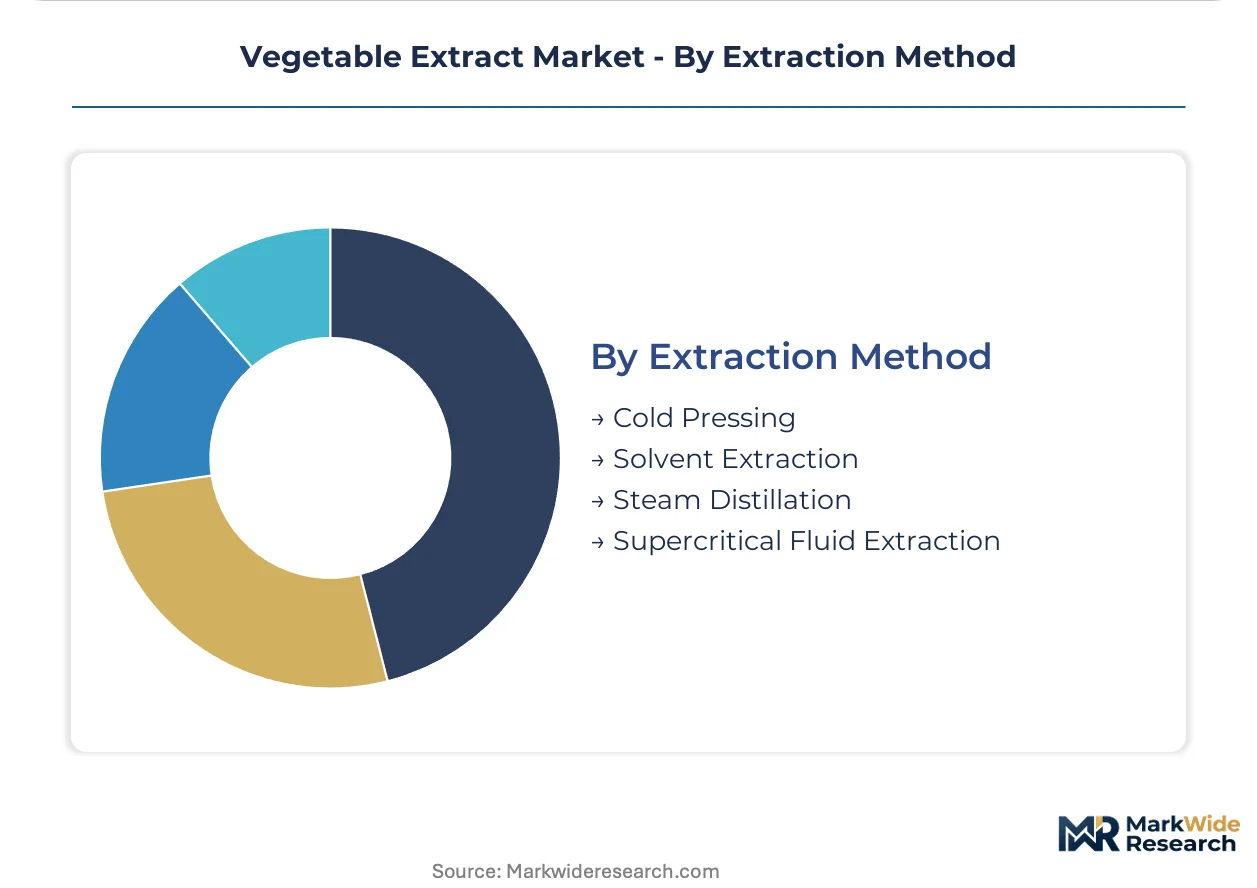
Extraction Method:
Margin structure separates solvent-intensive commodity processing from supercritical systems commanding organic certification premiums.
- Supercritical Fluid Extraction:Pressurized CO2 processing below 40°C preserves thermolabile actives without residual petrochemical solvents. Swiss and German contract manufacturers retrofit existing systems with inline near-infrared spectroscopy for real-time quality assurance integration.
- Solvent Extraction:Ethanol and hexane-based processing for high-yield commodity concentrates. EU REACH substance restrictions on residual solvents tighten documentation burdens, favoring European producers with captive cultivation networks over fragmented Asian suppliers.
- Cold Pressing:Mechanical oil extraction without thermal degradation.
- Steam Distillation:Thermal separation for volatile essential oil recovery.
Solvent Extraction retains volume dominance; supercritical systems show the steepest expansion trajectory on organic certification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mediterranean capsicum and carrot cultivation networks anchor European supply security, while South American botanical partnerships extend raw material access across hemispheres. Climate volatility in these growing regions destabilizes year-round extract commitments for multinational formulators.
Germany
EFSA novel food dossiers drive demand for validated phytochemical profiles in immune and adaptogenic positioning. REACH substance restrictions on residual petrochemical solvents tighten documentation burdens for imported concentrates. Bavarian nutraceutical contract manufacturers retrofit supercritical CO2 systems with inline near-infrared spectroscopy for real-time quality assurance.
China
SAMR novel food regulations and dual carbon goals create preferential market access for low-carbon extraction technologies. Functional beverage manufacturers in the Yangtze River Delta specify liquid extract forms for streamlined production workflows. Cold-chain logistics infrastructure expansion supports ready-to-drink formulation growth despite added cost complexity.
India
FSSAI ingredient licensing reforms streamline import documentation for standardized vegetable concentrates entering domestic supplement manufacturing. Maharashtra-based contract manufacturers expand export-oriented capacity for European and North American nutraceutical brands. Climate-driven harvest fluctuations in domestic botanical growing regions constrain supply security for year-round commitments.
Switzerland
Swissmedic pharmacopeial standards elevate API-grade extract specifications for pharmaceutical applications. Precision fermentation integration with botanical extraction reduces solvent dependency in thermolabile compound production. Zurich-Geneva industrial corridor concentrates supercritical CO2 equipment retrofitting activity for organic certification compliance.
United States
FDA GRAS self-affirmation creates parallel compliance tracks that shape regional competitive entry costs distinct from European pathways. Midwest capsicum and carrot cultivation supports vertically integrated extract operations with captive supply networks. California beverage formulators mandate dual-specification documentation covering identity preservation and quantitative active profiling for clean-label coloring projects.
Vegetable Extract Market Vendor Landscape
Capacity expansion dominates the current landscape as established players retrofit extraction infrastructure with inline spectroscopy and fermentation integration. The vendor base concentrates around vertically integrated cultivator-processors and technology-specialized contract manufacturers. Three archetypes define competitive positioning: Mediterranean-South American cultivation partnerships, fermentation-derived bioprocessing specialists, and precision extraction equipment integrators. M&A activity and strategic technology licensing represent the dominant competitive moves reshaping supply relationships.
Within the vertically integrated tier, Naturex leverages its Mediterranean and South American cultivation partnerships to secure year-round raw material flows. Kalsec Inc. anchors its competitive stance through in-house capsicum and carrot extract operations in the United States. Symrise AG exemplifies the fermentation-synergy archetype, reducing solvent dependency while expanding yield consistency for thermolabile compound production.
| Leading Market Players |
|---|
| Naturex |
| Kalsec Inc. |
| Döhler GmbH |
| Martin Bauer Group |
| Symrise AG |
| Givaudan |
| Sensient Technologies Corporation |
| Archer Daniels Midland Company |
| Kerry Group |
| Others |
Supply Flow & Price Mechanics
Supercritical CO2 extraction retrofits with inline near-infrared spectroscopy are compressing batch rejection rates while concentrating cost premiums among Swiss and German contract manufacturers with certified organic infrastructure. This technology bifurcation simultaneously elevates pricing power for pharmaceutical-grade suppliers and squeezes commodity solvent-extraction tiers facing EU REACH documentation burdens.
Pricing Analysis
Certificate-of-analysis bundling separates premium contract manufacturers from unbundled spot-market suppliers in extract procurement. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-standard, and food-economy levels reflects certification depth and chromatographic validation rigor. Cost compression in food-grade tiers intensifies because synthetic carotenoid alternatives undercut botanical sources on unit economics. Beverage formulators in China exhibit highest price sensitivity; Swiss pharmaceutical contract manufacturers demonstrate lowest sensitivity due to pharmacopeial compliance requirements.
Supply Chain Analysis
Direct-to-formulator digital procurement platforms are bypassing traditional ingredient distributors for compliant extract sourcing. Raw material flows draw from Mediterranean capsicum cultivation, Midwest United States carrot operations, and South American botanical partnerships. Specific inputs include capsicum oleoresin, carrot seed oil, and standardized polyphenol concentrates. Single-source vulnerability concentrates in climate-exposed Mediterranean growing regions where harvest fluctuations destabilize year-round commitments. Distribution runs through certified regional hubs in Germany, China, and India for documentation efficiency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized analytical chemist scarcity for phytochemical validation is constraining batch throughput and propping pricing premiums for certified contract manufacturers with captive laboratory capacity.
For Market Incumbents: Deploy supercritical CO2 equipment retrofitting as a defensive moat against fermentation-derived synthetic biology entrants. Consolidate backward integration into Mediterranean and South American cultivation partnerships to secure raw material flows against climate volatility. Expand in-house chromatography capacity to reduce third-party validation dependency and compress batch release timelines. For New Entrants and Emerging Players: Capture white-space in FSSAI-licensed Indian contract manufacturing for European and North American nutraceutical brand export. Target direct-to-formulator digital procurement channels with streamlined documentation packages for mid-tier beverage manufacturers. Lead with low-carbon extraction technology credentials aligned with SAMR dual carbon goals in China functional beverage applications. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated cultivator-processors possessing captive supercritical CO2 infrastructure given EU REACH solvent restriction tightening. Long-term viability hinges on certification depth spanning EU organic, USDA NOP, and India Organic filings. Monitor ethylene oxide residue limit harmonization across EU REACH, FDA GRAS, and FSSAI as inflection indicator for cross-border supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Equipment Retrofitting | Inline spectroscopy integration collapses batch rejection rates at Swiss and German contract manufacturers. |
| Fermentation-Derived Bioactive Expansion | Symrise AG's bioprocessing reduces solvent dependency for thermolabile compound production. |
| Captive Cultivation Network Development | Mediterranean-South American partnerships secure year-round raw material flows against climate volatility. |
| Direct-to-Formulator Digital Platforms | Bypassing traditional distributors reduces documentation lag for EFSA-compliant extract sourcing. |
| Multi-Jurisdiction Certification Investment | Parallel EU organic, USDA NOP, and India Organic filings extend product launch cycles but lock in premium positioning. |
Methodological Framework
EFSA novel food dossier databases, FSSAI ingredient licensing records, and EU REACH substance restriction filings formed the secondary backbone for regulatory pathway mapping. Primary interviews with extraction equipment engineers, nutraceutical contract manufacturing procurement leads, botanical cultivation operations managers, and analytical laboratory directors validated supply-side capacity constraints. Customs trade data for capsicum and carrot extract flows supplemented bottom-up triangulation against top-down market sizing.
Historical trendline analysis of supercritical CO2 equipment installations and solvent extraction capacity retirements informed technology transition modeling across the projection horizon. Segmentation dimensions included extraction method tier, end-use industry application, form factor stability requirements, and regional regulatory cluster. CAGRs were derived from demand elasticity modeling against synthetic substitute pricing and certification premium persistence. Industry-specific inputs incorporated climate-driven harvest variance coefficients and multi-jurisdiction certification timeline distributions.
The model holds under stable EU REACH enforcement intensity and consistent FSSAI licensing reform trajectory; deviation in residue limit harmonization or sudden solvent restriction tightening would shift competitive positioning toward vertically integrated players. Periodic stress-testing of base assumptions against regulatory arbitrage developments and fermentation technology cost curves is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Synephrine Market
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Smoked Yeast Market
Ingredients
Macleaya Cordata Extract Market
Ingredients
Medium-Chain Triglyceride (MCT) Fat Market
Ingredients
RTD/High Strength Premixes Market
Ingredients
Vegetable Powder Market
Ingredients
Specialty Fats and Oils Market
Ingredients
Multi-Grain Premixes Market
Ingredients
North America Gluten Free Flour Market
Ingredients
Palm Mid-Fraction Market
Ingredients
Europe Potato Protein Market
Ingredients
Clean Label Starch Market
Ingredients
Bromelain Ingredient Market
Ingredients
Corn Steep Liquor Market
Ingredients
Malted Barley Flour Market