
 Vegan Chocolate Confectionery Market | 2026-2036
Vegan Chocolate Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Chocolate Confectionery Market Intelligence
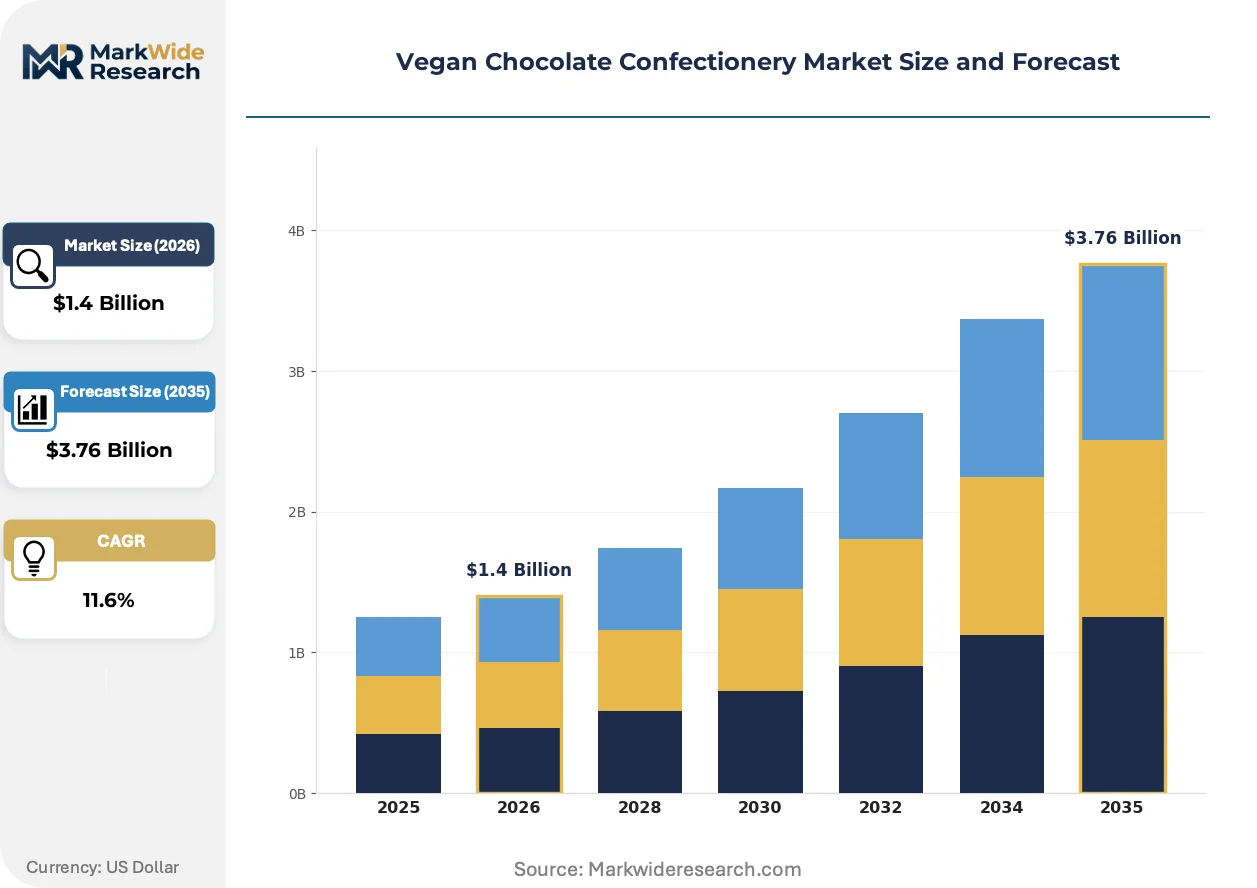
Fair Trade certification is collapsing the price and quality gap between conventional and vegan chocolate. This shift allows major confectioners to enter the segment without diluting brand equity. Chocoladefabriken Lindt and Spruengli leverages its global distribution network to introduce vegan lines to mainstream consumers. In contrast, Alter Eco differentiates through its deep commitment to regenerative agriculture and transparent sourcing models.
Vegan chocolate confectionery refers to chocolate products manufactured without any animal-derived ingredients, notably dairy milk solids, whey, or casein. These formulations substitute traditional dairy with plant-based milks from oats, almonds, or soy, combined with cocoa mass and cocoa butter. Dark chocolate remains the dominant product type due to its naturally dairy-free composition in high-cocoa-content versions. The milk chocolate segment is expanding rapidly as ingredient technology improves, with distribution moving from specialty health food stores into mainstream supermarkets.
Labeling accuracy is a key regulatory focus, governed by bodies like the US Food and Drug Administration (FDA) and the EU's Food Information to Consumers (FIC) regulation. These frameworks mandate clear allergen declarations and prevent misleading "dairy-free" claims if cross-contamination risks exist. The central challenge for manufacturers is securing consistent, price-stable supplies of high-quality plant-based milk powders and fats to support mainstream scaling.
Market Dynamics
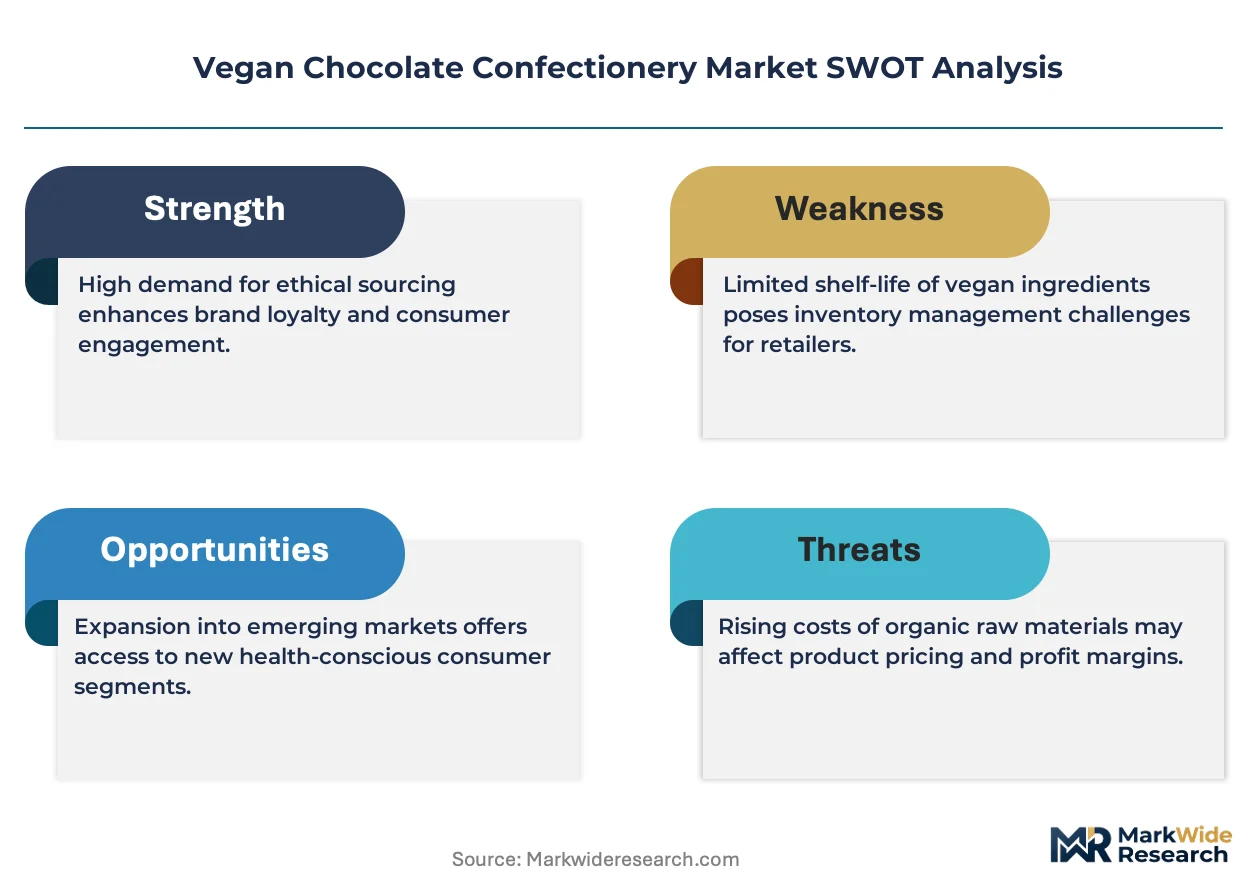
The central force shaping the vegan chocolate confectionery market is the rapid maturation of plant-based ingredient technology. Innovations in oat, soy, and almond milk powders are enabling manufacturers to replicate the sensory properties of dairy milk chocolate. This technological advance is collapsing the quality gap, allowing the category to move beyond its dark chocolate origins and compete directly in the mass-market milk chocolate segment.
Growth Catalysts
- Ingredient Innovation:Advances in plant-based milk powders, particularly oat and almond, are improving the taste and texture of vegan milk chocolate, expanding product development possibilities beyond naturally dairy-free dark chocolate.
- Ethical Consumerism:A rising consumer focus on animal welfare and environmental sustainability, supported by frameworks like Fair Trade certification, creates persistent demand for products with transparent and ethical supply chains.
- Mainstream Retail Expansion:The migration of vegan confectionery from specialty health food stores to dedicated plant-based sections in major supermarkets across Europe and North America significantly increases accessibility and consumer exposure.
Market Restraints
- Input Cost Volatility:Prices for key inputs such as high-quality, single-origin cocoa and specialized plant-based milk powders exhibit significant volatility, complicating cost structures and pressuring manufacturer margins.
- Cocoa Supply Concentration:The geographic concentration of cocoa farming in West African nations exposes the entire supply chain to risks from climate change, crop disease, and regional political instability.
- Sensory Parity Challenges:Achieving the exact creamy mouthfeel and flavor profile of traditional dairy milk chocolate remains a significant technical hurdle, with some vegan alternatives facing consumer resistance due to off-notes or textural differences.
Strategic Opportunities
- Functional Confectionery:The integration of functional ingredients such as probiotics, adaptogens, or plant-based proteins into vegan chocolate bars opens a new market segment at the intersection of indulgence and wellness.
- Geographic Expansion:Significant white space exists in Asia-Pacific markets like Japan and South Korea, where growing interest in plant-based diets presents an opportunity for market entry ahead of widespread competition.
- Food Service and Gifting:Developing premium vegan chocolate offerings for the corporate gifting, hospitality, and airline catering channels provides a new avenue for growth beyond traditional retail.
Industry Challenges
- Allergen Cross-Contamination:Manufacturers operating hybrid facilities face the operational challenge of preventing dairy cross-contamination to comply with stringent allergen labeling laws like the FDA's FALCPA, which requires significant investment in cleaning protocols.
- Scaling Novel Ingredients:Securing a consistent, price-stable, and large-volume supply of emerging ingredients like pea or fava bean protein isolates for chocolate applications remains a primary operational hurdle for scaling production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Chocolate Confectionery Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.76 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, White Chocolate, Milk Chocolate, Chocolate Bars Ingredient Source: Organic, Non-GMO, Fair Trade, Artisan Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Consumer Segment: Health Conscious, Ethical Consumers, Plant-Based Diet Advocates, Gourmet Shoppers |
| Companies Covered | Mondelez International, Endorfin Foods, Endangered Species Chocolate, Alter Eco, Goodio, Equal Exchange, Chocoladefabriken Lindt and Spruengli, No Whey Chocolate, Taza Chocolate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Chocolate Confectionery Market Strategic Shifts & Innovations
Product development is rapidly moving beyond simple dairy substitution toward creating functionally equivalent and even superior sensory experiences. This evolution is driven by advanced ingredient science and a deeper understanding of how plant-based proteins and fats interact with cocoa. The market is shifting from a niche alternative to a mainstream contender for consumer indulgence spending.
Advanced ingredient processing, particularly for oat and nut milk powders, now yields finer particles that create a creamier mouthfeel in finished products. Confectioners targeting the premium segment are adopting these next-generation ingredients to enhance their formulations. This technological refinement is displacing the reliance on earlier plant-based ingredients that often imparted undesirable gritty textures or off-flavors, thereby elevating the entire category's quality perception.
Regulatory frameworks are increasingly focused on supply chain transparency. The EU's Corporate Sustainability Reporting Directive (CSRD) compels large companies to disclose detailed environmental and social impacts, including those from their cocoa sourcing. This forces major confectioners to invest in traceable, certified supply chains to meet disclosure requirements. The milk chocolate segment is particularly affected, as it must now verify sustainability for both cocoa and plant-milk ingredients.
Consumer purchasing behavior is shifting from destination shopping at specialty health stores to routine inclusion in weekly grocery runs. This change is disrupting the channel strategy, forcing brands to compete for shelf space in the mainstream supermarket aisles of retailers in Germany, the UK, and the US. The rise of direct-to-consumer (DTC) e-commerce platforms also allows smaller, artisanal brands to bypass traditional retail gatekeepers and build a direct relationship with their customer base.
Vegan Chocolate Confectionery Market Segmentation
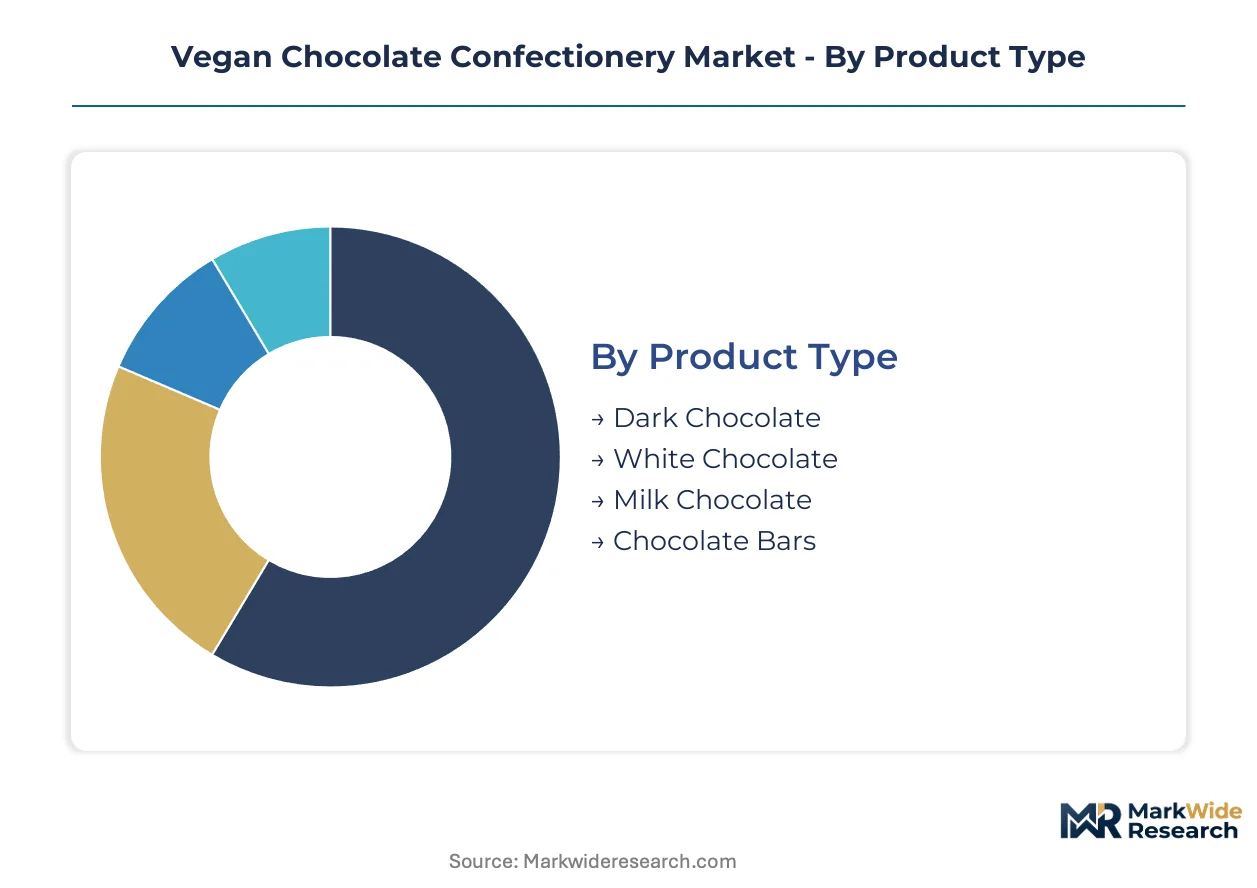
Understanding the distinct segments within the vegan chocolate confectionery market is crucial for targeted product development and effective market penetration strategies. Manufacturers tailor offerings to specific consumer demands, optimizing both ingredient selection and distribution channels. This granular view helps identify underserved niches and emerging consumer preferences.
Product Type:
The product type segmentation reveals distinct consumption patterns across different geographies, with some formats showing stronger domestic demand while others are gaining traction in export markets.
- Dark Chocolate:Dark chocolate, typically composed of cocoa solids, cocoa butter, and sugar, naturally avoids dairy and is often preferred for its intense flavor profile. Demand for high-cocoa dark vegan chocolate concentrates in European markets like Germany, driven by health-conscious consumers seeking antioxidant benefits.
- Milk Chocolate:Vegan milk chocolate utilizes plant-based milk powders, such as oat or almond, to replicate the creamy texture and familiar taste of traditional dairy versions. This segment experiences rapid expansion in North American supermarkets, as ingredient innovation allows for mainstream appeal without sensory compromise.
- White Chocolate:Vegan white chocolate relies on cocoa butter, sugar, and plant-based milk alternatives like rice or coconut, offering a sweet, dairy-free indulgence.
- Chocolate Bars:Chocolate bars, a versatile format, often serve as the primary vehicle for new vegan product innovations, ranging from plain to inclusion-filled varieties.
Dark Chocolate commands the established base. The steepest expansion runs through Milk Chocolate.
Ingredient Source:
Ingredient sourcing directly reflects consumer values, with specific certifications appealing to distinct ethical and quality-focused customer types.
- Fair Trade:Fair Trade certification ensures equitable compensation for cocoa farmers and adherence to social and environmental standards throughout the supply chain. Ethical consumers in the United Kingdom prioritize Fair Trade products, linking their purchasing decisions to transparent sourcing and producer welfare.
- Organic:Organic ingredients are cultivated without synthetic pesticides, herbicides, or genetically modified organisms, appealing to health-conscious and environmentally aware consumers. Demand for organic vegan chocolate is particularly strong in Germany, where a significant consumer base values clean label products.
- Non-GMO:Non-GMO certified ingredients guarantee products are free from genetically modified organisms, addressing consumer concerns about food safety and naturalness.
- Artisan:Artisan-sourced ingredients emphasize small-batch production, unique flavor profiles, and often direct relationships with growers, attracting gourmet shoppers.
The market exhibits a clear preference for Fair Trade among conscious buyers, while Artisan represents a premium niche.
Distribution Channel:
The choice of distribution channel significantly impacts product accessibility and brand positioning, ranging from broad market penetration to curated consumer experiences.
- Supermarkets:Supermarkets provide mass-market accessibility, offering vegan chocolate confectionery alongside conventional products in dedicated plant-based sections. Mainstream adoption in the United States and the UK is driven by consumer convenience and competitive pricing in large retail chains.
- Online Retail:Online retail platforms, including brand-specific DTC sites and e-commerce giants, offer extensive product selections and direct delivery to consumers. This channel facilitates market entry for smaller artisanal brands and serves consumers seeking niche or hard-to-find vegan chocolate varieties across Europe.
- Health Food Stores:Health food stores historically served as primary outlets for vegan chocolate, catering to early adopters and consumers focused on wellness attributes.
- Specialty Shops:Specialty shops provide curated selections, often focusing on premium, ethically sourced, or unique vegan chocolate offerings for discerning buyers.
While Health Food Stores remain a foundational route, Online Retail is rapidly redefining market reach.
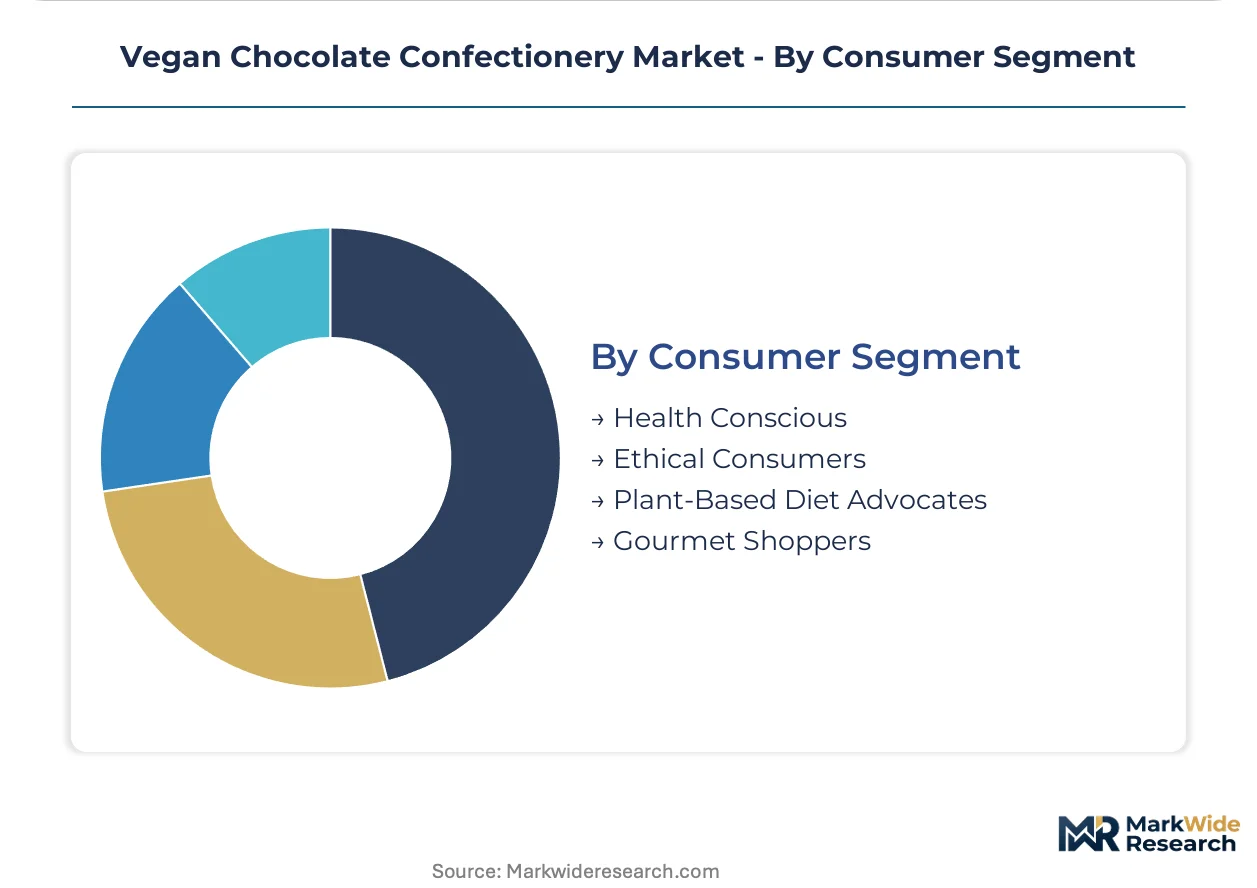
Consumer Segment:
Consumer segmentation highlights the diverse motivations driving purchasing decisions, from health and ethics to lifestyle choices and indulgent preferences.
- Plant-Based Diet Advocates:This segment comprises individuals who actively follow a vegan or plant-based diet, seeking chocolate products that align with their dietary restrictions and lifestyle. Their purchasing is driven by the fundamental need for dairy-free alternatives, particularly in countries with high plant-based adoption like Germany.
- Ethical Consumers:Ethical consumers prioritize products with transparent supply chains, sustainable practices, and fair labor conditions, often seeking certifications like Fair Trade. This group influences brand reputation and demand for responsibly sourced cocoa, particularly in markets with strong sustainability awareness such as the UK.
- Health Conscious:Health Conscious consumers seek vegan chocolate with lower sugar content, added functional ingredients, or specific nutritional benefits.
- Gourmet Shoppers:Gourmet Shoppers value premium ingredients, unique flavor combinations, and sophisticated packaging, viewing vegan chocolate as a luxury indulgence.
A significant portion of demand originates from Plant-Based Diet Advocates, with Gourmet Shoppers representing a high-value growth area.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU's Food Information to Consumers (FIC) regulation and the Corporate Sustainability Reporting Directive (CSRD) drive demand for transparently sourced vegan products across Europe. This regulatory push encourages manufacturers to expand vegan offerings in key markets. Ethical consumer preferences and ingredient innovation also shape regional market dynamics, fostering growth in plant-based confectionery.
Germany
Consumer demand for vegan chocolate confectionery in Germany is robust, driven by a significant plant-based consumer base and health-conscious preferences. The EU's Food Information to Consumers (FIC) regulation mandates clear labeling, supporting consumer trust in vegan claims. Berlin's vibrant food tech ecosystem fosters new product development and market penetration for innovative vegan chocolate brands.
United States
The United States market experiences strong demand for vegan chocolate due to mainstream retail expansion and continuous ingredient innovation. The US Food and Drug Administration (FDA) enforces stringent allergen labeling laws (FALCPA), requiring clear declarations for cross-contamination risks. California's dynamic health food industry serves as a hub for new vegan chocolate brands and product launches.
United Kingdom
Ethical consumerism and a strong preference for Fair Trade products fuel demand for vegan chocolate in the United Kingdom. The UK's Food Information Regulations, similar to EU FIC, ensure transparency in ingredient sourcing and allergen information. London's diverse food market supports a growing number of specialty vegan chocolate shops and premium offerings.
Japan
Growing interest in plant-based diets and healthy indulgence drives demand for vegan chocolate in Japan. Japan's Food Labeling Standards encourage clear ingredient declarations, aligning with consumer preferences for natural products. Tokyo's sophisticated premium confectionery sector introduces high-end vegan chocolate products targeting discerning consumers.
Canada
Rising plant-based food trends and a focus on ethical sourcing contribute to the expanding vegan chocolate market in Canada. Health Canada's food labeling requirements promote transparency regarding ingredients and nutritional information. Toronto's diverse food scene sees increasing availability of vegan chocolate in mainstream supermarkets and specialty stores.
Vegan Chocolate Confectionery Market Key Industry Players
Player mix skews toward a blend of established global confectioners and agile specialized vegan brands. This market structure supports both mass-market penetration and niche product innovation. Strategic archetypes include large-scale manufacturers leveraging existing distribution, ingredient-focused innovators, and sustainability-driven artisanal producers. Dominant competitive moves involve portfolio diversification into plant-based lines and strategic partnerships for ingredient sourcing.
At the scale-driven end, companies like Chocoladefabriken Lindt and Spruengli exemplify how established confectioners integrate vegan lines into global distribution networks. Alter Eco represents the sustainability-focused archetype, emphasizing regenerative agriculture and transparent sourcing models. Mondelez International occupies a position among large multinational food corporations expanding their plant-based offerings to capture new consumer segments.
| Leading Market Players |
|---|
| Mondelez International |
| Endorfin Foods |
| Endangered Species Chocolate |
| Alter Eco |
| Goodio |
| Equal Exchange |
| Chocoladefabriken Lindt and Spruengli |
| No Whey Chocolate |
| Taza Chocolate |
| Others |
Cost & Logistics Intelligence
Economies of scale in plant-based ingredient production are driving down costs for manufacturers, shaping both supply concentration and the achievable price floor for vegan chocolate confectionery. This allows for greater market penetration and competitive pricing.
Pricing Analysis
Certification level, particularly Fair Trade and Organic standards, creates the primary spread in vegan chocolate pricing. The dominant pricing model is per-unit transactional, with premium-mid-economy pricing differentiation based on ingredient quality and brand perception. Pricing pressure stems from input cost volatility for specialized plant-based milks and high-quality cocoa, impacting manufacturer margins. Ethical consumers and gourmet shoppers exhibit lower price sensitivity, prioritizing quality and sustainable sourcing, while mainstream plant-based diet advocates are more sensitive to price parity with conventional options.
Supply Chain Analysis
Elevated inbound logistics costs, particularly for intercontinental cocoa shipments, influence the overall supply chain efficiency for vegan chocolate. Geographic supply of cocoa concentrates in West African nations, while specialized plant-based milk ingredients source from diverse agricultural regions. Key raw material dependencies include high-quality cocoa mass, cocoa butter, and plant-based milk powders like oat or almond. A structural risk is single-source vulnerability for specific novel ingredients or specialized processing capabilities. Downstream distribution runs predominantly through mainstream supermarkets and rapidly expanding online retail platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegan chocolate market is at a platform-economics inflection, driven by ingredient technology advancements creating a broader ecosystem for plant-based indulgence. This shift allows for unprecedented product diversity and consumer reach.
For Market Incumbents: Compound investment in plant-based R&D to maintain sensory parity with traditional dairy chocolate, directly addressing the threat from agile specialized vegan brands. Diversify ingredient sourcing to mitigate input cost volatility for specialized milk powders. Leverage existing global distribution networks to introduce new vegan lines, securing mainstream shelf space. Invest in comprehensive supply chain traceability to meet evolving regulatory demands like the EU's CSRD.
For New Entrants and Emerging Players: Service-layer gaps exist in functional confectionery, where incumbents under-serve consumers seeking health benefits alongside indulgence. Target Asia-Pacific markets, particularly Japan and South Korea, which show growing interest in plant-based diets but have less established vegan chocolate offerings. A direct-to-consumer e-commerce model provides a cost-effective go-to-market angle, fostering direct customer relationships and brand loyalty without traditional retail gatekeepers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized vegan brands with strong brand equity and transparent sourcing models, appealing to ethical consumers. Long-term viability hinges on sustained ingredient innovation and expanding mainstream consumer adoption of plant-based alternatives over the next decade. Target acquisition archetypes include ingredient-focused innovators and artisanal producers with unique formulations or strong regional presence. A key signal to watch is the consistent expansion of dedicated plant-based sections within major supermarket chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Plant-Based Lines | Established confectioners like Lindt expand consumer reach by offering dairy-free alternatives to mainstream buyers. |
| Investment in Ingredient Technology R&D | Advances in oat and almond milk powders enhance the sensory experience of vegan milk chocolate, improving market acceptance. |
| Enhanced Supply Chain Traceability Programs | Compliance with regulations like the EU CSRD ensures ethical sourcing and builds consumer trust in cocoa and plant-milk ingredients. |
| Expansion of Direct-to-Consumer E-commerce | Artisanal brands gain market access and build direct relationships with niche consumer segments, bypassing traditional retail. |
| Integration of Functional Ingredients | Developing vegan chocolate with probiotics or adaptogens taps into the growing consumer demand for wellness-oriented indulgence. |
Research Approach
A standing panel of confectioners (R&D, procurement), ingredient suppliers (plant-based milk, cocoa), retailers (category managers), and food tech innovators provided ongoing calibration for primary insights. This involved extensive interviews with industry stakeholders, validated against secondary data from regulatory filings, Fair Trade reports, and industry association publications. The approach utilized both bottom-up and top-down triangulation to ensure comprehensive market understanding.
Model outputs underwent rigorous consistency checks against external benchmarks across the analysis window. The analytical framework segmented the market by product type (dark, milk, white), ingredient source (Fair Trade, Organic), distribution channel (supermarkets, online), and consumer segment (plant-based advocates, ethical consumers). Compound annual growth rates were derived from historical trends, projected ingredient availability, and anticipated shifts in consumer preferences. Key industry-specific forecast inputs included plant-based milk ingredient costs and Fair Trade cocoa supply dynamics.
Underlying assumptions cover stable regulatory environments and consistent consumer shifts towards plant-based diets, with deviation risk concentrated in unforeseen raw material price shocks or rapid technological obsolescence. Forecasts reflect these assumptions, acknowledging that significant disruptions could alter market trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
Gummy Market
Confectionery
Middle-East and Africa Compound Chocolate Market
Confectionery
Vegan Candies Market
Confectionery
Mints Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
Caramel Market
Confectionery
Citrus Gummies Market
Confectionery
Chocolate Spread Market
Confectionery
Global Mochi Market
Confectionery
Chocolate Couverture Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Jellies and Gummies Market
Confectionery
Ice Cream Coating Market
Confectionery
South America Confectionery Market
Confectionery
Boiled-Cooked Icing Market