
 Collagen Casings Market | 2026-2036
Collagen Casings Market Size, Share, and Industry Trends Forecast 2026-2036
Collagen Casings Market Intelligence
Direct supply relationships between casing manufacturers and meat packing plants is reconfiguring procurement patterns across the Collagen Casings Market. Viscofan SA leverages its integrated extrusion and shirring capabilities to sustain volume leadership in European sausage applications. Devro plc anchors Asia-Pacific expansion through dedicated collagen film production in China. Nitta Gelatin Inc. differentiates via specialized edible-grade formulations for Japanese processed meat exporters.
Collagen casings consist of regenerated collagen fibers derived from bovine or porcine corium layers, extruded into uniform tubes with calibrated diameters ranging from 15 mm to 50 mm and moisture content typically controlled between 12% and 18% for optimal machinability on high-speed stuffing equipment. These engineered films serve as edible or peelable barriers that standardize portion weights, accelerate smoke permeation, and eliminate microbial variation inherent in natural gut. Edible collagen dominates volume flows into sausage applications where bite texture and snap retention determine consumer acceptance. Fibrous collagen commands premium positioning in large-diameter salami and bologna formats where structural integrity during extended aging cycles creates margin pools for specialized producers. Reconstituted collagen occupies a growing niche among pet food manufacturers seeking uniform cylindrical shapes for dried meat snacks.
USDA food safety standards and FDA food-contact substance notifications govern collagen extraction purity and cross-species traceability requirements in the United States, while REACH and EFSA migration limits constrain plasticizer selection and additive packages across European conversion facilities. China's SAMR national food safety standards and GB specifications for collagen-based food additives create parallel compliance tracks for exporters serving domestic processors. Stakeholders must monitor evolving distinctions between edible and non-edible collagen grades as regulatory bodies tighten species-origin documentation and allergen labeling protocols.
Market Dynamics
Direct supply relationships between casing manufacturers and meat packing plants are reconfiguring procurement patterns across the Collagen Casings Market, compressing distributor margins and forcing extrusion specialists to build captive logistics networks.
Growth Catalysts
- EU F-Gas Regulation:REACH compliance frameworks are tightening material specifications for food-contact substances, accelerating conversion from plastic alternatives to collagen-based barriers in German sausage manufacturing corridors.
- Processed meat automation:High-speed stuffing equipment demands calibrated moisture content between 12% and 18%, pulling volume toward engineered collagen films that natural gut cannot match.
- Species-origin traceability mandates:USDA and EFSA documentation requirements are eliminating small-batch natural casing suppliers, consolidating demand among collagen producers with integrated bovine and porcine corium supply chains.
Market Restraints
- Bovine spongiform encephalopathy protocols:Cross-species collagen extraction faces persistent regulatory friction in markets with strict ruminant material controls, limiting raw material sourcing flexibility.
- Corium layer concentration:Premium-grade collagen feedstock concentrates in Brazilian and Argentine hide processing clusters, exposing converters to South American supply disruptions and currency volatility.
- Cellulose casing substitution:Peelable fibrous alternatives from regenerated cellulose maintain cost advantages in large-diameter applications, capping collagen penetration in bologna and salami formats.
Strategic Opportunities
- Chinese domestic processors:SAMR national food safety standards and GB specifications for collagen-based food additives create parallel compliance tracks for exporters building localized production.
- Pet food cylindrical shaping:Reconstituted collagen occupies a growing niche among dried meat snack manufacturers seeking uniform product geometry absent in extruded alternatives.
- Edible-grade certification convergence:Japanese processed meat exporters are demanding specialized formulations that bridge EFSA migration limits and PMDA pharmaceutical-grade purity standards.
Industry Challenges
- Extrusion technician scarcity:Regenerated collagen fiber calibration requires specialized expertise in moisture control and diameter uniformity that vocational programs have not scaled to match equipment deployment.
- Dual certification timelines:Simultaneous FDA food-contact substance notifications and REACH dossier preparation extend product launch cycles by 18-24 months for multi-territory suppliers.
- Legacy stuffing line retrofit costs:European charcuterie producers converting from natural gut must reconfigure shirring and clipping mechanisms, demanding capital outlays that mid-tier processors defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collagen Casings Market |
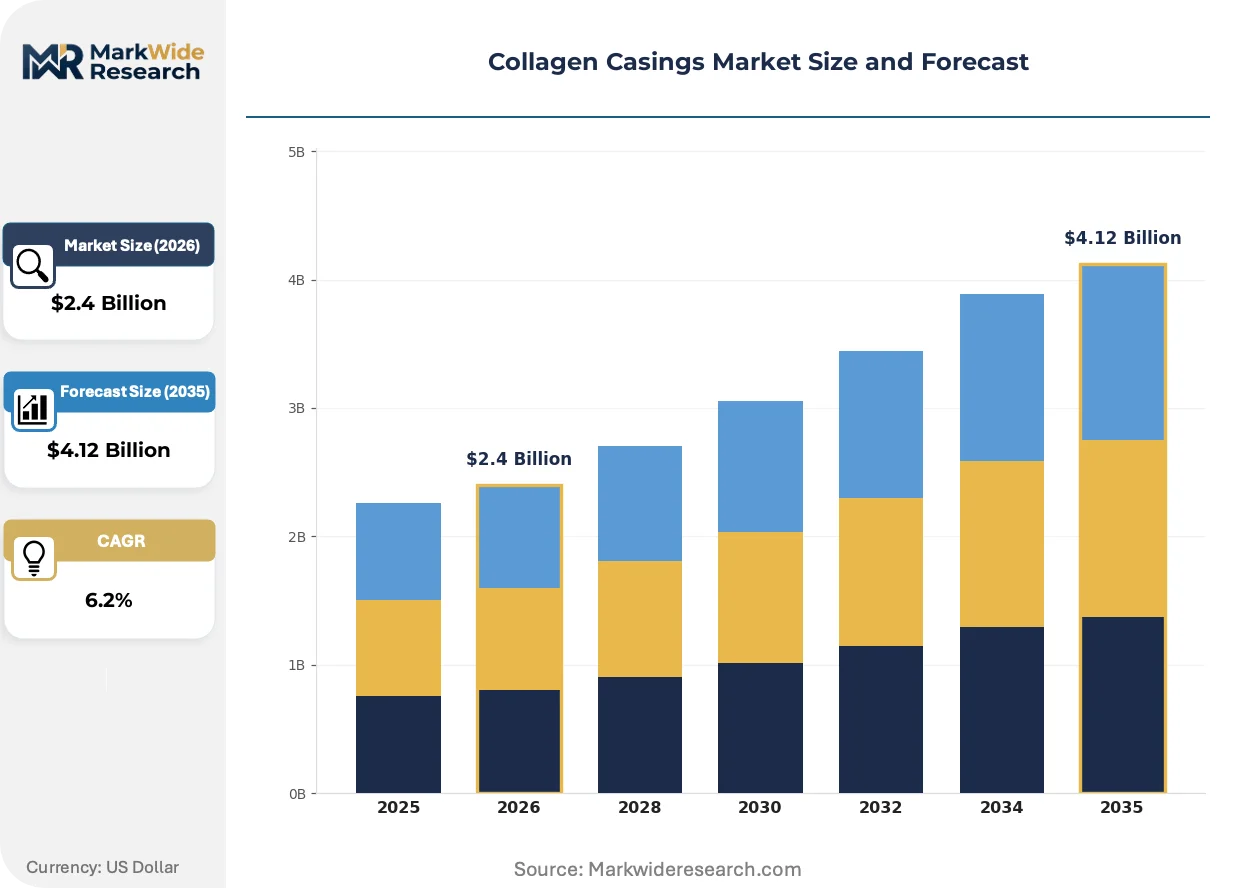
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Collagen, Edible Collagen, Plasticized Collagen, Fibrous Collagen, Reconstituted Collagen Application: Sausages, Meat Snacks, Pet Food, Processed Meat, Cheese Stick, Frozen Food End Use Industry: Food Processing Units, Meat Packing Plants, Pet Food Manufacturers, Cheese Makers, Frozen Food Producers Packaging Type: Tubes, Sheets, Fibers, Preformed Casings, Coated Casings |
| Companies Covered | Fibran Group, Nippi Inc., Viscofan SA, Fabios SA, SARIA SE & Co. KG, Devro plc, Nitta Gelatin Inc., LEM Products Inc., Shenguan Holdings (Group) Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collagen Casings Market Strategic Shifts & Innovations
Extrusion precision and regulatory harmonization are compressing the competitive set, rewarding specialists with integrated corium-to-film capabilities while marginalizing commodity distributors.
Continuous moisture-control extrusion systems are rendering obsolete batch-processed collagen with variable diameter tolerances. German sausage manufacturers with automated high-speed lines have adopted these systems at replacement cycle pace. The technology is rendering obsolete regional converters lacking real-time fiber alignment feedback.
REACH Annex XVII restrictions on plasticizers in food-contact materials are tightening additive package specifications across European conversion facilities. Industrial consequence includes forced reformulation of traditional collagen softening agents toward bio-based alternatives. Edible-grade collagen producers serving German charcuterie corridors face the steepest compliance costs and are vertically integrating into hide processing to control input purity.
Direct contracting between meat packing plants and extrusion specialists is displacing traditional distributor networks in procurement channels. The distributor segment serving mid-tier European processors is consolidating or exiting as volume concentrates with manufacturers offering integrated shirring and logistics. This pattern is most visible in Germany's sausage manufacturing belt where Viscofan SA and Devro plc have established captive supply agreements with major packing groups.
Collagen Casings Market Segmentation
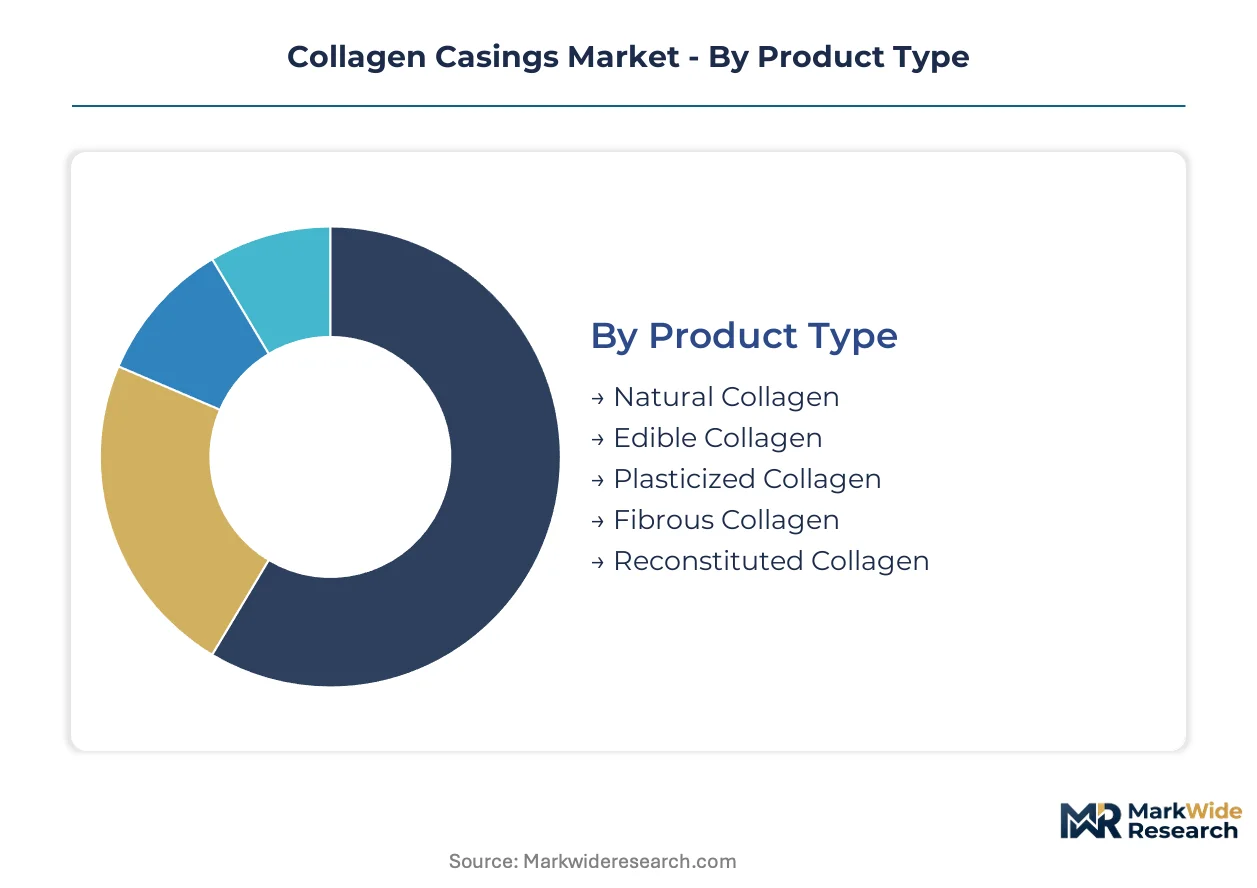
Segmentation in the Collagen Casings Market determines procurement complexity and technical service requirements. Product-grade specifications dictate extrusion calibration protocols, while application-specific moisture tolerances shape after-sales support intensity across customer tiers.
Product Type:
After-sales service intensity varies sharply across collagen grades, with edible and fibrous variants demanding continuous technical calibration support that natural alternatives rarely require.
- Edible Collagen:Regenerated bovine or porcine corium fibers extruded into uniform tubes with 12-18% moisture content for direct consumption. German sausage manufacturers in the charcuterie corridor are converting from natural gut to edible collagen as automated high-speed stuffing equipment demands diameter tolerances natural casings cannot match.
- Fibrous Collagen:Reinforced collagen matrices laminated onto paper or textile backings for large-diameter applications requiring structural rigidity during extended aging. Demand concentrates in Italian and Spanish salami producers where 40-50mm diameter formats and multi-month curing cycles create premium positioning for specialized suppliers.
- Natural Collagen:Untreated animal tissue casings requiring minimal processing but exhibiting high diameter variability.
- Plasticized Collagen:Softened formulations with glycerin or sorbitol additives for enhanced pliability in manual stuffing operations.
- Reconstituted Collagen:Ground and reformed collagen matrices for non-food applications requiring geometric precision.
By volume, edible collagen leads. By growth pace, fibrous collagen is climbing the fastest as aged meat formats expand.
Application:
Application segmentation tracks equipment compatibility requirements and smoke permeation specifications that determine formulation chemistry.
- Sausages:The dominant application spanning fresh, smoked, and dried formats with calibrated snap retention requirements. European processors in Poland and the Netherlands are driving volume as traditional butcher operations consolidate into automated packing plants.
- Processed Meat:Bologna, mortadella, and luncheon meat formats requiring uniform sliceability and extended shelf stability. North American deli meat producers favor fibrous collagen for large-diameter logs where structural integrity during thermal processing determines yield rates.
- Meat Snacks:Pepperoni sticks and jerky formats requiring controlled moisture barrier properties.
- Pet Food:Dried meat snacks and treat formats where cylindrical uniformity supports automated packaging.
- Cheese Stick:Barrier applications for smoked or processed cheese formats.
- Frozen Food:Ready-to-cook meat products requiring freezer-stable flexibility.
Sausages generate the highest absolute volume. Processed meat applications are expanding most quickly as portion-controlled retail formats proliferate.
End Use Industry:
Customer-type segmentation reveals diverging procurement patterns between integrated packing operations and specialized processors.
- Meat Packing Plants:High-volume automated facilities demanding just-in-time delivery and diameter consistency across million-unit production runs. Direct supply agreements with extrusion specialists are displacing distributor networks in Germany and the United States.
- Food Processing Units:Mid-tier sausage and processed meat manufacturers with mixed manual-automated lines. These operators face the steepest retrofit costs when converting from natural gut, deferring capital outlays and sustaining demand for semi-automated compatible casing grades.
- Pet Food Manufacturers:Niche demand for geometric precision in dried treat formats.
- Cheese Makers:Limited specialty demand for smoked cheese barrier applications.
- Frozen Food Producers:Emerging demand for freezer-stable collagen alternatives to synthetic casings.
Meat packing plants command the largest volume share. Food processing units are gaining share fastest as regional consolidation accelerates.
Packaging Type:
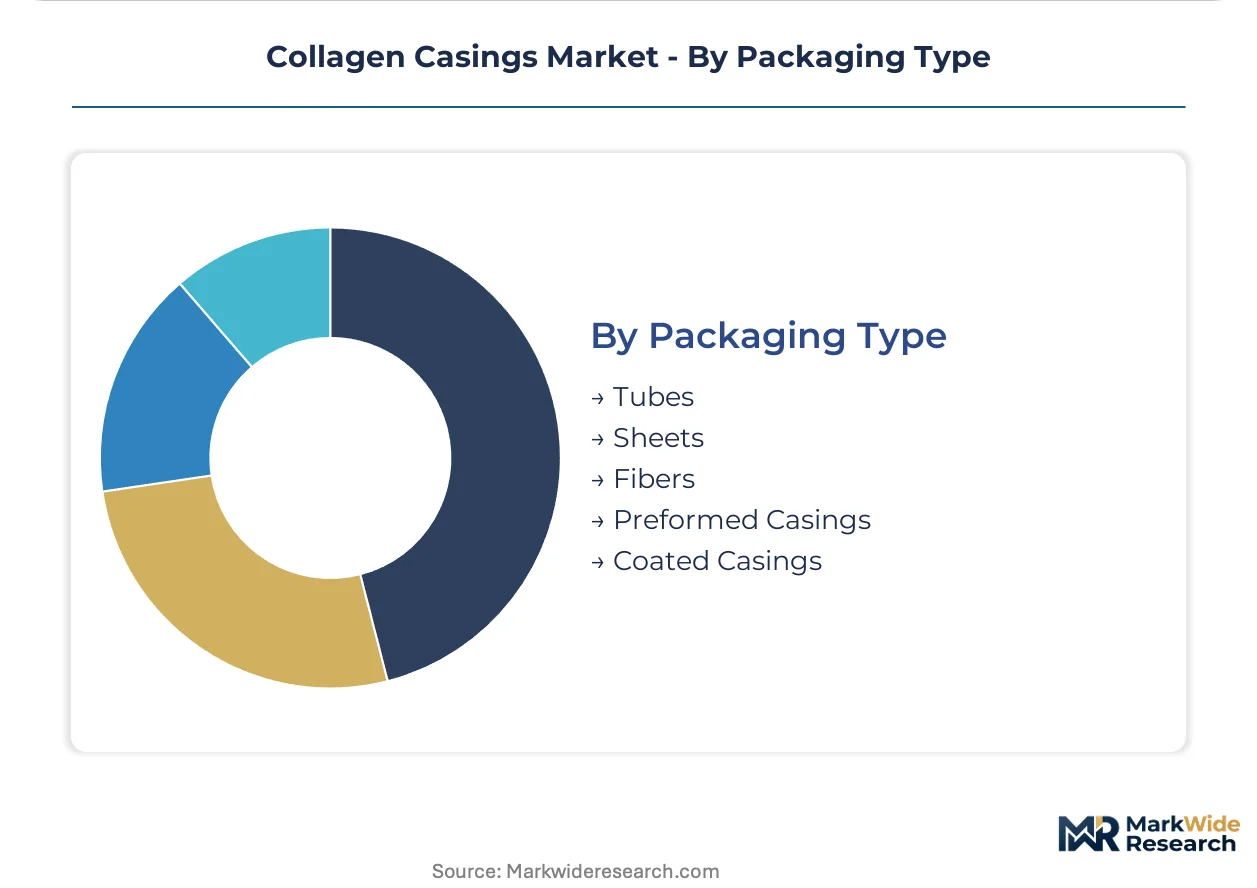
Physical format segmentation determines logistics configurations and shirring equipment compatibility across customer sites.
- Preformed Casings:Factory-shirred tubes ready for direct mounting onto stuffing horns, eliminating on-site preparation labor. Major European packing groups have standardized on preformed formats to maximize line utilization rates and minimize changeover downtime.
- Tubes:Unshirred continuous lengths requiring manual or semi-automated preparation. Smaller processors in Eastern Europe continue purchasing tubes to avoid capital investment in high-speed shirring equipment.
- Sheets:Flat collagen films for manual wrapping or specialty applications.
- Fibers:Loose regenerated collagen for reconstitution or non-standard formats.
- Coated Casings:Surface-treated variants with smoke or colorant pre-applications.
Tubes still lead by volume due to legacy equipment bases. Preformed casings are expanding most quickly as automation investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European collagen distribution, handling containerized raw corium imports from Brazilian hide processors and finished casing exports to sausage manufacturers across the continent.
Germany
Automated high-speed stuffing equipment conversion drives edible collagen procurement in Bavaria and Lower Saxony. ECHA REACH compliance mandates plasticizer reformulation for food-contact materials. The Nuremberg-Regensburg sausage manufacturing corridor witnesses packing plants establishing direct supply agreements with extrusion specialists to bypass distributor networks.
United States
USDA food safety standards and FDA food-contact substance notifications govern bovine collagen extraction purity for domestic processed meat producers. Cross-species traceability requirements eliminate small-batch natural casing suppliers. Wisconsin and Illinois meat packing clusters consolidate procurement with integrated corium-to-film manufacturers to secure million-unit production runs.
China
SAMR national food safety standards and GB specifications for collagen-based food additives create compliance tracks for domestic processors and exporters. Yangtze River Delta meat processing automation accelerates demand for preformed shirred casings. Shanghai-area packing groups retrofit legacy lines to accommodate calibrated moisture-content films from local extrusion facilities.
Japan
PMDA pharmaceutical-grade purity standards converge with EFSA migration limits for processed meat exporters seeking dual-market certification. METI industrial standards shape equipment compatibility specifications. Osaka-Kobe manufacturing clusters demand specialized edible-grade formulations that bridge European and Japanese regulatory frameworks.
Brazil
Premium-grade collagen feedstock concentrates in São Paulo state hide processing clusters serving global converter demand. ANVISA sanitary surveillance standards govern bovine material traceability for export certification. Campinas and Sorocaba industrial zones face currency volatility exposure as corium layer supply concentrates among regional tannery cooperatives.
Collagen Casings Market Key Industry Players
On the supply side, the industry is consolidating around integrated extrusion specialists with captive corium sourcing and shirring capabilities. Mid-tier regional converters lacking real-time fiber alignment technology face displacement as automated packing plants demand diameter tolerances batch processes cannot achieve. Three archetypes dominate: integrated multinationals with hide-to-film operations, regional extrusion specialists serving single geographies, and reconstituted collagen niche producers targeting pet food geometry requirements. Capacity expansion and backward integration into hide processing represent the dominant competitive moves as producers seek input purity control.
Among European-integrated specialists, Viscofan SA and Devro plc exemplify the archetype of extrusion-dominant manufacturers with established logistics networks. Viscofan occupies a position representing Spanish-originated integrated capabilities, while Devro anchors British-structured multinational presence. Nitta Gelatin Inc. represents Japanese-formulated specialization bridging pharmaceutical-grade standards with food-contact applications. These three entities collectively illustrate how geographic regulatory convergence and equipment compatibility demands reshape competitive positioning without requiring specific strategic action claims.
| Leading Market Players |
|---|
| Fibran Group |
| Nippi Inc. |
| Viscofan SA |
| Fabios SA |
| SARIA SE & Co. KG |
| Devro plc |
| Nitta Gelatin Inc. |
| LEM Products Inc. |
| Shenguan Holdings (Group) Limited |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese extrusion facilities is compressing export pricing for standard-grade edible collagen while tightening margins for European converters serving automated German packing lines. This utilization divergence rewards integrated producers with captive corium sourcing and punishes toll manufacturers exposed to spot hide markets.
Pricing Analysis
Volume-discount tiering structures separate million-unit meat packing contracts from mid-tier processor spot purchases by 15-25% at equivalent specification levels. Three-tier pricing stratification across pharmaceutical-grade, food-grade, and industrial-grade certifications determines contract eligibility for Japanese exporters bridging PMDA and EFSA standards. Pricing pressure intensifies in fibrous collagen segments as cellulose casing substitutes maintain cost advantages in large-diameter salami applications. Mid-tier European processors with mixed manual-automated lines exhibit highest price sensitivity, while integrated German packing groups prioritize diameter consistency over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Brazilian and Argentine hide processing cooperatives supplying corium layers to global extrusion specialists. Raw material sourcing draws from South American bovine hide clusters, Southeast Asian porcine processing facilities, and European tannery byproduct streams. Single-source vulnerability concentrates in São Paulo state hide processing zones exposed to currency volatility and ANVISA export certification delays. Distribution runs through direct supply agreements between extrusion specialists and meat packing plants, displacing traditional distributor networks in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service attach rates for extrusion calibration and moisture-control optimization are expanding faster than base casing volumes as automated packing lines demand continuous diameter monitoring. This service layer recurrence transforms procurement relationships from transactional commodity supply toward integrated production partnerships.
For Market Incumbents: Insulate margin pools by backward integration into hide processing clusters in Brazil and Argentina to secure corium layer supply purity. Captive sourcing of bovine and porcine feedstock eliminates cross-species traceability documentation bottlenecks threatening million-unit contracts. Capacity addition in Yangtze River Delta extrusion facilities addresses Chinese domestic processor automation demand while reducing freight exposure to European REACH compliance costs. For New Entrants and Emerging Players: Build out reconstituted collagen production capabilities targeting pet food manufacturers seeking cylindrical geometry precision for dried meat snacks. This segment exhibits lowest incumbent concentration and tolerates higher unit pricing due to premium positioning in treat categories. Technical calibration services bundled with casing supply create differentiation against commodity distributors exiting the market. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among extrusion specialists offering integrated shirring and logistics services under multi-year direct supply agreements. Long-term viability favors integrated hide-to-film operators with real-time fiber alignment technology and EFSA-FDA dual certification capabilities. Acquisition targets should demonstrate established relationships with automated packing groups in Germany or the United States. The signal to watch is stuffing equipment replacement cycle acceleration indicating demand inflection for preformed shirred casings.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hide Processing | Captive corium sourcing from Brazilian tannery clusters secures input purity for EFSA compliance. |
| Continuous Moisture-Control Extrusion Deployment | Real-time fiber alignment technology eliminates diameter tolerance failures on high-speed German lines. |
| Dual Certification Investment | Simultaneous FDA and REACH dossier preparation accelerates multi-territory product launches. |
| Direct Supply Agreement Expansion | Captive logistics networks with major packing groups displace distributor intermediaries in procurement channels. |
| Technical Service Attach Development | On-site extrusion calibration contracts transform transactional supply into recurring revenue relationships. |
Research Approach
A standing panel of extrusion operations managers, meat packing procurement directors, hide processing cooperative executives, and EFSA regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with stuffing equipment manufacturers and technical service technicians supplemented field intelligence on automation compatibility requirements. Secondary validation drew from ANVISA export certification databases, SAMR national food safety standard filings, USDA FSIS establishment directories, and customs trade records for collagen-based food additive imports. Bottom-up volume modeling from individual extrusion facility capacities triangulated against top-down demand estimates from processed meat production statistics.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated automation adoption paths throughout the forecast period. Segmentation dimensions modeled include product grade tier, application equipment compatibility, end-use industry procurement scale, packaging format shirring requirements, and regional regulatory cluster alignment. CAGRs derived from equipment replacement cycle analysis and packing plant automation investment intentions. Industry-specific forecast inputs incorporated stuffing line retrofit capital expenditure plans and REACH Annex XVII plasticizer restriction implementation timelines.
Sensitivities concentrate around Brazilian real currency volatility affecting corium layer input costs, cellulose casing substitution rates in large-diameter applications, and extrusion technician training pipeline capacity constraints. Forecasts reflect documented assumptions regarding automation adoption curves and regulatory harmonization progress across FDA and EFSA frameworks. Quarterly review of hide processing cluster output volumes, stuffing equipment order backlogs, and dual-certification application filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Eucalyptus Oil Market
Ingredients
Edible Oils and Fats Market
Ingredients
Indonesia Edible Oil Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
Liquid Egg Market
Ingredients
Non-GMO Oil Market
Ingredients
Asia-Pacific Carrageenan Market
Ingredients
Pine Needle Oil Market
Ingredients
Drum to Hopper Blends Premix Market
Ingredients
US Choline Bitartrate Market
Ingredients
Wheat Starch Market
Ingredients
Wheat Gluten Market
Ingredients
South America Vegetable Oil Market
Ingredients
Lentils Flour Market
Ingredients
Phytogenic Market
Ingredients
Grape Seed Extracts Market