
 North America Malt Ingredients Market | 2026-2036
North America Malt Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Malt Ingredients Market Analytics
Craft brewers and small-batch distillers is reorganizing procurement priorities across the North America malt ingredients supply base. Rahr Corporation leverages its integrated malting and distribution footprint across the US Midwest to serve regional brewpubs efficiently. Muntons PLC anchors its position through specialized roasted and caramel malt portfolios that command premium placement. Briess Malt & Ingredients Co. differentiates via technical brewing support and custom malt specification services for emerging craft accounts.
Malt ingredients encompass germinated cereal grains—primarily barley—dried in kilns to develop enzymatic activity, color, and flavor compounds measured by diastatic power and Lovibond ratings, serving as the fermentable backbone for beer, spirits, and baked goods. Specialty malts command disproportionate margin pools as craft producers chase distinct flavor profiles beyond base malt commoditization. Powder and extract forms are gaining formulation share in food and confectionery applications where consistent solubility and batch control outweigh traditional grain handling economics.
The FDA governs food-grade malt labeling and allergen declarations while the Alcohol and Tobacco Tax and Trade Bureau enforces brewing material standards that directly shape malt supplier qualification protocols. State-level alcohol manufacturing permits in Texas, Colorado, and Michigan create localized compliance layers that favor regionally certified malt houses. Stakeholders must monitor how carbon accounting requirements and water-use disclosures under evolving EPA frameworks reshape sourcing decisions for water-intensive malting operations.
Market Dynamics
Specialty malt procurement is reorganizing around flavor differentiation mandates as craft brewers and small-batch distillers abandon commodity base malt sourcing. This structural pull concentrates purchasing power among regional malting clusters capable of delivering custom roasted and caramel specifications.
Growth Catalysts
- TTB Labeling Standards:The Alcohol and Tobacco Tax and Trade Bureau mandates origin disclosure for brewing materials, compelling distillers to document malt provenance and favor domestic certified suppliers.
- Barley Cluster Proximity:Production concentrates in the US Great Plains and Canadian Prairie provinces where malting facilities sit adjacent to barley cultivation, compressing logistics costs and moisture-loss risks.
- Craft Flavor Arms Race:Small-batch brewers chase distinct diastatic power and Lovibond ratings through specialty roasted malts that command premium placement in limited-release portfolios.
Market Restraints
- Input Cost Volatility:Barley prices fluctuate with drought cycles across Montana and Alberta, squeezing malting margins when irrigation restrictions tighten.
- Supply Concentration Risk:Regional malting capacity clusters near rail terminals in Minnesota and Saskatchewan, creating single-point vulnerability during harvest logistics crunches.
- Substitution Pressure:Adjunct grains and enzyme additives threaten base malt volumes in cost-optimized lager production.
Strategic Opportunities
- Underpenetrated Extract Formulation:Food and confectionery manufacturers in Mexico represent untapped demand for malt powder with consistent solubility profiles.
- Carbon Accounting Tailwinds:EPA water-use disclosure frameworks favor malters with verified low-intensity kilning operations, creating qualification advantages.
- Technical Service Bundling:Custom malt specification support paired with brewing consultancy opens new revenue streams beyond commodity grain sales.
Industry Challenges
- Master Maltster Talent Scarcity:Kiln operation and germination control expertise is aging out faster than apprenticeship pipelines replenish.
- Certification Timeline Compression:FDA allergen declaration updates and state-level alcohol manufacturing permits in Texas and Colorado impose overlapping compliance calendars.
- Capex Intensity for Roasting Lines:Specialty caramel and chocolate malt production requires dedicated drum equipment with long depreciation horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Malt Ingredients Market |
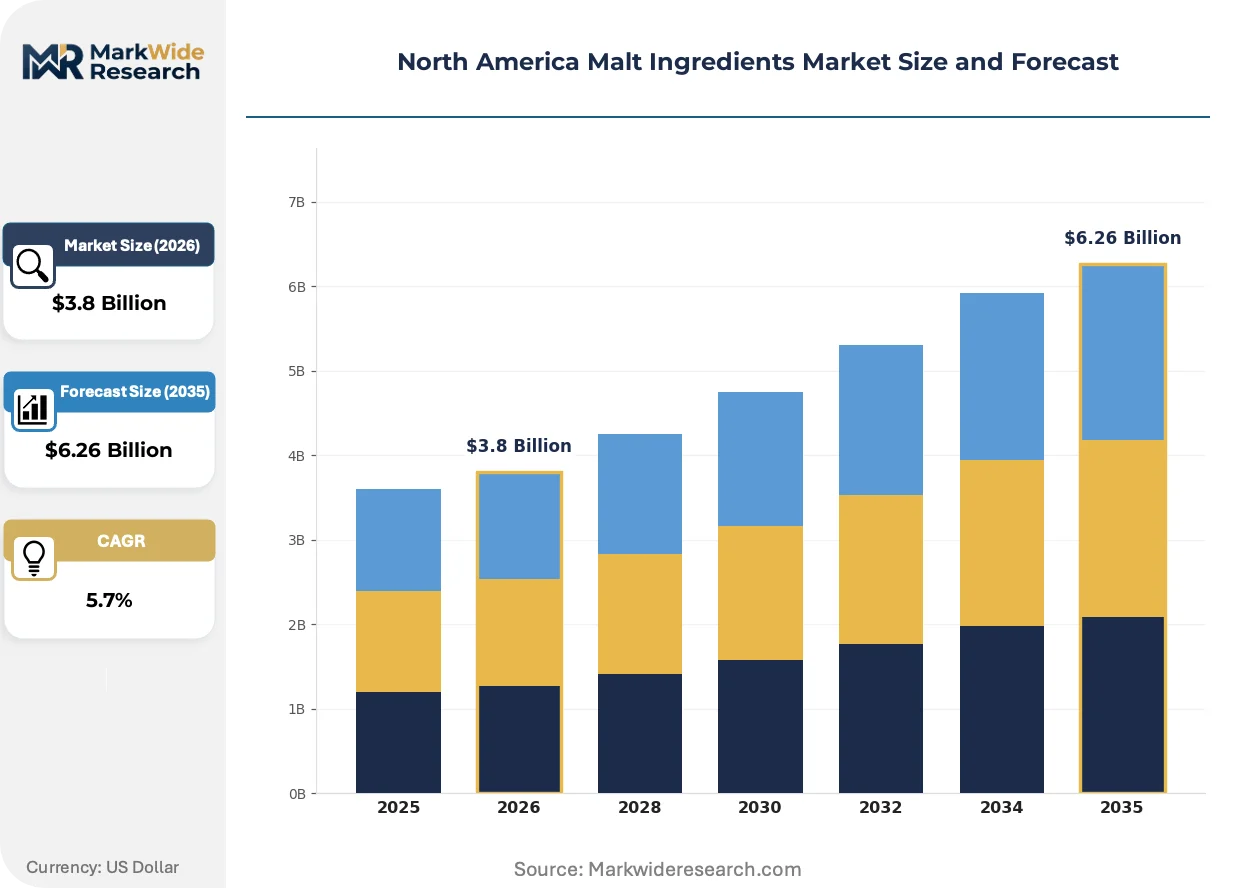
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Malted Barley, Malted Wheat, Malted Rye, Specialty Malts End Use Industry: Beverage, Food, Animal Feed, Confectionery Application: Brewing, Distilling, Baking, Flavoring Form: Grains, Powder, Extract, Syrup |
| Companies Covered | Axereal, GrainCorp Limited, Rahr Corporation, Simpsons Malt Limited, Muntons PLC, Malteurop Malting Company, Group Soufflet, InVivo Group, Briess Malt & Ingredients Co., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Malt Ingredients Market Evolving Landscape
Malting technology and procurement architecture are diverging sharply between commodity efficiency plays and craft customization capabilities. This bifurcation rewards suppliers who can operate across both modes without cross-contamination of production runs.
Precision kilning control systems leveraging IoT moisture sensors and automated airflow modulation are bifurcating the installed base of malting equipment. Large-scale brewers adopt these systems for batch consistency and energy recovery, while craft malters deploy them for rapid roast-profile experimentation. The technology is compressing the innovation cycle for specialty malt development from seasonal to monthly release cadences.
EPA frameworks governing water-use disclosures and carbon intensity reporting are tightening qualification protocols for malting facility permits. Facilities in water-stressed watersheds face heightened scrutiny of steeping and germination water recycling systems. Canadian Prairie malters with closed-loop infrastructure are capturing preferential supplier status with sustainability-focused distillers.
Direct contracting between craft brewers and single-origin barley growers is displacing traditional commodity grain brokerage channels. This relationship model transfers agronomic risk to brewers who specify varietal and terroir parameters. The pattern concentrates in Michigan and Colorado where estate brewery concepts align with local barley breeding programs.
North America Malt Ingredients Market Segmentation
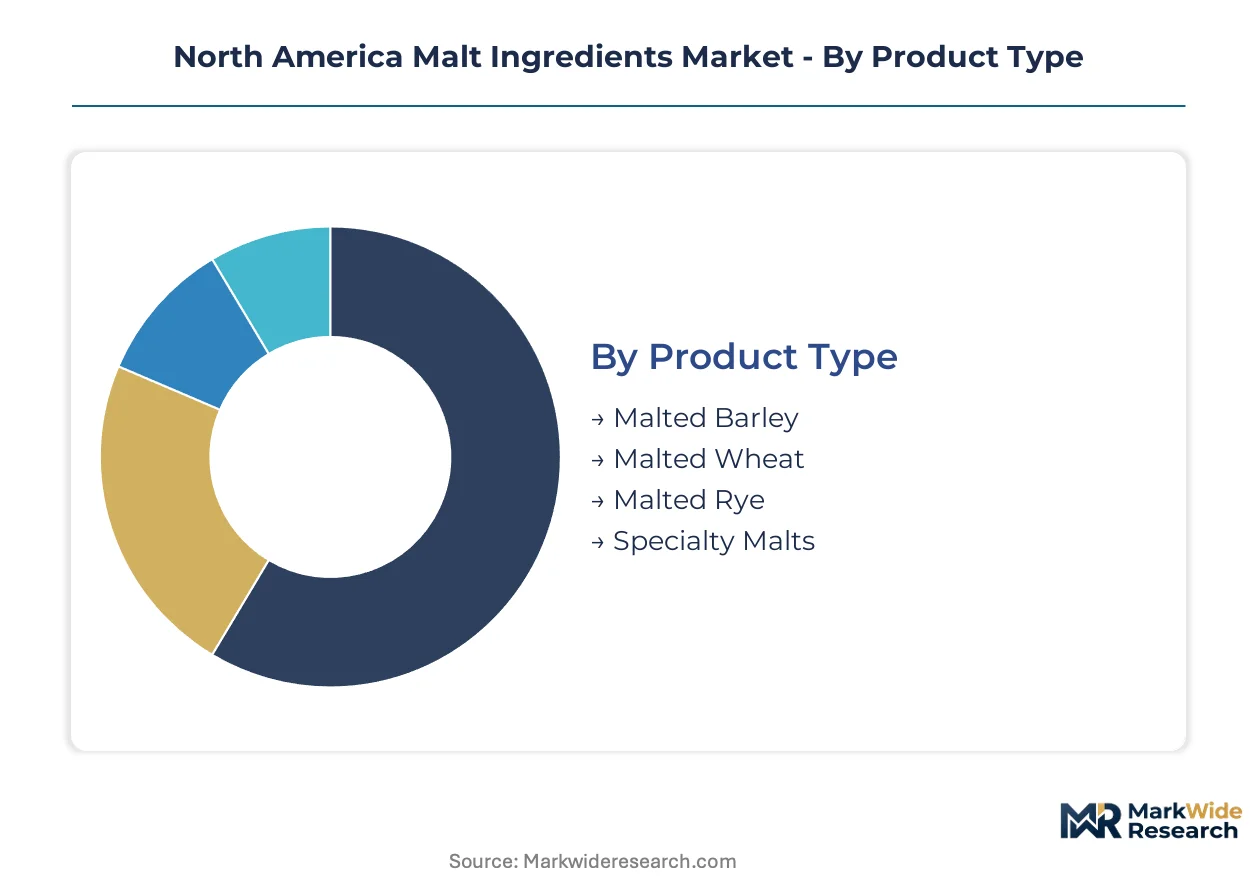
Malt ingredient suppliers configure production lines around distinct technical specifications that separate commodity base malts from premium specialty grades. Segment boundaries determine margin capture, with craft beverage producers driving disproportionate value in roasted and caramel categories while food manufacturers prioritize consistent solubility profiles.
Product Type:
Domestic procurement concentrates in Montana and Alberta barley belts, while specialty malt exports from Minnesota malting clusters serve craft distillers across Texas and Colorado.
- Malted Barley:Standard two-row and six-row varieties provide enzymatic diastatic power measured in degrees Lintner, forming the fermentable foundation for lager and ale production. Demand clusters near rail terminals in the US Great Plains where steeping and germination facilities minimize moisture-loss transit risks.
- Specialty Malts:Roasted, caramel, and chocolate specifications command premium placement through controlled kilning profiles that develop distinct Lovibond color ratings and Maillard reaction compounds. Craft brewers in Michigan and Colorado specify custom roast curves that differentiate limited-release portfolios.
- Malted Wheat:Higher protein content and haze contribution support Belgian-style wheat beers and certain distilled spirits requiring softer mouthfeel.
- Malted Rye:Spicy flavor precursors and beta-glucan structure appeal to craft distillers producing rye whiskey and farmhouse ale variants.
Malted barley holds the largest share; momentum sits with specialty malts.
End Use Industry:
Cost tier separation is pronounced, with beverage applications absorbing price volatility while food and confectionery buyers enforce rigid specification contracts.
- Beverage:Beer and spirits production consumes the majority of malt volume, with craft brewers driving specialty grade premiums through small-batch procurement. TTB labeling mandates for origin disclosure favor domestic certified suppliers in Texas and Colorado permit jurisdictions.
- Food:Malt powder and extract formulations supply bakeries and cereal manufacturers requiring consistent enzyme activity and solubility. Canadian Prairie malters with closed-loop water systems capture preferential supplier status under tightening EPA disclosure frameworks.
- Confectionery:Malt syrup and extract provide color and flavor in chocolate coatings and malted milk balls.
- Animal Feed:Spent grain and lower-grade malt co-products serve dairy and poultry operations near malting facilities.
Beverage dominates volume; confectionery is climbing fastest on Mexican formulation demand.
Application:
Customer type bifurcation separates large-scale brewers seeking batch consistency from craft operators pursuing experimental roast profiles.
- Brewing:Base malt specifications vary by beer style, with IPA producers favoring higher diastatic power and lager brewers prioritizing neutral flavor platforms. Precision kilning control systems enable rapid profile experimentation previously constrained to seasonal release cycles.
- Distilling:Whiskey and specialty spirits require specific enzyme spectra and fermentable sugar profiles that influence yield and congenor development. Direct contracting between Colorado distillers and single-origin barley growers is displacing traditional commodity brokerage channels.
- Baking:Malt extract provides fermentable sugars and browning agents in artisan bread production.
- Flavoring:Roasted malt derivatives contribute color and taste to sauces and seasonings.
Brewing commands the largest share; distilling is expanding most quickly on craft whiskey proliferation.
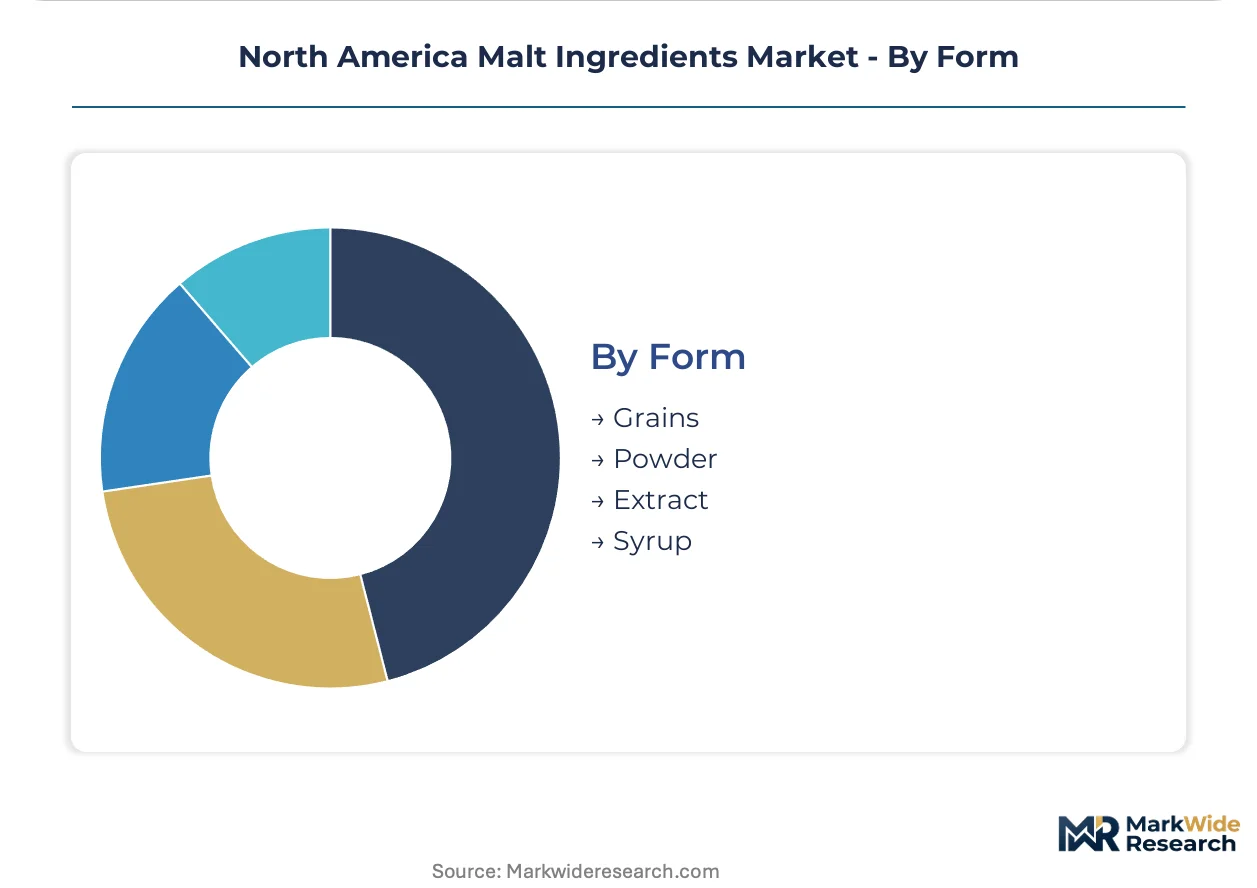
Form:
Supply concentration near rail terminals in Minnesota and Saskatchewan shapes grain logistics, while powder and extract production clusters with food manufacturing corridors.
- Grains:Whole malted kernels require controlled moisture handling and remain the dominant form for traditional brewing operations. Regional malting capacity near barley cultivation in the Canadian Prairie provinces compresses procurement costs for Great Plains brewers.
- Extract:Concentrated liquid or dried formulations provide batch consistency for food manufacturers and homebrew kit producers. Mexican confectionery manufacturers represent underpenetrated demand for consistent solubility profiles.
- Powder:Spray-dried malt extracts serve instant beverage and baking applications requiring precise moisture content.
- Syrup:Viscous liquid concentrates supply caramel color and flavor in industrial food production.
Grains hold the largest share; extract is gaining share fastest on food formulation standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The BNSF and Canadian Pacific Kansas City rail networks link Prairie barley fields to malting facilities across the Great Plains, compressing transit costs and moisture-loss risks for regional brewers.
United States
Craft distilleries in Colorado and Texas drive specialty malt procurement as TTB labeling mandates tighten origin disclosure requirements. The EPA's evolving water-use disclosure frameworks favor malters with verified low-intensity kilning operations. Minnesota malting clusters near rail terminals serve craft brewers across Michigan and Wisconsin with custom roast profiles.
Canada
Alberta and Saskatchewan barley belts anchor continental supply with closed-loop steeping infrastructure that captures preferential supplier status. Health Canada and PMRA standards govern food-grade malt labeling and allergen declarations for cross-border trade. Prairie malting facilities leverage proximity to cultivation to minimize logistics costs and quality degradation.
Mexico
Confectionery manufacturers in Mexico City and Monterrey represent underpenetrated demand for malt powder with consistent solubility profiles. The country's national food safety regulator enforces import standards that favor certified North American suppliers. Bajío Region food processing corridors are expanding formulation capacity for malt extract applications.
North America Malt Ingredients Market Competitive Landscape
Concentration sits with integrated malting and distribution specialists who control regional procurement channels across the US Midwest and Canadian Prairie provinces. The vendor base spans multinational grain processors, family-owned malting houses, and craft-focused specialty suppliers. Two strategic archetypes dominate: scale-driven commodity malters with captive barley sourcing and technical-service bundlers who pair custom specification support with brewing consultancy. Competitive moves center on backward integration into single-origin barley contracting and precision kilning technology licensing.
Among North American integrated operators, Rahr Corporation, Muntons PLC, and Briess Malt & Ingredients Co. occupy positions that exemplify the technical-service archetype. These companies anchor regional supply relationships through specialized roasted and caramel malt portfolios combined with brewing support capabilities. Their positioning reflects the market's bifurcation between commodity efficiency and craft customization demands.
| Leading Market Players |
|---|
| Axereal |
| GrainCorp Limited |
| Rahr Corporation |
| Simpsons Malt Limited |
| Muntons PLC |
| Malteurop Malting Company |
| Group Soufflet |
| InVivo Group |
| Briess Malt & Ingredients Co. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Great Plains brewers and Prairie malting facilities lock in multi-year barley supply access while capping price volatility exposure for craft distillers facing TTB origin disclosure mandates. These bilateral agreements transfer drought risk to malt houses while guaranteeing volume allocation during harvest crunches.
Pricing Analysis
Volume-discount tiering separates craft microbrewers purchasing sub-container quantities from regional brewpubs negotiating railcar-scale commitments and multinational beverage conglomerates commanding captive sourcing terms. Three-tier pricing structure across premium specialty, standard base malt, and economy feed-grade levels reflects diastatic power certification and Lovibond specification precision. Pricing pressure stems from barley yield volatility across Montana and Alberta irrigation districts. Food manufacturers enforce rigid specification contracts with minimal price elasticity, while craft distillers absorb premiums for provenance-verified single-origin grades.
Supply Chain Analysis
The United States and Canada anchor continental malted barley production, with Minnesota and Saskatchewan malting clusters drawing from adjacent Prairie cultivation belts. Germination kilns rest on two-row and six-row barley varietal inputs, plus steeping water volumes governed by EPA disclosure frameworks. Single-source vulnerability concentrates at rail terminals serving Minnesota-Saskatchewan corridors where harvest logistics crunches cascade. Distribution runs through BNSF and Canadian Pacific Kansas City networks linking Prairie fields to Texas and Colorado craft distillery clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master maltster apprenticeship pipelines are failing to replenish kiln operation expertise faster than aging specialists exit, constraining specialty roast capacity expansion across the US Midwest and Canadian Prairie provinces.
For Market Incumbents: Compound technical service bundling advantages by embedding brewing consultancy within custom malt specification contracts, defending against enzyme additive substitution threats in cost-optimized lager segments. Deepen backward integration into single-origin barley contracting with Michigan and Colorado estate brewery programs to secure provenance-verified supply streams. Prioritize precision kilning technology licensing to capture recurring revenue beyond commodity grain sales. For New Entrants and Emerging Players: Differentiate on extract formulation consistency for Mexican confectionery manufacturers in Mexico City and Monterrey corridors where solubility specification gaps persist among incumbent suppliers. Target carbon accounting qualification advantages by deploying closed-loop steeping infrastructure in water-stressed watersheds facing heightened EPA scrutiny. Lead with technical brewing support capabilities rather than price competition against established Prairie malting clusters. For Investors and Strategic Acquirers: Regional craft-focused malting houses with captive barley sourcing relationships and established TTB certification protocols represent the most defensible acquisition archetype within a consolidating vendor base. Long-term viability hinges on specialty malt margin capture sustaining through craft beverage flavor differentiation cycles. Monitor EPA water-use disclosure framework enforcement intensity as inflection indicator for preferential supplier qualification advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Single-Origin Barley Contracting | Captures provenance verification premiums demanded by Colorado craft distillers under TTB mandates. |
| Precision Kilning Technology Licensing | Generates recurring revenue streams from IoT-enabled roast-profile systems deployed across Minnesota malting clusters. |
| Closed-Loop Steeping Infrastructure Deployment | Secures EPA compliance advantages for water-intensive germination operations in drought-exposed Alberta districts. |
| Extract Formulation Capacity Expansion | Addresses underpenetrated Mexican confectionery demand for consistent solubility profiles in Monterrey processing corridors. |
| Technical Brewing Consultancy Bundling | Differentiates commodity-adjacent malt sales through embedded specification support for emerging craft accounts. |
Research Methodology
The analysis maps specialty malt, base malt, and extract formulation sub-sectors, each validated through master maltsters, craft brewery procurement directors, and TTB compliance officers across primary interviews with secondary triangulation against FDA labeling guidance documents, EPA water-use disclosure frameworks, and BNSF rail shipment manifests. Bottom-up volume modeling from individual malting facility capacity feeds into top-down cross-checks against Canadian Grain Commission export data and TTB brewing material certification records.
Consistency checks against USDA barley production surveys and Health Canada cross-border trade statistics validated analytical outputs across the projection horizon. Segmentation dimensions include product type, end-use industry, application, and form specifications with regional production cluster overlays. CAGRs derive from compound growth trajectory modeling incorporating barley yield variance coefficients and craft distillery permit issuance patterns as industry-specific forecast inputs.
Material uncertainties — drought cycle severity across Prairie provinces, EPA framework enforcement timing, and enzyme additive substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained craft flavor differentiation procurement and TTB origin disclosure compliance adherence. Recalibration cycles align with material shifts in barley cultivation economics and regulatory disclosure mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Tannin Market
Ingredients
Cocoa Solids Market
Ingredients
Yeast Flakes Market
Ingredients
Protein Ingredients Market
Ingredients
Red Orange Anthocyanin Extract Ingredients Market
Ingredients
Pea Peptones Market
Ingredients
Dried Beet Pulp Market
Ingredients
Vitamin and Mineral Premixes Market
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
Textural Food Ingredients Market
Ingredients
Anhydrous Caffeine Market
Ingredients
Hydrolyzed Starch Market
Ingredients
Bangladesh Mustard Oil Market
Ingredients
Botanical Extracts Market
Ingredients
China Soy Protein Market
Ingredients
Fats and Oils Market