
 EPA and DHA Omega-3 Ingredient Market | 2026-2036
EPA and DHA Omega-3 Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
EPA and DHA Omega-3 Ingredient Market Analytics
REACH compliance is repositioning the cost-of-entry calculus for European omega-3 suppliers, forcing contaminant testing and supply chain documentation upgrades. DSM-Firmenich leverages its integrated algal fermentation platform to control quality from strain to finished oil. Croda International anchors its position through specialized pharmaceutical-grade EPA concentrates for prescription cardiovascular therapies. Epax Norway AS dominates the high-purity marine segment with Norwegian cold-water fish oil sourcing and advanced molecular distillation capabilities.
EPA and DHA omega-3 ingredients are long-chain polyunsaturated fatty acids, typically supplied at concentrations ranging from 30% to over 90% active content depending on refinement level, serving primarily as bioactive compounds for cardiovascular, cognitive, and anti-inflammatory health applications. The oil format occupies the largest volume share due to its processing efficiency in softgel encapsulation and liquid formulations, while algal-sourced DHA represents the fastest-expanding source category as plant-based and allergen-free positioning reshapes procurement patterns across infant formula and vegan supplement channels. Powder formats command premium positioning in functional foods and sports nutrition where solubility and shelf stability determine formulation feasibility.
FDA New Dietary Ingredient notifications and EFSA health claim substantiation requirements create divergent compliance pathways that fragment market access strategies between North American and European suppliers. China's NMPA and SAMR oversight of blue-hat health food registrations adds a third regulatory layer for brands targeting the world's largest supplement consumer base. Stakeholders must monitor evolving contaminant thresholds for heavy metals and oxidation markers as regulatory stringency tightens across all major jurisdictions.
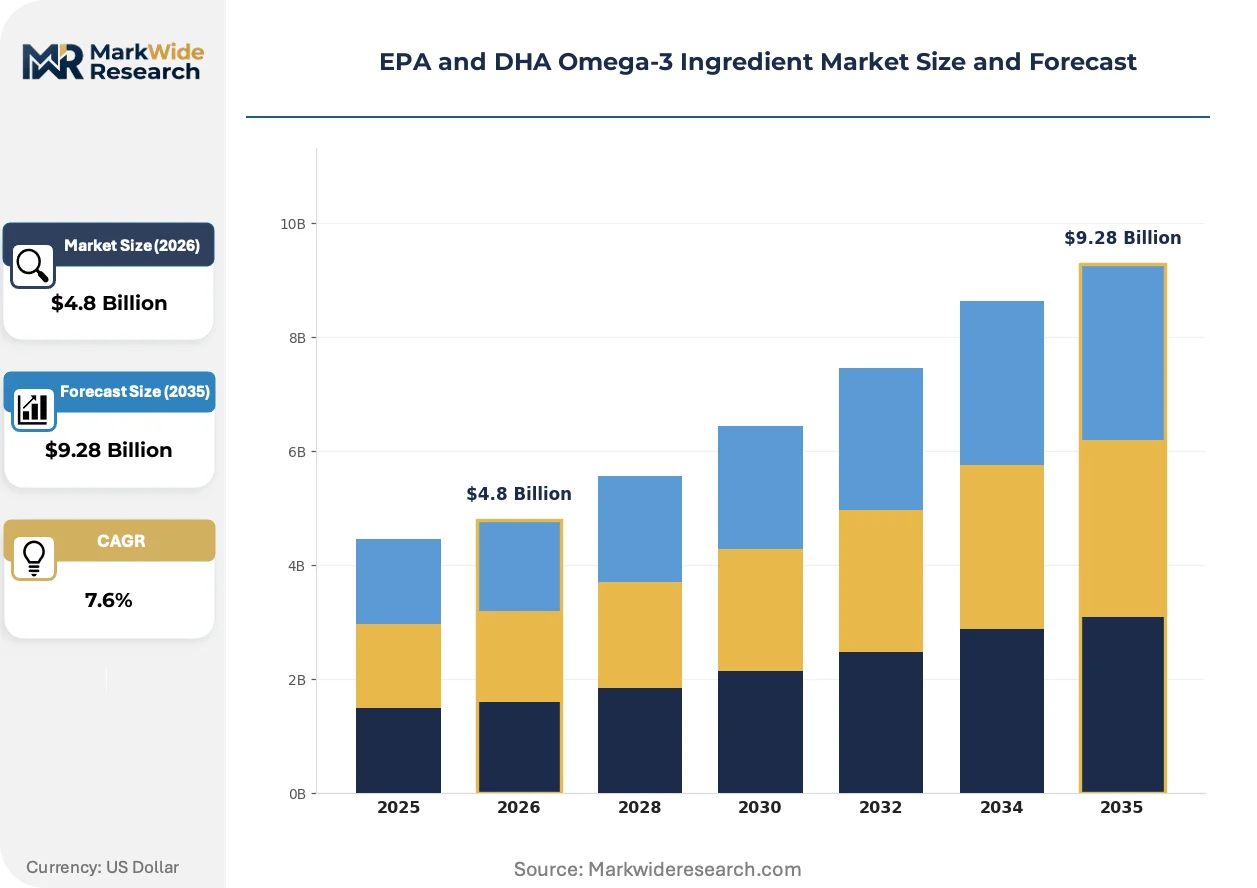
Market Dynamics
Pharmaceutical formulators are expanding omega-3 incorporation into prescription drug pipelines, fundamentally altering the competitive landscape by elevating purity requirements and regulatory compliance standards beyond traditional supplement applications.
Growth Catalysts
- EFSA Health Claim Authorization:The European Union's Novel Food regulation and EFSA health claim authorization process accelerates ingredient standardization across member states, creating harmonized market access for compliant suppliers.
- Infant Nutrition Formulation:Domestic supplement manufacturers in China scale algal DHA sourcing for infant nutrition applications, concentrating demand in the world's largest supplement consumer base.
- Cold-Water Marine Sourcing:Norwegian cold-water fish oil sourcing combined with advanced molecular distillation capabilities enables high-purity EPA concentrate production for cardiovascular therapeutic applications.
Market Restraints
- REACH Compliance Burden:ECHA's REACH regulation repositions cost-of-entry calculus for European suppliers, forcing contaminant testing and supply chain documentation upgrades that disproportionately burden smaller operators.
- Algal Fermentation Capital Intensity:Integrated algal fermentation platforms require substantial upstream investment in strain development and bioreactor infrastructure, limiting viable competitors to well-capitalized players.
- Oxidation Marker Volatility:Tightening regulatory thresholds for peroxide and anisidine values in marine oils create batch rejection risk and working capital pressure across the supply chain.
Strategic Opportunities
- Vegan Supplement Channel Expansion:Plant-based and allergen-free positioning reshapes procurement patterns, with algal-sourced DHA capturing share in vegan supplement channels previously inaccessible to marine-derived alternatives.
- Sports Nutrition Powder Formats:Powder formats command premium positioning in functional foods and sports nutrition where solubility and shelf stability determine formulation feasibility, opening white space beyond traditional softgel applications.
- FDA Prescription Drug Pathway:New Dietary Ingredient notifications and prescription drug pipelines create dual-track market development, with pharmaceutical-grade concentrates accessing reimbursement-backed revenue streams.
Industry Challenges
- SAMR Blue-Hat Registration Timeline:China's NMPA and SAMR oversight of blue-hat health food registrations imposes extended approval cycles, compressing speed-to-market for brands targeting domestic consumers.
- Heavy Metals Testing Protocol Divergence:Evolving contaminant thresholds for lead, mercury, and cadmium across FDA, EFSA, and SAMR jurisdictions force redundant testing regimes and documentation fragmentation.
- Legacy Encapsulation Equipment Retrofit:Softgel manufacturing lines require modification to handle high-concentration EPA concentrates above 85% active content, creating integration friction with existing pharmaceutical contract manufacturing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EPA and DHA Omega-3 Ingredient Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil, Powder, Emulsion, Liquid End User: Food & Beverages, Dietary Supplements, Pharmaceuticals, Animal Feed Source: Fish, Algal, Krill, Plant Application: Nutraceuticals, Functional Foods, Sports Nutrition, Personal Care |
| Companies Covered | ADM, Croda International, BASF SE, GC Rieber, Epax Norway AS, DSM-Firmenich, Aker BioMarine, Golden Omega, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EPA and DHA Omega-3 Ingredient Market Evolving Landscape
Advanced refinement technologies and regulatory convergence are compressing the gap between nutraceutical and pharmaceutical grade standards, while procurement models evolve to prioritize traceability and sustainability credentials.
Supercritical CO2 extraction combined with short-path molecular distillation is unifying the previously separate quality tiers of dietary supplement and prescription-grade omega-3s. Pharmaceutical formulators in Germany and Switzerland now specify 90%+ EPA concentrates that were historically confined to research applications. This technology compression is unifying pricing benchmarks across what were distinct market segments.
REACH authorization timelines for novel algal strains are extending from 18 to 36 months as ECHA applies stricter substance evaluation criteria to fermentation-derived lipids. The industrial consequence is delayed market entry for next-generation DHA producers seeking European positioning. Infant formula manufacturers are responding by dual-sourcing from established marine suppliers while awaiting novel food approvals.
Certification-driven procurement now dominates buyer evaluation, with Marine Stewardship Council and Friends of the Sea credentials displacing price-first sourcing in Nordic and North American contract negotiations. Brand owners in the United States and Canada increasingly require batch-level blockchain traceability from catch location to finished oil. This behavioral shift is most visible in premium private label channels where sustainability claims support 15-20% price premiums.
EPA and DHA Omega-3 Ingredient Market Segmentation
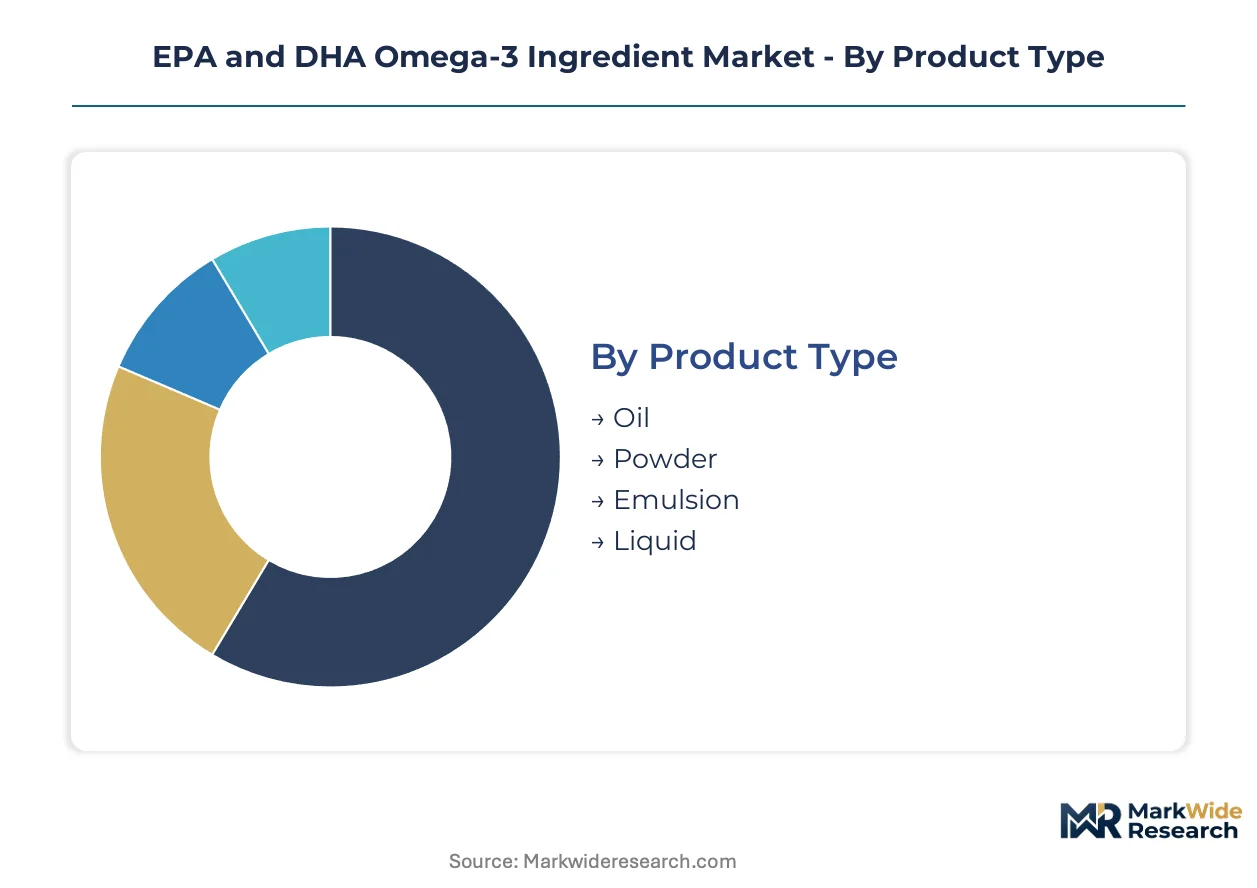
EPA and DHA omega-3 ingredients fragment across four critical dimensions that determine formulation feasibility, regulatory pathway, and margin capture. Procurement teams weight source traceability against concentration requirements, while finished product positioning hinges on format compatibility with target delivery systems.
Product Type:
Buyers select formats based on encapsulation equipment compatibility and shelf stability requirements rather than unit cost alone.
- Oil:Triglyceride and ethyl ester concentrates ranging from 30% to 90%+ active EPA/DHA content dominate softgel manufacturing. Pharmaceutical contract manufacturers in Germany and Switzerland specify oil formats for prescription cardiovascular therapies requiring precise dosing reproducibility.
- Powder:Microencapsulated and spray-dried variants enable functional food integration where water dispersibility and oxidative protection determine formulation success. Sports nutrition brands in the United States prioritize powder formats for ready-to-mix applications.
- Emulsion:Water-dispersible lipid droplets suit beverage fortification and liquid supplement applications requiring homogenous suspension stability.
- Liquid:Bulk oil presentations serve institutional manufacturing and pharmaceutical compounding operations with dedicated handling infrastructure.
Oil leads on scale; powder leads on momentum.
End User:
Regulatory stringency and purity specifications create distinct commercial tiers across downstream industries.
- Dietary Supplements:Softgel and liquid formulations targeting cardiovascular, cognitive, and prenatal health applications constitute the primary volume channel. FDA New Dietary Ingredient notifications and EFSA health claim substantiation requirements fragment market access strategies between North American and European suppliers.
- Pharmaceuticals:Prescription-grade EPA concentrates above 85% active content for cardiovascular therapeutic indications command premium positioning. Supercritical CO2 extraction combined with short-path molecular distillation unifies quality tiers previously separated between nutraceutical and pharmaceutical applications.
- Food & Beverages:Infant formula manufacturers represent concentrated demand for algal DHA with documented allergen-free and sustainable sourcing credentials.
- Animal Feed:Aquaculture and pet nutrition applications prioritize cost-efficient marine sourcing with standardized oxidation marker thresholds.
Dietary supplements lead on scale; pharmaceuticals lead on momentum.
Source:
Procurement patterns increasingly prioritize sustainability certification and supply chain documentation over historical price-first evaluation.
- Algal:Fermentation-derived DHA from Schizochytrium and Crypthecodinium strains enables vegan positioning and eliminates marine allergen concerns. Infant formula manufacturers in China scale algal sourcing while awaiting REACH authorization timelines for novel strains.
- Fish:Anchovy, sardine, and Norwegian cold-water fish oil sourcing combined with advanced molecular distillation capabilities anchors high-purity EPA concentrate production.
- Krill:Antarctic Euphausia superba phospholipid-bound omega-3s command premium positioning for enhanced bioavailability claims in specialized supplement channels.
- Plant:Alpha-linolenic acid precursors and emerging genetically engineered oilseed sources serve niche applications requiring non-marine, non-algal positioning.
Fish leads on scale; algal leads on momentum.
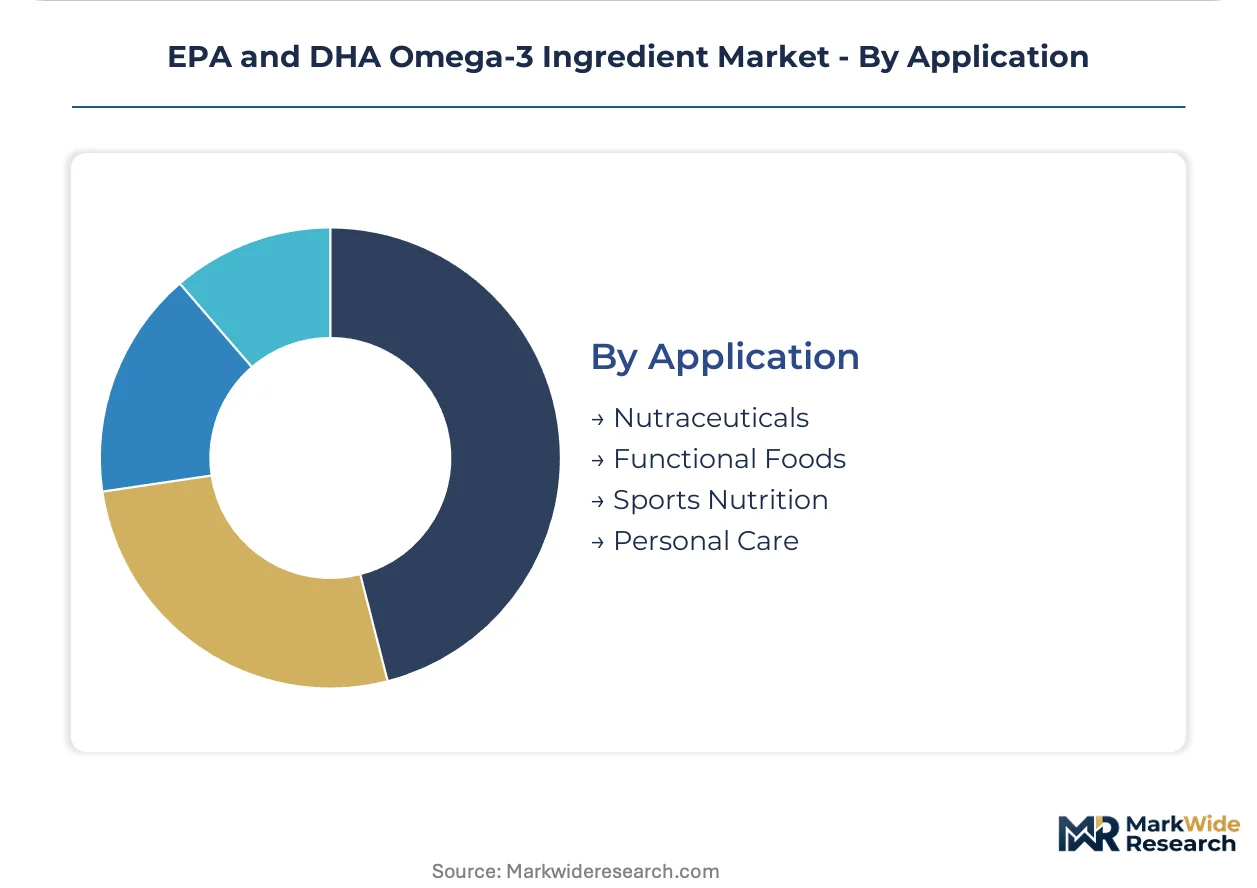
Application:
Finished product positioning determines concentration requirements, stability specifications, and regulatory compliance burden.
- Nutraceuticals:Encapsulated softgels and liquid drops targeting preventive health maintenance constitute the established revenue base. EFSA health claim authorization for cardiovascular and cognitive benefits accelerates ingredient standardization across EU member states.
- Functional Foods:Fortified dairy, bakery, and beverage applications demand microencapsulated formats with proven sensory neutrality and shelf life extension.
- Sports Nutrition:Powder formats with rapid solubility and low oxidation markers capture share in pre-workout and recovery formulations.
- Personal Care:Topical omega-3 incorporation in dermocosmetic applications remains nascent, constrained by formulation stability challenges and regulatory classification ambiguity.
Nutraceuticals lead on scale; functional foods lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine biochemists and fermentation specialists cluster near coastal processing facilities and biotech corridors, anchoring regional supply capabilities.
United States
FDA prescription drug pathways and New Dietary Ingredient notifications attract pharmaceutical formulators to the Northeast corridor. Boston and New Jersey host contract manufacturers upgrading softgel lines for high-concentration EPA concentrates. Sports nutrition brands in California drive powder format demand for ready-to-mix applications.
Norway
Cold-water fish oil sourcing and molecular distillation expertise concentrate around Bergen and Ålesund. EFSA health claim authorization processes accelerate ingredient standardization for EU market access. Epax Norway AS anchors the high-purity marine segment with Norwegian processing capabilities.
China
Domestic supplement manufacturers scale algal DHA sourcing for infant nutrition applications, concentrating demand in Shanghai and Guangzhou. SAMR blue-hat health food registrations impose extended approval cycles. NMPA oversight shapes procurement patterns for imported marine concentrates.
Germany
Pharmaceutical-grade EPA concentrates for cardiovascular therapies drive demand in Frankfurt and Basel-adjacent corridors. REACH compliance repositions cost-of-entry calculus for European suppliers. Supercritical CO2 extraction specialists cluster in Baden-Württemberg.
Switzerland
DSM-Firmenich leverages integrated algal fermentation platforms from Basel operations, controlling quality from strain to finished oil. Swissmedic oversight aligns with pharmaceutical-grade specifications. Geneva-based procurement teams specify batch-level blockchain traceability for premium private label channels.
EPA and DHA Omega-3 Ingredient Market Competitive Landscape
The competitive structure tilts toward integrated biotech specialists with captive fermentation capacity. Consolidation around pharmaceutical-grade capabilities separates tier-one suppliers from commodity marine oil traders. Three archetypes dominate: algal fermentation platforms, Norwegian marine distillers, and diversified nutrition ingredient houses. Capacity expansion into high-purity concentrates and strategic partnerships for infant formula sourcing represent the dominant competitive vectors.
Among integrated fermentation specialists, DSM-Firmenich exemplifies the strain-to-finished-oil control model. Norwegian marine processors anchor the high-purity segment, with Epax Norway AS representing cold-water sourcing and advanced molecular distillation capabilities. Diversified ingredient houses including Croda International occupy positions spanning pharmaceutical-grade concentrates and specialized EPA formulations for prescription cardiovascular therapies.
| Leading Market Players |
|---|
| ADM |
| Croda International |
| BASF SE |
| GC Rieber |
| Epax Norway AS |
| DSM-Firmenich |
| Aker BioMarine |
| Golden Omega |
| Cargill |
| Others |
Value Network & Pricing Analysis
Supercritical CO2 extraction combined with short-path molecular distillation compresses production economics while concentrating quality-tier supply among integrated Norwegian marine processors and Swiss fermentation specialists. This technology convergence simultaneously elevates purity thresholds and eliminates mid-tier competitors unable to fund capital-intensive refinement infrastructure.
Pricing Analysis
Unbundled testing and certification services now command separate line-item pricing from base oil supply, with EFSA Novel Food dossier preparation and REACH authorization consulting treated as distinct procurement decisions. Pharmaceutical-grade EPA concentrates above 85% active content price at substantial premiums over dietary supplement tiers, with differentiation driven by oxidation marker thresholds and batch-level documentation depth. Price erosion runs through standard-grade fish oil concentrates as Peruvian and Chilean anchovy sourcing expands processing capacity. Contract manufacturers represent the most price-sensitive buyer segment, while infant formula brands absorb premium positioning for algal DHA with documented sustainability credentials.
Supply Chain Analysis
Reverse-logistics flows for expired or oxidized marine oils remain underdeveloped, creating working capital drag and batch write-off exposure without established re-refinement channels. Raw material sourcing concentrates in Norway, Peru, and China, with Bergen-area processors anchoring high-purity EPA production and Shanghai corridor fermentation facilities scaling algal DHA output. Supply chains draw from Antarctic krill fisheries, North Atlantic cold-water species, and Schizochytrium strain banks. Single-source vulnerability permeates pharmaceutical-grade concentrate supply, where molecular distillation capacity clusters among three Norwegian operators. Distribution runs through specialized lipid distributors and direct pharmaceutical contract manufacturing relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on supercritical extraction cost-down curves and pharmaceutical-grade tier migration, with quality-tier compression enabling premium capture across broader volume bases.
For Market Incumbents: To counter algal fermentation platform expansion from DSM-Firmenich and emerging Chinese biotech entrants, Norwegian marine processors should deepen backward integration into catch-fleet ownership and secure exclusive long-term supply agreements with pharmaceutical contract manufacturers in Germany and Switzerland. REACH authorization timelines for novel strains create temporary defensive moats worth exploiting through accelerated capacity expansion. For New Entrants and Emerging Players: Sports nutrition powder formats in the United States represent the most penetrable white space, with solubility-optimized microencapsulated DHA commanding formulation premiums in ready-to-mix applications underserved by incumbent oil-format specialists. Direct brand partnerships with functional beverage developers bypass established softgel distribution chokepoints. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale marine oil traders lacking captive processing infrastructure, as quality-tier compression erodes commodity-grade margins faster than integrated players. Long-term viability favors strain-to-finished-oil fermentation platforms and Norwegian molecular distillation specialists with pharmaceutical-grade certification depth. Monitor EFSA health claim authorization timelines for cardiovascular indications as inflection signals for prescription-channel revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade EPA Concentrate Capacity Expansion | Norwegian processors capture prescription cardiovascular therapy demand from German and Swiss formulators. |
| Integrated Algal Fermentation Platform Development | Strain-to-finished-oil control eliminates quality variability for infant formula manufacturers in China. |
| REACH Authorization Dossier Investment | Novel food approvals unlock European market access for next-generation Schizochytrium-derived DHA producers. |
| Blockchain Traceability Infrastructure Deployment | Batch-level catch-to-capsule documentation supports 15-20% price premiums in North American private label channels. |
| Sports Nutrition Powder Format Commercialization | Microencapsulated rapid-solubility variants penetrate ready-to-mix applications beyond traditional softgel constraints. |
Research Methodology
Direct dialogue with pharmaceutical formulation scientists, infant formula procurement directors, marine oil processing engineers, and regulatory affairs specialists at EFSA and SAMR provided qualitative grounding, cross-referenced with FDA New Dietary Ingredient notifications, EFSA Novel Food register entries, SAMR blue-hat registration databases, and customs trade flow data for omega-3 concentrate imports. Bottom-up volume modeling triangulated against top-down market sizing from disclosed capacity expansions and pharmaceutical contract manufacturing announcements.
Bottom-up segmentation analysis modeled oil, powder, emulsion, and liquid formats across dietary supplement, pharmaceutical, food and beverage, and animal feed end uses, with source differentiation between algal, fish, krill, and plant origins. CAGRs derived from regression analysis of historical price-volume relationships and projected pharmaceutical pipeline advancement rates across the analysis window. Forecast inputs incorporated EFSA health claim authorization probability assessments and SAMR registration timeline distributions.
Underlying measurement precision varies by segment; pharmaceutical-grade concentrates with documented prescription drug partnerships carry tighter precision than emerging algal fermentation capacity projections. Forecasts reflect assumptions regarding regulatory authorization timelines, strain development success rates, and marine raw material supply stability. Practitioners should monitor EFSA cardiovascular health claim decisions, REACH authorization outcomes for novel algal strains, and SAMR blue-hat registration queue progression for early demand inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Coconut Derivatives Market
Ingredients
Konjac Flour Market
Ingredients
China Gelatin Market
Ingredients
Omega 6 Market
Ingredients
Corn Steep Liquor Market
Ingredients
Baking Ingredients Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Proteose Peptone Market
Ingredients
Oat Ingredients Market
Ingredients
Acetylated Starch Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Pea Flour Market
Ingredients
Rose Hips Extract Market
Ingredients
Dry Malt Products Market
Ingredients
North America Collagen Ingredients Market
Ingredients
Global Autolyzed Yeast Extract Market