
 Coconut Oil Market | 2026-2036
Coconut Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Oil Market Analysis
Skilled copra processing labor is unwinding across Southeast Asian production clusters, tightening virgin oil throughput and pushing manufacturers toward mechanized extraction. Cargill Incorporated leverages its integrated supply chain from plantation to refinery across Pacific island economies. Marico Limited sustains dominant branded coconut oil positions in South Asian consumer markets through extensive rural distribution. Greenville Agro Corporation anchors premium virgin oil output for North American and European cosmetic ingredient buyers.
Coconut oil comprises primarily lauric acid triglycerides extracted from copra or fresh kernel through cold-press or solvent methods, serving as a functional lipid in food, cosmetic, and pharmaceutical matrices. Virgin Coconut Oil commands premium positioning in personal care and nutraceutical channels due to retained polyphenol content and minimal processing credentials. Refined Coconut Oil occupies bulk food manufacturing and frying applications where neutral flavor and high smoke point determine procurement decisions. Fractionated Coconut Oil leads pharmaceutical and cosmetic formulation growth through stable liquid-phase MCT delivery.
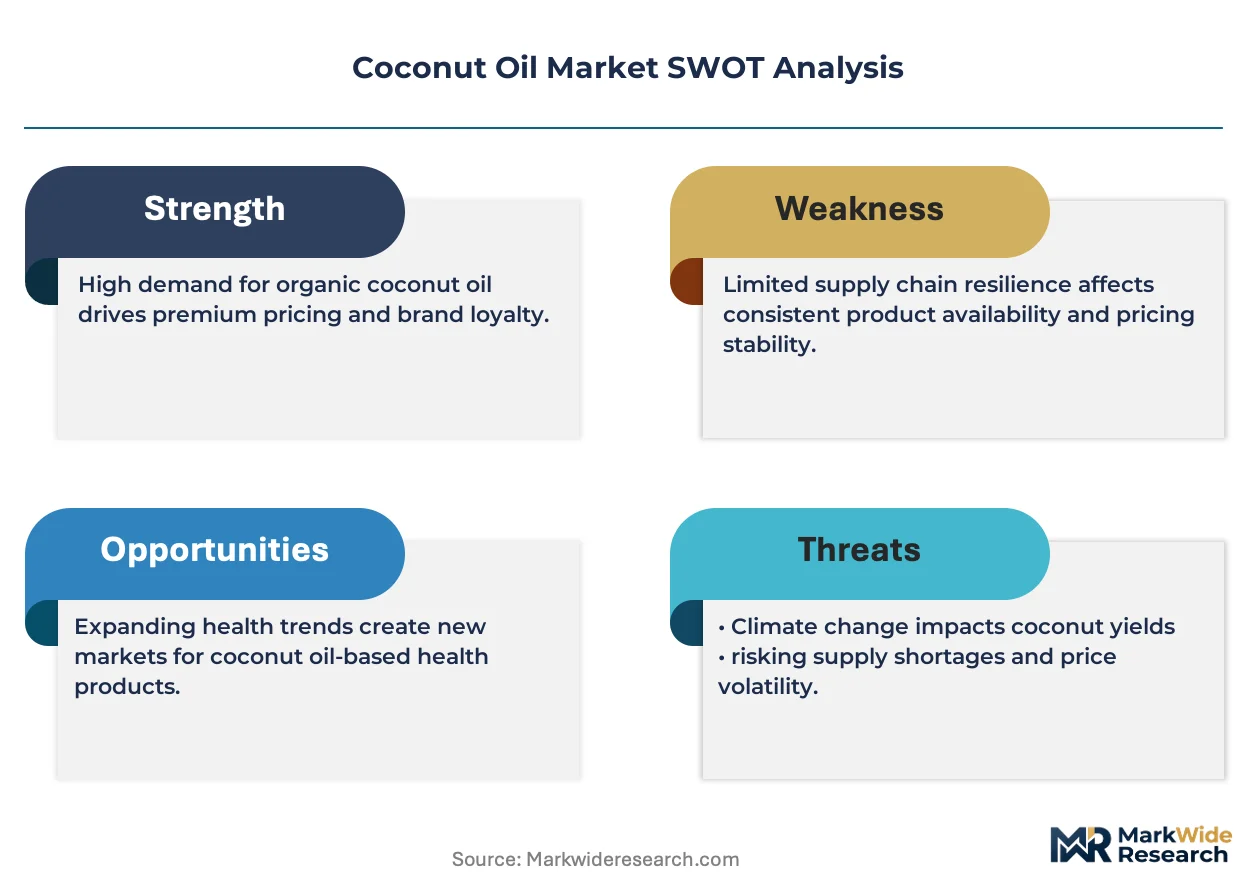
The FDA governs coconut oil safety in US food and cosmetic applications, while EFSA evaluates novel health claim substantiation for European market access. BIS certification requirements in India shape domestic edible oil quality benchmarks and import substitution dynamics. REACH compliance in Europe constrains residual solvent thresholds for refined grades entering cosmetic ingredient supply chains. Stakeholders must monitor evolving fractionation technology costs and lauric acid substitution threats from palm kernel oil to sustain margin structures.
Market Dynamics
Skilled copra processing labor is unwinding across Southeast Asian production clusters, tightening virgin oil throughput and pushing manufacturers toward mechanized extraction systems that reshape competitive positioning.
Growth Catalysts
- EFSA novel health claim pathways:European nutraceutical brands accelerate virgin oil procurement to substantiate lauric acid benefits through approved functional food channels.
- Personal care clean-label mandates:Cosmetic formulators in North America specify cold-pressed grades to meet retailer sustainability scorecards and consumer ingredient transparency expectations.
- Indonesia-Philippines copra concentration:Integrated plantation-to-refinery operations in these archipelagic supply zones secure feedstock continuity for global cosmetic ingredient buyers.
Market Restraints
- Palm kernel oil substitution:Oleochemical manufacturers in Malaysia and Indonesia switch lauric acid sourcing to palm kernel derivatives, compressing coconut oil premium pricing power in bulk surfactant applications.
- REACH residual solvent thresholds:European cosmetic ingredient buyers face compliance costs and testing delays when sourcing refined grades from solvent-extraction facilities lacking certified purification infrastructure.
- Copra weather volatility:Typhoon frequency in the Philippine Visayas and drought cycles in Sulawesi create raw material availability swings that disrupt contract fulfillment for North American food manufacturers.
Strategic Opportunities
- Fractionated MCT pharmaceutical channels:Parenteral nutrition and therapeutic ketone formulations in US and German hospital systems specify medical-grade caprylic-capric triglycerides with documented chain-length purity.
- Direct-to-consumer subscription models:Virgin oil brands bypass traditional retail distribution through personalized wellness platforms targeting functional food enthusiasts in Australian and Canadian urban markets.
- BIS edible oil quality benchmarks:Indian domestic manufacturers leverage certification requirements to displace imported refined volumes in institutional food service and mid-market consumer segments.
Industry Challenges
- Cold-press technician scarcity:Traditional wet-milling expertise is concentrating in aging worker populations across Kerala and Tamil Nadu processing clusters, constraining artisanal virgin oil capacity expansion.
- Organic certification timeline compression:Three-year conversion requirements for copra plantations seeking USDA Organic or EU Organic status delay premium positioning for new market entrants targeting clean-label cosmetic channels.
- Mechanized extraction capex intensity:Centrifugal and expeller system investments for virgin oil production require capital deployment that mid-scale Philippine processors struggle to finance without plantation-backed credit facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Oil Market |
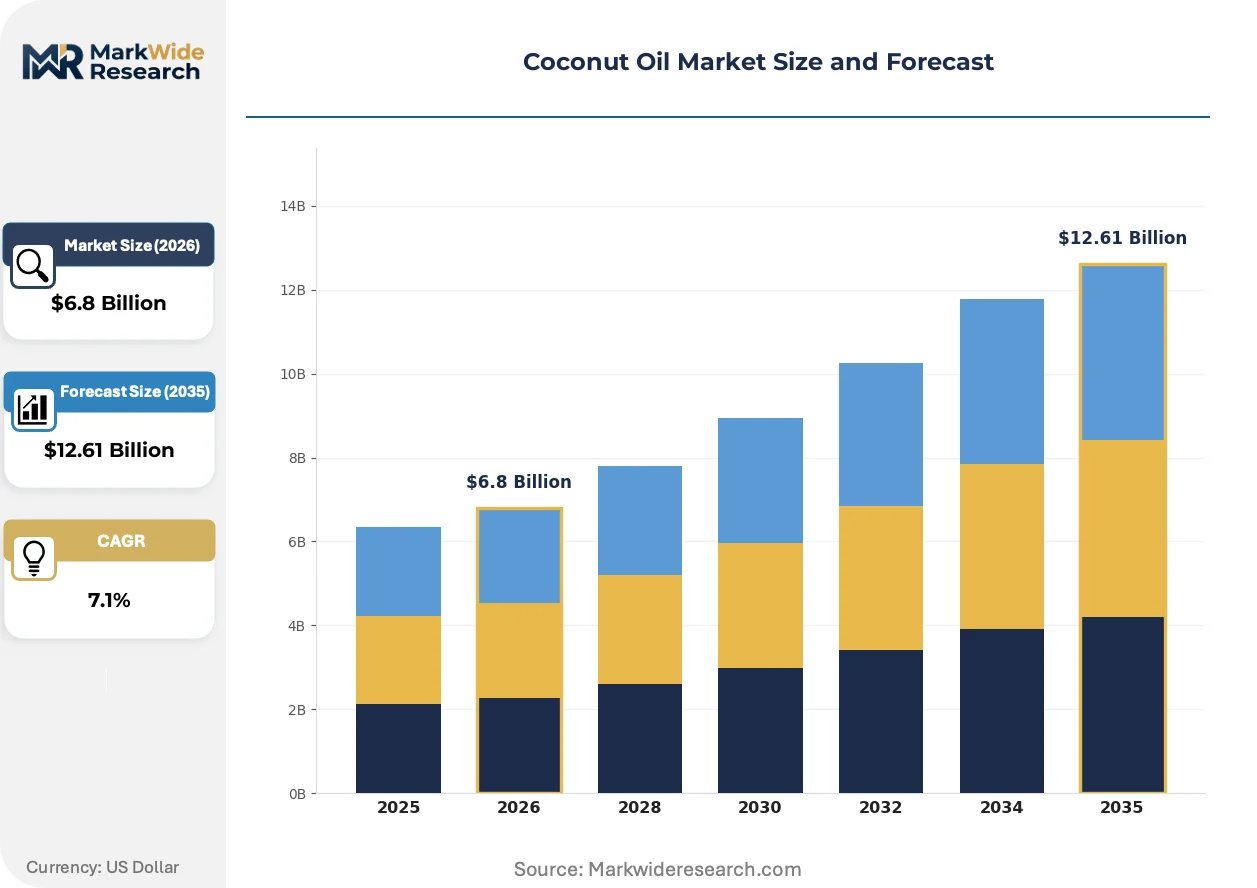
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.61 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virgin Coconut Oil, Refined Coconut Oil, Fractionated Coconut Oil, Culinary Coconut Oil Application: Cosmetics, Food & Beverages, Pharmaceuticals, Personal Care Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Households, Food Manufacturers, Personal Care Brands, Healthcare Providers |
| Companies Covered | Greenville Agro Corporation, Marico Limited, Cargill Incorporated, Tantuco Enterprises, The Hain Celestial Group, Bunge Limited, Celebes Coconut Corporation, SC Global Coco Products, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Oil Market Emerging Trajectories
Processing technology is compressing equipment footprints while regulatory frameworks harden purity documentation requirements across multiple geographies simultaneously.
Centrifugal virgin oil extraction systems is miniaturizing from industrial-scale continuous flow units to modular skid-mounted configurations suitable for cooperative-level deployment in Indonesian outer island communities. Philippine equipment distributors report accelerating inquiries from municipality-backed agricultural collectives seeking to capture premium export margins previously accessible only to integrated plantation operations. This distributed processing architecture is fragmenting supply concentration and enabling geographic diversification of certified organic virgin oil origins.
REACH compliance documentation for cosmetic-grade refined coconut oil now mandates comprehensive residual solvent testing and supply chain mass balance verification extending to copra source plantations. German and French cosmetic ingredient buyers are disqualifying Southeast Asian suppliers lacking third-party audited extraction facility certifications. The compliance burden is concentrating procurement relationships among vertically integrated processors with captive laboratory testing capabilities and documented chain-of-custody systems.
Clean-label preference is rotating procurement authority from bulk commodity traders to finished goods brand technical teams with direct supplier qualification responsibilities. North American natural personal care companies now specify virgin oil polyphenol retention minimums and fatty acid profile certificates in purchase agreements previously negotiated on price-per-metric-ton basis alone. This specification intensity is compressing spot market liquidity and lengthening contract durations for qualified supply relationships.
Coconut Oil Market Segmentation
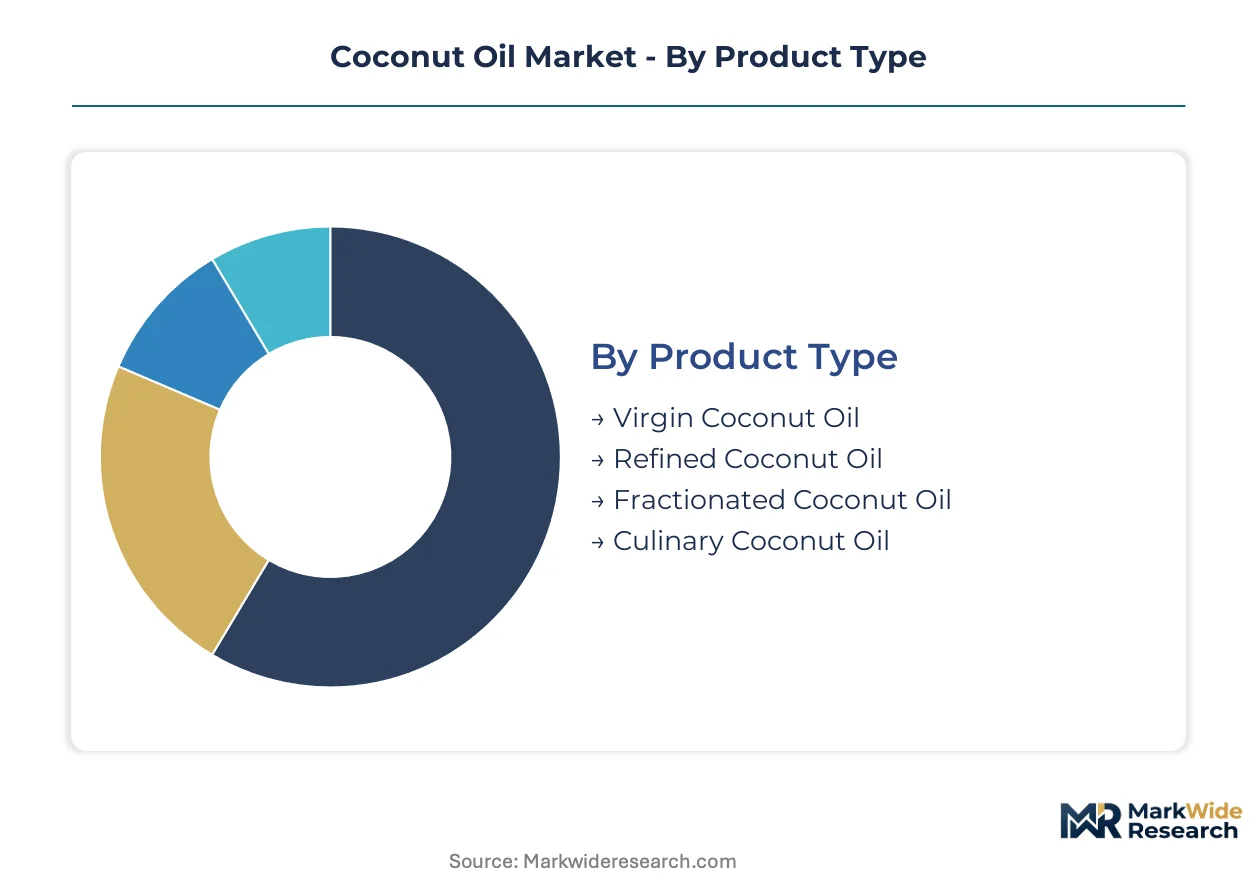
Coconut oil procurement decisions split across technical specifications, regulatory pathways, and channel economics. Buyers in personal care, food manufacturing, and pharmaceutical formulation each demand distinct purity grades and documentation standards.
Product Type:
FDA and EFSA labeling requirements diverge sharply between cold-pressed virgin grades and solvent-extracted refined volumes, creating compliance-driven procurement segmentation.
- Virgin Coconut Oil:Cold-pressed extraction retains polyphenol antioxidants and lauric acid integrity above 50% concentration. North American natural personal care brands specify this grade for clean-label moisturizers and hair treatments, though organic certification timelines constrain new supplier qualification.
- Refined Coconut Oil:Neutralized, bleached, and deodorized through high-temperature processing to achieve smoke points above 200°C. Bulk food manufacturers in US snack frying and European confectionery applications prioritize this grade for flavor consistency and extended fry life.
- Fractionated Coconut Oil:Caprylic-capric triglyceride isolation yields stable liquid-phase MCTs for pharmaceutical delivery systems.
- Culinary Coconut Oil:Standardized edible grades meeting BIS, FDA, or national food safety thresholds for direct consumer cooking applications.
Refined Coconut Oil handles the majority of throughput; Fractionated Coconut Oil is the fastest mover on share.
Application:
End-use specifications determine whether copra sourcing prioritizes polyphenol retention, oxidative stability, or fatty acid chain-length precision.
- Cosmetics:Formulators specify virgin grades with documented antioxidant content for emollient creams and surfactant-free cleansing oils. REACH compliance mandates residual solvent thresholds below 50 ppm for any refined oil entering European cosmetic ingredient supply chains.
- Food & Beverages:Neutral-flavor refined oil dominates commercial baking, confectionery coating, and plant-based dairy alternatives where saturated fat functionality replaces hydrogenated oils.
- Pharmaceuticals:Medical-grade fractionated MCTs serve parenteral nutrition and therapeutic ketone formulations requiring documented C8:C10 ratios.
- Personal Care:Direct-application hair oils and body moisturizers in South Asian and Southeast Asian consumer markets drive volume through traditional retail and e-commerce channels.
Food & Beverages absorbs the largest volume base; Pharmaceuticals is expanding most quickly on formulation specificity.
Distribution Channel:
Channel selection determines margin capture, certification documentation requirements, and buyer relationship intensity.
- Online Retail:Direct-to-consumer virgin oil brands leverage subscription models and wellness content marketing to bypass traditional retail markups in Australian and Canadian urban markets.
- Supermarkets:Mass-market refined and culinary grades move through centralized procurement with price-per-metric-ton negotiation and limited supplier qualification depth.
- Specialty Stores:Organic and fair-trade certified virgin oils command shelf space in natural product retailers with documented chain-of-custody requirements.
- Direct Sales:Cosmetic ingredient buyers and pharmaceutical formulators establish long-term contracts with vertically integrated processors for customized fatty acid profiles and batch-specific certificates of analysis.
Supermarkets handle the largest transaction volume; Direct Sales is climbing the fastest on contract duration and specification intensity.
End User:
Procurement sophistication varies from household price sensitivity to pharmaceutical-grade documentation demands.
- Households:Consumer purchases concentrate on 500ml to 1-liter virgin oil formats for cooking and personal care, with organic and cold-pressed claims driving premium positioning in urban Indian and Southeast Asian markets.
- Food Manufacturers:Institutional buyers in US snack food and European confectionery sectors negotiate annual refined oil contracts with smoke point and free fatty acid specifications.
- Personal Care Brands:Technical teams now specify polyphenol retention minimums and lauric acid certificates, displacing commodity traders from supplier selection authority.
- Healthcare Providers:Hospital nutrition departments and compounding pharmacies source medical-grade fractionated MCTs with documented chain-length purity for enteral and parenteral applications.
Food Manufacturers represent the deepest volume commitment; Healthcare Providers is gaining share fastest on clinical formulation expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium virgin oil commands 40-60% price spreads over refined grades in North American and European cosmetic channels, while Southeast Asian producers capture margin compression from palm kernel substitution in bulk surfactant applications.
United States
Natural personal care brands in California and New York Metro specify cold-pressed virgin grades with polyphenol retention minimums. FDA labeling requirements for edible and cosmetic applications shape procurement documentation standards. Personal care technical teams in Los Angeles and Brooklyn now displace commodity traders from supplier selection authority.
Germany
Pharmaceutical formulators in Frankfurt-Rhine-Main and Cologne source medical-grade fractionated MCTs for parenteral nutrition applications. REACH compliance mandates residual solvent thresholds below 50 ppm for refined grades entering cosmetic ingredient supply chains. German cosmetic ingredient buyers disqualify Southeast Asian suppliers lacking third-party audited extraction facility certifications.
India
Household consumption concentrates on 500ml to 1-liter virgin oil formats for cooking and hair care across Maharashtra and Tamil Nadu. BIS certification requirements shape domestic edible oil quality benchmarks and import substitution dynamics. Marico Limited sustains dominant branded positions through extensive rural distribution networks in Kerala and Karnataka processing clusters.
Indonesia
Integrated plantation-to-refinery operations in Sulawesi and North Sumatra secure feedstock continuity for global cosmetic ingredient buyers. Typhoon frequency and drought cycles create raw material availability swings that disrupt contract fulfillment. Cargill Incorporated leverages its integrated supply chain from plantation to refinery across Pacific island economies.
Philippines
Copra processing labor unwinds across Visayas and Mindanao production clusters, tightening virgin oil throughput. Traditional wet-milling expertise concentrates in aging worker populations across Quezon and Bicol regions. Mechanized extraction system investments reshape competitive positioning among mid-scale processors struggling to finance centrifugal and expeller deployments.
Coconut Oil Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated plantation operators commanding premium virgin oil channels while commodity traders dominate refined bulk flows. The market structure fragments across vertically integrated agribusiness conglomerates, regional branded consumer goods specialists, and distributed cooperative processors. Three archetypes define competitive positioning: plantation-integrated refiners with captive laboratory testing capabilities, branded consumer goods companies with rural distribution depth, and equipment-financed cooperative collectives in outer island communities. Dominant competitive moves include mechanized extraction capacity expansion and organic certification timeline acceleration through plantation-backed credit facilities.
Among Philippines-based agribusiness operators, Greenville Agro Corporation anchors premium virgin oil output for North American and European cosmetic ingredient buyers, while Tantuco Enterprises and Celebes Coconut Corporation occupy positions within the integrated processing tier. Marico Limited, an India-based consumer goods company, exemplifies the branded distribution archetype through its extensive rural network penetration. Cargill Incorporated, a US-based agribusiness conglomerate, represents the plantation-integrated refiner model with documented chain-of-custody systems spanning Pacific island supply zones.
| Leading Market Players |
|---|
| Greenville Agro Corporation |
| Marico Limited |
| Cargill Incorporated |
| Tantuco Enterprises |
| The Hain Celestial Group |
| Bunge Limited |
| Celebes Coconut Corporation |
| SC Global Coco Products |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day virgin oil lead times from Philippine Visayas processors concentrate pricing power among integrated plantation operators with captive copra stocks, while spot buyers absorb volatility from typhoon-disrupted harvest cycles. This inventory compression dynamic rewards backward integration and punishes traders lacking upstream control.
Pricing Analysis
Configured-to-order virgin oil with documented polyphenol certificates and organic credentials commands forty-to-sixty percent spreads over standard refined grades in North American cosmetic ingredient procurement. Three-tier pricing structure across premium virgin, standard refined, and economy bulk surfactant grades dominates transaction structures. Cost compression in refined bulk channels is intensifying because Malaysian oleochemical manufacturers switch lauric acid sourcing to palm kernel derivatives. Food manufacturers exhibit highest price sensitivity due to annual contract negotiation frameworks, while pharmaceutical formulators show lowest sensitivity given chain-length purity requirements.
Supply Chain Analysis
Strategic stockpile preferences concentrate among integrated plantation operators in Indonesia and the Philippines, while just-in-time procurement dominates North American cosmetic ingredient buyers with qualified supplier relationships. Supply draws from Sulawesi and North Sumatra in Indonesia, Quezon and Bicol in the Philippines, and Kerala and Tamil Nadu in India. Raw material dependencies center on copra moisture content, lauric acid concentration, and polyphenol retention through extraction. Single-source vulnerability from typhoon exposure in the Philippine Visayas creates contract fulfillment risk. Distribution runs through vertically integrated processors with documented chain-of-custody systems for premium channels, and commodity traders for bulk refined flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification intensity in personal care and pharmaceutical channels fragments procurement authority and creates niche entry points for certified organic processors with laboratory documentation capabilities.
For Market Incumbents: Compound defensive positioning through mechanized extraction capacity expansion in Philippine Visayas and Mindanao clusters, and accelerate organic certification timelines through plantation-backed credit facilities. Palm kernel substitution in Malaysian oleochemical feedstock sourcing threatens lauric acid premium capture. Backward integration into captive copra production secures margin control. For New Entrants and Emerging Players: Lead with direct-to-consumer subscription models targeting Australian and Canadian urban wellness platforms, where virgin oil brands bypass traditional retail markups. White-space concentration sits in medical-grade fractionated MCT channels for German and US hospital nutrition departments. Go-to-market leverage centers on documented chain-length purity certificates and batch-specific analysis documentation. For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates with underutilized virgin oil extraction assets and stranded organic certification investments. Long-term viability favors processors with integrated laboratory testing capabilities and REACH-compliant documentation systems. Watch for EFSA novel health claim approvals as inflection indicators for European nutraceutical channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanized Extraction Capacity Expansion | Centrifugal and expeller deployments in Philippine cooperatives capture premium export margins previously restricted to plantation operations. |
| Organic Certification Timeline Acceleration | Three-year conversion requirements for USDA Organic and EU Organic status constrain new supplier qualification in clean-label cosmetic channels. |
| Fractionated MCT Pharmaceutical Channel Development | Medical-grade caprylic-capric triglycerides with documented C8:C10 ratios serve parenteral nutrition formulations in US and German hospital systems. |
| Direct-to-Consumer Subscription Platform Launch | Virgin oil brands bypass traditional retail distribution through personalized wellness platforms in Australian and Canadian urban markets. |
| REACH Compliance Documentation Investment | Residual solvent testing below 50 ppm and mass balance verification enables European cosmetic ingredient buyer qualification. |
Methodological Framework
Desk research of customs and trade flow databases, BIS and FDA regulatory filings, and EFSA novel food application records preceded structured interviews with virgin oil extraction facility managers, cosmetic ingredient procurement leads at North American personal care brands, pharmaceutical formulators in German hospital nutrition departments, and copra cooperative representatives in Indonesian outer island communities. Secondary validation drew from plantation production statistics, REACH compliance documentation, and organic certification registry data. Bottom-up volume estimates from processing facility capacities triangulated against top-down demand segmentation from end-use application analysis.
Variance decomposition across product type, application channel, and geographic supply zone shaped analytical framework construction throughout the forecast period. Segmentation dimensions modeled include virgin versus refined versus fractionated grades, cosmetics versus food versus pharmaceutical end-uses, and direct sales versus retail distribution channels. CAGRs derived from fitted trend analysis of historical volume trajectories adjusted for regulatory pathway timing and substitution elasticity estimates. Industry-specific forecast inputs incorporated lauric acid price correlation with palm kernel oil spreads and organic certification conversion pipeline visibility.
Forecasts assume regulatory continuity in FDA food and cosmetic safety enforcement, EFSA novel health claim evaluation protocols, and REACH residual solvent thresholds; material policy shifts would require re-modeling of European cosmetic ingredient procurement patterns. Specific risk factors include palm kernel substitution acceleration in Malaysian oleochemical feedstock sourcing, typhoon frequency elevation in Philippine production clusters, and cold-press technician scarcity concentration in aging Kerala and Tamil Nadu worker populations. Revision becomes warranted when palm kernel oil lauric acid yield economics cross substitution threshold margins.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hexane-Free Protein Market
Ingredients
Europe Malt Ingredient Market
Ingredients
Konjac Flour Market
Ingredients
Egg Phosphatidylcholine Market
Ingredients
Plant Protein Ingredients Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
Chickpea Protein Ingredients Market
Ingredients
Kairomones Market
Ingredients
Salad Oil Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
China Corn Glucose Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Tryptose Market
Ingredients
Pig Protein Concentrate Market
Ingredients
Seaweed Extracts Market
Ingredients
North America Dairy Protein Ingredients Market