
 Spain Sodium Reduction Ingredient Market | 2026-2036
Spain Sodium Reduction Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Sodium Reduction Ingredient Market Analytics
The premium natural-extract tier is consolidating against commodity potassium chloride as Spanish food manufacturers face reformulation mandates and clean-label expectations. Cargill leverages its agricultural supply chain to anchor downstream salt-substitute production. Kerry Group specializes in yeast-extract flavor systems that mask off-notes in reduced-sodium recipes. DSM Nutritional Products competes through mineral-based technologies that preserve taste profiles in bakery applications.
Sodium reduction ingredients encompass salt substitutes, flavor enhancers, potassium chloride, and yeast extracts formulated to lower sodium content while maintaining sensory properties in processed foods; potassium chloride typically replaces sodium chloride at 25-40% inclusion rates, often blended with bitter blockers and umami compounds to restore palatability. The powder and granule forms dominate current volume given their compatibility with existing seasoning lines, while liquid formats gain traction in sauce and dressing applications where dispersion uniformity matters. Bakery and processed foods represent the deepest margin pools, though snack applications show the fastest reformulation velocity as brands respond to NAOS labeling thresholds.
Spain's Agency for Food Safety and Nutrition enforces the NAOS strategy sodium reduction targets, while the Ministry of Health coordinates with industry on voluntary reformulation timelines that increasingly harden into procurement requirements. EFSA sodium intake benchmarks shape product development specifications for exporters targeting broader European retail channels. Stakeholders must monitor whether Spanish regulators accelerate mandatory caps beyond current voluntary commitments, as this timing will determine capacity investment priorities for domestic ingredient suppliers.
Market Dynamics
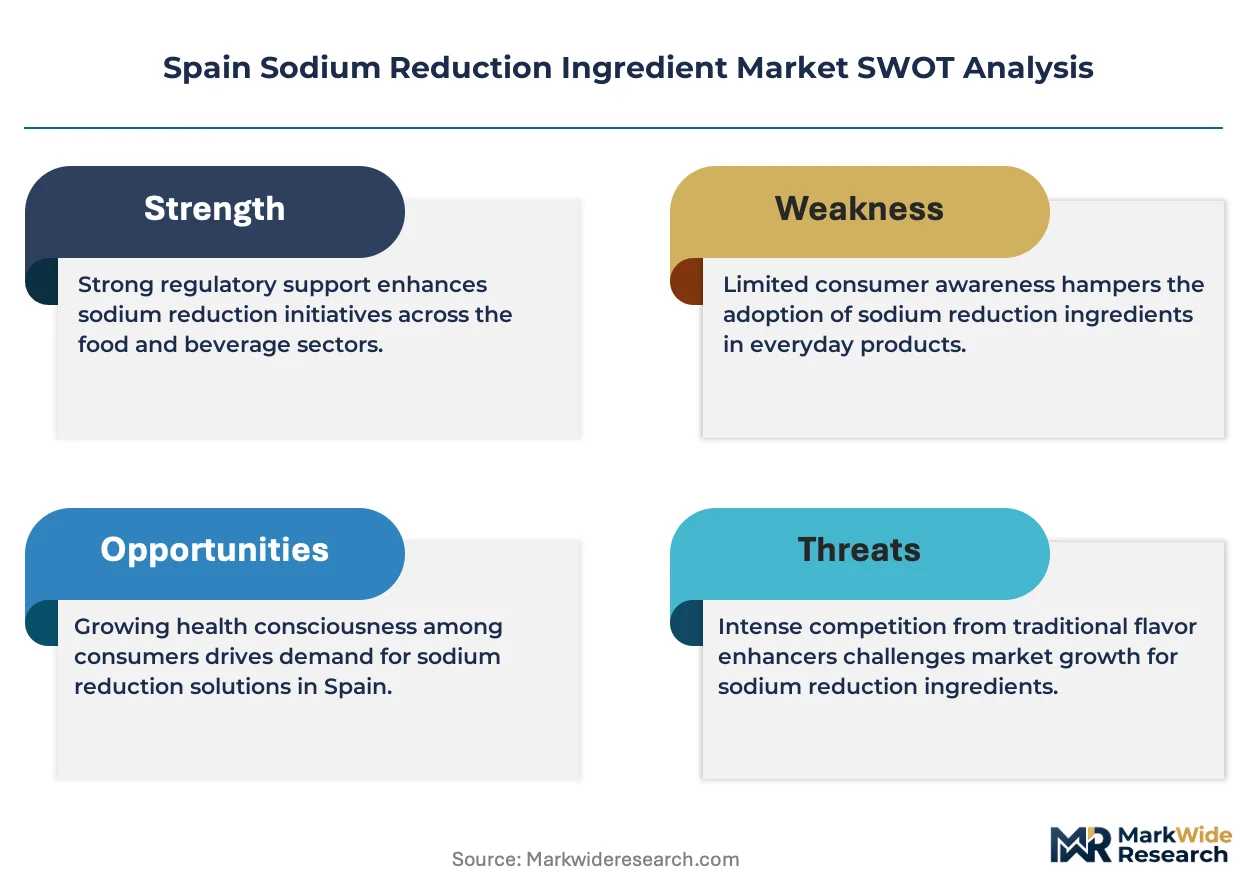
Spain's NAOS strategy front-of-pack labeling rules are forcing packaged food manufacturers into accelerated sodium reformulation cycles, compressing supplier qualification timelines and reshaping procurement criteria across Catalonia's bakery clusters and Basque processed meat corridors.
Growth Catalysts
- EFSA sodium benchmarks:Exporters targeting broader European retail channels must meet these specifications, pulling Spanish ingredient suppliers toward certified production lines.
- Yeast-extract flavor systems:These technologies mask potassium chloride off-notes in reduced-sodium bread recipes, enabling cleaner-label positioning for manufacturers.
- Catalonia bakery concentration:Dense packaged bread production in Barcelona and Lleida provinces creates localized demand pull for salt-substitute ingredients.
Market Restraints
- Potassium chloride price volatility:Agricultural input costs for this primary salt substitute fluctuate with fertilizer market cycles, squeezing margin predictability for formulators.
- Bitter blocker supply concentration:Specialty compounds that mask metallic aftertastes source from limited European chemical suppliers, creating single-source vulnerabilities.
- Mineral taste ceiling:Potassium chloride cannot exceed 40% sodium replacement rates without triggering consumer rejection, capping reformulation depth.
Strategic Opportunities
- Andalusia processed seafood:Canned fish and shellfish manufacturers in Cádiz and Huelva provinces remain underpenetrated for sodium reduction solutions.
- Liquid format sauces:Dressing and condiment applications in Madrid's food service corridor show rising demand for dispersion-uniform sodium reduction systems.
- Ministry of Health procurement mandates:Voluntary reformulation timelines are hardening into institutional purchasing requirements for school and hospital food contracts.
Industry Challenges
- Sensory scientist scarcity:Spain's food technology programs produce insufficient flavor chemists trained in sodium-reduction palatability mapping.
- Clean-label certification timelines:EU organic and natural claim verifications for new mineral-based ingredients extend product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Sodium Reduction Ingredient Market |
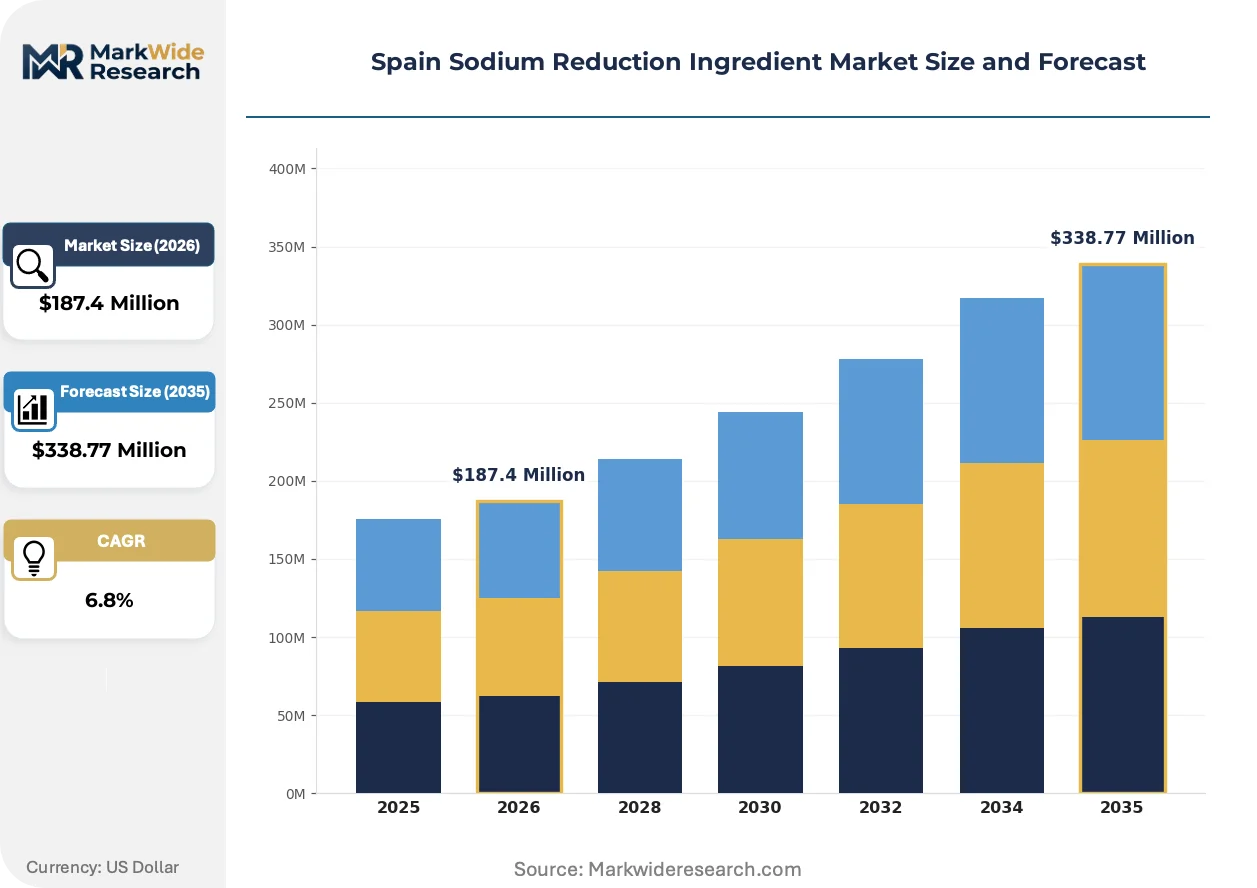
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salt Substitutes, Flavor Enhancers, Potassium Chloride, Yeast Extract Application: Bakery, Sauces, Snacks, Processed Foods Form: Powder, Granules, Liquid, Paste End User: Food Manufacturers, Restaurants, Retailers, Consumers |
| Companies Covered | Sodium Reduction Ingredients (SRI) Group, DSM Nutritional Products, Tate & Lyle, Ingredion Incorporated, Kerry Group, Cargill, Givaudan, Barcelonesa Food Ingredients, Ajinomoto, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Sodium Reduction Ingredient Market Evolving Landscape
Spanish sodium reduction ingredient development is pivoting from simple salt substitution toward integrated flavor-reconstruction systems that preserve sensory integrity while meeting tightening NAOS labeling thresholds.
Potassium chloride blends with bitter-blocking peptides and umami nucleotides are consolidating as the dominant technical approach for mid-sodium bakery applications. Catalonia's industrial bread producers have adopted these systems at scale since 2023. The technology is consolidating commodity potassium chloride suppliers into downstream formulation partnerships with flavor houses.
Spain's Agency for Food Safety and Nutrition is tightening NAOS strategy enforcement timelines, converting voluntary sodium reduction commitments into de facto procurement prerequisites for public sector food contracts. Packaged bread and processed meat manufacturers face compressed reformulation deadlines. Basque Country cured meat producers are responding by pre-qualifying multiple salt-substitute suppliers simultaneously.
Direct ingredient sourcing from yeast-extract and mineral specialists is displacing traditional distributor intermediaries among mid-size Spanish food manufacturers. Madrid-based sauce and dressing producers now contract directly with Kerry Group and DSM Nutritional Products for customized sodium reduction systems. This channel compression is most visible in the snack segment, where brands reformulate rapidly to exploit NAOS-compliant labeling advantages.
Spain Sodium Reduction Ingredient Market Segmentation
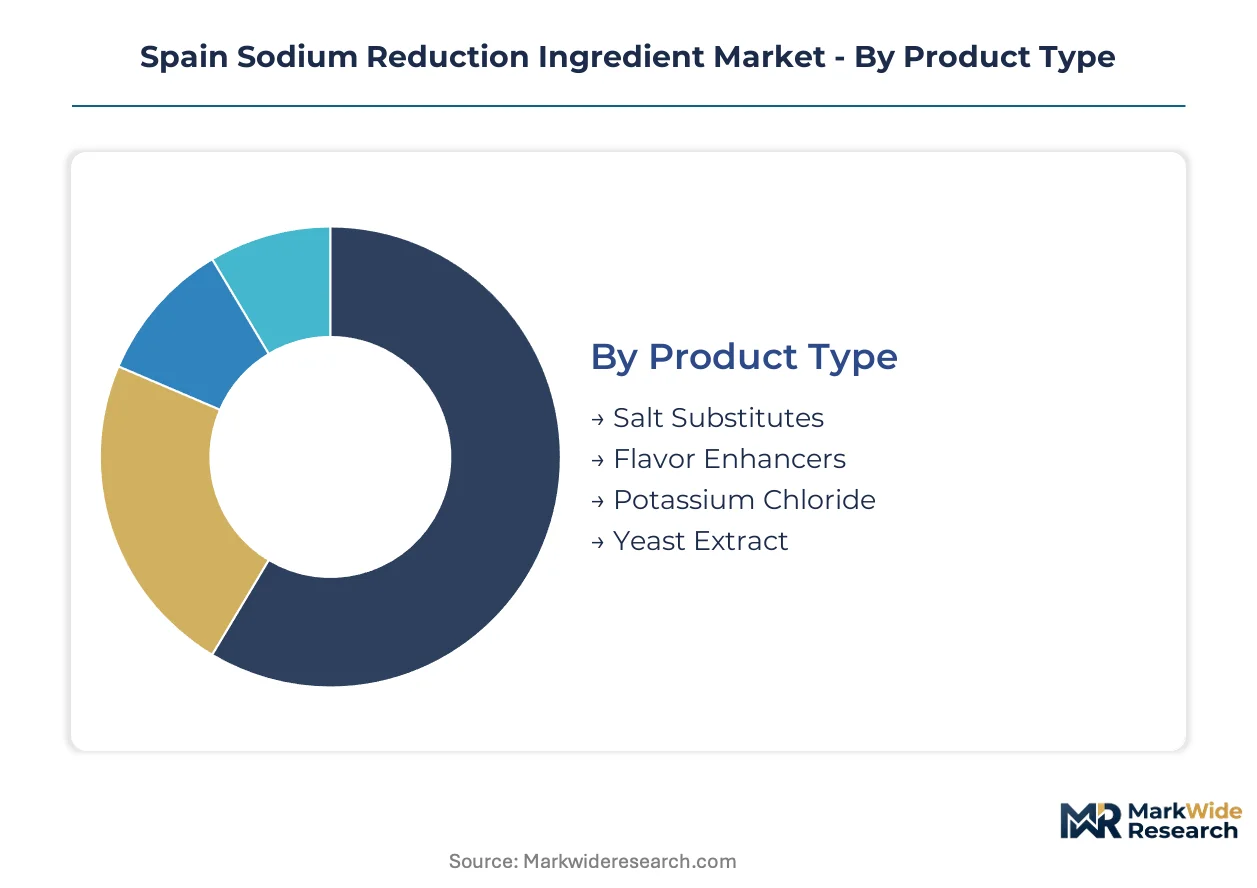
Sodium reduction ingredient procurement in Spain fragments across four distinct classification axes. Each dimension shapes supplier selection criteria, capital deployment patterns, and regulatory compliance pathways for reformulating manufacturers.
Product Type:
Potassium chloride and yeast-extract systems demand the heaviest upfront investment in flavor-chemistry R&D and bitter-masking patent portfolios.
- Yeast Extract:Umami-rich autolyzed derivatives deliver sodium-free savory depth. Catalonia's industrial bread producers source these systems from Kerry Group to mask potassium chloride metallic notes in reduced-sodium pan de molde formulations.
- Flavor Enhancers:Nucleotide and peptide-based compounds amplify salt perception at lower inclusion rates. Basque cured-meat processors deploy these technologies to maintain jamon serrano sensory profiles while meeting NAOS labeling thresholds.
- Salt Substitutes:Mineral blends replace sodium chloride at 25-40% rates. Madrid-based sauce manufacturers blend these with bitter blockers for dispersion-uniform reformulation.
- Potassium Chloride:The primary commodity salt substitute. Agricultural supply chains from Cargill anchor downstream production for Spanish bakery clusters.
Potassium chloride absorbs the bulk of installed capacity; yeast extract is expanding most quickly.
Application:
Margin structures vary sharply across end-use categories, with bakery commanding premium formulation fees and snacks driving volume throughput.
- Bakery:Packaged bread reformulation requires precise sodium replacement to preserve gluten structure and fermentation kinetics. Barcelona and Lleida production corridors source integrated salt-substitute systems from DSM Nutritional Products for clean-label positioning.
- Processed Foods:Canned seafood and ready-meal manufacturers in Andalusia represent underpenetrated demand for sodium reduction solutions. Cádiz and Huelva processors face emerging NAOS procurement pressure for institutional contracts.
- Snacks:Potato chip and cracker brands reformulate rapidly to exploit front-of-pack labeling advantages. The segment shows steepest expansion trajectory as manufacturers pre-qualify multiple salt-substitute suppliers.
- Sauces:Dressing and condiment applications in Madrid's food service corridor demand liquid-format sodium reduction systems with dispersion uniformity.
Bakery commands the deepest margin pools; snacks are climbing the fastest on reformulation velocity.
Form:
Equipment retrofit costs determine form selection, with powder systems leveraging existing seasoning lines and liquid formats requiring new dosing infrastructure.
- Powder:Dominant volume format compatible with standard seasoning equipment. Catalonia bakery clusters process these through existing pneumatic conveying systems without capital expenditure.
- Granules:Free-flowing crystalline structures prevent caking in high-humidity production environments. Basque meat processors favor these for dry-cure applications.
- Liquid:Emerging format for sauce and dressing applications where homogeneous dispersion matters. Madrid manufacturers contract directly with flavor houses for customized systems.
- Paste:Concentrated semi-solid formats for artisanal and small-batch producers. Limited penetration outside specialty food service channels.
Powder and granules absorb the bulk of installed capacity; liquid is gaining share fastest on food service demand.
End User:
Procurement sophistication stratifies sharply, with food manufacturers driving technical specification and retailers imposing labeling compliance downstream.
- Food Manufacturers:Primary demand source with dedicated R&D teams and direct supplier relationships. Mid-size Spanish brands now bypass distributors to contract with Kerry Group and DSM Nutritional Products.
- Restaurants:Chain operators face institutional procurement mandates from Spain's Ministry of Health for school and hospital food contracts. Reformulation timelines compress supplier qualification windows.
- Retailers:Supermarket private-label buyers impose NAOS-compliant specifications on contract manufacturers. Mercadona and Carrefour España push sodium thresholds into procurement requirements.
- Consumers:Direct retail purchases of salt substitutes remain marginal. Health-conscious households in Madrid and Barcelona drive limited specialty channel volume.
Food manufacturers absorb the bulk of supplier attention; restaurants are expanding most quickly on institutional mandate conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barcelona and Lleida anchor Spain's sodium reduction ingredient demand through Catalonia's dense packaged bread production corridors. The country's regional fragmentation shapes supplier deployment patterns across four distinct industrial geographies.
Catalonia
Industrial bread manufacturers in Barcelona and Lleida provinces drive concentrated demand for potassium chloride blends and yeast-extract masking systems. Spain's Agency for Food Safety and Nutrition enforces NAOS strategy sodium thresholds that compress reformulation timelines for local producers. DSM Nutritional Products and Kerry Group maintain direct supply relationships with mid-size brands bypassing traditional distributors.
Basque Country
Cured meat processors in Guipúzcoa and Vizcaya provinces deploy flavor enhancers to preserve jamon serrano sensory profiles under tightening labeling rules. EFSA sodium intake benchmarks shape product specifications for Basque exporters targeting broader European retail channels. Local meat clusters pre-qualify multiple salt-substitute suppliers simultaneously to hedge procurement risk.
Madrid
Sauce and dressing manufacturers in the capital's food service corridor show rising demand for liquid-format sodium reduction systems. The Ministry of Health coordinates voluntary reformulation timelines that harden into institutional purchasing requirements for school and hospital contracts. Direct contracting with flavor houses displaces distributor intermediaries among mid-size producers.
Andalusia
Canned seafood processors in Cádiz and Huelva provinces represent underpenetrated demand for sodium reduction solutions. Emerging NAOS procurement pressure for institutional contracts is pulling reformulation activity into the region. Cargill's agricultural supply chain anchors downstream salt-substitute production for expanding seafood manufacturing.
Spain Sodium Reduction Ingredient Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and clean-label certification depth. The market structures around three tiers: agricultural-commodity suppliers with captive mineral production, flavor-specialist houses with bitter-masking patent portfolios, and integrated nutrition platforms with direct manufacturer relationships. Dominant competitive moves include backward integration into yeast-extract fermentation capacity and strategic partnerships with Catalonia bakery clusters for co-development agreements.
Within the integrated nutrition tier, DSM Nutritional Products and Kerry Group exemplify the shift toward direct manufacturer contracting. Cargill occupies a position bridging agricultural supply security with downstream formulation partnerships. These three anchors represent distinct archetypes: mineral-based taste preservation, yeast-extract flavor reconstruction, and supply-chain-integrated commodity positioning.
| Leading Market Players |
|---|
| Sodium Reduction Ingredients (SRI) Group |
| DSM Nutritional Products |
| Tate & Lyle |
| Ingredion Incorporated |
| Kerry Group |
| Cargill |
| Givaudan |
| Barcelonesa Food Ingredients |
| Ajinomoto |
| Others |
Value Network & Pricing Analysis
Yeast-extract fermentation capacity expansion in Catalonia and the Basque Country simultaneously compresses unit economics for flavor-masking systems and concentrates procurement leverage among three integrated suppliers. Potassium chloride commodity streams from Cargill's agricultural network anchor downstream pricing, while specialty bitter-blocker sourcing from limited European chemical houses creates tiered cost structures across formulation complexity levels.
Pricing Analysis
Outcome-based pricing tied to sodium-reduction yield rates in finished bread and cured-meat applications anchors commercial negotiations. Three-tier pricing structure across premium, standard, and economy levels separates clean-label certified yeast extracts from commodity potassium chloride and unmasked mineral blends. Cost compression in the standard tier is intensifying because agricultural input volatility feeds directly into salt-substitute base costs. Mid-size food manufacturers in Madrid's sauce corridor show highest price sensitivity, while Catalonia's industrial bakeries prioritize sensory performance over unit cost.
Supply Chain Analysis
Flavor chemist scarcity in Barcelona and Lleida provinces constrains production scaling for integrated sodium-reduction systems. Supply concentrates in Germany and the Netherlands for specialty bitter-blocking compounds, while potassium chloride feeds from Cargill's North American and South American agricultural operations. Single-source vulnerability runs through the limited European suppliers of peptide-based taste modulators. Distribution runs through direct manufacturer contracting that displaces traditional ingredient distributors among reformulating Spanish food producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized fermentation capacity for yeast-extract flavor systems operates at effective utilization ceilings, propping pricing power for qualified suppliers. This supply constraint shapes strategic positioning across all participant archetypes.
For Market Incumbents: Deepen backward integration into captive yeast-extract fermentation capacity to secure supply continuity against emerging biotech entrants. Defend margin position by pre-qualifying multiple bitter-blocker suppliers simultaneously to hedge single-source exposure from European chemical houses. Prioritize co-development agreements with Catalonia bakery clusters to lock in reformulation partnerships before NAOS mandates harden.
For New Entrants and Emerging Players: Begin with Andalusia's underpenetrated canned seafood processors in Cádiz and Huelva provinces, where institutional procurement pressure is emerging but supplier relationships remain unconsolidated. Target liquid-format sauce applications in Madrid's food service corridor, where dispersion-uniformity requirements favor specialized entrants over commodity suppliers. Lead with direct technical service models that bypass distributor markups and accelerate qualification timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated flavor-reconstruction platforms given the conversion of voluntary NAOS commitments into mandatory procurement thresholds. Long-term viability favors suppliers with simultaneous yeast-extract fermentation capacity and mineral-blend formulation expertise. The signal to watch is Ministry of Health acceleration of sodium caps beyond current voluntary timelines, which would trigger step-function demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yeast-Extract Fermentation | Captive production capacity insulates Kerry Group and DSM Nutritional Products from specialty supplier bottlenecks. |
| Direct Manufacturer Contracting | Channel compression accelerates reformulation timelines for Madrid-based sauce producers bypassing distributors. |
| Co-Development Agreements with Catalonia Clusters | Partnerships with Barcelona bread manufacturers lock in multi-year supply commitments ahead of NAOS enforcement. |
| Clean-Label Certification Investment | EU organic claim verification extends product launch windows but commands premium positioning in Mercadona procurement. |
| Multi-Source Bitter-Blocker Qualification | Pre-qualification with German and Dutch chemical houses reduces single-source vulnerability for Basque meat processors. |
Research Methodology
Independent corroboration across plant managers at Catalonia bakery facilities, procurement leads at Basque cured-meat processors, and technical R&D directors at Madrid sauce manufacturers underwrites the qualitative findings. Secondary validation draws from Spain's Agency for Food Safety and Nutrition NAOS strategy documentation, EFSA sodium intake benchmark publications, and customs records tracking potassium chloride import flows. Bottom-up demand modeling from individual reformulation projects triangulates against top-down market sizing from ingredient supplier capacity disclosures.
Comparable-period anchoring to historical NAOS strategy implementation phases shapes the projection horizon, with segmentation modeling across product type, application, form, and end-user sophistication. CAGRs derive from weighted average of volume trajectories in bakery, processed foods, snacks, and sauces, calibrated against EFSA benchmark adoption curves and Ministry of Health procurement mandate conversion timelines. Industry-specific forecast inputs include yeast-extract fermentation capacity utilization rates and potassium chloride agricultural input cost cycles.
Underlying measurement precision varies by segment; yeast-extract systems carry tighter precision than commodity potassium chloride given concentrated supplier disclosure. Forecasts reflect assumptions about NAOS enforcement acceleration and EFSA benchmark harmonization across European retail channels. Material deviation in Ministry of Health mandatory cap timing or bitter-blocker supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Dry Blended Products Market
Ingredients
Sesame Oil Market
Ingredients
Cholesterol API Market
Ingredients
Bulk Food Ingredients Market
Ingredients
Algae Omega-3 Ingredients Market
Ingredients
Vegan Ingredients Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
USA Yeast Extracts Market
Ingredients
United Kingdom Protein Market
Ingredients
Europe Insoluble Dietary Fibers Market
Ingredients
2'-Fucosyllactose (2'-FL) Market
Ingredients
Virginiamycin Market
Ingredients
China Corn Glucose Market
Ingredients
Ingredients Market
Ingredients
Peanut Ingredients Market
Ingredients
Native Whey Protein Ingredients Market