
 Terminalia Extract Market | 2026-2036
Terminalia Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Terminalia Extract Market Analytics
Raw material sourcing and toll extraction revenue is fragmenting across South Asian supply bases and North American finishing facilities. Arjuna Natural Extracts Ltd. anchors its position through backward integration into Kerala and Tamil Nadu bark collection networks. Sabinsa Corporation differentiates via U.S.-based cGMP extraction and patented bioavailability enhancement technologies. Hawaii-Pharm competes through small-batch liquid extract specialization targeting naturopathic practitioners.
Terminalia extract comprises concentrated phytochemical preparations derived from Terminalia chebula, Terminalia arjuna, and Terminalia bellerica species, typically standardized to gallic acid, ellagic acid, or arjunolic acid content via solvent or supercritical CO2 extraction for antioxidant, cardioprotective, and gastrointestinal applications. Powder formulations dominate bulk pharmaceutical and functional food ingredient procurement due to stability and blending compatibility, while liquid extracts sustain faster growth in direct-to-consumer wellness channels where dosing flexibility matters. Capsule segments occupy concentrated margin pools as branded supplement manufacturers seek finished dosage forms with validated dissolution profiles.
India's CDSCO mandates botanical drug master file submissions for pharmaceutical-grade extracts, while the U.S. FDA enforces cGMP and NDI notification requirements that filter out under-documented suppliers. The European Medicines Agency's Community Herbal Monographs for Terminalia species create compliance benchmarks that determine market access for standardized extracts. Stakeholders must monitor evolving pharmacopeial harmonization between Indian Ayurvedic Pharmacopoeia standards and European Pharmacopoeia acceptance criteria to anticipate qualification barriers.
Market Dynamics
Pharmaceutical formulators in Germany and the United States are tightening procurement specifications around Terminalia chebula and Terminalia arjuna extracts, forcing extraction facilities to document phytochemical standardization to gallic acid, ellagic acid, and arjunolic acid benchmarks.
Growth Catalysts
- EMA Community Herbal Monographs:The European Medicines Agency's herbal monograph requirements for Terminalia species create compliance benchmarks that determine market access for standardized extracts, pulling pharmaceutical-grade procurement toward documented suppliers.
- Cardioprotective formulation demand:Botanical drug developers in Germany and the United States are expanding procurement of Terminalia arjuna extracts for validated dissolution profiles in finished dosage forms.
- Karnataka and Kerala cultivation networks:Contract cultivation clusters in these Indian states supply raw material to extraction facilities, concentrating quality-controlled bark and fruit sourcing.
Market Restraints
- Wild-harvested bark supply volatility:Terminalia arjuna bark collection depends on seasonal harvesting cycles in Kerala and Tamil Nadu, creating input cost fluctuations and volume uncertainty.
- CDSCO master file documentation burden:India's Central Drugs Standard Control Organization mandates botanical drug master file submissions that filter out under-resourced extraction facilities.
- Synthetic antioxidant substitution:Butylated hydroxytoluene and butylated hydroxyanisole remain cost-competitive alternatives in functional food applications, pressuring natural extract pricing.
Strategic Opportunities
- Direct-to-consumer liquid extract channels:Naturopathic practitioner networks and wellness platforms represent underpenetrated distribution for small-batch Terminalia preparations with dosing flexibility.
- U.S. FDA NDI notification pathway:The New Dietary Ingredient notification framework creates first-mover advantages for extract suppliers with validated safety documentation.
- Supercritical CO2 and ethanol extraction convergence:Combining these technologies enables tunable selectivity for gallic acid and ellagic acid fractions, opening pharmaceutical-grade contract manufacturing.
Industry Challenges
- Pharmacopeial harmonization skill gaps:Bridging Indian Ayurvedic Pharmacopoeia standards with European Pharmacopoeia acceptance criteria requires regulatory affairs specialists scarce in South Asian extraction facilities.
- cGMP certification capex intensity:U.S.-based extraction and finishing facilities require capital deployment for equipment validation and quality management systems.
- Raw material identity testing complexity:Adulteration of Terminalia chebula with related Combretaceae species demands HPLC and DNA barcoding capabilities that strain quality control timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terminalia Extract Market |
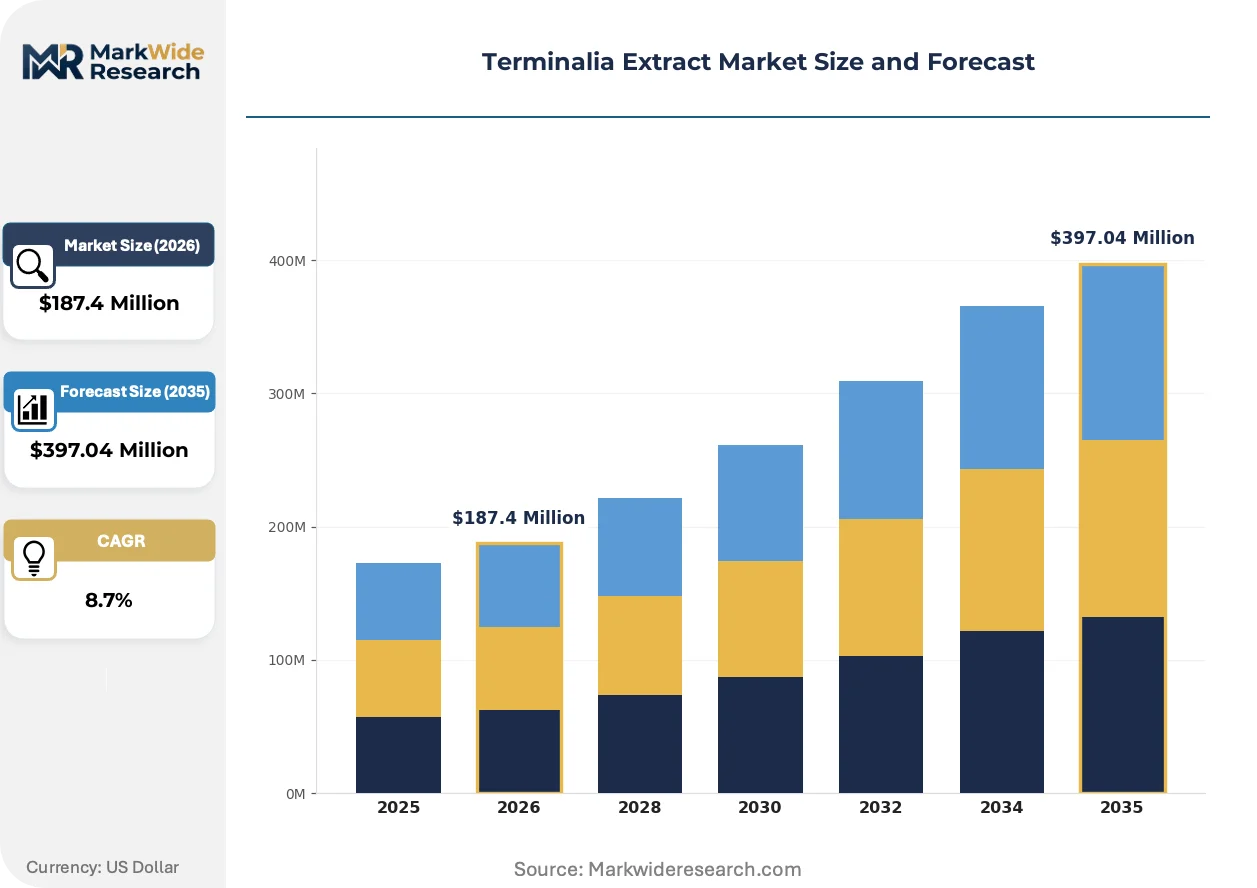
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Extract Application: Dietary Supplements, Cosmetics, Pharmaceuticals, Functional Foods End User: Individuals, Health Professionals, Manufacturers, Retailers Distribution Channel: Online, Offline, Specialty Stores, Pharmacies |
| Companies Covered | Arjuna Natural Extracts Ltd., Sabinsa Corporation, Hawaii-Pharm, Charkit Chemical Company, Herbal Hills, LifeSeasons, La-Medicca (India) Private Limited, Thangam Extracts, Nucleus Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terminalia Extract Market Evolving Landscape
Extraction technology and regulatory documentation requirements are compressing competitive differentiation from raw material access toward validated phytochemical profiles and bioavailability enhancement.
Supercritical CO2 extraction with ethanol co-solvent modification is rendering obsolete conventional solvent extraction for high-value Terminalia fractions. Pharmaceutical formulators in Germany are adopting this technology for gallic acid standardization at commercial scale. The shift is compressing margins for facilities dependent on hexane or methanol extraction infrastructure.
REACH registration requirements for botanical substances are reshaping import documentation for European compounders sourcing Terminalia extracts. The European Chemicals Agency's substance evaluation process demands analytical characterization that many South Asian suppliers cannot furnish. German and Swiss finished product manufacturers are consolidating procurement toward REACH-registered extractors with full dossier support.
Naturopathic practitioners are consolidating purchasing through specialized liquid extract distributors rather than sourcing bulk powders for in-house compounding. Hawaii-Pharm and comparable specialists are capturing this channel with small-batch, alcohol-based preparations. This behavioral shift is most visible in North American direct-to-consumer wellness markets where dosing flexibility commands premium positioning.
Terminalia Extract Market Segmentation
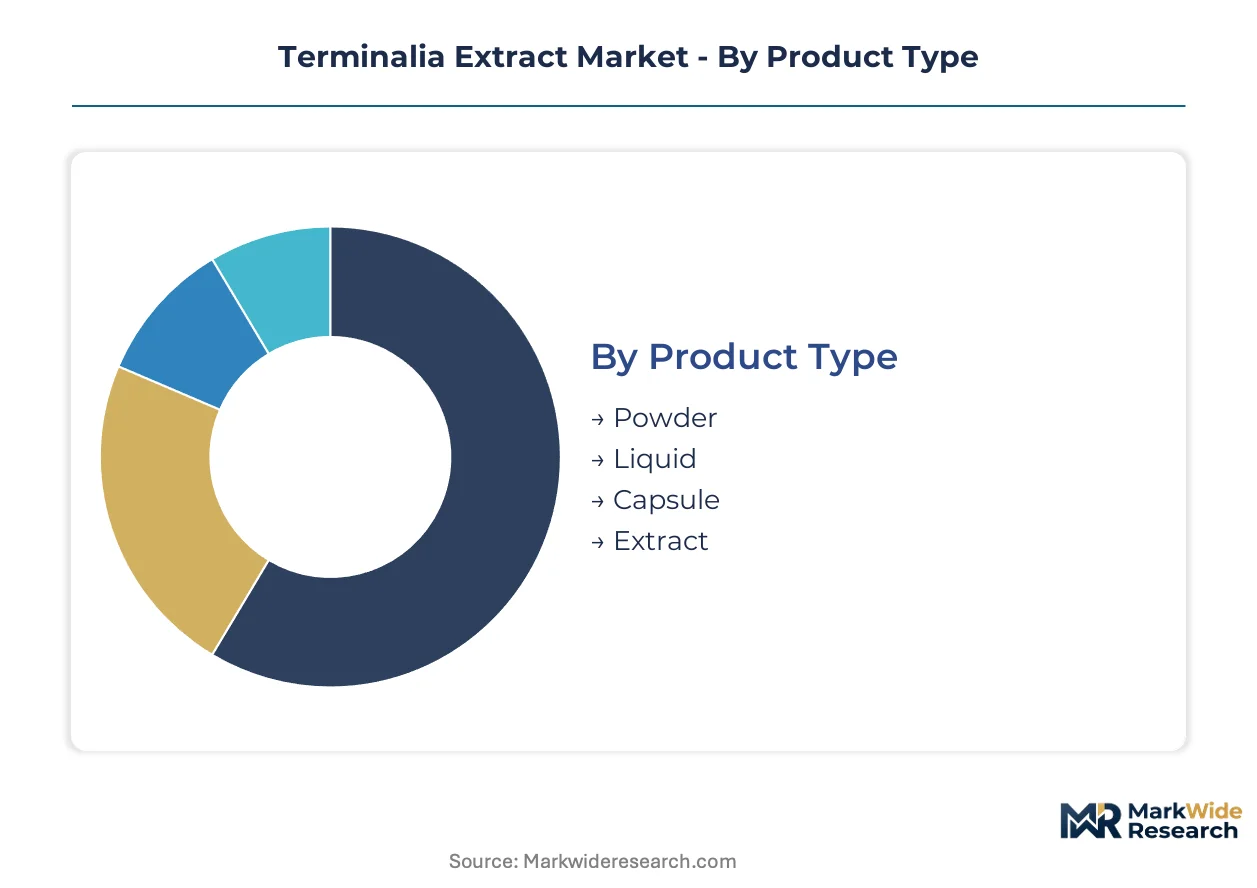
Terminalia extract procurement splits across four distinct axes: physical form determines stability and blending economics, application verticals dictate regulatory compliance intensity, end-user sophistication shapes documentation requirements, and channel structure governs margin capture. Each segmentation dimension carries strategic implications for extraction facility investment and geographic market entry sequencing.
Product Type:
Physical form determines stability profiles, handling economics, and end-use compatibility across pharmaceutical compounding, functional food manufacturing, and direct-to-consumer wellness applications.
- Powder:Spray-dried or freeze-dried preparations standardized to gallic acid or ellagic acid content offer extended shelf stability and homogeneous blending characteristics. Bulk pharmaceutical procurement in Germany and functional food ingredient sourcing in the United States concentrate demand here, though synthetic antioxidant substitution pressure from butylated hydroxytoluene constrains pricing power.
- Liquid:Hydroalcoholic or glycerite preparations enable flexible dosing protocols and faster absorption kinetics. Naturopathic practitioner networks in North American direct-to-consumer channels are consolidating purchasing through specialized distributors like Hawaii-Pharm, where dosing flexibility commands premium positioning.
- Capsule:Hard gelatin or HPMC encapsulations with validated dissolution profiles serve branded supplement manufacturers seeking finished dosage form convenience.
- Extract:Concentrated phytochemical preparations—often resinous or semi-solid—supply downstream formulators requiring high-potency active fractions for pharmaceutical drug master file submissions.
Powder holds installed capacity. Liquid is rotating up the share rankings.
Application:
End-use verticals impose divergent regulatory burdens and quality documentation thresholds that filter supplier qualification.
- Dietary Supplements:Finished products targeting cardiovascular and gastrointestinal wellness applications dominate volume consumption. The U.S. FDA's New Dietary Ingredient notification pathway creates first-mover advantages for extract suppliers with validated safety documentation, while cGMP compliance requirements filter out under-resourced competitors.
- Pharmaceuticals:Botanical drug developers in Germany require EMA Community Herbal Monograph alignment and REACH-registered dossiers for Terminalia arjuna cardioprotective formulations. CDSCO botanical drug master file submissions in India impose parallel documentation burdens that strain South Asian extraction facilities lacking regulatory affairs specialists.
- Cosmetics:Antioxidant active ingredients for topical applications leverage Terminalia chebula's gallic acid content for oxidative stress protection formulations.
- Functional Foods:Natural preservative and nutraceutical fortification applications compete directly with synthetic alternatives, compressing margin structures.
Dietary Supplements captures volume concentration. Pharmaceuticals is climbing the fastest as regulatory documentation barriers concentrate procurement toward qualified suppliers.
End User:
Customer sophistication tiers determine information requirements, purchasing protocols, and price elasticity.
- Individuals:Direct-to-consumer purchasers through online wellness platforms and specialty retail channels prioritize convenience and brand narrative over technical specification sheets.
- Health Professionals:Naturopathic practitioners and integrative medicine clinicians demand batch-specific certificates of analysis and therapeutic dosing guidance, consolidating purchasing through specialized liquid extract distributors.
- Manufacturers:Pharmaceutical formulators and functional food compounders in Germany and the United States impose stringent procurement specifications around phytochemical standardization, forcing extraction facilities to document gallic acid, ellagic acid, and arjunolic acid benchmarks.
- Retailers:Natural product and pharmacy chains require supply chain transparency documentation and third-party certification alignment for shelf placement.
Manufacturers holds qualification concentration. Health Professionals is gaining share fastest as practitioner-channel consolidation accelerates.
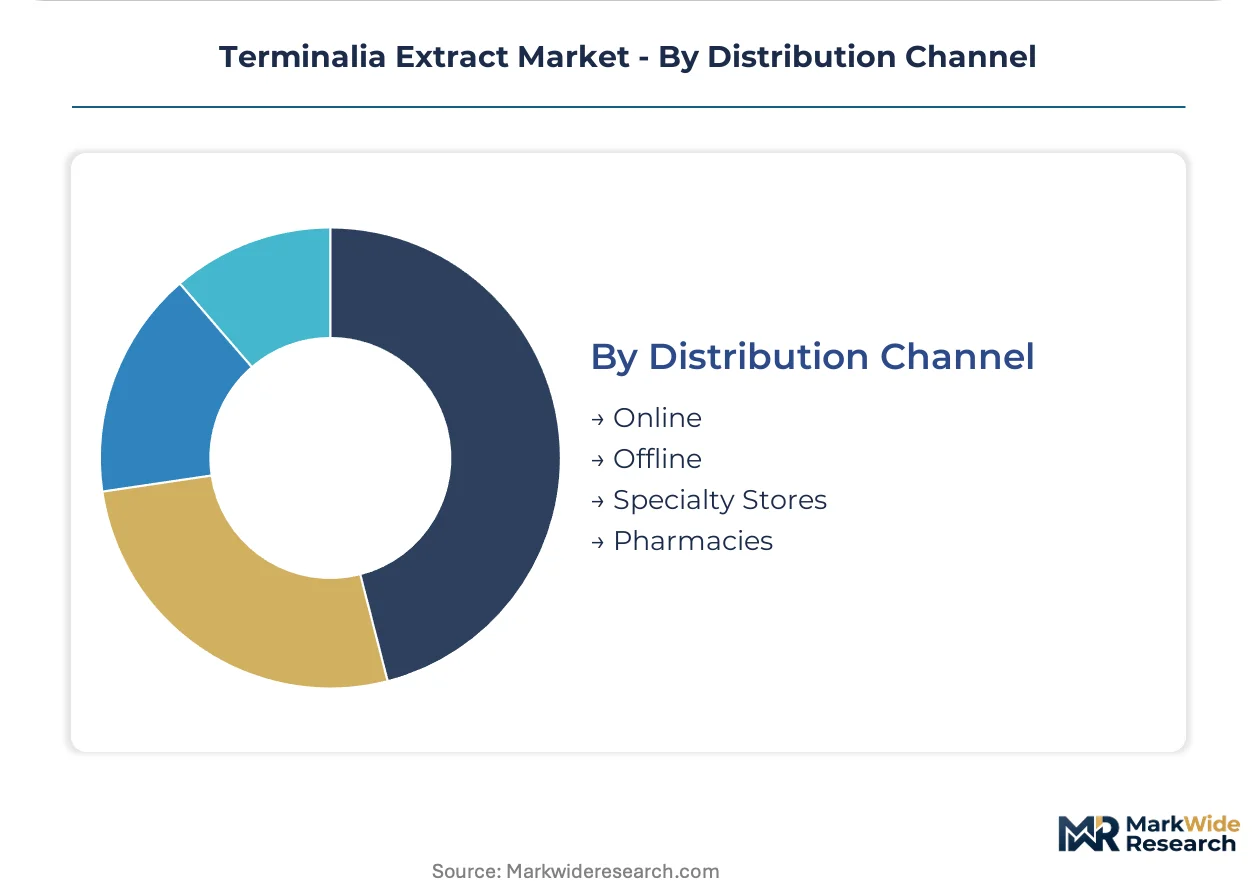
Distribution Channel:
Channel structure governs margin stacking, customer relationship intensity, and inventory risk allocation between extractors and finished product brands.
- Online:Direct-to-consumer platforms and B2B marketplaces enable geographic reach without physical infrastructure investment, though customer acquisition costs and return logistics erode net margins.
- Offline:Traditional wholesale and distributor relationships sustain bulk pharmaceutical and functional food ingredient procurement where relationship trust and supply security dominate purchasing criteria.
- Specialty Stores:Natural product retailers and Ayurvedic medicine shops serve culturally anchored consumer segments with education-intensive sales assistance.
- Pharmacies:Regulated retail environments in Germany and other European markets require pharmacovigilance documentation and professional sales representation for botanical drug positioning.
Offline maintains volume foundation. Online is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India demonstrate the highest price elasticity as wild-harvested bark volatility compresses margins, while German pharmaceutical formulators absorb premium pricing for REACH-registered dossiers. The United States occupies the middle ground, where NDI notification costs filter suppliers but cGMP compliance commands measurable premiums.
United States
Dietary supplement manufacturers and botanical drug developers drive procurement of Terminalia chebula and Terminalia arjuna extracts for cardiovascular and gastrointestinal applications. The FDA enforces cGMP compliance and New Dietary Ingredient notification requirements that filter out under-documented suppliers. Extraction and finishing facilities concentrate in California and New Jersey, where contract manufacturers invest in equipment validation and quality management systems to serve branded supplement companies.
Germany
Pharmaceutical formulators prioritize Terminalia arjuna extracts with validated dissolution profiles for cardioprotective botanical drug applications. The EMA's Community Herbal Monographs for Terminalia species create compliance benchmarks that determine market access, while REACH registration requirements reshape import documentation obligations. Industrial clusters in Bavaria and North Rhine-Westphalia host finished product manufacturers consolidating procurement toward REACH-registered extractors with full dossier support.
India
Contract cultivation networks in Karnataka and Kerala supply raw material to extraction facilities, concentrating quality-controlled bark and fruit sourcing for domestic and export markets. The CDSCO mandates botanical drug master file submissions for pharmaceutical-grade extracts, imposing documentation burdens that strain South Asian facilities lacking regulatory affairs specialists. Extraction capabilities cluster in Tamil Nadu and Maharashtra, where facilities bridge Indian Ayurvedic Pharmacopoeia standards with European Pharmacopoeia acceptance criteria.
Switzerland
Finished product manufacturers source standardized extracts for premium botanical drug and nutraceutical applications where pharmacovigilance documentation commands professional sales positioning. Swissmedic requirements for botanical substances demand analytical characterization that filters supplier qualification toward established extractors. Industrial activity concentrates in Basel and Zurich, where pharmaceutical compounders integrate Terminalia extracts into cardiovascular wellness portfolios.
Canada
Natural health product manufacturers procure Terminalia extracts for antioxidant and digestive health applications targeting practitioner and direct-to-consumer channels. Health Canada and the PMRA enforce natural health product licensing and site licensing requirements that parallel U.S. cGMP intensity. Extraction demand concentrates in Ontario and British Columbia, where facilities serve North American wellness platforms and naturopathic practitioner networks.
Terminalia Extract Market Competitive Landscape
Backward-integrated specialists and technology-differentiated contract manufacturers split the market into distinct competitive spheres. The vendor base compresses toward documented suppliers as regulatory barriers intensify across EMA, FDA, and CDSCO jurisdictions. Three archetypes dominate: Kerala-based bark collection networks with captive raw material access, U.S.-based cGMP facilities with bioavailability enhancement patents, and small-batch liquid extract specialists serving practitioner channels. Competitive moves center on pharmacopeial harmonization investments and supercritical CO2 extraction capacity deployment.
Among India-based extraction specialists, Arjuna Natural Extracts Ltd. exemplifies backward-integrated operations with Kerala and Tamil Nadu sourcing control. Sabinsa Corporation anchors the U.S.-based cGMP tier with patented delivery technologies. Hawaii-Pharm occupies the practitioner-channel specialist position with small-batch liquid extract capabilities targeting naturopathic networks.
| Leading Market Players |
|---|
| Arjuna Natural Extracts Ltd. |
| Sabinsa Corporation |
| Hawaii-Pharm |
| Charkit Chemical Company |
| Herbal Hills |
| LifeSeasons |
| La-Medicca (India) Private Limited |
| Thangam Extracts |
| Nucleus Biotech |
| Others |
Value Network & Pricing Analysis
Wild-harvested bark supply volatility in Kerala and Tamil Nadu determines both the spread between REACH-registered and uncertified extract tiers and the geographic configuration of finishing capacity. Pharmaceutical formulators in Germany absorb premium pricing for dossier-compliant Terminalia arjuna extracts while South Asian toll manufacturers compete on raw material access economics.
Pricing Analysis
After-sales documentation and regulatory filing support drive lifetime value for extraction specialists serving pharmaceutical channels. Three-tier pricing structure across EMA-aligned, cGMP-certified, and uncertified supplier levels reflects documentation burden and batch testing intensity. Cost compression in the uncertified tier is intensifying because synthetic antioxidant substitution pressures natural extract positioning in functional food applications. Manufacturers in Germany demonstrate lowest price sensitivity while Indian domestic buyers exhibit highest elasticity to bark harvest fluctuations.
Supply Chain Analysis
Contract manufacturing concentration rests with Arjuna Natural Extracts Ltd. in Kerala and Tamil Nadu, Sabinsa Corporation in New Jersey, and Hawaii-Pharm in specialized liquid extract batches. Geographic supply concentration centers on India for raw bark and fruit sourcing, the United States for cGMP finishing and formulation, and Germany for REACH-registered botanical drug compounding. Raw material dependencies hinge on Terminalia arjuna bark seasonal harvests, Terminalia chebula fruit collection cycles, and certified organic cultivation contracts. Single-source vulnerability runs through wild-harvested Kerala bark networks. Distribution runs through specialized extract distributors for practitioner channels and direct B2B procurement for pharmaceutical compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terminalia extract demand sits in early-cycle expansion as EMA Community Herbal Monograph adoption pulls pharmaceutical procurement toward standardized botanical drugs. Regulatory documentation requirements favor first movers with validated safety dossiers.
For Market Incumbents: Harden supply security through captive cultivation contracts in Karnataka and Kerala to offset wild-harvest volatility. Deepen EMA and FDA filing capabilities to defend margin position against emerging South Asian competitors with raw material access but weak regulatory affairs capacity.
For New Entrants and Emerging Players: Establish a beachhead in North American direct-to-consumer liquid extract channels where Hawaii-Pharm's small-batch model has demonstrated practitioner network penetration. Target naturopathic distributor consolidation with alcohol-based preparations and batch-specific certificates of analysis as the primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a documentation-intensification phase that favors backward-integrated extraction specialists with pharmacopeial harmonization capabilities. Long-term viability rests on bridging Indian Ayurvedic Pharmacopoeia standards with European Pharmacopoeia acceptance criteria. Acquisition focus should center on Kerala-based bark collection networks with captive raw material access and emerging regulatory affairs capacity. Watch CDSCO master file submission volumes as the inflection signal for qualified supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Harmonization Investment | Bridges Indian Ayurvedic Pharmacopoeia with EMA acceptance criteria for market access. |
| Supercritical CO2 Capacity Deployment | Enables gallic acid standardization that displaces conventional solvent extraction infrastructure. |
| Captive Cultivation Contracting | Secures quality-controlled Terminalia arjuna bark supply in Kerala and Karnataka clusters. |
| NDI Notification Pathway Entry | Creates first-mover advantage for U.S. dietary supplement channel positioning. |
| Practitioner Channel Distributor Partnership | Captures naturopathic network consolidation in North American wellness markets. |
Research Methodology
Operator-level perspectives from extraction facility managers, pharmaceutical regulatory affairs leads, botanical drug formulators, and naturopathic practitioner procurement heads anchored the qualitative base. Primary fieldwork combined with secondary validation through EMA Community Herbal Monograph databases, FDA NDI notification filings, CDSCO botanical drug master file records, and Indian customs export data. Bottom-up capacity and production estimates triangulated against top-down demand segmentation across pharmaceutical, dietary supplement, and functional food verticals.
Scenario-bracketing framed analytical outputs across the projection horizon. Segmentation dimensions modeled include physical form tier, application vertical regulatory intensity, end-user sophistication level, and geographic compliance cluster. CAGRs derived from production capacity buildout timelines, regulatory filing velocity, and end-use demand elasticity estimates. Forecast inputs incorporated EMA monograph adoption curves and supercritical CO2 extraction technology diffusion rates.
Sensitivities concentrate around wild-harvest bark supply disruptions, REACH registration timeline delays, and synthetic antioxidant pricing volatility. Forecasts reflect documented assumptions on cultivation contract expansion and pharmacopeial harmonization progress. Quarterly review of CDSCO master file submission volumes and EMA herbal monograph update cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
United Kingdom Gelatin Market
Ingredients
Fiber Rich Flours Market
Ingredients
Feed Ingredients Market
Ingredients
Non-PHO Ingredients Market
Ingredients
Australia Sodium Reduction Ingredients Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Corn Starch Market
Ingredients
Immunity Support Ingredients Market
Ingredients
Caramel Ingredient Market
Ingredients
Centella Asiatica Extract Market
Ingredients
Vegetable Glycerin Market
Ingredients
Fruit Powder Market
Ingredients
Wheat Starch Market
Ingredients
Fish Peptones Market
Ingredients
Protein Trends and Technologies Market
Ingredients
North America Whey Protein Ingredients Market