
 Corn Silage Market | 2026-2036
Corn Silage Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Silage Market Analysis
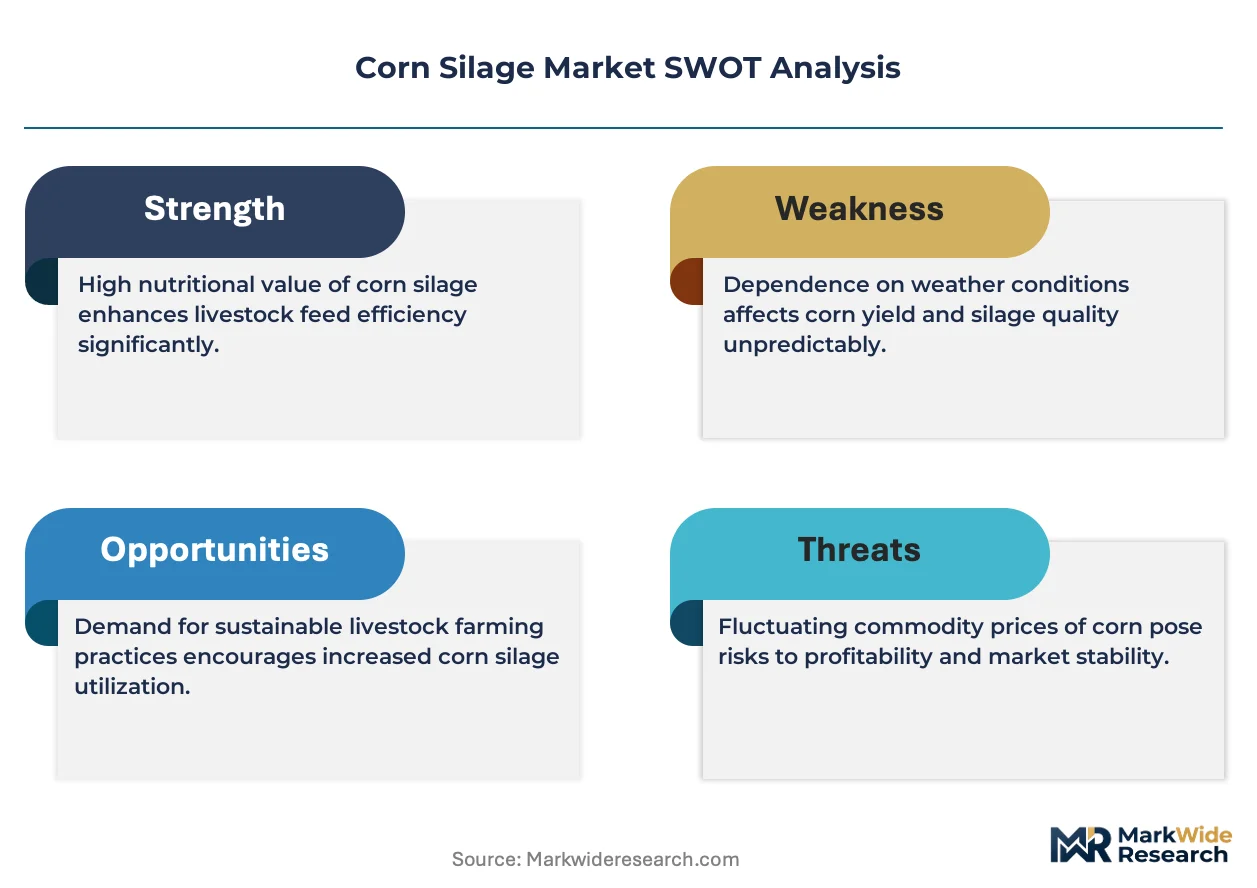
Aftermarket nutrition consulting and feed formulation services is reconfiguring how corn silage suppliers capture value beyond commodity tonnage. Qadir Exports leverages its South Asian sourcing network to supply chopped corn to Middle Eastern dairy operations. Lakkavaram Silage Fodder anchors its position through region-specific baled corn production for Indian cooperative dairies. Krishna Multicomm Private differentiates via direct farmgate relationships that bypass traditional wholesale channels.
Corn silage is fermented, high-moisture fodder made from whole corn plants harvested at 32-38% dry matter, packed anaerobically to preserve nutritional value through lactic acid fermentation for ruminant livestock feed. Chopped corn dominates volume due to faster field throughput and compatibility with bunker silo systems, while fermented corn commands premium positioning among precision-dairy operations seeking enhanced starch digestibility. Dairy farms represent the largest end-user pool, though biogas plants are emerging as a structurally distinct demand segment driven by anaerobic digestion subsidies.
The USDA's Natural Resources Conservation Service shapes on-farm storage compliance through environmental quality incentives, while the EU Green Deal's Farm to Fork Strategy limits chemical fertilizer use on feed crops, altering agronomic practices for silage corn growers. India's FSSAI monitors feed-grade commodity safety standards, creating entry barriers for informal suppliers. Stakeholders must track how carbon accounting methodologies for livestock feed enter national climate plans, as this will determine which packaging and fermentation formats qualify for green financing.
Market Dynamics
Dairy cooperatives in the Upper Midwest are consolidating procurement volumes, squeezing regional silage suppliers into long-term supply contracts with fixed pricing clauses that compress margin flexibility.
Growth Catalysts
- EU Green Deal nitrogen caps:German and Dutch dairy operations must reduce crude protein waste in feed rations, accelerating demand for precision-fermented corn silage with optimized starch digestibility.
- Biogas digester subsidies:Anaerobic digestion plants in Denmark and Italy now source corn silage as primary feedstock, creating a structurally distinct demand channel separate from livestock nutrition.
- Kernel processing technology:Advanced roller mill systems at harvest are improving starch availability in chopped corn, raising per-ton feed value for high-producing Holstein herds.
Market Restraints
- Fertilizer input volatility:Ammonia and potash price swings directly compress silage corn grower margins, forcing acreage shifts into soy or wheat in marginal production zones.
- Storage infrastructure concentration:Bunker silo construction requires significant capital, locking out smallholder dairies in India and fragmenting supply into informal baled segments.
- Alternative forage competition:Alfalfa and sorghum-sudangrass hybrids compete for dairy ration inclusion, particularly in water-stressed regions of Spain and Portugal.
Strategic Opportunities
- Carbon credit monetization:Methane-reduction protocols for feed additives could extend to fermented silage formats, qualifying suppliers for green financing under evolving national climate plans.
- Direct farmgate platforms:Digital procurement networks are bypassing traditional wholesale channels, enabling price transparency for Indian cooperative dairies sourcing from Andhra Pradesh baled producers.
- Biogas feedstock contracting:Long-term offtake agreements with anaerobic digestion facilities in Germany offer volume certainty independent of dairy commodity cycles.
Industry Challenges
- Fermentation quality control:Anaerobic packing expertise remains scarce, causing spoilage losses in bunker silos operated by expanding mid-scale dairies without technical support.
- Moisture testing precision:Field-level dry matter assessment errors at harvest propagate through ration formulation, destabilizing milk production consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Silage Market |
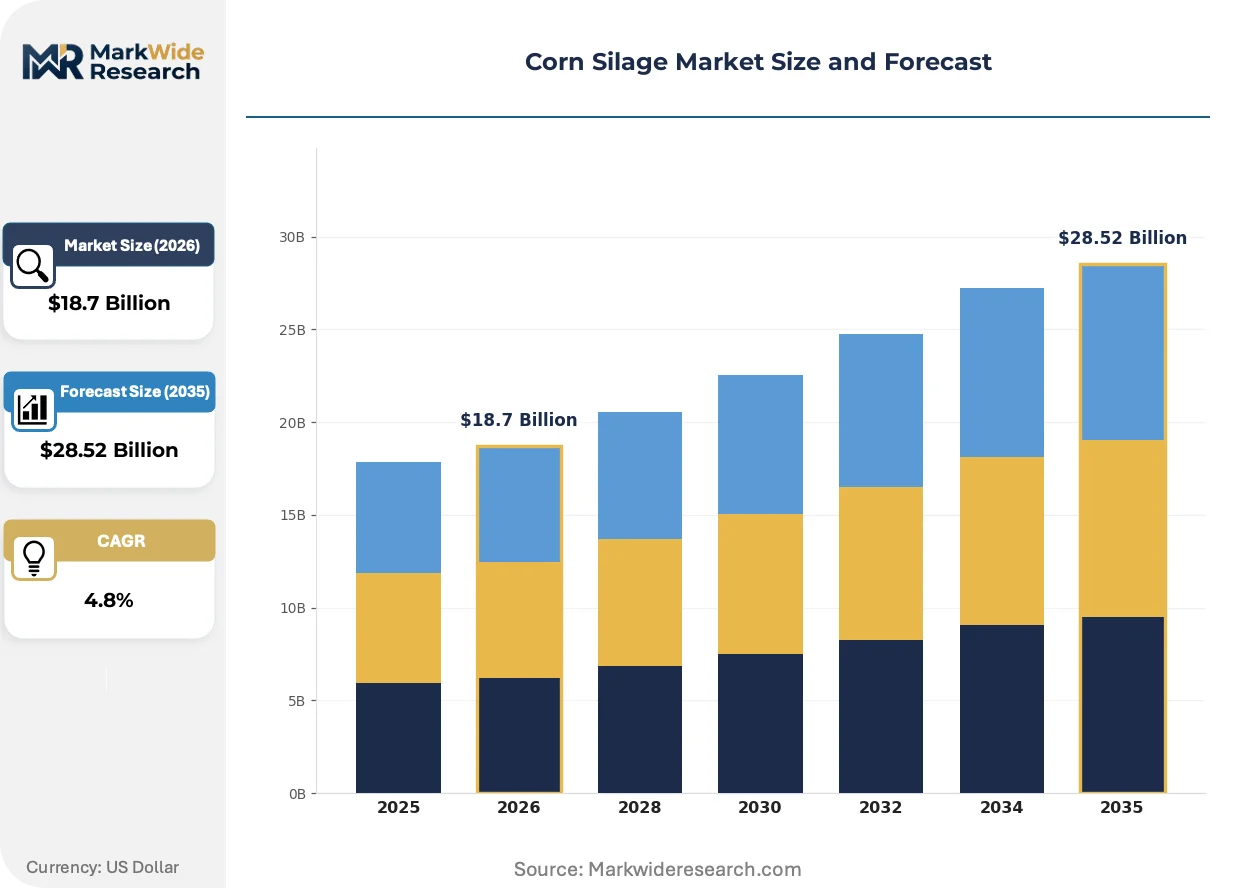
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chopped Corn, Whole Plant Silage, Fermented Corn, Baled Corn End User: Dairy Farms, Beef Cattle Ranches, Biogas Plants, Poultry Farms Packaging Type: Bags, Bales, Bulk, Silos Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Qadir Exports, Bac Quang Trading Investment JSO, United Agro Feeds, Azure Enterprise, Lakkavaram Silage Fodder, HKN Exim, Krishna Multicomm Private, Ambica Enterprise, BF Global Trading, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Silage Market Emerging Trajectories
Silage production is absorbing digital agriculture tools that compress decision cycles from harvest timing through ration optimization, restructuring how nutritional value is captured and priced.
Near-infrared spectroscopy mounted on forage harvesters is digitizing real-time dry matter and starch content mapping during field operations. Large-scale dairy cooperatives in Wisconsin and Minnesota are deploying these systems across contracted acreage, compressing the gap between harvest moisture targets and actual packing conditions. This data layer is digitizing quality assurance, enabling premium pricing tiers tied to verified nutritional metrics rather than commodity tonnage.
The EU Green Deal's Farm to Fork Strategy is tightening chemical fertilizer limits on feed crops, forcing silage corn growers into precision nutrient management. This regulatory pressure is accelerating variable-rate application adoption and cover-crop integration in French and Polish maize zones. Organic and reduced-input silage certifications are emerging as procurement filters for sustainability-linked dairy supply contracts.
Aftermarket nutrition consulting is displacing traditional commodity trading relationships across North American dairy procurement. Independent feed formulation specialists now contract directly with silage suppliers to customize fermentation profiles for specific herd production targets. This service-layer unbundling concentrates in California's Central Valley and New York's Finger Lakes dairy clusters, where milk-over-feed margins drive precision investment.
Corn Silage Market Segmentation
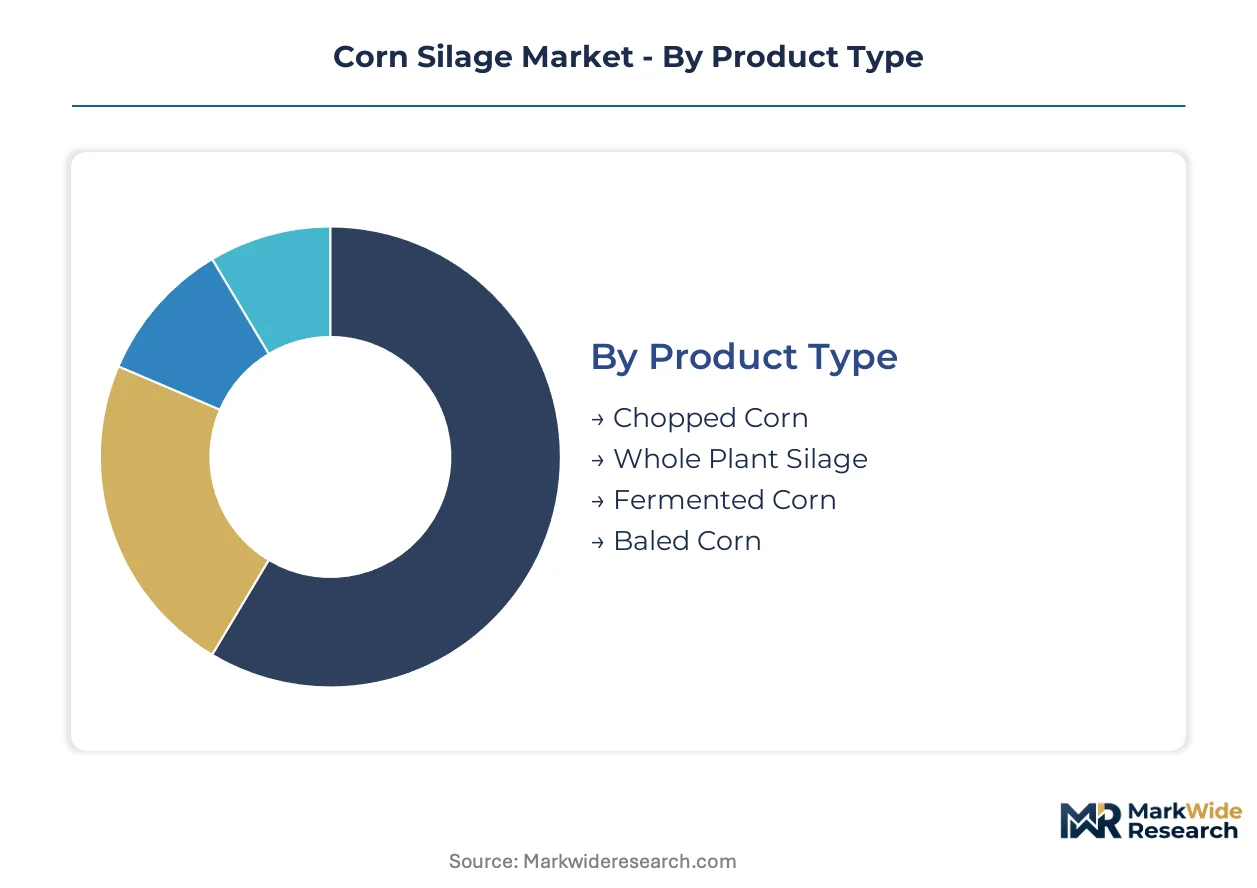
Corn silage procurement patterns diverge sharply across product formats, end-use applications, and distribution channels. Each segmentation axis reveals distinct margin structures and technical requirements that reshape supplier positioning.
Product Type:
Product formats span the use-case spectrum from high-volume field operations to precision-fermented nutrition systems.
- Chopped Corn:Harvested and processed through forage harvesters into 3-8mm theoretical length of cut for rapid bunker silo packing. Dairy cooperatives in Wisconsin and Minnesota concentrate procurement here, driven by kernel processing technology that boosts starch digestibility for Holstein herds.
- Fermented Corn:Anaerobically preserved at 32-38% dry matter with controlled lactic acid fermentation for enhanced feed stability. German and Dutch precision-dairy operations under EU Green Deal nitrogen caps command premium positioning for this format.
- Whole Plant Silage:Entire corn plant harvested and ensiled without grain separation for maximum biomass capture. Biogas digesters in Denmark source this format for methane yield optimization.
- Baled Corn:Wrapped in plastic film for smallholder accessibility without fixed silo infrastructure. Indian cooperative dairies in Andhra Pradesh rely on this format where capital constraints block bunker construction.
The dominant share belongs to Chopped Corn, while Fermented Corn is closing the gap fastest.
End User:
Customer types range from livestock nutrition optimization to renewable energy feedstock conversion.
- Dairy Farms:Largest demand pool requiring starch-dense rations for milk yield maximization. Upper Midwest cooperatives consolidate procurement volumes into long-term supply contracts with fixed pricing clauses.
- Biogas Plants:Structurally distinct demand channel driven by anaerobic digestion subsidies in Italy and Denmark. These facilities source corn silage purely for methane generation rather than nutritional value.
- Beef Cattle Ranches:Backgrounding and finishing operations in the US Great Plains utilizing silage for cost-effective weight gain protocols.
- Poultry Farms:Limited adoption for layer and broiler operations where grain-based concentrates dominate ration economics.
Dairy Farms command the volume lead, though Biogas Plants are expanding most quickly as energy policy tightens.
Packaging Type:
Storage configurations separate capital-intensive permanent infrastructure from flexible seasonal solutions.
- Bulk:Delivered loose for immediate bunker or pile placement without secondary handling. Large-scale operations in California's Central Valley favor this format for labor efficiency.
- Silos:Upright or horizontal sealed structures enabling multi-year storage with minimal spoilage. German farm clusters under strict environmental compliance invest here.
- Bales:Individual wrapped units enabling decentralized storage and transport flexibility. Indian informal supply chains depend on this packaging tier.
- Bags:Polyethylene silage bags for temporary field-edge storage without concrete pad requirements. Mid-scale dairies expanding without technical support utilize this entry-level option.
Bulk handling dominates volume throughput, while Silos capture the steepest expansion trajectory among sustainability-certified operations.
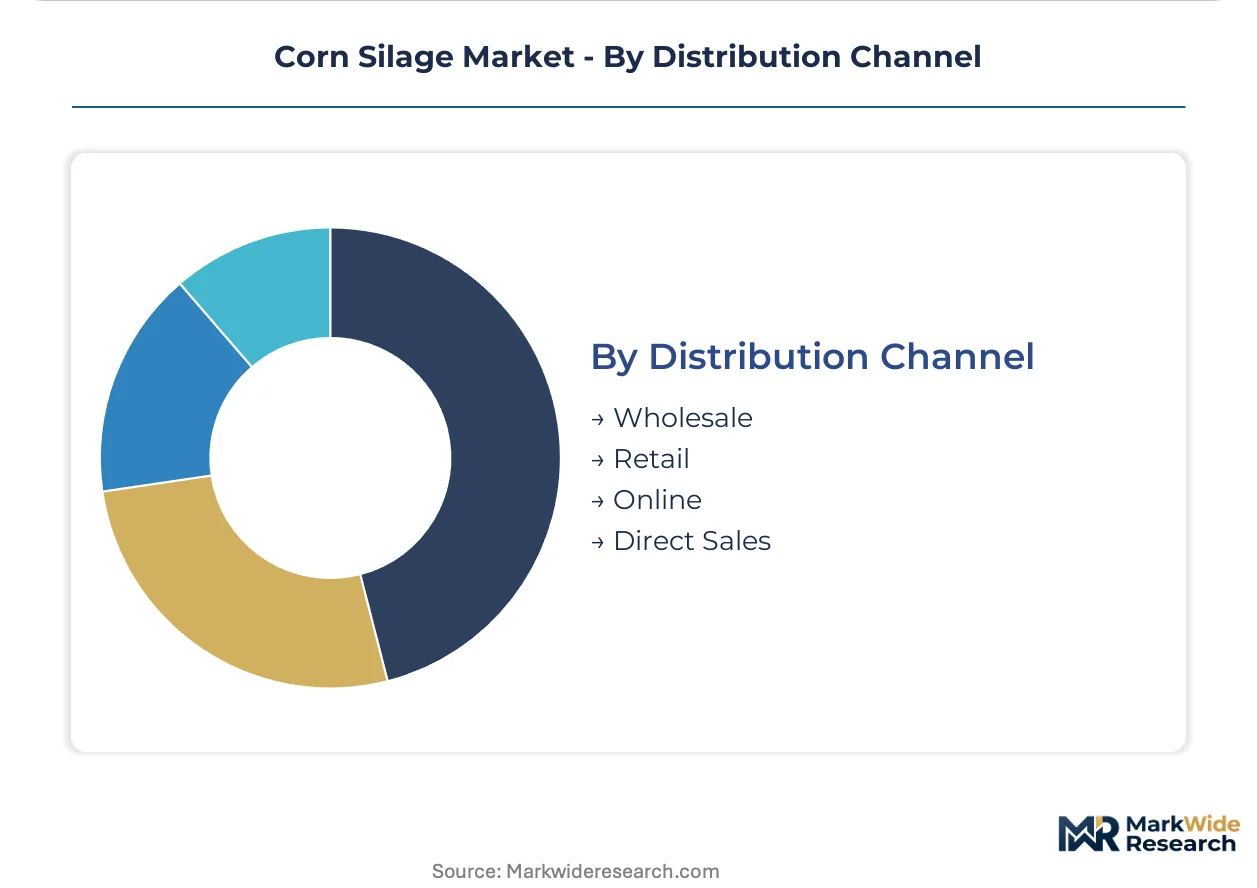
Distribution Channel:
Channel structure determines price transparency and margin capture across fragmented supply bases.
- Direct Sales:Farmgate contracting between silage growers and dairy operations eliminating wholesale markups. Digital procurement platforms in India are accelerating this channel's penetration.
- Wholesale:Aggregator-mediated volume pooling for standardized quality tiers. Traditional procurement in the Upper Midwest runs through this established channel.
- Retail:Bagged and small-bale sales to hobby farms and specialty livestock operations. Limited scale constrains supplier interest.
- Online:Emerging platform-based matching of regional supply with demand transparency. Early-stage adoption concentrates in cooperative dairy clusters seeking price discovery.
Direct Sales holds the dominant position, with Online channels gaining share fastest among tech-enabled procurement networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Indian cooperative dairies negotiate aggressively on baled corn margins, while German precision-dairy operations absorb premiums for fermented silage with verified starch digestibility. The United States sits between these extremes, with Upper Midwest consolidators driving volume discounts while California operations pay for nutrition consulting layers.
United States
Dairy cooperatives in Wisconsin and Minnesota consolidate procurement into long-term contracts with fixed pricing clauses. The USDA Natural Resources Conservation Service shapes on-farm storage compliance through environmental quality incentives. Kernel processing technology deployment concentrates in the Upper Midwest, where advanced roller mill systems raise per-ton feed value for Holstein herds.
Germany
Precision-dairy operations under EU Green Deal nitrogen caps demand optimized starch digestibility and pay premiums for verified fermentation profiles. The Farm to Fork Strategy tightens chemical fertilizer limits on feed crops, forcing precision nutrient management adoption. Variable-rate application technology clusters in Lower Saxony and Bavaria, where large farm cooperatives invest in multi-year silo infrastructure.
India
Capital-constrained smallholder dairies depend on baled corn formats where bunker silo construction is economically inaccessible. The FSSAI monitors feed-grade commodity safety standards, creating entry barriers for informal suppliers. Andhra Pradesh baled producers supply cooperative dairies through emerging digital procurement networks that bypass traditional wholesale markups.
Denmark
Anaerobic digestion subsidies drive structurally distinct demand from biogas plants sourcing whole plant silage for methane yield optimization. National energy policy treats agricultural feedstock as strategic renewable infrastructure. Jutland farm clusters now contract directly with digester operators, decoupling silage value from dairy commodity cycles.
Italy
Biogas digester expansion in the Po Valley creates alternative offtake channels independent of livestock nutrition demand. EU renewable energy directives accelerate anaerobic digestion capacity additions. Emilia-Romagna agricultural zones reconfigure crop rotations to supply both dairy rations and methane generation facilities.
Corn Silage Market Vendor Landscape
Capability concentration sits with nutrition consulting specialists who customize fermentation profiles; scale advantage sits with commodity aggregators who pool volumes across fragmented grower bases. The vendor base spans South Asian exporters, regional baled producers, and direct farmgate platforms. Three archetypes dominate: geography-specific sourcing networks, region-anchored production specialists, and digital procurement bypass platforms. Competitive moves concentrate on backward integration into grower relationships and technology licensing for quality verification.
Within the South Asian export tier, Qadir Exports leverages its sourcing network to supply Middle Eastern dairy operations. Lakkavaram Silage Fodder anchors a position through region-specific baled production for Indian cooperative dairies. Krishna Multicomm Private exemplifies the direct farmgate archetype, occupying a position that bypasses traditional wholesale channels through established grower relationships.
| Leading Market Players |
|---|
| Qadir Exports |
| Bac Quang Trading Investment JSO |
| United Agro Feeds |
| Azure Enterprise |
| Lakkavaram Silage Fodder |
| HKN Exim |
| Krishna Multicomm Private |
| Ambica Enterprise |
| BF Global Trading |
| Others |
Supply Flow & Price Mechanics
Fertilizer input volatility functions as the primary risk vector determining both pricing tier spreads and supply chain configuration across corn silage markets. Ammonia and potash price swings compress grower margins unevenly, forcing acreage shifts into alternative crops in marginal zones while concentrating viable production in regions with integrated nutrient management capabilities.
Pricing Analysis
Aftermarket nutrition consulting and feed formulation services now drive lifetime value capture beyond commodity tonnage transactions. Pricing stratifies across premium, standard, and economy tiers tied to verified fermentation profiles, kernel processing precision, and starch digestibility certification. Cost compression in the standard tier is intensifying because Upper Midwest dairy cooperatives consolidate procurement into fixed-price long-term contracts. Indian cooperative dairies sourcing baled formats exhibit the highest price sensitivity, while German precision-dairy operations under EU Green Deal nitrogen caps absorb premiums for verified nutritional metrics.
Supply Chain Analysis
Extended payment terms from dairy cooperatives and supply-chain finance facilities are restructuring working capital requirements for regional silage suppliers. Production concentrates in the United States, Germany, and India, with each node serving distinct end-use specifications. The supply chain draws from ammonia, potash, and specialized kernel processing equipment as critical inputs. Single-source vulnerability around precision fermentation expertise creates spoilage losses in expanding mid-scale dairies lacking technical support. Distribution runs through direct farmgate contracting in India, wholesale aggregation in the Upper Midwest, and nutrition-consultant-mediated procurement in California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corn silage markets increasingly function as service-attach opportunities where aftermarket nutrition consulting expands faster than commodity tonnage. Feed formulation specialists now contract directly with suppliers to customize fermentation profiles, capturing margin layers unavailable to pure commodity traders.
For Market Incumbents: Pre-empt margin compression from cooperative procurement consolidation by backward integration into kernel processing technology deployment and certified fermentation expertise. Invest in multi-year silo infrastructure in German farm clusters where EU Green Deal environmental compliance creates durable demand for verified storage systems. Capture nutrition consulting relationships before independent specialists displace traditional commodity trading channels entirely.
For New Entrants and Emerging Players: Establish a beachhead in digital procurement platforms connecting Andhra Pradesh baled producers with capital-constrained Indian cooperative dairies. Target biogas feedstock contracting in Denmark and Italy where anaerobic digestion subsidies decouple silage value from dairy commodity cycles. Deploy direct farmgate relationships as the primary go-to-market angle, bypassing wholesale markups through grower connectivity.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors nutrition consulting specialists with verified quality control capabilities. Over the projection horizon, acquisition value concentrates in firms combining fermentation expertise with digital procurement infrastructure. Watch carbon credit monetization protocols for feed additives as the inflection signal determining which packaging and fermentation formats qualify for green financing.
| Strategic Initiative | Industry Significance |
|---|---|
| Kernel Processing Technology Deployment | Advanced roller mill systems raise per-ton feed value for Holstein herds in Wisconsin. |
| Direct Farmgate Platform Development | Digital procurement networks bypass wholesale channels for Andhra Pradesh baled producers. |
| Biogas Feedstock Contracting | Long-term offtake agreements with Danish digesters decouple value from dairy cycles. |
| Fermentation Quality Certification | Verified profiles command premiums from German precision-dairy operations under nitrogen caps. |
| Carbon Credit Protocol Alignment | Methane-reduction qualification determines green financing access under national climate plans. |
Methodological Framework
Operator-level perspectives from dairy nutrition consultants, cooperative procurement managers, silage growers, biogas plant operators, and feed formulation specialists anchored the qualitative base. Primary interviews combined with secondary validation from USDA NRCS environmental quality filings, EU Farm to Fork Strategy documentation, FSSAI feed-grade standards, and anaerobic digestion subsidy records. Bottom-up acreage and tonnage estimates triangulated against top-down dairy herd expansion projections and biogas capacity additions.
Scenario-bracketing around fertilizer price volatility, nitrogen cap enforcement intensity, and biogas subsidy durability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, end-use application, packaging type, and distribution channel, with regional regulatory clusters as an additional industry-specific dimension. CAGRs derived from trend extrapolation of dairy productivity targets and renewable energy policy trajectories, incorporating kernel processing adoption curves and digital procurement penetration rates as forecast inputs.
Sensitivities concentrate around ammonia and potash price trajectories, EU Green Deal enforcement timing, and anaerobic digestion subsidy renewal decisions. Forecasts reflect documented assumptions about herd expansion rates and fermentation technology diffusion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Organic Oats Market
Grains
Ancient Grain Market
Grains
Corn Market
Grains
Wheat Flour Market
Grains
Grain Storage Silos Market
Grains
Asia-Pacific Wheat Market
Grains
Global Rice Market
Grains
China Wheat Protein Market
Grains
Global Oats Market
Grains
Organic Cereals Market
Grains
United States Gluten-Free Oats Market
Grains
Global Wheat Market
Grains
Barley Market
Grains
Black Gram Market
Grains
Masa Corn Products Market
Grains
Dried Spent Grain Market