
 United States Gluten-Free Oats Market | 2026-2036
United States Gluten-Free Oats Market Size, Share, and Industry Trends Forecast 2026-2036
United States Gluten-Free Oats Market Intelligence
Market Context
American oat millers is restructuring capacity to segregate gluten-free lines from conventional processing, tightening supply chain integrity across the Great Plains and Upper Midwest. General Mills leverages its national distribution network to secure shelf space in mainstream retail channels. Nature's Path Foods sustains organic and gluten-free dual certification, commanding premium positioning in natural grocery. Bob's Red Mill Natural Foods anchors its reputation on heritage milling techniques and transparent sourcing from dedicated gluten-free facilities.
Technical Definition and Segments
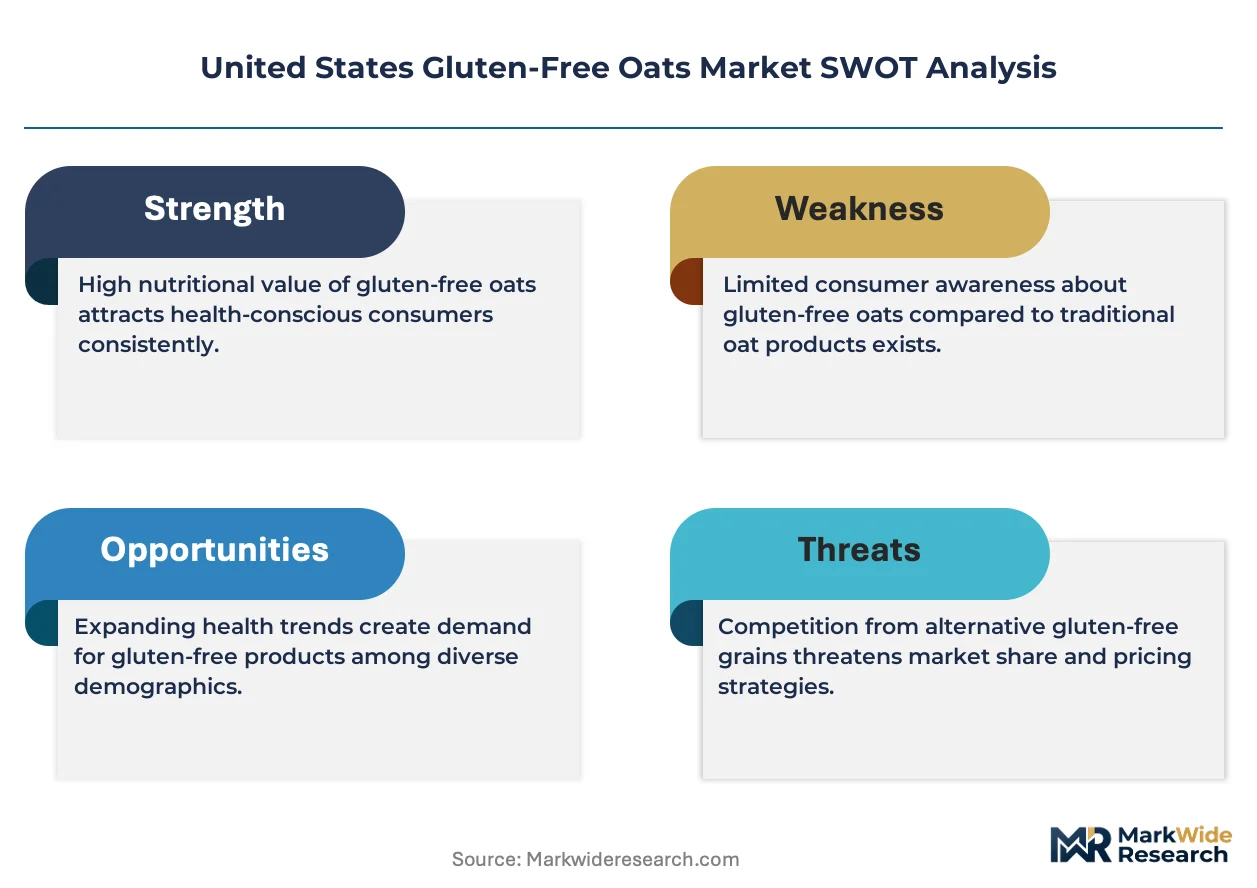
United States Gluten-Free Oats consist of Avena sativa grains processed, transported, and tested to contain less than 20 parts per million gluten, achieving this through field selection, dedicated equipment, and validated laboratory analysis to serve celiac patients and gluten-avoidant consumers. Rolled oats dominate retail volume due to shorter cook times and familiar texture, while steel-cut oats capture the premium breakfast segment with superior satiety claims and lower glycemic positioning. Instant oats compete aggressively in food service and single-serve convenience channels where preparation speed determines contract awards.
Regulatory Framework
The FDA enforces gluten-free labeling standards under the Food Allergen Labeling and Consumer Protection Act, requiring sub-20 ppm verification and preventing cross-contact claims without substantiation. The USDA Organic seal frequently co-appears, adding production location and input traceability requirements that shape grower contracts and elevator logistics. Stakeholders must monitor evolving class-action litigation around gluten threshold enforcement and the potential for stricter ppm standards that would force additional capital investment in testing infrastructure.
Market Dynamics
Segregated milling infrastructure is tightening supply chain integrity across the Great Plains and Upper Midwest as dedicated gluten-free facilities displace shared processing lines. This capital reconfiguration is reshaping grower contracts and elevator logistics.
Growth Catalysts
- FDA Gluten-Free Labeling Rule:The sub-20 ppm standard creates enforceable product differentiation that rewards verified supply chains and locks out unverified imports.
- Steel-cut oats format:Premium breakfast positioning with lower glycemic claims commands shelf space expansion in natural grocery channels.
- Pacific Northwest consumer clusters:Health-conscious demographics with organic food infrastructure overlap generate concentrated demand pull.
Market Restraints
- Avena sativa purity protocols:Field selection, dedicated equipment, and validated laboratory analysis impose input cost premiums that compress margin at scale.
- Upper Midwest supply concentration:Gluten-free oat milling capacity clusters in the Great Plains, exposing buyers to regional weather and logistics disruptions.
- Instant oats substitution:Food service channels prioritize preparation speed over certified gluten-free provenance, diverting volume to conventional alternatives.
Strategic Opportunities
- California retail expansion:Health-conscious consumer density and organic certification infrastructure support premium positioning in conventional grocery.
- USDA Organic dual certification:Production location and input traceability requirements create contract premiums for compliant growers.
- Single-serve convenience channels:Portion-controlled formats for food service and travel segments remain underpenetrated relative to rolled oats retail.
Industry Challenges
- ELISA testing capacity:Validated laboratory analysis for sub-20 ppm verification requires capital-intensive equipment and trained technicians that concentrate in coastal metros.
- Cross-contact litigation exposure:Class-action enforcement of gluten threshold claims creates liability uncertainty that delays new facility investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Gluten-Free Oats Market |
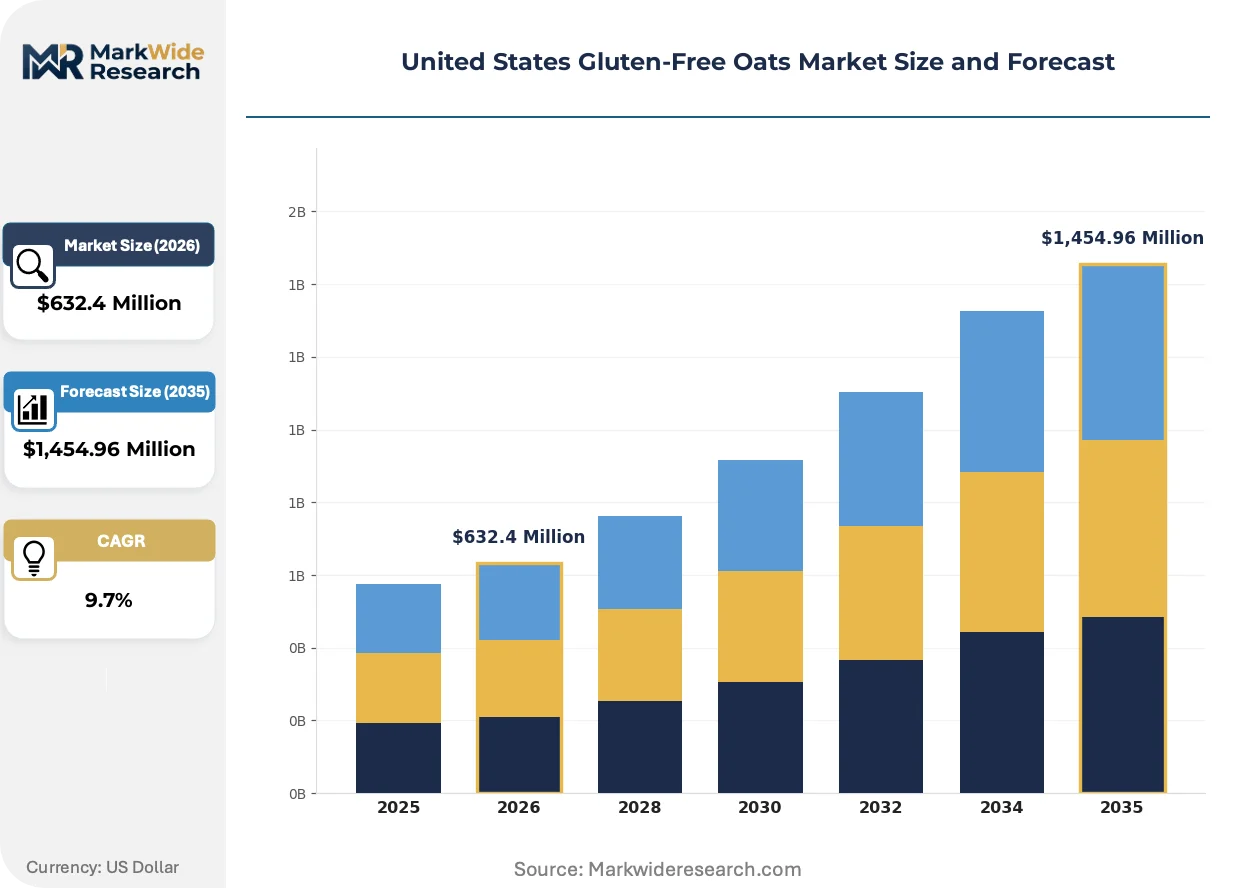
| Market Size in 2026 | $632.4 Million |
| Market Size in 2035 | $1,454.96 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Oats, Rolled Oats, Steel-Cut Oats, Oat Flour End User: Retail Consumers, Food Service, Manufacturers, Health Enthusiasts Packaging Type: Bags, Boxes, Sachets, Tubs Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Nature's Path Foods, Grain Millers, General Mills, Archer-Daniels-Midland Company, Avena Foods, Bob's Red Mill Natural Foods, Cargill, Glutenfreeda Foods, Quaker Oats, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Gluten-Free Oats Market Strategic Shifts & Innovations
Digital traceability platforms and rapid testing protocols are compressing verification timelines while reshaping buyer expectations around transparency. These shifts favor vertically coordinated supply chains over fragmented sourcing.
Optical sorting technology combined with DNA-based contamination detection is consolidating quality assurance protocols across the Great Plains milling corridor. Mid-scale processors in Minnesota and North Dakota are adopting these systems to secure contracts with national retail distributors. The technology is consolidating market share among facilities that can substantiate sub-20 ppm claims with batch-level documentation.
The FDA's enforcement posture under the Food Allergen Labeling and Consumer Protection Act is tightening substantiation requirements for gluten-free claims. Third-party certification bodies now face heightened scrutiny that elevates their liability and cost structures. California and Pacific Northwest retailers are responding by demanding dual FDA-USDA documentation before shelf placement.
Consumer preference is rotating toward heritage grain provenance and transparent sourcing claims that extend beyond gluten-free certification. Natural grocery channels in Portland and Seattle are displacing conventional breakfast aisles as the primary discovery point for new entrants. This channel shift concentrates marketing spend on in-store education and sampling rather than mass media.
United States Gluten-Free Oats Market Segmentation
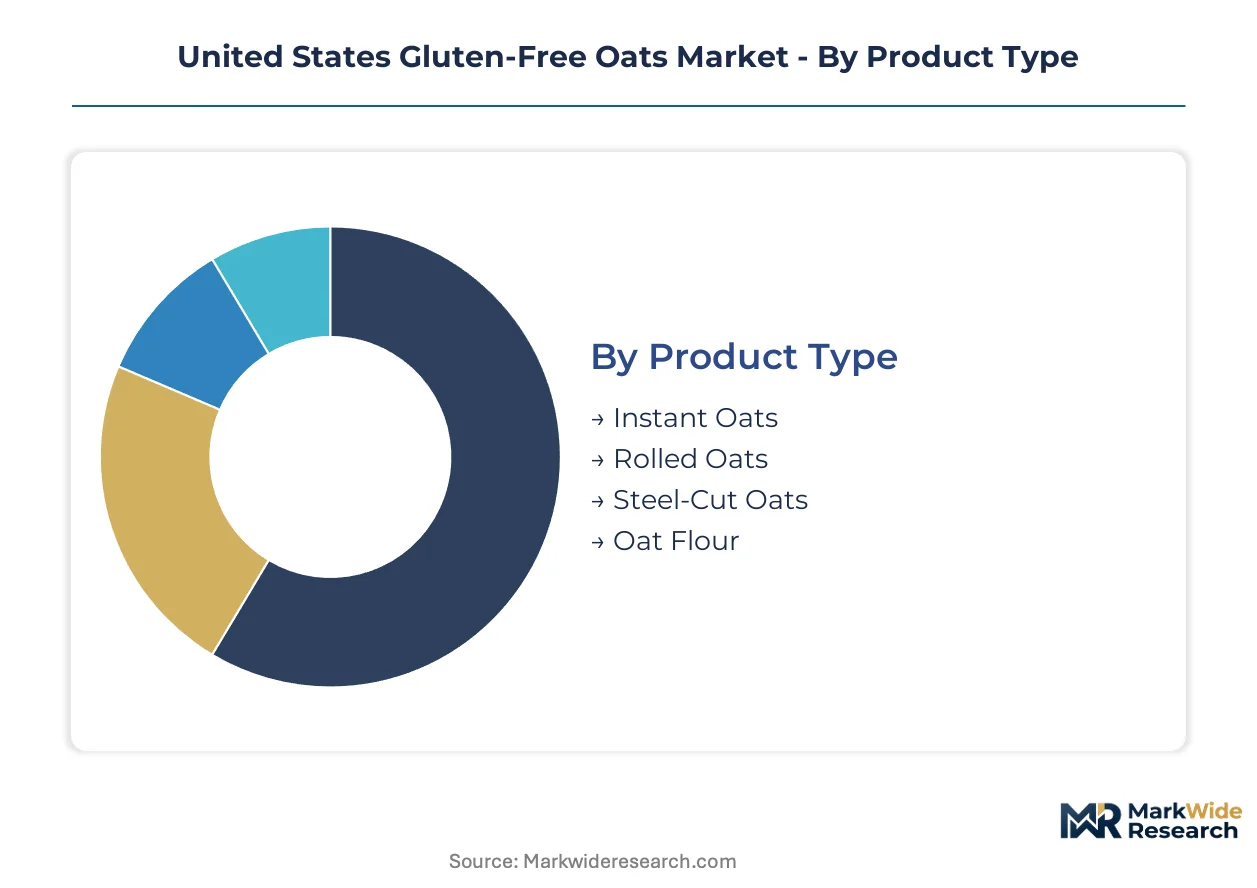
Gluten-free oat segmentation reflects divergent processing investments and certification requirements across formats. Each category channels distinct margin structures and buyer procurement patterns.
Product Type:
Standardization dominates instant and rolled formats while steel-cut and flour segments reward customization premiums.
- Rolled Oats:Steam-stabilized flakes processed through roller mills achieve sub-20 ppm verification through dedicated Great Plains facilities. California and Pacific Northwest retail consumers concentrate demand here, driven by shorter cook times and familiar texture that supports household penetration.
- Steel-Cut Oats:Groats chopped into pinhead-sized pieces retain bran layers and slower digestion profiles. Premium breakfast positioning in natural grocery channels commands shelf space expansion, with lower glycemic claims attracting health-conscious demographics in Portland and Seattle.
- Instant Oats:Pre-cooked flakes designed for single-serve preparation meet food service speed requirements.
- Oat Flour:Finely milled groats serve gluten-free baking applications and manufacturer ingredient sourcing.
Leading the category by volume: Rolled Oats. Growing fastest: Steel-Cut Oats.
End User:
Procurement authority separates direct consumers from intermediaries with divergent specification rigor.
- Retail Consumers:Individual purchasers seeking celiac-safe breakfast options drive FDA-verified product selection through mainstream grocery and natural food channels. Pacific Northwest health-conscious clusters generate concentrated demand pull where organic infrastructure overlaps gluten-free certification.
- Food Service:Institutional kitchens and restaurant chains prioritize preparation speed and portion control over certified provenance, diverting volume toward conventional alternatives despite growing allergen accommodation requirements.
- Manufacturers:CPG companies source gluten-free oat ingredients for granola, snack bars, and bakery applications requiring batch-level documentation.
- Health Enthusiasts:Fitness-focused consumers seeking macronutrient-dense carbohydrates populate specialty shop and online retail channels.
Volume concentrates with Retail Consumers. Fastest expansion trajectory: Food Service allergen accommodation protocols.
Packaging Type:
Format selection tracks consumption occasion and channel shelf constraints.
- Bags:Flexible pouches dominate bulk retail and club store formats where per-ounce cost visibility drives purchase decisions.
- Boxes:Rigid cartons secure mainstream supermarket placement with stackable shelf geometry and front-panel certification display.
- Sachets:Single-serve packets capture travel and food service convenience channels with portion-controlled dispensing.
- Tubs:Rigid containers target health food store and specialty shop environments where premium positioning justifies higher unit economics.
Bag formats lead by volume. Sachets climb the fastest as single-serve convenience penetrates food service.
Distribution Channel:
Channel selection determines certification documentation requirements and margin capture.
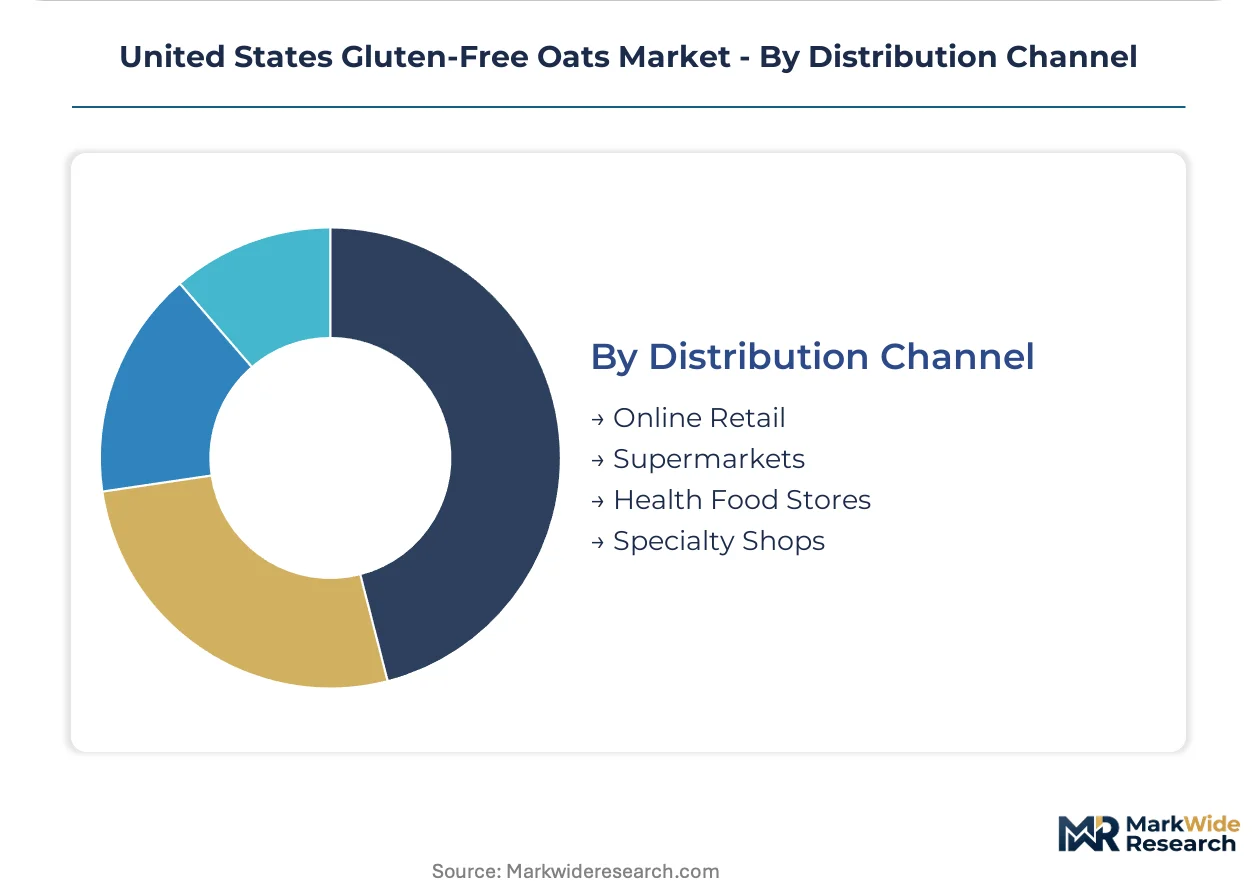
- Supermarkets:Conventional grocery chains in California and the Upper Midwest anchor volume through national brand placement and promotional programming. FDA Gluten-Free Labeling Rule compliance serves as table stakes for shelf access, with dual USDA Organic certification commanding premium positioning.
- Health Food Stores:Natural grocery channels in Portland and Seattle function as discovery environments for heritage grain provenance and transparent sourcing claims. In-store education and sampling displace mass media for new entrant marketing.
- Online Retail:Direct-to-consumer platforms serve subscription models and bulk purchasing for celiac households seeking verified supply chains.
- Specialty Shops:Independent retailers curate artisanal and regional miller products for enthusiast consumers.
Supermarkets dominate volume. Health Food Stores gain share fastest through channel shift toward natural grocery discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Plains oat belt anchors domestic gluten-free supply, with dedicated milling corridors in Minnesota and North Dakota processing Avena sativa varieties under segregated protocols. Demand clusters concentrate along coastal health-conscious corridors where organic certification infrastructure overlaps with celiac-aware retail channels.
Pacific Northwest
Portland and Seattle health-conscious consumer clusters generate concentrated demand pull for steel-cut and heritage grain formats. Washington State's organic certification infrastructure supports dual USDA Organic and gluten-free verification requirements that shape grower contracts. Regional natural grocery channels function as primary discovery environments for new oat entrants, displacing conventional breakfast aisles through in-store education investments.
California
Los Angeles and San Francisco metropolitan areas sustain premium retail expansion for rolled oats with dual certification positioning. The state's Department of Public Health enforces allergen labeling standards that exceed baseline FDA requirements, tightening substantiation documentation for shelf placement. Sacramento Valley organic handlers coordinate elevator logistics with Great Plains millers to secure verified gluten-free grain flows.
Upper Midwest
Minnesota and North Dakota milling capacity clusters expose buyers to regional weather disruptions despite supply chain integrity gains from dedicated facility investments. The USDA's Grain Inspection, Packers and Stockyards Administration oversees elevator certification protocols that validate segregation compliance. Fargo-Moorhead and Minneapolis-St. Paul industrial corridors concentrate optical sorting and DNA-based contamination detection infrastructure.
Southeast
Atlanta and Florida metropolitan areas represent underpenetrated retail expansion territory for conventional grocery channel placement. State agriculture departments in Georgia and Florida coordinate with FDA regional offices on gluten-free claim enforcement consistency. Regional distributors are building direct relationships with Great Plains millers to bypass traditional commodity elevator networks.
Northeast Corridor
Boston and New York City metro areas concentrate ELISA testing capacity and validated laboratory infrastructure for sub-20 ppm verification. Massachusetts and New York state attorneys general have pursued class-action litigation against mislabeled gluten-free products, elevating liability exposure for unsubstantiated claims. Regional food service operators are developing allergen accommodation protocols that diverge from certified provenance requirements.
United States Gluten-Free Oats Market Key Industry Players
Global majors compete with regional champions across certification depth and channel access, creating a tiered structure where scale-driven CPG conglomerates anchor mainstream retail while heritage millers command natural grocery premiums. The vendor base separates into three strategic archetypes: diversified grain processors with national distribution networks, organic-certified specialists with transparent sourcing claims, and vertically integrated regional millers with dedicated gluten-free facilities. Dominant competitive moves include backward integration into certified oat acreage and strategic partnerships with third-party verification laboratories to substantiate batch-level documentation.
Among diversified CPG conglomerates, General Mills and Quaker Oats occupy positions defined by mainstream supermarket shelf space and promotional programming scale. Heritage-focused specialists exemplified by Bob's Red Mill Natural Foods and Nature's Path Foods represent the premium-tier vector through dual organic-gluten-free certification and transparent milling narratives. Grain Millers and Avena Foods sit within the supply-side infrastructure tier, providing ingredient sourcing and toll processing services to branded CPG customers.
| Leading Market Players |
|---|
| Nature's Path Foods |
| Grain Millers |
| General Mills |
| Archer-Daniels-Midland Company |
| Avena Foods |
| Bob's Red Mill Natural Foods |
| Cargill |
| Glutenfreeda Foods |
| Quaker Oats |
| Others |
Cost & Logistics Intelligence
ELISA testing costs cascade through gluten-free oat supply chains, starting at $45-120 per sample in coastal validation labs and accumulating into finished-product premiums that separate dual-certified organic offerings from conventional breakfast alternatives. This input cost structure concentrates pricing power among Great Plains millers with captive laboratory partnerships, while buyers in California and Pacific Northwest retail channels absorb tiered premiums for batch-level documentation.
Pricing Analysis
Third-party certification bundling separates premium positioning from unverified commodity alternatives, with USDA Organic dual certification commanding shelf-space premiums in natural grocery channels. Pricing stratifies across certified heritage, standard gluten-free, and economy conventional tiers based on field traceability depth and optical sorting investment. Cost compression in standard gluten-free tier is intensifying because Minnesota and North Dakota millers are expanding segregated capacity simultaneously. Food service buyers exhibit highest price sensitivity, prioritizing preparation speed over certified provenance and diverting volume toward lower-cost conventional alternatives.
Supply Chain Analysis
Dual-sourcing requirements from national retail distributors mandate qualified supplier rosters spanning Minnesota, North Dakota, and Saskatchewan oat belts to mitigate single-origin weather exposure. Avena sativa grain draws from dedicated field programs, certified seed stock, and validated elevator infrastructure that locks in three-year grower contracts. Single-source vulnerability concentrates in ELISA testing capacity, where coastal metro laboratory bottlenecks delay batch release timelines. Distribution runs through Great Plains milling corridors into Sacramento Valley organic handlers, then onward to Pacific Northwest and California retail consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's sub-20 ppm Gluten-Free Labeling Rule constructs a cost-of-compliance moat that rewards verified supply chain investments and locks out unverified imports, creating sustainable advantage for domestic millers with segregated facilities.
For Market Incumbents: Acquire dedicated gluten-free milling assets in the Upper Midwest to consolidate supply chain integrity before optical sorting technology becomes table stakes. Defend against steel-cut oat specialists by securing exclusive grower contracts with dual USDA Organic certification, locking in premium channel access that unverified competitors cannot replicate.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting celiac households in underpenetrated Southeast metropolitan areas, bypassing conventional grocery slotting fees entirely. Food service allergen accommodation protocols represent the most penetrable white space, with institutional kitchens seeking reliable certified suppliers for accommodation menus.
For Investors and Strategic Acquirers: Class-action litigation settlement announcements are the leading indicator that liability exposure is concentrating among legacy players with unsubstantiated gluten claims, creating distressed acquisition opportunities. Over the medium-term horizon, vertically integrated regional millers with captive laboratory partnerships and dedicated field programs represent the optimal acquisition archetype, with batch-level documentation capabilities serving as the scarce capability separating viable targets from commodity processors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Acreage | Secures dedicated Avena sativa supply chains under FDA-verified field protocols. |
| Dual Certification Investment | Unlocks premium positioning in Portland and Seattle natural grocery channels. |
| Laboratory Partnership Expansion | Compresses ELISA testing turnaround times for batch-level documentation. |
| Food Service Channel Development | Captures allergen accommodation volume diverting from conventional alternatives. |
| Optical Sorting Technology Deployment | Consolidates quality assurance protocols across Great Plains milling corridors. |
Research Approach
Document review covered FDA enforcement actions, USDA organic certification databases, and grain elevator inspection records, complemented by interviews with oat mill operations directors, natural grocery category buyers, celiac patient advocacy organization leaders, and third-party gluten testing laboratory managers. Secondary validation drew from FGIS segregation compliance reports, Great Plains agricultural extension data, and retail scanner datasets. Bottom-up volume modeling triangulated against top-down consumer expenditure analysis.
Segment-level demand outputs across the projection horizon reflect product format, end-user procurement authority, packaging configuration, and distribution channel certification requirements. CAGRs were derived from trend extrapolation of verified gluten-free oat adoption rates, steel-cut format premiumization, and food service allergen protocol expansion. Forecast inputs incorporated FDA enforcement posture evolution, optical sorting technology diffusion curves, and Pacific Northwest organic infrastructure capacity.
Regulatory threshold tightening, ELISA testing capacity constraints, and cross-contact litigation outcomes are the dominant revision risks that could alter trajectory assumptions. A model refresh is warranted upon material change in FDA ppm standard enforcement or class-action settlement precedents establishing new liability baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Green Banana Flour Market
Grains
North America Wheat Protein Market
Grains
Global Oats Market
Grains
Basmati Rice Market
Grains
Grain-Based Flours Market
Grains
Wheat Protein Market
Grains
Millet Flour Market
Grains
Black Gram Market
Grains
Sorghum Market
Grains
Asia Pacific Maize Market
Grains
00 Flour Market
Grains
Bangladesh Rice Market
Grains
North America Oats Market
Grains
Quinoa Flour Market
Grains
Africa Wheat Protein Market
Grains
Asia-Pacific Guar Market