
 Asia-Pacific Wheat Market | 2026-2036
Asia-Pacific Wheat Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Wheat Market Analytics
Grain trading margins is narrowing as price transparency from digital commodity platforms compresses spreads between origin and destination markets. COFCO leverages its state-backed storage network across coastal China to control inland logistics costs. Cargill competes through integrated ocean freight and port terminal operations that reduce handoff delays. Louis Dreyfus Company anchors its position in Australian export corridors, sustaining origination volumes through long-term farm contracts.
Asia-Pacific wheat comprises cultivated Triticum aestivum and Triticum durum varieties with protein content ranging from 9% in soft wheats to 14% in premium hard wheats, milled into flour for human consumption or processed into animal feed. The crop serves as the primary carbohydrate input for noodles, bread, and industrial food manufacturing across temperate and subtropical growing zones. Hard wheat and durum wheat command premium positioning in pasta production and specialized milling, where protein strength determines end-product elasticity and manufacturing yield. Soft wheat occupies the volume base for general-purpose flour and snack applications, while whole wheat segments are expanding on health-positioned bakery reformulations across urban markets.
China's SAMR enforces GB standards on wheat flour fortification and labeling, while Australia's FSANZ-equivalent Food Standards Code governs export certification for Asian destination markets. India's FSSAI mandates pesticide residue testing and mycotoxin thresholds that filter import eligibility and domestic storage practices. BIS grading protocols in India further segment procurement pools by protein and moisture specifications. Stakeholders must monitor how divergent national fortification mandates reshape blending requirements and cross-border grain flows.
Market Dynamics
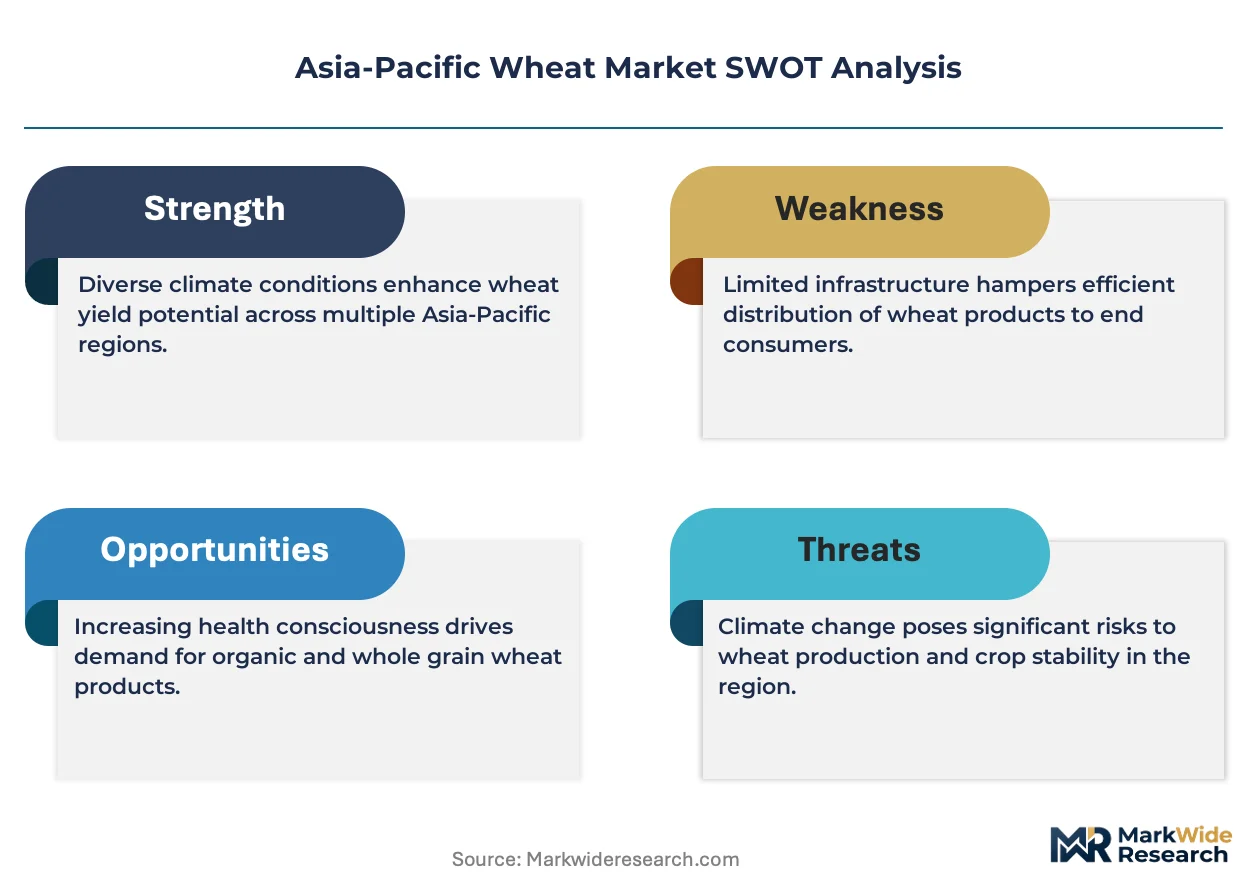
Digital commodity platforms are compressing grain trading spreads across Asia-Pacific wheat corridors, forcing traditional traders to reposition around logistics control and origination assets rather than information arbitrage.
Growth Catalysts
- Hard wheat demand from Southeast Asian noodle manufacturers:Processed food diets are pulling higher-protein Triticum durum into regional milling clusters, expanding premium grade absorption.
- FSSAI mycotoxin enforcement:India's tightened import testing protocols are filtering out substandard suppliers and concentrating volumes through certified channels.
- Coastal China milling concentration:Eastern port clusters now aggregate half of regional import flows, creating density economies for logistics operators.
Market Restraints
- Input cost volatility from ocean freight rates:Bulk grain shipping exposes traders to bunker fuel and charter market swings that erode contracted margins.
- Supply concentration in Australian export corridors:Origination dependence on a single dominant southern hemisphere source creates weather and policy risk.
- Technical limitation in rapid mycotoxin detection:Testing throughput bottlenecks at Indian ports delay customs clearance and inflate demurrage costs.
Strategic Opportunities
- Underpenetrated whole wheat bakery segments in urban China:Health-positioned reformulations are opening premium flour categories beyond traditional soft wheat applications.
- Technology convergence of IoT sensors and blockchain traceability:Integrated systems enable real-time moisture monitoring and origin verification for contract compliance.
- Distribution innovation through direct farm-to-mill procurement platforms:Digital marketplaces are disintermediating traditional grain merchants in Australian origination zones.
Industry Challenges
- Skill gap in mycotoxin laboratory certification:India's FSSAI-accredited testing facilities face technician shortages that extend import clearance timelines.
- Capex intensity in coastal storage infrastructure:State-backed silo networks require sustained capital deployment to maintain quality segregation and aeration systems.
- Integration complexity with legacy procurement software:Established traders struggle to embed real-time price transparency tools into existing contract management workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Wheat Market |
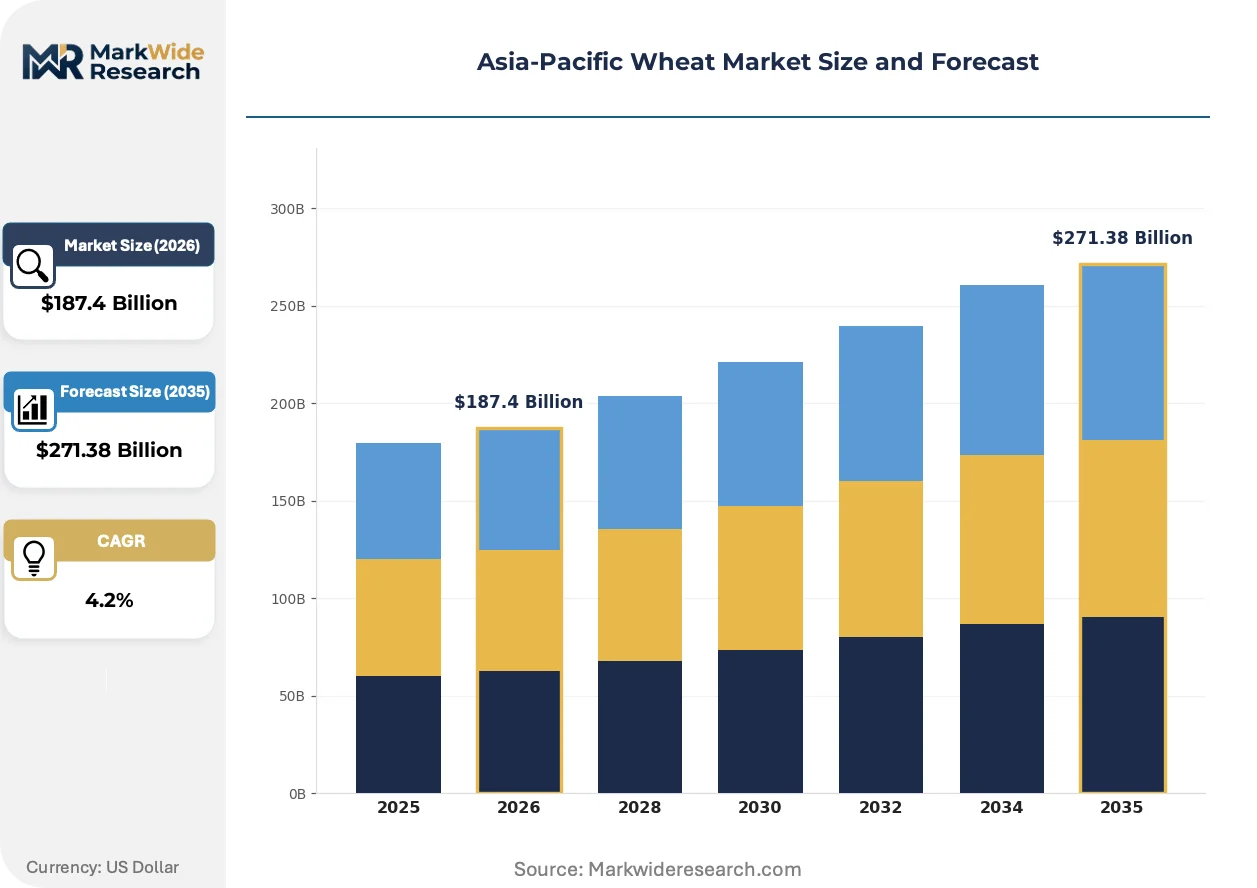
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $271.38 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Wheat, Hard Wheat, Durum Wheat, Whole Wheat End Use: Bakeries, Pasta Production, Animal Feed, Food Processing Distribution Channel: Wholesale, Retail, Direct Sales, Online Platforms Quality Grade: Grade A, Grade B, Feed Grade, Specialty |
| Companies Covered | China National Cereals, Oils and Foodstuffs Corporation (COFCO), Cargill, Archer-Daniels-Midland (ADM), Bunge, Louis Dreyfus Company, Glencore, Nisshin Seifun Group, Adani Wilmar, Syngenta, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Wheat Market Evolving Landscape
Asia-Pacific wheat markets are experiencing simultaneous pressure on trading margins and quality verification standards, reshaping how grain flows from Australian farms to Chinese mills.
Spectroscopic grain analyzers equipped with near-infrared sensors are digitizing quality assessment at intake points, replacing visual inspection and laboratory grinding. Major coastal millers in China are deploying these units at port terminals to accelerate protein and moisture verification. This technology is digitizing the handoff between shipping and processing, compressing the time from vessel discharge to silo acceptance.
India's FSSAI has implemented sequential tightening of aflatoxin and ochratoxin limits for imported wheat, mandating pre-shipment certificates from accredited laboratories. The regulation forces trading houses to maintain dual testing protocols—origin and destination—adding cost layers but filtering non-compliant supply. Australian exporters are responding by securing third-party certification coverage across their entire export book.
Urban Chinese bakery chains are consolidating procurement through long-term flour supply agreements that specify protein ranges and falling number parameters. These contracts displace spot market purchases and concentrate volume with integrated millers capable of consistent blending. The shift is most visible in Shanghai and Guangzhou, where industrial bakers now specify wheat origin and crop year in purchase orders.
Asia-Pacific Wheat Market Segmentation
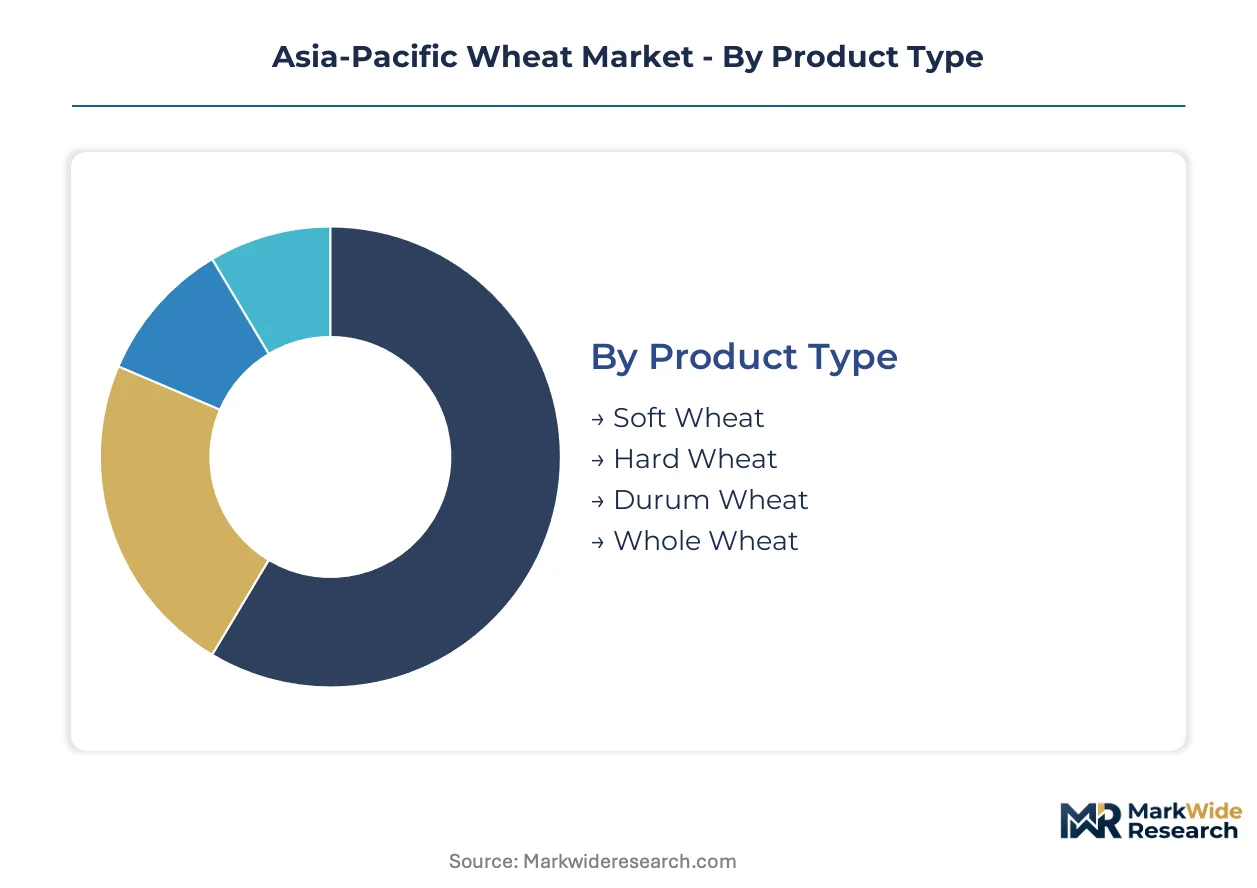
Asia-Pacific wheat procurement patterns diverge sharply across protein specifications, processing applications, and quality certification tiers. Understanding these segment boundaries clarifies where margin compression hits hardest and where premium positioning remains defensible.
Product Type:
Protein content and gluten strength separate the four wheat categories, with each commanding distinct milling economics and end-use premiums.
- Hard Wheat:High-protein Triticum aestivum varieties deliver the gluten strength required for industrial noodle manufacturing across Southeast Asia. Coastal millers in eastern China now specify hard wheat origin and crop year in long-term supply agreements, locking in consistent elasticity parameters for automated production lines.
- Soft Wheat:Lower-protein varieties serve general-purpose flour applications and snack manufacturing where extensibility matters more than structural strength. Demand concentrates in urban Chinese bakery chains reformulating product lines for cost-conscious consumers.
- Durum Wheat:Triticum durum's extreme hardness and amber color support premium pasta extrusion; Australian export corridors dominate origination volumes through long-term farm contracts.
- Whole Wheat:Bran-inclusive milling responds to health-positioned bakery reformulations in Shanghai and Guangzhou, though volume remains constrained by shorter shelf life and aeration requirements in subtropical storage.
Soft wheat commands the established base. The steepest expansion runs through hard wheat as Southeast Asian noodle manufacturers scale automated production.
End Use:
Application-driven demand splits between human food manufacturing and compound feed formulation, with divergent quality thresholds and procurement cycles.
- Bakeries:Industrial bakers in eastern Chinese port clusters now aggregate half of regional import flows, specifying protein ranges and falling number parameters in multi-year flour supply agreements that displace spot market purchases.
- Pasta Production:Premium durum absorption depends on extrusion equipment capable of handling high-temperature drying; Thai and Vietnamese manufacturers are upgrading lines to capture export-oriented production.
- Animal Feed:Feed-grade wheat competes with corn and sorghum in ration formulation; price-sensitive procurement through wholesale channels dominates this segment.
- Food Processing:Diverse applications from snack extrusion to brewing adjuncts pull variable protein specifications, with FSSAI mycotoxin enforcement filtering substandard supply from Indian import channels.
Bakeries anchor volume concentration. Pasta production is climbing the fastest as Southeast Asian manufacturers absorb larger volumes of high-protein durum.
Distribution Channel:
Channel selection reflects buyer scale, quality verification requirements, and tolerance for supply chain intermediation.
- Wholesale:Traditional grain merchants dominate bulk movement from Australian export terminals to Chinese port silos, though margins narrow as digital platforms compress origin-destination spreads.
- Direct Sales:Integrated millers with captive storage networks bypass merchant intermediaries; COFCO's state-backed coastal infrastructure exemplifies this channel's logistics control advantages.
- Retail:Packaged flour for small commercial bakers and institutional kitchens moves through regional distributors with localized blending capabilities.
- Online Platforms:Digital marketplaces are disintermediating traditional procurement in Australian origination zones, connecting farm cooperatives directly to Asian millers with blockchain-verified quality documentation.
Wholesale retains the volume base. Online platforms are gaining share fastest through farm-to-mill disintermediation and real-time price transparency.
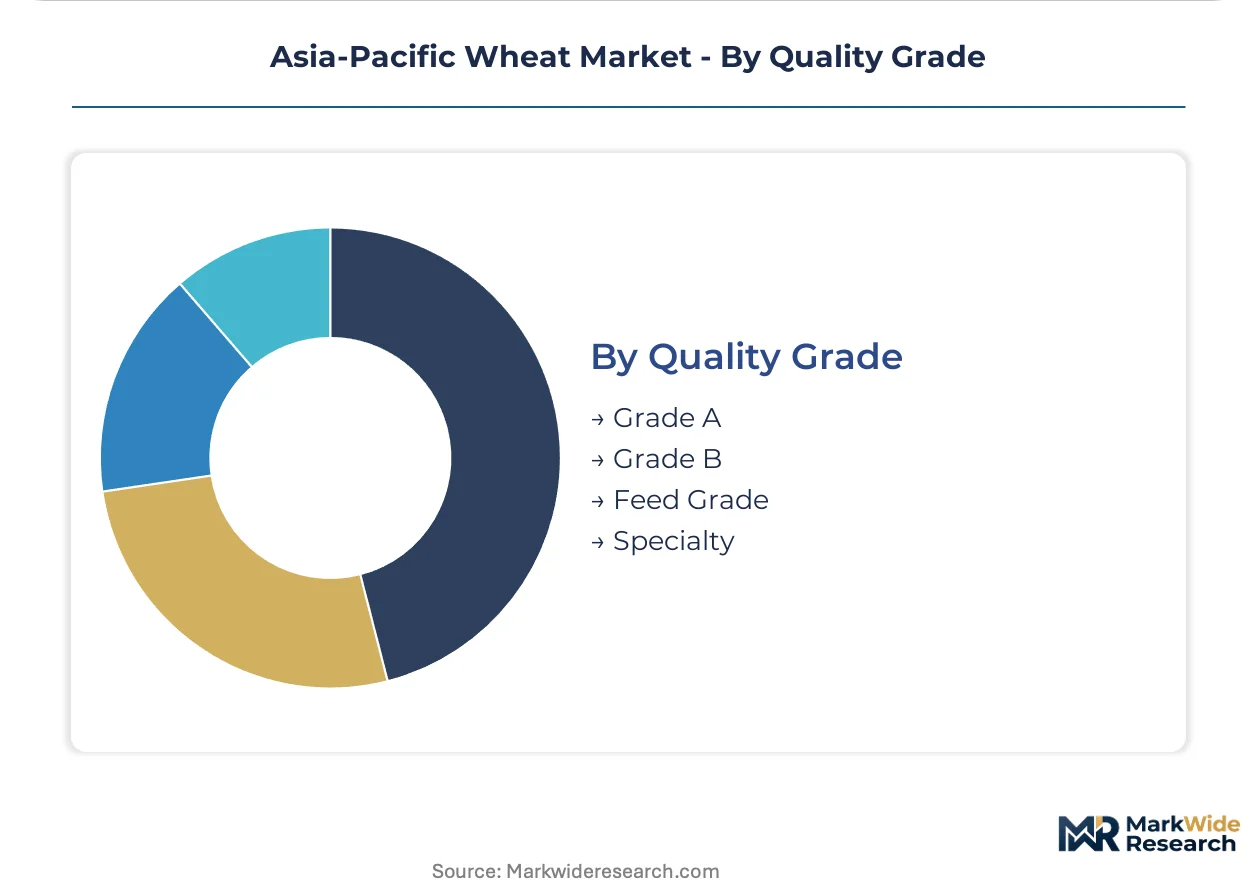
Quality Grade:
Certification tiers separate food-grade milling wheat from feed-acceptable material, with regulatory thresholds tightening fastest in Indian import channels.
- Grade A:Premium milling wheat meets GB standards for flour fortification and labeling enforced by China's SAMR; protein specifications typically exceed 12% with moisture below 14%.
- Grade B:Standard milling quality serves general-purpose applications with relaxed protein windows; BIS grading protocols in India segment procurement pools by these specifications.
- Feed Grade:Sub-milling wheat diverted to compound feed production; FSSAI mycotoxin limits do not apply, though aflatoxin screening remains prudent for dairy ration safety.
- Specialty:Identity-preserved varieties for organic certification, specific heritage cultivars, or contract-specified end uses; traceability systems verify origin and handling segregation.
Grade B commands the established base. Specialty grades are expanding most quickly as urban Chinese bakery chains specify wheat origin and crop year in purchase orders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Asia-Pacific wheat market, with China absorbing imported volumes for industrial milling while India prioritizes domestic procurement and food security buffers. Southeast Asian manufacturers source premium hard varieties for noodle extrusion, contrasting with Australia's export-focused origination economy.
China
Eastern coastal millers now aggregate half of regional import flows, driving density economies for logistics operators. SAMR enforces GB standards on wheat flour fortification and labeling, tightening compliance requirements for inbound shipments. Shanghai and Guangzhou industrial bakeries specify protein ranges and falling number parameters in multi-year supply agreements.
India
FSSAI mandates pesticide residue testing and mycotoxin thresholds that filter import eligibility and reshape domestic storage practices. BIS grading protocols segment procurement pools by protein and moisture specifications. Port clusters in Maharashtra and Gujarat face testing throughput bottlenecks that delay customs clearance and inflate demurrage costs.
Australia
Export corridors dominate origination volumes through long-term farm contracts, anchoring southern hemisphere supply to Asian destination markets. The country's Food Standards Code governs export certification for regional buyers. Grain handlers in New South Wales and Victoria deploy spectroscopic analyzers at intake points to accelerate protein verification.
Japan
Nisshin Seifun Group and integrated millers maintain captive procurement relationships with Australian and North American suppliers. METI oversees food security stockpiling programs that buffer against supply disruptions. Kanto region milling clusters process high-protein hard wheat for industrial noodle manufacturing.
Vietnam
Thai and Vietnamese pasta manufacturers are upgrading extrusion lines to capture export-oriented production, absorbing larger volumes of premium durum. The country's national food safety regulator enforces mycotoxin screening at port terminals. Ho Chi Minh City processing zones concentrate import handling for Mekong Delta distribution.
Asia-Pacific Wheat Market Competitive Landscape
Capability concentration sits with integrated traders controlling origination assets and port infrastructure; scale advantage sits with state-backed operators leveraging domestic storage networks. The market structures around three tiers: multinational agribusiness houses with ocean freight integration, national champions with captive logistics, and regional specialists in quality verification. Dominant competitive moves include backward integration into farm-level origination and technology licensing for traceability systems.
Among multinational agribusiness houses, Cargill and Louis Dreyfus Company exemplify the integrated trading archetype, with the former competing through ocean freight and terminal operations and the latter anchoring position in Australian export corridors. COFCO represents the state-backed national champion model, leveraging coastal storage infrastructure to control inland logistics costs. Archer-Daniels-Midland occupies a position within the quality-verified origination tier.
| Leading Market Players |
|---|
| China National Cereals, Oils and Foodstuffs Corporation (COFCO) |
| Cargill |
| Archer-Daniels-Midland (ADM) |
| Bunge |
| Louis Dreyfus Company |
| Glencore |
| Nisshin Seifun Group |
| Adani Wilmar |
| Syngenta |
| Others |
Value Network & Pricing Analysis
Undercapacity in Australian export corridors during El Niño cycles compresses available tonnage and hands origination pricing power to grain handlers with long-term farm contracts. This utilization squeeze propagates through Asian destination markets, where coastal millers absorb cost pass-throughs while spot buyers face volatile protein premiums.
Pricing Analysis
Long-term offtake agreements between eastern Chinese millers and Australian exporters lock in protein specifications and crop-year origination, displacing spot market liquidity. Pricing stratifies across premium hard wheat, standard soft wheat, and feed-grade tiers, with quality certification from SAMR-accredited laboratories commanding measurable premiums. Cost compression in soft wheat is intensifying because digital commodity platforms expose origin-destination spreads to real-time arbitrage. Feed-grade procurement shows highest price sensitivity among compound feed manufacturers, while industrial noodle manufacturers demonstrate lowest sensitivity due to formulation lock-in.
Supply Chain Analysis
Contract-manufacturing concentration sits with COFCO's state-backed coastal silo networks, Cargill's integrated ocean freight terminals, and Louis Dreyfus Company's Australian export corridor assets. Geographic supply concentration centers on Australia, eastern China, and India, with origination heavily weighted toward southern hemisphere production cycles. Raw material dependencies include bunker fuel for bulk charter rates, phosphorus fertilizers for yield optimization, and fungicide inputs for mycotoxin prevention. Single-source vulnerability from Australian weather exposure represents the dominant structural risk. Distribution runs through wholesale merchant channels toward direct sales integration at scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific wheat sits in early-cycle expansion as Southeast Asian noodle manufacturers scale automated production lines and absorb larger hard wheat volumes. Protein specification tightening across FSSAI and SAMR jurisdictions accelerates premium grade penetration.
For Market Incumbents: Harden origination control through backward integration into Australian farm contracting and captive storage infrastructure. Defend against digital platform disintermediation by embedding blockchain traceability into quality verification workflows. Certification investment in FSSAI-accredited laboratory networks filters competitor access to Indian import channels.
For New Entrants and Emerging Players: Whole wheat bakery segments in Shanghai and Guangzhou represent the most penetrable entry point for health-positioned flour categories. Direct farm-to-mill procurement platforms in Australian origination zones offer disintermediation leverage against established merchant houses. Go-to-market execution should anchor on blockchain-verified quality documentation for contract compliance.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated traders with captive port infrastructure and origination assets across Australian export corridors. Long-term viability over the next decade rests on logistics control rather than information arbitrage. The signal to watch is coastal China milling concentration exceeding threshold density for regional pricing formation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm Origination | Long-term contracts with Australian grain handlers secure protein supply through El Niño cycles. |
| Blockchain Traceability Deployment | Real-time origin verification satisfies FSSAI pre-shipment certificate requirements for Indian imports. |
| Coastal Storage Infrastructure Expansion | COFCO's state-backed silo networks capture density economies in eastern China port clusters. |
| Spectroscopic Analyzer Technology Licensing | Near-infrared protein verification accelerates vessel discharge-to-silo acceptance timelines. |
| Whole Wheat Product Line Extension | Health-positioned bakery reformulations in urban China open premium flour categories beyond soft wheat. |
Research Methodology
A standing panel of grain trading executives, coastal milling operations managers, FSSAI-accredited laboratory directors, and Australian farm cooperative representatives provided ongoing calibration against market developments. Primary interview findings combined with secondary validation from customs trade data, GB standards documentation, BIS grading protocols, and SEC filings from listed agribusiness houses. Bottom-up volume modeling across protein specifications and top-down macroeconomic triangulation anchored forecast integrity.
Scenario-bracketing around El Niño frequency, ocean freight rate volatility bands, and regulatory tightening pace structured the analytical framework across the projection horizon. Segmentation dimensions modeled include protein grade tier, end-use application, distribution channel structure, and quality certification level. CAGRs derived from historical volume trajectories adjusted for structural shifts in coastal China milling concentration and FSSAI enforcement intensity. Industry-specific forecast inputs encompassed Australian crop yield variance and Southeast Asian noodle production capacity expansion.
Stress conditions across Australian rainfall deviation, bunker fuel price spikes, and Indian port testing throughput were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding SAMR fortification mandate stability and long-term offtake contract renewal rates. Quarterly review of FSSAI laboratory accreditation expansion and coastal China silo utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
North America Rice Market
Grains
Bangladesh Rice Market
Grains
GCC Basmati Rice Market
Grains
IQF Rice Market
Grains
Asia Pacific Wheat Protein Market
Grains
Africa Wheat Protein Market
Grains
Soybean Market
Grains
Global Quinoa Market
Grains
Corn Gluten Feed Market
Grains
Grain Silos Market
Grains
Lentil Market
Grains
Global Precooked Corn Flour Market
Grains
Gluten Feed Market
Grains
Non-Basmati Rice Market
Grains
Rice Flour Market
Grains
Soy Grits Market