
 Organic Oats Market | 2026-2036
Organic Oats Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Oats Market Analysis
Multi-source grain procurement is recalibrating how organic oat suppliers manage price volatility and quality consistency across harvest cycles. The Quaker Oats Company leverages its extensive milling infrastructure to secure premium organic grades from contracted North American growers. Nature's Path Foods Inc. anchors its competitive stance through deep channel relationships with natural food retailers and co-op networks. Bob's Red Mill Natural Foods, Inc. differentiates via stone-milling heritage and transparent sourcing narratives that resonate with ingredient-conscious buyers.
Organic oats comprise Avena sativa cultivated without synthetic pesticides, genetically modified organisms, or petroleum-based fertilizers, typically achieving 95% or higher organic matter content through certified field-to-facility chain of custody protocols. Rolled oats and steel-cut oats command the largest volume positions, though instant oats capture disproportionate margin pools through convenience-oriented urban consumers. Food manufacturers represent the fastest-expanding end-user category as oat milk processors scale capacity to replace dairy and soy alternatives in coffee shop and retail channels.
USDA Organic certification governs domestic market access, while EFSA and EU Organic Regulation standards dictate European trade eligibility and labeling requirements. The FDA's Food Safety Modernization Act imposes preventive controls that elevate compliance costs for smaller organic oat processors. Stakeholders must monitor evolving carbon accounting methodologies and soil health verification protocols as downstream buyers embed Scope 3 emissions requirements into procurement contracts.
Market Dynamics
EU Organic Regulation harmonization across member states is forcing processors to consolidate certification chains, while German consumer preference for oat-based beverages concentrates procurement power among large-scale millers.
Growth Catalysts
- EU Organic Regulation:Certification harmonization eliminates cross-border trade friction, enabling processors to source from multiple member states under unified standards.
- Oat milk processors:Coffee shop and retail channel expansion creates dedicated offtake agreements for certified organic grades at volume premiums.
- Soil health verification protocols:Downstream buyers embed Scope 3 emissions requirements into procurement contracts, rewarding regenerative organic oat cultivation.
Market Restraints
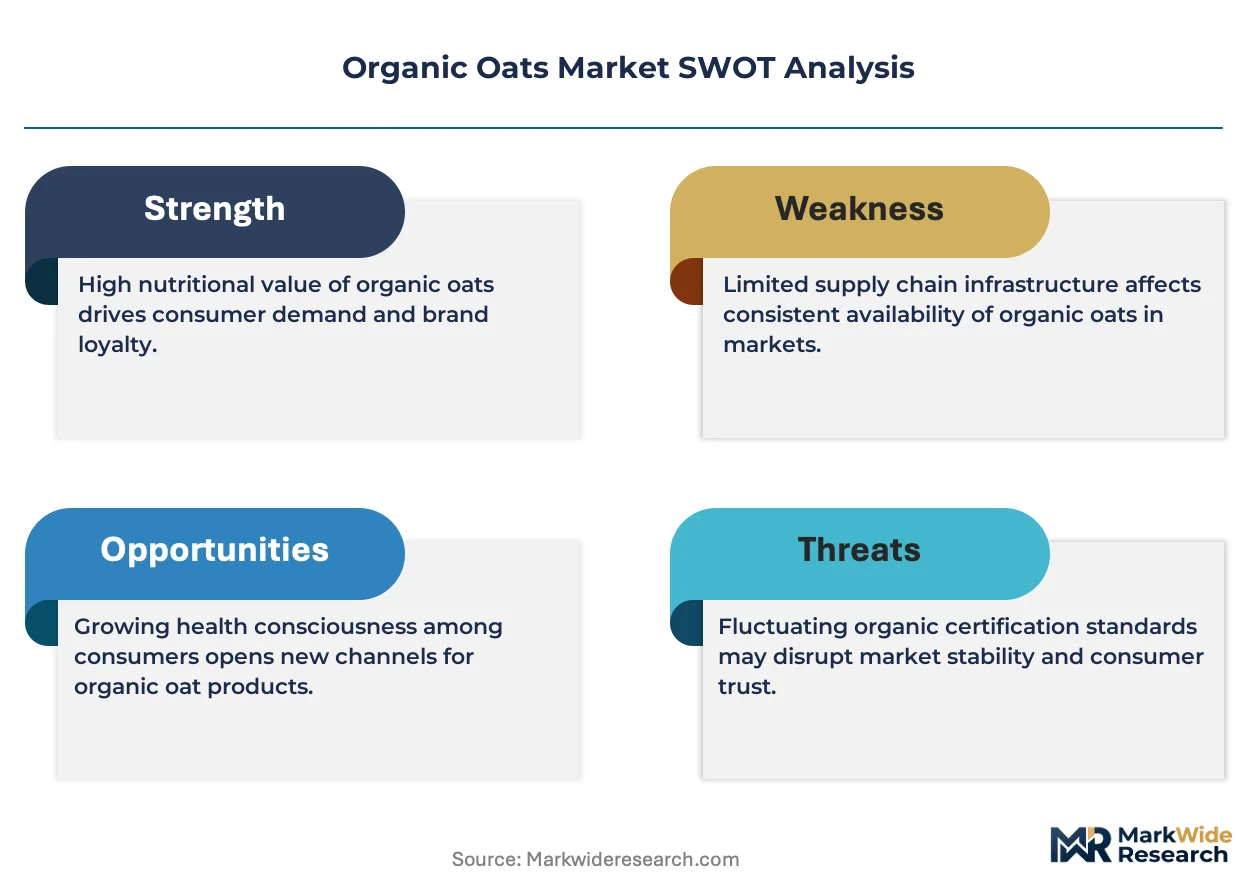
- Input cost volatility:Organic nitrogen sources and mechanical weed control elevate production costs versus conventional oat farming by substantial margins.
- Supply concentration risk:North American contracted growers dominate premium organic grade availability, creating geographic dependency for multinational processors.
- FDA preventive controls:Food Safety Modernization Act compliance costs disproportionately burden smaller organic oat processors with limited quality assurance infrastructure.
Strategic Opportunities
- German retail consolidation:Discounters and organic-specialist chains seek direct miller relationships, bypassing traditional broker networks for breakfast cereal and beverage ingredients.
- Carbon accounting methodologies:Verified carbon-negative oat production commands procurement preference from sustainability-linked institutional foodservice buyers.
- Stone-milling heritage positioning:Transparent field-to-facility narratives enable premium pricing to ingredient-conscious consumers in natural food retail channels.
Industry Challenges
- Certification timeline compression:Three-year field conversion periods and annual audit costs strain grower retention in volatile commodity price environments.
- Chain of custody integrity:Maintaining 95% organic matter thresholds through multi-handler storage and transport networks requires expensive tracking infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Oats Market |
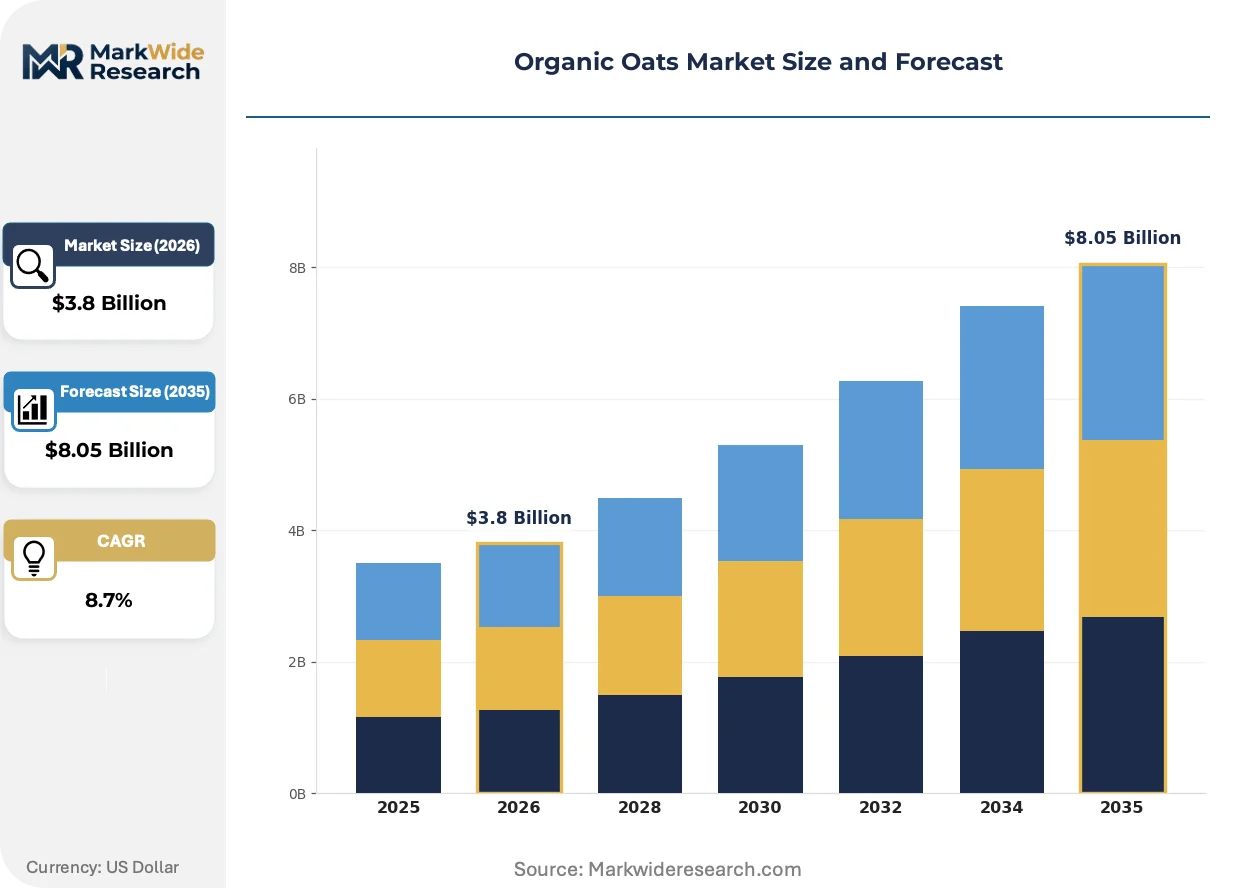
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Oats, Rolled Oats, Steel-Cut Oats, Instant Oats End User: Retail Consumers, Food Manufacturers, Bakeries, Health Food Stores Form: Flakes, Flour, Granules, Groats Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | The Quaker Oats Company, The Kellogg Company, The Hain Celestial Group, Inc., Nature's Path Foods Inc., Grain Millers, Inc., Richardson International Limited, Bob's Red Mill Natural Foods, Inc., Nairns Oatcakes Limited, General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Oats Market Emerging Trajectories
Processing technology and certification transparency are converging to reshape how organic oat value chains capture margin and defend quality positioning against conventional alternatives.
Optical sorting and near-infrared spectroscopy is automating contamination detection and protein grading at receiving terminals. Large-scale millers deploy these systems to reduce laboratory testing bottlenecks and accelerate payment cycles for contracted growers. This automation compresses quality assurance timelines from days to hours, enabling just-in-time processing schedules that match volatile organic raw material availability.
EFSA and EU Organic Regulation standards now mandate stricter residue testing thresholds and enhanced traceability documentation for third-country imports. European processors face reformulation pressures as enforcement tightens on conventional oat commingling risks. German and Dutch importers are responding by vertically integrating into North American grower networks to secure certified supply.
Ingredient-conscious buyers now demand batch-specific sourcing narratives rather than generic organic claims. Natural food retailers and cooperative networks replace conventional distribution with direct miller partnerships that publish field-level provenance data. This transparency preference concentrates in German-speaking markets where breakfast cereal and oat-based beverage purchasing decisions heavily weight certification credibility.
Organic Oats Market Segmentation
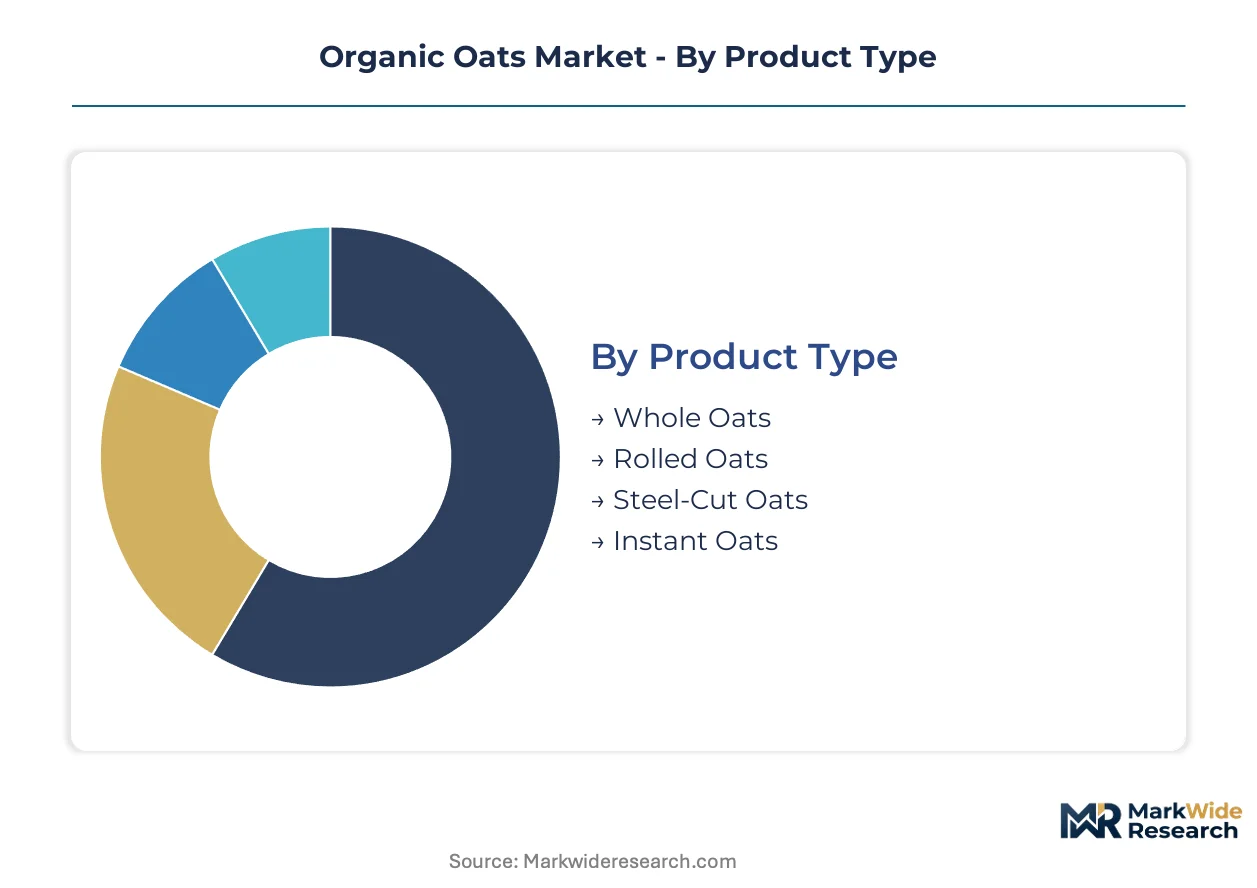
Organic oat processors configure milling lines and inventory pools around distinct product specifications that command divergent price premiums and shelf-life requirements. Segmentation clarity enables procurement teams to align contracted acreage with end-use demand concentration in beverage manufacturing and retail breakfast categories.
Product Type:
Supply concentration among North American millers favors formats with standardized kernel sizing and moisture specifications that integrate efficiently into continuous production systems.
- Whole Oats:Unprocessed kernels with intact hulls serve as the raw input for downstream milling operations and sprouted grain applications. German oat milk processors source whole oats directly to control in-house groat production and achieve specific beta-glucan extraction yields.
- Rolled Oats:Steam-stabilized and flattened kernels dominate breakfast cereal formulations and granola manufacturing due to rehydration speed and texture consistency. Food manufacturers in the Pacific Northwest specify rolled thickness tolerances within 0.3 millimeters to ensure uniform baking performance in energy bar applications.
- Steel-Cut Oats:Groats chopped into pinhead pieces deliver chewier texture profiles for hot cereal and artisanal bread applications. Irish and Scottish heritage brands anchor premium positioning through traditional steel-cutting narratives that resonate with ingredient-conscious buyers in natural food co-ops.
- Instant Oats:Pre-cooked and thin-rolled for sub-60-second hydration, this format captures convenience-oriented urban demand through single-serve packaging. Coffee shop chains specify instant oat specifications for on-demand oatmeal bowls that match service speed targets.
Rolled oats absorb the bulk of installed capacity; instant oats is expanding most quickly.
End User:
Cost tier differentiation separates commodity-scale purchasers from premium-channel buyers who fund traceability premiums and regenerative certification programs.
- Retail Consumers:Individual households purchasing packaged oats through grocery and natural food channels drive brand loyalty through transparent sourcing narratives. German discounters and organic-specialist chains now publish field-level provenance data to satisfy verification demands from breakfast cereal purchasers.
- Food Manufacturers:Oat milk processors, cereal blenders, and energy bar producers constitute the volume anchor for certified organic grade contracting. Swedish and Dutch beverage companies secure multi-year offtake agreements with North American growers to guarantee supply for capacity expansion in retail and foodservice channels.
- Bakeries:Artisan and commercial bakeries specify organic oat flour for gluten-free formulations and texture modification in bread and pastry applications. Pacific Northwest bakery cooperatives source stone-ground flour directly from heritage millers to differentiate finished products in farmers market and specialty retail channels.
- Health Food Stores:Cooperative and independent natural food retailers curate bulk and packaged oat selections around certification credibility and regenerative agriculture claims. These channels emphasize USDA Organic and EU Organic Regulation compliance to satisfy ingredient-conscious buyers who scrutinize supply chain documentation.
Food manufacturers absorb the bulk of installed capacity; health food stores are expanding most quickly.
Form:
Volume concentration in beverage manufacturing elevates flour and flake specifications that integrate into continuous extraction and drying systems.
- Flakes:Rolled and toasted oat flakes serve as the structural base for muesli, granola, and ready-to-eat cereal formulations. German breakfast cereal producers specify flake thickness and moisture content to achieve target crunch retention through distribution cycles.
- Flour:Finely milled oat flour enables gluten-free baking applications and serves as the primary input for oat milk base production. Swedish processors deploy hammer and impact milling systems to achieve particle size distributions that optimize enzymatic hydrolysis efficiency in beverage manufacturing.
- Granules:Agglomerated oat particles function as instant hot cereal bases and texture modifiers in soup and sauce applications. These intermediate formats suit foodservice operations requiring rapid hydration without clumping in high-volume preparation environments.
- Groats:Hulled whole kernels represent the least processed edible form, prized for hot cereal texture and sprouting applications. Heritage millers in the northern Great Plains region market groats to specialty buyers seeking traditional preparation methods and extended shelf stability.
Flour absorbs the bulk of installed capacity; groats are expanding most quickly.
Distribution Channel:
Customer type fragmentation between convenience-seeking urban households and bulk-purchasing rural cooperatives shapes channel investment priorities for organic oat suppliers.
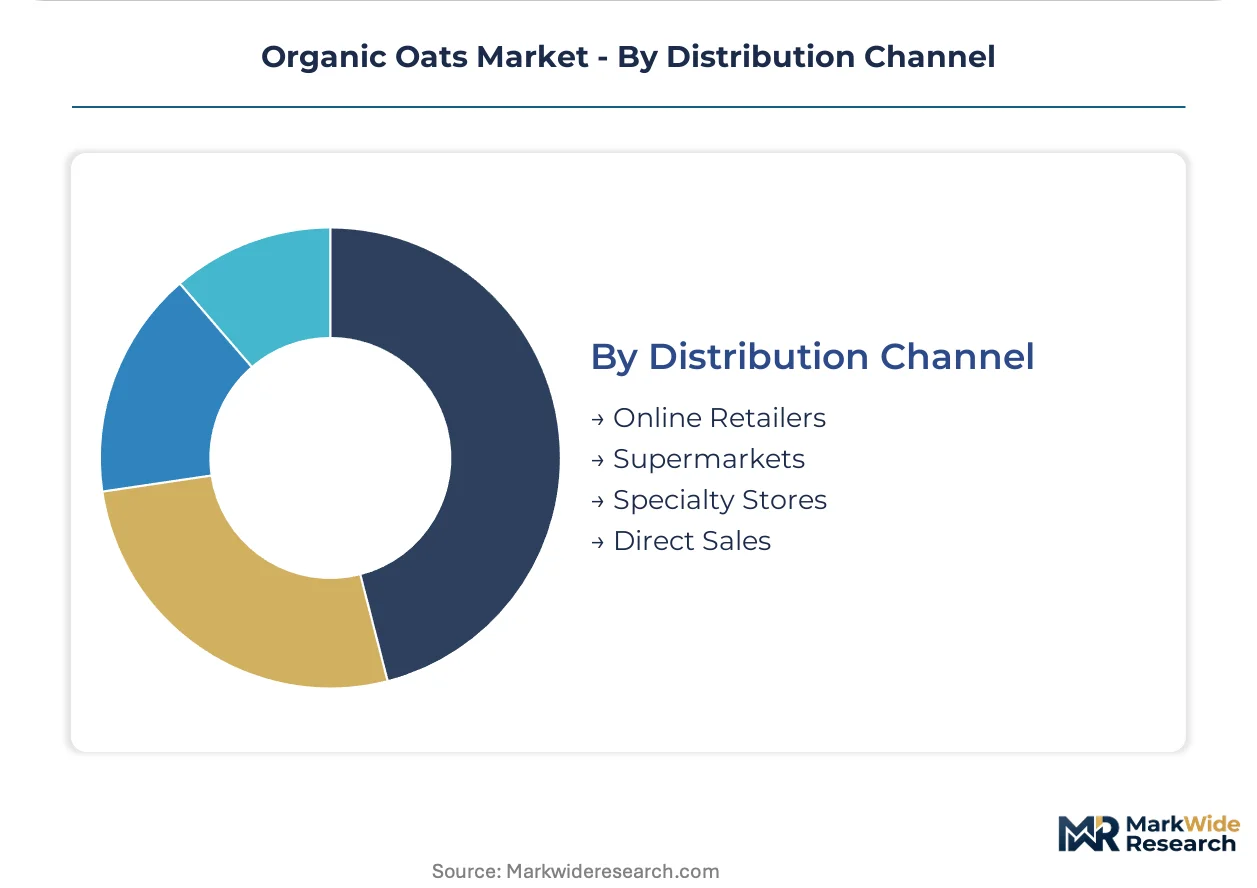
- Online Retailers:E-commerce platforms aggregate subscription and direct-to-consumer sales for specialty and bulk organic oat formats. Amazon and Thrive Market capture repeat purchases through auto-delivery programs that lock in household consumption patterns.
- Supermarkets:Conventional and natural grocery chains stock rolled and instant oats as staple breakfast aisle items with high inventory turnover velocity. German REWE and Edeka banners negotiate direct miller relationships to secure private-label organic oat supply at volume premiums below branded alternatives.
- Specialty Stores:Natural food cooperatives and organic boutiques emphasize transparent sourcing narratives and regenerative certification claims. These channels reward stone-milling heritage and field-to-facility traceability with shelf placement priority and promotional support.
- Direct Sales:Millers and grower cooperatives bypass wholesale distribution to supply bakeries, food manufacturers, and institutional buyers under contract terms. This channel captures margin pools otherwise allocated to broker networks and enables customized specification development for oat milk processors.
Supermarkets absorb the bulk of installed capacity; online retailers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian prairie provinces anchor organic oat cultivation through contracted acreage agreements that supply North American milling operations. German demand for oat-based beverages and certified breakfast cereals reshapes European procurement patterns. Swedish beverage processors secure multi-year supply contracts with Prairie growers to guarantee organic grade availability for capacity expansion.
United States
Pacific Northwest food manufacturers specify rolled oat thickness tolerances for energy bar applications. USDA Organic certification governs domestic market access and labeling requirements. Portland and Seattle bakery cooperatives source stone-ground flour directly from heritage millers for farmers market differentiation.
Germany
Discounters and organic-specialist chains concentrate procurement power through direct miller relationships for breakfast cereal ingredients. EU Organic Regulation harmonization eliminates cross-border trade friction for certified oat imports. Hamburg and Berlin retail clusters publish field-level provenance data to satisfy verification demands from ingredient-conscious buyers.
Sweden
Oat milk processors scale capacity to replace dairy alternatives in coffee shop and retail channels. EFSA standards dictate residue testing thresholds for third-country organic oat imports. Malmö and Stockholm beverage companies deploy hammer milling systems to optimize enzymatic hydrolysis efficiency.
Netherlands
Rotterdam importers vertically integrate into North American grower networks to secure certified organic supply. EU Organic Regulation mandates enhanced traceability documentation for oat shipments. Dutch breakfast cereal producers specify flake thickness and moisture content to achieve target crunch retention through distribution cycles.
United Kingdom
Scottish heritage brands anchor premium positioning through traditional steel-cutting narratives. Health food store cooperatives emphasize USDA Organic and EU Organic Regulation compliance to satisfy supply chain documentation scrutiny. Edinburgh and Glasgow natural food retailers curate bulk oat selections around regenerative agriculture claims.
Organic Oats Market Vendor Landscape
Global majors compete with regional champions across milling infrastructure and channel access dimensions. The vendor base clusters around three tiers: diversified food conglomerates with integrated grain procurement, heritage millers with stone-processing differentiation, and oat milk specialists securing captive organic supply. Three strategic archetypes dominate: scale-driven commodity processors, transparency-focused heritage brands, and beverage-forward vertical integrators. Capacity expansion and backward integration into grower networks represent the dominant competitive moves.
Within the heritage miller tier, Bob's Red Mill Natural Foods, Inc. and Nature's Path Foods Inc. exemplify transparency-focused positioning through field-to-facility sourcing narratives. The Quaker Oats Company occupies a scale-driven archetype leveraging extensive North American milling infrastructure. These three entities represent distinct competitive vectors: stone-milling heritage, deep natural food retail relationships, and commodity-scale procurement respectively.
| Leading Market Players |
|---|
| The Quaker Oats Company |
| The Kellogg Company |
| The Hain Celestial Group, Inc. |
| Nature's Path Foods Inc. |
| Grain Millers, Inc. |
| Richardson International Limited |
| Bob's Red Mill Natural Foods, Inc. |
| Nairns Oatcakes Limited |
| General Mills Inc. |
| Others |
Supply Flow & Price Mechanics
Backward integration into North American grower networks anchors supply security and pricing power for processors serving EU Organic Regulation-compliant markets. This upstream control over certified acreage enables volume premiums that commodity traders cannot match, while three-year field conversion timelines create captive supply positions that insulate against spot market volatility.
Pricing Analysis
Certification-bundled pricing separates USDA Organic and EU Organic Regulation tiers from uncertified commodity grades, with residue testing documentation and chain-of-custody warranties included in premium quotations. Price differentiation rests on beta-glucan content verification and regenerative agriculture claims that attract sustainability-linked institutional buyers. Cost compression in standard-grade rolled oats is intensifying because German discounters negotiate direct miller relationships that bypass broker margins. Food manufacturers exhibit highest price sensitivity due to oat milk margin pressures, while heritage stone-millers command inelastic demand from natural food cooperatives.
Supply Chain Analysis
Seasonal labor availability in Canadian prairie provinces and northern Great Plains milling centers constrains processing capacity during peak harvest windows. Geographic supply concentration centers on Canada, the United States, and Sweden for finished oat milk production. Raw material dependencies include organic nitrogen fertilizers, mechanical weed control equipment, and optical sorting technology for contamination detection. Single-source vulnerability runs through North American premium grade availability, as EU processors lack alternative certified suppliers meeting EFSA residue thresholds. Distribution runs through direct miller relationships with German retail banners and Swedish beverage companies, supplemented by natural food cooperative networks in Pacific Northwest cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic oat supply remains structurally constrained by three-year field conversion requirements that cap certified acreage expansion, propping volume premiums for incumbent processors with contracted grower networks.
For Market Incumbents: Deploy optical sorting and near-infrared spectroscopy automation to compress quality assurance timelines and accelerate grower payment cycles. Secure multi-year offtake agreements with Swedish and Dutch oat milk processors before competitors capture capacity expansion demand. Invest in soil health verification protocols to meet Scope 3 emissions procurement requirements from sustainability-linked institutional buyers. For New Entrants and Emerging Players: Launch via direct-to-bakery sales channels in Pacific Northwest cooperative networks where heritage stone-milling narratives command premium positioning. Target German organic-specialist retail chains seeking field-level provenance data that established millers cannot rapidly deploy. Exploit underpenetrated groats segments for sprouting applications and traditional hot cereal markets. For Investors and Strategic Acquirers: Exit pathways concentrate in beverage-forward vertical integrators securing captive organic supply for oat milk capacity expansion. Long-term viability favors processors with certified North American acreage positions and EU Organic Regulation compliance infrastructure. Watch German retail consolidation velocity as the inflection signal for direct miller relationship premiums versus broker-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grower Networks | Captive supply of USDA Organic certified acreage insulates processors from spot market volatility and EU import competition. |
| Optical Sorting Technology Deployment | Near-infrared spectroscopy automation reduces laboratory testing bottlenecks at receiving terminals for contracted prairie growers. |
| Soil Health Verification Programs | Regenerative agriculture certification meets Scope 3 emissions requirements embedded in procurement contracts from institutional foodservice buyers. |
| Direct Retail Banner Relationships | German REWE and Edeka negotiations bypass traditional broker networks and capture private-label organic oat volume premiums. |
| Stone-Milling Heritage Repositioning | Transparent field-to-facility sourcing narratives differentiate heritage millers in natural food cooperative channels. |
Methodological Framework
Independent corroboration across primary interviews with organic oat processors, grain procurement directors, and EU regulatory compliance officers underwrites the qualitative findings. Secondary validation draws from USDA Organic certification databases, EFSA residue testing protocols, EU Organic Regulation harmonization documents, and North American agricultural trade statistics. Bottom-up triangulation of contracted acreage data with top-down beverage manufacturing capacity announcements ensures segmentation integrity.
Rate-of-change decomposition separates volume expansion from price premium capture across the projection horizon. The analytical framework models product type, end-user category, and distribution channel dimensions alongside certification tier differentiation. CAGRs were derived from trend extrapolation of oat milk processor capacity announcements and German retail scanner data. Forecast inputs include organic nitrogen fertilizer cost trajectories and EU member state enforcement tightening on third-country residue thresholds.
Regulatory enforcement variance, organic input cost spikes, and oat milk demand deceleration are the dominant revision risks. Forecasts reflect assumptions regarding EU Organic Regulation harmonization maintenance and North American harvest yield stability. Material deviation in certification timeline compression or German retail consolidation velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Organic Rice Flour Market
Grains
Wheat Fiber Market
Grains
GCC Basmati Rice Market
Grains
Pulses Market
Grains
Torrified Wheat Market
Grains
White Rice Flour Market
Grains
Europe Wheat Market
Grains
South America Wheat Market
Grains
Non-Basmati Rice Market
Grains
White Beans Market
Grains
Chickpeas Market
Grains
Mexico Rice Market
Grains
Cultured Wheat Market
Grains
Wild Rice Market
Grains
China Maize Market
Grains
North America Pulses Market