
 Masa Corn Products Market | 2026-2036
Masa Corn Products Market Size, Share, and Industry Trends Forecast 2026-2036
Masa Corn Products Market Foresight
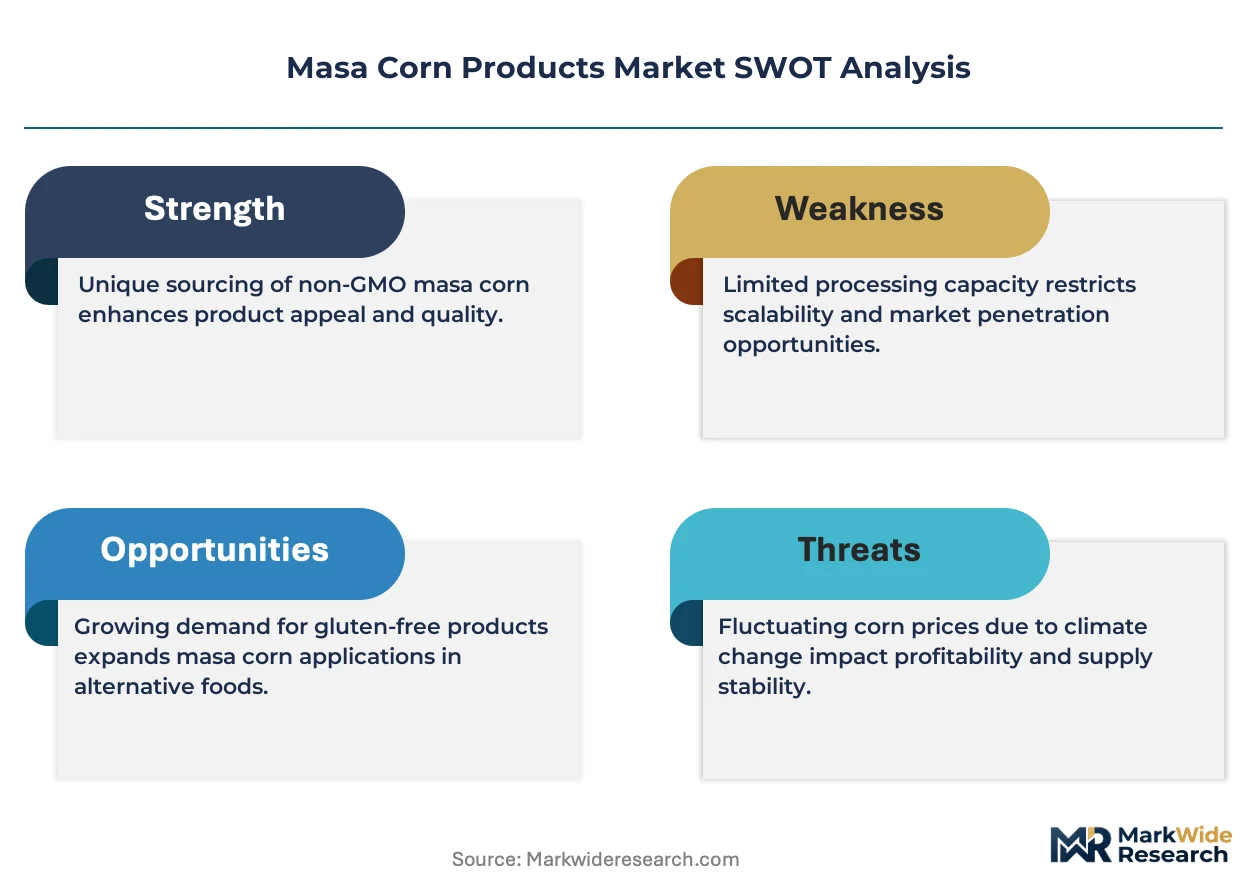
Restaurant services is expanding as a dominant demand channel for masa corn products, pulling volume away from traditional retail as operators seek consistent, scalable masa supplies for tortillas and tamales. Gruma S.A.B. de C.V. leverages its integrated nixtamalization network across Mexico and the United States to anchor supply security for food service chains. Cargill Incorporated competes through its grain origination infrastructure, sustaining cost advantages in corn procurement for masa millers. Bunge North America specializes in identity-preserved corn streams, differentiating its offerings for customers requiring non-GMO or organic masa inputs.
Masa corn products consist of nixtamalized corn dough or flour produced through alkaline cooking with lime, followed by grinding to achieve specific particle size distributions typically ranging from fine flour to coarse masa for tortillas. The nixtamalization process increases bioavailable niacin and modifies starch gelatinization properties, making masa functionally distinct from untreated cornmeal for leavened and flatbread applications. Tortillas within the product type segment dominate absolute volume, while ready-to-cook products capture expanding margin pools as convenience-oriented households shift preparation labor to manufacturers. Food service operators among end users represent the fastest-growing demand cluster, with procurement patterns favoring just-in-time delivery contracts over bulk spot purchases.
FDA food safety modernization requirements and USDA organic certification standards shape product specifications and facility auditing protocols for masa manufacturers serving the United States market. Mexico's COFEPRIS, the country's national health regulator, enforces nixtamalization process standards and additive limits that determine market access for imported masa derivatives. Stakeholders must monitor evolving nixtamalization equipment regulations and corn bioengineering approval pathways, as these will determine which suppliers can maintain cross-border product flows without reformulation costs.
Market Dynamics
Restaurant chains are consolidating masa procurement through direct mill partnerships, bypassing traditional distributor tiers to secure volume commitments and traceability documentation required under FDA food safety modernization protocols.
Growth Catalysts
- Clean-label mandates:FDA and USDA frameworks for ingredient transparency are pulling reformulated masa SKUs into food service menus, creating specification premiums for additive-free nixtamalized products.
- Nixtamalization automation:Continuous-process cooking systems are reducing labor intensity and batch variability, enabling tortilla manufacturers to scale output without proportional workforce expansion.
- US Southwest concentration:Demographic density of Hispanic populations in Texas, California, and Arizona anchors per-capita consumption rates that exceed national averages by substantial margins.
Market Restraints
- White corn price volatility:Drought cycles in Mexican growing regions and US Plains states transmit directly to masa input costs, compressing margins for non-integrated millers.
- Supply concentration risk:Nixtamalization capacity clusters in central Mexico and border-adjacent US counties, creating single-source vulnerability for regional distributors.
- Perishability constraints:Fresh masa's 72-hour shelf life limits geographic radius for non-frozen distribution, constraining market expansion into northern US markets.
Strategic Opportunities
- Underpenetrated US Midwest:Urban centers outside traditional consumption zones present whitespace for refrigerated masa distribution through specialty grocers.
- Ready-to-cook formats:Pre-portioned tamale dough and par-baked tortilla bases capture convenience demand from time-constrained households.
- USDA organic certification:Premium positioning for identity-preserved organic corn streams commands price multiples in natural channel retail.
Industry Challenges
- Nixtamalization technician scarcity:Traditional lime-cooking expertise is aging out of the workforce faster than automated systems can replicate quality consistency.
- COFEPRIS cross-border alignment:Divergent additive approvals between Mexico's health regulator and FDA create reformulation burdens for dual-market suppliers.
- Legacy equipment retrofit costs:Stone-grinding infrastructure requires capital-intensive upgrades to meet modern sanitation standards without sacrificing texture profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Masa Corn Products Market |
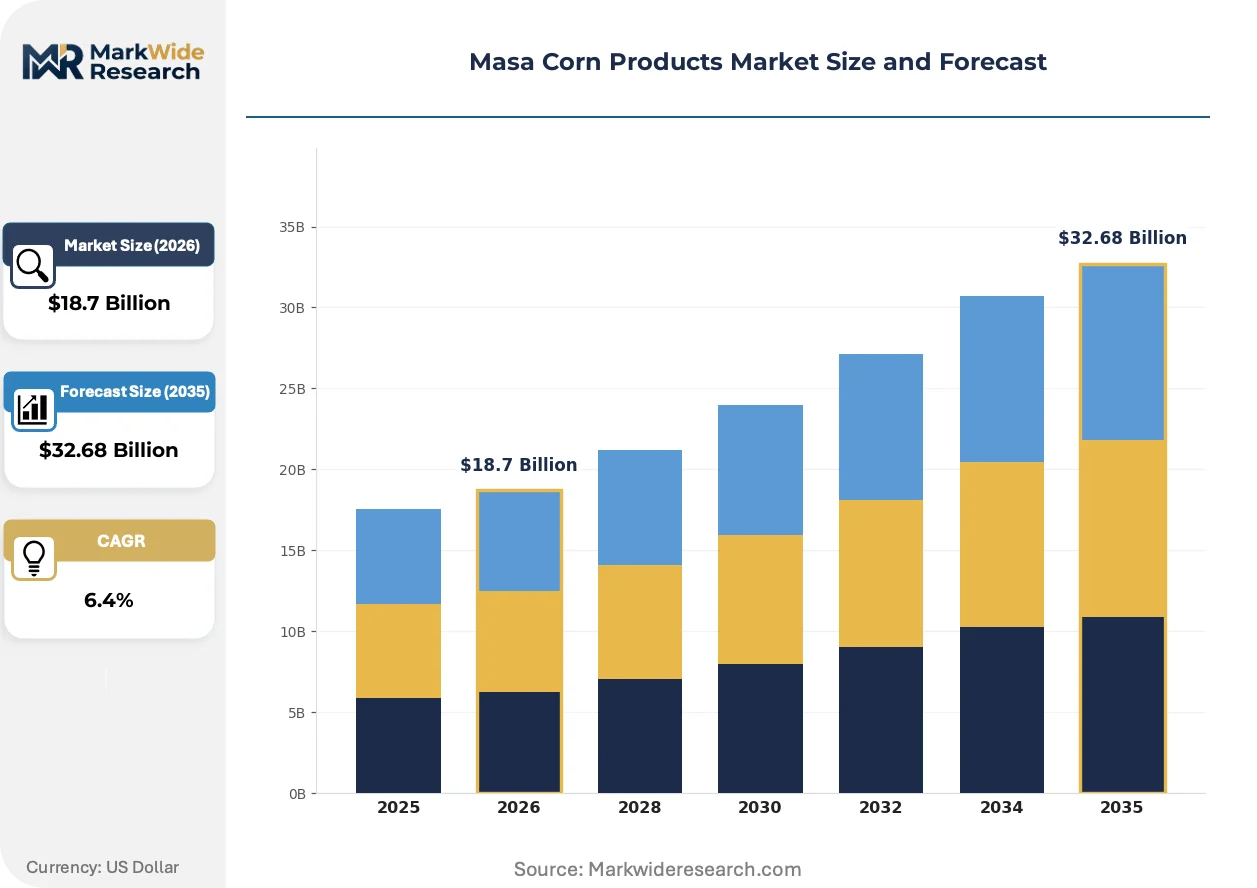
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tortillas, Tamales, Snack Foods, Ready-to-Cook Products Application: Food Industry, Restaurant Services, Retail, Catering End User: Households, Food Manufacturers, Food Service Operators, Wholesalers Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Direct Sales |
| Companies Covered | Bunge North America, Cornexo GmbH, Gruma S.A.B. de C.V., Bob's Red Mill Natural Foods, Limagrain Cereales Ingredients, Cargill Incorporated, Bühler AG, Minsa, Archer Daniels Midland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Masa Corn Products Market Shifts & Advancements
Equipment digitization and process control systems are compressing quality variance in masa production, while regulatory documentation requirements reshape competitive capabilities across the value chain.
Continuous nixtamalization systems with real-time pH monitoring and automated lime dosing are absorbing variability from traditional batch cooking. Mid-scale tortilla manufacturers in Texas and California are adopting these systems to meet chain restaurant specifications for consistent masa performance. The technology is absorbing quality-control labor into capital equipment, shifting competitive advantage toward mechanized producers.
COFEPRIS process standards for nixtamalization are tightening additive limits and documentation requirements for masa derivatives entering Mexican commerce. Industrial millers serving cross-border markets must maintain dual compliance protocols to avoid detention at ports of entry. Food service distributors with integrated US-Mexico supply chains are most affected, investing in segregated production lines and enhanced lot tracking.
Direct procurement contracts between restaurant chains and regional masa mills are displacing traditional broadline distributor relationships. Operators seek captive supply security and custom formulation capabilities unavailable through multi-brand distributors. This pattern concentrates most visibly in Arizona and New Mexico, where fast-casual tortilla concepts are scaling rapidly.
Masa Corn Products Market Segmentation
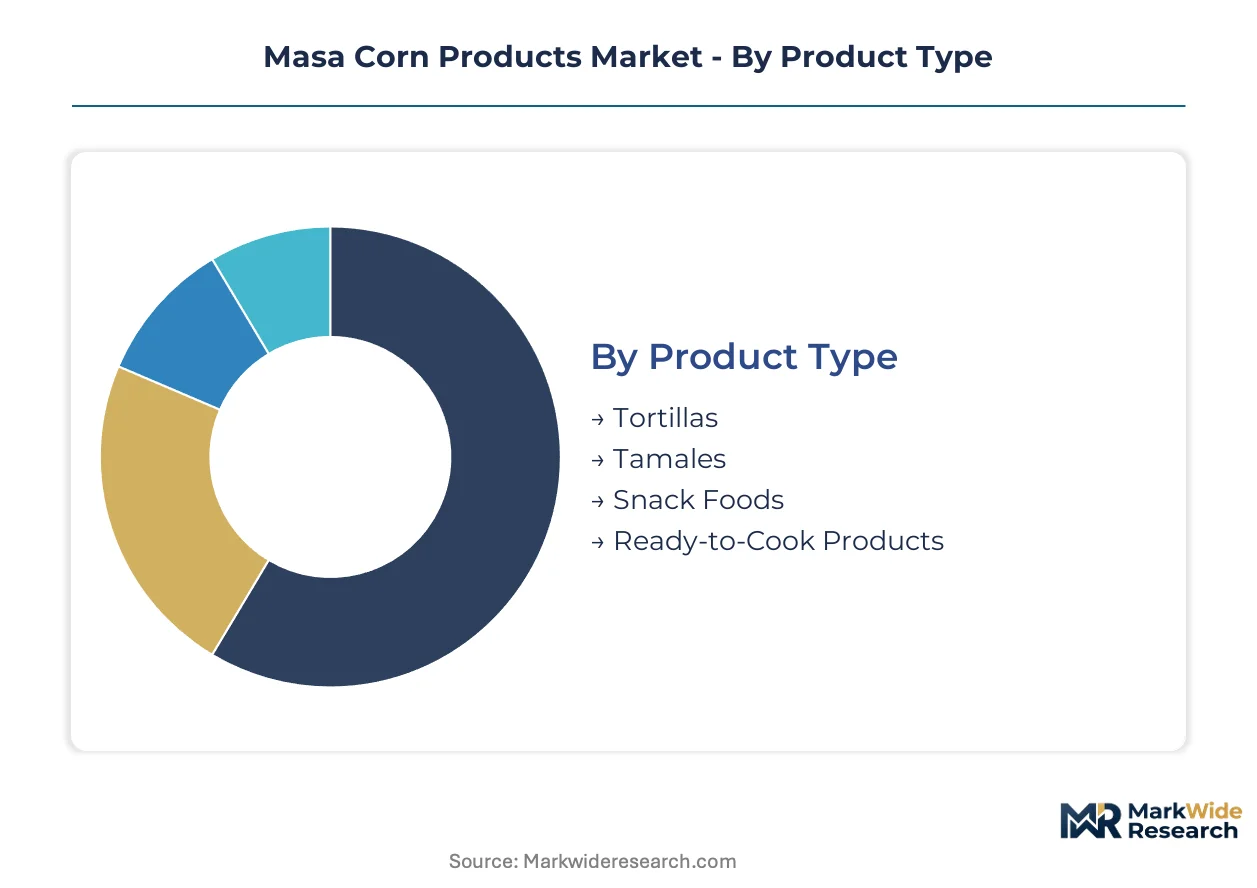
Masa corn products fragment across four distinct segmentation axes, each revealing different competitive dynamics. Product type determines capital intensity and margin structure, while application and end-user channels expose divergent growth trajectories. Distribution channel selection directly constrains geographic reach and brand positioning.
Product Type:
Supply concentration clusters around high-volume formats with established nixtamalization infrastructure, while emerging categories attract specialized equipment investment.
- Tortillas:Flatbread formats produced from fine to coarse particle distributions dominate absolute production volume across Mexican and US Southwest facilities. Restaurant chains in Texas and California anchor procurement through direct mill contracts requiring consistent moisture content and rollability specifications.
- Tamales:Coarse masa with higher fat absorption capacity serves both traditional household preparation and commercial steam-table operations. Demand concentrates in border-adjacent counties where tamale-focused catering operations sustain regional distribution networks.
- Snack Foods:Extruded and fried masa derivatives for tortilla chips and corn puffs.
- Ready-to-Cook Products:Pre-portioned dough and par-baked bases capturing convenience-oriented households.
Tortillas absorb the bulk of installed capacity; ready-to-cook products are expanding most quickly.
Application:
Cost tier differentiation separates commodity-volume applications from specification-driven channels commanding premium positioning.
- Restaurant Services:Chain operators and independent taquerias procure through just-in-time delivery contracts with traceability documentation under FDA food safety protocols. Arizona and New Mexico fast-casual concepts are scaling procurement volumes fastest.
- Food Industry:Processed food manufacturers integrate masa as an ingredient input for frozen prepared meals and retail snack production.
- Retail:Packaged fresh and shelf-stable masa products moving through grocery channels.
- Catering:Event-service operations requiring bulk format flexibility and custom formulation capabilities.
Restaurant services captures the steepest expansion trajectory; retail maintains the broadest geographic footprint.
End User:
Customer type determines order frequency, specification complexity, and relationship intensity with mill operators.
- Food Service Operators:Restaurants, institutional feeders, and mobile food vendors requiring consistent quality for menu execution. Direct procurement patterns favor regional mills with US-Mexico supply chain integration.
- Households:Traditional consumers in Hispanic-dense markets purchasing fresh masa from tortillerías and specialty grocers.
- Food Manufacturers:Industrial buyers processing masa into downstream packaged goods.
- Wholesalers:Distributor intermediaries consolidating volume for fragmented retail and food service accounts.
Food service operators command the most intensive supplier relationships; households sustain the highest per-capita consumption density.
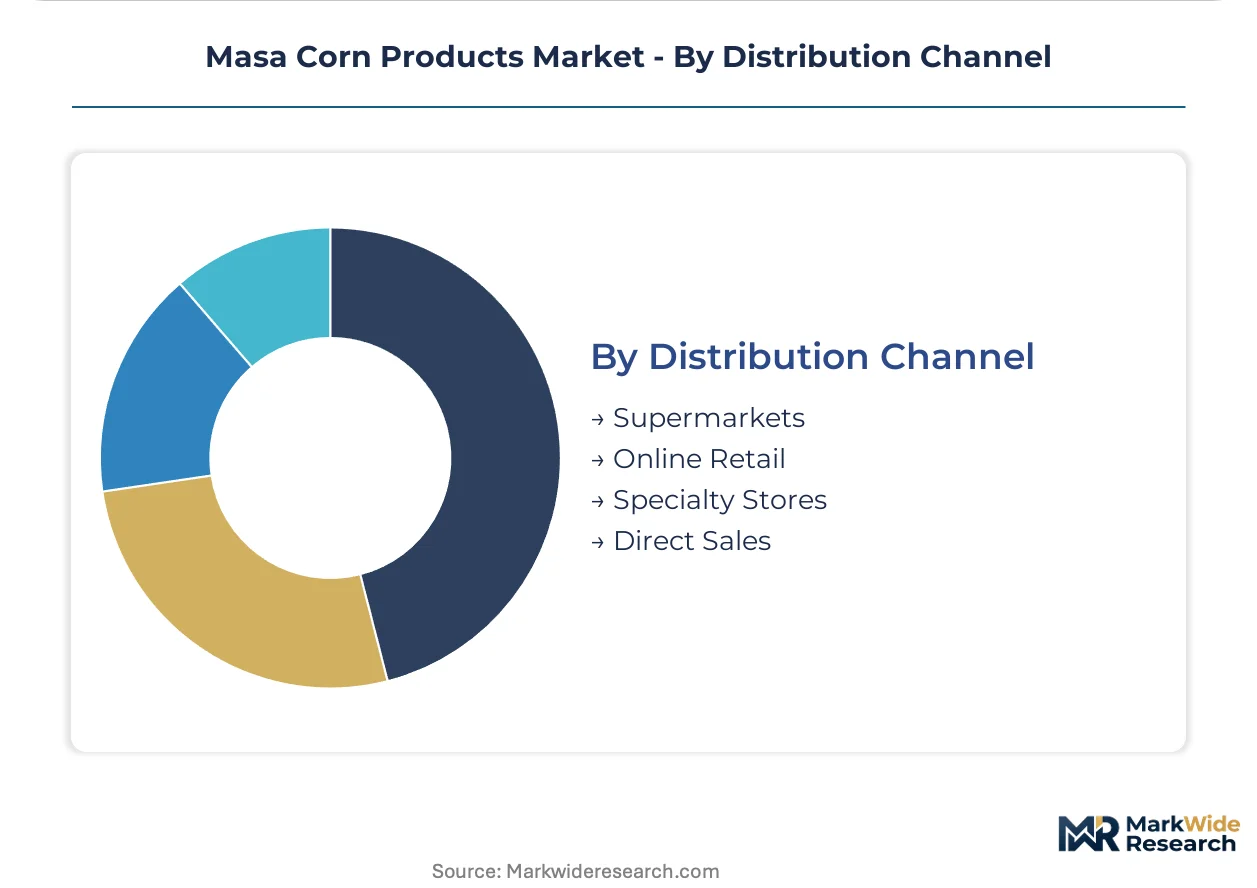
Distribution Channel:
Geographic maturity shapes channel viability, with refrigerated logistics requirements limiting expansion into underpenetrated northern markets.
- Supermarkets:Mainstream grocery retailers in Texas, California, and Arizona carrying both fresh deli-section masa and packaged flour formats.
- Specialty Stores:Hispanic-focused independent grocers and tortillerías serving first-generation immigrant communities.
- Direct Sales:Mill-to-restaurant contracts bypassing distributor markups for volume-committed chain accounts.
- Online Retail:E-commerce platforms for shelf-stable masa flour shipping beyond traditional consumption zones.
Supermarkets anchor volume throughput; direct sales channels are gaining share fastest among chain restaurant accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export processing zones along the US-Mexico border concentrate nixtamalization capacity, drawing investment through tariff exemptions and streamlined customs protocols for corn derivative trade.
United States
Texas and California anchor demand through Hispanic demographic density and fast-casual restaurant expansion. FDA food safety modernization protocols mandate traceability documentation for masa entering interstate commerce. Phoenix and Tucson industrial corridors host automated tortilla manufacturing clusters serving southwestern chain operators.
Mexico
Traditional household consumption and tortillería networks sustain per-capita volumes exceeding all other markets. COFEPRIS enforces nixtamalization additive limits and process documentation for domestic and export-bound production. Mexico City metropolitan area and Jalisco state concentrate industrial milling capacity for cross-border supply chains.
Canada
Specialty retail channels in Toronto and Vancouver metropolitan areas drive demand for organic and non-GMO masa flour formats. Health Canada and CFIA regulate imported corn products through sanitary and phytosanitary protocols. Prairie province grain elevators supply identity-preserved white corn streams to Ontario-based millers.
Germany
Food service distributors in Bavaria and North Rhine-Westphalia source masa for Central European Mexican restaurant concepts. EFSA and BfR frameworks govern additive approvals and novel food classifications for corn derivatives. Hamburg port logistics clusters handle bulk corn imports for regional nixtamalization facilities.
Masa Corn Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated millers commanding food service procurement while commodity traders supply ingredient-grade inputs. Market structure tilts toward consolidation among large-scale nixtamalization operators with cross-border supply chain integration. Three archetypes dominate: vertically integrated corn-to-masa processors, grain origination specialists with downstream partnerships, and equipment-technology providers licensing process control systems. Capacity expansion and direct mill-to-restaurant contracting represent the primary competitive moves reshaping distributor relationships.
Within the integrated processor tier, Gruma S.A.B. de C.V. and Cargill Incorporated exemplify divergent strategic positions. Gruma occupies a position representing captive nixtamalization networks spanning Mexico and the southwestern United States. Cargill sits within the grain origination archetype, leveraging upstream corn procurement infrastructure to supply regional millers. Bunge North America represents the specialty ingredients vector, with name signaling North American operational focus and GmbH-structure competitors like Cornexo GmbH anchoring European technical capabilities.
| Leading Market Players |
|---|
| Bunge North America |
| Cornexo GmbH |
| Gruma S.A.B. de C.V. |
| Bob's Red Mill Natural Foods |
| Limagrain Cereales Ingredients |
| Cargill Incorporated |
| Bühler AG |
| Minsa |
| Archer Daniels Midland |
| Others |
Supply & Pricing Matrix
Chain restaurant procurement consolidation in Texas and California anchors contract-based pricing structures for high-volume masa suppliers. These buyers leverage multi-year offtake agreements to lock in margin protection against white corn input volatility.
Pricing Analysis
Short lead-time premiums dominate spot procurement for fresh masa, while extended contracts command volume discounts from integrated millers. Three-tier pricing structure across premium organic, standard food-grade, and economy commodity tiers separates USDA-certified identity-preserved streams from conventional white corn derivatives. Cost compression in economy tiers is intensifying because drought-driven feed corn diversion squeezes available milling supply. Independent taquerias exhibit highest price sensitivity due to thin menu margins; fast-casual chains with captive supply agreements show least sensitivity.
Supply Chain Analysis
Direct-to-restaurant channels handle hyperscale buyer demand across Arizona and New Mexico, bypassing traditional broadline distributors. Geographic supply concentration clusters in Mexico, the United States, and Canada, with Jalisco state and Texas border counties hosting integrated nixtamalization capacity. Raw material flows draw from white corn streams in Mexican central highlands, US Plains states, and Prairie province elevators. Single-source vulnerability pervades regional distributor networks dependent on central Mexico milling clusters. Distribution runs through temperature-controlled logistics for fresh formats, with shelf-stable flour shipping via standard freight.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around automated nixtamalization scale, with FDA traceability mandates and technician scarcity forcing sub-scale millers toward exit or acquisition.
For Market Incumbents: Anticipate margin compression from continuous-process equipment adopters by securing backward integration into identity-preserved corn origination. Invest in COFEPRIS-compliant documentation systems to defend cross-border supply chain positioning against reformulation-cost barriers. For New Entrants and Emerging Players: Enter via refrigerated fresh masa distribution into Chicago and Denver metropolitan areas, where Hispanic demographic growth outpaces local milling capacity. Target USDA organic certification gaps in Midwest specialty retail channels, leveraging direct-store-delivery relationships with independent Hispanic grocers. For Investors and Strategic Acquirers: The window for entry favors mid-scale automated millers with existing restaurant chain contracts and dual US-Mexico facility footprints. Monitor nixtamalization equipment utilization rates as inflection indicator for capacity-constraint pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Nixtamalization System Deployment | Absorbs quality-control labor into capital equipment, shifting advantage toward mechanized Texas and California producers. |
| Backward Integration into Identity-Preserved Corn | Secures non-GMO and organic input streams against drought-driven white corn price spikes in Mexican highlands. |
| Dual COFEPRIS-FDA Compliance Certification | Enables cross-border product flows without detention at ports of entry or reformulation cost burdens. |
| Direct Restaurant Chain Contracting | Bypasses distributor markups while capturing volume-committed accounts with custom formulation requirements. |
| Refrigerated Distribution Network Expansion | Extends fresh masa geographic radius beyond 72-hour shelf-life constraints into underpenetrated northern US markets. |
Research Methodology
USDA crop production reports, COFEPRIS regulatory filings, and FDA food safety modernization documentation formed the secondary backbone, cross-referenced against primary interviews with tortilla manufacturing plant managers, chain restaurant procurement directors, and Hispanic grocery category buyers. Bottom-up volume estimates from state-level tortillería counts and industrial milling capacity registrations were triangulated against top-down consumption models derived from demographic consumption-rate benchmarks.
Bottom-up modeling segmented volume across product type, application channel, end-user archetype, and distribution format throughout the forecast period. CAGRs were derived from trend extrapolation of nixtamalization automation adoption curves and restaurant services procurement growth patterns, with corn price cycle assumptions stress-tested against historical drought impact correlations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended drought scenarios in Mexican growing regions or abrupt COFEPRIS additive limit revisions. Periodic stress-testing of base assumptions is recommended against white corn futures volatility and cross-border sanitary protocol alignment developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Oatmeal Market
Grains
South Africa Grain Market
Grains
Grain and Cereal Crop Market
Grains
Wheat Bran Market
Grains
Grain Storage Systems Market
Grains
Chickpeas Market
Grains
Africa Wheat Protein Market
Grains
Barley Market
Grains
Asia-Pacific Wheat Market
Grains
Quinoa Flour Market
Grains
South America Rice Market
Grains
Ancient and Specialty Grain Flour Market
Grains
Low Fat Rice Market
Grains
North America Wheat Flour Market
Grains
Europe Wheat Market
Grains
China Wheat Protein Market