
 Global Wheat Market | 2026-2036
Global Wheat Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wheat Market Outlook
Black Sea export capacity is hardening following infrastructure investments in Ukrainian port corridors and Russian grain terminal expansions. Cargill leverages its vertically integrated origination network across North American and Australian wheat belts. Bunge Limited anchors its position through strategic port assets along the Mississippi River system and Brazilian export terminals. Louis Dreyfus Company competes via specialized grain handling infrastructure in key export corridors.
Wheat comprises the dried, ground seeds of Triticum aestivum and related species, typically containing 11-15% protein by dry weight with moisture content standardized below 14.5% for commercial storage. Its primary commercial purpose centers on flour milling for human consumption, with lower-protein grades diverted to animal feed and industrial starch production. Durum wheat commands premium positioning in pasta production due to its elevated gluten strength and semolina yield. The baking segment sustains the largest volume absorption, though animal feed applications are gaining share as coarse grain prices fluctuate. Direct sales channels dominate commercial transactions, while retail and online segments service specialty and organic wheat varieties.
The EU Green Deal and F-Gas Regulation influence agricultural input costs and storage technology adoption across European wheat production zones. India's FSSAI and BIS standards govern import quality specifications and domestic food safety compliance for wheat derivatives. USDA grading standards and FDA food safety mandates shape US export competitiveness and domestic milling requirements. Stakeholders must monitor climate volatility patterns, biofuel policy shifts, and origin diversification strategies to secure supply continuity and margin protection.
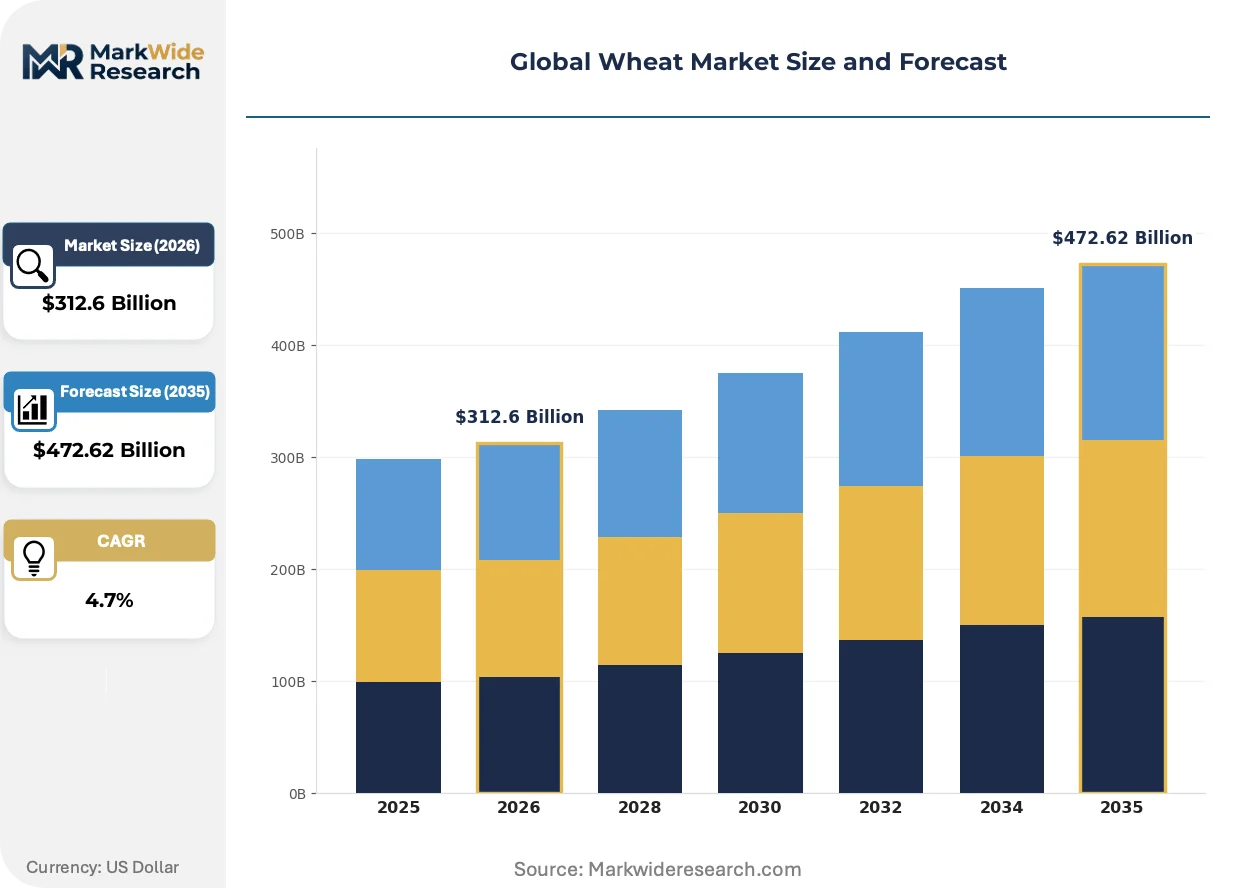
Market Dynamics
The Black Sea corridor's export capacity expansion is redrawing wheat trade flows, with Ukrainian port infrastructure investments and Russian terminal upgrades compressing traditional Atlantic and Pacific shipping lanes.
Growth Catalysts
- Biofuel Mandates:The EU Green Deal's renewable energy directives are channeling feedstock-grade wheat toward ethanol refineries, creating dedicated offtake agreements that insulate growers from food-price volatility.
- India:Government food security programs and state-sponsored milling infrastructure expansion are absorbing record import volumes, tightening global exportable surplus calculations.
- Precision Agriculture:Satellite-guided variable-rate fertilization and AI-powered yield forecasting are lifting per-hectare productivity in Australian and Canadian spring wheat belts.
Market Restraints
- Input Cost Volatility:Ammonium nitrate and potash prices, shaped by EU F-Gas Regulation compliance costs and sanctions-affected Belarusian supply, are compressing farm-level margins across European production zones.
- Concentration Risk:Black Sea origin dependence—specifically Ukrainian and Russian export terminals—exposes buyers to corridor closure risks from military activity or insurance market withdrawals.
- Substitution Threat:Corn and sorghum are capturing feed ration formulations when coarse grain price spreads widen, eroding lower-protein wheat's historical lock on livestock nutrition.
Strategic Opportunities
- Brazil:Underdeveloped winter wheat cultivation in Rio Grande do Sul and Paraná offers expansion potential as Mercosur trade integration deepens regional flour milling demand.
- Carbon Markets:EU CSRD disclosure requirements and voluntary carbon credit schemes are rewarding regenerative wheat rotations with premium pricing from sustainability-linked procurement contracts.
- Blockchain Traceability:Integration of distributed ledger systems with elevator receipt systems is enabling origin-verified premium tiers for identity-preserved durum and heritage varieties.
Industry Challenges
- Skill Shortage:Agronomic expertise in cover-crop integration and reduced-tillage systems lags adoption targets, particularly among tenant operators in US Plains states.
- Certification Bottlenecks:FSSAI import clearance timelines and BIS laboratory capacity constraints are delaying Indian shipments, forcing inventory carry costs onto exporters.
- Legacy System Integration:Siloed elevator management software blocks real-time interoperability with port logistics platforms, fragmenting supply chain visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wheat Market |
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $472.62 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Wheat, White Wheat, Durum Wheat, Hard Red Wheat End Use: Baking, Pasta Production, Animal Feed, Beer Production Distribution Channel: Direct Sales, Retail, Wholesale, Online Market Segment: Commercial, Industrial, Household, Export |
| Companies Covered | Viterra, Ardent Mills, Archer Daniels Midland, Glencore Agriculture, General Mills, Bunge Limited, Louis Dreyfus Company, Grain Craft, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wheat Market Strategic Shifts
Digital origination platforms and climate-adaptive breeding programs are compressing the gap between farm production and end-use specification, enabling tighter alignment between varietal selection and downstream processing requirements.
Gene-edited CRISPR varieties with enhanced drought tolerance and Fusarium head blight resistance are overtaking conventional hybrid lines in North American breeding pipelines. Seed companies are prioritizing stacked-trait releases for the Southern Plains hard red winter belt. This acceleration is compressing the variety turnover cycle from eight years to four, forcing elevator operators to segregate more narrowly.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is mandating cold-storage retrofits across European grain handling infrastructure. Elevator operators face capital outlays for ammonia-based systems or CO2 cascade alternatives. The baking and milling segment, with its temperature-sensitive semolina and specialty flour inventories, bears the steepest compliance cost trajectory.
Identity-preserved contracting is displacing spot-market accumulation for high-value wheat categories. Pasta manufacturers in Italy and Japan are locking in multi-year durum supply agreements directly with Canadian and Australian farm cooperatives, bypassing traditional merchant intermediaries. This disintermediation concentrates most visibly in the premium semolina channel, where traceability commands measurable price premiums.
Global Wheat Market Segmentation
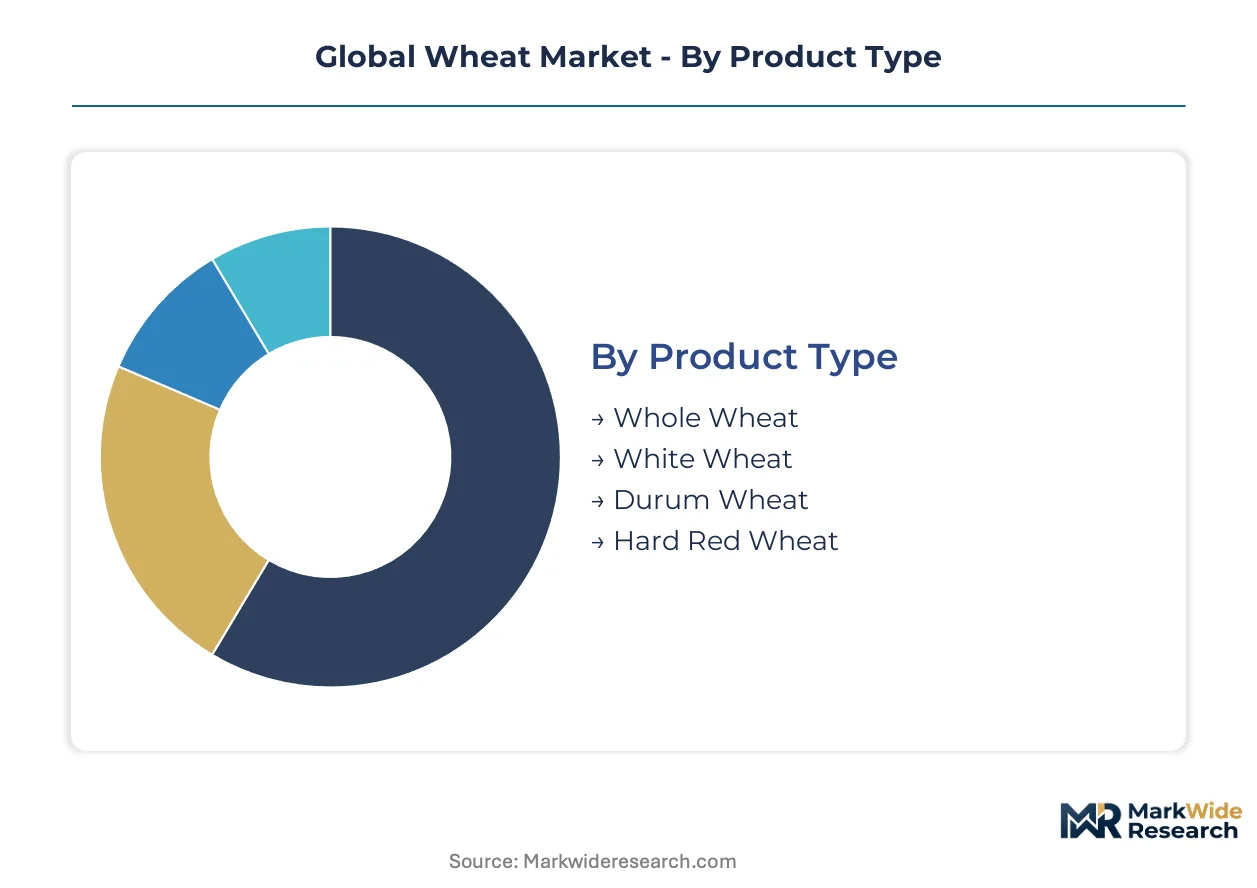
Wheat segmentation reflects divergent certification burdens across food safety, biofuel, and export corridors. Each category channels distinct regulatory compliance costs and margin structures.
Product Type:
FDA, EFSA, and FSSAI standards impose differentiated testing protocols on protein content, mycotoxin thresholds, and gluten specifications across wheat grades.
- Whole Wheat:Retains bran and germ layers with 13-16% protein content. Indian government procurement programs and EU organic labeling mandates are concentrating demand in food security channels and health-positioned bakery segments.
- White Wheat:Milled to remove bran and germ, yielding finer flour with 10-12% protein. Japanese noodle manufacturers and Southeast Asian steamed bread processors specify white wheat for texture consistency, tightening Australian and US Pacific Northwest origination premiums.
- Durum Wheat:Elevated gluten strength and semolina extraction rates suit pasta extrusion. Italian and Japanese mills lock identity-preserved contracts with Canadian and Australian farm cooperatives.
- Hard Red Wheat:High protein content (13-15%) supports bread loaf volume. US Plains elevators segregate hard red winter and spring sub-varieties for export to North African and Middle Eastern milling markets.
Leading the category by volume: White Wheat. Growing fastest: Durum Wheat.
End Use:
Application-specific quality tiers stratify procurement relationships, with industrial buyers demanding tighter specification bands than commodity channels.
- Baking:Absorbs the largest volume share across artisan, industrial, and frozen dough segments. Egyptian and Indonesian flour millers source blended hard and soft wheats for flatbread and pan bread production.
- Pasta Production:Requires durum semolina with minimum 12% protein and amber color index. Italian pasta manufacturers enforce blockchain traceability from Canadian prairie farms to processing facilities.
- Animal Feed:Lower-protein wheat grades substitute for corn and sorghum in poultry and swine rations when price spreads favor inclusion. EU biofuel refineries compete for feedstock-grade supply under renewable energy mandates.
- Beer Production:Specialty malted wheat varieties contribute head retention and haze stability to Belgian-style and American wheat beers. Craft brewery procurement favors small-lot contracts with identity-preserved handling.
Volume concentration: Baking. Steepest expansion trajectory: Animal Feed.
Distribution Channel:
Channel selection determines documentation depth, with direct sales requiring origin certificates and wholesale demanding lot-traceable elevator receipts.
- Direct Sales:Large flour millers and biofuel refineries contract directly with grain elevators and farm cooperatives. These arrangements specify protein ranges, moisture limits, and delivery windows.
- Retail:Packaged flour and specialty wheat products move through supermarket chains and independent grocers. Organic and heritage varieties command shelf space in premium retail formats.
- Wholesale:Regional distributors aggregate elevator receipts for resale to smaller millers and food manufacturers. Lot blending and commingling reduce per-unit handling costs.
- Online:Direct-to-consumer platforms serve home bakers and small-scale food producers seeking heritage varieties and small-batch flours. Cold-chain logistics add cost complexity for whole-grain products.
Dominant by tonnage: Direct Sales. Gaining share fastest: Online.
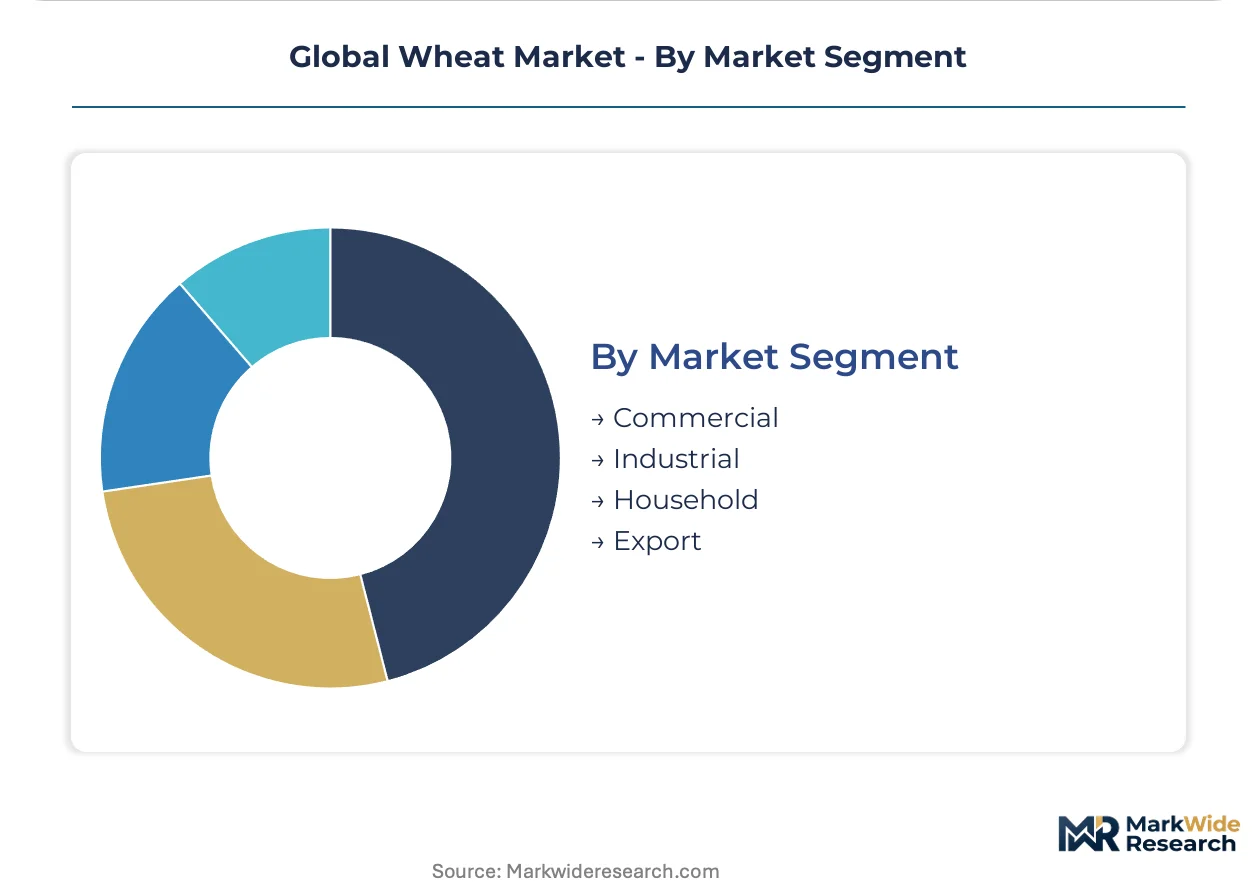
Market Segment:
Segment scale dictates financing structures, with commercial and industrial buyers accessing commodity credit facilities unavailable to household purchasers.
- Commercial:Encompasses flour milling, bakery manufacturing, and pasta production at industrial scale. Mexican and Brazilian millers represent expanding commercial demand within Mercosur trade zones.
- Industrial:Starch extraction, gluten processing, and biofuel ethanol production consume lower-grade wheat in continuous-process operations. EU Green Deal renewable targets are redirecting feedstock flows.
- Household:Small-package flour and wheat berry sales through retail channels. Health and wellness positioning drives whole wheat and ancient variety adoption.
- Export:Bulk vessel shipments from Black Sea, US Gulf, and Australian ports to deficit markets in North Africa, Middle East, and Southeast Asia. FSSAI clearance timelines and BIS laboratory capacity constrain Indian-bound shipments.
Volume leader: Commercial. Climbing the fastest: Export.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Prairie Provinces of Canada anchor North American hard wheat production, while the Indo-Gangetic Plain drives Asian consumption gravity. Regulatory divergence across FSSAI, USDA, and EU Green Deal jurisdictions is fragmenting trade corridor economics.
United States
Hard red winter and spring wheat varieties from Kansas and North Dakota supply Egyptian and Indonesian flour millers. USDA grading standards and FDA food safety mandates shape export competitiveness. Gulf Coast elevators in Houston and New Orleans aggregate Plains-origin grain for bulk vessel loading to North African markets.
India
Government food security programs and state-sponsored milling infrastructure expansion absorb record import volumes. FSSAI and BIS standards govern import quality specifications and domestic food safety compliance. Port clusters in Mumbai and Kandla face clearance bottlenecks from laboratory capacity constraints.
Canada
Canadian prairie farm cooperatives lock identity-preserved durum contracts with Italian and Japanese pasta manufacturers. CFIA phytosanitary protocols align with EU Green Deal sustainable agriculture benchmarks. Vancouver and Thunder Bay terminals channel Prairie-origin wheat to Pacific Rim and Atlantic markets respectively.
Australia
Precision agriculture adoption in Western Australia and New South Wales lifts per-hectare productivity for noodle-grade white wheat. TGA-equivalent state grain authorities enforce strict varietal purity for Japanese and Southeast Asian buyers. Port infrastructure in Adelaide and Newcastle specializes in containerized specialty wheat shipments.
Brazil
Underdeveloped winter wheat cultivation in Rio Grande do Sul and Paraná offers expansion potential as Mercosur trade integration deepens. ANVISA food safety alignment with Mercosur protocols streamlines cross-border flour milling supply chains. São Paulo-based millers represent the dominant commercial demand concentration within the trade zone.
Global Wheat Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue carbon-credit-linked origination and blockchain traceability premiums. The vendor base concentrates around vertically integrated grain merchants with captive port assets and elevator networks. Three archetypes dominate: multinational traders with origination-to-export control, regional millers with backward integration into elevator assets, and specialty handlers focused on identity-preserved varieties. Competitive moves center on strategic port acquisitions and regenerative agriculture certification partnerships.
Among North American-based agribusiness conglomerates, Cargill, Bunge Limited, and Archer Daniels Midland exemplify the multinational trader archetype through their elevator-to-vessel origination networks. Cargill anchors positions across North American and Australian wheat belts. Bunge Limited leverages Mississippi River system and Brazilian export terminal assets. Archer Daniels Midland completes the tier with origination density in US Plains states and European port access.
| Leading Market Players |
|---|
| Viterra |
| Ardent Mills |
| Archer Daniels Midland |
| Glencore Agriculture |
| General Mills |
| Bunge Limited |
| Louis Dreyfus Company |
| Grain Craft |
| Cargill |
| Others |
Value Chain & Pricing Dynamics
Gene-edited CRISPR variety adoption across North American breeding pipelines is compressing elevator segregation costs while concentrating origination premiums among operators with identity-preserved handling infrastructure. This dual cost-quality shift simultaneously tightens farm-level margins and rewards supply chain participants who control varietal purity from field to port.
Pricing Analysis
Certification and testing service bundling separates premium identity-preserved durum contracts from unbundled commodity spot transactions. Three-tier pricing structure across premium, standard, and economy levels reflects protein content, mycotoxin certification, and blockchain traceability investment. Price differentiation hinges on FSSAI clearance speed and EU Green Deal carbon credit eligibility. Biofuel refineries exhibit lowest price sensitivity due to mandate-backed offtake agreements, while small-scale pasta manufacturers face acute cost compression.
Supply Chain Analysis
Dual-sourcing requirements from Indian and Japanese millers mandate simultaneous Ukrainian and Canadian supplier qualification to mitigate Black Sea corridor disruption risk. Geographic supply concentration centers on Russia, Ukraine, and Australia for exportable surplus. Raw material dependencies encompass ammonium nitrate fertilizers, potash from Belarusian-affected supply, and certified seed stock. Tariff exposure from EU F-Gas Regulation compliance costs threatens European elevator operating margins. Distribution runs through vertically integrated merchant networks with captive Gulf Coast and Black Sea terminal assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Wheat Market has become a vertical-integration race where origination-to-port control determines margin capture. Players are pursuing backward integration into precision agriculture service platforms to lock in varietal specification compliance.
For Market Incumbents: Anchor defensive positioning through exclusive elevator receipt systems tied to CRISPR variety segregation protocols. Consolidate threatened market share by acquiring Brazilian winter wheat cultivation assets before Mercosur integration accelerates. Cargill-type origination networks face disintermediation pressure from direct farm-to-mill blockchain contracting.
For New Entrants and Emerging Players: Launch via carbon-credit-linked procurement platforms targeting EU CSRD disclosure-compliant buyers seeking regenerative rotation verification. White-space concentration sits with underdeveloped Rio Grande do Sul cultivation and heritage variety direct-to-consumer channels. FSSAI certification bottlenecks create service-layer entry points for laboratory capacity expansion.
For Investors and Strategic Acquirers: Re-rating potential sits with identity-preserved specialty handlers given EU renewable energy mandate expansion and pasta manufacturer traceability premiums. Long-term viability favors operators with dual Black Sea and Pacific Rim port access. Monitor biofuel policy threshold adjustments as inflection signal for feedstock-grade demand redirection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Agriculture | Cargill-type merchants lock varietal specification compliance through satellite-guided farm service platforms. |
| Identity-Preserved Contracting Expansion | Italian pasta manufacturers bypass traditional intermediaries via direct Canadian prairie cooperative agreements. |
| Carbon Credit Certification Program | EU CSRD disclosure requirements reward regenerative wheat rotations with sustainability-linked procurement premiums. |
| Blockchain Traceability Implementation | Distributed ledger integration with elevator receipts enables origin-verified premium tiers for durum varieties. |
| Black Sea Corridor Diversification | Ukrainian port infrastructure investments compress traditional Atlantic shipping lanes and redraw trade flows. |
Study Parameters
USDA crop production reports, EU F-Gas Regulation compliance filings, and FSSAI import clearance databases formed the secondary backbone. Primary interviews with grain elevator operators, pasta manufacturer procurement directors, biofuel refinery feedstock managers, and carbon credit verification specialists validated segmentation assumptions. Bottom-up acreage and yield estimates triangulated against top-down trade flow analysis from customs and vessel tracking data.
Historical trendline analysis of varietal adoption cycles and protein premium spreads informed projection elasticity. The analytical framework segments by product type, end use, distribution channel, and market segment across the modeling period. CAGRs derive from supply-demand balance modeling incorporating biofuel mandate trajectory, Indian government procurement expansion, and climate volatility pattern assumptions.
The model assumes a particular technology adoption path; alternative pathways for CRISPR drought-tolerance traits would alter the outlook. Forecasts reflect assumptions regarding Black Sea corridor stability, EU renewable energy target enforcement, and FSSAI laboratory capacity expansion. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
North America Wheat Flour Market
Grains
Asia-Pacific Wheat Market
Grains
Egypt Rice Market
Grains
Italy Rice Market
Grains
Uganda Grains Market
Grains
Soya Flour Market
Grains
Non-Basmati Rice Market
Grains
Green Pea Grits Market
Grains
Corn Flour Market
Grains
Spelt Wheat Market
Grains
Paraguay Grains Market
Grains
Dried Spent Grain Market
Grains
Europe Wheat Market
Grains
Grain and Cereal Crop Market
Grains
GMO Corn Market
Grains
South American Maize Market