
 Ancient Grain Market | 2026-2036
Ancient Grain Market Size, Share, and Industry Trends Forecast 2026-2036
Ancient Grain Market Analysis
The capital-intensity divergence between integrated millers and specialty grain processors is unwinding as scale advantages erode. Bob's Red Mill leverages its employee-owned structure to sustain premium pricing in direct-to-consumer channels. Ardent Mills anchors North American supply through its network of regional flour mills and grain elevators. The J. M. Smucker Company competes by extending its breakfast and snacking portfolio into ancient grain formulations.
Ancient grains comprise cereal species cultivated for millennia with minimal genetic modification, typically exhibiting higher protein, fiber, and micronutrient density than modern wheat cultivars, and they serve functional roles in gluten-free, high-fiber, and clean-label food systems. Quinoa and farro lead product type demand due to established consumer recognition and versatile culinary applications, while millet is gaining traction in gluten-free baking as formulators seek cost-competitive alternatives to almond and coconut flours. Whole grain form dominates volume through health food retail and bakery channels, though flour and flake forms command stronger margin pools in food manufacturing where processing efficiency reduces downstream waste.
The USDA organic certification and FDA food labeling standards govern product claims and interstate commerce in the United States, while the EU Green Deal and EFSA nutrition protocols shape import requirements and sustainability benchmarks across European markets. India's FSSAI and BIS standards increasingly influence export-oriented suppliers targeting its expanding health food sector. Stakeholders must monitor how evolving carbon-accounting rules and regenerative agriculture certifications reshape sourcing premiums and supplier qualification criteria.
Market Dynamics
Clean-label certification requirements and regenerative agriculture premiums are compressing margins for conventional grain processors while rewarding certified organic suppliers with pricing power in direct-to-consumer channels.
Growth Catalysts
- EU Green Deal carbon-accounting mandates:Food manufacturers across Germany, France, and Italy now require verified regenerative sourcing credentials to meet Scope 3 reduction targets, pulling premium ancient grains into formulated products.
- Gluten-free bakery expansion:Millet and sorghum formulations are displacing almond and coconut flours in cost-sensitive gluten-free applications, opening volume channels beyond health food retail.
- India's FSSAI health food standardization:The regulator's codification of ancient grain nutritional claims is enabling export-oriented suppliers to access organized retail and e-commerce platforms in Mumbai and Bangalore.
Market Restraints
- Input cost volatility:Organic quinoa from the Peruvian Altiplano faces price swings from drought-induced yield compression, destabilizing contract pricing for North American millers.
- Supply concentration risk:Ethiopian teff exports remain concentrated through Addis Ababa trading houses, creating single-point vulnerability for European specialty bakers.
- Technical limitation:Ancient wheat varieties lack the gluten strength of modern cultivars, restricting their use in industrial bread production without expensive enzyme supplementation.
Strategic Opportunities
- Underpenetrated Brazil:ANVISA's recent gluten-free labeling harmonization creates a regulatory pathway for quinoa and amaranth suppliers to access São Paulo's expanding health food retail.
- Cell-cultured hybrid applications:Precision fermentation companies are converging with grain processors to develop mycoprotein-ancient grain composite ingredients for alternative meat textures.
- USDA Climate-Smart Commodities funding:The IRA-authorized grant program offers direct payments to farmers transitioning heritage wheat and emmer into certified regenerative rotations.
Industry Challenges
- Certification timeline compression:Three-year organic conversion periods and emerging regenerative verification protocols delay supplier qualification for time-sensitive food manufacturing contracts.
- Skill scarcity in heritage grain milling:Stone milling expertise for preserving ancient grain germ integrity has atrophied as industrial roller milling dominated wheat processing for decades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ancient Grain Market |
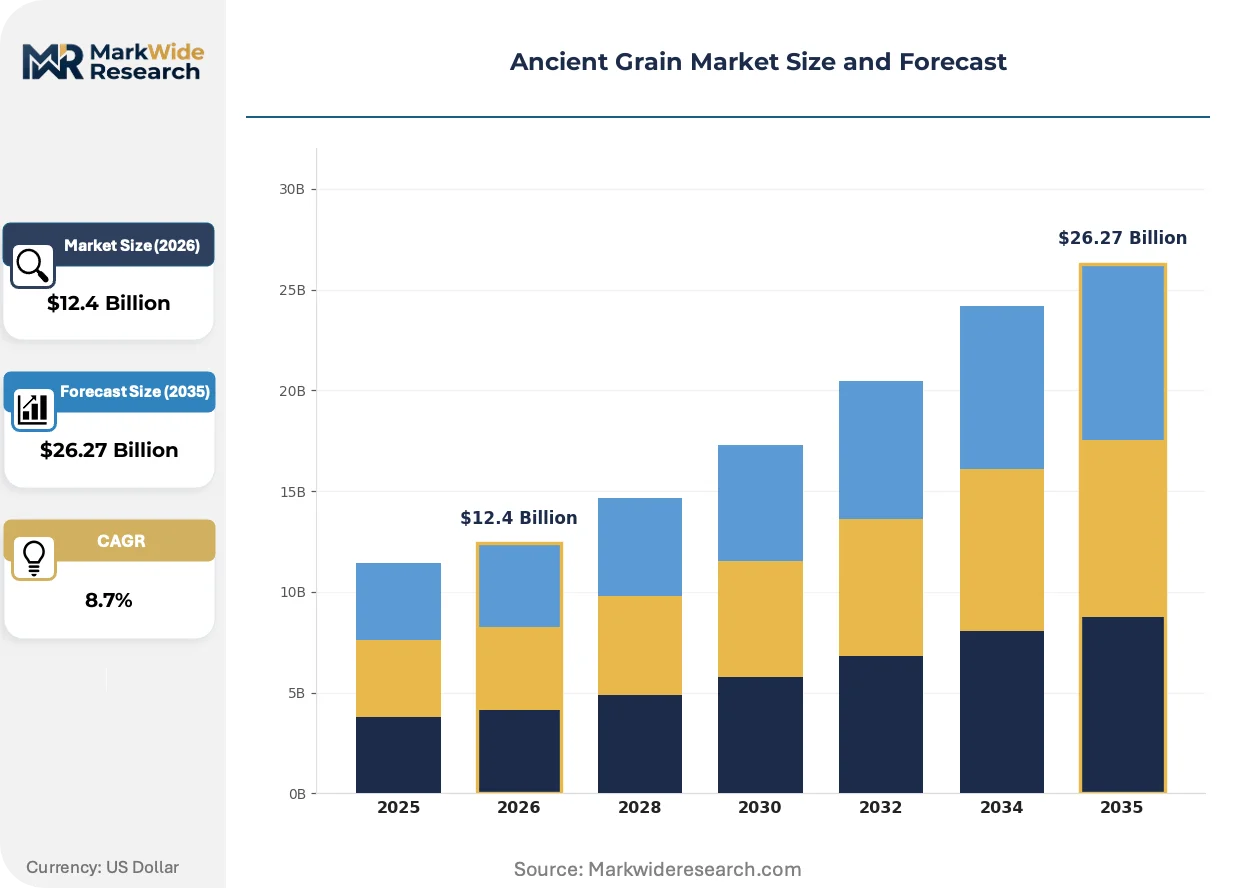
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quinoa, Farro, Barley, Millet Form: Whole Grain, Flour, Couscous, Flakes End User: Food Manufacturers, Bakeries, Restaurants, Health Food Stores Distribution Channel: Online Retail, Supermarkets, Organic Stores, Direct Sales |
| Companies Covered | Bob's Red Mill, The J. M. Smucker Company, Archer Daniels Midland Company, Ingredion Incorporated, Ardent Mills, Cargill, Incorporated, Nature's Path Foods, The Hain Celestial Group, Inc., General Mills, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ancient Grain Market Emerging Trajectories
Processing technology convergence and procurement transparency requirements are rewriting supplier qualification criteria, favoring vertically integrated operators with captive regenerative acreage and direct-to-manufacturer digital platforms.
Sprouted ancient grain flours are supplanting conventional whole grain meals in premium infant nutrition and senior dietary products. Gerber and Nestlé's pediatric divisions have accelerated sourcing timelines for sprouted quinoa and amaranth bases. This processing innovation is supplanting enzymatic pre-digestion additives while commanding 40-60% price premiums over unsprouted equivalents.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon refrigerants is forcing grain storage and milling facilities to retrofit climate-controlled silos with ammonia or CO2-based systems. German organic milling clusters in Bavaria face six-figure capital outlays per facility. Smaller operators are responding through cooperative storage pooling arrangements to amortize compliance costs.
Direct-from-farm procurement contracts are displacing spot-market purchasing among mid-sized US bakery chains. King Arthur Baking and regional cooperatives now source heritage wheat through multi-year offtake agreements with Montana and North Dakota growers. This shift concentrates most visibly in the Pacific Northwest, where traceability marketing commands consumer willingness-to-pay premiums of 15-25% over commodity flour.
Ancient Grain Market Segmentation
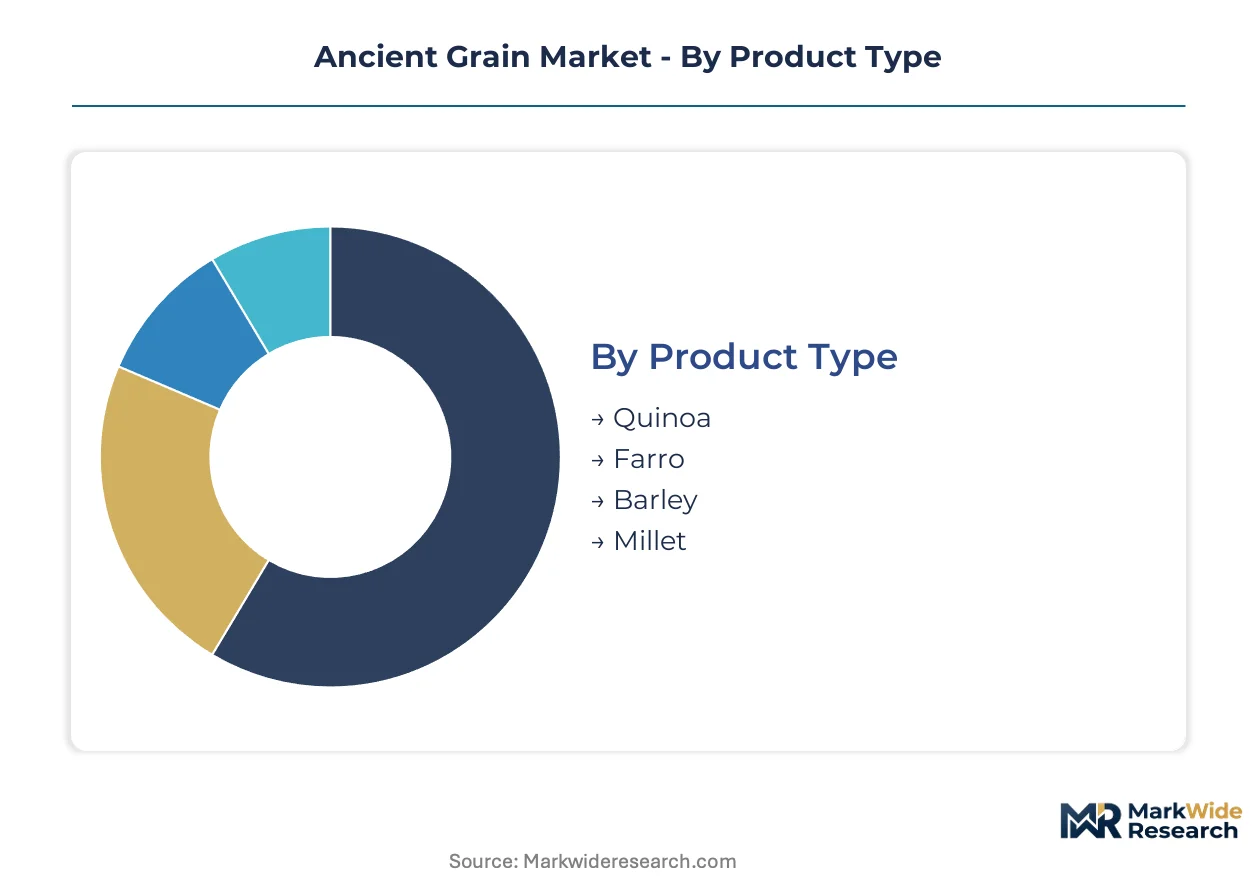
Ancient grain procurement strategies diverge sharply across product types and end-use channels, with regulatory certification requirements and processing specifications dictating supplier qualification criteria. Formulators must match grain functionality to application constraints while navigating fragmented distribution architectures that separate commodity volume from premium pricing pools.
Product Type:
USDA organic certification and EU organic regulations create divergent sourcing premiums across heritage cereal species, with altitude-origin requirements and genetic purity standards reshaping supplier landscapes.
- Quinoa:Native to the Peruvian and Bolivian Altiplano, this pseudocereal delivers complete protein profiles with all nine essential amino acids. Demand concentrates in US gluten-free manufacturing and German organic retail, where altitude-origin certification commands sourcing premiums from drought-induced yield compression.
- Farro:Three distinct wheat species—emmer, einkorn, and spelt—comprise this category, each with varying gluten content and cooking properties. Italian heritage grain cooperatives in Tuscany and Umbria anchor supply for European artisan bakeries seeking DOP-protected provenance claims.
- Barley:High beta-glucan soluble fiber content supports cholesterol-reduction health claims approved by EFSA and FDA.
- Millet:Drought-resistant cultivation and neutral flavor profile position this segment for cost-sensitive gluten-free applications displacing nut-based flours.
Established volume favors quinoa; emerging adoption favors millet.
Form:
Processing intensity and shelf-stability requirements segment margin structures, with minimal-intervention formats capturing health-food retail premiums while milled products unlock food-service scale.
- Whole Grain:Intact bran, germ, and endosperm preservation maximizes micronutrient density and extends shelf life through reduced surface-area oxidation. German organic milling clusters in Bavaria and Baden-Württemberg dominate supply for European health food retail, where stone-milled provenance commands consumer willingness-to-pay premiums.
- Flour:Roller and stone milling reduce particle size for incorporation into industrial baking and pasta extrusion. North American contract manufacturers prefer flour form for throughput efficiency, though enzyme supplementation costs erode margins when ancient wheat varieties lack modern gluten strength.
- Couscous:Pre-steamed and dried semolina granules from durum wheat or barley enable rapid hydration in food-service environments.
- Flakes:Rolled and toasted processing creates ready-to-eat breakfast applications with accelerated hydration properties.
Volume concentrates in flour for manufacturing efficiency; margin expansion concentrates in whole grain for retail differentiation.
End User:
Formulation expertise and certification requirements stratify customer procurement patterns, with direct-to-manufacturer contracts displacing spot-market purchasing among scaled buyers.
- Food Manufacturers:Industrial formulators of breakfast cereals, snack bars, and infant nutrition products require consistent lot-to-lot specifications and validated supply chains. Multi-year offtake agreements with Montana and North Dakota heritage wheat growers are displacing commodity purchasing among mid-sized US bakery chains.
- Bakeries:Artisan and industrial bread producers face technical constraints from ancient wheat gluten weakness, requiring enzyme supplementation or blending with modern cultivars.
- Restaurants:Menu differentiation drives procurement of heritage grain varieties with traceable provenance for narrative pricing.
- Health Food Stores:Retail shelf space allocation favors certified organic and regenerative-sourced SKUs with transparent supply chain documentation.
Contract security favors food manufacturers; sourcing flexibility favors restaurants.
Distribution Channel:
Channel selection determines margin capture and consumer education requirements, with digital platforms enabling direct-to-consumer traceability marketing.
- Online Retail:E-commerce platforms enable subscription-based replenishment and detailed provenance storytelling for premium heritage varieties. Direct-to-consumer channels sustain 40-60% price premiums over conventional retail through traceability marketing and subscription convenience.
- Supermarkets:Mass retail placement requires slotting fee investments and scaled supply guarantees that favor integrated millers with captive grain elevators.
- Organic Stores:Curated assortment and educated staff support premium positioning for certified regenerative and heritage-protected varieties.
- Direct Sales:Farm-gate and farmers-market channels capture maximum margin for small-scale producers with established local recognition.
Scale economies favor supermarkets; margin retention favors online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German buyers absorb steep organic premiums for certified provenance, while Indian procurement prioritizes cost-competitive millet for gluten-free mass-market penetration. US demand splits between coastal traceability premiums and Midwest volume efficiency.
Germany
Clean-label certification and EU Green Deal Scope 3 mandates drive food manufacturer procurement of regenerative-sourced ancient grains. The F-Gas Regulation forces Bavarian organic milling clusters to retrofit climate-controlled silos with ammonia-based refrigeration systems. Stone-milling heritage in Baden-Württemberg preserves germ integrity for health food retail premiums.
United States
Direct-from-farm contracts displace spot purchasing among Pacific Northwest bakery chains seeking traceability marketing advantages. USDA Climate-Smart Commodities funding under the IRA pays Montana and North Dakota farmers transitioning heritage wheat into certified regenerative rotations. King Arthur Baking anchors multi-year offtake agreements with regional growers.
India
FSSAI codification of ancient grain nutritional claims enables export-oriented suppliers to access organized retail and e-commerce platforms in Mumbai and Bangalore. Cost-sensitive gluten-free baking drives millet adoption as almond flour displacement accelerates. Maharashtra and Karnataka processing hubs scale for domestic health food sector expansion.
Peru
Altitude-origin quinoa from the Altiplano commands sourcing premiums despite drought-induced yield compression destabilizing contract pricing. Organic certification requirements and genetic purity standards reshape supplier landscapes around Puno and Cusco. Trading houses consolidate export logistics for North American gluten-free manufacturing demand.
Italy
Artisan bakery demand for DOP-protected farro varieties anchors Tuscan and Umbrian heritage grain cooperatives. EFSA nutrition protocols shape import requirements for beta-glucan health claims in barley formulations. Emilia-Romagna pasta extruders blend ancient wheat varieties with modern cultivars to overcome gluten strength limitations.
Ancient Grain Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages eroding as regenerative certification and direct-to-consumer traceability rewrite supplier qualification criteria. Integrated millers with captive grain elevators compete against employee-owned structures sustaining premium pricing through mission-driven branding. Strategic archetypes include vertically integrated commodity processors, specialty organic millers with stone-milling expertise, and diversified food manufacturers extending breakfast and snacking portfolios. Competitive moves concentrate on multi-year grower offtake agreements and cooperative storage pooling to amortize F-Gas compliance costs.
Within the employee-owned specialty tier, Bob's Red Mill represents mission-driven premium positioning in direct-to-consumer channels. Ardent Mills anchors North American supply security through regional flour mill and grain elevator networks. The J. M. Smucker Company occupies a diversified portfolio position extending packaged food formulations into ancient grain ingredients. These three exemplify distinct competitive archetypes: purpose-driven specialty milling, scale-integrated commodity processing, and brand-extended food manufacturing.
| Leading Market Players |
|---|
| Bob's Red Mill |
| The J. M. Smucker Company |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Ardent Mills |
| Cargill, Incorporated |
| Nature's Path Foods |
| The Hain Celestial Group, Inc. |
| General Mills, Inc. |
| Others |
Supply Flow & Price Mechanics
Multi-year offtake agreements between Montana heritage wheat growers and Pacific Northwest bakery chains lock in supply access while providing price visibility against Peruvian Altiplano quinoa volatility. These contract structures insulate North American millers from drought-induced yield compression while exposing Ethiopian teff buyers to Addis Ababa trading house concentration risk.
Pricing Analysis
After-sales revenue from sprouted grain processing services and regenerative certification consulting drives lifetime value for specialty millers. Three-tier pricing structure across certified organic, transitional regenerative, and conventional grades separates altitude-origin quinoa premiums from cost-competitive millet positioning. Pricing pressure stems from EU F-Gas Regulation compliance costs forcing six-figure ammonia refrigeration retrofits at Bavarian milling clusters. Food manufacturers exhibit lowest price sensitivity due to validated supply chain requirements, while cost-sensitive gluten-free bakers drive millet adoption as almond flour displacement accelerates.
Supply Chain Analysis
Strategic stockpile preferences dominate Peruvian Altiplano quinoa sourcing as drought-induced yield compression forces North American buyers to secure altitude-origin inventory ahead of harvest windows. Supply concentrates in Peru, Ethiopia, and Italy for quinoa, teff, and farro respectively. Raw material dependencies include heritage wheat germplasm, organic nitrogen inputs, and stone-milling equipment. Single-source vulnerability runs through Addis Ababa trading houses for European specialty teff demand. Distribution runs through cooperative storage pooling arrangements that amortize F-Gas compliance costs across German organic milling clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from input cost cyclicality as drought-induced Peruvian quinoa yield compression normalizes and regenerative certification premiums stabilize contract pricing visibility.
For Market Incumbents: Shield market position through backward integration into captive regenerative acreage in Montana and North Dakota heritage wheat rotations, while accelerating multi-year grower offtake agreements to preempt spot-market volatility from Ethiopian teff trading house concentration. For New Entrants and Emerging Players: Anchor in Brazil's underpenetrated health food retail as ANVISA gluten-free labeling harmonization creates regulatory pathway access for quinoa and amaranth suppliers targeting São Paulo's expanding consumer base through direct-to-manufacturer digital platforms. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialty millers with stone-milling expertise and captive regenerative certifications, as five-to-ten year viability hinges on EU Green Deal Scope 3 compliance capabilities; watch for USDA Climate-Smart Commodities funding disbursement velocity as inflection indicator for heritage grain rotation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Grower Offtake Agreements | King Arthur Baking's Montana contracts demonstrate price visibility against Peruvian drought volatility. |
| Regenerative Certification Investment | EU Green Deal Scope 3 mandates reward verified sourcing credentials with manufacturing contract access. |
| Cooperative Storage Pooling | Bavarian organic milling clusters amortize F-Gas ammonia refrigeration retrofits across shared facilities. |
| Sprouted Grain Processing Expansion | Gerber and Nestlé pediatric divisions command 40-60% premiums over unsprouted quinoa equivalents. |
| Direct-to-Manufacturer Digital Platforms | Traceability marketing enables Bob's Red Mill to sustain premium pricing in subscription channels. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through primary interviews with heritage grain procurement managers at North American bakery chains, organic certification auditors, stone-milling equipment specialists, and EU regulatory affairs leads, validated against secondary sources including USDA organic certification databases, EU F-Gas Regulation implementation filings, FSSAI nutritional claim codifications, and customs trade data for Peruvian quinoa exports, with bottom-up volume triangulation against top-down market sizing.
Across the analysis window, the forecast framework models segmentation by grain species, processing form, certification tier, end-use channel, and geographic regulatory cluster, with CAGRs derived from trend extrapolation of organic conversion timelines and regenerative adoption curves, incorporating heritage wheat gluten strength limitations and enzyme supplementation cost trajectories as industry-specific inputs.
Material uncertainties — drought-induced yield compression in the Peruvian Altiplano, Ethiopian teff export trading house consolidation, and EU carbon-accounting protocol evolution — sit outside the modeled envelope. Forecasts reflect assumptions regarding organic certification three-year conversion periods and F-Gas retrofit completion schedules. Revision becomes warranted when regenerative verification protocol adoption crosses 50% penetration among German food manufacturers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Pea Grits Market
Grains
Wheat Protein Market
Grains
Global Grain Mill Products Market
Grains
Heritage Grain Market
Grains
Green Banana Flour Market
Grains
Asia-Pacific Guar Market
Grains
Ghana Grain Market
Grains
Organic Wheat Flour Market
Grains
North America Maize Market
Grains
China Maize Market
Grains
United States Maize Market
Grains
Grain Dryers Market
Grains
Dried Spent Grain Market
Grains
Pulses Market
Grains
Wheat Bran Market
Grains
Triticale Market