
 Barley Market | 2026-2036
Barley Market Size, Share, and Industry Trends Forecast 2026-2036
Barley Market Intelligence
Malt ingredient procurement is fragmenting across contract farming networks and spot-market sourcing. Cargill Incorporated leverages its grain origination infrastructure to secure origination advantages across North American growing belts. Muntons PLC sustains its specialty roasting capabilities to differentiate within premium beverage formulations. The Soufflet Group anchors its position through integrated malting operations spanning French and Eastern European barley belts.
Barley is a cereal grain of the genus Hordeum vulgare, typically containing 11-13% protein and 65-70% starch by dry weight, which undergoes controlled germination and kilning to produce malt for enzymatic conversion in brewing and distillation. Its primary commercial purpose centers on fermentable sugar production for alcohol manufacture, alongside feed and food applications. Malt-grade barley captures the dominant margin pool within product type segmentation due to stringent kernel plumpness and protein specifications. Beverage applications lead application-level demand, while farm cooperatives represent the fastest-growing end-user channel as vertical coordination deepens between growers and processors.
The EU Green Deal and F-Gas Regulation shape crop input compliance across European barley cultivation, while the USDA's crop insurance programs and FDA food safety standards govern North American market access and quality benchmarks. China's GB standards and NMPA oversight increasingly influence import specifications for malting barley entering Asian processing facilities. Stakeholders must monitor carbon accounting requirements and water-stress indices as these criteria progressively filter supplier eligibility and contract terms.
Market Dynamics
Specialty malt demand from craft breweries is fragmenting procurement architectures across contract farming networks and spot-market sourcing, while the EU Green Deal's sustainable agriculture mandates reshape crop certification requirements.
Growth Catalysts
- Craft brewery expansion:Specialty roasting specifications for small-batch production are pulling premium kernel plumpness grades into shorter supply chains.
- EU Green Deal compliance:Carbon accounting requirements for malting barley are accelerating farm-level certification adoption across Bavaria and Eastern European growing belts.
- Farm cooperative vertical coordination:Backward integration between growers and processors is compressing origination margins and securing varietal traceability.
Market Restraints
- Input cost volatility:Nitrogen fertilizer price swings tied to natural gas markets destabilize farm-level margin planning.
- Supply concentration risk:French and Eastern European malting belts dominate premium-grade origination, creating single-region exposure.
- Regulatory friction:China's GB standards and NMPA import specifications add inspection layers for Asian-bound shipments.
Strategic Opportunities
- Underpenetrated feed-grade markets:India and Southeast Asian livestock sectors offer volume expansion for lower-specification barley grades.
- Carbon credit monetization:EU Green Deal soil carbon protocols enable certified growers to capture secondary revenue streams.
- Direct-to-brewer channels:E-commerce platforms and regional malt houses are disintermediating traditional grain merchants.
Industry Challenges
- Malting technician scarcity:Controlled germination and kilning expertise is concentrating among legacy European operators.
- Capex intensity for roasting capacity:Specialty drum roasting equipment requires multi-year payback periods.
- Dual certification timelines:Organic and carbon-neutral accreditations impose overlapping audit burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barley Market |
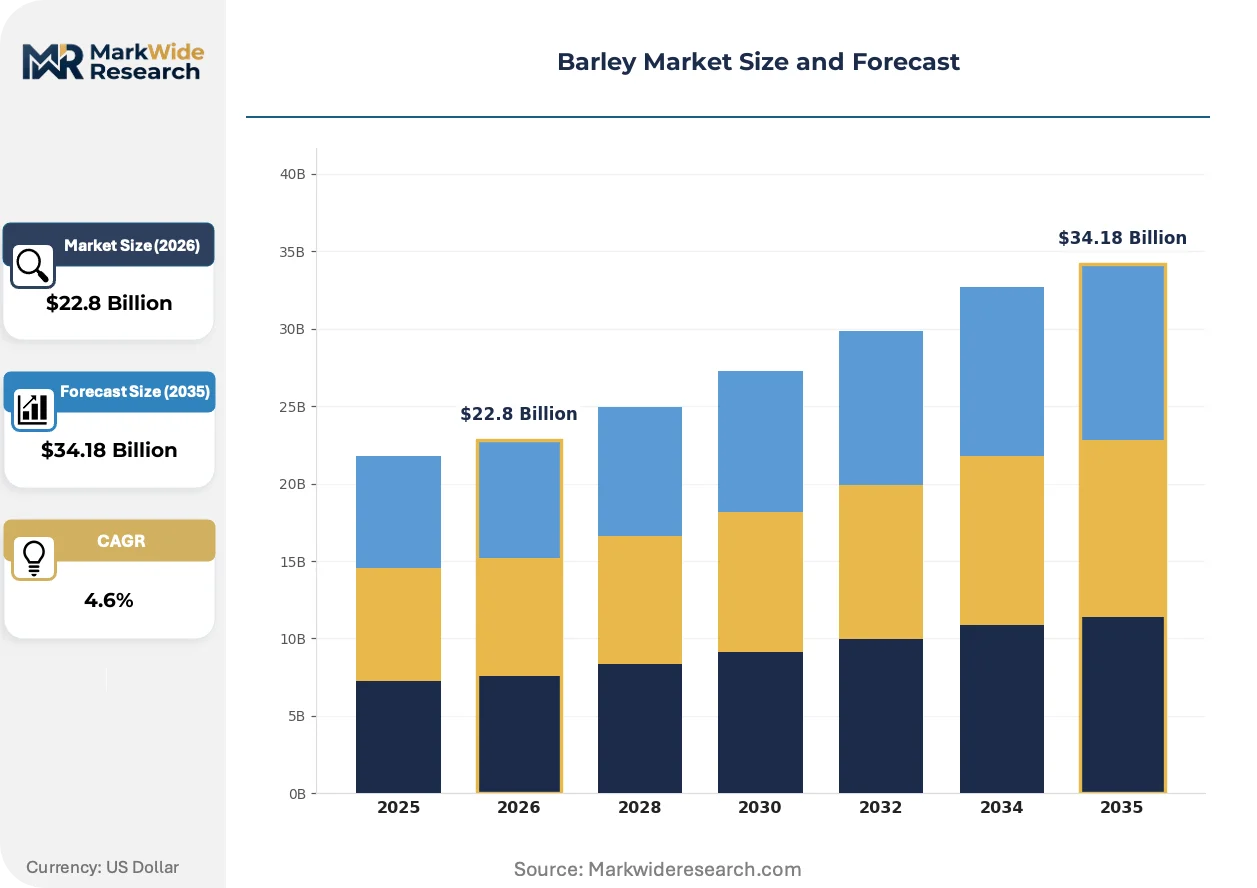
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $34.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Animal Feed, Malt, Industrial Application: Beverages, Food Processing, Animal Nutrition, Biofuel End User: Beverage Manufacturers, Farm Cooperatives, Food Producers, Breweries Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Malteurop Groupe S.A., Muntons PLC, Cargill Incorporated, Briess Malt & Ingredients Co., IREKS GmbH, The Soufflet Group, Crisp Malting Group, Grain Millers Inc., GrainCorp Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barley Market Strategic Shifts & Innovations
Digital agronomy tools and precision fermentation are compressing traditional malting timelines, while regulatory carbon accounting forces traceability investments.
Near-infrared spectroscopy is virtualizing kernel quality assessment at intake points. Regional malt houses in Germany and the Czech Republic are adopting inline protein and moisture detection. This technology is virtualizing laboratory turnaround times and enabling real-time pricing adjustments.
The EU F-Gas Regulation and national carbon border adjustments are imposing emissions disclosure requirements on imported grain. Malting operations must now document cultivation-phase greenhouse gas intensity. German and Polish processors are investing in supplier audit platforms to maintain market access.
Spot-market hedging through digital commodity exchanges is displacing long-term contract dominance. Craft breweries in Bavaria and Bohemia are building direct supplier relationships via blockchain-traceability platforms. This behavioral shift is most visible in premium pilsner and lager segments where varietal provenance commands price premiums.
Barley Market Segmentation
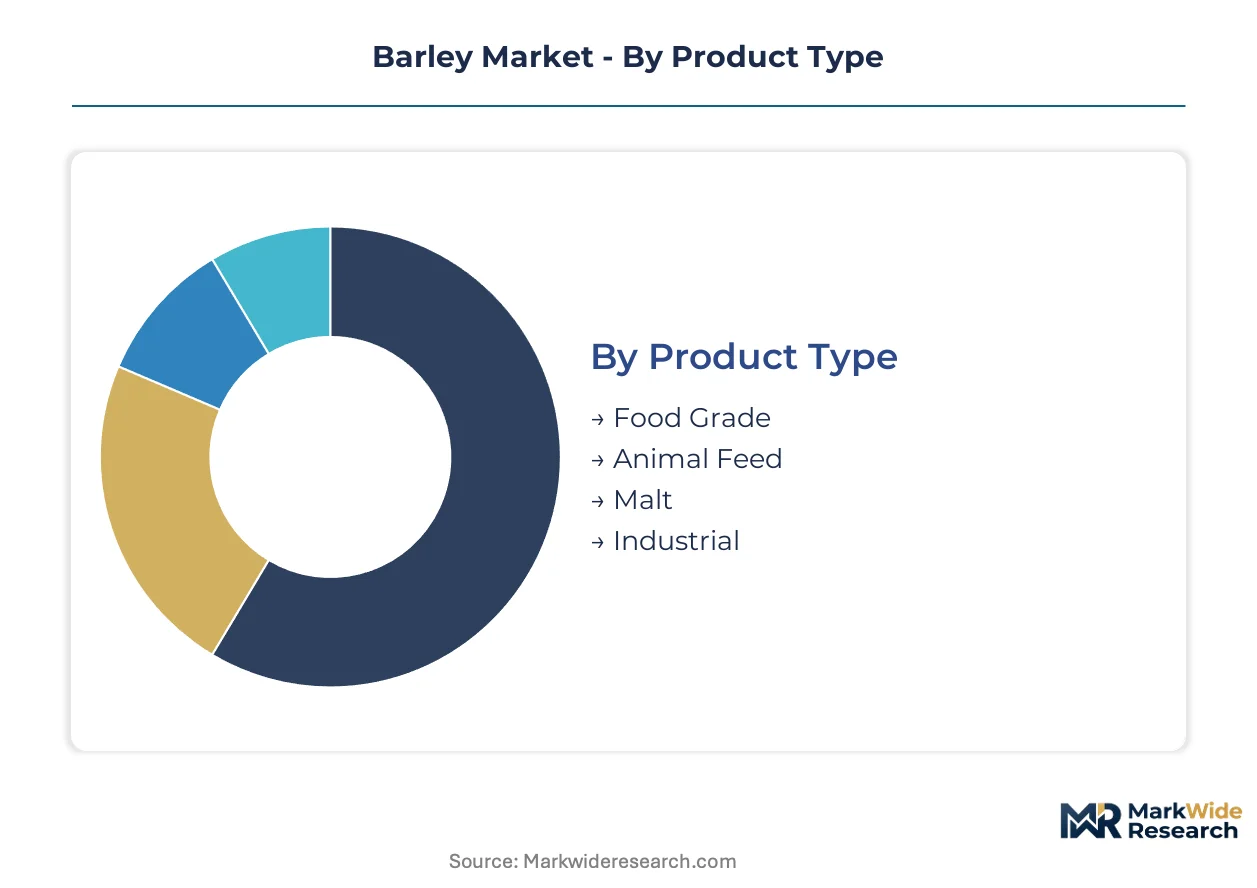
Barley procurement patterns diverge sharply across end-use specifications, with malt-grade premiums reflecting enzymatic performance requirements while feed-grade volumes track livestock economics. Understanding these segment boundaries enables targeted origination strategies and margin capture across divergent quality tiers.
Product Type:
Cost tier differentiation separates commodity feed grades from specification-intensive malting varieties, with protein and kernel plumpness thresholds determining price multiples.
- Malt:Germinated and kilned barley delivering diastatic enzymes for starch conversion in brewing and distillation. Bavarian craft breweries and Czech lager producers anchor demand for premium kernel plumpness specifications above 90%. The EU Green Deal's carbon accounting requirements are accelerating farm-level certification adoption across German and Eastern European malting belts.
- Animal Feed:Lower-protein grades destined for ruminant and monogastric livestock rations, typically bypassing malting quality thresholds. India's expanding dairy sector and Southeast Asian poultry operations are pulling volume expansion for feed-grade specifications that tolerate higher fiber content and lower test weights.
- Food Grade:Pearled or flaked barley for human consumption in soups, cereals, and health-oriented products. BIS standards in India and FDA guidelines in the United States govern mycotoxin limits and processing hygiene.
- Industrial:Non-food applications spanning bio-based materials, paper sizing, and biochemical feedstocks. Emerging demand from European bioplastics producers is testing supply chain adaptability for non-standard kernel specifications.
Malt commands the established base. The steepest expansion runs through Animal Feed.
Application:
End-use functionality determines procurement architecture, with enzymatic performance requirements in beverages contrasting against caloric density priorities in animal nutrition.
- Beverages:Fermentation applications spanning beer, whiskey, and malt-based drinks, where diastatic power and fermentable extract drive sourcing decisions. German and Czech brewing clusters maintain stringent varietal traceability requirements, with Bohemian Saaz and Bavarian Hallertau heritage varieties commanding origination premiums.
- Animal Nutrition:Ruminant feed rations and compound feed formulations where metabolizable energy and crude protein content determine value. Vietnamese and Indonesian aquafeed producers are testing barley inclusion rates as fishmeal substitution pressures intensify.
- Food Processing:Ingredient applications in baked goods, breakfast cereals, and plant-based meat extenders. Health Canada and FDA oversight governs gluten content labeling and allergen management protocols.
- Biofuel:Cellulosic ethanol and biogas substrates where starch content and harvest moisture affect conversion economics. Polish and Danish anaerobic digestion facilities are contracting dedicated feedstock supply.
Beverages anchors revenue concentration. Animal Nutrition is climbing the fastest.
End User:
Customer type shapes contract structure, with integrated beverage manufacturers favoring long-term origination agreements while farm cooperatives compress spot-market cycles.
- Farm Cooperatives:Grower-owned processing entities that backward integrate into malting and feed manufacturing, securing varietal traceability and margin capture. Eastern European cooperative networks in Poland and Romania are expanding roasting capacity to serve craft brewery clusters directly.
- Beverage Manufacturers:Integrated brewing and distilling operations with captive malt houses or tight supplier partnerships. Guinness at St. James's Gate and Pilsner Urquell in Plzeň maintain heritage varietal programs with multi-decade breeding commitments.
- Food Producers:Cereal manufacturers and ingredient suppliers sourcing pearled or flaked barley for consumer packaged goods. General Mills and Kellogg's procurement specifications drive kernel size uniformity requirements.
- Breweries:Independent craft and regional beer producers, often sourcing through specialized malt houses rather than direct grain origination. Bavarian microbreweries in Bamberg and Freising are building blockchain-traceability platforms for direct farmer relationships.
Beverage Manufacturers command the established base. Farm Cooperatives are gaining share fastest.
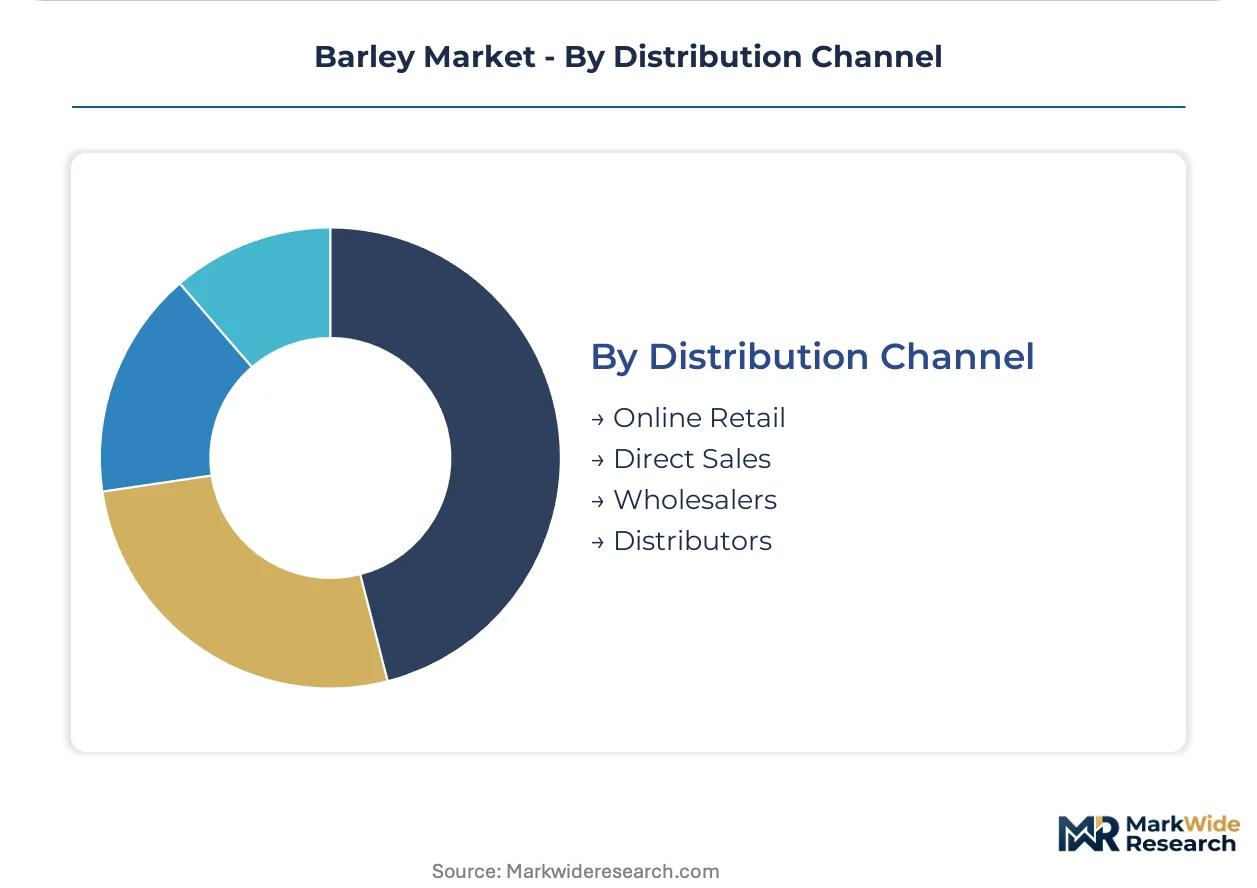
Distribution Channel:
Supply chain configuration determines price transparency and working capital intensity, with direct sales compressing merchant margins while digital platforms fragment traditional wholesale relationships.
- Direct Sales:Origination contracts linking processors to farm cooperatives or large-scale growers, eliminating intermediary handling. Cargill's North American grain origination infrastructure and Soufflet's French-Eastern European integrated malting operations exemplify this channel's margin compression effects.
- Distributors:Regional grain merchants aggregating multiple origins for resale to smaller processors and feed compounders. Traditional merchant networks in Australia's grain belt and Argentina's Pampas maintain quality blending capabilities.
- Online Retail:Emerging digital commodity exchanges and farm-to-processor platforms enabling spot-market hedging and price discovery. Bohemian craft breweries are piloting blockchain-traceability procurement through specialized agricultural e-commerce platforms.
- Wholesalers:Volume aggregators serving feed mills and food manufacturers with standardized grade specifications. Lower-margin operations dominate this channel where price competition limits service differentiation.
Direct Sales commands the established base. Online Retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the Czech Republic concentrate malt-grade consumption for brewing heritage, while Australia and Canada dominate export origination for Asian feed markets. France and Poland anchor European malting capacity through integrated cooperative networks. This geographic specialization creates divergent procurement architectures across premium beverage and commodity feed channels.
Germany
Bavarian craft breweries and industrial lager producers pull premium kernel plumpness specifications above 90%. The EU Green Deal's carbon accounting requirements accelerate farm-level certification adoption across Franconian and Hallertau growing belts. Bamberg and Freising microbreweries build blockchain-traceability platforms for direct farmer relationships.
Czech Republic
Bohemian Saaz heritage varieties command origination premiums from Pilsner-style lager producers. EU F-Gas Regulation emissions disclosure requirements reshape malting operation compliance documentation. Plzeň maintains multi-decade breeding commitments with captive malt houses for varietal purity.
France
Integrated malting operations across Champagne and Picardy barley belts secure varietal traceability through cooperative backward integration. ECHA REACH compliance governs crop input registration across malting-grade cultivation. Soufflet Group operations anchor premium origination through French-Eastern European supply corridors.
Australia
Grain export infrastructure serves Asian feed-grade demand from Vietnamese aquafeed and Indonesian poultry operations. The country's national agricultural regulator oversees mycotoxin limits for barley shipments entering Chinese processing facilities. New South Wales and Victoria grain belts concentrate bulk export origination capacity.
Canada
Prairie province farm cooperatives expand roasting capacity to serve North American craft brewery clusters. Health Canada and PMRA oversight governs pesticide residue limits for malting-grade shipments. Alberta and Saskatchewan growing regions anchor feed-grade volume expansion for livestock sectors.
Barley Market Key Industry Players
Capability concentration sits with specialty roasting operators; scale advantage sits with grain origination conglomerates. The market structures around three tiers: integrated malting groups with captive supply networks, agricultural commodity traders with origination infrastructure, and regional specialists with heritage varietal programs. Competitive moves center on backward integration into farm-level certification platforms and direct-to-brewer channel development.
Within the integrated malting tier, Malteurop Groupe S.A. and Muntons PLC exemplify European operators with captive malting and roasting capabilities. Cargill Incorporated represents the grain origination archetype with North American infrastructure scale. These three entities anchor divergent competitive positions across premium specialty and commodity volume segments.
| Leading Market Players |
|---|
| Malteurop Groupe S.A. |
| Muntons PLC |
| Cargill Incorporated |
| Briess Malt & Ingredients Co. |
| IREKS GmbH |
| The Soufflet Group |
| Crisp Malting Group |
| Grain Millers Inc. |
| GrainCorp Limited |
| Others |
Cost & Logistics Intelligence
Nitrogen fertilizer price volatility tied to natural gas markets compresses farm-level margin planning and simultaneously widens premium-to-feed-grade price spreads while forcing processors toward backward integration into cooperative supply networks. This input cost instability rewards contracted origination over spot-market exposure.
Pricing Analysis
Long-term offtake contracts dominate malt-grade procurement from Bavarian and Czech brewing clusters, while spot-market hedging through digital commodity exchanges gains traction in feed-grade channels. Price differentiation rests on kernel plumpness specifications above 90% and EU Green Deal carbon certification status. Cost compression in standard malting grades intensifies as farm cooperatives backward integrate into roasting capacity. Craft breweries exhibit lowest price sensitivity due to heritage varietal premiums, while Southeast Asian feed compounders drive hardest bargaining on test weight tolerances.
Supply Chain Analysis
Upstream feedstock origination concentrates in France, Poland, and Romania for premium malting grades, with Australia and Canada anchoring feed-grade export volumes. The supply chain draws from nitrogen fertilizer inputs, certified seed stock, and malting technician labor pools. Single-region concentration in Eastern European malting belts creates weather-driven volume risk. Distribution runs through direct sales contracts linking processors to farm cooperatives, displacing traditional grain merchant intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barley incumbents face substitution pressure from alternative grains in feed rations and from precision fermentation in beverage applications, requiring defensive positioning around irreplaceable heritage varietals and carbon-certified origination.
For Market Incumbents: Build certification moats through EU Green Deal soil carbon protocol adoption and dual organic-carbon-neutral accreditation. Secure captive supply through cooperative equity stakes in Franconian and Hallertau growing belts. Malteurop and Muntons anchor positions through specialty roasting capabilities that precision fermentation cannot replicate. For New Entrants and Emerging Players: India's underpenetrated feed-grade market offers volume expansion as dairy sector compound feed demand accelerates. Target Southeast Asian aquafeed producers testing barley inclusion rates for fishmeal substitution. Launch through direct-to-brewer digital platforms enabling blockchain-traceability premiums from Bavarian craft clusters. For Investors and Strategic Acquirers: EU F-Gas Regulation compliance deadlines reshape the acquisition landscape toward processors with documented cultivation-phase greenhouse gas audit platforms. Five-to-ten year viability favors integrated malting groups with captive Eastern European supply corridors over pure-trading origination plays. Monitor carbon border adjustment mechanism implementation as inflection signal for certified-grower valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Farm Cooperative Backward Integration | Captures margin compression effects from direct origination contracts in Polish and Romanian belts. |
| Carbon Certification Program | Enables secondary revenue streams through EU Green Deal soil carbon credit monetization protocols. |
| Specialty Roasting Capacity Expansion | Differentiates within premium pilsner segments where Bavarian Hallertau varieties command provenance premiums. |
| Blockchain-Traceability Platform | Disintermediates grain merchants for direct farmer relationships in Bohemian craft brewery clusters. |
| Feed-Grade Geographic Expansion | Captures Vietnamese and Indonesian aquafeed volume as fishmeal substitution pressures intensify. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interviews with malting technicians, farm cooperative procurement directors, craft brewery sourcing managers, and grain origination traders. Secondary validation drew from EU F-Gas Regulation compliance filings, USDA crop insurance program data, Chinese GB standards documentation, and customs trade records. Bottom-up volume modeling triangulated against top-down value estimates across product type, application, and end-user segmentation dimensions.
Calibration anchored historical volume trajectories to observed procurement pattern shifts, with CAGRs derived from regression analysis across the projection horizon. Segmentation modeling incorporated malt-grade versus feed-grade quality tier splits, beverage versus animal nutrition application demand, and farm cooperative versus beverage manufacturer end-user channel dynamics. Forecast inputs included nitrogen fertilizer price indices, EU carbon accounting adoption curves, and craft brewery formation rates in Bavaria and Bohemia.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation startups or carbon credit aggregators would shift outcomes beyond modeled ranges. Cross-checking against USDA planted acreage reports and EU agricultural outlook publications is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Asia Pacific Wheat Protein Market
Grains
United States Rice Market
Grains
Global Flour Market
Grains
Soya Flour Market
Grains
Green Banana Flour Market
Grains
Organic Oats Market
Grains
South Africa Grain Market
Grains
Global Maize Market
Grains
Brazil Maize Market
Grains
Europe Wheat Protein Market
Grains
Global Grain Analysis Market
Grains
Black Gram Market
Grains
Oat Bran Market
Grains
Rolled Oats Market
Grains
North America Maize Market
Grains
Paraguay Grains Market