
 Alfalfa Powder Market | 2026-2036
Alfalfa Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Alfalfa Powder Market Insights
Single-serve sachet bundling is repositioning buyer choice in the alfalfa powder channel, shifting volume away from bulk canisters toward trial-sized multipacks for direct-to-consumer subscription models. Now Foods leverages its retail shelf presence to sustain visibility in conventional and natural grocery sets. Amazing Grass differentiates through flavor-forward positioning within the green powder category. Go India Organic anchors its supply chain with India-origin organic certification, competing on traceability for export markets.
Alfalfa powder consists of dried, milled aerial parts of Medicago sativa, typically processed at temperatures below 45°C to preserve chlorophyll, saponin, and carotenoid content for nutritional applications. The powder functions primarily as a plant-based protein, vitamin K, and mineral fortifier in human supplements and premium animal feed rations. Organic alfalfa commands premium positioning in nutraceutical and food-grade channels where end users require residue-free botanical identity. Conventional alfalfa retains volume leadership in animal feed applications where cost sensitivity dominates procurement decisions. Powder form maintains the largest share of human consumption, while granules and pellets serve ruminant nutrition with different handling and flow properties.
USDA National Organic Program standards and FDA Good Manufacturing Practices govern product identity, heavy metal limits, and facility sanitation for alfalfa powder sold in the United States. EFSA novel food evaluations and EU pesticide residue regulations under Regulation (EC) No 396/2005 shape import eligibility and labeling claims for European market access. India's FSSAI and APEDA organic export protocols determine whether domestic processors qualify for international shipment. Stakeholders must monitor evolving maximum residue limits for glyphosate and heavy metals, as tightening thresholds in multiple jurisdictions will force upstream cultivation and processing investments.
Market Dynamics
Organic certification thresholds are tightening procurement standards for alfalfa powder, forcing upstream suppliers to retool cultivation and processing infrastructure to meet residue-free specifications across nutraceutical and food-grade channels.
Growth Catalysts
- USDA Organic Program expansion:Rising demand for certified organic green supplements in North America is pulling premium-grade alfalfa powder into formulation pipelines for direct-to-consumer wellness brands.
- Ayurvedic wellness scaling:India's domestic herbal supplement industry is accelerating captive sourcing of alfalfa ingredients, reducing import dependency for traditional medicine manufacturers.
- Low-temperature milling advances:Sub-45°C processing protocols are preserving bioactive saponin and chlorophyll content, unlocking higher-value applications in functional nutrition.
Market Restraints
- Glyphosate residue volatility:Pre-harvest desiccation practices in conventional alfalfa cultivation create regulatory rejection risk at EU and Japanese borders.
- Organic input cost premiums:Certified organic seed and biological pest management raise cultivation expenses substantially versus conventional commodity production.
- Spirulina substitution pressure:Competing green superfoods with established supply chains and lower per-unit protein costs capture share in price-sensitive supplement formulations.
Strategic Opportunities
- Single-serve sachet formats:Trial-sized multipack bundling is opening subscription-channel penetration for green powder newcomers unwilling to commit to bulk canister purchases.
- EFSA novel food pathway:Processors achieving European novel food approval for proprietary extraction methods gain first-mover positioning in EU-compliant superfood formulations.
- Premium pet nutrition convergence:Human-grade organic alfalfa specifications are transferring into high-end companion animal supplement lines, commanding unit economics above feed-grade channels.
Industry Challenges
- Heavy metal compliance timelines:Cadmium and lead testing protocols for botanical powders extend batch release cycles, compressing working capital efficiency for smaller processors.
- Identity preservation complexity:Maintaining lot-level traceability from field to finished powder requires integrated ERP systems that many regional Indian suppliers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alfalfa Powder Market |
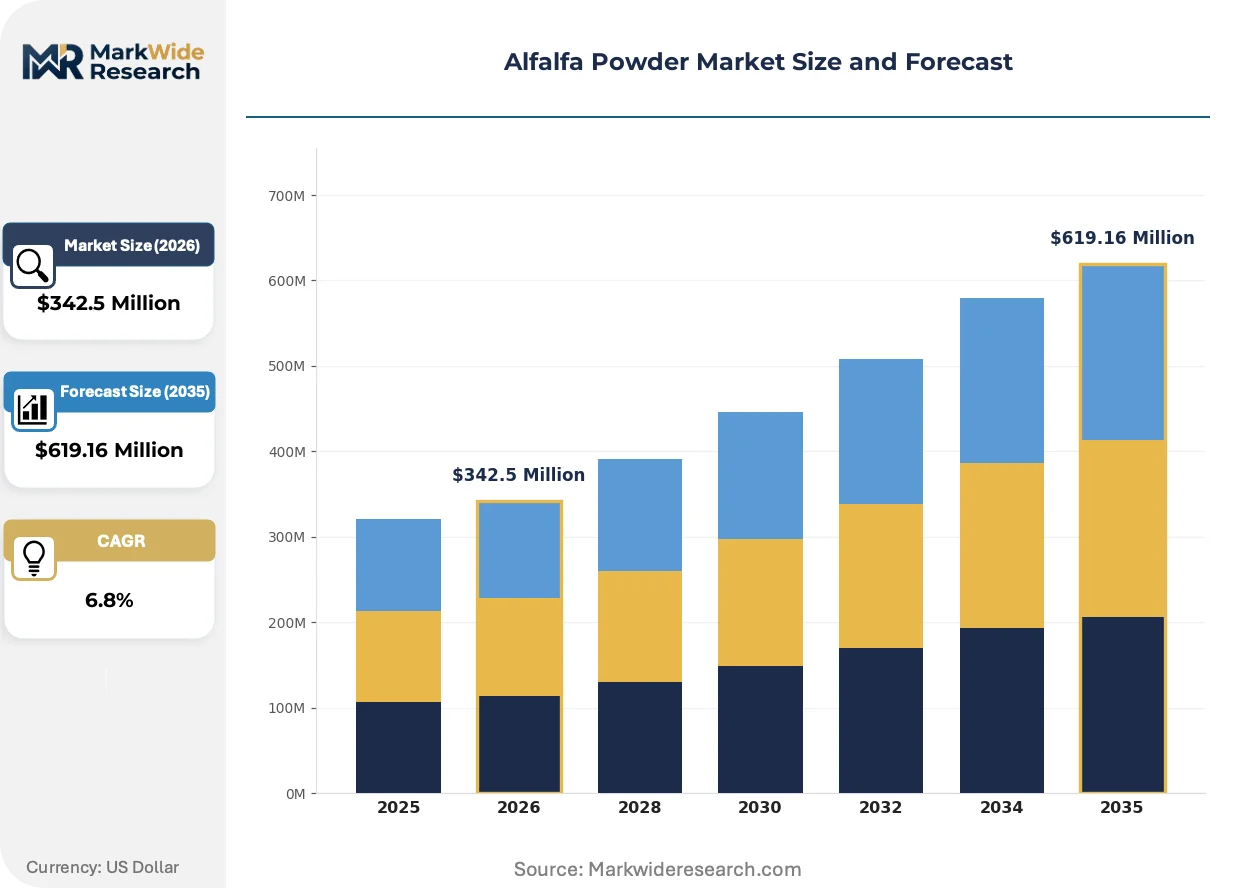
| Market Size in 2026 | $342.5 Million |
| Market Size in 2035 | $619.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Alfalfa, Conventional Alfalfa, Alfalfa Pellets, Alfalfa Extract End Use Industry: Food & Beverage, Nutraceuticals, Animal Feed, Cosmetics Form: Powder, Granules, Tablets, Liquid Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | NP Nutra, Nutrient Innovations, Go India Organic, Brewster Nutrition, Now Foods, Amazing Grass, Bare Organics, Bioriginal Food & Science Corp, Herbal Hills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alfalfa Powder Market Trends and Innovations
Processing automation and regulatory harmonization are compressing traditional supply timelines while reshaping how alfalfa powder moves from cultivation to finished formulation.
Near-infrared spectroscopy coupled with automated sorting is automating real-time chlorophyll and moisture content verification during milling operations. Mid-scale Indian processors are deploying these systems to reduce laboratory testing bottlenecks. The technology is automating quality assurance workflows that previously required manual sampling and third-party lab turnaround.
REACH Annex XVII restrictions on persistent organic pollutants are tightening import documentation requirements for botanical powders entering European customs. Compliance costs are rising for exporters lacking EU-recognized laboratory partnerships. Organic-certified Indian suppliers with pre-validated testing protocols are capturing preferential clearance timelines at Rotterdam and Hamburg ports.
Direct-to-consumer subscription bundling is displacing traditional wholesale bulk purchasing for green powder newcomers. Trial-sized sachet multipacks reduce entry barriers for hesitant buyers while capturing recurring revenue streams. This channel rotation is most visible in North American urban markets where wellness subscription boxes concentrate buyer attention.
Alfalfa Powder Market Segmentation
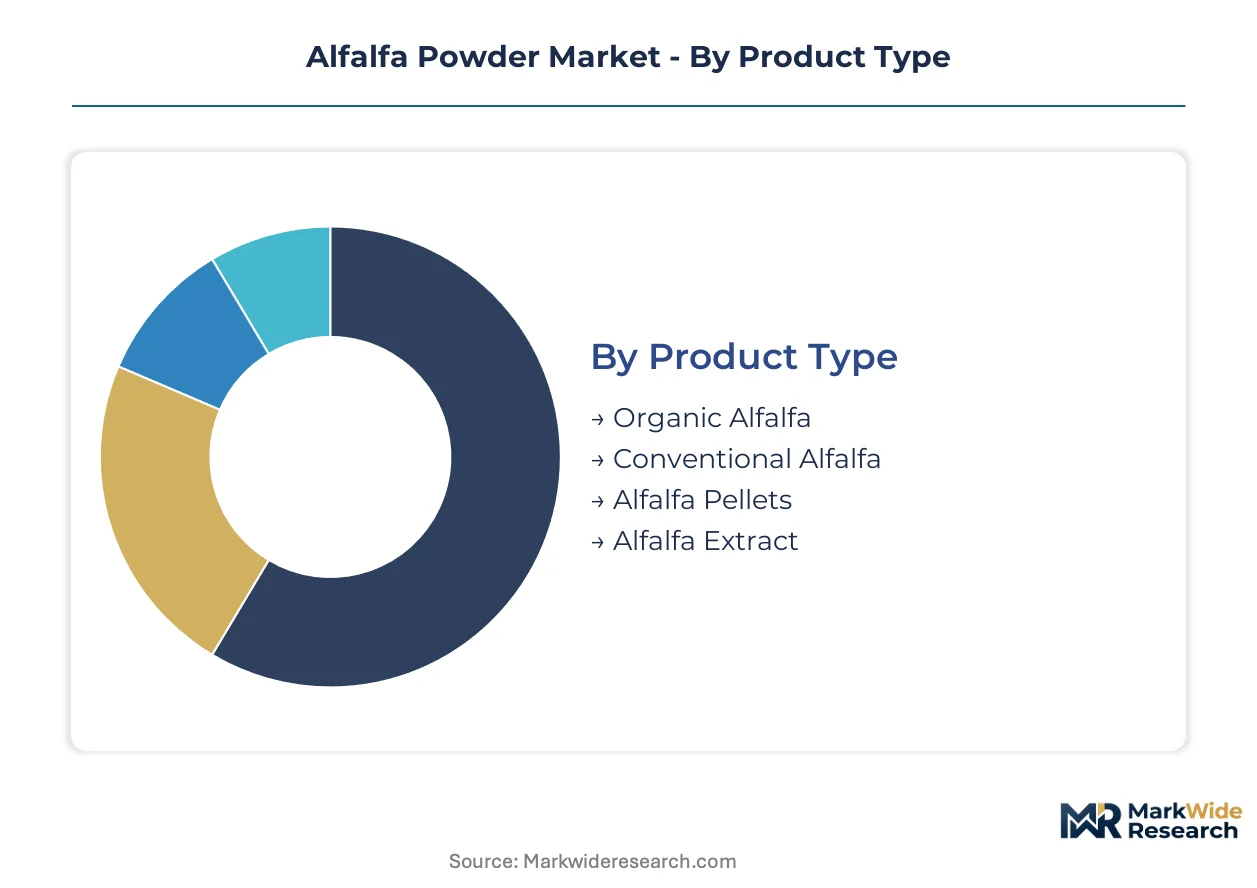
Alfalfa powder segmentation reflects divergent buyer priorities across human nutrition, animal agriculture, and cosmetic chemistry. Certification grade, particle morphology, and channel access determine procurement patterns and margin capture for suppliers.
Product Type:
Buyers select certification grade based on end-use residue tolerance and price elasticity.
- Organic Alfalfa:Cultivated without synthetic pesticides or genetically modified seed, meeting USDA National Organic Program and EU organic regulation thresholds. Nutraceutical formulators in Germany and California concentrate procurement here, driven by EFSA novel food compliance requirements and clean-label positioning in premium supplement lines.
- Conventional Alfalfa:Standard agricultural production with conventional pest management and mineral fertilization. Dairy and beef feed operations in Wisconsin and Argentina dominate volume procurement, constrained by glyphosate residue testing protocols at EU and Japanese import terminals.
- Alfalfa Pellets:Compressed cylindrical feed form with standardized density for mechanical handling systems. Ruminant nutrition programs in Australia's Murray-Darling basin specify this format for automated feeding infrastructure.
- Alfalfa Extract:Concentrated bioactive fractions standardized for saponin or chlorophyll content. Cosmetic chemists in South Korea formulate with these inputs for topical antioxidant applications.
Conventional Alfalfa leads on scale; Organic Alfalfa leads on momentum.
End Use Industry:
Application chemistry and regulatory pathway determine supplier qualification requirements.
- Food & Beverage:Fortification applications in baked goods, smoothies, and plant-based dairy alternatives. European clean-label brands in the Netherlands and Denmark source here, navigating EFSA food additive evaluations.
- Nutraceuticals:Dietary supplement capsules, green powder blends, and functional beverage formulations. Direct-to-consumer wellness brands in Austin and Toronto drive specification toward single-serve sachet compatibility and sub-45°C processing verification.
- Animal Feed:Protein and fiber supplementation for dairy cattle, horses, and poultry. Argentine and Californian alfalfa processors anchor supply contracts with large-scale livestock operations.
- Cosmetics:Topical antioxidant and anti-inflammatory ingredient applications. South Korean and French formulators specify chlorophyll-standardized grades for skin care lines.
Animal Feed commands volume concentration; Nutraceuticals exhibit the steepest expansion trajectory.
Form:
Particle engineering aligns with dissolution requirements and handling automation.
- Powder:Fine-milled aerial parts with particle size distribution optimized for beverage solubility and capsule fill density. Human supplement manufacturers in India and the United States specify this form for green blend formulations.
- Granules:Agglomerated particles with improved flow properties for tablet compression and bulk feed handling. European contract manufacturers prefer this format for high-speed encapsulation lines.
- Tablets:Pre-compressed dosage forms with binders and disintegrants for direct consumer use. Retail pharmacy channels in Japan stock these for convenience positioning.
- Liquid:Aqueous suspensions or glycerin-based extracts for beverage fortification and cosmetic serums. Functional drink innovators in California test this format for ready-to-drink green shots.
Powder dominates current procurement; Liquid is gaining share fastest among emerging format trials.
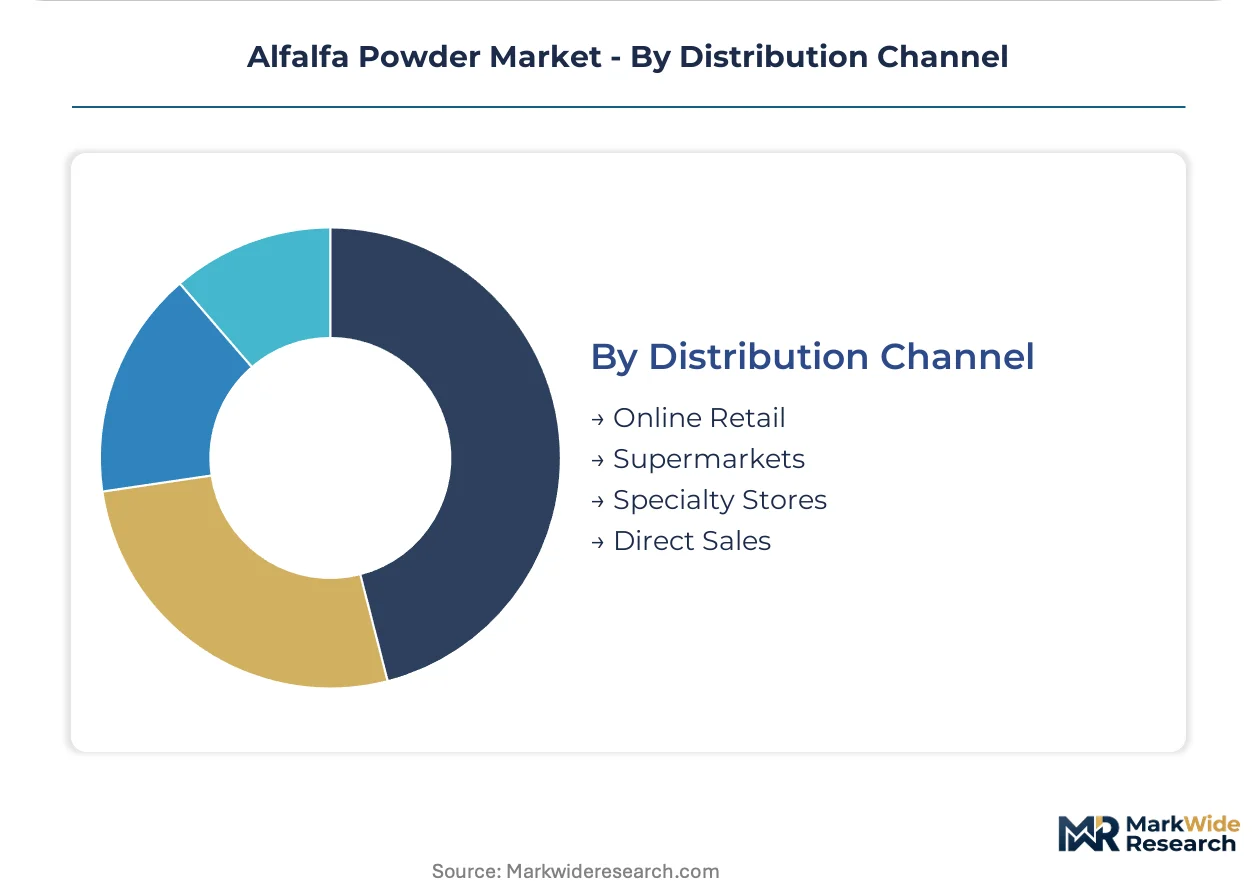
Distribution Channel:
Channel selection reflects buyer sophistication, purchase frequency, and lot size requirements.
- Online Retail:Direct-to-consumer platforms and marketplace listings enabling subscription bundling and trial-sized multipacks. North American wellness startups concentrate customer acquisition here, leveraging automated reorder algorithms.
- Supermarkets:Conventional and natural grocery shelf placement for established brands with retail velocity history. Now Foods and comparable suppliers defend position through slotting fee investments and promotional calendar coordination.
- Specialty Stores:Health food retailers, co-ops, and Ayurvedic medicine shops with trained staff consultation. Indian urban markets and European bio-shops sustain this channel through relationship-based repeat purchasing.
- Direct Sales:Bulk procurement contracts between processors and industrial formulators, feed mills, or cosmetic manufacturers. Large-volume buyers in Argentina and Australia negotiate multi-year supply agreements with identity-preserved traceability.
Direct Sales anchors industrial volume; Online Retail drives newcomer penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alfalfa cultivation and powder processing originated in the Mediterranean basin and Central Asia before scaling across North American Great Plains and South American pampas during the twentieth century. Modern procurement networks now span certified organic operations in India, mechanized hay production in the United States, and export-oriented processing in Argentina.
United States
California and Wisconsin dairy operations sustain bulk demand for conventional alfalfa pellets and powder, while nutraceutical formulators in Austin and Los Angeles specify USDA Organic-certified grades for green supplement blends. FDA Good Manufacturing Practices govern heavy metal limits and facility sanitation for domestic consumption. The Imperial Valley and Central Valley clusters anchor cultivation, with processors near Fresno deploying near-infrared spectroscopy for real-time chlorophyll verification.
India
Ayurvedic wellness brands in Maharashtra and Karnataka are scaling captive sourcing of organic alfalfa powder, reducing import dependency for traditional medicine manufacturers. FSSAI and APEDA organic export protocols determine qualification for international shipment to European and North American markets. Processing concentration sits in Gujarat and Rajasthan, where mid-scale mills are automating quality assurance to reduce laboratory testing bottlenecks.
Germany
EFSA novel food evaluations and REACH Annex XVII restrictions on persistent organic pollutants shape import eligibility for botanical powders entering Rotterdam and Hamburg ports. Clean-label brands in Berlin and Munich concentrate procurement of certified organic grades for premium supplement lines. The North Rhine-Westphalia logistics corridor serves as the primary customs clearance and redistribution hub for Indian-origin organic shipments.
Argentina
Dairy and beef feed operations in the Pampas region dominate volume procurement of conventional alfalfa pellets, constrained by glyphosate residue testing protocols at Japanese and European import terminals. National agricultural inspection protocols align with Mercosur trade standards for phytosanitary certification. Córdoba and Santa Fe provinces anchor mechanized hay production, with processors near Rosario managing identity-preserved traceability for export contracts.
South Korea
Cosmetic chemists in Seoul and Incheon formulate with chlorophyll-standardized alfalfa extracts for topical antioxidant applications in skin care lines. MFDS cosmetic ingredient regulations govern botanical extract safety assessments and labeling requirements. The Gyeonggi-do biocluster houses formulators testing liquid suspension formats for ready-to-drink green shots and functional beverage fortification.
Alfalfa Powder Market Competitive Landscape
The competitive structure tilts toward mid-scale specialists with integrated organic certification rather than diversified conglomerates. Processing capability concentrates among suppliers with captive cultivation relationships and sub-45°C milling infrastructure. Two strategic archetypes dominate: India-origin organic exporters competing on traceability documentation, and North American retail-branded formulators defending shelf position through slotting investments. Capacity expansion and single-serve format diversification represent the dominant competitive moves, with processors retooling lines for sachet bundling and subscription-channel compatibility.
Among India-origin organic specialists, Go India Organic anchors supply chain positioning with domestic certification credentials for export markets. Within the North American retail-branded tier, Now Foods leverages established grocery shelf presence across conventional and natural channels, while Amazing Grass occupies flavor-forward positioning within the green powder category. These three exemplify divergent archetypes: traceability-centric export processing, retail velocity defense, and category innovation through sensory differentiation.
| Leading Market Players |
|---|
| NP Nutra |
| Nutrient Innovations |
| Go India Organic |
| Brewster Nutrition |
| Now Foods |
| Amazing Grass |
| Bare Organics |
| Bioriginal Food & Science Corp |
| Herbal Hills |
| Others |
Pricing and Supply Chain Analysis
Alfalfa hay futures on the CME Group benchmark index cascade through cultivation contracts into finished powder pricing tiers, compressing margins for conventional processors while organic-certified suppliers capture residue-free premiums across nutraceutical channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and end-use tolerance. USDA Organic and EU organic certification tiers command substantial premiums over conventional feed-grade powder, with price differentiation driven by glyphosate testing protocols and sub-45°C processing verification. Cost compression in conventional tiers is intensifying because spirulina substitution pressures protein-equivalent formulations. Animal feed operations exhibit highest price sensitivity, while cosmetic chemists in South Korea demonstrate lowest elasticity for chlorophyll-standardized extracts.
Supply Chain Analysis
Skilled milling technicians and quality assurance specialists concentrate in Gujarat and Rajasthan processing clusters, where mid-scale Indian suppliers are automating near-infrared spectroscopy workflows to reduce laboratory bottlenecks. Raw material sourcing draws from mechanized hay operations in California's Central Valley, Argentina's Pampas region, and certified organic cultivation in Maharashtra. Single-source vulnerability runs through Rotterdam and Hamburg customs clearance nodes for EU-bound shipments. Distribution runs through direct sales contracts for industrial volume and subscription-platform bundling for direct-to-consumer penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alfalfa powder market functions as a stable compounder anchored by persistent clean-label demand from nutraceutical formulators seeking residue-free botanical identity.
For Market Incumbents: Extend backward integration into certified organic seed programs and captive cultivation to lock in residue-free supply before EU glyphosate thresholds tighten further. Deepen channel control through exclusive subscription-platform partnerships that capture recurring revenue from green powder newcomers. Spirulina substitution pressure demands sensory differentiation investments to defend shelf position against lower-cost protein alternatives. For New Entrants and Emerging Players: Enter via single-serve sachet format innovation targeting North American urban wellness subscription boxes, where trial-sized multipacks reduce buyer commitment barriers. Premium pet nutrition convergence offers the most penetrable white-space, transferring human-grade organic specifications into companion animal supplements with superior unit economics. Position through India-origin organic certification to compete on traceability documentation for European export markets. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale Indian processors possessing integrated organic certification and automated quality assurance infrastructure. The five-to-ten year viability window favors suppliers with captive cultivation relationships and sub-45°C milling capability. Watch EFSA novel food approval timelines as the critical inflection signal for first-mover positioning in EU-compliant superfood formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Seed | Captive supply of certified seed locks in residue-free cultivation for EU and North American nutraceutical channels. |
| Single-Serve Sachet Format Launch | Trial-sized multipacks reduce entry barriers for subscription-channel penetration among hesitant green powder buyers. |
| EFSA Novel Food Approval Pathway | First-mover positioning in EU-compliant superfood formulations requires proprietary extraction method validation. |
| Near-Infrared Spectroscopy Deployment | Real-time chlorophyll verification compresses batch release cycles at Gujarat and Rajasthan processing clusters. |
| Premium Pet Nutrition Line Extension | Human-grade organic specifications transfer into companion animal supplements commanding superior unit economics. |
Research Methodology
Coverage spans North America, Europe, India, and South America, with primary inputs from each region combining structured interviews with nutraceutical formulators, organic certification auditors, feed mill procurement managers, and cosmetic R&D directors with secondary validation. Trade data from APEDA export protocols, USDA National Organic Program filings, EFSA novel food registers, and EU pesticide residue monitoring reports anchor quantitative baselines. Bottom-up volume triangulation across cultivation hectares and processing capacity overlays with top-down demand segmentation from end-use industries.
Granularity-level modeling disaggregates volume and value across certification grade, particle morphology, end-use application, and distribution channel throughout the forecast period. CAGRs derive from regression analysis against organic certification adoption curves and green supplement subscription growth trajectories. Near-infrared spectroscopy penetration rates and REACH Annex XVII compliance cost trajectories inform technology adoption and regulatory scenario inputs.
Inputs from APEDA export databases and EFSA novel food registers were available through the study window; gaps in real-time glyphosate residue testing protocols introduce uncertainty bands around EU import eligibility forecasts. Material deviation in EU maximum residue limit revisions or USDA Organic Program enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Blood Meal Market
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
Peat Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Sod Peat Market
Agricultural Commodities
Europe Ruminant Feed Market
Agricultural Commodities
Vietnam Feed Concentrate and Basemix Market
Agricultural Commodities
Feed Yeast Market
Agricultural Commodities
Black Pellet Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
South America Feed Premix Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
Africa Feed Amino Acids Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
Bladderpod Oil Market