
 Aloe Vera Market | 2026-2036
Aloe Vera Market Size, Share, and Industry Trends Forecast 2026-2036
Aloe Vera Market Intelligence
Mexico's Jalisco growing belt is narrowing the raw material deficit that has long constrained processors in Asia and Europe. Aloecorp leverages its integrated farming and extraction footprint across Central America to sustain supply security for global cosmetic houses. Terry Laboratories differentiates through cold-process stabilization technology that preserves polysaccharide integrity for pharmaceutical-grade contracts. Forever Living Products controls one of the largest direct-to-consumer distribution networks for finished aloe goods, occupying a unique channel position that bypasses traditional retail markups.
Aloe vera comprises the fleshy leaves of Aloe barbadensis miller, a succulent species whose inner gel contains acemannan polysaccharides, anthraquinones, and glycoproteins extracted through filleting, grinding, or whole-leaf processing followed by decolorization and stabilization. The substance serves primarily as an emollient, humectant, and anti-inflammatory agent across topical and ingestible formulations. Gel and juice categories dominate volume throughput due to their versatility in cosmetics and beverages, while powder and supplements command stronger unit economics in pharmaceutical and nutraceutical channels where standardization requirements elevate processing complexity. Cosmetics and pharmaceuticals together anchor value capture, though food and beverage applications are gaining shelf space as natural preservative systems replace synthetic alternatives.
The US FDA governs aloe ingredient safety in dietary supplements and cosmetics through GRAS notifications and cosmetic labeling rules, while the EU EFSA evaluates novel food applications and ECHA monitors REACH compliance for imported extracts. India's BIS certifies aloe powder grades for domestic Ayurvedic manufacturers, and China's NMPA requires registration of aloe-containing health foods entering its market. Stakeholders must monitor evolving botanical authentication standards and traceability mandates that will determine which suppliers retain market access across major economies.
Market Dynamics
Clean-label ingredient mandates from EU REACH and US FDA cosmetic labeling rules are compressing formulation timelines for aloe vera processors, forcing rapid qualification of traceable supply chains from Jalisco to Jodhpur.
Growth Catalysts
- EU REACH compliance deadlines:Cosmetics manufacturers accelerate aloe-based formulation shifts to meet decolorization and stabilization documentation requirements for imported botanical extracts.
- Ayurvedic product clusters in India:Domestic BIS certification programs for aloe powder grades unlock standardized raw material flows into traditional medicine manufacturing corridors.
- Cold-process stabilization:Pharmaceutical-grade contract manufacturers adopt low-temperature extraction methods that preserve acemannan polysaccharide integrity for therapeutic applications.
Market Restraints
- Raw material concentration in Jalisco:Mexico's growing belt supplies disproportionate global leaf volume, creating weather-dependent supply vulnerability for Asian and European processors.
- Anthraquinone content thresholds:Whole-leaf processing methods face stricter EFSA novel food application scrutiny for ingestible formulations, limiting extraction technology options.
- Synthetic humectant substitution:Petrochemical-derived glycerin and propylene glycol compete on cost in mass-market cosmetics, pressuring aloe gel pricing in economy-tier personal care.
Strategic Opportunities
- China's NMPA health food registration:Aloe-containing supplements entering the Chinese market gain premium positioning through mandatory safety dossiers that filter out low-grade competitors.
- Natural preservative systems:Food and beverage formulators replace synthetic alternatives with aloe-derived antimicrobial compounds in clean-label packaged goods.
- Direct-to-consumer channel expansion:Bypassing traditional retail markups through captive distribution networks captures margin otherwise lost to wholesale intermediaries.
Industry Challenges
- Botanical authentication expertise:DNA barcoding and isotope testing capabilities remain scarce among mid-tier processors, delaying compliance with emerging traceability mandates.
- Decolorization capex requirements:Activated carbon and membrane filtration infrastructure demands substantial upfront investment for processors upgrading from basic grinding operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aloe Vera Market |
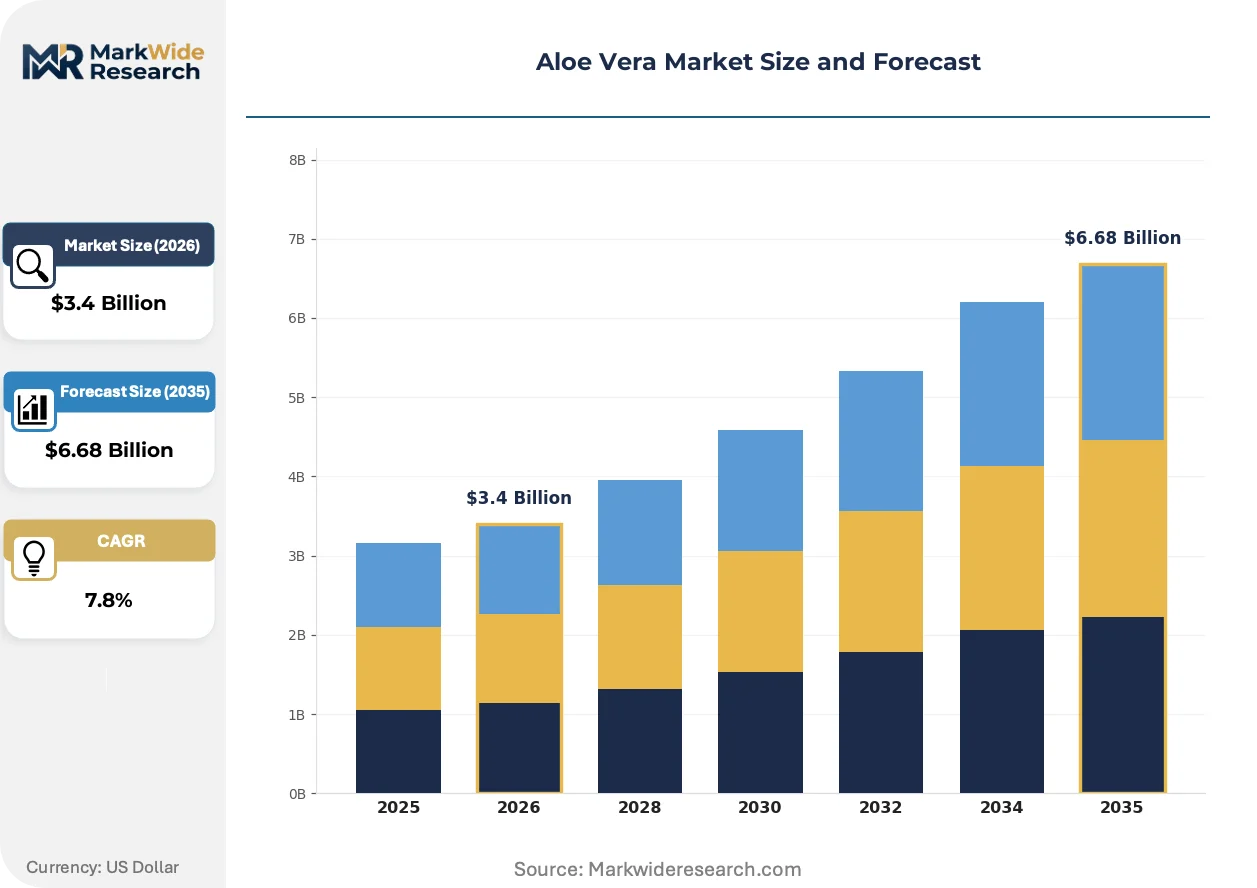
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.68 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Juice, Powder, Supplements Application: Cosmetics, Pharmaceuticals, Food & Beverage, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies End User: Consumers, Restaurants, Hospitals, Skincare Clinics |
| Companies Covered | Forever Living Products, Herbalife International, Aloecorp, Terry Laboratories, Aloe Laboratories, Lily of the Desert, LR Health & Beauty Systems, Aloe Queen, Pharmachem Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aloe Vera Market Strategic Shifts & Innovations
Processing technology convergence with pharmaceutical-grade standards is elevating quality thresholds across cosmetic and nutraceutical channels, compressing the viable supplier base to qualified operators.
Lyophilization (freeze-drying) technology preserves heat-sensitive bioactive compounds in aloe gel concentrates for pharmaceutical applications. Contract manufacturers serving dermatology and wound-care segments adopt this method at accelerating rates. Thermal degradation of acemannan in conventional drying is rendering obsolete older spray-drying installations in premium supply chains.
EU EFSA novel food application pathways for ingestible aloe extracts impose toxicological dossier requirements that smaller exporters cannot assemble. This regulatory friction concentrates import authorization among vertically integrated operators with dedicated regulatory affairs functions. German natural skincare manufacturing corridors absorb the compliance burden fastest, locking in supplier relationships ahead of enforcement deadlines.
Ingredient buyers in cosmetics now demand batch-level blockchain traceability from farm to formulation, displacing paper-based chain-of-custody documentation. Third-party certification bodies scramble to validate digital systems against ISO botanical authentication standards. This verification infrastructure investment divides most acutely in India's Ayurvedic clusters, where traditional sourcing relationships conflict with modern documentation requirements.
Aloe Vera Market Segmentation
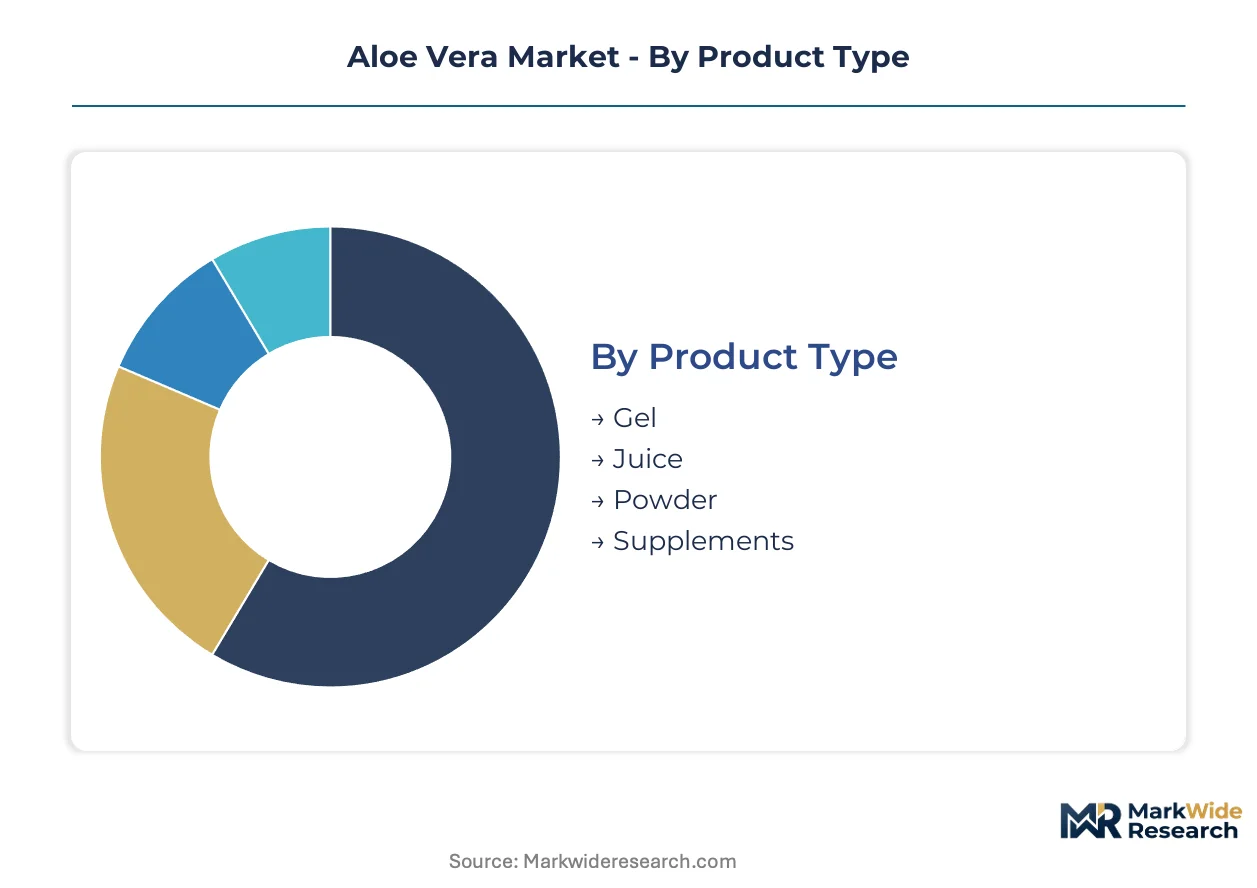
Segmentation in aloe vera reveals how processing complexity and regulatory intensity fragment value capture across channels. Gel and juice categories dominate volume throughput, while powder and supplements concentrate margin in pharmaceutical-grade supply chains where standardization requirements elevate entry barriers.
Product Type:
Cost tier differentiation separates commodity-grade bulk extracts from certified pharmaceutical inputs, with processing depth determining unit economics and customer qualification requirements.
- Gel:The inner leaf fillet contains acemannan polysaccharides, anthraquinones, and glycoproteins extracted through cold-process stabilization. Cosmetics manufacturers in Germany's natural skincare corridors concentrate procurement here as EU REACH decolorization documentation tightens on imported botanicals.
- Juice:Whole-leaf or inner-fillet liquid extracts serve beverage formulators and topical applications with shorter shelf-life requirements. India's Ayurvedic product clusters absorb significant volume for traditional medicine manufacturing, though BIS certification programs are compressing the qualified supplier base.
- Powder:Spray-dried or lyophilized concentrates enable transport-efficient formulation for nutraceutical tablets and capsules.
- Supplements:Standardized extracts in capsule, tablet, or softgel formats command premium positioning through mandatory safety dossiers for NMPA health food registration in China.
Gel holds installed capacity. Supplements is rotating up the share rankings.
Application:
End-use maturity spans established cosmetic emollient demand through emerging natural preservative adoption in packaged foods, with regulatory scrutiny intensity varying sharply across verticals.
- Cosmetics:Emollient, humectant, and anti-inflammatory functions in skincare, haircare, and personal care formulations. Clean-label ingredient mandates from US FDA cosmetic labeling rules are accelerating formulation shifts as traceable supply chains from Jalisco to Jodhpur undergo rapid qualification.
- Pharmaceuticals:Wound-care, dermatology, and therapeutic applications requiring acemannan integrity preserved through lyophilization. Cold-process stabilization technology is displacing older spray-drying installations in premium supply chains serving pharmaceutical-grade contracts.
- Food & Beverage:Natural flavoring, functional beverages, and clean-label preservative systems replacing synthetic alternatives.
- Nutraceuticals:Digestive health, immune support, and wellness positioning in dietary supplement formats.
Cosmetics maintains volume leadership. Food & Beverage is climbing the fastest as natural preservative adoption accelerates.
Distribution Channel:
Channel configuration determines margin retention, with captive direct-to-consumer networks bypassing wholesale markups that erode profitability in traditional retail pathways.
- Online Retail:Direct-to-consumer platforms and e-commerce marketplaces enabling bypass of traditional retail intermediaries. Forever Living Products occupies a unique channel position through one of the largest captive distribution networks for finished aloe goods.
- Supermarkets:Mass-market retail placement for beverage and basic personal care SKUs competing with synthetic humectant alternatives on shelf price.
- Health Stores:Specialty retail targeting wellness-conscious consumers with premium-positioned supplements and organic-certified topicals.
- Pharmacies:Professional recommendation channel for dermatological and therapeutic-grade formulations requiring pharmacist counsel.
Pharmacies holds professional trust positioning. Online Retail is gaining share fastest through margin capture and geographic reach extension.
End User:
Customer type fragmentation runs from individual consumers through institutional foodservice and clinical settings, with specification stringency escalating across the spectrum.
- Consumers:Individual purchasers of topical skincare, beverages, and dietary supplements for personal use. India's domestic Ayurvedic market concentrates significant consumer demand through traditional medicine consumption patterns.
- Restaurants:Foodservice operators incorporating aloe into functional beverages, desserts, and health-focused menu items.
- Hospitals:Clinical procurement of wound-care and therapeutic formulations for patient treatment protocols.
- Skincare Clinics:Professional aesthetic and dermatological practices utilizing pharmaceutical-grade extracts in treatment applications.
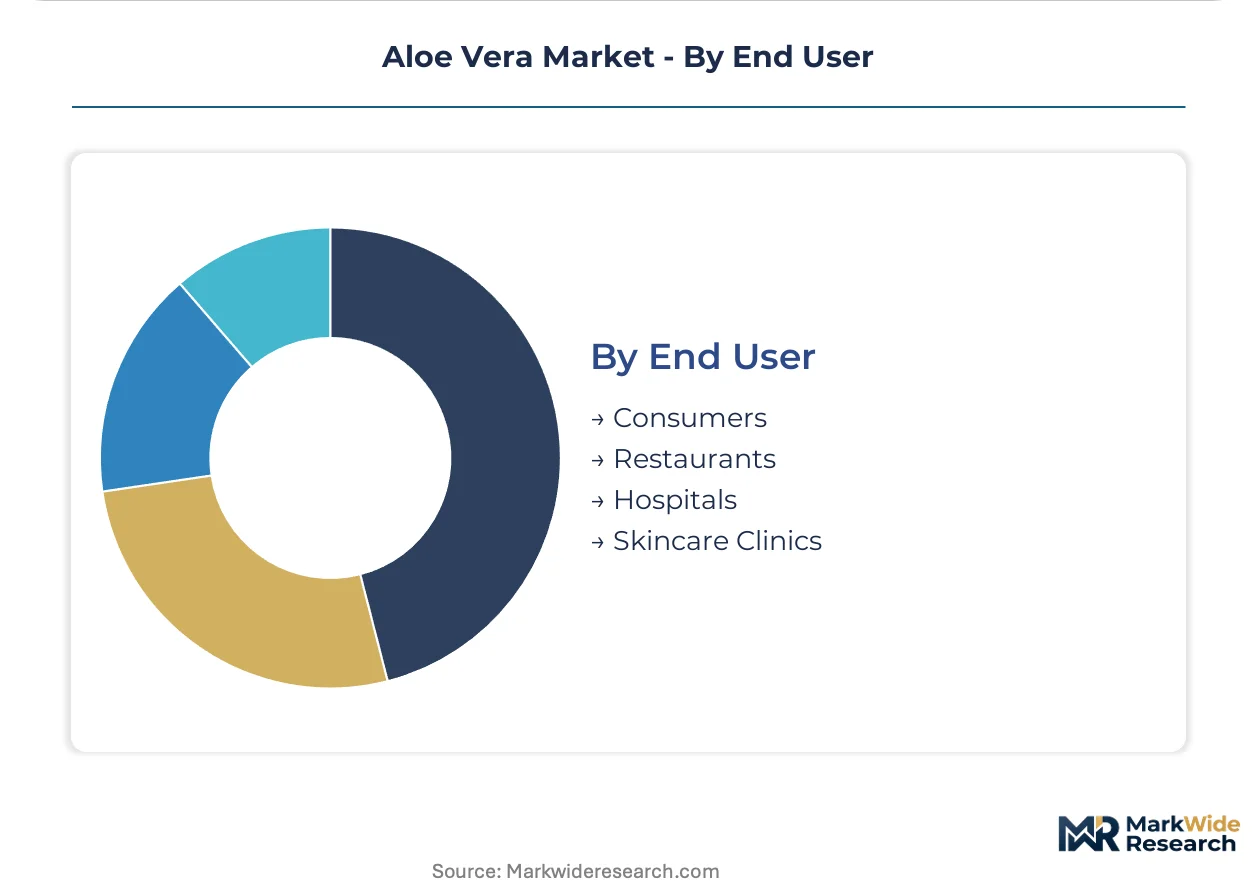
Consumers represents the largest addressable base. Skincare Clinics is rotating up the share rankings through professional-grade specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Germany absorbs pharmaceutical-grade extracts for natural skincare manufacturing, while India's Ayurvedic corridors consume raw gel and juice for traditional medicine processing. China's nutraceutical channel demands standardized powder grades for health food registration compliance.
United States
Cosmetics manufacturers in California and New York Metro accelerate clean-label formulation shifts under FDA cosmetic labeling rules. The agency's GRAS notification pathway governs aloe ingredient safety in dietary supplements. Terry Laboratories in Florida exemplifies cold-process stabilization adoption for pharmaceutical-grade contracts.
Germany
Natural skincare manufacturing corridors in Bavaria and North Rhine-Westphalia concentrate procurement of decolorized gel extracts. ECHA REACH compliance deadlines force rapid qualification of traceable supply chains from Mexico. EFSA novel food applications for ingestible aloe extracts impose toxicological dossier requirements that filter supplier access.
India
Ayurvedic product clusters in Maharashtra and Gujarat absorb significant gel and juice volume for traditional medicine manufacturing. BIS certification programs for aloe powder grades standardize raw material flows into domestic processing facilities. Jodhpur and Jaipur processing centers face documentation pressure from EU-bound export contracts.
China
Nutraceutical manufacturers in Guangdong and Zhejiang provinces drive standardized powder demand for NMPA health food registration. The regulator's mandatory safety dossiers elevate processing complexity and filter low-grade competitors. Yangtze River Delta formulation houses increasingly specify batch-level traceability documentation.
Mexico
Jalisco's growing belt supplies disproportionate global leaf volume to processors in Asia and Europe. Weather-dependent supply vulnerability constrains year-round availability for distant manufacturers. Aloecorp leverages integrated farming and extraction footprints across Central America to sustain supply security for international cosmetic houses.
Aloe Vera Market Key Industry Players
Capability concentration sits with integrated operators possessing cold-process stabilization and decolorization infrastructure; scale advantage sits with direct-to-consumer distributors commanding captive channel networks. The market structures around three archetypes: vertically integrated farm-to-extract operators, technology-differentiated contract manufacturers, and captive distribution network holders. Dominant competitive moves include backward integration into Jalisco growing operations and technology licensing for pharmaceutical-grade extraction protocols.
Within the integrated operator tier, Aloecorp anchors supply security through Central American farming and extraction footprints. Terry Laboratories exemplifies technology-differentiated positioning through specialized stabilization capabilities. Forever Living Products occupies a unique channel position through one of the largest direct-to-consumer distribution networks for finished aloe goods, bypassing traditional retail markups entirely.
| Leading Market Players |
|---|
| Forever Living Products |
| Herbalife International |
| Aloecorp |
| Terry Laboratories |
| Aloe Laboratories |
| Lily of the Desert |
| LR Health & Beauty Systems |
| Aloe Queen |
| Pharmachem Laboratories |
| Others |
Cost & Logistics Intelligence
Jalisco-to-Long Beach container freight corridors transmit Mexican harvest volatility directly into European and Asian processor cost bases, amplifying price spreads between spot gel purchases and long-term pharmaceutical-grade offtake contracts. This logistics tension concentrates margin capture with integrated operators possessing captive Central American farming assets while forcing distant buyers into premium positioning for supply security.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical-grade gel procurement, locking in volume commitments from Jalisco growers to German natural skincare manufacturers ahead of EU REACH decolorization deadlines. Spot market transactions persist for commodity-grade juice flows into India's Ayurvedic clusters, where BIS certification tiering separates standardized powder premiums from uncertified bulk discounts. Pricing pressure intensifies in mass-market cosmetics as synthetic glycerin substitution erodes aloe gel's cost competitiveness in economy-tier personal care. Hospital procurement channels exhibit lowest price sensitivity due to therapeutic-grade acemannan standardization requirements, while beverage formulators face acute cost compression from petrochemical humectant alternatives.
Supply Chain Analysis
Upstream feedstock from Aloe barbadensis cultivation concentrates overwhelmingly in Mexico's Jalisco belt, with secondary volumes from Dominican Republic and Venezuelan growing regions supplementing seasonal gaps. Raw material flows draw from leaf harvesting, cold-chain transport, and activated carbon decolorization infrastructure, with lyophilization capacity representing the critical processing bottleneck for pharmaceutical-grade output. Single-source vulnerability from Jalisco's weather-dependent harvest cycles threatens year-round availability for distant Asian and European processors lacking integrated Central American footprints. Distribution runs through three distinct channels: direct-to-consumer captive networks bypassing retail markups, pharmaceutical wholesale serving dermatology and wound-care segments, and commodity bulk supply into beverage and mass cosmetic manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
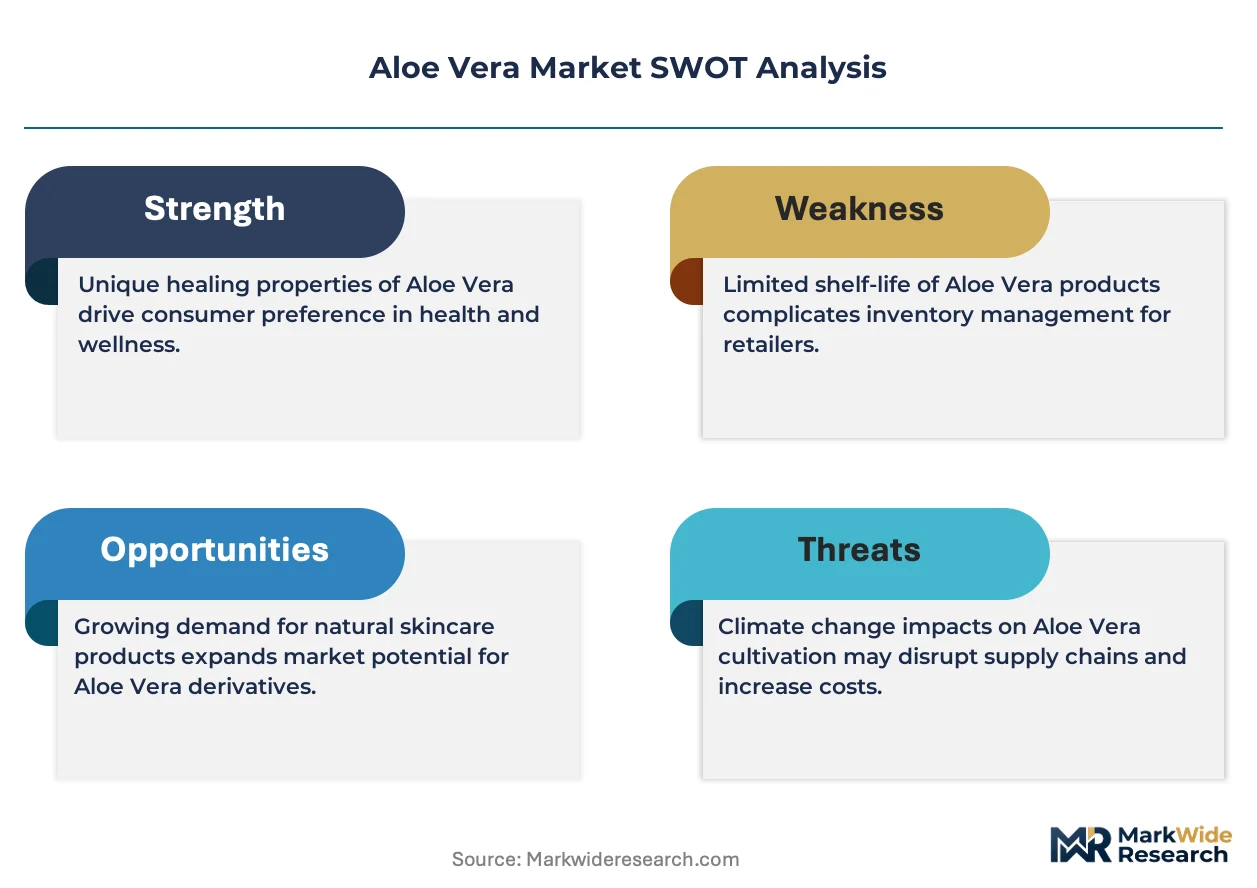
Buyer power is concentrating among German natural skincare houses and Chinese nutraceutical manufacturers with dedicated regulatory affairs functions, fragmenting price negotiation leverage for unqualified mid-tier processors. This consolidation dynamic favors suppliers with pre-certified traceability infrastructure over commodity-grade competitors.
For Market Incumbents: Build regulatory certification moats through EFSA novel food dossier completion and blockchain traceability deployment ahead of enforcement deadlines. Aloecorp's integrated farming-extraction footprint across Central America demonstrates supply security architecture that locks out competitors dependent on Jalisco spot markets. Incumbents should accelerate cold-process stabilization capacity additions in pharmaceutical-grade corridors while defending against synthetic humectant substitution through therapeutic efficacy documentation in dermatology applications.
For New Entrants and Emerging Players: Mid-tier Ayurvedic processors in Rajasthan lacking EU export certification represent the most penetrable entry point for contract manufacturing partnerships with German natural skincare brands. China's NMPA health food registration pathway filters out low-grade competitors, creating premium positioning opportunities for entrants with toxicological dossier capabilities. A go-to-market angle through direct-to-consumer supplement platforms bypasses wholesale margin compression while building brand equity for downstream pharmacy channel expansion.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated operators with lyophilization capabilities and captive Jalisco growing assets over asset-light trading houses. Long-term viability across the projection horizon rests on decolorization infrastructure ownership and regulatory approval velocity rather than commodity volume scale. Acquisition targets should demonstrate established ECHA REACH compliance documentation and existing pharmaceutical-grade contract relationships. The signal to watch is accelerating batch-level traceability mandates from EU botanical authentication standards, which will abruptly disqualify paper-based chain-of-custody suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Jalisco Growing Operations | Captive leaf supply secures pharmaceutical-grade contract volumes against weather-driven spot market volatility. |
| Cold-Process Stabilization Technology Licensing | Preserved acemannan integrity commands therapeutic-grade pricing premiums in dermatology channels. |
| EU REACH Decolorization Compliance Certification | Documentation infrastructure unlocks German natural skincare procurement ahead of enforcement deadlines. |
| Direct-to-Consumer Channel Expansion | Forever Living Products demonstrates margin capture through bypass of traditional retail intermediaries. |
| Blockchain Traceability Infrastructure Deployment | Batch-level farm-to-formulation documentation satisfies emerging ISO botanical authentication mandates. |
Research Approach
Initial hypotheses were tested against primary input from cosmetic formulation chemists, Ayurvedic manufacturing directors, pharmaceutical procurement managers, and cold-chain logistics operators, then refined through secondary validation against EFSA novel food application databases, BIS certification registries, NMPA health food registration filings, and EU REACH compliance documentation. Bottom-up volume estimates from processor capacity utilization were triangulated against top-down consumption projections from end-use sector demand modeling.
Demand-supply balance dynamics across the analysis window were assessed through segmentation across gel, juice, powder, and supplement product types; cosmetics, pharmaceutical, food and beverage, and nutraceutical applications; and online retail, supermarket, health store, and pharmacy distribution channels. CAGRs were derived from fitted growth curves incorporating regulatory deadline acceleration effects and synthetic substitution elasticity parameters. Forecast inputs included ECHA enforcement timeline probabilities, NMPA registration queue velocities, and Jalisco harvest yield variance patterns.
Practitioners should monitor EFSA toxicological dossier approval velocities and ISO botanical authentication standard finalization for early signals of supplier base compression. Forecasts reflect assumptions regarding REACH compliance deadline adherence and cold-process stabilization technology adoption rates without guarantee of regulatory timeline precision. Cross-checking against customs trade data for aloe extract import volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Soy Hulls Market
Agricultural Commodities
Corn Hydrolysate Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Premix Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Feed Sucrose Market
Agricultural Commodities
Corn and Corn Starch Derivatives Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
Vietnam Compound Feed Market
Agricultural Commodities
Black Pellet Market
Agricultural Commodities
Growing Peat Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
Cattle Feed Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
Cottonseed Hulls Market