
 Tissue Cultured Date Palm Market | 2026-2036
Tissue Cultured Date Palm Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Cultured Date Palm Market Outlook
Saudi Arabia's Al-Qassim region is narrowing the supply gap for certified disease-free planting material through expanded laboratory capacity. Kutch Crop Services Pvt. Ltd. leverages its micropropagation infrastructure to serve Gujarat's commercial date sector. RANA Agro-Industry Corporation anchors North African distribution through hardened offshoot supply chains. Emirates BioTech differentiates via in-house virus indexing protocols before field release.
Tissue cultured date palm refers to asexually propagated plantlets derived from meristematic tissue via somatic embryogenesis or organogenesis, typically requiring 12-18 months of in vitro hardening before field transplantation. The process yields genetically uniform specimens with guaranteed sex determination and pathogen exclusion, primarily serving commercial orchard establishment and varietal replacement programs. Hybrid varieties command the dominant volume position due to their yield consistency and Bayoud disease tolerance. Disease-resistant cultivars represent the fastest-expanding segment as Fusarium oxysporum f.sp. albedinis pressure intensifies across traditional growing belts. Food production applications absorb the majority of offtake, while ornamental use generates premium margin pools through landscaping contracts in Gulf urban developments.
UAE's MOHAP and Saudi Arabia's SFDA jointly enforce phytosanitary certification standards for cross-border tissue culture shipments, tightening market access for uncertified suppliers. ISO 17025 accreditation for in vitro laboratories is becoming a de facto requirement for government procurement tenders across Gulf Cooperation Council states. Stakeholders must monitor evolving varietal registration protocols and build compliance capacity ahead of anticipated harmonization.
Market Dynamics
Somatic embryogenesis protocol acceleration is compressing propagation cycles from 24 months to 12-18 months, forcing laboratory operators to recalibrate capacity planning and pricing models around throughput gains rather than scarcity premiums.
Growth Catalysts
- Al-Qassim laboratory expansion:Saudi Arabia's central date belt is scaling certified disease-free stock output to replace aging orchards suffering Bayoud disease pressure.
- Somatic embryogenesis maturation:Refined in vitro protocols now guarantee genetic uniformity and sex determination, eliminating field culling losses that plagued traditional offshoot propagation.
- SFDA-MOHAP phytosanitary harmonization:Cross-border tissue culture shipment standards between Saudi Arabia and UAE are unlocking Gulf Cooperation Council procurement scale for certified suppliers.
Market Restraints
- Laboratory capex intensity:ISO 17025 accreditation requirements for in vitro facilities demand laminar flow infrastructure and virus indexing capabilities that exclude small-scale operators.
- Fusarium oxysporum f.sp. albedinis geographic concentration:Morocco's traditional growing belts face intensifying Bayoud pressure that outpaces resistant cultivar supply, creating varietal transition risk.
- Offshoot substitution persistence:Low-cost traditional propagation from established mother palms retains cost advantage in price-sensitive North African replacement programs.
Strategic Opportunities
- Gujarat commercial sector penetration:India's Kutch region presents underexploited demand for tissue-cultured Barhi and Medjool stock as orchard modernization accelerates.
- Ornamental landscaping channel:Gulf urban development contracts for palm-lined boulevards and hotel grounds generate premium margin pools distinct from food-production offtake.
- ISO 17025 certification arbitrage:Laboratories achieving accreditation ahead of anticipated Gulf Cooperation Council tender harmonization will capture government procurement preference.
Industry Challenges
- Virus indexing technician scarcity:In-house ELISA and PCR protocol execution requires molecular diagnostics expertise that outstrips regional training pipeline output.
- Hardening facility capex cycles:Acclimatization greenhouse infrastructure for 12-18 month field-ready stock transitions demands land and climate control investment that strains balance sheets.
- Varietal registration timeline friction:National cultivar approval protocols in Saudi Arabia and UAE create 18-24 month commercialization delays for new resistant lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Cultured Date Palm Market |
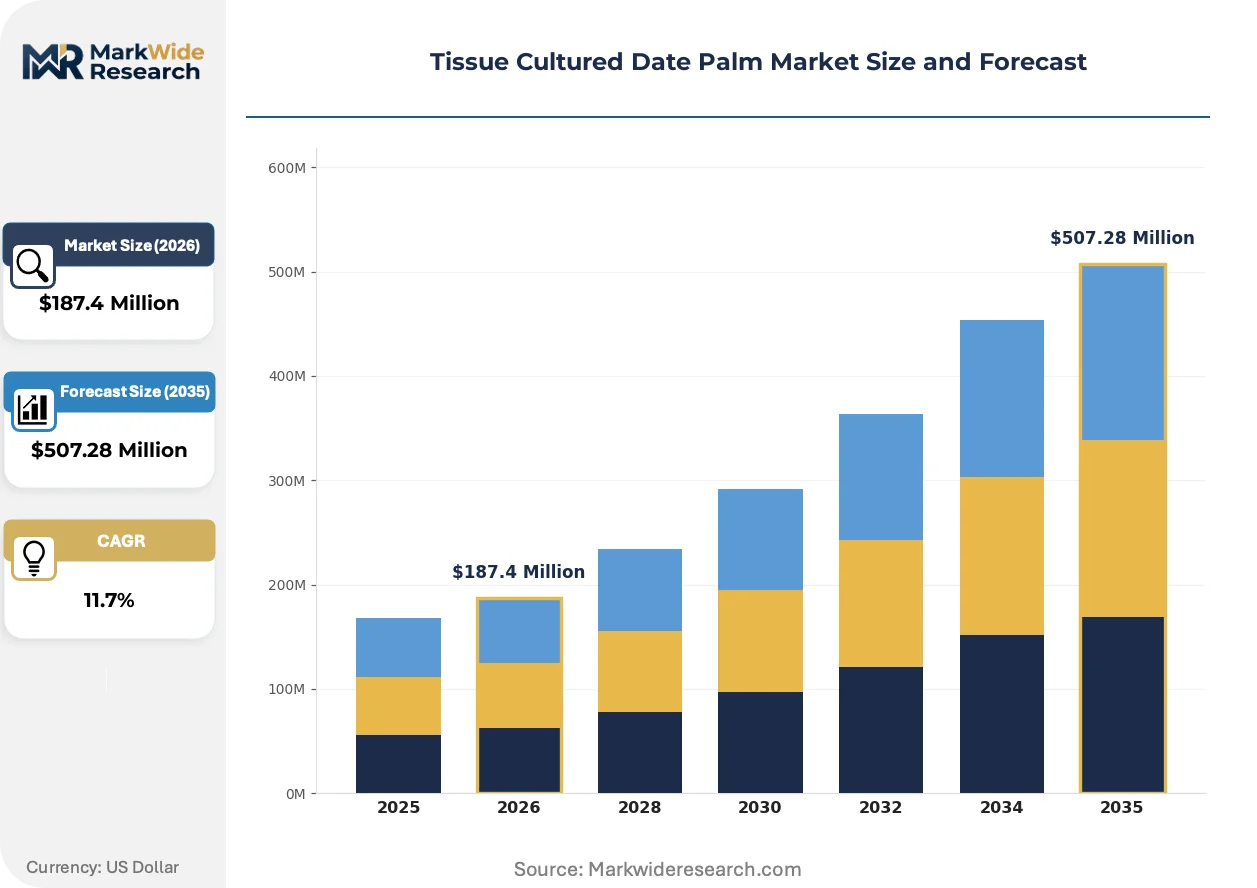
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Varieties, Disease-Resistant Cultivars, Organic Dates, Premium Quality Dates End User: Agricultural Producers, Commercial Growers, Retailers, Exporters Application: Landscaping, Food Production, Ornamental Use, Research Distribution Channel: Direct Sales, Online Retail, Wholesale, Nurseries |
| Companies Covered | Kutch Crop Services Pvt. Ltd., RANA Agro-Industry Corporation, Atul Ltd, Agrobiosys, Date Palm Developments, Al Wathba Marionnet LLC, Zemach Tissue Culture Ltd, Emirates BioTech, Phoenix Agrotech LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Cultured Date Palm Market Strategic Shifts
Digital monitoring systems and precision climate control are transforming laboratory economics, while regulatory certification requirements reshape competitive access barriers across Gulf supply chains.
Automated bioreactor systems for somatic embryo multiplication are virtualizing the scale economics of date palm micropropagation. Commercial laboratories in Saudi Arabia and UAE are deploying sensor-networked culture vessels that reduce contamination losses and labor input per plantlet. This virtualization is compressing unit costs and enabling batch sizes that previously required multiple facility expansions.
SFDA and UAE's MOHAP are tightening phytosanitary certification reciprocity for cross-border tissue culture shipments, creating de facto market access gates. Uncertified suppliers face exclusion from government procurement tenders across the Gulf Cooperation Council. Disease-resistant cultivar registration applications now dominate regulatory submission queues as Fusarium pressure intensifies.
Certification-driven procurement is displacing price-primary supplier selection in commercial orchard establishment programs. Large-scale growers in Al-Qassim and Kutch now mandate ISO 17025 laboratory accreditation and virus-free documentation before contract award. This preference shift is most visible in Saudi Arabia's varietal replacement tenders, where technical compliance outweighs unit cost differentials.
Tissue Cultured Date Palm Market Segmentation
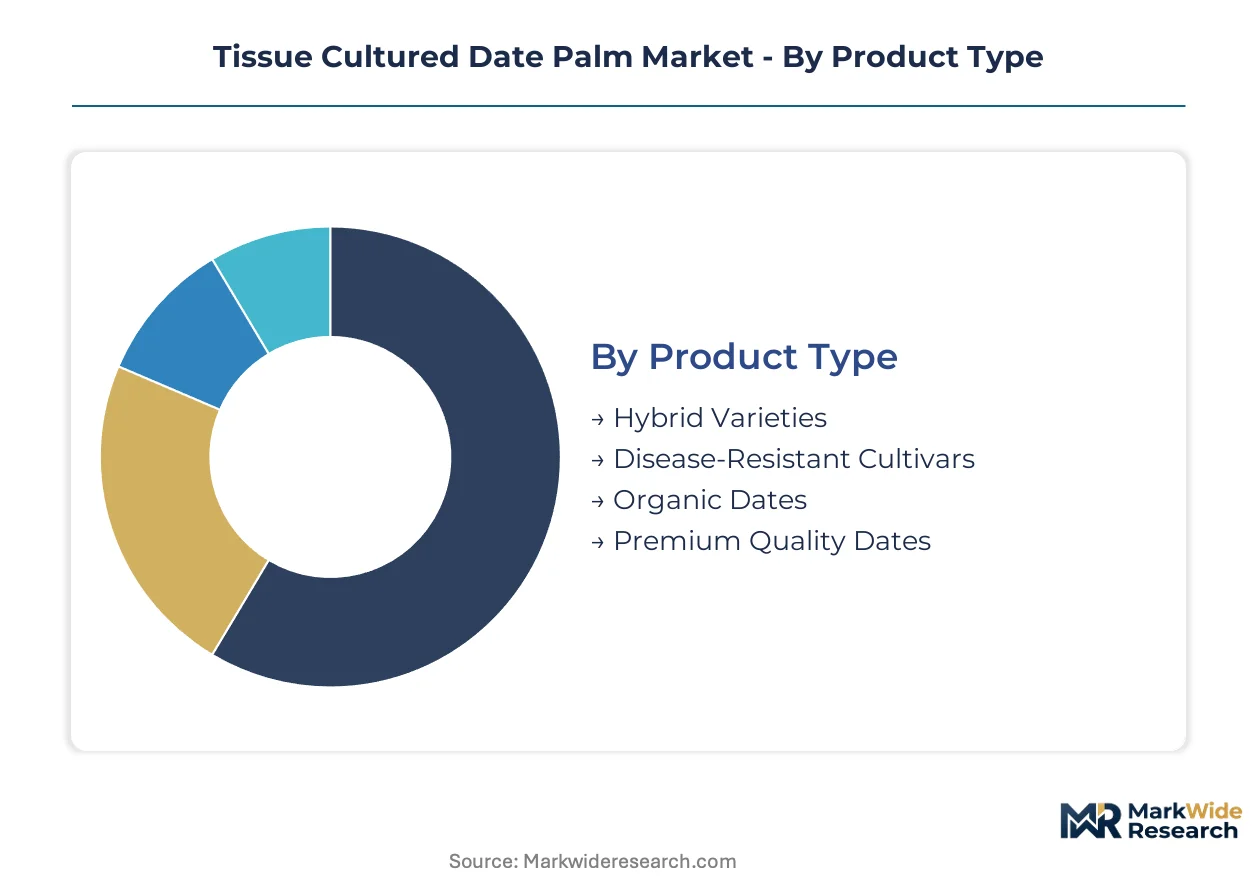
Tissue cultured date palm segmentation reveals how propagation technology, certification tiers, and downstream use cases fragment procurement patterns. Laboratories calibrate production protocols around varietal resistance profiles and hardening duration, while buyers prioritize genetic uniformity guarantees or ornamental specifications based on end-use economics.
Product Type:
Cost tier differentiation separates certified disease-free stock from premium genetic lines, with propagation cycle duration and indexing rigor driving price stratification across laboratory outputs.
- Hybrid Varieties:Crossbred lines combining high yield potential with environmental adaptability, typically Barhi and Medjool derivatives. Saudi Arabia's Al-Qassim replacement programs absorb the dominant volume as growers retire Bayoud-susceptible mother palms.
- Disease-Resistant Cultivars:Fusarium oxysporum f.sp. albedinis-tolerant selections developed through marker-assisted breeding. Morocco's traditional growing belts generate urgent demand as soil-borne pressure outpaces conventional varietal tolerance.
- Organic Dates:Plantlets propagated under certified organic protocols without synthetic inputs during in vitro phases.
- Premium Quality Dates:Elite genetic lines selected for sugar content, fruit size, and shelf-life specifications targeting export markets.
Hybrid varieties command the established base. The steepest expansion runs through disease-resistant cultivars.
End User:
Customer type determines contract structure, with volume scale and technical compliance requirements varying sharply between estate operators and intermediary traders.
- Commercial Growers:Large-scale orchard operators in Saudi Arabia and UAE purchasing hardened plantlets in 1,000-unit batches. SFDA and MOHAP certification mandates now dominate supplier selection criteria ahead of unit pricing.
- Agricultural Producers:Mid-scale farm operators across North Africa and India seeking varietal replacement for aging offshoot stock. Gujarat's Kutch region presents concentrated demand as Barhi modernization accelerates.
- Retailers:Garden centers and agricultural supply chains distributing small-batch plantlets to hobbyist and specialty growers.
- Exporters:Trading entities facilitating cross-border shipment of certified stock, subject to phytosanitary reciprocity agreements between Gulf Cooperation Council states.
Commercial growers absorb the majority volume. Agricultural producers are gaining share fastest as mid-scale orchard modernization spreads beyond the Gulf.
Application:
Volume concentration in food-production offtake contrasts with margin premium capture in non-agricultural deployment channels.
- Food Production:Commercial date harvesting operations requiring genetically uniform female plantlets with guaranteed productivity. Saudi Arabia's central date belt dominates procurement scale for established cultivar replacement.
- Ornamental Use:Landscaping contracts for palm-lined boulevards, hotel grounds, and urban developments across Gulf cities. Dubai and Abu Dhabi municipal tenders generate price premiums distinct from agricultural economics.
- Landscaping:Large-scale green infrastructure projects requiring hardened specimens with immediate visual impact.
- Research:University and government breeding programs utilizing tissue culture for germplasm conservation and varietal development.
Food production anchors volume demand. Ornamental use delivers the highest margin realization per plantlet.
Distribution Channel:
Supply concentration shapes channel viability, with certification requirements filtering participant eligibility across procurement pathways.
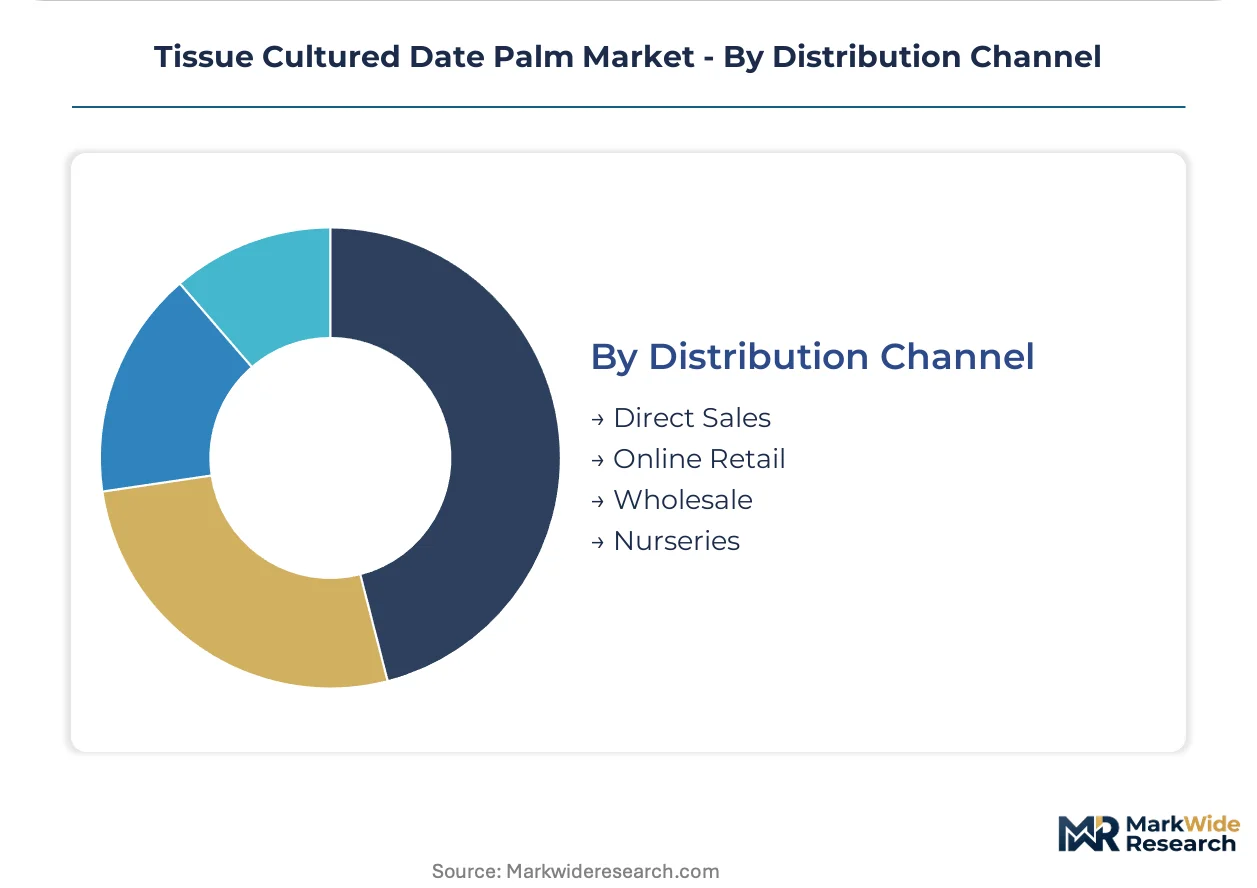
- Direct Sales:Laboratory-to-grower contracts for large-batch hardened stock, prevalent in Saudi Arabia's government tender system. ISO 17025 accreditation functions as a de facto entry barrier for uncertified facilities.
- Wholesale:Aggregator networks distributing certified plantlets to regional agricultural cooperatives and nursery chains.
- Nurseries:Specialized operators completing final hardening phases and local adaptation before field release.
- Online Retail:Emerging channel for small-batch specialty varieties and hobbyist markets, limited by live plant phytosanitary shipping constraints.
Direct sales capture the largest transaction values. Nurseries are expanding fastest as regional hardening capacity localizes supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia consumes tissue-cultured date palms primarily for commercial orchard replacement, while the UAE channels significant volumes into ornamental landscaping contracts. India and Morocco represent emerging demand centers with distinct procurement logics. Geographic variation in end-use intensity shapes laboratory output specifications across supplier networks.
Saudi Arabia
Al-Qassim region drives concentrated procurement for Bayoud-resistant Barhi and Medjool replacement stock. SFDA enforces phytosanitary certification reciprocity with Gulf Cooperation Council partners, tightening market access for uncertified laboratories. Riyadh-based procurement aggregators coordinate government tender distribution across central date belt modernization programs.
United Arab Emirates
Dubai and Abu Dhabi municipal authorities generate premium-margin demand for hardened specimens in urban landscaping and hotel ground contracts. MOHAP coordinates phytosanitary standards with Saudi SFDA to facilitate cross-border tissue culture shipments. Emirates BioTech anchors supply capacity through in-house virus indexing protocols serving government procurement channels.
India
Gujarat's Kutch region presents accelerating demand for tissue-cultured Barhi stock as commercial orchard modernization displaces aging offshoot propagation. The country's national agricultural regulator oversees varietal import protocols for certified disease-free planting material. Kutch Crop Services leverages micropropagation infrastructure to serve regional commercial date sector expansion.
Morocco
Traditional growing belts face intensifying Fusarium oxysporum f.sp. albedinis pressure that outpaces resistant cultivar availability. The country's national phytosanitary authority manages cultivar registration timelines that create commercialization friction for new tolerant lines. RANA Agro-Industry Corporation anchors North African distribution through hardened offshoot supply chains serving varietal transition demand.
Israel
Advanced somatic embryogenesis research infrastructure supports germplasm conservation and marker-assisted breeding programs. The national agricultural research authority coordinates regional collaboration on Bayoud resistance genetics. Zemach Tissue Culture anchors laboratory capacity serving domestic commercial growers and export-oriented propagation services.
Tissue Cultured Date Palm Market Competitive Environment
Capability concentration sits with ISO 17025-accredited laboratories possessing in-house virus indexing; scale advantage sits with vertically integrated operators controlling hardening greenhouse infrastructure. The market structures around three tiers: certification-heavy government suppliers, mid-scale regional hardening specialists, and research-oriented germplasm developers. Dominant competitive moves include accreditation pre-positioning ahead of Gulf Cooperation Council tender harmonization and backward integration into climate-controlled acclimatization facilities.
Within the certification-driven tier, Emirates BioTech and Kutch Crop Services exemplify laboratories that have anchored government procurement relationships through phytosanitary compliance capacity. RANA Agro-Industry Corporation occupies a position bridging North African distribution logistics with hardened stock regionalization. These three entities represent distinct geographic anchoring strategies—Gulf-based regulatory arbitrage, Indian subcontinent commercial sector penetration, and Maghreb varietal transition servicing.
| Leading Market Players |
|---|
| Kutch Crop Services Pvt. Ltd. |
| RANA Agro-Industry Corporation |
| Atul Ltd |
| Agrobiosys |
| Date Palm Developments |
| Al Wathba Marionnet LLC |
| Zemach Tissue Culture Ltd |
| Emirates BioTech |
| Phoenix Agrotech LLC |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on ISO 17025-accredited laboratories in Saudi Arabia and the UAE determines both pricing tier spreads and supply chain shape, as SFDA-MOHAP phytosanitary reciprocity requirements concentrate certified capacity in Gulf Cooperation Council states while excluding uncertified competitors from government procurement channels.
Pricing Analysis
Price spreads between Saudi Arabia and India exceed threefold for equivalent Barhi plantlet specifications. Pricing stratifies across certified disease-free, standard hardened, and unindexed economy tiers, with ISO 17025 accreditation and in-house virus indexing as the primary differentiation drivers. Cost compression in the economy tier is intensifying because Moroccan and North African growers persist with low-cost offshoot substitution. Agricultural producers in Gujarat's Kutch region exhibit highest price sensitivity, while Dubai municipal landscaping contracts show least sensitivity due to premium margin pools for immediate visual impact specimens.
Supply Chain Analysis
Tariff exposure between Saudi Arabia and Morocco dominates supply chain risk planning as SFDA phytosanitary reciprocity does not extend to North African suppliers. Geographic supply concentration centers on Saudi Arabia, the UAE, and India, with Israel anchoring germplasm conservation and breeding program inputs. Raw material dependencies draw from agar substrate suppliers, laminar flow equipment manufacturers, and ELISA/PCR reagent providers. Single-source vulnerability sits with hardening facility capacity in Al-Qassim and Kutch regions. Distribution runs through direct laboratory-to-grower contracts for large-batch procurement, with nursery intermediaries expanding for regional final-stage acclimatization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Virus indexing service contracts and multi-year varietal maintenance agreements expand faster than plantlet hardware sales, creating recurring revenue layers that laboratories can attach to initial propagation transactions.
For Market Incumbents: Build certification moats through early ISO 17025 accreditation and in-house PCR protocol capacity before anticipated Gulf Cooperation Council tender harmonization. SFDA procurement preference shifts threaten price-primary competitors. Backward integration into climate-controlled hardening greenhouses in Al-Qassim and Kutch secures throughput capacity and margin control against regional nursery intermediaries. For New Entrants and Emerging Players: Pursue ornamental landscaping penetration in Abu Dhabi and Dubai municipal contracts as the most penetrable segment, where premium pricing tolerates new supplier qualification timelines. Gujarat's commercial date sector presents white-space demand for tissue-cultured Barhi stock as orchard modernization accelerates. A certification-first go-to-market angle—achieving phytosanitary documentation before volume scaling—unlocks government procurement channels that exclude established but uncertified competitors. For Investors and Strategic Acquirers: Gulf Cooperation Council tender harmonization reshapes the acquisition landscape toward laboratories with existing SFDA-MOHAP compliance infrastructure and hardening facility real estate. Long-term viability centers on service-attach revenue durability through multi-year indexing and varietal maintenance contracts. Acquisition target archetype: mid-scale regional operators with accredited capacity but underutilized throughput. The signal to watch is varietal registration queue acceleration for Fusarium-resistant cultivars as Bayoud pressure intensifies across Moroccan growing belts.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Investment | SFDA procurement preference locks out uncertified competitors from Saudi government tenders. |
| Hardening Facility Expansion | Climate-controlled greenhouse capacity in Al-Qassim shortens field-ready timelines for commercial growers. |
| Virus Indexing Service Launch | In-house ELISA and PCR protocols create recurring revenue attachment to plantlet sales. |
| Ornamental Channel Partnership | Dubai municipal landscaping contracts generate premium margins distinct from agricultural economics. |
| Resistant Cultivar Registration | Marker-assisted breeding programs address Fusarium pressure outpacing conventional varietal tolerance. |
Study Parameters
A standing panel of tissue culture laboratory directors, commercial orchard operators in Al-Qassim and Kutch, SFDA regulatory affairs specialists, and municipal landscaping procurement officers provided ongoing calibration across the study. Primary interviews with these stakeholders combined with secondary validation from SFDA phytosanitary bulletins, MOHAP certification registries, Gulf Cooperation Council trade documentation, and varietal registration databases. Bottom-up plantlet production estimates and top-down orchard replacement demand triangulation anchored volume and value outputs.
Scenario-bracketing around somatic embryogenesis protocol acceleration and Fusarium resistance breeding timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end user scale, application channel, and distribution pathway, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derived from fitted growth curves applied to laboratory capacity expansion announcements and government tender award patterns, with cross-checks against hardening facility capex cycles and varietal registration queue velocities.
Sensitivities concentrate around SFDA-MOHAP harmonization delays, Fusarium resistance cultivar commercialization timelines, and offshoot substitution persistence in North African price-sensitive markets. Forecasts reflect documented assumptions regarding laboratory throughput gains and certification penetration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Elaeis Guineensis (Palm) Fruit Extract Market
Agriculture and Agri Products
Animal Feed and Feed Additives Market
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Ghana Agriculture Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
Oman Agriculture Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Swine Feed Premix Market
Agriculture and Agri Products
Netherlands Commercial Greenhouse Market
Agriculture and Agri Products
Bee Pollen Market
Agriculture and Agri Products
Asia-Pacific Rapeseed Oil Market
Agriculture and Agri Products
United Arab Emirates Poultry Meat Market
Agriculture and Agri Products
Italy Compound Feed Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
North America Compound Feed Market