
 Corn Gluten Feed Market | 2026-2036
Corn Gluten Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Gluten Feed Market Analysis
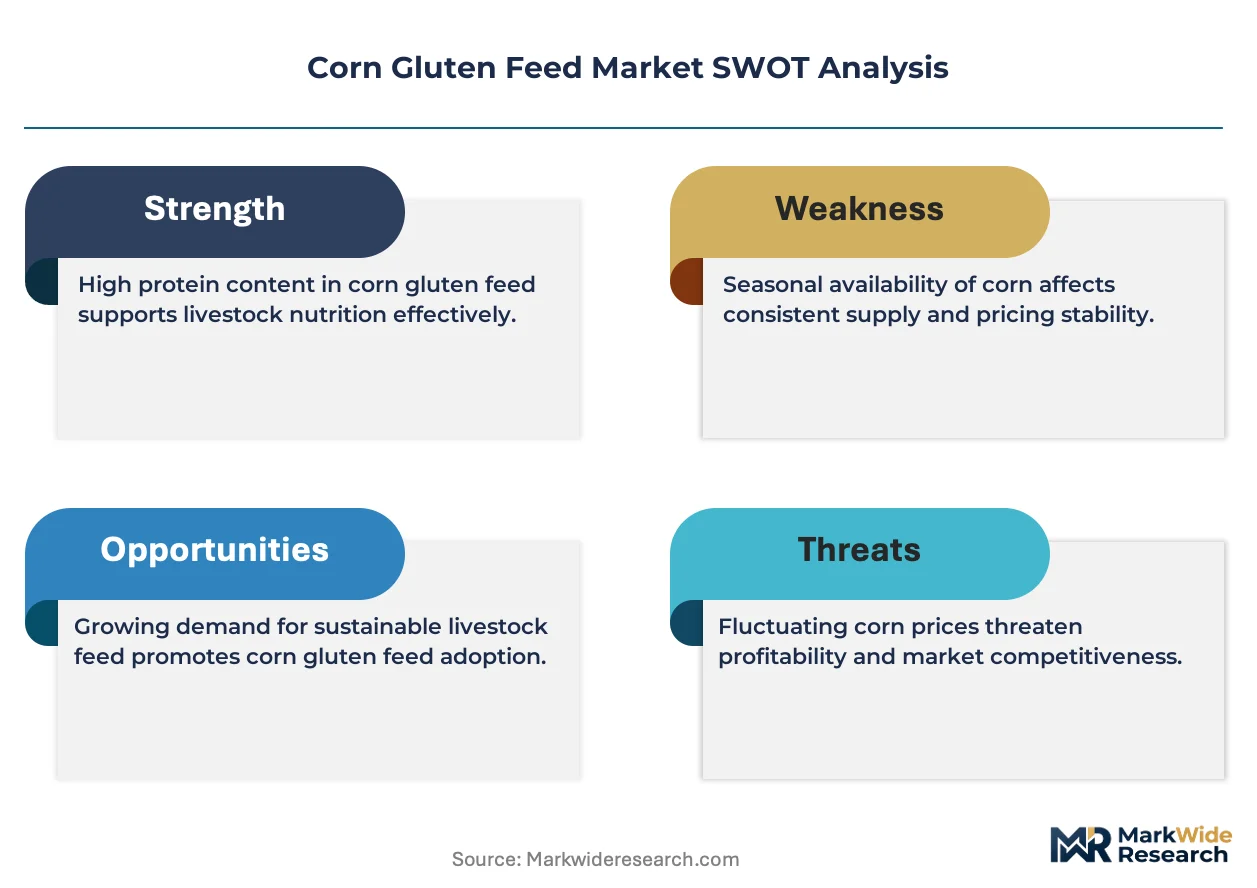
Precision fermentation and enzyme-enhanced wet milling is tilting co-product recovery economics toward higher-protein, lower-fiber outputs that redefine feed value propositions. Archer Daniels Midland Company leverages its Decatur, Illinois wet milling complex to sustain captive supply chains for regional dairy cooperatives. Cargill, Incorporated competes through backward integration into corn origination, while Tate & Lyle PLC differentiates via specialty carbohydrate co-product streams that occupy premium feed ingredient niches.
Corn gluten feed comprises the protein-rich residue remaining after corn starch extraction, typically containing 21% crude protein, 2.5% crude fat, and 10% fiber on a dry matter basis, serving primarily as an energy-protein balancer in ruminant diets. Dry corn gluten feed dominates volume flows due to extended shelf stability and lower freight costs, though pelleted corn gluten feed captures margin pools by reducing dust losses and improving handling efficiency at large poultry farms. The aquaculture application segment shows structural momentum as shrimp and salmon producers seek alternatives to fishmeal, with distributors in coastal zones building dedicated blending capacity for this channel.
The USDA sets grading standards for feed ingredients that shape protein guarantee requirements and mycotoxin thresholds, while the FDA's Food Safety Modernization Act imposes preventive controls on feed manufacturing facilities that filter market access for smaller processors. State-level nutrient management regulations in Iowa and Illinois restrict phosphorus loading from livestock operations, indirectly steering formulation preferences toward lower-phosphorus co-products like corn gluten feed over soybean meal. Stakeholders must monitor how evolving carbon accounting frameworks for agricultural supply chains reshape procurement criteria for feed ingredients.
Market Dynamics
Precision fermentation and enzyme-enhanced wet milling is compressing fiber content in corn gluten feed while elevating protein density, forcing feed formulators to recalibrate ruminant rations around nutrient concentration rather than bulk handling economics.
Growth Catalysts
- EPA Renewable Fuel Standard:Mandated ethanol production volumes expand corn wet milling throughput, indirectly enlarging co-product supply streams available to livestock operations.
- Dairy farm consolidation:Large-scale operations in Wisconsin and Minnesota seek cost-competitive protein alternatives to soybean meal, concentrating procurement volume in regional wet milling corridors.
- Aquaculture feed substitution:Shrimp and salmon producers in coastal zones pilot corn gluten feed blends as fishmeal alternatives, opening channel-specific demand nodes.
Market Restraints
- Input cost volatility:Corn price swings tied to weather patterns and biofuel policy uncertainty compress margin predictability for wet millers and feed compounders alike.
- Supply concentration risk:Wet milling capacity clusters disproportionately in Illinois and Iowa, creating geographic vulnerability to localized infrastructure disruptions or state-level regulatory shifts.
- Substitution threat:Distillers dried grains with solubles from ethanol plants compete directly on protein content and price, limiting corn gluten feed pricing power in energy-protein balancer applications.
Strategic Opportunities
- Underpenetrated aquaculture channels:Southeast Asian shrimp farming operations remain minimally served by corn gluten feed distributors, presenting first-mover expansion potential for coastal blending facilities.
- Carbon accounting frameworks:Emerging agricultural supply chain emissions tracking favors lower-carbon protein sources, positioning corn gluten feed favorably against soybean meal in sustainability-scored procurement.
- Pellet technology convergence:Pelleting equipment upgrades combined with dust suppression chemistry enable premium product formats for large poultry integrators seeking handling efficiency.
Industry Challenges
- Phosphorus compliance complexity:Iowa and Illinois nutrient management regulations restrict livestock operation phosphorus loading, requiring feed formulators to maintain precise mineral balance documentation.
- Mycotoxin surveillance burden:FDA Food Safety Modernization Act preventive controls mandate continuous testing infrastructure that filters smaller processors from market participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Gluten Feed Market |
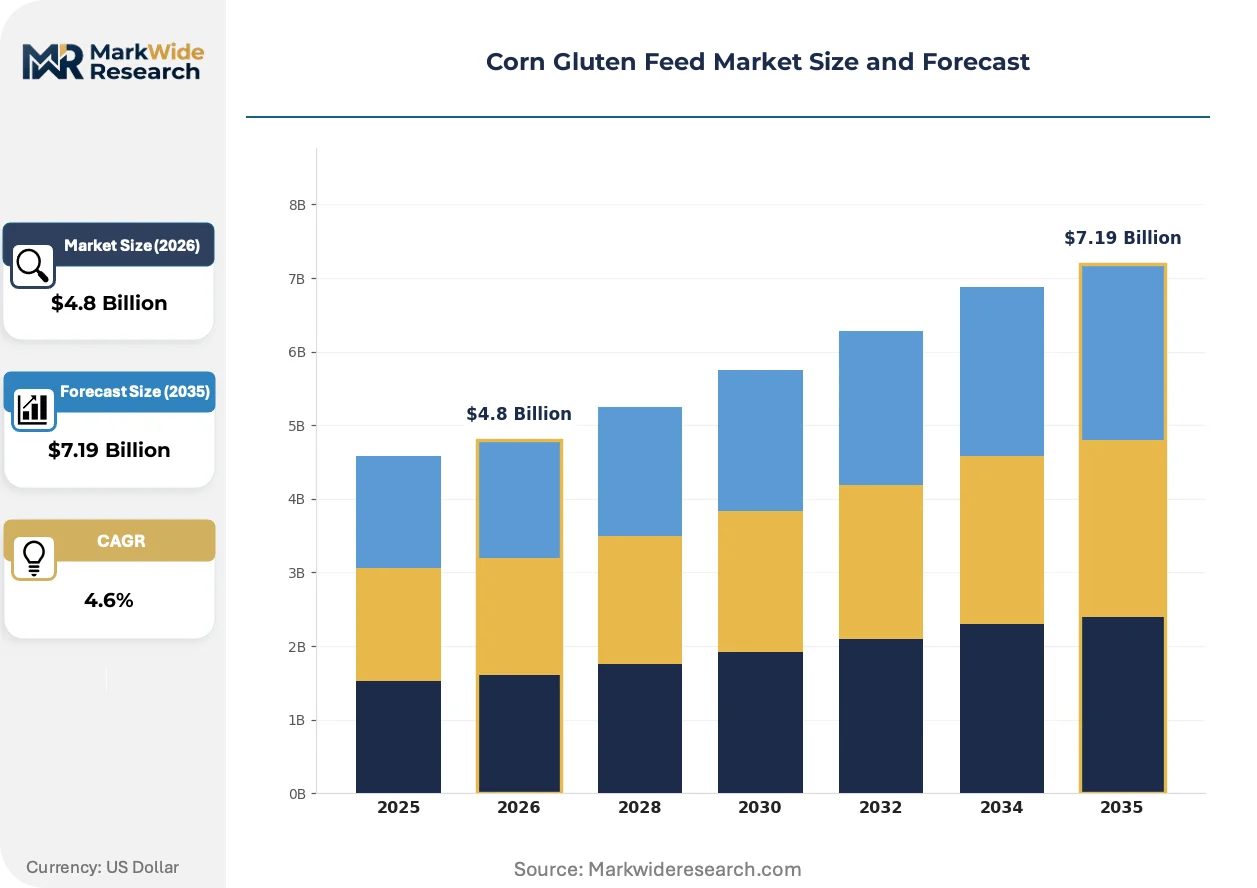
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Corn Gluten Feed, Wet Corn Gluten Feed, Pelleted Corn Gluten Feed, Liquid Corn Gluten Feed Application: Animal Feed, Aquaculture Feed, Organic Fertilizer, Food Industry End User: Dairy Farms, Poultry Farms, Swine Farms, Aquaculture Operations Distribution Channel: Online Sales, Retail Outlets, Direct Sales, Distributors |
| Companies Covered | Ingredion Incorporated, Roquette Frères S.A., Archer Daniels Midland Company, Grain Processing Corporation, Tereos SCA, Cargill, Incorporated, Tate & Lyle PLC, CHS Inc., Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Gluten Feed Market Emerging Trajectories
Enzymatic processing advances and carbon footprint tracking protocols are restructuring how feed value gets measured, shifting buyer criteria from crude protein guarantees to nutrient density per unit of environmental impact.
Enzyme-enhanced wet milling systems deploy targeted cellulase and protease treatments during starch extraction to degrade fiber matrices and liberate bound protein fractions. Large dairy cooperatives in the American Midwest are retrofitting receiving facilities to handle these higher-protein, lower-bulk-density formulations. This technological trajectory is rendering obsolete traditional valuation models based on dry matter tonnage rather than metabolizable protein content.
The EU Green Deal Farm to Fork Strategy imposes binding targets for livestock feed sustainability certification, requiring imported protein ingredients to demonstrate deforestation-free supply chains and measured carbon intensity. European compound feed manufacturers are now screening North American corn gluten feed suppliers for compliance documentation. This regulatory architecture most acutely affects exporters serving Dutch and Danish pork and dairy operations, where procurement departments have embedded sustainability scoring into supplier scorecards.
Buyer concentration among mega-dairies and integrated poultry operations is compressing purchasing cycles and demanding real-time nutrient data transparency through digital feed management platforms. Traditional distributor relationships based on seasonal contracting and guaranteed tonnage are yielding to direct mill-to-farm arrangements with monthly price adjustments tied to futures markets. This behavioral shift is most visible in California's Central Valley, where vertically integrated dairy processors have established captive corn gluten feed supply agreements with specific wet milling facilities.
Corn Gluten Feed Market Segmentation
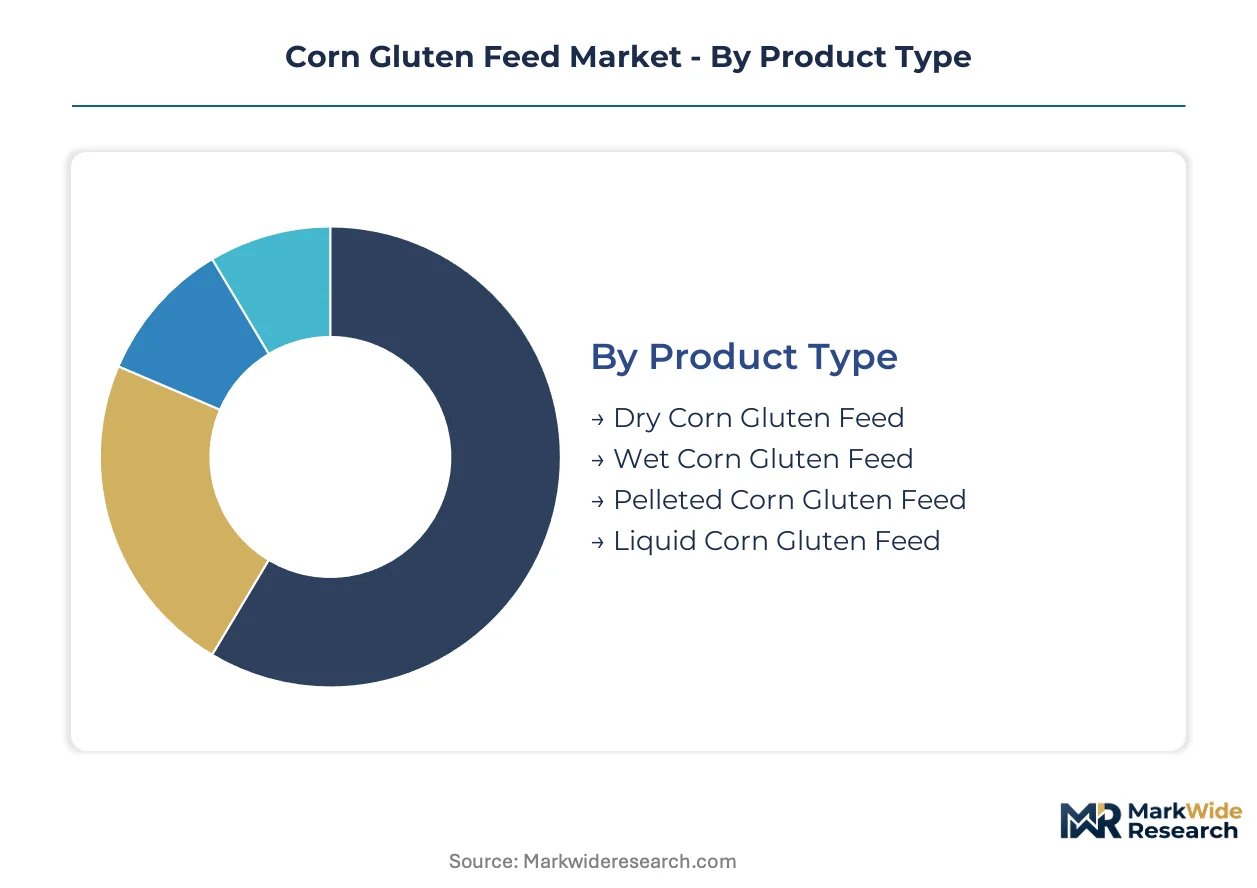
Corn gluten feed segmentation reveals how physical form, application channel, and customer scale interact to determine margin capture and inventory velocity. Wet millers calibrate product specifications against handling economics and nutritional density requirements across distinct end-use clusters.
Product Type:
Dry corn gluten feed turns inventory fastest in bulk commodity channels, while liquid and wet formats require just-in-time coordination with nearby livestock operations.
- Dry Corn Gluten Feed:Contains 90% dry matter with extended shelf stability enabling long-haul distribution to deficit regions. Dairy cooperatives in Wisconsin and Minnesota specify this format for year-round bunker storage and TMR mixing flexibility.
- Wet Corn Gluten Feed:Delivers 40-60% moisture content with superior palatability but 10-14 day spoilage windows restricting radius to 150 miles from wet milling facilities. Large cattle feedlots in Nebraska and Kansas source this format through direct pipeline agreements with Decatur-area processors.
- Pelleted Corn Gluten Feed:Compresses dusty fines into flowable units reducing handling losses at automated poultry houses.
- Liquid Corn Gluten Feed:Soluble protein fractions blended into total mixed rations via tanker delivery systems.
Dry corn gluten feed dominates installed base. Wet corn gluten feed is where expansion concentrates.
Application:
Margin tiers separate commodity feed rations from certified organic fertilizer and food-grade protein isolates demanding traceability documentation.
- Animal Feed:Serves as energy-protein balancer in ruminant diets at 21% crude protein specification, with formulators in Iowa and Illinois adjusting inclusion rates seasonally against distillers grains pricing.
- Aquaculture Feed:Shrimp producers in Southeast Asia pilot corn gluten feed as fishmeal replacement, requiring 45% protein concentrate upgrades and mycotoxin certification below EU threshold levels.
- Organic Fertilizer:Nitrogen-rich residuals command organic certification premiums in specialty crop districts.
- Food Industry:Protein isolates enter gluten-free and plant-based ingredient streams with identity-preserved handling.
Animal feed absorbs volume concentration. Aquaculture feed represents the fastest-growing trajectory.
End User:
Procurement scale determines pricing leverage, with mega-dairies negotiating direct mill contracts while smaller operations rely on distributor tiering.
- Dairy Farms:Large-scale operations in California's Central Valley and Wisconsin's Fox River Valley specify corn gluten feed at 15-25% of dry matter intake, prioritizing cost per unit metabolizable protein over crude protein guarantees alone.
- Poultry Farms:Integrated broiler operations in Georgia and Arkansas demand pelleted formats with dust suppression for automated house systems, paying handling efficiency premiums over bulk commodity pricing.
- Swine Farms:Finishing operations in Iowa and North Carolina limit inclusion to 10% of ration due to fiber tolerance thresholds.
- Aquaculture Operations:Coastal shrimp and salmon producers require specialized blending with amino acid fortification.
Dairy farms anchor procurement volume. Aquaculture operations are climbing the fastest.
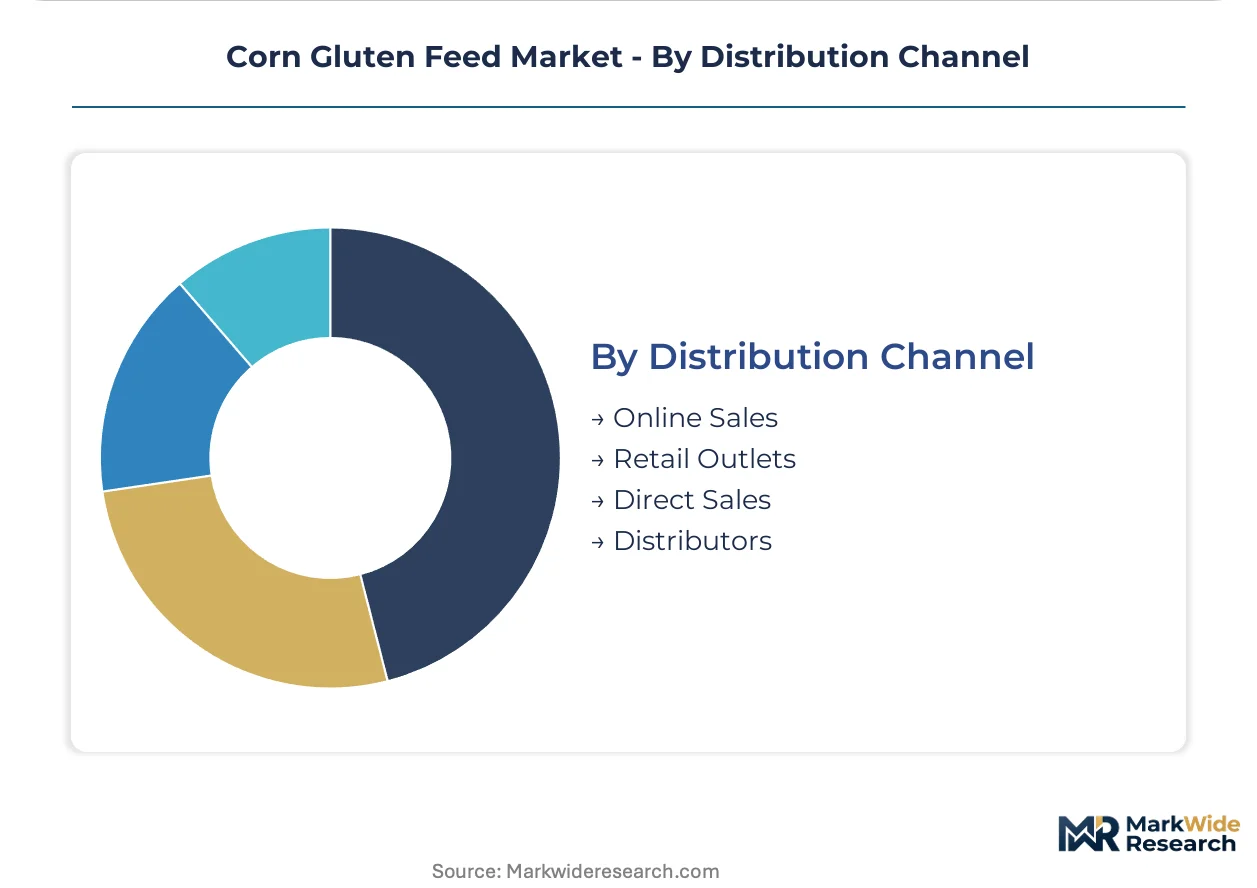
Distribution Channel:
Channel selection reflects customer scale and geographic proximity to wet milling clusters, with direct sales capturing margin from large accounts and distributors serving fragmented demand.
- Direct Sales:Wet millers like Archer Daniels Midland and Cargill route captive volumes to dairy cooperatives through dedicated logistics contracts, eliminating intermediary markups and enabling real-time price adjustments tied to Chicago Board of Trade corn futures.
- Distributors:Regional feed dealers in Minnesota and Ohio aggregate smaller livestock operations into consolidated truckloads, earning 8-12% margins for inventory risk and credit extension.
- Online Sales:Emerging platforms connect specialty organic fertilizer buyers with certified suppliers.
- Retail Outlets:Farm supply stores serve hobby livestock and smallholder segments with bagged formats.
Direct sales command value concentration. Distributors retain reach expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy cooperatives and integrated poultry operations concentrate procurement in wet milling corridors, while aquaculture expansion pulls supply toward coastal blending nodes. Regulatory frameworks governing phosphorus loading and carbon intensity increasingly shape sourcing decisions across production regions.
United States
Large-scale dairy operations in Wisconsin and Minnesota specify corn gluten feed at 15-25% of dry matter intake, prioritizing cost per unit metabolizable protein. The EPA's Renewable Fuel Standard mandates ethanol production volumes that expand wet milling throughput and co-product supply. Decatur, Illinois anchors the largest wet milling cluster, with Archer Daniels Midland and Cargill operating integrated facilities serving regional dairy cooperatives through direct pipeline agreements.
France
Pork and dairy compound feed manufacturers in Brittany and Normandy screen North American suppliers for deforestation-free supply chain documentation. The EU Green Deal Farm to Fork Strategy imposes binding sustainability certification targets on imported protein ingredients. Roquette Frères S.A. operates wet milling capacity in Lestrem, supplying regional feed compounders with co-product streams that meet emerging carbon intensity thresholds.
China
Aquaculture feed mills in Guangdong and Fujian provinces pilot corn gluten feed blends as fishmeal replacements in shrimp and salmon rations. The country's national agricultural regulator enforces mycotoxin thresholds and protein guarantee requirements on imported feed ingredients. The Yangtze River Delta concentration of feed processing capacity creates demand pull for higher-protein, lower-fiber co-product formulations from enzyme-enhanced wet milling systems.
Brazil
Beef cattle feedlots in Mato Grosso and Goiás incorporate corn gluten feed as energy-protein balancers in finishing rations. The national agricultural supply agency monitors feed ingredient quality standards and import documentation requirements. Bunge Limited operates processing infrastructure in São Paulo state, linking domestic corn origination to regional livestock operations through integrated supply chains.
Netherlands
Pork and dairy procurement departments in Gelderland and Overijssel have embedded sustainability scoring into supplier scorecards, favoring lower-carbon protein sources. EU EFSA regulations shape mycotoxin surveillance and preventive control mandates for feed manufacturing facilities. The Randstad logistics corridor enables efficient distribution of imported corn gluten feed to compounders serving Dutch and Danish export-oriented livestock operations.
Corn Gluten Feed Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a consolidated structure where wet milling scale determines supply security. Three archetypes dominate: integrated agribusiness conglomerates with captive corn origination, regional wet milling specialists with co-product diversification, and commodity traders with blending and logistics assets. Competitive moves center on backward integration into corn supply and geographic expansion into underpenetrated aquaculture corridors.
Within the integrated agribusiness tier, Archer Daniels Midland Company and Cargill, Incorporated exemplify channel-control strategies through captive wet milling complexes and direct mill-to-farm arrangements. Tate & Lyle PLC occupies a position emphasizing specialty carbohydrate co-product streams that command premium feed ingredient positioning. These three entities represent distinct competitive vectors: scale-driven supply security, origination-integrated cost control, and differentiated product specialization.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Roquette Frères S.A. |
| Archer Daniels Midland Company |
| Grain Processing Corporation |
| Tereos SCA |
| Cargill, Incorporated |
| Tate & Lyle PLC |
| CHS Inc. |
| Bunge Limited |
| Others |
Supply Flow & Price Mechanics
Decatur, Illinois anchors North American wet milling capacity, with Archer Daniels Midland and Cargill operating integrated complexes that translate corn origination scale into captive pricing power over regional dairy cooperatives. This geographic concentration enables mill-to-farm contracts with real-time indexation, while distant buyers absorb freight premiums that erode delivered cost competitiveness.
Pricing Analysis
Cost-plus contracts tied to Chicago Board of Trade corn futures dominate procurement between wet millers and large dairy operations, with protein guarantee tiers separating standard 21% crude protein specifications from enzyme-enhanced concentrates commanding handling efficiency premiums. Price differentiation hinges on volume scale and geographic proximity to milling clusters, with mega-dairies in Wisconsin negotiating direct pipeline agreements while smaller operations pay distributor markups. Pricing pressure stems from distillers dried grains with solubles competing on protein content, compressing margin pools in energy-protein balancer applications. Large integrated poultry operations show least price sensitivity, prioritizing dust-suppressed pellet formats for automated handling systems over bulk commodity pricing.
Supply Chain Analysis
Upstream corn origination draws from Iowa, Illinois, and Nebraska harvest corridors, with wet milling capacity tethered to rail-served processing clusters within 200 miles of major production zones. Corn supply, natural gas for drying, and enzyme inputs for protein concentration constitute critical cost components. Single-source vulnerability concentrates in the Decatur-Chicago corridor, where infrastructure disruptions ripple through dairy feed rations across the Upper Midwest. Distribution runs through direct sales contracts for large cooperatives and regional distributor networks aggregating fragmented livestock operations into consolidated truckloads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized capabilities in enzyme-enhanced protein concentration and mycotoxin certification infrastructure remain scarce relative to projected aquaculture demand expansion, creating acquisition premiums for operators possessing both technical competencies and coastal logistics access.
For Market Incumbents: Insulate core dairy supply relationships through backward integration into corn origination in Iowa and Illinois, while retrofitting facilities for 45% protein concentrate output to serve Southeast Asian shrimp producers. Distillers grains substitution threatens pricing power in ruminant applications; priority investment in pelleted format capacity captures poultry integrator premiums for handling efficiency. For New Entrants and Emerging Players: Coastal blending facilities in Vietnam and Indonesia represent the most penetrable entry point, with underdeveloped distributor networks and rising fishmeal replacement demand creating first-mover advantages. Enzyme-enhanced wet milling partnerships with established processors offer asset-light capacity access without greenfield capital requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates divesting non-core co-product streams, particularly European compounders facing EU Green Deal compliance cost pressures. Long-term viability favors operators with integrated carbon accounting documentation and deforestation-free supply chain certification. The signal to watch is binding sustainability scoring adoption by Dutch and Danish procurement departments, which would accelerate premium-tier demand bifurcation.| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme-Enhanced Wet Milling Capacity Expansion | Roquette Frères and ADM retrofit facilities to produce 45% protein concentrates for Southeast Asian aquaculture feed mills. |
| Backward Integration into Corn Origination | Cargill's Iowa grain elevator network secures captive supply for Decatur processing complex amid harvest volatility. |
| Coastal Blending Facility Development | Guangdong and Fujian feed processors build dedicated corn gluten feed handling for shrimp farming operations. |
| Carbon Intensity Certification Investment | EU Green Deal compliance documentation enables premium positioning in Dutch and Danish pork procurement scorecards. |
| Pellet Technology Upgrade Program | Georgia and Arkansas poultry integrators specify dust-suppressed formats for automated house systems. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wet milling plant managers, dairy cooperative nutritionists, aquaculture feed formulators, and regional distribution channel partners. Secondary validation drew from USDA grading standards documentation, EPA Renewable Fuel Standard implementation reports, FDA Food Safety Modernization Act guidance, and customs trade flow records. Bottom-up volume estimates from facility-level throughput data were triangulated against top-down consumption models derived from livestock inventory and ration inclusion rate assumptions.
Calibration against historical price spreads between corn gluten feed and competing protein sources anchored elasticity assumptions across the projection horizon. Segmentation dimensions modeled include physical form (dry, wet, pelleted, liquid), application channel (dairy, poultry, swine, aquaculture), and customer scale (direct mill contracts versus distributor-mediated procurement). CAGRs were derived from trend extrapolation of wet milling capacity expansion, ethanol mandate trajectories, and aquaculture feed substitution elasticities, with cross-reference to protein meal trade flow projections.
Practitioners should monitor EPA biofuel policy revisions, Southeast Asian aquaculture disease outbreaks, and Iowa-Illinois phosphorus regulation enforcement intensity for early signals requiring forecast reassessment. Cross-checking against Chicago Board of Trade corn futures curves and EU compound feed production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
IQF Rice Market
Grains
China Maize Market
Grains
Global Wheat Market
Grains
North America Wheat Market
Grains
Global Cassava Flour Market
Grains
Grain Silos Market
Grains
Cornmeal Market
Grains
Global Rice Market
Grains
Argentina Maize Market
Grains
Bangladesh Rice Market
Grains
Europe Maize Market
Grains
White Rice Flour Market
Grains
Green Banana Flour Market
Grains
00 Flour Market
Grains
Soya Flour Market
Grains
Europe Rice Market