
 South America Feed Amino Acids Market | 2026-2036
South America Feed Amino Acids Market Size, Share, and Industry Trends Forecast 2026-2036
South America Feed Amino Acids Market Analytics
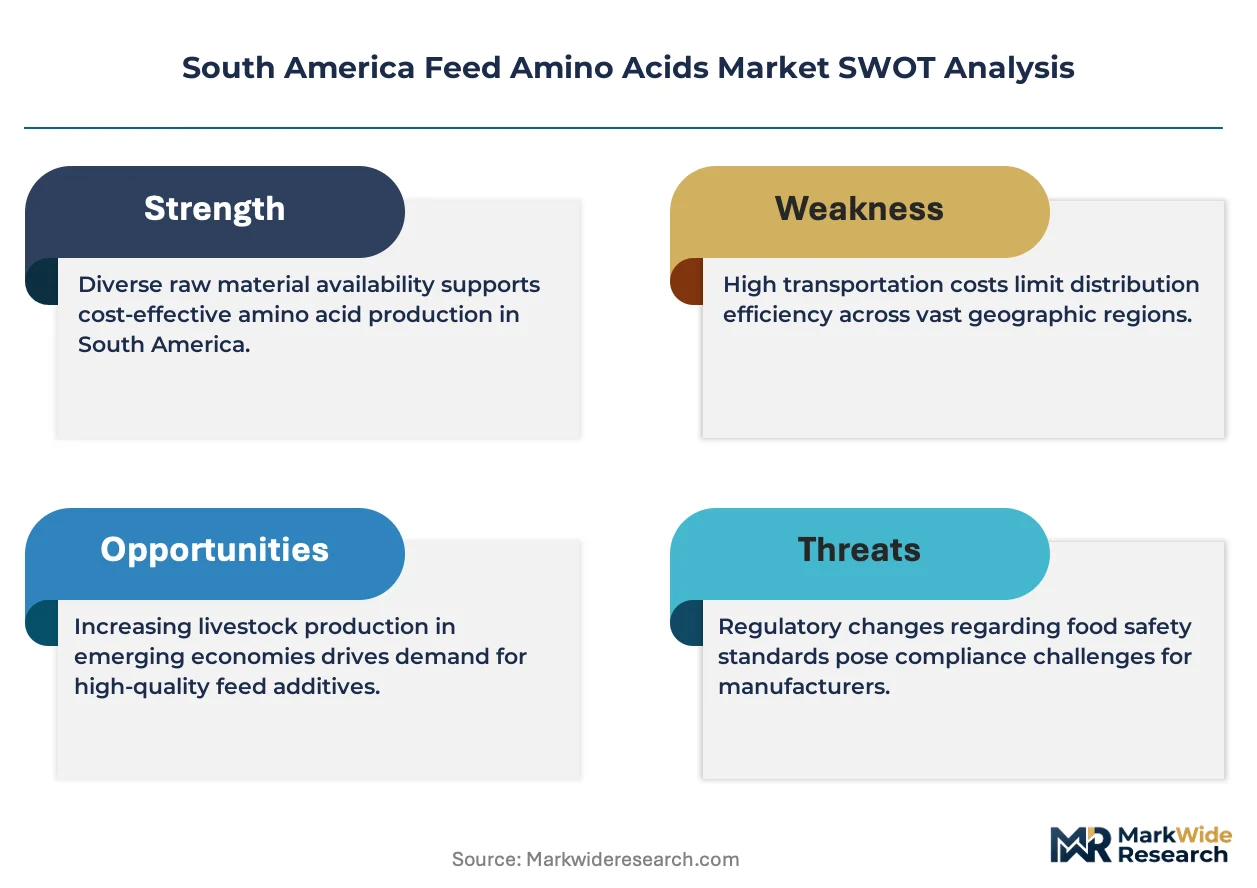
A capital-intensity divergence between integrated fermentation specialists and regional blenders is bifurcating competitive dynamics across the South America feed amino acids landscape. Evonik Industries AG leverages its backward integration into methionine precursors to sustain margin capture in ruminant and poultry applications. Ajinomoto Co Inc anchors its position through biotechnology leadership in L-lysine fermentation, while Archer Daniels Midland Co competes via extensive grain origination networks that secure carbohydrate feedstock for amino acid synthesis.
Feed amino acids constitute biologically active nitrogenous compounds, typically supplied as crystalline L-isomers with minimum purity thresholds of 98.5 percent, that serve as limiting nutrients in monogastric and ruminant diets to optimize nitrogen retention and reduce crude protein requirements. L-Methionine and L-Lysine dominate volume flows due to their status as first-limiting amino acids in corn-soybean meal formulations prevalent across Brazilian and Argentine feed mills. The fermentation-derived source category is expanding fastest as manufacturers convert sugarcane molasses and corn dextrose into specific amino acid profiles, while plant-based extraction from soybean protein concentrates occupies mature, cost-sensitive tiers of the market.
Brazil's MAPA and Argentina's SENASA enforce feed additive registration protocols that align with Codex Alimentarius standards, creating compliance barriers for non-registered imports and shaping product availability across the Mercosur trade zone. ANVISA in Brazil monitors veterinary drug residues in animal products, indirectly pressuring feed mills to document amino acid inclusion rates precisely. Stakeholders must monitor evolving SENASA biosecurity mandates and MAPA feed labeling requirements to anticipate reformulation cycles and import substitution opportunities.
Market Dynamics
MAPAs enforcement of maximum residue limits is forcing feed mills across Brazil to reformulate amino acid inclusion rates, compressing formulation windows and elevating documentation burdens for suppliers serving the Mercosur trade zone.
Growth Catalysts
- SENASA Biosecurity Mandates:Argentina's veterinary regulator is tightening pathogen surveillance in imported feed additives, creating replacement demand for domestically fermented lysine and methionine.
- Poultry Protein Conversion Optimization:Broiler integrators in São Paulo state are intensifying synthetic amino acid supplementation to reduce soybean meal dependency and lower nitrogen excretion rates.
- Fermentation Feedstock Abundance:Brazil's sugarcane molasses and corn dextrose surpluses are anchoring cost-competitive L-lysine production for export throughout Latin America.
Market Restraints
- Input Cost Volatility:Corn and sugarcane price swings directly squeeze fermentation economics, compressing margins for producers lacking backward integration into carbohydrate supply.
- Import Concentration Risk:Chinese-manufactured amino acid precursors dominate regional supply chains, exposing Brazilian formulators to shipping disruptions and currency fluctuations.
- Technical Substitution Ceiling:Ruminant nutritionists face biological limits on how far methionine analogues can replace intact protein before rumen microbial efficiency degrades.
Strategic Opportunities
- Paraguayan Feed Mill Expansion:Underdeveloped amino acid penetration in Paraguay's nascent poultry sector offers first-mover positioning ahead of infrastructure maturation.
- ANVISA Traceability Alignment:Brazil's pharmaceutical regulator is extending veterinary drug tracking requirements to feed additives, rewarding suppliers with pre-certified documentation systems.
- Precision Fermentation Convergence:CRISPR-edited microbial strains combined with continuous bioreactor design are opening novel amino acid profiles beyond standard L-isomers.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Brazilian universities produce insufficient fermentation specialists to staff expanding amino acid production facilities in Minas Gerais.
- MAPA Registration Timelines:New amino acid product approvals stretch 18-24 months, freezing reformulation pipelines and locking mills into suboptimal legacy specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Feed Amino Acids Market |
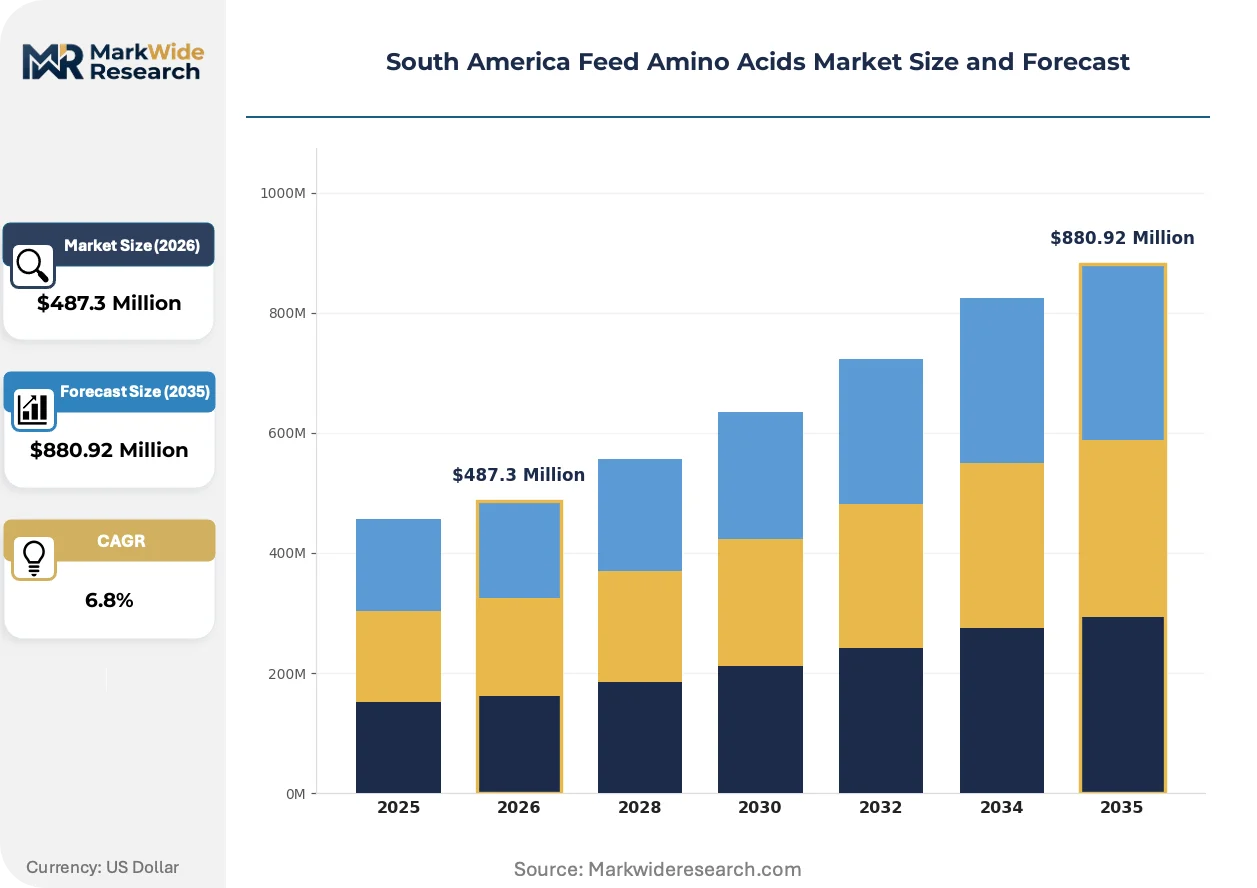
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Lysine, L-Threonine, L-Methionine, L-Tryptophan Source: Plant-Based, Animal-Based, Synthetic, Fermentation Derived End User: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granule, Tablet |
| Companies Covered | IFF (Danisco Animal Nutrition), Ajinomoto Co Inc, Evonik Industries AG, Novus International Inc, Archer Daniels Midland Co, SHV (Nutreco NV), Lonza Group Ltd, Kemin Industries, Adisseo, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Feed Amino Acids Market Evolving Landscape
Fermentation technology advances and regulatory digitization are compressing production cycles while elevating compliance automation requirements across South American feed amino acid operations.
Continuous fermentation systems using immobilized cell bioreactors are displacing traditional batch methods in Brazilian lysine plants. Large integrators in Paraná state are retrofitting facilities to capture 15-20% yield improvements and reduce energy intensity. This displacement is consolidating production among capital-rich operators capable of absorbing bioreactor automation investments.
MAPA's electronic feed additive registry is mandating real-time traceability documentation from manufacturers. The regulation forces amino acid suppliers to integrate blockchain-verified batch records into their quality management systems. Mid-sized Argentine blenders lacking IT infrastructure face exclusion from formal distribution channels serving SENASA-inspected facilities.
Integrated poultry and pork processors are unbundling amino acid procurement from full-feed contracts, establishing direct supplier relationships that bypass traditional distributor markups. This disintermediation concentrates purchasing power among Brazil's top five protein exporters while fragmenting order flows for regional blenders dependent on smallholder livestock operations.
South America Feed Amino Acids Market Segmentation
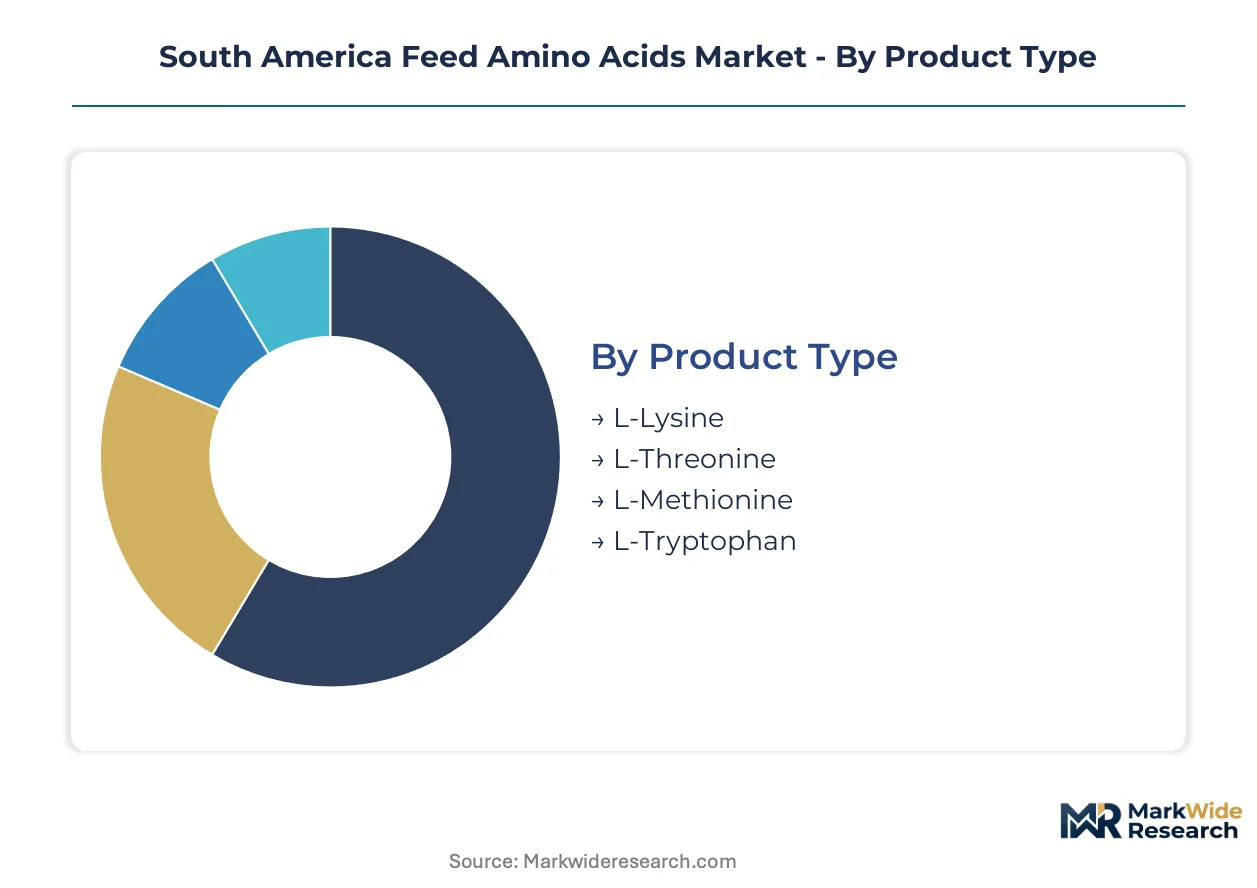
Feed amino acid segmentation in South America reflects divergent supply chain logics across Brazil's industrial corridor and Argentina's Pampas feed belt. Product specifications and sourcing strategies vary sharply between export-oriented integrators and domestic-focused cooperatives.
Product Type:
Domestic consumption concentrates on lysine and methionine for poultry integration in São Paulo and Paraná, while threonine and tryptophan volumes track swine sector export demand to Asian markets.
- L-Lysine:Crystalline L-isomer supplied at minimum 98.5 percent purity serves as the first-limiting amino acid in corn-soybean meal formulations. Demand clusters in Brazil's southeastern feed mill corridor where broiler integrators intensify supplementation to optimize protein conversion ratios and reduce nitrogen excretion.
- L-Methionine:Synthetic and fermentation-derived forms dominate, with hydroxy analogues penetrating ruminant applications. Argentine feed mills in Buenos Aires province drive volume for dairy protein enhancement, constrained by biological limits on rumen bypass efficiency.
- L-Threonine:Second-limiting amino acid for swine diets, primarily imported as Chinese-manufactured premixes for Brazilian pork exporters.
- L-Tryptophan:Niche volume for high-performance breeder diets, concentrated in specialty contracts with integrated layer operations.
L-Lysine holds the largest share; momentum sits with L-Methionine as ruminant applications expand.
Source:
Cost structures bifurcate between carbohydrate-anchored domestic fermentation and import-dependent synthetic chemistry.
- Plant-Based:Extraction from soybean protein concentrates serves cost-sensitive tiers, with Argentine crushing plants supplying defatted meal for amino acid isolation.
- Animal-Based:Hydrolyzed feather and blood meal derivatives face declining acceptance under MAPA residue monitoring protocols.
- Synthetic:Chemical synthesis of methionine precursors dominates import flows, exposing formulators to currency volatility and shipping disruptions from Asian suppliers.
- Fermentation Derived:Expanding most quickly as Brazilian manufacturers convert sugarcane molasses and corn dextrose into specific amino acid profiles, capturing yield advantages from continuous bioreactor investments.
Fermentation derived commands premium positioning; synthetic maintains volume leadership through established supply contracts.
End User:
Species-specific formulation requirements create divergent procurement patterns across the Mercosur trade zone.
- Poultry:Broiler and layer operations in Brazil's Triângulo Mineiro and western Paraná drive lysine and methionine intensity, with integrators unbundling amino acid procurement from full-feed contracts.
- Swine:Export-oriented pork processors in Santa Catarina and Rio Grande do Sul specify threonine-enriched diets for Asian market compliance.
- Ruminants:Dairy operations in Argentina's Córdoba and Santa Fe provinces absorb protected methionine analogues for milk protein enhancement.
- Aquaculture:Nascent tilapia and shrimp feed production in Ecuador and Colombia generates emerging demand for tryptophan-balanced formulations.
Poultry generates the steepest expansion trajectory; ruminant applications face technical substitution ceilings.
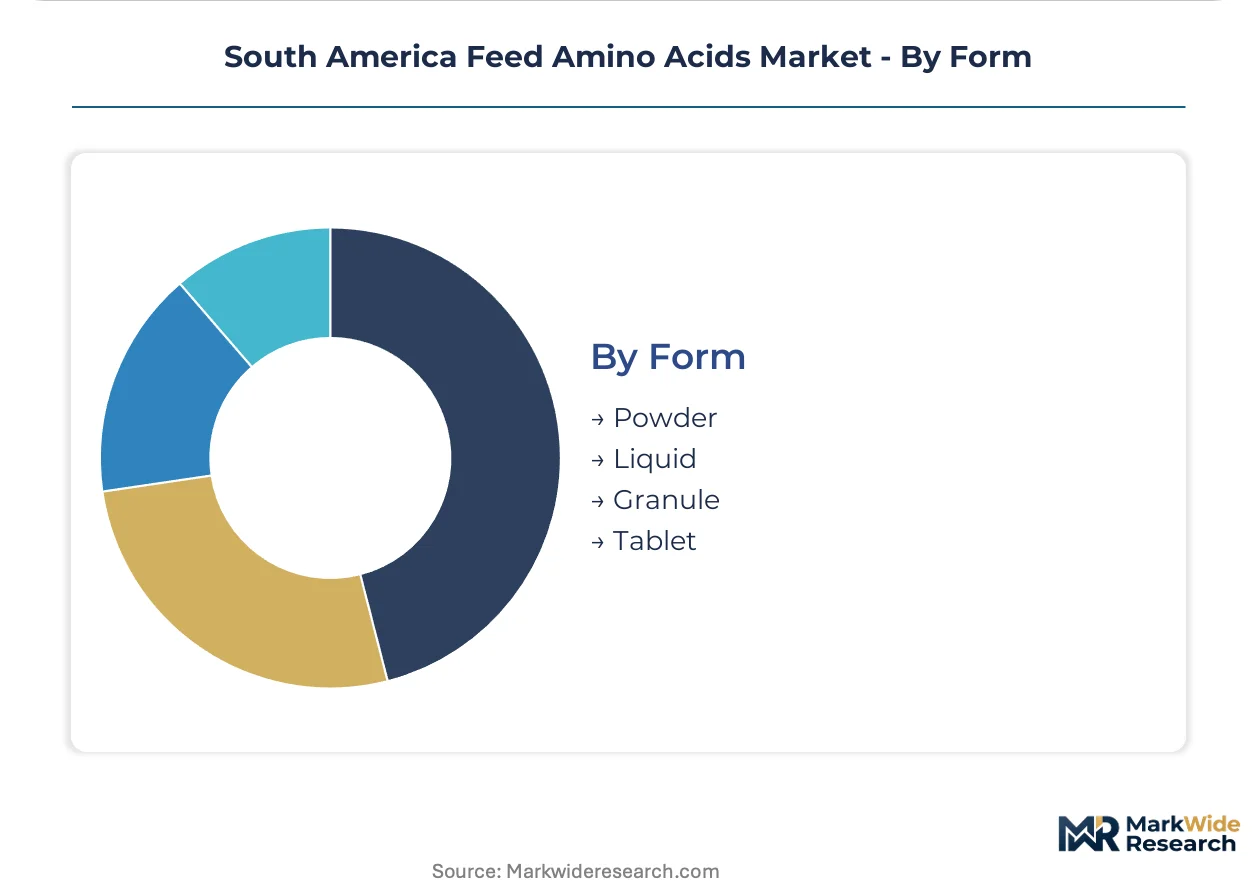
Form:
Handling properties and dosing precision determine format selection across automated and manual feed mill infrastructure.
- Powder:Standard crystalline form for bulk inclusion in complete feeds, dominating large mill operations with pneumatic conveying systems.
- Liquid:Methionine hydroxy analogue dominates liquid applications for post-pelleting application and uniform distribution in high-moisture feeds.
- Granule:Dust-free handling format preferred by mid-sized cooperatives lacking advanced containment infrastructure.
- Tablet:Niche precision-dosing format for research facilities and specialty breeder operations requiring exact inclusion rates.
Powder maintains dominant share; liquid formats gain traction in automated pelleting lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented protein production across the Mercosur trade zone is driving feed amino acid trade flows, with Brazilian fermentation capacity supplying lysine and methionine to Argentine and Chilean feed mills while importing synthetic precursors from Asian suppliers.
Brazil
Broiler integrators in São Paulo and Paraná states are intensifying lysine supplementation to reduce soybean meal inclusion rates and lower nitrogen excretion. MAPA enforces strict maximum residue limits for feed additives, compelling manufacturers to reformulate products for compliance. The southeastern feed mill corridor spanning São Paulo, Minas Gerais, and Paraná concentrates demand, with continuous bioreactor investments capturing yield improvements.
Argentina
Dairy operations in Córdoba and Santa Fe provinces absorb protected methionine analogues for milk protein enhancement, constrained by biological limits on rumen bypass efficiency. SENASA is tightening pathogen surveillance in imported feed additives, creating replacement demand for domestically fermented amino acids. Buenos Aires province feed mills drive volume for ruminant applications, with Pampas-based cooperatives managing procurement for smaller livestock operations.
Chile
Salmon aquaculture feed producers in the Los Lagos region generate specialized demand for tryptophan-balanced formulations to optimize fish growth rates. The country's national agricultural regulator maintains veterinary drug residue monitoring protocols that pressure feed mills to document amino acid inclusion rates precisely. Puerto Montt and surrounding aquaculture clusters anchor consumption, with processors specifying crystalline L-isomer purity thresholds.
Paraguay
Nascent poultry sector expansion in the Central Department and Alto Paraná region offers first-mover positioning ahead of infrastructure maturation. Mercosur trade alignment facilitates Brazilian amino acid exports across the border with reduced tariff barriers. Asunción-based feed distributors are establishing direct supplier relationships with integrated processors, bypassing traditional import channels.
Colombia
Tilapia and shrimp feed production in the Magdalena River basin generates emerging demand for amino acid-enriched formulations targeting export market compliance. The country's national food and drug surveillance institute monitors veterinary drug residues in animal products, indirectly pressuring feed mills to document inclusion rates. Barranquilla and Cartagena processing clusters are retrofitting facilities to capture precision fermentation technologies.
South America Feed Amino Acids Market Competitive Landscape
Concentration sits with integrated fermentation specialists possessing backward integration into carbohydrate feedstock supply, while regional blenders compete on formulation services for mid-sized cooperatives. Three archetypes define competitive positioning: global chemical conglomerates with amino acid divisions, dedicated animal nutrition specialists, and diversified agribusiness traders leveraging grain origination networks. Dominant competitive moves include capacity expansion in Brazilian sugarcane-anchored fermentation corridors and strategic partnerships with poultry integrators unbundling amino acid procurement from full-feed contracts.
Within the biotechnology leadership tier, Ajinomoto Co Inc exemplifies fermentation excellence through L-lysine specialization, while Evonik Industries AG anchors the methionine precursor segment with integrated production systems. Archer Daniels Midland Co occupies a position among agribusiness traders converting grain origination advantages into amino acid synthesis feedstock security. These three entities represent divergent strategic pathways: biotechnology specialization, chemical process integration, and agricultural commodity leverage.
| Leading Market Players |
|---|
| IFF (Danisco Animal Nutrition) |
| Ajinomoto Co Inc |
| Evonik Industries AG |
| Novus International Inc |
| Archer Daniels Midland Co |
| SHV (Nutreco NV) |
| Lonza Group Ltd |
| Kemin Industries |
| Adisseo |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Brazilian fermentation specialists and integrated poultry processors lock in both supply access and price visibility across the Mercosur trade zone, insulating buyers from sugarcane molasses cost swings while constraining supplier margin expansion. These arrangements concentrate pricing power among backward-integrated producers in Minas Gerais while exposing non-integrated blenders to raw material volatility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate Brazilian lysine procurement, with premium-mid-economy pricing differentiation driven by certification grade under MAPA protocols and volume scale commitments. Cost compression in synthetic methionine imports is intensifying because Chinese precursor suppliers face currency headwinds, leaving smallholder cooperatives most price-sensitive while export-oriented integrators absorb modest premiums for traceability documentation.
Supply Chain Analysis
Brazil and China anchor fermentation-derived and synthetic amino acid production respectively, with Brazilian sugarcane molasses and corn dextrose feeding domestic bioreactors while Chinese-manufactured methionine precursors dominate import flows. The regional supply chain rests on carbohydrate feedstock security and Asian chemical synthesis capacity, exposing formulators to single-source vulnerability from shipping disruptions through the Panama Canal. Distribution runs through integrated poultry processors unbundling procurement from full-feed contracts, concentrating purchasing power among Brazil's top protein exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate intensifying substitution pressure from precision fermentation technologies that could displace traditional batch methods, requiring defensive positioning around bioprocess engineering capabilities and regulatory certification depth.
For Market Incumbents: Shield fermentation yield advantages through continuous bioreactor investments in Minas Gerais production corridors, locking in 15-20% efficiency gains that emerging precision fermentation entrants cannot immediately replicate. Deepen backward integration into sugarcane molasses supply through long-term crush agreements with São Paulo ethanol processors, denying feedstock access to potential competitors while securing cost visibility against MAPA residue monitoring compliance costs.
For New Entrants and Emerging Players: Documentation automation services represent a critical service-layer gap where incumbent suppliers under-serve mid-sized Argentine blenders lacking IT infrastructure for MAPA electronic registry compliance. Target Paraguay's nascent poultry sector in the Central Department through direct supplier relationships with Asunción-based feed distributors, bypassing established Brazilian import channels while infrastructure maturation creates first-mover positioning ahead of Mercosur trade alignment completion.
For Investors and Strategic Acquirers: Capital is best deployed toward fermentation specialists possessing captive carbohydrate supply and pre-certified documentation systems for ANVISA traceability alignment, as these assets compound defensibility across regulatory tightening cycles. Monitor SENASA biosecurity mandate implementation velocity as the inflection indicator for domestic substitution demand shifting import-dependent Argentine mills toward Brazilian-sourced lysine.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioreactor Retrofit | Captures yield improvements for lysine producers in Paraná state competing on fermentation efficiency. |
| Backward Integration into Molasses | Secures feedstock cost visibility for Brazilian manufacturers against sugarcane price volatility. |
| Blockchain Traceability Implementation | Aligns quality systems with MAPA electronic registry mandates for amino acid batch documentation. |
| Paraguayan Distribution Partnership | Establishes direct supplier relationships ahead of poultry sector infrastructure maturation. |
| Precision Fermentation R&D Alliance | Develops CRISPR-edited microbial strains for novel amino acid profiles beyond standard L-isomers. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation plant managers, MAPA regulatory affairs leads, poultry integrator procurement directors, and Argentine cooperative supply planners and refined through secondary validation across ANVISA residue monitoring protocols, SENASA biosecurity filings, Brazilian customs trade data, and SEC disclosures from listed animal nutrition specialists. Bottom-up volume estimates from individual production facilities were triangulated against top-down demand projections derived from broiler and swine feed formulation standards.
Variance decomposition across product type, source category, end-use species, and regional production hub dimensions structured the analytical framework over the projection horizon, with CAGRs derived from logistic diffusion curves fitted to amino acid penetration rates in corn-soybean meal formulations. Modeled inputs included MAPA registration timeline distributions, continuous fermentation adoption curves, and poultry protein conversion optimization intensity across São Paulo and Paraná integrators.
Forecasts assume regulatory continuity in Brazilian MAPA feed additive protocols and Argentine SENASA import surveillance regimes; material policy shifts would require re-modeling around accelerated domestic substitution or relaxed residue limits. Recalibration cycles align with material shifts in biosecurity mandate enforcement, precision fermentation commercialization timelines, and Mercosur trade zone tariff harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Straw Market
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Market
Agricultural Commodities
Copra Meal Market
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Bladderpod Oil Market
Agricultural Commodities
Africa Feed Amino Acids Market
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Soy Hulls Market
Agricultural Commodities
South America Feed Premix Market
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
Artificial Fishing Baits Market
Agricultural Commodities
Vietnam Compound Feed Market