
 Beet Pulp Pellets Market | 2026-2036
Beet Pulp Pellets Market Size, Share, and Industry Trends Forecast 2026-2036
Beet Pulp Pellets Market Analysis
Beef and dairy cattle nutrition is recalibrating toward high-fiber, low-starch rations as producers manage rumen health and methane output. Südzucker AG leverages its integrated sugar-to-pellet stream across Central European processing plants. Nordzucker AG anchors supply through Nordic Sugar's Scandinavian beet sourcing network. American Crystal Sugar competes on manufacturing scale from its Red River Valley concentration.
Beet pulp pellets are dried, compressed fibrous residues from sugar beet processing, typically containing 8-10% moisture and 15-20% crude protein by dry weight, manufactured through mechanical pressing and thermal dehydration to serve as rumen-degradable fiber in ruminant diets. The pellets product format dominates bulk logistics and automated feeding systems, while the animal feed end use industry captures the dominant value pool as dairy operations standardize inclusion rates. Nutraceuticals applications represent the fastest-growing segment as functional fiber claims gain regulatory traction in human supplement formulations.
The EU F-Gas Regulation shapes processing energy choices for thermal dehydration stages, while REACH compliance governs additive treatments in pellet binding. USDA grading standards under the Federal Grain Inspection Service influence US export acceptance criteria for animal feed applications. Stakeholders must monitor evolving ammonia emission ceilings in livestock-dense member states and their feed formulation ripple effects.
Market Dynamics
Dairy operations across Germany's Lower Saxony belt are recalibrating feed formulations as ammonia emission ceilings tighten, compressing sourcing flexibility and elevating beet pulp pellet premiums relative to alternative fiber sources.
Growth Catalysts
- EU F-Gas Regulation:Thermal dehydration processes face refrigerant phase-down mandates, accelerating capital turnover toward energy-efficient pellet dryers that lower unit processing costs.
- Netherlands intensive farming corridor:Dairy density concentrates demand for rumen-degradable fiber as producers substitute starch-heavy rations to meet national ammonia reduction targets.
- Pelleting technology:Mechanical pressing advances are compressing moisture variance to 8-10% bands, enabling automated feeding system compatibility and reducing labor input at feed mills.
Market Restraints
- Input cost volatility:Natural gas pricing for thermal dehydration stages compresses processor margins when energy markets spike, particularly affecting Central European sugar beet cooperatives.
- Supply concentration risk:Processing capacity clusters around Red River Valley and Central European beet belts, creating logistics vulnerability during regional harvest disruptions.
- Soy hull substitution:Oilseed processing residues compete on protein-adjusted fiber pricing, displacing beet pulp pellet inclusion in cost-sensitive beef finishing operations.
Strategic Opportunities
- Human nutraceuticals channel:Functional fiber claims under EFSA novel food pathways are opening supplement formulation demand with 40-60% margin premiums over feed-grade volumes.
- REACH additive compliance:Binding agent approvals for pellet integrity create first-mover advantage for processors investing in ECHA-registered lignin derivatives.
- Biogas integration:Anaerobic digestion co-location captures waste heat for dehydration, cutting energy intensity and qualifying installations for EU Green Deal transition financing.
Industry Challenges
- Feed safety certification timelines:FAMI-QS and GMP+ accreditation for cross-border EU trade requires 12-18 month validation cycles that freeze new supplier market entry.
- Moisture calibration expertise:Automated feeding system integration demands precision moisture control that outstrips available technical talent pools in Eastern European dairy expansion zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beet Pulp Pellets Market |
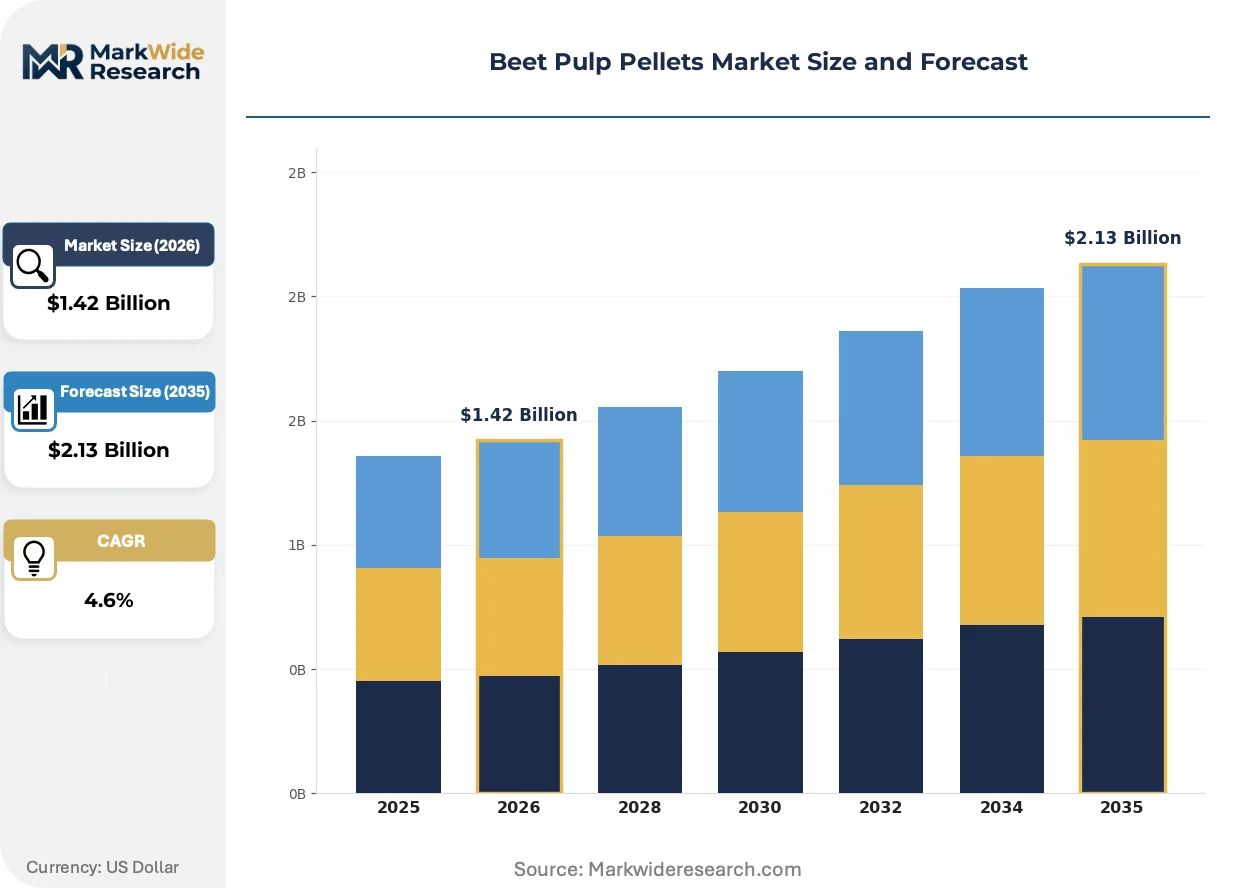
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Flakes, Pellets, Powder End Use Industry: Animal Feed, Food & Beverage, Nutraceuticals, Agriculture Packaging Type: Bags, Bulk Containers, Loose, Pallets Distribution Channel: Direct Sales, Retail, E-commerce, Wholesalers |
| Companies Covered | Südzucker AG, Nordzucker AG, Tereos Group, Nordic Sugar, American Crystal Sugar, Michigan Sugar Company, British Sugar, Midwest Agri-Commodities, Ontario Dehy Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beet Pulp Pellets Market Emerging Trajectories
Processing automation and regulatory chemistry compliance are compressing traditional batch operations while nutraceutical channel development restructures downstream value capture away from commodity feed pricing.
Near-infrared moisture sensors coupled with programmable logic controllers are automating real-time pelleting adjustments. Large dairy cooperatives in Denmark and the Netherlands are retrofitting feed mills with these systems to eliminate manual sampling delays. The technology is automating quality variance reduction that previously required dedicated laboratory staffing.
REACH registration requirements for pellet binding additives are tightening formulation disclosure standards across EU member states. Processors must now document lignin derivative sourcing through ECHA-registered supply chains to maintain market access. German sugar beet processors are consolidating additive procurement to reduce compliance fragmentation costs.
Long-term fiber supply agreements are displacing spot market purchasing among 500-plus cow operations in the Netherlands and Germany's intensive dairy zones. These contracts bundle pellet delivery with nutritional advisory services, compressing independent feed dealer margins. The shift is most visible in Lower Saxony, where three-year supply locks now cover 60% of beet pulp pellet volume.
Beet Pulp Pellets Market Segmentation
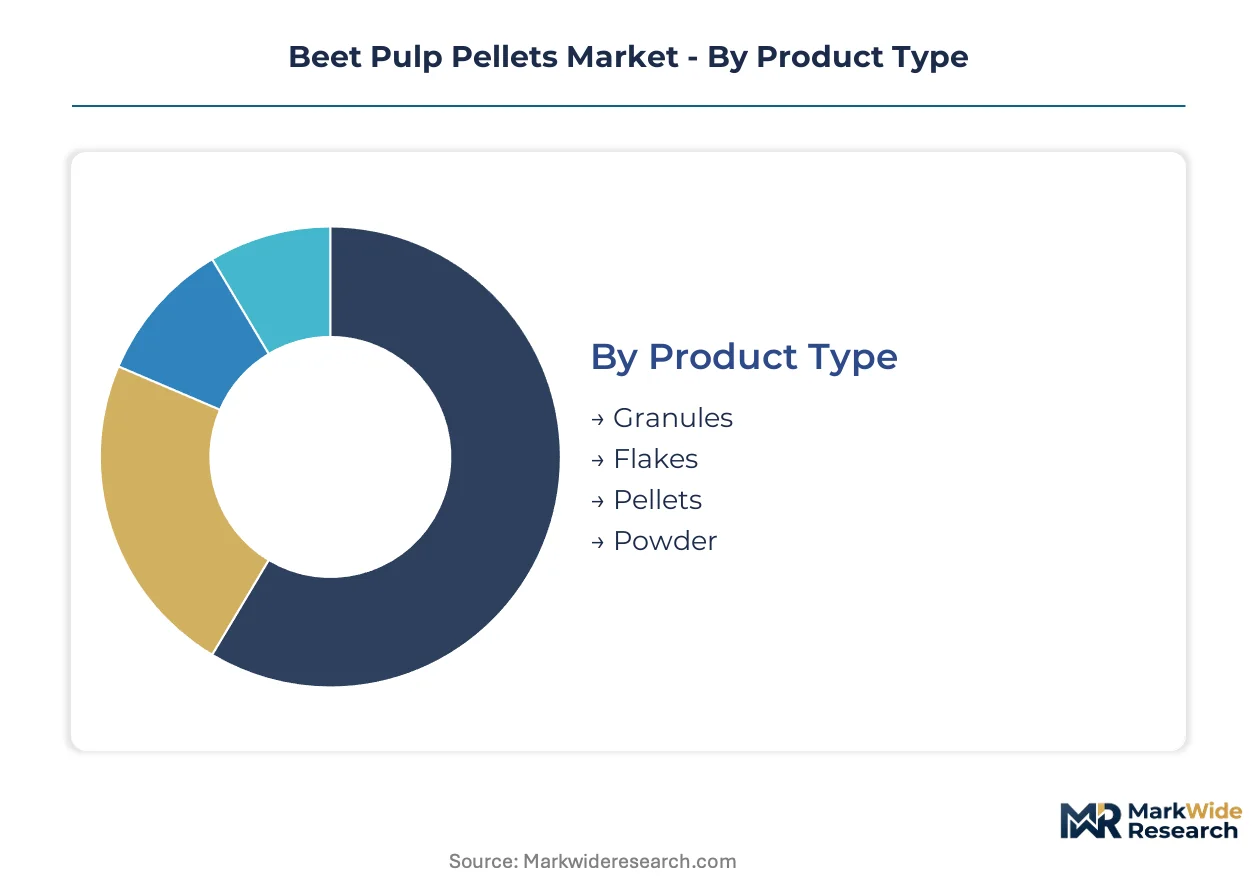
Segmentation in beet pulp pellets reveals how physical form, supply chain configuration, and regulatory compliance requirements fragment value capture across distinct customer workflows. Understanding these divisions exposes where margin pools concentrate and where standardization yields to specification-driven customization.
Product Type:
The customization-vs-standardization spectrum runs from precision-formatted feed ingredients to unprocessed residues requiring on-site handling infrastructure.
- Pellets:Compressed cylindrical forms with standardized 8-10% moisture content enable automated feeding system integration and bulk logistics efficiency. Dairy operations across Germany's Lower Saxony belt specify pellet diameter tolerances to prevent feed mill jamming, tightening procurement specifications beyond commodity grades.
- Granules:Irregular fractured particles with higher surface area accelerate rumen fermentation rates for high-producing dairy herds. Dutch intensive farming corridor operations favor granule inclusion for fresh cow rations where rapid fiber degradation supports milk yield targets.
- Flakes:Thin compressed sheets with expanded surface area suit specialized calf starter formulations requiring softer texture profiles.
- Powder:Fine-milled residue demands dust suppression systems and finds limited application outside industrial binding agent production.
Leading the category by volume: Pellets. Growing fastest: Granules.
End Use Industry:
Cost tier stratification separates commodity feed applications from premium nutraceutical channels with divergent margin structures and regulatory burdens.
- Animal Feed:Rumen-degradable fiber source dominates tonnage flow into dairy and beef cattle operations with inclusion rates calibrated to ammonia emission compliance. Netherlands and German dairy belts standardize beet pulp pellet rations as starch substitutes under national emission ceilings.
- Nutraceuticals:Functional fiber claims under EFSA novel food pathways command substantial margin premiums for human supplement formulations targeting digestive health positioning.
- Food & Beverage:Limited penetration as fiber fortification ingredient constrained by sensory profile challenges in mainstream product applications.
- Agriculture:Soil amendment applications compete with lower-cost organic alternatives, compressing volume growth in specialty crop segments.
Highest volume concentration: Animal Feed. Steepest expansion trajectory: Nutraceuticals.
Packaging Type:
Customer scale and automation investment determine packaging selection across integrated dairy cooperatives versus independent farm operations.
- Bulk Containers:Tote-style intermediate bulk containers bridge manual handling and automated system requirements for mid-scale operations.
- Bags:Multi-wall paper or woven polypropylene sacks serve smaller dairy operations lacking pneumatic handling infrastructure.
- Loose:Unpackaged bulk delivery via pneumatic trailer suits largest integrated feed mills with dedicated receiving equipment.
- Pallets:Unitized load formats support retail and specialty channel distribution with forklift-compatible logistics.
Dominant format by tonnage: Loose. Fastest adoption: Bulk Containers.
Distribution Channel:
Supply chain length and service bundling separate direct processor relationships from intermediated purchasing with nutritional advisory attachments.
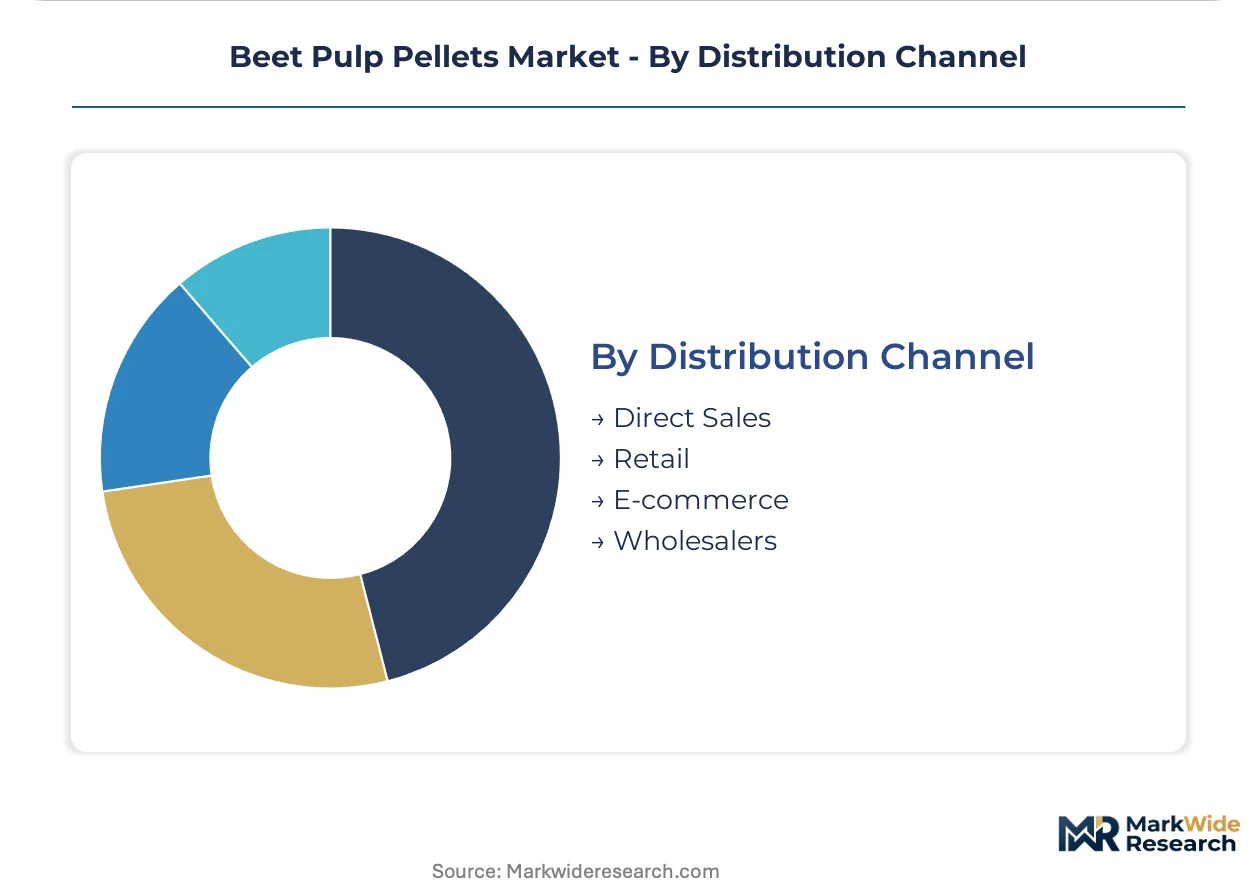
- Direct Sales:Processor-to-farm contracts bundle pellet supply with formulation consulting, capturing long-term supply locks among 500-plus cow operations in intensive dairy zones.
- Wholesalers:Regional feed distributors aggregate demand from smaller operations, compressing margins through volume pooling but extending geographic reach.
- Retail:Farm supply stores serve hobby farmers and equine operations with bagged product at premium pricing.
- E-commerce:Digital procurement channels remain nascent, constrained by bulk logistics requirements and feed safety certification verification needs.
Largest volume flow: Direct Sales. Expanding most quickly: Wholesalers consolidating regional dairy cooperative demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal transition financing zones and ammonia emission control corridors concentrate beet pulp pellet demand in specialized agricultural belts. Processing capacity clusters around established sugar beet cultivation regions where thermal dehydration infrastructure already exists.
Germany
Lower Saxony's dairy belt drives beet pulp pellet consumption as 500-plus cow operations lock in three-year supply contracts. The F-Gas Regulation mandates refrigerant phase-downs for thermal dryers, accelerating capital replacement toward energy-efficient equipment. Südzucker AG operates integrated sugar-to-pellet streams across Central European processing plants serving this corridor.
Netherlands
The intensive farming corridor between Gelderland and North Brabant standardizes beet pulp pellet inclusion as starch substitutes under national ammonia reduction targets. REACH compliance governs lignin derivative binding agents used in pellet integrity formulations. Dairy cooperatives here pioneered long-term fiber supply agreements bundling nutritional advisory services with physical delivery.
United States
Red River Valley concentration supports American Crystal Sugar's manufacturing scale for domestic dairy and export feed markets. USDA grading standards under the Federal Grain Inspection Service establish export acceptance criteria for animal feed applications. Michigan Sugar Company anchors supply through Great Lakes regional processing infrastructure.
United Kingdom
East Anglia's sugar beet zone supplies British Sugar's domestic pellet production for ruminant feed formulations. Post-Brexit sanitary regulations reshape cross-border trade flows with Irish dairy operations. The region's biogas integration potential attracts EU Green Deal transition financing for anaerobic digestion co-location projects.
France
Tereos Group leverages cooperative processing infrastructure across the Champagne-Ardenne beet belt for pellet output. EFSA novel food pathways enable functional fiber claims development for nutraceutical channel expansion. The country's central geographic position supports distribution logistics into both domestic dairy regions and export markets.
Beet Pulp Pellets Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated sugar processors dominating feed-grade volumes while niche operators capture nutraceutical premiums. The vendor base concentrates around established beet cultivation regions where captive pulp supply eliminates raw material procurement risk. Three archetypes prevail: integrated sugar-to-pellet processors, cooperative agricultural marketing organizations, and regional dehydration specialists serving single-country markets. Capacity expansion and REACH-registered additive development represent the dominant competitive vectors as regulatory compliance becomes a market access gate.
Among integrated European processors, Südzucker AG and Nordzucker AG exemplify the scale-driven archetype through captive sugar beet supply networks spanning multiple countries. American Crystal Sugar occupies a position representing North American manufacturing concentration from Red River Valley infrastructure. These three entities anchor the competitive structure by demonstrating how geographic proximity to beet cultivation clusters determines processing economics and supply security.
| Leading Market Players |
|---|
| Südzucker AG |
| Nordzucker AG |
| Tereos Group |
| Nordic Sugar |
| American Crystal Sugar |
| Michigan Sugar Company |
| British Sugar |
| Midwest Agri-Commodities |
| Ontario Dehy Inc |
| Others |
Supply Flow & Price Mechanics
Family-owned sugar beet cooperatives across Central Europe anchor supply discipline through captive pulp streams, converting thermal dehydration cost advantages into pricing power over independent regional dehydration specialists lacking backward integration into beet cultivation.
Pricing Analysis
Short lead-time premiums compress spot market liquidity as Dutch dairy cooperatives pay elevated rates for uncontracted volumes during ammonia compliance deadline periods. Contract-based long-term offtake dominates volume flow, with price differentiation hinging on FAMI-QS certification tier and bundled nutritional advisory services. Pricing pressure stems from natural gas cost volatility in thermal dehydration stages, squeezing processor margins during energy market spikes. Cost-sensitive beef finishing operations in Eastern European expansion zones exhibit highest price sensitivity, while 500-plus cow operations in Germany's Lower Saxony belt prioritize supply security over unit cost.
Supply Chain Analysis
Reverse-logistics infrastructure for bagged product returns remains underdeveloped, creating working capital drag for regional distributors handling retail and equine channel volumes. Supply concentrates in Germany, the Netherlands, and the United States, with processing capacity clustering around Red River Valley and Central European beet belts. Raw material flows draw from sugar beet cultivation, natural gas for thermal dehydration, and ECHA-registered lignin derivative binding agents. Single-source vulnerability runs through concentrated processing geography during regional harvest disruptions. Distribution runs through direct processor-to-farm contracts for largest dairy operations, with wholesalers consolidating mid-scale demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as REACH-registered additive compliance costs freeze new supplier entry for 12-18 month validation cycles, forcing capital-constrained regional players toward exit or acquisition.
For Market Incumbents: Lock in three-year supply agreements with 500-plus cow operations before ammonia emission ceilings tighten further in Dutch and German dairy corridors. Invest in ECHA-registered lignin derivative procurement consolidation to reduce compliance fragmentation costs against emerging cooperative dehydration specialists. Prioritize biogas integration for thermal dehydration co-location to capture EU Green Deal transition financing and secure energy cost insulation. For New Entrants and Emerging Players: Begin with nutraceuticals channel development under EFSA novel food pathways, where functional fiber claims command substantial margin premiums over feed-grade commodity pricing. Target human supplement formulation partnerships as the most penetrable segment, bypassing FAMI-QS accreditation barriers that block feed market entry. Pursue toll manufacturing arrangements with established sugar processors lacking in-house dehydration capacity as the lowest-capital go-to-market angle. For Investors and Strategic Acquirers: First-mover REACH additive registration among Nordic Sugar's Scandinavian network is the leading indicator that captive supply chain control is becoming the decisive competitive moat. The 5-10 year viability window favors processors with integrated sugar-to-pellet streams and existing ECHA-registered additive supply chains. Acquisition target archetype: regional dehydration specialists with biogas co-location permits and pending FAMI-QS accreditation. Watch for ammonia emission ceiling reductions in livestock-dense member states as the signal for accelerated contract restructuring and margin compression among non-integrated players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beet Cultivation | Südzucker AG's captive supply network eliminates raw material procurement risk across Central European processing plants. |
| REACH-Registered Additive Development | ECHA-registered lignin derivatives create first-mover market access gates as binding agent disclosure standards tighten. |
| Biogas Integration for Thermal Dehydration | Anaerobic digestion co-location captures waste heat and qualifies installations for EU Green Deal transition financing. |
| Long-Term Supply Agreement Expansion | Three-year fiber supply locks now cover dominant volume share in Netherlands and Germany's intensive dairy zones. |
| Nutraceuticals Channel Diversification | EFSA novel food pathways enable functional fiber claims with substantial margin premiums over feed-grade volumes. |
Methodological Framework
Independent corroboration across processor procurement directors, dairy cooperative nutritionists, and feed mill automation engineers underwrites the qualitative findings in this analysis. Primary fieldwork combined structured interviews with these stakeholder roles alongside secondary validation through EU F-Gas Regulation implementation documents, ECHA REACH registration databases, and USDA Federal Grain Inspection Service grading standards. Trade data from customs authorities and agricultural cooperative financial disclosures provided volume and flow triangulation. Bottom-up demand modeling across dairy operation scale tiers and top-down supply assessment from sugar beet processing capacity yielded convergent estimates.
Rate-of-change decomposition across the projection horizon separates volume growth from value expansion through price-mix effects. Segmentation dimensions modeled include product type precision, end-use industry margin tier, packaging automation compatibility, and distribution channel service bundling. CAGRs were derived from fitted growth curves against historical sugar beet pulp utilization patterns and projected ammonia emission compliance trajectories. Industry-specific forecast inputs incorporate natural gas price scenarios for thermal dehydration energy costs and EFSA novel food approval timelines for nutraceutical channel development.
Natural gas price volatility, EFSA regulatory decision delays, and ammonia emission ceiling revisions are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding energy market stability, additive registration continuity, and livestock emission policy trajectory. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Roundwood Market
Agricultural Commodities
North America Corn Glucose Market
Agricultural Commodities
Corn and Corn Starch Derivatives Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
Vietnam Feed Concentrate and Basemix Market
Agricultural Commodities
Hermetic Food Grain Storage Market
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market
Agricultural Commodities
Artificial Fishing Baits Market
Agricultural Commodities
Growing Peat Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Black Pellet Market
Agricultural Commodities
Castor Oil Market