
 Straw Market | 2026-2036
Straw Market Size, Share, and Industry Trends Forecast 2026-2036
Straw Market Outlook
ISO 17088 certification for compostable plastics is collapsing the supplier base eligible for European foodservice contracts. Huhtamaki Oyj leverages its molded fiber infrastructure across Nordic markets to sustain volume leadership in QSR channels. Transcend Packaging anchors UK supply through its Wales-based paper straw facility, while Footprint differentiates via plant-based polymer formulations designed for hot-beverage endurance.
Straw denotes a slender tubular device engineered for beverage consumption, typically manufactured from paper, polylactic acid, polypropylene, or post-consumer recycled content with diameters ranging from four to eight millimeters and wall thickness calibrated for collapse resistance under suction pressure. The product serves as a critical interface between packaged beverages and consumers across foodservice, institutional catering, and retail channels. Natural straw products lead unit volume in European markets where compostability mandates dominate procurement specifications, while synthetic straw variants retain cost advantages in price-sensitive emerging markets. Packaging applications command the largest value share within the application dimension, though construction-grade straw bales gain traction in low-carbon building projects across North America.
The EU Single-Use Plastics Directive and FDA food-contact substance notifications jointly determine which materials gain market access across Atlantic trade corridors, with compostability certifications increasingly substituting for conventional polymer approvals. REACH chemical registrations and state-level extended producer responsibility frameworks in California and New York impose additional compliance layers on importers. Stakeholders must monitor evolving biodegradability testing protocols and substrate-specific bans as municipalities accelerate implementation timelines beyond federal minimums.
Market Dynamics
The EU Single-Use Plastics Directive is collapsing the supplier base for conventional polymer straws while accelerating capital flows into compostable material extrusion infrastructure across European packaging corridors.
Growth Catalysts
- EU Green Deal implementation:Mandatory compostability standards for foodservice packaging are redirecting procurement budgets toward certified biopolymer substrates. Quick-service restaurant chains now specify ISO 17088-compliant materials in tender documents.
- Hot-beverage endurance specifications:Plant-based polymer formulations that maintain structural integrity above sixty degrees Celsius are unlocking premium placement in coffeehouse channels previously dominated by plastic.
- Germany's packaging conversion corridor:Biopolymer extrusion capacity expansion in Baden-Württemberg and Bavaria is reducing lead times for foodservice distributors serving Central European markets.
Market Restraints
- PLA resin price volatility:Corn starch feedstock costs fluctuate with agricultural commodity cycles, compressing converter margins during harvest shortfalls in North American grain belts.
- ISO 17088 certification scarcity:Third-party testing laboratory capacity constraints in Europe extend validation timelines to fourteen months, freezing new entrants from contract eligibility.
- Molded fiber substitution threat:Lid-integrated drinking spouts in hot-cup designs eliminate straw requirements entirely in grab-and-go coffee segments.
Strategic Opportunities
- California extended producer responsibility frameworks:State-level mandates for packaging recyclability create first-mover advantage for suppliers with pre-approved material dossiers.
- Construction-grade straw bales:Low-carbon building projects across North America are absorbing agricultural residue streams as insulation material, diverting supply from traditional livestock bedding.
- Direct-to-foodservice digital procurement:Platform-based ordering systems are disintermediating distributor networks, enabling converters to capture margin previously allocated to wholesale intermediaries.
Industry Challenges
- Composting infrastructure mismatch:Industrial composting facility coverage remains patchy across municipalities, creating consumer confusion about actual disposal pathways for certified products.
- Extrusion equipment retooling costs:Conventional polypropylene lines require capital-intensive modification to process temperature-sensitive biopolymers without thermal degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Straw Market |
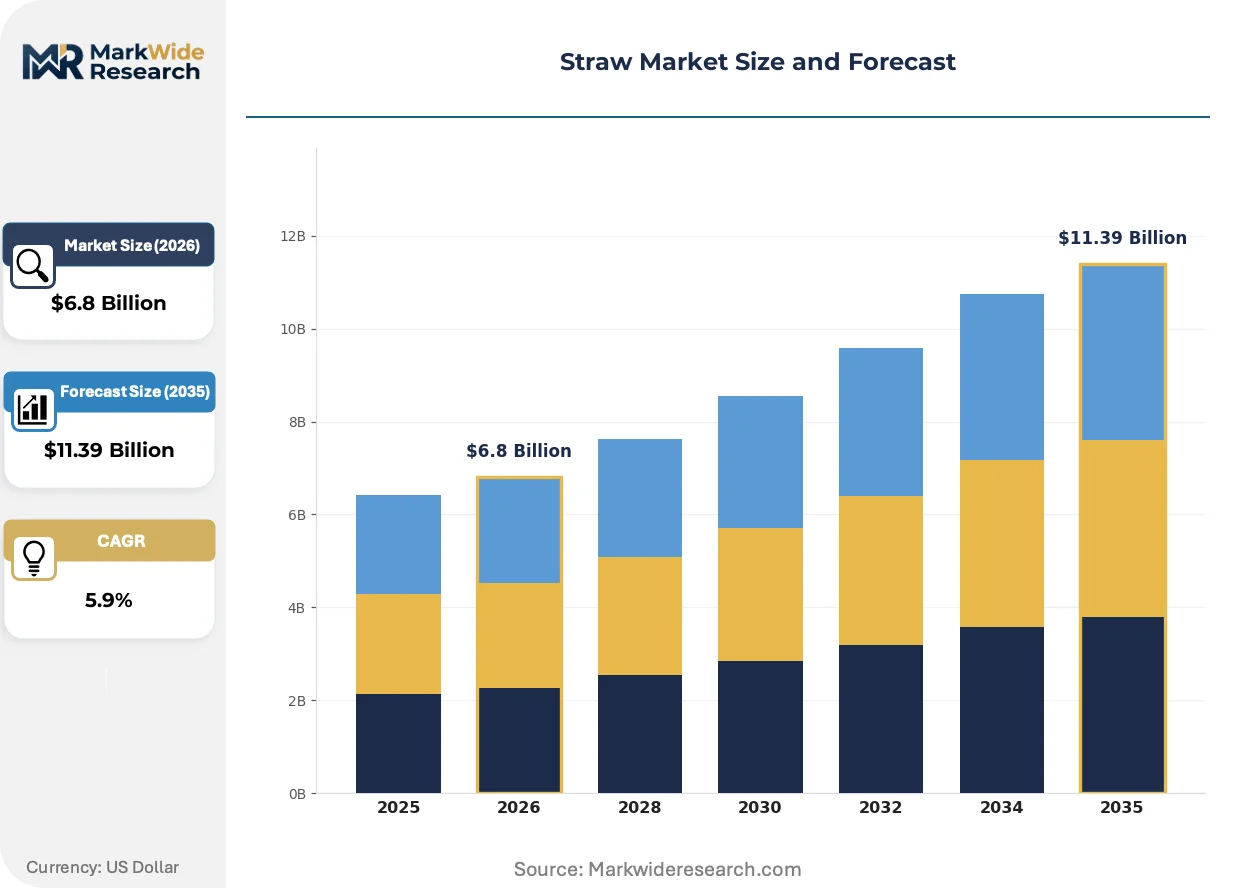
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Straw, Synthetic Straw, Straw Bales, Straw Boards Application: Packaging, Construction, Agriculture, Crafts End User: Farmers, Manufacturers, Retailers, Artisans Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | Hoffmaster Group, Huhtamaki Oyj, Transcend Packaging, Footprint, Canada Brown Eco Products, Tetra Pak Group, Fuling Global, Biopak, Vegware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Straw Market Strategic Shifts
Material scientists and packaging engineers are converging on multi-layer substrate architectures that reconcile performance specifications with end-of-life compostability requirements.
Biopolymer barrier coating technology is miniaturizing. Thin-film polylactic acid formulations now provide liquid resistance equivalent to conventional plastics at half the caliper weight. Quick-service beverage chains in Nordic markets are adopting these substrates for cold-drink applications. The technology is miniaturizing material throughput requirements per thousand straws, compressing raw material costs toward parity with fossil-based alternatives.
REACH chemical registrations for novel biopolymer additives are tightening. ECHA's updated guidance on substance evaluation for food-contact applications extends dossier preparation timelines. European converters with legacy additive portfolios face reformulation costs or supply discontinuation. Small and mid-scale extrusion houses in Poland and Czechia are consolidating to share regulatory compliance expenses.
Foodservice procurement departments now mandate compostability certifications ahead of unit cost in vendor scorecards. Large contract catering operators have displaced price-primary selection criteria with environmental compliance thresholds. Multi-unit restaurant groups in Germany and France are consolidating supplier panels to three approved vendors per material category, compressing competitive field density in those markets.
Straw Market Segmentation
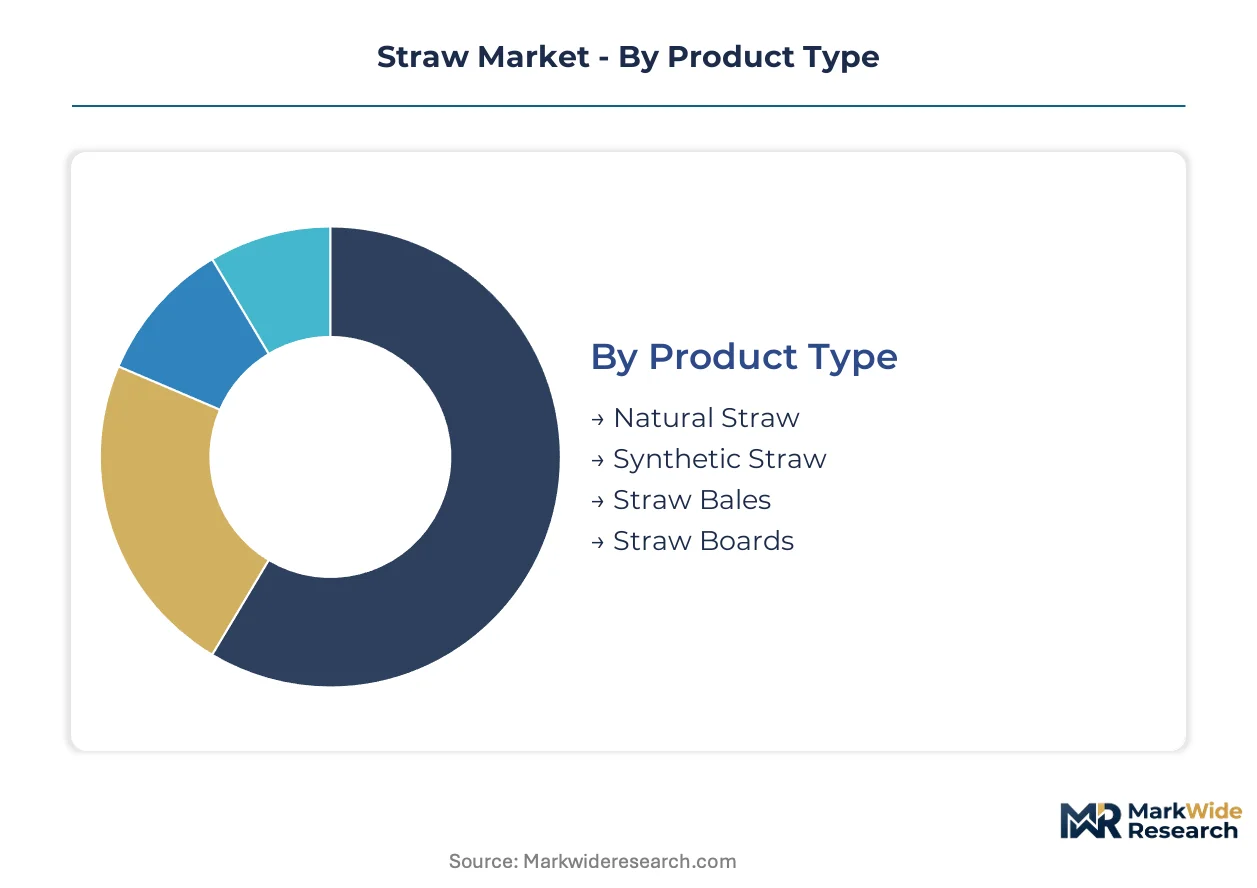
Material compliance requirements diverge sharply across end-use applications, forcing suppliers to maintain parallel certification portfolios. Segmentation clarity enables converters to align extrusion capacity with specific regulatory corridors rather than pursuing undifferentiated volume.
Product Type:
REACH chemical registrations and EU Green Deal mandates are bifurcating the supplier base between compostable-certified and conventional polymer portfolios.
- Natural Straw:Derived from wheat, rice, or barley stalks with minimal processing, these products carry inherent compostability without additive-dependent certification pathways. Quick-service restaurant chains in Germany and France now mandate natural straw specifications in procurement tenders to preempt municipal disposal restrictions. Established volume favors natural straw; emerging adoption favors straw boards.
- Synthetic Straw:Manufactured from polylactic acid, polypropylene, or post-consumer recycled polymers with calibrated wall thickness for collapse resistance under suction pressure. FDA food-contact substance notifications and ECHA REACH registrations determine Atlantic trade corridor eligibility, with PLA formulations gaining share in Nordic coffeehouse channels requiring hot-beverage endurance above sixty degrees Celsius.
- Straw Bales:Compressed agricultural residue bundles serving livestock bedding and emerging low-carbon construction insulation markets across North America.
- Straw Boards:Engineered fiber panels binding straw stalks with natural adhesives for interior cladding and furniture substrate applications.
Cost tier separation runs deepest between certified compostable grades and uncertified commodity polymers.
Application:
End-of-life disposal infrastructure availability dictates material selection more than unit economics in European corridors.
- Packaging:Beverage consumption interfaces dominate unit volume, with diameter specifications ranging four to eight millimeters calibrated for suction pressure tolerance. Industrial composting facility coverage gaps across municipalities create consumer confusion about actual disposal pathways despite ISO 17088 certification claims.
- Construction:Low-carbon building projects absorb agricultural residue streams as insulation material, diverting supply from traditional livestock bedding applications. California extended producer responsibility frameworks create first-mover advantage for suppliers with pre-approved material dossiers in this segment.
- Agriculture:Mulching substrates and erosion control blankets utilize unprocessed straw stalks without extrusion or coating requirements.
- Crafts:Decorative and artisanal applications prioritize aesthetic uniformity over structural performance specifications.
Application maturity inverses across geographies: packaging leads in Europe while construction climbs fastest in North American markets.
End User:
Procurement sophistication varies dramatically between institutional buyers and fragmented artisanal demand.
- Farmers:Direct agricultural residue producers with captive supply of unprocessed straw stalks for on-farm utilization or regional sale.
- Manufacturers:Converters operating extrusion and molding infrastructure across Baden-Württemberg and Bavaria, scaling biopolymer capacity to serve Central European foodservice distributors. Margin pressure concentrates among manufacturers lacking backward integration into feedstock supply.
- Retailers:Multi-unit restaurant groups consolidating supplier panels to three approved vendors per material category, compressing competitive field density in German and French markets.
- Artisans:Fragmented demand requiring small-batch fulfillment without minimum order quantity leverage.
Customer concentration favors manufacturers; margin capture favors farmers with residue monetization infrastructure.
Distribution Channel:
Platform-based ordering systems are disintermediating traditional wholesale networks in foodservice procurement.
- Online Retail:Direct-to-consumer fulfillment for craft and small-batch agricultural applications, bypassing distributor margin layers.
- Wholesale:Distributor networks serving institutional catering operators with consolidated environmental compliance thresholds replacing price-primary selection criteria.
- Direct Sales:Converter relationships with quick-service restaurant chains specifying ISO 17088-compliant materials in tender documents, enabling margin capture previously allocated to wholesale intermediaries.
- Distributors:Regional logistics providers facing disintermediation as digital procurement platforms enable direct converter-to-operator contracting.
Channel evolution favors direct sales; infrastructure legacy favors wholesale networks with established cold-chain capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal implementation and extended producer responsibility frameworks are redirecting procurement budgets toward certified biopolymer substrates across foodservice channels. National compostability mandates are collapsing supplier bases in some markets while accelerating capital flows into compliant material infrastructure in others.
Germany
Baden-Württemberg and Bavaria host the densest concentration of biopolymer extrusion capacity in Europe. The country's packaging conversion corridor reduces lead times for Central European foodservice distributors. ISO 17088 certification requirements in procurement tenders are compressing competitive field density to three approved vendors per material category.
United States
California and New York state-level extended producer responsibility frameworks create first-mover advantage for suppliers with pre-approved material dossiers. FDA food-contact substance notifications determine market access for Atlantic trade corridors. Construction-grade straw bale demand in low-carbon building projects diverts agricultural residue from traditional livestock bedding applications.
United Kingdom
Wales-based paper straw manufacturing anchors UK supply for quick-service restaurant chains. The country's foodservice procurement departments now mandate compostability certifications ahead of unit cost in vendor scorecards. REACH chemical registrations for novel biopolymer additives extend dossier preparation timelines for European trade compliance.
France
Multi-unit restaurant groups are consolidating supplier panels to three approved vendors per material category. The national regulator enforces EU Single-Use Plastics Directive implementation timelines that exceed federal minimums. Île-de-France hosts the largest concentration of institutional catering operators with environmental compliance thresholds replacing price-primary selection criteria.
China
Domestic biopolymer resin production scales to serve export markets facing compostability mandates. The country's national standards body aligns testing protocols with ISO frameworks for food-contact applications. Yangtze River Delta converters process temperature-sensitive polymers for European foodservice contract eligibility.
Straw Market Competitive Environment
Player mix skews toward integrated packaging conglomerates with molded fiber infrastructure and specialized biopolymer converters with certification depth. The competitive field compresses around three strategic archetypes: volume leaders leveraging Nordic distribution networks, regional specialists anchoring national supply through single-facility scale, and material innovators differentiating via hot-beverage endurance formulations. Dominant competitive moves include backward integration into feedstock supply and direct-to-foodservice digital procurement platform development.
Among Nordic-based volume leaders, Huhtamaki Oyj exemplifies the integrated conglomerate archetype with cross-border molded fiber deployment. Transcend Packaging represents the regional specialist model with Wales-based manufacturing anchoring UK foodservice supply. Footprint occupies a position within the material innovation tier, exemplifying plant-based polymer formulation differentiation for premium channel placement.
| Leading Market Players |
|---|
| Hoffmaster Group |
| Huhtamaki Oyj |
| Transcend Packaging |
| Footprint |
| Canada Brown Eco Products |
| Tetra Pak Group |
| Fuling Global |
| Biopak |
| Vegware |
| Others |
Value Chain & Pricing Dynamics
Fourteen-month ISO 17088 certification timelines compress converter margins while amplifying pricing power for incumbent suppliers with pre-validated dossiers. Procurement officers at multi-unit restaurant groups now weight compliance ahead of unit cost, shifting margin capture toward certified manufacturers.
Pricing Analysis
Certification level creates the primary spread across the straw market, with ISO 17088-compliant biopolymers commanding premium placement against uncertified commodity polymers. Three-tier pricing structure separates premium PLA formulations for hot-beverage endurance from standard cold-drink grades and economy polypropylene alternatives. Pricing pressure stems from corn starch feedstock volatility in North American grain belts, squeezing converter margins during harvest shortfalls. Quick-service restaurant chains exhibit lowest price sensitivity, prioritizing tender compliance over unit economics, while fragmented artisanal buyers remain most cost-responsive.
Supply Chain Analysis
Inbound logistics costs from Yangtze River Delta ports to European foodservice distributors fluctuate with container availability on Asia-Europe trade lanes. Biopolymer extrusion capacity concentrates in Germany, China, and the United States, with Baden-Württemberg converters serving Central European lead time requirements. Raw material flows hinge on corn starch supply from Midwest grain belts, sugarcane bagasse from Brazilian processors, and post-consumer recycled pulp from Nordic collection systems. Single-source vulnerability runs through third-party testing laboratory capacity constraints in Europe. Distribution runs through direct-to-foodservice digital platforms disintermediating traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as multi-unit restaurant groups consolidate supplier panels to three approved vendors per material category, fragmenting competitive access for uncertified converters.
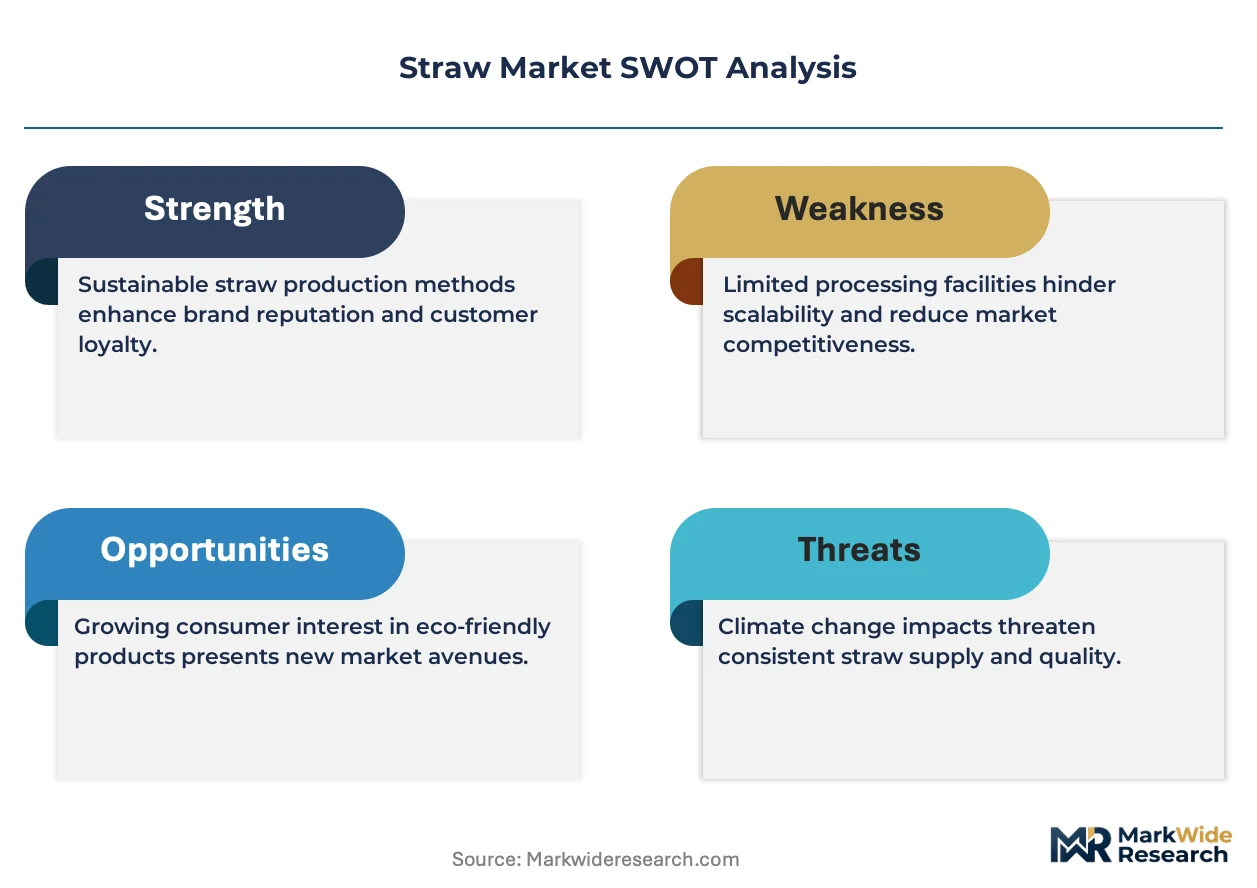
For Market Incumbents: Secure backward integration into PLA resin supply or captive corn starch processing to insulate margins from agricultural commodity cycles. Expand extrusion capacity in Baden-Württemberg to capture lead time advantages for Central European distributors. Prioritize hot-beverage endurance R&D to defend premium positioning against molded fiber lid-integrated spouts eliminating straw requirements entirely. For New Entrants and Emerging Players: Differentiate on construction-grade straw bales for North American low-carbon building projects, a segment absorbing agricultural residue streams with minimal certification overhead. Target California extended producer responsibility frameworks where pre-approved material dossiers create first-mover advantage. Pursue direct-to-foodservice digital procurement platforms to bypass distributor margin layers entirely. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EU Green Deal implementation timelines and state-level mandates in California and New York will perpetually reshape eligible supplier bases. Acquisition targets should display integrated molded fiber infrastructure or biopolymer formulation depth with validated ISO 17088 dossiers. Monitor industrial composting facility coverage expansion across municipalities as the inflection signal for certified product demand realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn starch processing captivity insulates PLA converters from Midwest grain belt harvest volatility. |
| ISO 17088 Certification Investment | Pre-validated dossiers unlock tender eligibility for EU Single-Use Plastics Directive-compliant foodservice contracts. |
| Hot-Beverage Endurance Formulation R&D | PLA architectures maintaining integrity above sixty degrees Celsius capture premium coffeehouse channel placement. |
| Direct-to-Foodservice Digital Platform Development | Platform-based ordering disintermediates wholesale distributors, capturing margin previously allocated to intermediaries. |
| Construction-Grade Straw Bale Capacity Expansion | North American low-carbon building projects absorb agricultural residue with minimal regulatory compliance overhead. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with foodservice procurement directors, biopolymer extrusion plant managers, packaging compliance officers, and agricultural residue processors. Secondary validation drew from EU Single-Use Plastics Directive implementation documents, FDA food-contact substance notification databases, ECHA REACH registration filings, and customs trade flow records. Bottom-up volume triangulation across material grades and top-down value reconciliation against foodservice channel spend produced convergent estimates.
Across the analysis window, the forecast framework modeled product type segmentation, application end-use, and geographic regulatory corridor dimensions. CAGRs were derived from elasticity-adjusted demand projections calibrated against extrusion capacity expansion timelines and certification validation backlogs. Key inputs included PLA resin price indices, industrial composting facility coverage maps, and quick-service restaurant chain procurement tender specifications.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated municipal composting infrastructure buildout would require recalibration. Forecasts reflect assumptions around biopolymer additive approval timelines and agricultural commodity price stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Middle East Feed Amino Acids Market
Agricultural Commodities
Beet Pulp Pellets Market
Agricultural Commodities
Copra Meal Market
Agricultural Commodities
North America Feed Lutein and Zeaxanthin Market
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
Soybean Derivatives Market
Agricultural Commodities
Hermetic Food Grain Storage Market
Agricultural Commodities
Europe Feed Amino Acids Market
Agricultural Commodities
Feed Sucrose Market
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
Artificial Fishing Baits Market
Agricultural Commodities
Europe Ruminant Feed Market
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Corn and Corn Starch Derivatives Market
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
North America Corn Glucose Market