
 Vietnam Compound Feed Market | 2026-2036
Vietnam Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Compound Feed Market Analytics
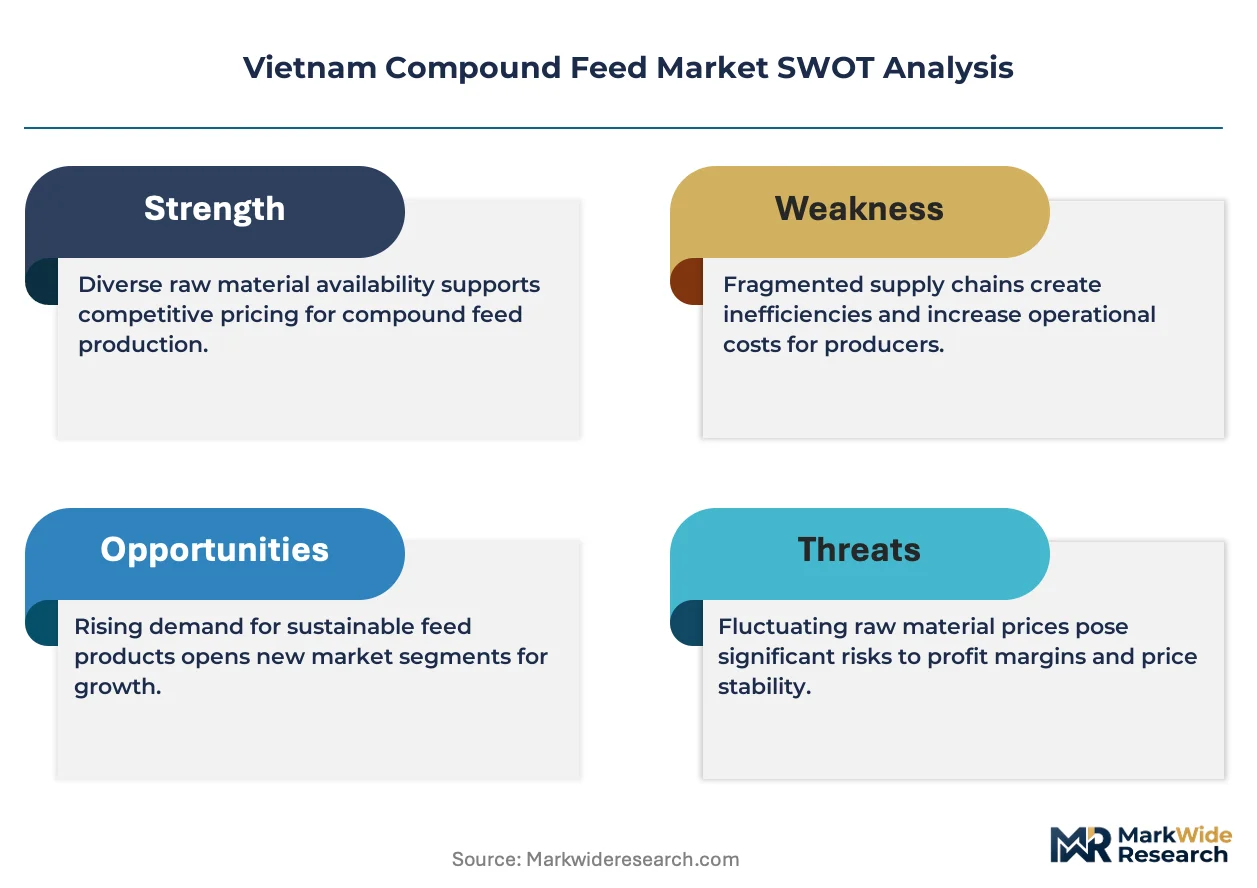
Premium-grade aquaculture feed formulations is redrawing competitive boundaries in Vietnam. Cargill Incorporated leverages its integrated supply chain across the Mekong Delta to secure raw material access. De Heus Company Limited anchors its position through specialized shrimp and pangasius nutrition programs. GreenFeed Group JSC differentiates via localized R&D facilities that adapt formulations to regional water chemistry.
Compound feed denotes industrially manufactured, nutritionally complete rations formulated from cereal grains, protein meals, additives, and vitamins to meet species-specific growth requirements, typically processed through extrusion or pelleting to achieve standardized pellet durability and digestibility coefficients. Poultry feed occupies the largest volume share as broiler integration scales in northern provinces. Aquaculture feed represents the fastest-expanding margin pool driven by pangasius and shrimp export quotas. Swine feed maintains structural importance despite African swine fever volatility affecting herd replenishment cycles.
Vietnam's Ministry of Agriculture and Rural Development enforces feed safety standards through mandatory GMP certification and periodic facility inspections, while the country's national standards body administers BIS-aligned quality benchmarks for imported premixes. MARD's antibiotic residue monitoring program restricts growth promoter usage, redirecting formulation investment toward enzyme and probiotic additives. Stakeholders must monitor evolving MEE environmental discharge rules for feed mill effluent as provincial authorities tighten watershed protections.
Market Dynamics
Vietnam's compound feed sector is restructuring around MARD's antibiotic residue monitoring program, which redirects formulation investment toward enzyme and probiotic additives while compressing margins for legacy growth promoter-dependent producers.
Growth Catalysts
- Intensive Aquaculture Expansion:Pangasius and shrimp export quotas drive specialized feed demand across Mekong Delta processing clusters. Commercial farms scale pellet consumption as integration deepens.
- MARD Feed Safety Certification:Mandatory GMP requirements accelerate facility upgrades and consolidate procurement toward certified suppliers, improving product standardization.
- Enzyme Additive Adoption:Phytase and carbohydrase formulations improve feed conversion ratios in poultry and swine operations, reducing input costs per kilogram of live weight.
Market Restraints
- Soybean Meal Import Dependence:Vietnam sources over 80 percent of protein meal requirements through international trade, exposing millers to currency volatility and supply disruptions.
- African Swine Fever Cyclicality:Herd replenishment volatility in swine operations creates demand instability that complicates production planning and inventory management.
- Watershed Protection Enforcement:Provincial authorities under MEE environmental discharge rules restrict feed mill effluent permits, raising compliance costs for Mekong Delta facilities.
Strategic Opportunities
- Central Highlands Poultry Integration:Broiler contract farming expansion in Dak Lak and Lam Dong provinces creates underpenetrated feed demand outside traditional northern strongholds.
- Probiotic Formulation Premiumization:MARD's antibiotic restrictions create white space for Bacillus-based and yeast-derived additive suppliers to capture margin from banned growth promoters.
- Direct Farm Distribution Networks:Bypassing traditional dealer channels through company-owned technical service teams improves formulation customization and locks in volume commitments.
Industry Challenges
- Feed Safety Auditor Scarcity:MARD's inspection capacity constraints delay GMP certification timelines, freezing market access for new mill entrants.
- Formulation Talent Migration:Specialized aquaculture nutritionists command premium compensation from integrated exporters, draining technical capacity from independent feed producers.
- Legacy Mill Retrofit Costs:Extrusion equipment upgrades required for floating aquafeed production demand capital outlays that strain mid-tier operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Compound Feed Market |
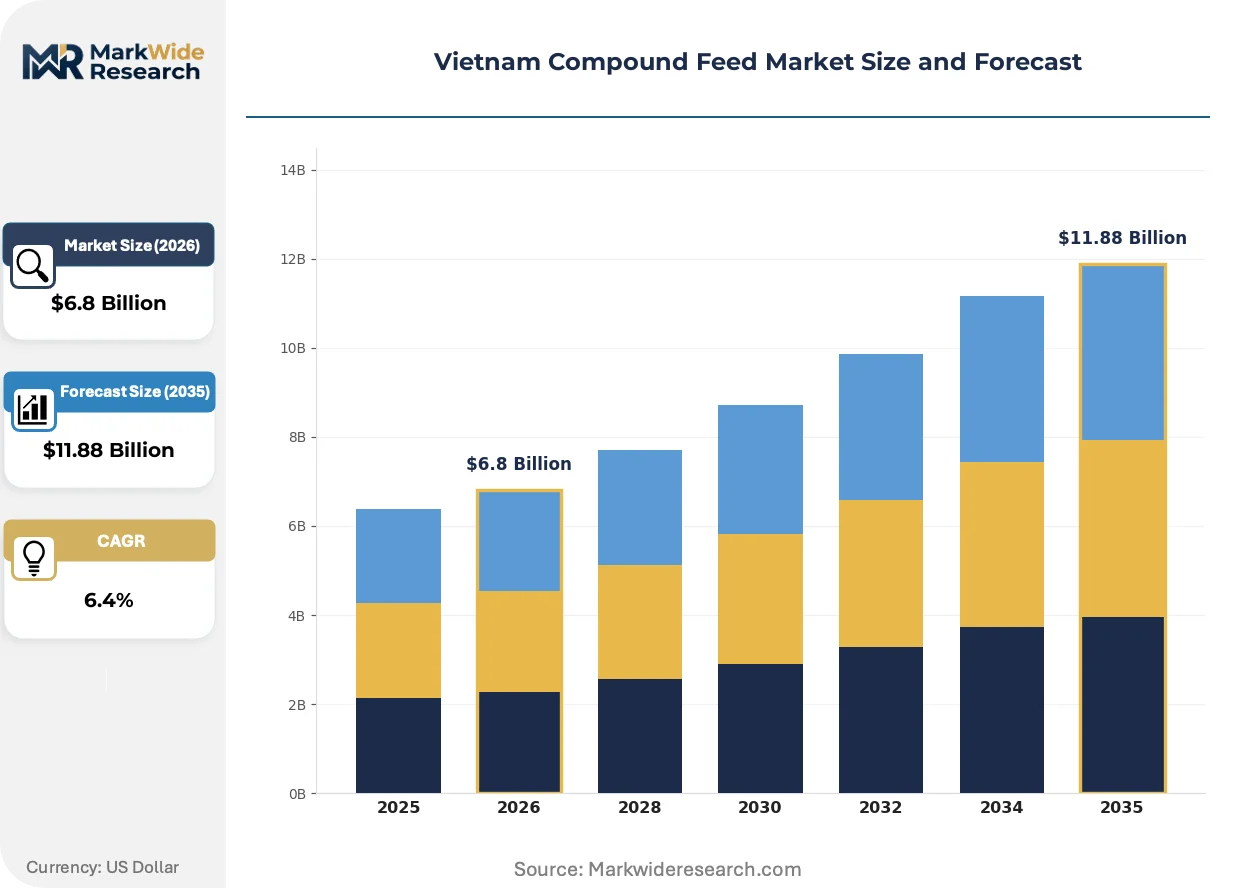
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Swine Feed, Ruminant Feed, Aquaculture Feed Ingredient Type: Cereal Grains, Protein Meals, Additives, Vitamins Distribution Channel: Retail Stores, Wholesalers, Online, Direct Sales End User: Farmers, Livestock Producers, Aquaculture Operations, Feed Manufacturers |
| Companies Covered | GreenFeed Group JSC, Alltech Inc., Cargill Incorporated, CJ CheilJedang Corp, Lai Thieu Feed Mill Co. Ltd, Charoen Pokphand Group Co., Ltd, Archer Daniels Midland Co., Emivest Feedmill Vietnam Co. Ltd., De Heus Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Compound Feed Market Evolving Landscape
Formulation science and regulatory compliance are converging to redefine competitive advantage in Vietnamese feed manufacturing, with additive portfolios and processing capabilities separating market tiers.
Extruded floating aquafeed is supplanting traditional sinking pellet formats in pangasius and shrimp operations. Mekong Delta intensive farms adopt the technology to monitor consumption rates and reduce bottom-water pollution. This shift compresses market share for legacy steam-pelleting equipment suppliers while expanding margins for extrusion-capable mills.
MARD's antibiotic residue monitoring program tightens enforcement of banned growth promoter lists across slaughterhouse sampling networks. Feed producers reformulate rations toward enzyme and organic acid additives to maintain performance metrics. Aquaculture and swine segments face the steepest compliance adjustments as export-oriented operations face EU and Japanese import testing protocols.
Commercial livestock producers consolidate procurement through annual volume contracts with technical service attachments. Dealer networks lose share as integrated poultry and aquaculture groups negotiate direct supply relationships with formulation guarantees. Northern provinces exhibit the fastest contract penetration as broiler integration accelerates beyond traditional Mekong Delta feed sourcing patterns.
Vietnam Compound Feed Market Segmentation
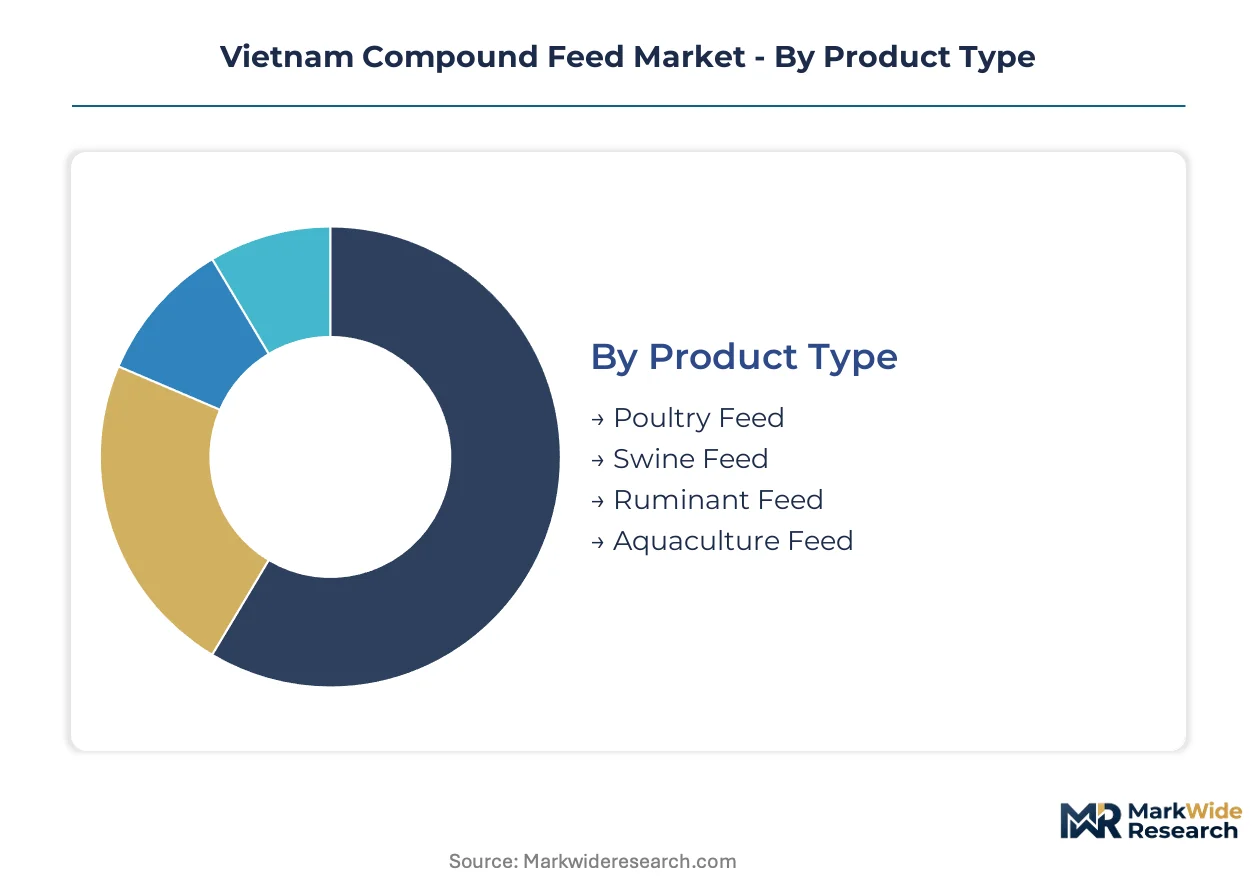
Segmentation in Vietnam's compound feed market reveals how procurement patterns diverge between export-oriented aquaculture clusters and domestic livestock operations. Understanding these divisions exposes where formulation premiums concentrate and which channels are consolidating volume.
Product Type:
Margin pools concentrate in species-specific formulations where export certification requirements create pricing power.
- Poultry Feed:Broiler and layer rations formulated with corn-soybean meal bases dominate northern province consumption. Dak Lak and Lam Dong integration projects are redirecting volume toward Central Highlands contract farming clusters.
- Aquaculture Feed:Extruded floating pellets for pangasius and shrimp carry the steepest formulation premiums. Mekong Delta processing clusters absorb the majority of output as export quota compliance demands specialized nutrition programs.
- Swine Feed:Sow, nursery, and finisher rations face demand instability from African swine fever herd cycles. MARD antibiotic restrictions are forcing reformulation toward enzyme-heavy additive packages.
- Ruminant Feed:Cattle and dairy rations remain underdeveloped outside specialized dairy cooperatives in Nghe An and Son La provinces. Low commercial integration limits pricing power for specialized formulations.
The dominant share belongs to Poultry Feed, while Aquaculture Feed is closing the gap fastest.
Ingredient Type:
Cost structures fragment between internationally traded commodities and domestically sourced inputs.
- Protein Meals:Soybean meal, fish meal, and alternative protein concentrates constitute the largest cost component. Over 80 percent dependency on imported soybean meal exposes millers to currency volatility and supply disruptions.
- Additives:Enzymes, probiotics, and organic acids are displacing banned growth promoters under MARD residue monitoring. Phytase and carbohydrase formulations command premium pricing as feed conversion ratio improvements justify higher inclusion rates.
- Cereal Grains:Corn and broken rice provide energy bases with significant domestic sourcing from Mekong Delta harvests. Local procurement reduces transport costs but seasonal availability creates formulation flexibility requirements.
- Vitamins:Premix concentrates are imported under BIS-aligned quality benchmarks administered by Vietnam's national standards body. Trace mineral and vitamin stability in tropical storage conditions drives specification premiums.
Additives capture expanding margin share as regulatory compliance reshapes formulation priorities, while Protein Meals remain the dominant cost center.
Distribution Channel:
Channel economics are inverting as technical service requirements override traditional dealer margins.
- Direct Sales:Company-owned technical teams deliver formulation guarantees and volume commitments to integrated poultry and aquaculture groups. Northern provinces exhibit the fastest contract penetration as broiler operations bypass dealer networks entirely.
- Wholesalers:Regional distributors retain relevance in fragmented swine and ruminant sectors where farm scale cannot justify direct supply relationships. Credit extension and inventory buffering sustain their intermediary position.
- Retail Stores:Provincial agricultural supply shops serve smallholder farmers with bagged feed and basic technical advice. Dealer margins compress as direct sales capture premium volume.
- Online:E-commerce platforms for feed inputs remain nascent, constrained by bulk logistics requirements and farmer preference for physical product inspection. Digital channels currently concentrate in veterinary pharmaceutical adjacencies.
Direct Sales commands the dominant volume position, while Online channels are expanding most quickly from a minimal base.
End User:
Customer sophistication determines pricing tolerance and technical service intensity.
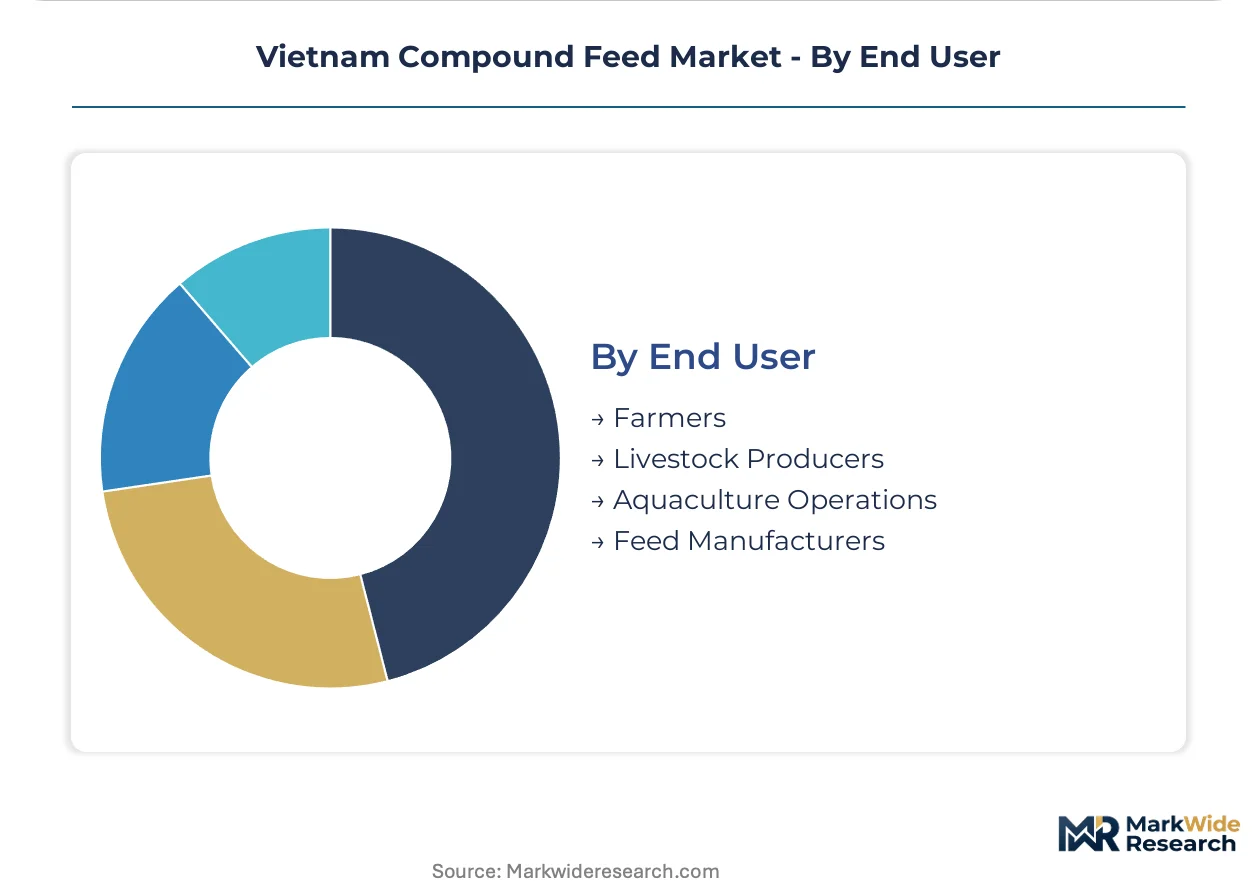
- Livestock Producers:Integrated broiler and layer operations in northern provinces negotiate annual contracts with formulation performance guarantees. Scale concentration enables direct procurement relationships that bypass traditional distribution.
- Aquaculture Operations:Pangasius and shrimp farms in Mekong Delta processing clusters demand species-specific extruded feeds with export certification documentation. EU and Japanese import testing protocols drive additive specification premiums.
- Farmers:Smallholder swine and poultry operations purchase through dealer networks with limited technical support. Price sensitivity dominates procurement decisions in this fragmented segment.
- Feed Manufacturers:Commercial mills purchasing premixes and base mixes for in-house formulation represent a specialized B2B channel. BIS-aligned quality benchmarks for imported inputs create compliance barriers for smaller operators.
Livestock Producers hold the dominant procurement volume, while Aquaculture Operations are gaining share fastest through export quota expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese compound feed exports flow primarily toward EU and Japanese seafood importers, with domestic consumption patterns diverging sharply between Mekong Delta aquaculture clusters and northern livestock integration zones.
Mekong Delta
Pangasius and shrimp export quotas drive specialized aquafeed demand across Can Tho and An Giang provinces. MARD's antibiotic residue monitoring program enforces strict additive compliance for EU-bound shipments. Floating extruded pellet production concentrates in Long Xuyen and Chau Doc processing corridors as farms upgrade from sinking formats.
Northern Region
Broiler contract farming expansion in Hung Yen and Bac Ninh provinces consumes corn-soybean based poultry rations. Provincial agricultural departments enforce GMP certification timelines that delay new mill market entry. Bac Giang and Hai Duong industrial zones host the densest concentration of integrated layer operations.
Central Highlands
Dak Lak and Lam Dong provinces emerge as underpenetrated poultry feed markets as contract farming displaces traditional smallholder structures. MARD feed safety mandates apply uniformly but auditor scarcity extends certification delays. Buon Ma Thuot and Da Lat agricultural corridors attract direct sales technical teams bypassing dealer networks.
South Central Coast
Shrimp hatchery density in Khanh Hoa and Phu Yen provinces generates specialized larval feed demand distinct from grow-out formulations. Provincial MEE offices tighten watershed discharge permits for coastal feed mill effluent. Nha Trang and Tuy Hoa processing clusters face capacity constraints during peak stocking seasons.
Red River Delta
Swine herd replenishment cycles in Thai Binh and Nam Dinh provinces create volatile feed demand following African swine fever disruptions. MARD's GMP inspection capacity prioritizes larger facilities, freezing smaller mill upgrades. Thai Binh City feed trading hubs retain relevance for fragmented farmer procurement.
Vietnam Compound Feed Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with multinational agribusinesses holding integrated supply chain advantages against domestic formulators. Market structure tilts toward consolidation as MARD's mandatory GMP requirements raise capital barriers for mid-tier operators. Three archetypes dominate: multinational integrated traders, regional Asian specialists, and domestic R&D-focused formulators. Capacity expansion and backward integration into raw material sourcing represent the primary competitive vectors.
Among multinational integrated players, Cargill Incorporated and Archer Daniels Midland Co. exemplify supply chain control strategies. De Heus Company Limited and CJ CheilJedang Corp occupy positions as Asian regional specialists with species-specific nutrition programs. GreenFeed Group JSC anchors the domestic tier through localized formulation adaptation.
| Leading Market Players |
|---|
| GreenFeed Group JSC |
| Alltech Inc. |
| Cargill Incorporated |
| CJ CheilJedang Corp |
| Lai Thieu Feed Mill Co. Ltd |
| Charoen Pokphand Group Co., Ltd |
| Archer Daniels Midland Co. |
| Emivest Feedmill Vietnam Co. Ltd. |
| De Heus Company Limited |
| Others |
Value Network & Pricing Analysis
Annual volume contracts with technical service attachments lock in both soybean meal supply access and six-month price visibility for integrated Mekong Delta aquaculture groups. This contracting pattern compresses spot market liquidity while concentrating procurement leverage among certified mill operators.
Pricing Analysis
Extrusion-capable versus steam-pelleting equipment generations command divergent pricing power in pangasius and shrimp feed. Three-tier pricing structure across export-certified premium, domestic-standard, and smallholder-economy levels stratifies by MARD GMP certification grade and volume scale. Pricing pressure stems from enzyme additive cost inflation as phytase inclusion rates rise under antibiotic restrictions. Smallholder farmers through dealer networks exhibit highest price sensitivity, while integrated exporters tolerate premium tiers for EU compliance documentation.
Supply Chain Analysis
Port congestion at Ho Chi Minh City and Cai Mep terminals elevates inbound logistics costs for Argentine and Brazilian soybean meal shipments. Vietnam's protein meal requirements draw from Argentina, Brazil, and the United States, with corn energy bases sourcing domestically from Mekong Delta harvests. Single-source vulnerability concentrates in fish meal from Peruvian anchovy fisheries. Distribution runs through direct sales technical teams to integrated poultry and aquaculture groups, bypassing traditional dealer margins in northern provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's compound feed sector sits in early-cycle expansion as MARD's GMP certification mandates force facility consolidation and redirect procurement toward certified suppliers. This regulatory tailwind accelerates penetration of formal feed channels across fragmented smallholder structures.
For Market Incumbents: Consolidate procurement relationships through captive supply of extrusion equipment and backward integration into Mekong Delta corn origination. Cargill and De Heus should expand technical service teams in Central Highlands poultry clusters before regional Asian specialists establish formulation adaptation facilities. Threat from domestic R&D-focused formulators like GreenFeed intensifies as localized water-chemistry adaptation commands premium pricing. For New Entrants and Emerging Players: MARD GMP certification fast-track programs offer market entry acceleration for mid-tier operators willing to pre-invest in auditor relationships. White-space targets concentrate in Central Highlands broiler contract farming and probiotic additive formulation for antibiotic-restricted swine operations. Go-to-market angle should emphasize direct farm distribution with embedded technical service rather than dealer network penetration. For Investors and Strategic Acquirers: Regional Asian specialists with species-specific nutrition programs represent the priority acquisition archetype for multinational agribusinesses seeking Mekong Delta aquafeed positioning. Long-term viability frames around export quota expansion and watershed protection enforcement tightening mill permits. Signal to watch is MEE environmental discharge rule provincial implementation timelines, which will freeze sub-scale capacity and accelerate consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Extrusion Equipment Upgrade | Floating aquafeed capability captures pangasius export quota premiums under EU antibiotic protocols. |
| Enzyme Additive Partnership | Phytase and carbohydrase supply agreements secure formulation performance as MARD restricts growth promoters. |
| Direct Farm Distribution Network | Company-owned technical teams in Central Highlands bypass dealer margins and lock volume commitments. |
| Backward Integration into Corn Origination | Mekong Delta harvest procurement reduces currency exposure from imported soybean meal dependency. |
| Probiotic Formulation R&D Investment | Bacillus-based additive development captures margin from banned antibiotic growth promoters in swine and poultry. |
Research Methodology
Initial hypotheses were tested against primary input from feed mill operations managers, MARD certification auditors, aquaculture farm technical directors, and integrated poultry procurement leads, then refined through secondary validation. Secondary sources included MARD GMP facility inspection records, Vietnam's national standards body premix import registrations, Mekong Delta provincial agricultural department statistics, and customs trade data on soybean meal arrivals. Bottom-up volume modeling from individual facility capacities triangulated against top-down consumption estimates from livestock and aquaculture production statistics.
Variance decomposition across product type, ingredient composition, distribution channel, and regional demand cluster informed the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate assumptions calibrated to MARD policy implementation timelines and export quota expansion trajectories. Industry-specific inputs incorporated African swine fever herd replenishment cycles and MEE watershed protection enforcement intensity by province.
Decision-makers should treat outputs as directional under assumptions of continued MARD certification mandate enforcement and stable Mekong Delta aquaculture export growth; material deviation in regulatory timelines or disease recurrence would warrant model refresh. Practitioners should keep alternative scenarios live as MEE environmental discharge permitting and EU import testing protocol evolution reshape facility compliance costs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
Feed Yeast Market
Agricultural Commodities
Alfalfa Powder Market
Agricultural Commodities
Growing Peat Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Africa Feed Amino Acids Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Sod Peat Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Premix Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Bladderpod Oil Market
Agricultural Commodities
Blood Meal Market
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
North America Corn Glucose Market
Agricultural Commodities
Global Seed Cotton Market