
 Aquaculture Feed and Pharmaceuticals Market | 2026-2036
Aquaculture Feed and Pharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Aquaculture Feed and Pharmaceuticals Market Analysis
Aquaculture nutritionists with marine biotechnology training is bifurcating the talent pipeline between commodity feed operations and precision pharmaceutical developers. Skretting leverages its integrated marine research stations to dominate Atlantic salmon nutrition systems. Zoetis anchors its competitive position through specialized vaccine development for warm-water species. Cargill sustains manufacturing scale across multiple coastal geographies through backward integration into raw material sourcing.
Aquaculture feed and pharmaceuticals encompass formulated diets, medicated premixes, vaccines, and water treatment agents designed to optimize growth rates, immune response, and survival in farmed aquatic species; formulations typically specify protein content between 32-55%, lipid profiles tailored to species metabolic requirements, and active pharmaceutical ingredients delivered through medicated feeds or immersion baths. Therapeutics and vaccines capture concentrated margin pools as disease outbreaks intensify biosecurity spending across fish farms and shellfish farms. Feed additives occupy the largest volume position but face margin compression from substitute ingredients like insect meal and single-cell proteins. Nutritional supplements for broodstock and larval stages represent the fastest-growing application segment as hatcheries professionalize their protocols.
The EU F-Gas Regulation and REACH framework constrain refrigerant choices in pharmaceutical cold chains while EMA veterinary guidelines dictate withdrawal periods for medicated feeds across European aquaculture operations. FDA Center for Veterinary Medicine oversight in the United States shapes approval pathways for new aquatic animal drugs, creating multi-year development timelines that favor established players with regulatory affairs capacity. Stakeholders must monitor evolving residue testing protocols and antimicrobial resistance policies to anticipate which product categories will retain market access.
Market Dynamics
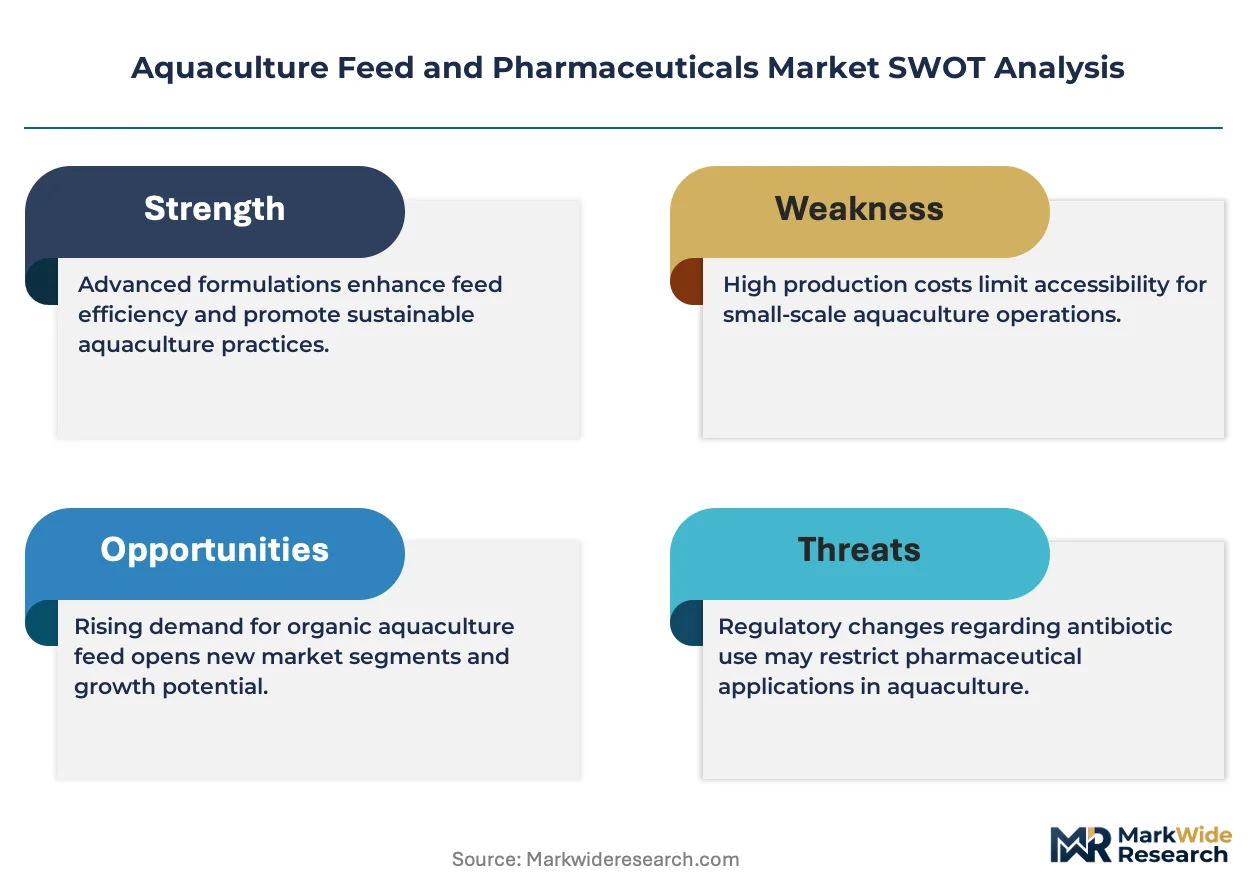
The EU F-Gas Regulation is forcing pharmaceutical cold-chain operators toward alternative refrigerants, while insect meal substitution is decomposing traditional fishmeal pricing power in feed formulations.
Growth Catalysts
- Shrimp Farming Intensification:Southeast Asian producers are expanding pond density, driving concentrated demand for specialized feed additives and water treatment agents.
- REACH Framework Compliance:European pharmaceutical manufacturers are investing in residue-testing infrastructure to meet withdrawal-period mandates for medicated feeds.
- Single-Cell Protein Commercialization:Norwegian salmon operations are integrating microbial biomass into nutritional formulations to reduce marine ingredient dependency.
Market Restraints
- Fishmeal Supply Concentration:Peruvian anchovy catch volatility creates raw material cost instability for premium feed producers.
- Antimicrobial Resistance Policies:FDA Center for Veterinary Medicine restrictions on prophylactic antibiotic use in medicated feeds limit therapeutic options.
- Technical Substitution Limits:Insect meal protein digestibility remains inferior to marine sources for larval-stage nutrition, constraining formulation flexibility.
Strategic Opportunities
- Brazilian Tilapia Expansion:ANVISA regulatory harmonization with international standards is opening pharmaceutical access to Latin America's largest warm-water species producer.
- Recirculating Aquaculture Systems:Land-based salmon facilities in Maine and Florida require precision water treatment agents and specialized broodstock nutrition.
- CSRD Reporting Mandates:European feed manufacturers capturing Scope 3 emissions data gain procurement preference from ESG-committed retailers.
Industry Challenges
- Marine Biotechnology Talent Scarcity:Hatchery operations struggle to recruit nutritionists with dual competency in aquaculture physiology and pharmaceutical formulation science.
- Multi-Year Approval Timelines:FDA aquatic animal drug pathways demand sustained regulatory affairs investment that mid-scale developers cannot sustain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquaculture Feed and Pharmaceuticals Market |
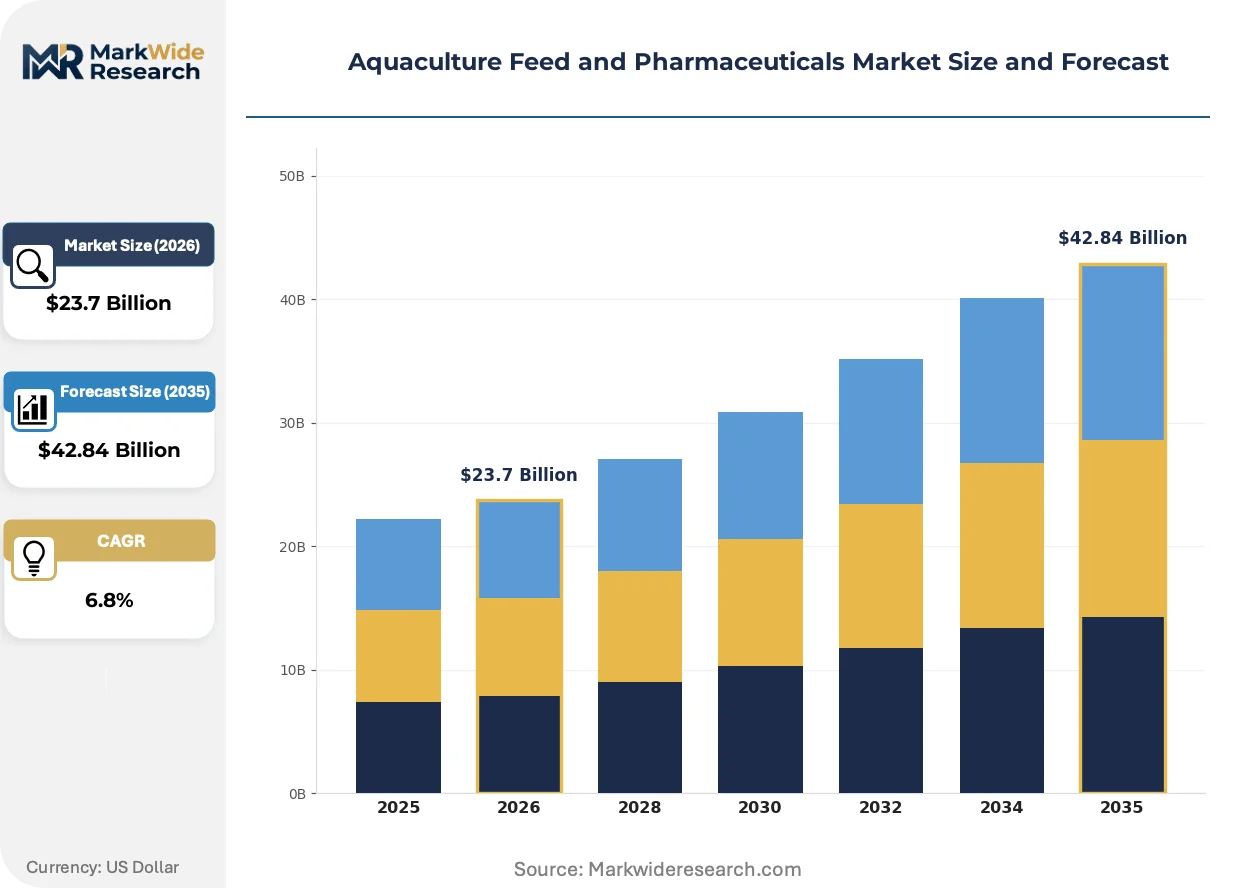
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feed Additives, Therapeutics, Vaccines, Nutritional Supplements End User: Fish Farms, Shellfish Farms, Aquaculture Companies, Research Institutions Distribution Channel: Direct Sales, E-Commerce, Distributors, Retail Stores Application: Growth Promotion, Health Management, Disease Prevention, Nutritional Support |
| Companies Covered | Skretting, Zoetis, Cargill, Alltech, Biomin Holding, Nutreco, Ridley Corporation, Evonik, BioMar Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquaculture Feed and Pharmaceuticals Market Emerging Trajectories
Precision nutrition systems and alternative protein platforms are fragmenting the commodity feed model, while biosecurity automation and cold-chain monitoring reshape pharmaceutical distribution requirements.
Single-cell protein fermentation is decomposing the marine ingredient lock-in that has structured feed economics for decades. Atlantic salmon integrators in Norway are scaling commercial trials of microbial biomass at feed inclusion rates exceeding 15%. This biotechnology is compressing the premium pricing power historically attached to fishmeal and fish oil concentrates.
EMA veterinary guidelines on antimicrobial resistance are tightening residue surveillance across European aquaculture operations. Feed mills must now document withdrawal periods through blockchain-traceable batch records. Norwegian and Scottish salmon producers face the steepest compliance costs, driving consolidation toward vertically integrated operators with captive laboratory testing capacity.
Buyer concentration among retail-certified salmon brands is fragmenting procurement across multiple feed suppliers. Norwegian supermarket chains now require third-party ASC certification for all sourced aquaculture products, forcing feed manufacturers to reformulate around prohibited ingredient lists. This certification-driven preference shift is most visible in Bergen and Oslo procurement offices, where sustainability scorecards override historical supplier relationships.
Aquaculture Feed and Pharmaceuticals Market Segmentation
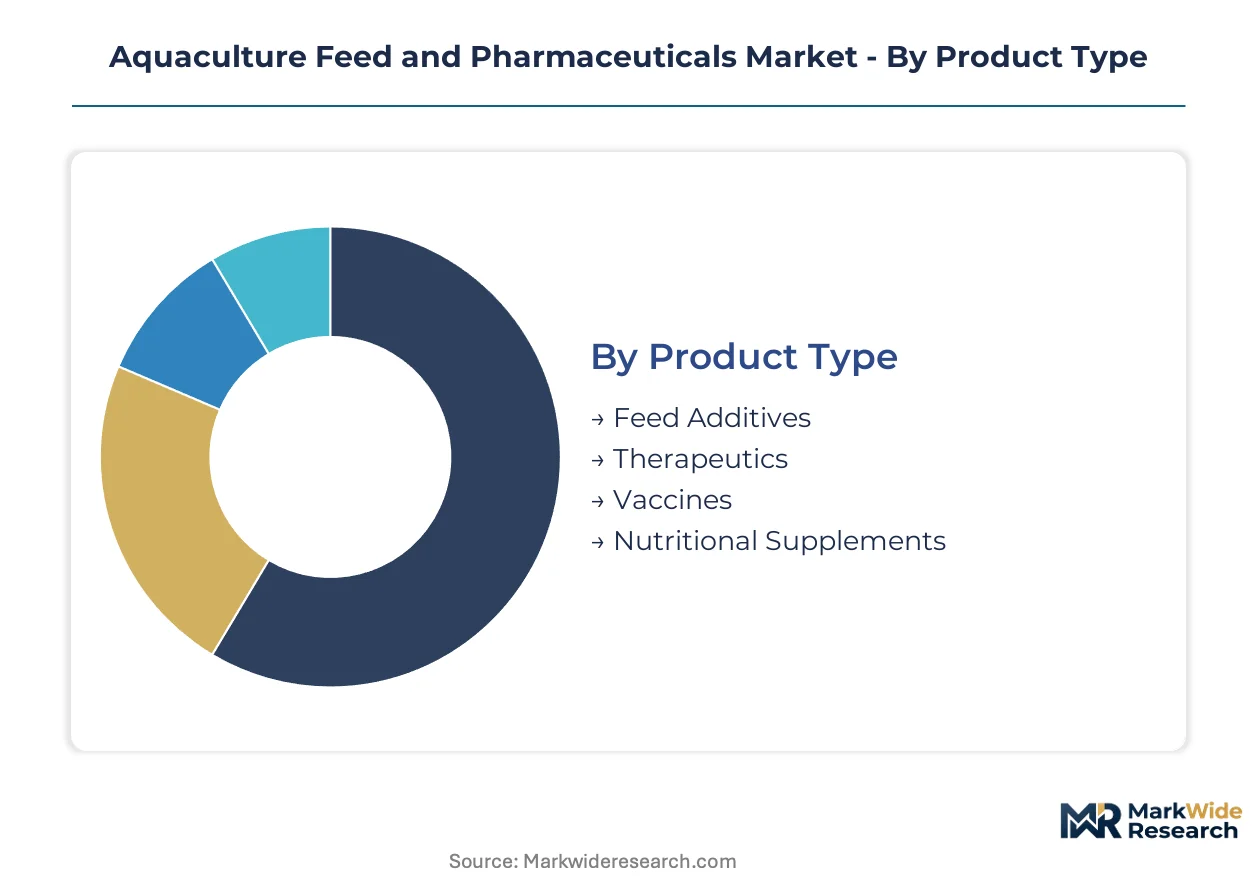
Segment boundaries in aquaculture nutrition are eroding as feed mills add pharmaceutical-grade manufacturing lines and vaccine producers acquire formulation capabilities. Procurement managers now source across traditional category lines, forcing suppliers to bundle additives with therapeutics.
Product Type:
Feed Additives face the most intense substitution pressure from insect meal and single-cell proteins, while Vaccines enjoy protected margins through biological manufacturing complexity.
- Feed Additives:Enzyme premixes, acidifiers, and binders formulated at inclusion rates between 0.5-5% to improve digestibility and pellet stability. Norwegian salmon integrators in Bergen and Trondheim are the dominant buyers, though they are cutting inclusion rates as microbial biomass substitutes gain traction.
- Therapeutics:Medicated feeds and immersion treatments containing antimicrobials or antiparasitic agents subject to FDA Center for Veterinary Medicine withdrawal periods. Demand concentrates in Vietnamese shrimp ponds and Indonesian tilapia cages where bacterial disease pressure exceeds biosecurity infrastructure.
- Vaccines:Inactivated and live-attenuated biological products for viral and bacterial pathogens.
- Nutritional Supplements:Broodstock and larval-stage formulations with elevated fatty acid profiles.
Feed Additives retains volume leadership; Nutritional Supplements holds the steepest expansion curve.
End User:
Customer scale determines procurement sophistication, with large integrators demanding formulation customization that commodity producers cannot supply.
- Fish Farms:Atlantic salmon cage operations in Norway, Chile, and Scotland generating concentrated demand for precision nutrition systems. Scottish producers near Shetland and Orkney are upgrading to automated feeding platforms that integrate real-time biomass sensors with feed delivery.
- Shellfish Farms:Oyster and mussel operations requiring algal concentrates and water treatment protocols rather than pelleted feeds. French Marennes-Oléron and Dutch Zeeland producers dominate European procurement for larval nutrition and depuration systems.
- Aquaculture Companies:Vertically integrated enterprises controlling hatchery through processing operations.
- Research Institutions:Universities and government laboratories conducting trials on alternative ingredients.
Fish Farms command the largest absolute spend; Shellfish Farms is climbing fastest as bivalve production scales.
Distribution Channel:
Channel selection tracks customer technical capability, with sophisticated buyers bypassing intermediaries while smaller farms rely on local stocking points.
- Direct Sales:Manufacturer-to-farm relationships for large-volume contracts with technical service requirements. Cargill and Skretting deploy nutritionists directly to Norwegian and Chilean salmon sites to adjust formulations based on seasonal performance data.
- Distributors:Regional wholesalers holding inventory for immediate delivery to smaller operations. Vietnamese Mekong Delta and Thai Samut Sakhon distributors dominate shrimp feed logistics, though cold-chain vaccines remain manufacturer-controlled.
- E-Commerce:Digital procurement platforms for standardized additives and equipment.
- Retail Stores:Point-of-sale availability for hobbyist and small-scale producers.
Direct Sales captures the premium tier; E-Commerce is expanding most quickly as farm management software integrates procurement modules.
Application:
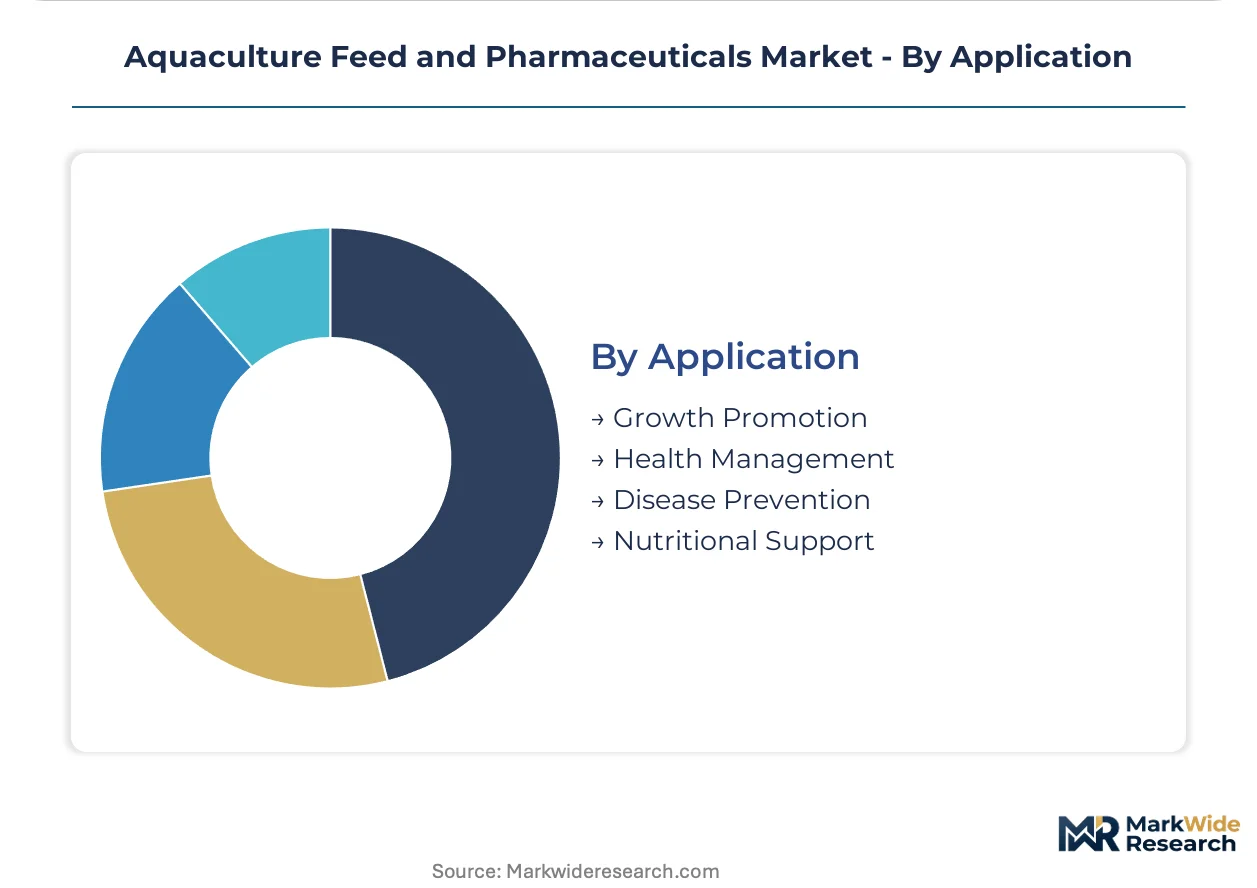
Application focus shifts with disease pressure cycles, with producers alternating between growth optimization and emergency health interventions.
- Health Management:Integrated disease monitoring and treatment protocols combining diagnostics, therapeutics, and recovery nutrition. Scottish and Norwegian salmon producers are investing in PCR-based pathogen surveillance that triggers preemptive feed adjustments before clinical outbreaks.
- Disease Prevention:Vaccination programs and prophylactic nutrition designed to reduce infection risk. Chilean salmon farms in Los Lagos and Aysén are expanding autogenous vaccine use against Piscirickettsia salmonis as commercial products show strain mismatch.
- Growth Promotion:Feed formulations maximizing feed conversion ratio and harvest weight.
- Nutritional Support:Stress recovery and broodstock conditioning protocols.
Growth Promotion retains the largest installed base; Health Management is gaining share fastest as biosecurity spending displaces reactive treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian salmon integrators command premium pricing power for precision nutrition systems, while Vietnamese shrimp operations compete on feed conversion efficiency at compressed margins. This asymmetry structures procurement sophistication across the value chain.
Norway
Atlantic salmon cage operations in Bergen and Trondheim drive demand for automated feeding platforms with real-time biomass sensors. The Norwegian Food Safety Authority enforces strict withdrawal periods for medicated feeds under EMA veterinary guidelines. Producers near Shetland and Orkney are upgrading PCR-based pathogen surveillance systems.
Vietnam
Mekong Delta shrimp pond intensification creates concentrated demand for specialized feed additives and water treatment agents. The country's national agricultural regulator monitors residue compliance for export-bound aquaculture products. Distributors in Cần Thơ and An Giang dominate cold-chain logistics for temperature-sensitive vaccines.
United States
Land-based recirculating aquaculture systems in Maine and Florida require precision water treatment agents and specialized broodstock nutrition. FDA Center for Veterinary Medicine oversight shapes multi-year approval pathways for new aquatic animal drugs. Operators near Portland and Miami are piloting closed-containment salmon facilities.
Chile
Los Lagos and Aysén salmon farms expand autogenous vaccine use against Piscirickettsia salmonis as commercial products show strain mismatch. The national fisheries service regulates antimicrobial use under international trade compliance protocols. Processing clusters near Puerto Montt integrate backward into hatchery feed formulation.
Indonesia
Java Sea tilapia cage operations generate demand for bacterial disease therapeutics where biosecurity infrastructure lags disease pressure. The national pharmaceutical regulator harmonizes with ASEAN standards for veterinary product registration. Surabaya-based distributors control procurement channels for smaller pond operators.
Aquaculture Feed and Pharmaceuticals Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Vertically integrated nutrition systems specialists compete against commodity-scale feed manufacturers with captive raw material sourcing. Three archetypes dominate: precision formulation developers with marine research stations, diversified agribusiness conglomerates with multi-coastal manufacturing footprints, and biological product specialists with vaccine manufacturing complexity. Consolidation pressures favor M&A activity between feed mills and pharmaceutical-grade manufacturing lines, while strategic partnerships link alternative protein developers with salmon integrators.
Within the integrated nutrition tier, Skretting and Nutreco exemplify archetypes combining marine biotechnology research with captive supply networks. Cargill anchors the scale-driven segment with backward integration into raw material sourcing across multiple coastal geographies. Zoetis occupies a distinct position representing biological manufacturing specialists focused on warm-water species vaccine development.
| Leading Market Players |
|---|
| Skretting |
| Zoetis |
| Cargill |
| Alltech |
| Biomin Holding |
| Nutreco |
| Ridley Corporation |
| Evonik |
| BioMar Group |
| Others |
Supply Flow & Price Mechanics
ASC certification gates both supplier qualification and price differentiation simultaneously, forcing feed manufacturers to absorb reformulation costs while Norwegian retailers award procurement preference to certified producers in Bergen and Oslo. This sustainability-driven segmentation splits the market between premium precision nutrition systems and commodity formulations facing margin compression from alternative protein substitution.
Pricing Analysis
Customization-premium spreads separate configured-to-order precision nutrition from standard commodity feeds. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with Norwegian salmon integrators commanding the widest spreads through ASC-compliant sourcing. Pricing pressure stems from single-cell protein and insect meal substitution eroding fishmeal-based premium positioning. Small-scale Vietnamese shrimp farms exhibit the highest price sensitivity, while Norwegian Atlantic salmon cage operations prioritize performance metrics over unit cost.
Supply Chain Analysis
Peruvian anchovy catch volatility creates a chokepoint that underwrites raw material cost instability for premium marine ingredient formulations. Supply concentrates in Peru, Norway, and Vietnam for fishmeal, precision nutrition systems, and shrimp feed additives respectively. Formulations draw from marine proteins, microbial biomass, and insect meal as substitute inputs. Single-source vulnerability in Peruvian fisheries exposes producers to El Niño-driven harvest disruptions. Distribution runs through direct manufacturer-to-farm relationships for large integrators and regional distributors for smaller operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-cell protein commercialization is disrupting decades of marine ingredient lock-in, creating acceleration windows for biotechnology-enabled entrants and consolidation pressure on legacy feed economics.
For Market Incumbents: Secure captive laboratory testing capacity to meet EMA veterinary guideline compliance costs that are consolidating Norwegian and Scottish salmon production toward vertically integrated operators. Defend formulation customization advantages by embedding nutritionists directly at farm sites with real-time biomass sensor integration. Counter microbial biomass substitution through backward integration into fermentation capacity and exclusive offtake agreements with alternative protein developers. For New Entrants and Emerging Players: Technical service gaps in Vietnamese Mekong Delta shrimp pond operations expose white-space for specialized water treatment and disease diagnostic bundling. Target Indonesian tilapia cage systems where bacterial disease pressure exceeds incumbent biosecurity infrastructure penetration. Penetrate through precision health management subscriptions that integrate PCR-based pathogen surveillance with preemptive feed adjustment protocols. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates seeking to divest non-core aquaculture feed assets amid alternative protein transition costs. Long-term viability favors biological manufacturing specialists with vaccine complexity moats and precision nutrition developers with captive marine research stations. Monitor FDA Center for Veterinary Medicine approval velocity as the signal indicating whether multi-year development timelines will favor established regulatory affairs capacity or create openings for agile entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternative Protein Supply | Cargill's raw material sourcing networks now extend to microbial biomass fermentation partnerships with Norwegian salmon integrators. |
| Regulatory Affairs Capacity Expansion | Zoetis anchors competitive positioning through specialized FDA aquatic animal drug pathway expertise for warm-water species vaccines. |
| Precision Health Management Platform Launch | Scottish producers near Shetland deploy PCR-based pathogen surveillance triggering preemptive feed adjustments before clinical outbreaks. |
| ASC Certification-Driven Reformulation | Skretting reformulates around prohibited ingredient lists to maintain procurement access with Oslo and Bergen supermarket chains. |
| Geographic Manufacturing Footprint Expansion | BioMar Group scales Brazilian tilapia feed production following ANVISA regulatory harmonization with international standards. |
Methodological Framework
Two parallel data streams informed the analysis: structured interviews with aquaculture nutritionists, hatchery operations managers, pharmaceutical regulatory affairs leads, and cold-chain logistics coordinators; and secondary validation through FDA Center for Veterinary Medicine filings, EMA veterinary guideline documentation, customs trade data on fishmeal and fish oil concentrates, and ASC certification registry records. Bottom-up demand modeling across species-specific feed conversion ratios triangulated against top-down market sizing from manufacturer production disclosures.
Across the analysis window, the forecasting framework modeled product type segmentation, end user scale tiers, distribution channel sophistication levels, and application focus shifts between growth promotion and health management. CAGRs derived from weighted average growth trajectories across Norwegian salmon integrators, Vietnamese shrimp intensification, and Brazilian tilapia expansion. Industry-specific inputs incorporated single-cell protein inclusion rate trials, autogenous vaccine adoption curves in Chilean Los Lagos operations, and ESG-linked procurement preference elasticity among European retailers.
Underlying assumptions cover sustained regulatory enforcement of antimicrobial resistance policies and continued alternative protein cost parity achievement, with deviation risk concentrated in Peruvian anchovy harvest volatility and FDA approval timeline extensions. Practitioners should keep alternative scenarios live as EU F-Gas Regulation compliance costs and CSRD reporting mandate adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Healthcare Market
Aquaculture Innovations
Marine Life Raft Market
Aquaculture Innovations
Clams, Cockles, Ark Shells Market
Aquaculture Innovations
Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems (RAS) Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
Aquaculture UAE in Market
Aquaculture Innovations
Aquaculture Cage Market
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Microalgae-Based Aquafeed Market
Aquaculture Innovations
Global Aquafeed Market
Aquaculture Innovations
Bacterial Diagnostics in Aquaculture Market
Aquaculture Innovations
Qatar Fisheries and Aquaculture Market
Aquaculture Innovations
Global Plant Based Fish Feed Market
Aquaculture Innovations
Europe Organic Aquaculture Market
Aquaculture Innovations
Japan Aquafeed Market
Aquaculture Innovations
Sandfish Market