
 North America Corn Glucose Market | 2026-2036
North America Corn Glucose Market Size, Share, and Industry Trends Forecast 2026-2036
North America Corn Glucose Market Intelligence
Food processing chemist shortages across the Midwest are redrawing competitive boundaries for glucose refiners. Cargill leverages its captive corn supply and wet-milling infrastructure to dominate bulk liquid glucose production. Archer Daniels Midland anchors its position through integrated ethanol-to-syrup flexibility and extensive Midwest processing capacity. Ingredion Incorporated differentiates via specialty glucose derivatives targeting pharmaceutical-grade specifications.
Corn glucose is a refined carbohydrate syrup derived from corn starch hydrolysis, typically containing 20-47 percent glucose solids with dextrose equivalence ranging from 20 to 100 depending on enzymatic conversion depth; manufacturers deploy acid-enzyme or dual-enzyme processes to control sweetness, viscosity, and browning reactions for targeted industrial applications. Liquid glucose commands the largest volume share among product types due to its ubiquity in soft drink formulations and industrial baking, while high fructose corn syrup faces structural headwinds from sugar-reduction mandates across beverage applications. Pharmaceutical and nutraceutical end users represent the fastest-expanding demand pool as glucose serves as a tablet binder, fermentation substrate, and excipient in parenteral solutions.
The FDA governs corn glucose labeling under 21 CFR regulations for sweeteners and carbohydrate ingredients, while the USDA oversees biobased procurement preferences that steer federal food purchasing toward domestically processed corn derivatives. Health Canada and the PMRA coordinate cross-border standards for glucose used in pharmaceutical manufacturing, creating compliance harmonization pressures for integrated North American suppliers. Stakeholders must monitor evolving added-sugar disclosure rules and bioprocessing tax credits that could reshape capital allocation between commodity and specialty glucose lines.
Market Dynamics
The FDA's updated nutrition labeling requirements are compressing beverage formulation timelines, forcing manufacturers to accelerate clean-label reformulations using modified corn syrups with reduced dextrose equivalence profiles.
Growth Catalysts
- Clean-label mandates:The FDA's added-sugar disclosure rules are pulling beverage manufacturers toward glucose syrups that deliver sweetness with lower perceived sugar content on nutrition panels.
- Pharmaceutical excipient demand:Tablet binders and parenteral solutions in the United States are expanding procurement of pharmaceutical-grade glucose derivatives with tight dextrose equivalence tolerances.
- Biobased procurement preferences:USDA federal purchasing guidelines are steering institutional food service toward domestically processed corn derivatives, reinforcing Midwest processing clusters.
Market Restraints
- Input cost volatility:Corn price swings tied to Iowa and Illinois harvest yields transmit directly into glucose refiner margins, compressing pricing flexibility.
- Substitution pressure:Tapioca-derived glucose syrups are gaining traction in premium clean-label applications, threatening corn-based volume in high-margin segments.
- Supply concentration risk:Wet-milling infrastructure clusters in the U.S. Midwest create geographic vulnerability to regional weather disruptions and logistics bottlenecks.
Strategic Opportunities
- Canadian pharmaceutical expansion:Health Canada and PMRA harmonization pressures are creating integrated North American supply opportunities for pharmaceutical-grade glucose specifications.
- Bioprocessing tax credits:The IRA's clean energy manufacturing incentives could redirect capital toward enzymatic conversion efficiency upgrades in existing Midwest facilities.
- Fermentation substrate demand:Cell-culture media and precision fermentation applications in biopharma represent emerging volume pools for high-purity glucose derivatives.
Industry Challenges
- Food processing chemist scarcity:Wet-milling and enzymatic conversion expertise shortages across Iowa, Illinois, and Nebraska are constraining operational scaling and process optimization.
- Dual-jurisdiction compliance complexity:Simultaneous FDA 21 CFR and Health Canada PMRA qualification requirements are extending product launch timelines for cross-border pharmaceutical suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Corn Glucose Market |
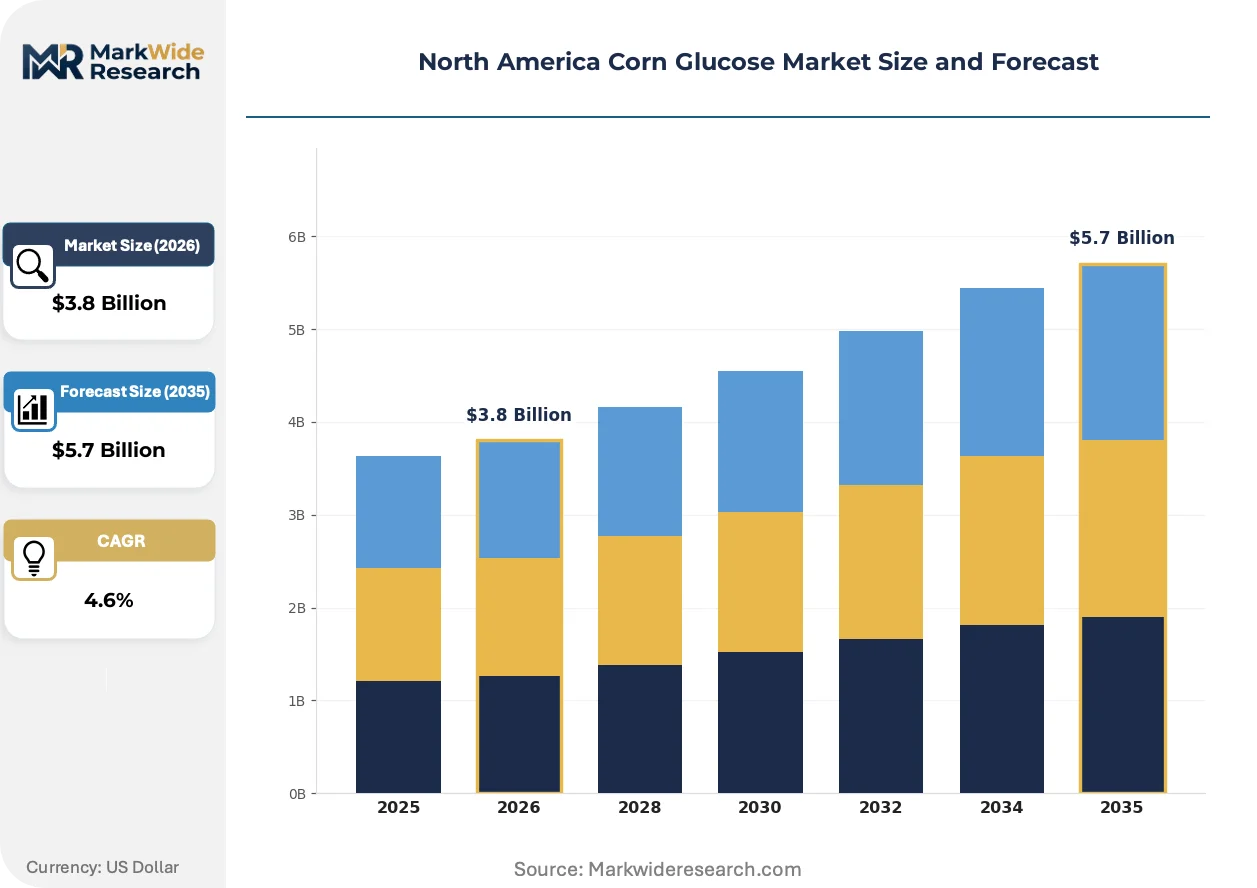
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Glucose, Powdered Glucose, High Fructose Corn Syrup, Corn Syrup Application: Beverages, Bakery Products, Dairy, Confectionery Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores End User: Food Manufacturers, Beverage Companies, Pharmaceutical Firms, Nutraceuticals |
| Companies Covered | Tate & Lyle, Grain Processing, Cargill, Sweetener Products, Corn Refiners Association, Archer Daniels Midland, Roquette, SC Foods, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Corn Glucose Market Strategic Shifts & Innovations
Enzymatic process control technologies are reshaping competitive boundaries between commodity bulk producers and specialty derivative manufacturers across North American glucose refining.
Dual-enzyme hydrolysis systems with real-time dextrose equivalence monitoring are supplanting traditional acid-enzyme batch processes in mid-scale refineries. Beverage manufacturers in the United States are adopting these systems to hit precise sweetness targets with reduced batch-to-batch variation. This technology is compressing the cost gap between commodity liquid glucose and premium specialty derivatives.
The FDA's updated Nutrition Facts label requirements for added-sugar disclosure are forcing formulation transparency across sweetened product categories. Beverage companies are reformulating with glucose syrups that register lower on added-sugar lines while maintaining equivalent functional performance. Soft drink and sports drink segments are most affected, with procurement teams demanding detailed dextrose equivalence documentation from suppliers.
Direct refinery-to-manufacturer contracting is displacing traditional distributor intermediaries in large-volume glucose procurement. Food and beverage manufacturers in the U.S. Midwest are negotiating long-term offtake agreements with Iowa and Illinois wet-mill operators to secure supply certainty. This pattern is most visible in industrial baking and confectionery verticals where volume predictability outweighs spot-market price flexibility.
North America Corn Glucose Market Segmentation
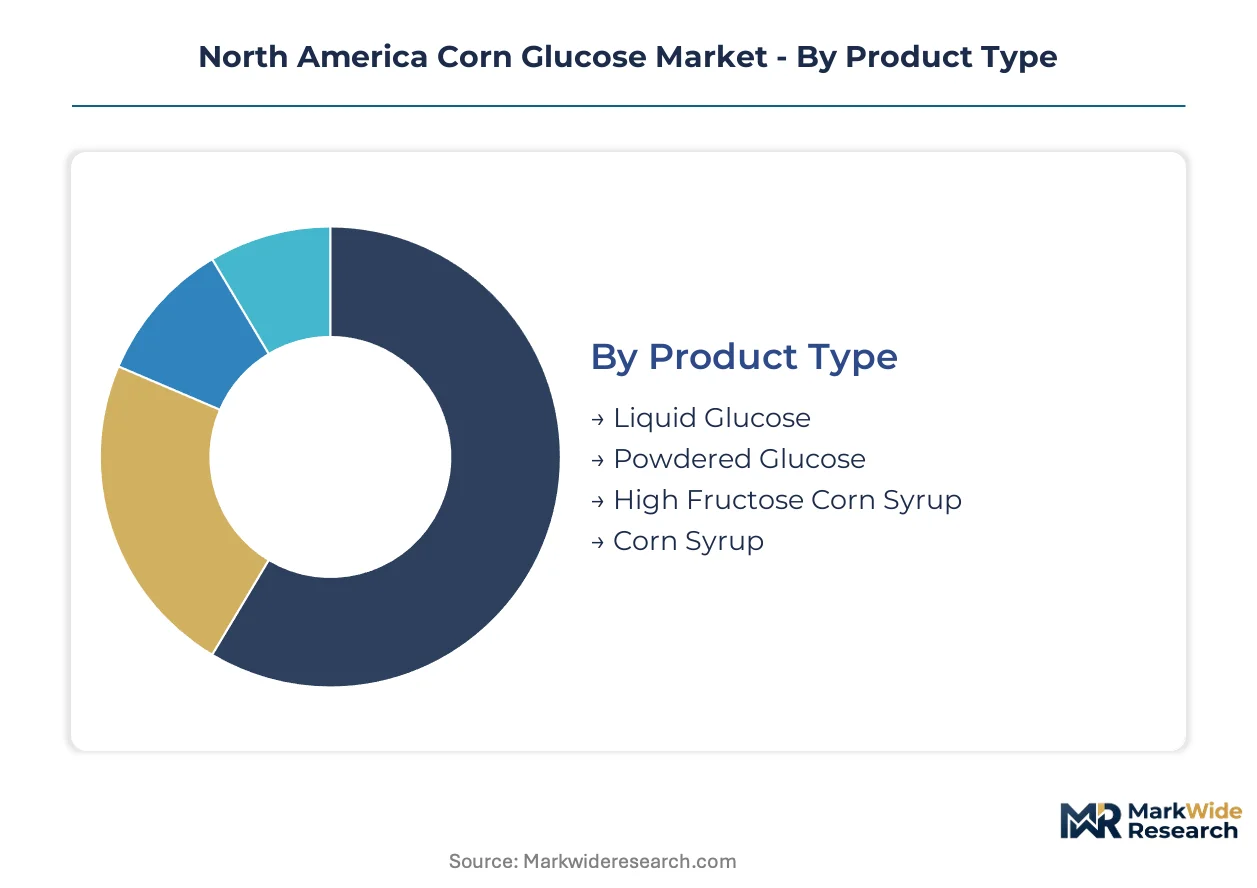
Corn glucose procurement patterns diverge sharply between bulk industrial buyers and specialty pharmaceutical purchasers across North America. Refiners structure product portfolios around dextrose equivalence specifications that align with FDA disclosure thresholds and Health Canada pharmaceutical standards.
Product Type:
Domestic Midwest wet-milling operations supply liquid glucose to U.S. food manufacturers, while pharmaceutical-grade derivatives increasingly cross into Canadian markets under harmonized PMRA standards.
- Liquid Glucose:A viscous syrup containing 20-47 percent glucose solids with adjustable dextrose equivalence from 20 to 100, produced through acid-enzyme or dual-enzyme hydrolysis. Demand concentrates in soft drink formulations across the U.S. Midwest, where beverage manufacturers reformulate to meet FDA added-sugar disclosure requirements while preserving sweetness functionality.
- Powdered Glucose:Dehydrated glucose solids with moisture content below 5 percent, offering extended shelf stability and precise dosing control. Pharmaceutical tablet binders and parenteral solution manufacturers in the United States and Canada are expanding procurement of spray-dried powders with tight particle-size distributions.
- High Fructose Corn Syrup:Enzymatically isomerized syrup with fructose content typically ranging from 42 to 55 percent. Faces structural pressure from sugar-reduction mandates in beverage applications.
- Corn Syrup:Less refined precursor with lower dextrose equivalence, serving industrial baking and confectionery as a cost-effective bulk sweetener and humectant.
Liquid glucose holds the largest share; momentum sits with powdered glucose as pharmaceutical applications expand.
Application:
Reformulation timelines vary by application, with beverage manufacturers facing the most compressed schedules due to FDA nutrition label enforcement.
- Beverages:Sports drinks, soft drinks, and flavored waters represent the volume anchor, with procurement teams demanding detailed dextrose equivalence documentation to navigate added-sugar line items on Nutrition Facts panels. Reformulation activity concentrates among multinational bottlers with U.S. manufacturing footprints.
- Confectionery:Hard candies, chewing gums, and chocolate coatings rely on glucose for crystallization control and texture modulation. Premium clean-label confectioners in the U.S. Northeast are testing tapioca-derived alternatives, threatening corn-based volume in high-margin segments.
- Bakery Products:Industrial bread and cake manufacturers use glucose for moisture retention, browning acceleration, and fermentation feed. Long-term offtake agreements with Iowa and Illinois wet-mill operators are displacing distributor intermediaries.
- Dairy:Ice cream and flavored milk applications leverage glucose for freezing point depression and viscosity enhancement. Faces substitution pressure from sucrose and alternative sweeteners in reduced-sugar product lines.
Beverages command the dominant volume position; confectionery is climbing the fastest as clean-label premiumization accelerates.
Distribution Channel:
Channel structure reflects buyer scale and specification complexity, with large food manufacturers bypassing traditional intermediaries.
- Wholesalers:Bulk liquid glucose moves through regional distributors serving mid-sized bakeries and confectioners with predictable volume requirements but limited storage infrastructure.
- Supermarkets:Retail-packaged glucose syrups for home baking and small commercial kitchens, concentrated in private-label offerings.
- Online Retail:Specialty glucose derivatives and pharmaceutical-grade powders reach nutraceutical formulators and research laboratories through B2B platforms.
- Specialty Stores:Artisan baking supply outlets stock premium glucose products for craft confectioners and boutique food producers.
Wholesalers retain the largest share; online retail is gaining share fastest as pharmaceutical and nutraceutical procurement digitizes.
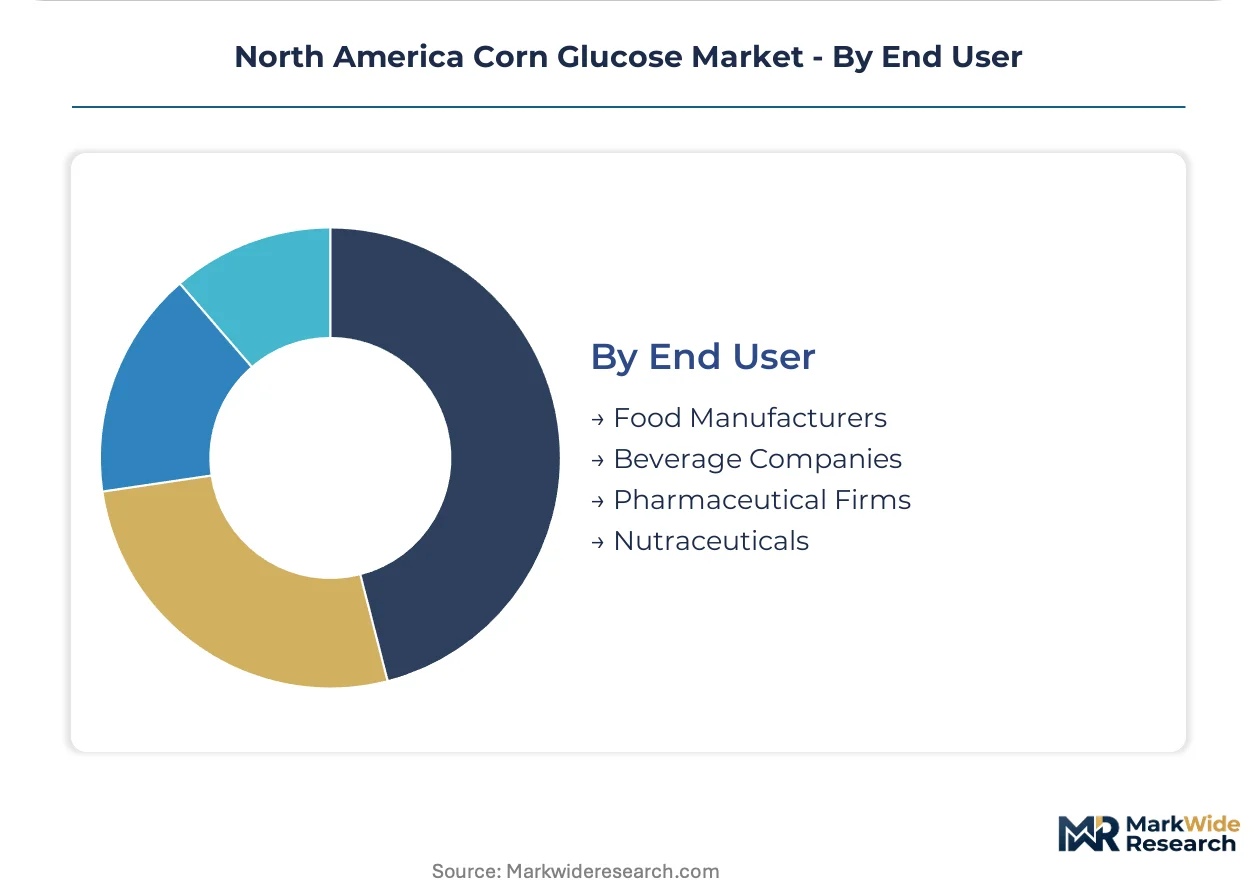
End User:
End-user concentration determines pricing leverage and contract structure, with pharmaceutical qualification requirements creating sticky supplier relationships.
- Food Manufacturers:Industrial baking and processed food operations across the U.S. Midwest negotiate direct refinery contracts for liquid glucose volume certainty.
- Beverage Companies:Multinational soft drink and sports drink bottlers drive specification innovation, demanding real-time dextrose equivalence monitoring and batch documentation.
- Pharmaceutical Firms:Tablet binders, parenteral solutions, and fermentation substrates require pharmaceutical-grade glucose with tight tolerances. Dual FDA-Health Canada qualification pressures extend product launch timelines but create integrated North American supply opportunities.
- Nutraceuticals:Dietary supplement and functional food producers represent an emerging demand pool for non-GMO and organic-certified glucose derivatives.
Food manufacturers hold the largest share; pharmaceutical firms are expanding most quickly as excipient demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns split sharply between the United States, where beverage reformulation drives glucose procurement, and Canada, where pharmaceutical-grade specifications anchor demand growth. Mexico's industrial baking sector operates on distinct cost structures that favor less refined corn syrup grades.
United States
Beverage manufacturers across the U.S. Midwest are accelerating clean-label reformulations to meet FDA added-sugar disclosure requirements. The FDA's updated Nutrition Facts label mandates are compressing procurement timelines for modified corn syrups with reduced dextrose equivalence profiles. Wet-milling clusters in Iowa and Illinois supply downstream refiners with captive corn supply chains that dominate bulk liquid glucose production.
Canada
Pharmaceutical and nutraceutical end users in Ontario and Quebec are expanding procurement of high-purity glucose derivatives for tablet binders and parenteral solutions. Health Canada and the PMRA coordinate cross-border standards with FDA 21 CFR regulations, creating compliance harmonization pressures for integrated North American suppliers. Toronto-area pharmaceutical manufacturing corridors are attracting glucose refiners seeking dual-jurisdiction qualification capabilities.
Mexico
Industrial baking and confectionery operations in Mexico City and Guadalajara metropolitan areas rely on cost-optimized corn syrup grades for moisture retention and browning control. The country's national food safety regulator oversees sweetener labeling standards that diverge from U.S. FDA requirements, creating formulation complexity for cross-border brands. Bimbo and regional baking cooperatives in Central Mexico negotiate direct supply agreements with U.S. wet-mill operators.
North America Corn Glucose Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in North American corn glucose refining. Cargill and Archer Daniels Midland anchor the consolidated upper tier through captive corn supply and Midwest wet-milling infrastructure. Mid-scale specialty refiners differentiate via pharmaceutical-grade specifications and enzymatic process control technologies. Competitive dynamics center on capacity expansion in Iowa and Illinois corridors alongside strategic partnerships targeting Canadian pharmaceutical qualification.
Among integrated agribusiness conglomerates, Cargill, Archer Daniels Midland, and Ingredion Incorporated occupy positions that exemplify distinct strategic archetypes. Cargill represents the captive supply model with backward integration into corn origination. Archer Daniels Midland exemplifies operational flexibility through integrated ethanol-to-syrup production switching. Ingredion Incorporated sits within the specialty derivative tier, anchoring pharmaceutical-grade glucose positioning for Health Canada and FDA dual-qualification markets.
| Leading Market Players |
|---|
| Tate & Lyle |
| Grain Processing |
| Cargill |
| Sweetener Products |
| Corn Refiners Association |
| Archer Daniels Midland |
| Roquette |
| SC Foods |
| Ingredion Incorporated |
| Others |
Cost & Logistics Intelligence
FDA 21 CFR qualification requirements for pharmaceutical-grade glucose derivatives simultaneously gate supplier entry and stratify price tiers, compressing margins for uncertified commodity producers while enabling premium capture for dual-jurisdiction qualified refiners.
Pricing Analysis
Long-term offtake agreements dominate volume procurement among U.S. Midwest food manufacturers, displacing spot-market transactions as buyers prioritize supply certainty over price flexibility. Pharmaceutical-grade glucose commands substantial premiums due to FDA-Health Canada dual-qualification requirements and tight dextrose equivalence tolerances. Cost compression in commodity liquid glucose is intensifying because tapioca-derived substitutes are gaining traction in premium clean-label segments. Industrial baking operations exhibit highest price sensitivity, while pharmaceutical firms prioritize specification compliance over unit cost.
Supply Chain Analysis
Inbound logistics costs from Iowa and Illinois corn origination points to downstream refiners hinge on barge availability along the Mississippi River system and railcar allocation during harvest peaks. Supply concentrates in the U.S. Midwest wet-milling corridor, with secondary processing clusters in Ontario serving Canadian pharmaceutical demand. Raw material inputs draw from Iowa and Illinois corn harvests, enzymatic conversion catalysts, and natural gas for drying operations. Single-source vulnerability runs through concentrated wet-milling infrastructure exposed to regional weather disruptions. Distribution runs through direct refinery-to-manufacturer contracting for large-volume buyers, with regional wholesalers serving mid-tier accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America corn glucose market is accelerating through FDA added-sugar disclosure mandates that force beverage reformulation timelines and expand demand for modified glucose syrups with reduced dextrose equivalence profiles.
For Market Incumbents: Secure captive corn supply through origination contracts in Iowa and Illinois corridors to defend against input cost volatility. Expand pharmaceutical-grade capacity in Ontario to capture Health Canada-PMRA harmonization benefits. Tapioca-derived substitutes threaten high-margin clean-label segments.
For New Entrants and Emerging Players: FDA 21 CFR fast-track qualification for pharmaceutical-grade specifications opens white-space in cross-border tablet binder and parenteral solution supply. Target nutraceutical formulators seeking non-GMO and organic-certified derivatives through B2B platform distribution. Fermentation substrate demand from precision fermentation represents the most penetrable emerging volume pool.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic process control technology upgrades as dual-enzyme systems displace acid-enzyme batch infrastructure. Mid-scale specialty refiners with Health Canada qualification capabilities present viable acquisition targets. Monitor bioprocessing tax credit utilization rates as inflection indicator for capital allocation shifts between commodity and specialty glucose lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Origination | Cargill's captive supply model insulates margins against Iowa and Illinois harvest volatility. |
| Pharmaceutical-Grade Capacity Expansion | Dual FDA-Health Canada qualification opens Toronto-area pharmaceutical manufacturing corridors. |
| Enzymatic Process Control Upgrade | Dual-enzyme systems with real-time dextrose equivalence monitoring compress specialty-commodity cost gaps. |
| Long-term Supply Agreement | Direct refinery contracts displace distributor intermediaries in industrial baking and confectionery. |
| Joint Venture for Fermentation Substrates | Cell-culture media partnerships with biopharma create emerging volume pools for high-purity derivatives. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and industry association disclosures. Wet-milling plant managers, beverage procurement leads, pharmaceutical formulation scientists, and enzymatic process engineers provided operational perspective. Bottom-up volume estimates from facility-level capacity triangulate against top-down demand segmentation from end-use consumption patterns.
Segmentation dimensions modeled include product type, application vertical, distribution channel, and end-user concentration across the analysis window. CAGRs derive from trend extrapolation of enzymatic conversion efficiency gains and pharmaceutical excipient demand intensification. Forecast inputs incorporate FDA label enforcement timelines and Health Canada-PMRA harmonization progress.
Underlying assumptions cover sustained corn price volatility, regulatory disclosure rule stability, and enzymatic technology diffusion rates, with deviation risk concentrated in substitution acceleration from tapioca-derived alternatives and bioprocessing tax credit policy shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Bladderpod Oil Market
Agricultural Commodities
Corn and Corn Starch Derivatives Market
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
Roundwood Market
Agricultural Commodities
Hermetic Food Grain Storage Market
Agricultural Commodities
Beet Pulp Pellets Market
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
North America Feed Lutein and Zeaxanthin Market
Agricultural Commodities
Black Pellet Market
Agricultural Commodities
Global Ruminant Feed Premix Market
Agricultural Commodities
Middle East Feed Amino Acids Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Africa Feed Amino Acids Market
Agricultural Commodities
Global Wood Chips Market