
 Peat Market | 2026-2036
Peat Market Size, Share, and Industry Trends Forecast 2026-2036
Peat Market Intelligence
The bundling of peat with other substrates into specialized horticultural mixes is hardening buyer preferences for value-added products. Klasmann-Deilmann GmbH leverages its extensive substrate formulation expertise to capture this professional grower segment. Premier Tech Ltd. differentiates through its integrated crop management solutions for horticulture. Vapo Group sustains a significant presence in both the horticultural and energy peat sectors across Nordic countries.
Peat is a heterogeneous mixture of partially decomposed plant material formed in anaerobic, water-saturated bog environments. Its defining characteristic is a high water-holding capacity, often exceeding 20 times its dry weight, combined with a stable, porous structure. Horticultural peat represents the primary value segment, driven by professional greenhouse and nursery operations. The fuel peat category, used for energy production, faces a structural decline due to carbon emission policies and the promotion of alternative energy sources.
Market access is shaped by strict environmental regulations governing peatland extraction, such as those under the EU Green Deal and national policies in Canada and Finland. The US EPA's Clean Water Act provisions influence extraction permits and mandate land restoration efforts post-harvest. Stakeholders must navigate the complex transition to peat-free alternatives while managing existing reserves and long-term ecological restoration obligations.
Market Dynamics
The peat market is defined by the structural tension between its utility in professional horticulture and increasing regulatory pressure on extraction. Policies like the EU Green Deal are forcing a reevaluation of peatland management and carbon sink preservation, influencing long-term supply availability and operational costs for producers.
Growth Catalysts
- Professional Horticulture Demand:Sustained use in greenhouse and nursery operations for high-value crops provides a stable demand base. Controlled environment agriculture requires consistent growing media.
- Value-Added Substrates:Formulating specialized horticultural mixes by blending peat with coir creates higher-margin products and hardens preference for professional growers.
- Food Security Focus:National food security initiatives indirectly support controlled environment agriculture, a major consumer of horticultural peat in areas with limited arable land.
Market Restraints
- Environmental Regulation:Policies like the EU Green Deal and national peatland protection strategies in Canada restrict new extraction permits, increasing compliance costs.
- Substitution Threat:The improving quality of peat-free substrates like coir and wood fiber presents a significant substitution threat in professional horticulture.
- Negative Public Perception:Activist pressure over the environmental impact of peat extraction influences retailers and growers, threatening the industry's social license to operate.
Strategic Opportunities
- Ecological Restoration Services:Expertise in peatland restoration creates a service revenue stream, helping operators meet regulatory obligations from bodies like the US EPA.
- Reduced-Peat Formulations:Developing high-performance, reduced-peat substrates allows companies to capture environmentally conscious segments and extend the life of existing reserves.
- New Agricultural Geographies:Controlled agriculture in arid regions like the Middle East is an underpenetrated market for growing media, including specialized peat mixes.
Industry Challenges
- Harvesting Volatility:Peat extraction is highly dependent on favorable weather, making annual harvest volumes unpredictable. This creates supply chain instability for producers in Canada and the Baltic states.
- Complex Restoration Mandates:Managing long-term ecological restoration obligations post-harvest is a significant operational challenge. This requires specialized ecological expertise and long-term capital commitment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peat Market |
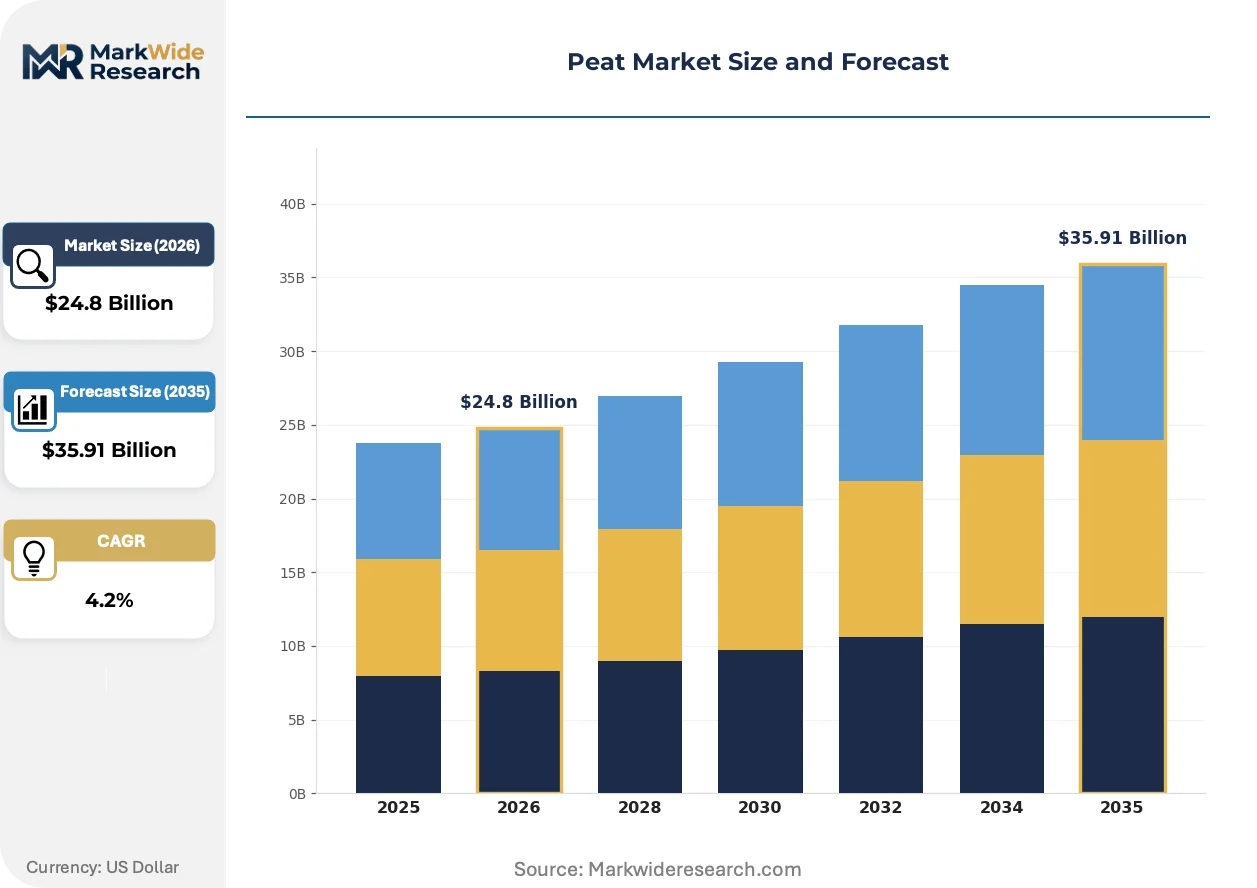
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $35.91 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horticultural Peat, Fuel Peat, Peat Moss, Peat Briquettes, Peat Pellets Extraction Method: Surface Mining, Hydraulic Mining, Mechanical Harvesting, Manual Peat Cutting Application: Soil Conditioner, Energy Production, Water Filtration, Animal Bedding, Horticulture End User Industry: Agricultural Producers, Power Generation Plants, Paper Manufacturing, Fisheries, Landscaping Services |
| Companies Covered | Bord na Móna, Vapo Group, Klasmann-Deilmann GmbH, Global Peat Ltd., Neova Oy, Lambert Peat Moss Inc., Sun Gro Horticulture, AB Rėkyva, Premier Tech Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peat Market Strategic Shifts & Innovations
Product innovation is focused on balancing horticultural performance with increasing environmental scrutiny. The industry is developing advanced substrate formulations and adapting extraction techniques to align with sustainability mandates from regulators and downstream customers, particularly in the professional horticulture segment.
Advanced substrate formulation combines peat with certified sustainable materials like wood fiber and coir to create high-performance blends. Professional growers are adopting these reduced-peat mixes to meet retailer sustainability targets without compromising crop quality. This innovation is expanding into markets previously inaccessible due to peat-free mandates, serving a broader customer base.
The European Union's Green Deal framework is fundamentally altering the regulatory landscape for peat extraction. Its policies classify peatlands as vital carbon sinks, causing a structural decline in fuel peat and stricter controls on horticultural harvesting. European producers are accelerating investment in alternative substrates and land restoration programs to maintain their license to operate.
A distinct bifurcation in buyer requirements is becoming more pronounced. Large retailers increasingly demand certified peat-free or reduced-peat products to meet corporate sustainability goals. In contrast, many professional greenhouse operators prioritize the unique performance and consistency of traditional horticultural peat, a divide most visible in the United Kingdom and Germany.
Peat Market Segmentation
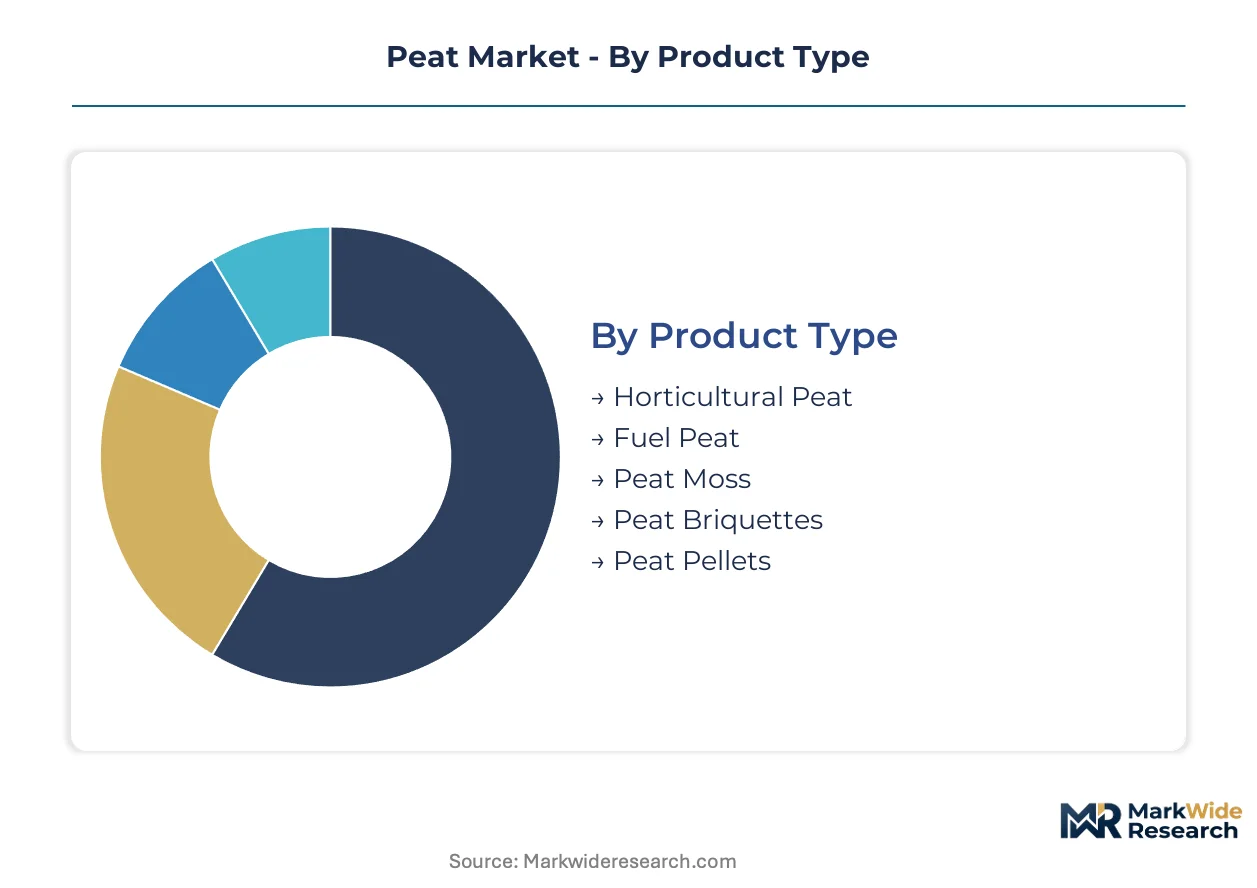
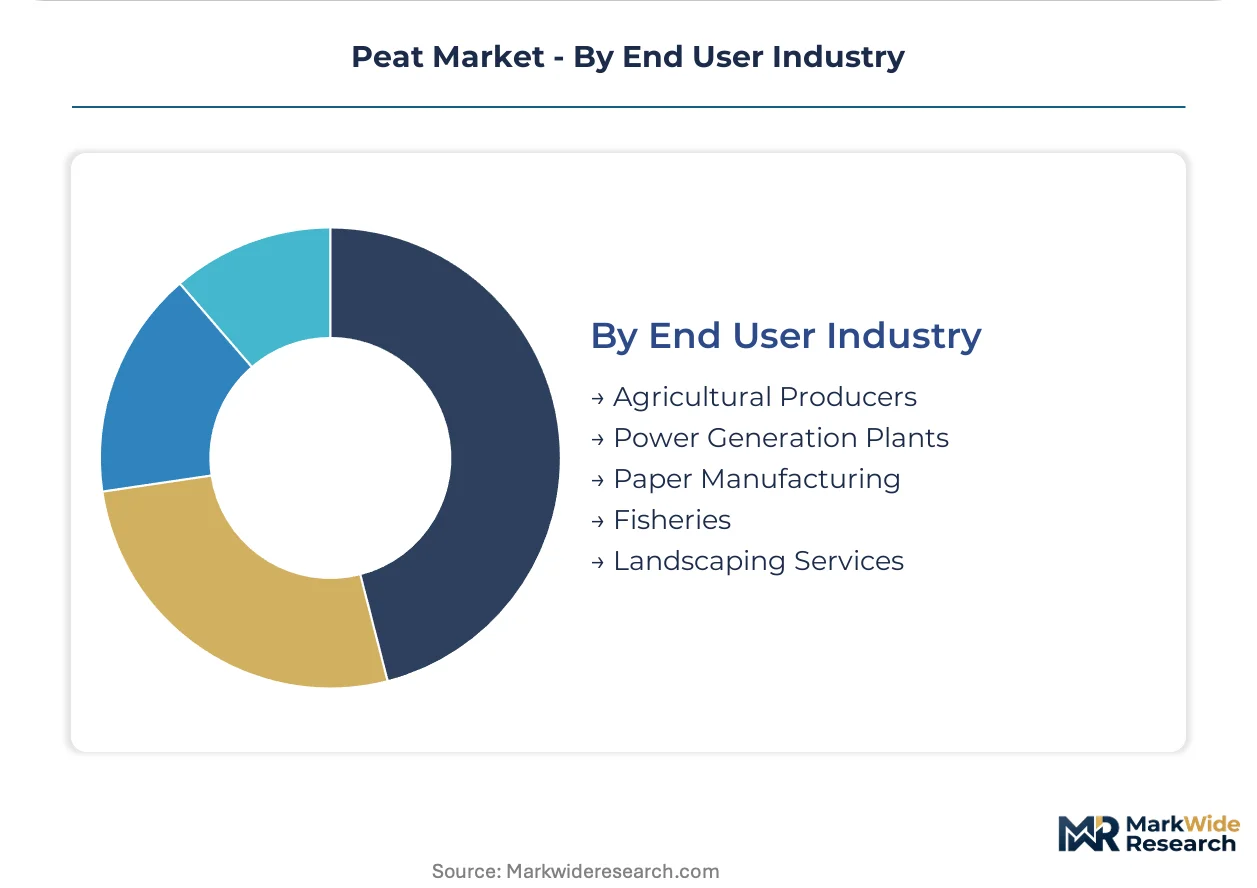
The peat market's segmentation reveals the distinct drivers and constraints influencing its various forms and applications amidst evolving environmental policies. Understanding these segments helps market participants navigate the structural shifts from traditional uses to specialized, value-added products.
Product Type:
Supply concentration in the peat market dictates product availability and pricing across different forms, influencing how various product types are developed and distributed.
- Horticultural Peat:This product is a heterogeneous mixture of partially decomposed plant material with high water-holding capacity, essential for stable, porous growing media. Demand concentrates in key agricultural markets like the Netherlands, Germany, and the United States, driven by professional greenhouse and nursery operations.
- Fuel Peat:Densely compressed organic matter used as a solid fuel for energy generation, historically significant in countries like Finland. Its demand is declining due to carbon emission policies and the promotion of alternative energy sources.
- Peat Moss:Light, fibrous material primarily used for soil amendment and often processed into various horticultural products for retail.
- Peat Briquettes:Compressed blocks of peat designed for efficient burning in domestic and industrial heating systems.
- Peat Pellets:Small, uniform units of processed peat, offering convenience for specialized heating applications or seed starting.
Today's leader: Horticultural Peat. Tomorrow's challenger: Peat Moss, particularly in processed blends.
Extraction Method:
The cost tier associated with peat extraction methods directly impacts operational expenses and the final product's market competitiveness.
- Surface Mining:This method involves removing layers of vegetation and soil to access peat deposits, often utilizing large-scale machinery for efficiency. This approach is prevalent in regions with extensive peatlands like Canada, where large volumes are extracted for horticulture.
- Mechanical Harvesting:Employs specialized machinery to cut and collect peat from drained bogs, allowing for higher productivity compared to manual methods. This approach is common in the Baltic states, where producers aim for consistent supply volumes.
- Hydraulic Mining:Uses high-pressure water jets to break up peat deposits, which are then pumped for processing.
- Manual Peat Cutting:Traditional method involving hand tools to cut peat blocks, often practiced in smaller-scale, localized operations.
Mechanical Harvesting is expanding most quickly due to efficiency demands, while Manual Peat Cutting faces structural decline.
Application:
Volume requirements for peat applications vary significantly, influencing extraction scales and processing technologies.
- Horticulture:Utilizes peat as a growing medium for professional greenhouse and nursery operations, providing a stable and porous structure for high-value crops. Demand for this application is concentrated in agricultural powerhouses such as the Netherlands.
- Energy Production:Involves burning peat as a fuel source in power generation plants, historically significant in Nordic countries. This application faces structural decline due to carbon emission policies and regulatory pressure from the EU Green Deal.
- Soil Conditioner:Peat is incorporated into agricultural soils to improve water retention, aeration, and nutrient availability.
- Water Filtration:Peat's absorbent properties are leveraged in industrial and municipal systems to remove impurities from water.
- Animal Bedding:Provides a soft, absorbent, and odor-controlling substrate for livestock and pet enclosures.
Horticulture continues to gain share fastest, while Energy Production declines rapidly.
End User Industry:
Customer type segmentation reveals distinct purchasing behaviors and product specifications across various industrial users of peat.
- Agricultural Producers:Professional growers and nurseries utilize peat for controlled environment agriculture, demanding consistent quality and specific substrate formulations. This segment underpins demand in regions with intensive greenhouse cultivation, including Germany.
- Power Generation Plants:These facilities consume fuel peat for electricity generation, particularly in countries with historical peat reserves like Finland. This end-user industry faces significant pressure to transition to renewable energy sources.
- Paper Manufacturing:Uses peat as a component in certain paper products or as a filtration aid in wastewater treatment.
- Fisheries:Employs peat in aquaculture for water conditioning and improving fish habitat.
- Landscaping Services:Incorporates peat into soil blends for new installations and garden maintenance, enhancing soil structure.
Agricultural Producers exhibit the steepest expansion trajectory, contrasting with the contraction in Power Generation Plants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peat extraction historically scaled in regions with abundant bog environments, particularly Northern Europe and North America. Early industrialization leveraged peat for energy production, establishing a foundational supply chain. Today, its specialized use in horticulture drives demand across diverse agricultural economies.
Netherlands
High-value horticulture drives significant demand for peat-based growing media within the Netherlands. The EU Green Deal significantly influences Dutch peatland management, pushing for reduced reliance on peat. The Westland region, a major greenhouse cluster, actively seeks high-performance reduced-peat substrates.
Germany
Professional greenhouse operations require consistent peat quality for ornamental and vegetable production in Germany. German environmental policies, aligning with EU directives, promote sustainable peatland use and restoration. Intensive horticultural centers like the Rhineland concentrate demand for specialized peat mixes.
United States
Extensive nursery and greenhouse production relies on peat for its unique water retention and aeration properties across the United States. The US EPA's Clean Water Act provisions regulate peat extraction and mandate post-harvest land restoration efforts. Florida's large ornamental plant nurseries represent a significant consumption hub for horticultural peat.
Canada
Canada possesses vast peatland resources, making it a major exporter of horticultural peat to international markets. Health Canada regulations influence peat harvesting practices, ensuring environmental stewardship and responsible resource management. The Quebec and New Brunswick provinces are primary extraction sites, supplying global demand.
Finland
Historically, Finland was a major user of fuel peat for energy generation, leveraging its extensive national reserves. Finnish national policies now prioritize carbon emission reductions, accelerating the decline of fuel peat consumption. The Ostrobothnia region, once a key peat production area, is transitioning towards alternative energy sources.
Peat Market Key Industry Players
Premium-margin players sit above commodity-margin players across substrate formulation expertise. The peat market exhibits a tiered structure, with specialized providers focusing on high-performance horticultural mixes. Strategic archetypes include integrated substrate suppliers, regional extraction specialists, and diversified energy-to-horticulture conglomerates. Companies pursue portfolio diversification into peat-free alternatives and strategic partnerships to navigate regulatory shifts.
Specialized substrate formulators like Klasmann-Deilmann GmbH exemplify the premium-tier approach, leveraging extensive research to create value-added horticultural products. Premier Tech Ltd., a Canadian-based firm, represents integrated crop management solutions, extending beyond raw peat to encompass broader horticultural needs. Vapo Group, a Finnish company, occupies a position within both the horticultural and energy peat sectors, demonstrating a diversified presence across Nordic countries. These entities reflect the industry's adaptation to environmental mandates and evolving grower preferences.
| Leading Market Players |
|---|
| Bord na Móna |
| Vapo Group |
| Klasmann-Deilmann GmbH |
| Global Peat Ltd. |
| Neova Oy |
| Lambert Peat Moss Inc. |
| Sun Gro Horticulture |
| AB Rėkyva |
| Premier Tech Ltd. |
Cost & Logistics Intelligence
Global Peat Futures Index movements directly influence pricing across the peat market, cascading into distinct pricing tiers for horticultural peat and fuel peat. This volatility impacts procurement costs for specialized substrate formulators and energy producers.
Pricing Analysis
Contract-based long-term offtake agreements define pricing for high-grade horticultural peat, reflecting its specialized application. Price differentiation stems from substrate formulation expertise, certified sustainable sourcing, and regional delivery costs. Pricing pressure intensifies on fuel peat due to carbon emission policies, while horticultural peat maintains premium pricing. Professional greenhouse operators exhibit lower price sensitivity for consistent, high-performance growing media.
Supply Chain Analysis
Logistics and freight costs significantly influence the landed price of peat, particularly for exports from Canada and the Baltic states to major agricultural markets. Supply concentration centers on vast peatland resources in Canada, Finland, and the Baltic states, drawing from partially decomposed plant material in specific bog environments. Harvesting volatility due to weather and increasing regulatory restrictions, like the EU Green Deal, represent structural supply risks. Distribution runs through specialized horticultural distributors and direct channels to large professional growers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The peat market operates as a regulatory compounder, where environmental policies like the EU Green Deal drive innovation in reduced-peat formulations. This regulatory pressure necessitates strategic adaptation across the value chain.
For Market Incumbents:
Anchor existing market share by accelerating investment in high-performance, reduced-peat substrate formulations. Incumbents must also deepen their expertise in ecological restoration services to meet mandates from bodies like the US EPA, mitigating negative public perception. This strategy defends against the growing substitution threat from peat-free alternatives and extends the social license to operate. Long-term capital commitment for land restoration ensures compliance and secures future extraction rights.
For New Entrants and Emerging Players:
Launch via strategic partnerships with local agricultural technology providers to penetrate new agricultural geographies like the Middle East. Focus on developing high-performance, reduced-peat formulations for environmentally conscious professional growers. This approach targets underpenetrated segments in controlled environment agriculture, where consistent growing media is critical. Niche high-value crops also represent a viable entry point for specialized mixes.
For Investors and Strategic Acquirers:
Asymmetric upside sits with specialized substrate formulators demonstrating strong R&D in peat-free and reduced-peat blends. The long-term viability centers on companies adept at navigating regulatory shifts and offering sustainable growing media solutions. Acquire entities with proven ecological restoration expertise to mitigate environmental liabilities. The signal to watch is the accelerating adoption rate of certified reduced-peat products by large retailers and professional growers.
| Strategic Initiative | Industry Significance |
|---|---|
| Investment in Peat-Free Production Facilities | Diversifies revenue streams and aligns with EU Green Deal mandates for sustainable horticulture. |
| Development of Advanced Reduced-Peat Substrates | Captures demand from environmentally conscious growers without compromising crop performance. |
| Expansion of Peatland Restoration Services | Creates new service revenue and fulfills regulatory obligations from bodies like the US EPA. |
| Long-term Supply Contracts for Coir and Wood Fiber | Secures alternative raw materials and mitigates supply chain risks for peat-free blends. |
| Strategic Partnerships in Controlled Environment Agriculture | Penetrates new high-growth markets in arid regions for specialized growing media. |
Research Approach
Coverage spans North America and Europe, with primary inputs from each region informing market dynamics. This involved in-depth interviews with horticultural facility managers, peat extraction operators, environmental regulators, and substrate R&D directors. Secondary validation utilized EU Green Deal policy documents, national environmental agency reports, and agricultural trade publications. Data triangulation, employing both bottom-up and top-down approaches, ensured robust market sizing.
Rate-of-change decomposition modeled the market across the analysis window, considering growth catalysts and market restraints. Segmentation dimensions included product type, extraction method, application, and end-user industry. Compound annual growth rates were derived from historical data and projected shifts in regulatory policy. Adoption rates of peat-free alternatives served as a key forecast input.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen changes in environmental regulations or rapid peat-free substrate innovation. Forecasts reflect assumptions regarding long-term peatland management policies. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market
Agricultural Commodities
Artificial Fishing Baits Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Black Pellet Market
Agricultural Commodities
Feed Yeast Market
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
Vietnam Compound Feed Market
Agricultural Commodities
Soybean Derivatives Market
Agricultural Commodities
Growing Peat Market
Agricultural Commodities
Copra Meal Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Market
Agricultural Commodities
Bladderpod Oil Market
Agricultural Commodities
Roundwood Market
Agricultural Commodities
South America Feed Premix Market
Agricultural Commodities
Africa Feed Amino Acids Market
Agricultural Commodities
Cattle Feed Market