
 Cottonseed Hulls Market | 2026-2036
Cottonseed Hulls Market Size, Share, and Industry Trends Forecast 2026-2036
Cottonseed Hulls Market Outlook
The EU Green Deal is rebalancing feed ingredient sourcing standards across European livestock supply chains. Cargill leverages its integrated oilseed processing network to secure consistent hull volumes from southern US gins. ADM anchors its position through direct relationships with cotton ginner cooperatives in the Mississippi Delta. Bunge competes by extending its crush footprint into hull pelletization for export dairy markets.
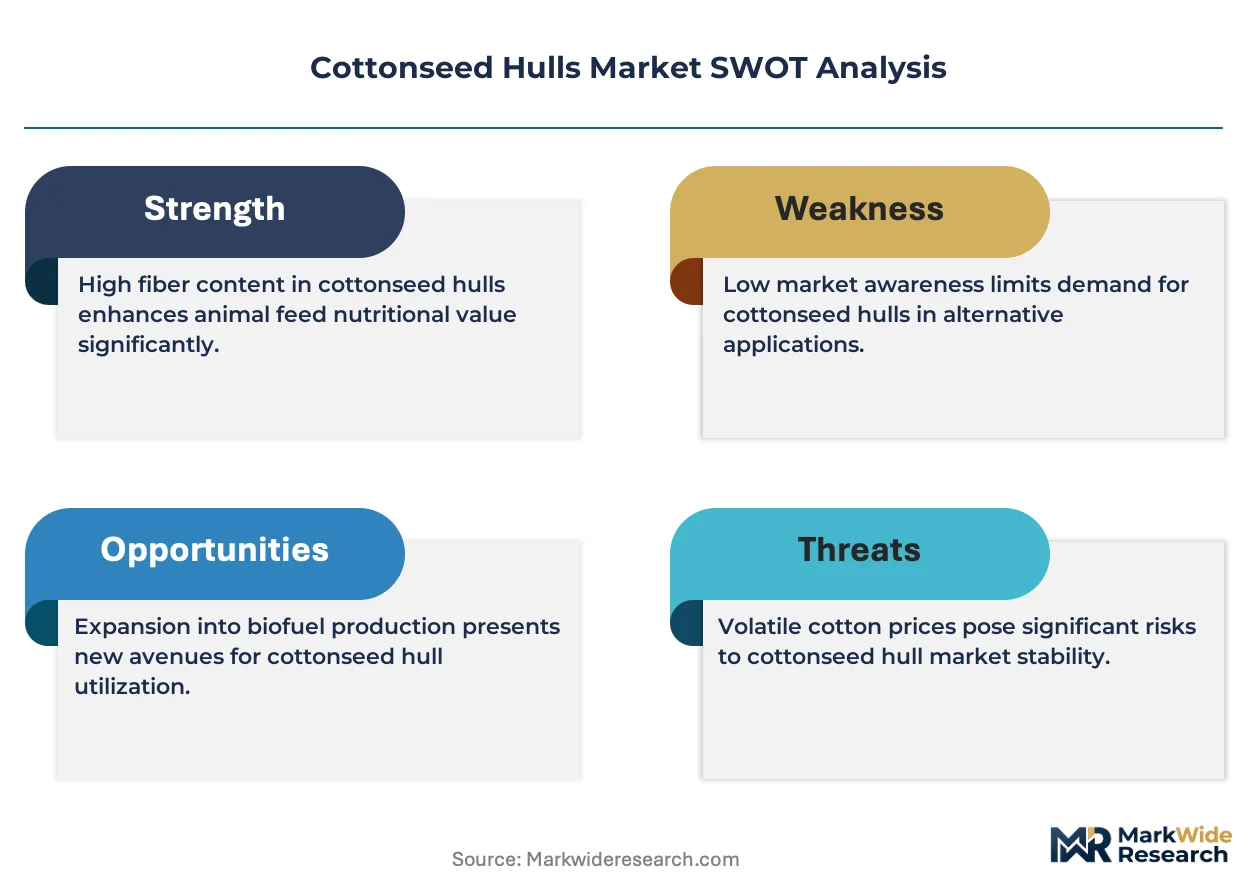
Cottonseed hulls constitute the fibrous outer covering of cottonseeds, typically containing 40–50% crude fiber and 3–8% protein by dry weight, separated during delinting and used primarily as bulk roughage in ruminant diets. Pelleted Hulls command premium positioning among Dairy Farmers due to reduced storage footprint and standardized intake rates, while Fiber Hulls sustain volume leadership in loose-fill bedding applications for Agricultural Feeders. Industrial Hulls differentiate through oil extraction residuals recovery, though Edible Hulls occupy a narrow specialty channel for human-grade fiber additives.
The USDA and FDA jointly govern feed ingredient safety through the Food Safety Modernization Act and BSE feed rules, requiring facility registration and hazard controls that elevate compliance costs for small hull processors. EPA air quality standards for cotton gin dust emissions indirectly constrain hull throughput capacity in concentrated production zones. Stakeholders must monitor evolving state-level carbon accounting frameworks that could recategorize agricultural residues as credit-eligible feedstock streams.
Market Dynamics
The cottonseed hulls market is being fundamentally reshaped by the USDA's tightening traceability requirements under the Food Safety Modernization Act, which forces processors to invest in batch-tracking infrastructure and elevates compliance costs for smaller ginning operations across the Texas cotton belt.
Growth Catalysts
- Dairy Ration Expansion:Dairy farmers in the United States are expanding cottonseed hull inclusion rates as a cost-effective fiber source that improves rumen function and reduces metabolic disorders in high-producing herds.
- EU Green Deal Feed Sourcing:The EU Green Deal is rebalancing ingredient standards across European livestock supply chains, creating export demand for certified sustainable hull products from established US processors.
- Pelletization Infrastructure:Advanced densification technologies are reducing storage footprints and transportation costs, enabling hull suppliers to reach distant feed markets previously uneconomical for loose bulk delivery.
Market Restraints
- Input Cost Volatility:Cotton acreage fluctuations and ginning capacity constraints in the Mississippi Delta create raw material availability uncertainty that compresses processor margins during drought cycles.
- Regulatory Friction:EPA air quality standards for cotton gin dust emissions indirectly constrain hull throughput capacity in concentrated production zones, limiting expansion without costly abatement equipment.
- Substitution Threat:Soybean hulls and almond hulls compete aggressively in ruminant fiber rations, particularly when cottonseed prices spike relative to alternative roughage sources.
Strategic Opportunities
- Carbon Credit Eligibility:Evolving state-level carbon accounting frameworks in California and the Pacific Northwest could recategorize agricultural residues as credit-eligible feedstock streams, unlocking new revenue layers for hull processors.
- Pellet Export Markets:Dairy regions in Mexico and Southeast Asia present underpenetrated demand for standardized pelleted hulls that reduce handling losses and enable precise ration formulation.
- Human-Grade Fiber Channel:Edible hulls for human-grade fiber additives occupy a narrow specialty segment with premium pricing potential as functional food markets expand.
Industry Challenges
- Compliance Timeline Compression:The FDA's hazard analysis requirements demand facility upgrades that strain capital reserves at small-to-midscale ginning cooperatives already facing thin operating margins.
- Skill Scarcity in Traceability Systems:Implementation of batch-tracking infrastructure requires technical personnel scarce in rural cotton belt communities, forcing processors to outsource or delay compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cottonseed Hulls Market |
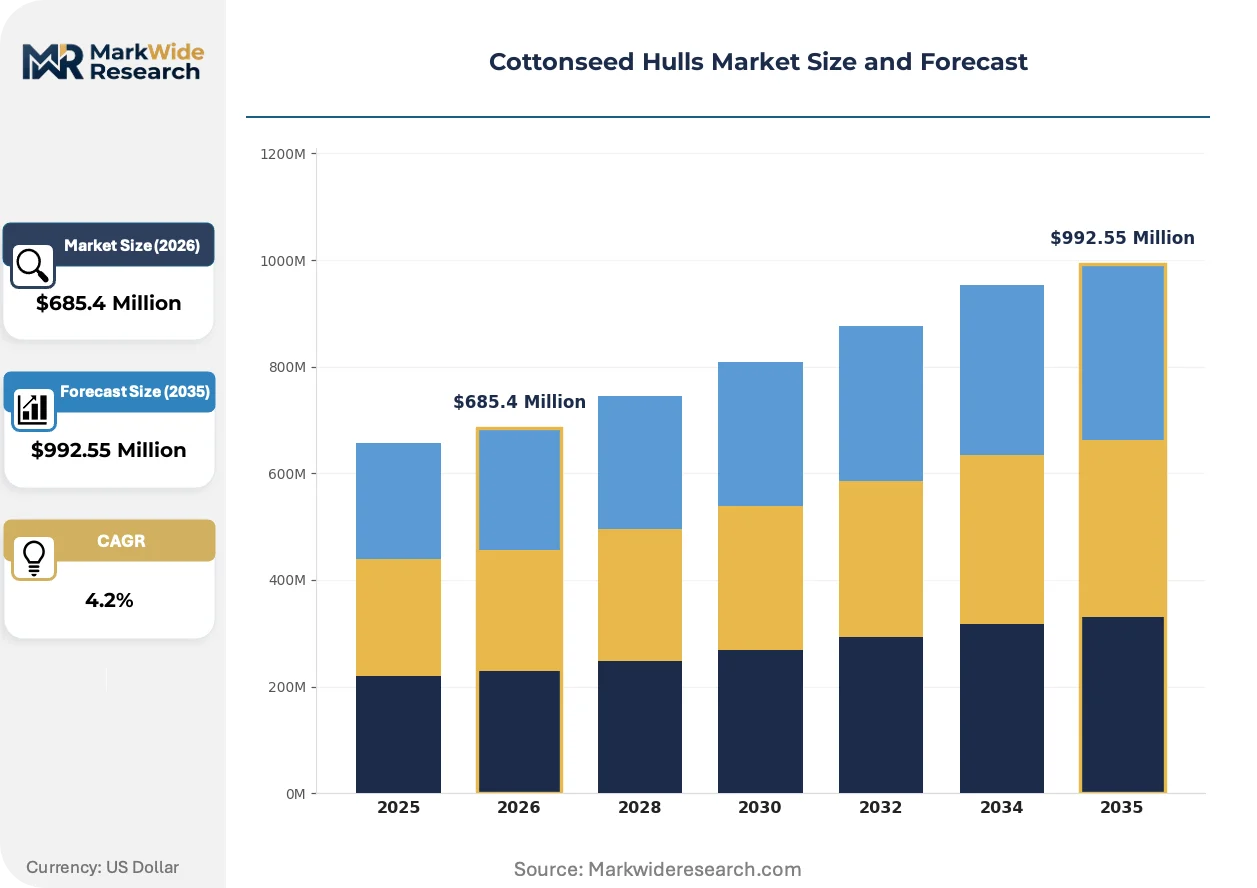
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edible Hulls, Industrial Hulls, Pelleted Hulls, Fiber Hulls Application: Animal Feed, Biofuels, Textiles, Mulching End User: Dairy Farmers, Poultry Producers, Textile Manufacturers, Agricultural Feeders Distribution Channel: Direct Sales, Wholesalers, Retail Outlets, Online Sales |
| Companies Covered | ADM, Bunge, Cargill, Mamta Cotton Industries, Pramoda Exim Corporation, Prem International, Shree Ram Proteins Ltd., GIMATex Industries Pvt. Ltd, Planters Cotton Oil Mill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cottonseed Hulls Market Strategic Shifts
Processing technology and regulatory frameworks are converging to transform how cottonseed hulls move from gin byproduct to valued feed ingredient. Three distinct shifts are compressing legacy supply arrangements and opening new value capture points for prepared operators.
Near-infrared spectroscopy coupled with automated sorting is rewriting quality assurance protocols at ginning facilities. Large dairy cooperatives in Wisconsin and New York now mandate real-time fiber and moisture verification before bulk purchases. This technology is compressing price variability between delivery lots and enabling outcome-based contracting that ties hull pricing to measured digestibility coefficients.
REACH compliance requirements in the European Union are tightening contaminant thresholds for imported feed materials. Processors seeking EU market access must demonstrate aflatoxin and pesticide residue controls exceeding domestic US standards. The pelleted hull segment faces the steepest compliance burden, as densification concentrates any residual contaminants and triggers enhanced scrutiny at port-of-entry inspections.
Dairy nutritionists are consolidating supplier relationships around vertically integrated processors capable of year-round volume guarantees. This pattern is displacing spot-market purchasing that dominated historical hull procurement. The shift is most visible across the upper Midwest, where large herd operations now contract directly with Texas and Delta ginner cooperatives, bypassing traditional feed dealer intermediaries entirely.
Cottonseed Hulls Market Segmentation
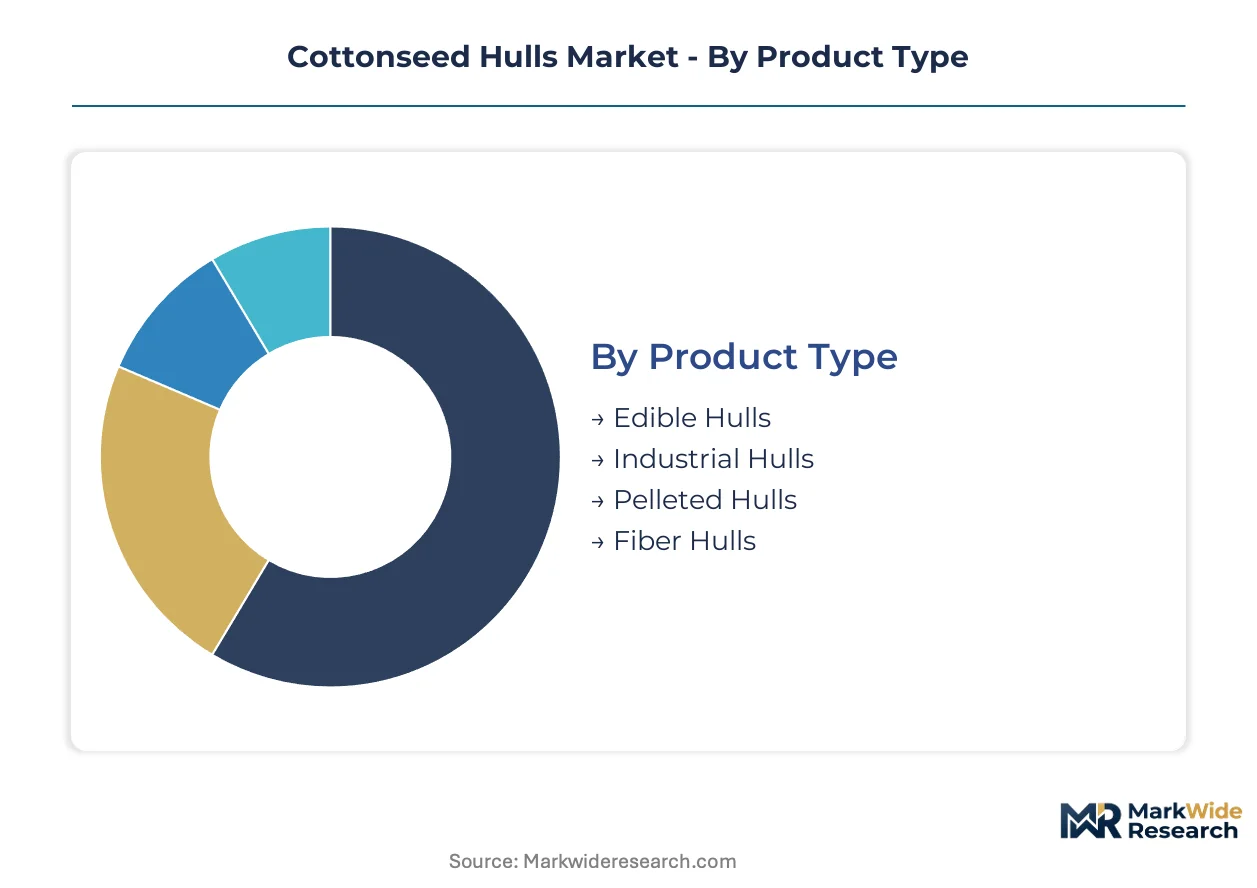
Cottonseed hulls flow through distinct processing tiers and end-use channels that reshape procurement patterns across livestock operations. Understanding these segment boundaries clarifies where margin pools concentrate and which product forms command pricing premiums.
Product Type:
Standalone hull products serve direct feed and industrial applications, while processed formats embed quality assurance and handling efficiencies that reshape buyer-seller relationships.
- Pelleted Hulls:Densified through mechanical compression to 6-8mm diameter pellets with standardized moisture below 12%. Dairy cooperatives in Wisconsin and New York mandate this format for automated feeding systems that reduce labor and enable precise ration formulation. The pelleting investment elevates per-ton pricing but compresses storage footprint and transportation costs for distant markets.
- Fiber Hulls:Loose, unprocessed hulls retaining natural bulk density of 120-150 kg/m³ with crude fiber content at 40-50% dry weight. Demand concentrates among beef cattle operations across the Texas Panhandle and dairy heifer raisers seeking low-cost roughage that stimulates rumen function without concentrate displacement.
- Industrial Hulls:Oil extraction residuals recovered from solvent-based processing at cottonseed crush facilities. Oil refiners in the Mississippi Delta channel this stream toward boiler fuel applications and absorbent material production.
- Edible Hulls:Specialty-grade material meeting food-contact purity standards for human fiber additive applications. Functional food manufacturers in California and the Pacific Northwest source limited volumes for digestive health formulations.
Volume placements concentrate in Fiber Hulls; the faster expansion belongs to Pelleted Hulls.
Application:
Cost tier differentiation separates commodity roughage from value-added processing streams that capture regulatory and sustainability premiums.
- Animal Feed:Ruminant ration inclusion at 10-25% of dry matter provides effective fiber that maintains milk fat percentages and reduces acidosis risk. Nutritionists at large herd operations in the upper Midwest specify cottonseed hulls when soybean hull prices spike or alfalfa quality deteriorates.
- Biofuels:Cellulosic ethanol developers and anaerobic digestion facilities evaluate hull lignin content for biochemical conversion potential. Pilot projects in Iowa and Nebraska test pretreatment protocols that unlock fermentable sugars from cottonseed fiber structures.
- Textiles:Absorbent cotton and low-grade fiber recovery from hull processing waste streams. Textile manufacturers in Georgia and the Carolinas blend recovered cellulose into nonwoven industrial wiping products.
- Mulching:Horticultural applications leverage hull biodegradability and weed suppression properties. Vineyards in California's Central Valley apply cottonseed hull mulch to retain soil moisture and regulate root zone temperature.
Feed applications absorb the greatest tonnage; biofuel pathways show the steepest expansion trajectory as carbon accounting frameworks mature.
End User:
Customer type fragmentation creates distinct service requirements that separate spot-market suppliers from contract-based volume guarantors.
- Dairy Farmers:Herd operations above 500 head dominate pelleted hull procurement through direct ginner relationships that bypass traditional feed dealers. These buyers prioritize year-round consistency and real-time quality verification via near-infrared spectroscopy protocols.
- Agricultural Feeders:Backgrounding operations and stocker cattle enterprises across Oklahoma and Kansas purchase loose Fiber Hulls through regional feed distributors. Price sensitivity drives spot-market purchasing with minimal quality specification beyond crude fiber minimums.
- Poultry Producers:Limited adoption in broiler and layer rations due to fiber digestibility constraints relative to soybean hull alternatives. Research stations in Arkansas and Georgia evaluate processing modifications that improve poultry metabolizable energy coefficients.
- Textile Manufacturers:Specialty nonwoven producers source hull-derived cellulose for industrial absorbent applications. Volume remains constrained by fiber length limitations and color consistency challenges.
Procurement volumes cluster with Dairy Farmers; Agricultural Feeders represent the most price-elastic demand segment.
Distribution Channel:
Supply concentration patterns favor direct relationships in high-volume segments while fragmented outlets serve scattered, small-scale buyers.
- Direct Sales:Ginner cooperatives in the Texas cotton belt and Mississippi Delta contract directly with dairy cooperatives and large feed manufacturers. This channel captures 60-70% of pelleted hull volume and enables outcome-based pricing tied to digestibility coefficients.
- Wholesalers:Regional feed distributors aggregate loose Fiber Hulls from multiple gins for redistribution to cattle operations and smaller dairies. Inventory pooling reduces supply interruption risk during ginning seasonality.
- Retail Outlets:Farm supply stores and cooperative extension points serve hobby farmers and small livestock holders with bagged hull products. Premium pricing reflects handling and packaging costs.
- Online Sales:E-commerce platforms connect specialty buyers with edible-grade and organic-certified hull suppliers. Human-grade fiber additive markets in functional food channels utilize this pathway for sample procurement and small-lot fulfillment.
Tonnage flows concentrate through Direct Sales; Online Sales channels are climbing the fastest as specialty ingredient platforms expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States produces the majority of cottonseed hulls yet consumes them domestically, while export demand from Mexico and Southeast Asia creates a production-consumption divide that reshapes ginning economics across the southern cotton belt.
United States
Dairy cooperatives in Wisconsin and New York drive pelleted hull procurement through direct contracts with Texas ginner cooperatives. The USDA's Food Safety Modernization Act mandates batch-tracking infrastructure that elevates compliance costs for smaller processors. The Mississippi Delta cluster anchors volume, where ADM and Bunge maintain crush facilities that channel hulls into domestic feed and export markets.
Mexico
Dairy regions in Baja California and Jalisco present underpenetrated demand for standardized pelleted hulls that reduce handling losses. Mexico's national feed safety regulator enforces aflatoxin thresholds aligned with US standards, easing cross-border trade flows. Guadalajara-based distributors aggregate volumes from Texas gins for redistribution to central plateau dairy operations.
India
Cotton ginneries in Gujarat and Maharashtra supply loose fiber hulls to domestic dairy and buffalo feed rations. The Food Safety and Standards Authority of India monitors pesticide residues in cotton byproducts destined for animal consumption. The Rajkot industrial corridor concentrates processing capacity where Mamta Cotton Industries and Pramoda Exim Corporation source raw material from surrounding ginning clusters.
Brazil
Expanding dairy herds in Minas Gerais and Paraná generate import demand for US-origin pelleted hulls when domestic soybean hull prices spike. Brazil's Ministry of Agriculture enforces sanitary protocols for imported feed materials that mirror EU contaminant thresholds. The Campinas logistics hub receives containerized hull shipments from US Gulf ports for redistribution to southeastern feed manufacturers.
China
Textile manufacturers in Jiangsu and Zhejiang provinces evaluate hull-derived cellulose for industrial nonwoven applications. The Ministry of Ecology and Environment enforces air quality standards that constrain cotton gin dust emissions in concentrated production zones. The Yangtze River Delta cluster hosts pilot facilities testing hull pretreatment for cellulosic ethanol conversion pathways.
Cottonseed Hulls Market Competitive Environment
The competitive structure tilts toward integrated agribusiness conglomerates with captive oilseed processing networks. Large multinational traders dominate pelleted hull supply through direct ginner relationships, while regional specialists capture loose fiber volumes in spot markets. Three archetypes prevail: vertically integrated oilseed crushers, cooperative ginning federations, and export-focused commodity traders. Capacity consolidation and geographic expansion constitute the dominant competitive moves, with processors acquiring ginning assets to secure upstream hull streams.
Within the integrated crusher tier, ADM, Bunge, and Cargill exemplify scale-driven positioning through their southern US oilseed processing footprints. ADM anchors supply security through direct relationships with Mississippi Delta ginner cooperatives. Bunge competes by extending crush operations into hull pelletization for dairy export markets. Cargill leverages its network density to secure consistent volumes from Texas cotton belt gins. These three agribusiness conglomerates sit within a structure where cooperative ginning federations supply raw material and regional exporters fill spot-market gaps.
| Leading Market Players |
|---|
| ADM |
| Bunge |
| Cargill |
| Mamta Cotton Industries |
| Pramoda Exim Corporation |
| Prem International |
| Shree Ram Proteins Ltd. |
| GIMATex Industries Pvt. Ltd |
| Planters Cotton Oil Mill |
| Others |
Value Chain & Pricing Dynamics
Family-owned ginning cooperatives across the Texas cotton belt and Mississippi Delta anchor upstream supply, translating seasonal harvest concentration into disciplined contract pricing that favors buyers with volume commitments over spot-market participants.
Pricing Analysis
Margin tightening in pelleted hull tiers reflects capital-intensive densification equipment and FDA-mandated batch-tracking infrastructure that elevates fixed costs for smaller processors. Three-tier pricing structure across premium, standard, and economy levels separates certified organic hulls from conventional pelleted grades and loose fiber bulk. Price differentiation hinges on near-infrared spectroscopy verification and geographic delivery distance from ginning clusters. Agricultural Feeders exhibit highest price sensitivity, while Dairy Farmers absorb premiums for year-round consistency guarantees.
Supply Chain Analysis
Skilled technician scarcity in rural Texas and Delta communities constrains traceability system deployment, forcing processors to outsource compliance functions or delay facility upgrades. Supply concentrates in the United States, India, and Brazil, with raw material flows drawing from cotton ginning clusters, solvent extraction facilities, and pelletization plants. The chain rests on cottonseed availability, ginning capacity utilization, and diesel freight costs. Single-source vulnerability emerges where dairy cooperatives bypass traditional feed dealers for direct ginner contracts. Distribution runs through direct sales channels capturing pelleted hull volume, supplemented by regional wholesalers aggregating loose fiber for scattered cattle operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cottonseed hulls market sits in a processing-technology transition, with near-infrared spectroscopy and automated densification displacing legacy visual grading and loose-bulk handling systems.
For Market Incumbents: Cement supply security through backward integration into ginning assets across the Texas cotton belt, countering ADM and Bunge's cooperative lock-up strategies. Invest in California-compliant carbon accounting infrastructure ahead of state-level agricultural residue credit frameworks, transforming compliance cost into revenue layer.
For New Entrants and Emerging Players: Dairy cooperatives in Mexico's Baja California and Jalisco regions present underpenetrated demand for standardized pelleted hulls with reduced handling losses. Partner with Guadalajara-based feed distributors to establish import aggregation nodes, leveraging aligned aflatoxin standards with US regulators for streamlined cross-border flows.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale ginning cooperatives in the Mississippi Delta facing FDA compliance timeline compression and thin operating margins. Watch for EPA enforcement actions on cotton gin dust emissions as inflection signal triggering forced consolidation among sub-scale processors unable to fund abatement equipment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ginning Assets | Captures upstream hull streams before ADM and Bunge cooperative lock-ups solidify. |
| Pelletization Capacity Expansion | Enables Wisconsin and New York dairy cooperative contracts with automated feeding compatibility. |
| Carbon Credit Infrastructure Investment | Positions agricultural residues for California state-level credit-eligible feedstock recategorization. |
| Near-Infrared Spectroscopy Deployment | Satisfies large herd operations demanding real-time fiber and moisture verification protocols. |
| EU REACH Compliance Certification | Unlocks export access for pelleted hulls facing tightened contaminant thresholds at European ports. |
Study Parameters
USDA crop production reports, EPA enforcement databases, and FDA facility registration records formed the secondary backbone, cross-referenced with primary interviews involving cotton ginning cooperative managers, dairy nutritionists at large herd operations, feed manufacturing procurement leads, and regulatory compliance officers. Bottom-up volume estimates from ginning capacity utilization data were triangulated against top-down feed ration inclusion rate surveys across the upper Midwest.
Historical trendline analysis of cotton acreage, ginning output, and hull price indices established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, application channel, end-user scale tier, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity constraints, with specific inputs including dairy herd expansion rates in Mexico and Southeast Asia and evolving state-level carbon accounting framework adoption.
Caveats apply where cotton acreage volatility from drought cycles, EPA air quality enforcement intensity, or EU REACH contaminant threshold revisions could materially shift the outlook. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Global Ruminant Feed Premix Market
Agricultural Commodities
Africa Feed Amino Acids Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Hermetic Food Grain Storage Market
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
Artificial Fishing Baits Market
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market
Agricultural Commodities
Growing Peat Market
Agricultural Commodities
Vietnam Feed Concentrate and Basemix Market
Agricultural Commodities
Europe Ruminant Feed Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Blood Meal Market
Agricultural Commodities
Feed Yeast Market
Agricultural Commodities
Cattle Feed Market
Agricultural Commodities
Castor Oil Market