
 Copra Meal Market | 2026-2036
Copra Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Copra Meal Market Analysis
Multi-source procurement from Philippine and Indonesian processors is pivoting as feed manufacturers seek supply security against coconut oil price volatility. Samar Coco Products Manufacturing Corp. leverages its Quezon-based crushing capacity to anchor regional supply chains. ADM Animal Nutrition competes through North American distribution networks for dairy nutrition formulations. Cargill, Incorporated sustains quality differentiation via integrated laboratory testing protocols at origin points.
Copra meal denotes the residual cake remaining after mechanical or solvent extraction of coconut oil, typically containing 20-25% crude protein and 10-12% crude fiber by dry weight, serving primarily as a protein and energy supplement in ruminant and monogastric feed formulations. Meal and pellet grades dominate volume throughput due to handling efficiency in automated feed mills, while powder segments occupy specialty niches in aquaculture starter diets. Animal feed applications lead absolute consumption, though fertilizer and biofuel off-take channels are expanding fastest as circular economy frameworks valorize processing residues.
The Philippines' Bureau of Agriculture and Fisheries Standards enforces maximum aflatoxin limits that shape export eligibility for copra meal shipments, while Indonesia's national feed safety agency monitors equivalent mycotoxin thresholds for domestic compounders. ISO 22000 and HACCP certifications function as de facto market access requirements for EU and North American buyers. Stakeholders must monitor evolving deforestation-linked sourcing disclosure rules that threaten to recast coconut supply chain compliance costs.
Market Dynamics
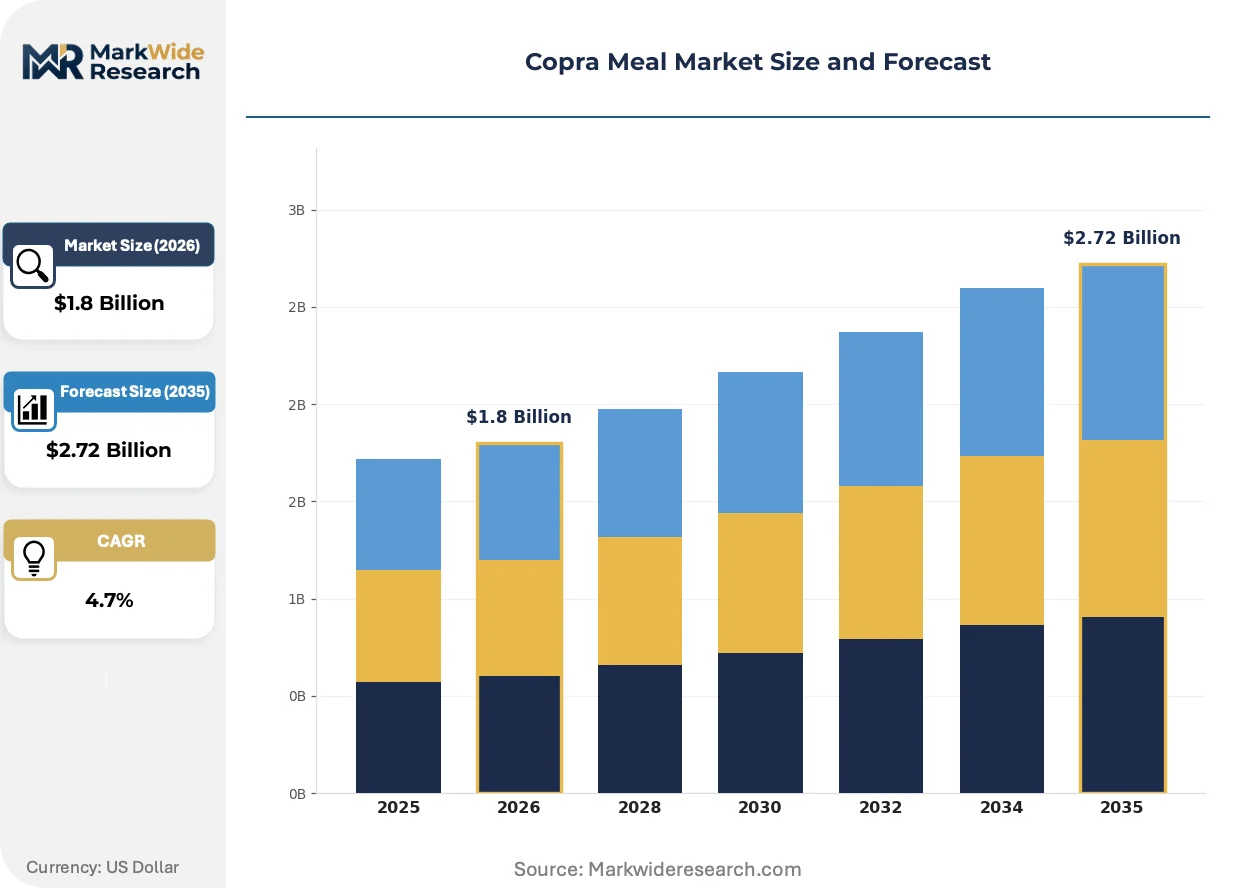
Coconut oil price volatility is restructuring procurement relationships across the copra meal value chain, forcing feed compounders to secure multi-origin supply contracts and laboratory-verified quality guarantees at Philippine and Indonesian crushing facilities.
Growth Catalysts
- FAO mycotoxin threshold tightening:Southeast Asian dairy farm operators are expanding copra meal inclusion rates in cattle rations as international feed safety standards harden aflatoxin limits, creating compliant demand pull from integrated compounders.
- Quezon Province processing cluster concentration:Mechanical crushing capacity expansion in the Philippines' coconut belt is shortening supply chains for regional feed manufacturers seeking origin-direct procurement.
- Circular economy residue valorization:Biofuel and organic fertilizer off-take channels are absorbing secondary copra meal streams as EU Green Deal frameworks incentivize agricultural waste-to-energy conversion pathways.
Market Restraints
- Coconut oil price volatility:Crude coconut oil futures fluctuations transmit directly to copra meal availability, forcing feed formulators to maintain costly buffer inventories against supply interruptions.
- Philippine-Indonesian supply concentration:Over 80% of exportable copra meal originates from two archipelagic nations exposed to typhoon disruption and port congestion risks.
- Soybean meal substitution elasticity:Ruminant nutritionists retain formula flexibility to displace copra meal with higher-protein alternatives when relative pricing inverts.
Strategic Opportunities
- EU deforestation-free sourcing mandates:Early compliance with emerging supply chain disclosure rules positions certified Philippine exporters for premium access to North European dairy nutrition markets.
- Aquaculture starter diet powder grades:Finely milled copra meal fractions are penetrating marine hatchery formulations as fishmeal cost pressures intensify across Southeast Asian shrimp farming zones.
- ISO 22000 certification arbitrage:Mid-sized Indonesian crushers investing in hazard analysis protocols capture price premiums from Japanese and South Korean compounders demanding documented safety systems.
Industry Challenges
- Mycotoxin testing capacity bottlenecks:Origin-point laboratory infrastructure shortages in remote Indonesian coconut processing districts delay export clearance timelines.
- Legacy feed mill handling equipment:Automated facilities designed for soybean meal flow characteristics require retrofit investment to process high-fiber copra meal pellets without bridging and segregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copra Meal Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meal, Cake, Pellets, Powder Application: Animal Feed, Fertilizers, Food Products, Biofuels Distribution Channel: Online Retail, Wholesale, Direct Sales, Feed Stores End User: Dairy Farms, Poultry Farms, Aquaculture, Livestock |
| Companies Covered | Samar Coco Products Manufacturing Corp., ADM Animal Nutrition, Cargill, Incorporated, Tantuco Enterprises Inc., Marico Limited, PT Indofood Sukses Makmur Tbk, CIIF OMG, PRIMA INDUSTRIES LTD., Ruchi Soya Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copra Meal Market Emerging Trajectories
Mechanical extraction efficiency gains and digital traceability platforms are compressing quality verification cycles, while regulatory disclosure requirements are rewriting supplier qualification protocols across destination markets.
Expeller-pressed copra meal with enhanced oil retention is unifying protein-energy supplementation for high-yielding dairy herds. Large-scale compounders in Vietnam and Thailand are adopting this grade at accelerating rates. The technology is unifying previously separate protein and energy ingredient slots in least-cost formulation software.
EU deforestation-linked sourcing disclosure rules are mandating geolocation verification for coconut plantation origins. Feed safety agencies in importing jurisdictions are cross-referencing satellite imagery against batch documentation. Philippine Bureau of Agriculture and Fisheries Standards auditors are expanding field inspection protocols to maintain EU market eligibility.
Direct mill-to-compounder contracting is displacing traditional broker-mediated procurement in major Southeast Asian feed manufacturing hubs. Tier-one nutrition firms are establishing quality-based pricing frameworks with named crushing facilities. This pattern concentrates most visibly in Luzon-based supply chains serving Metro Manila integrated livestock operations.
Copra Meal Market Segmentation
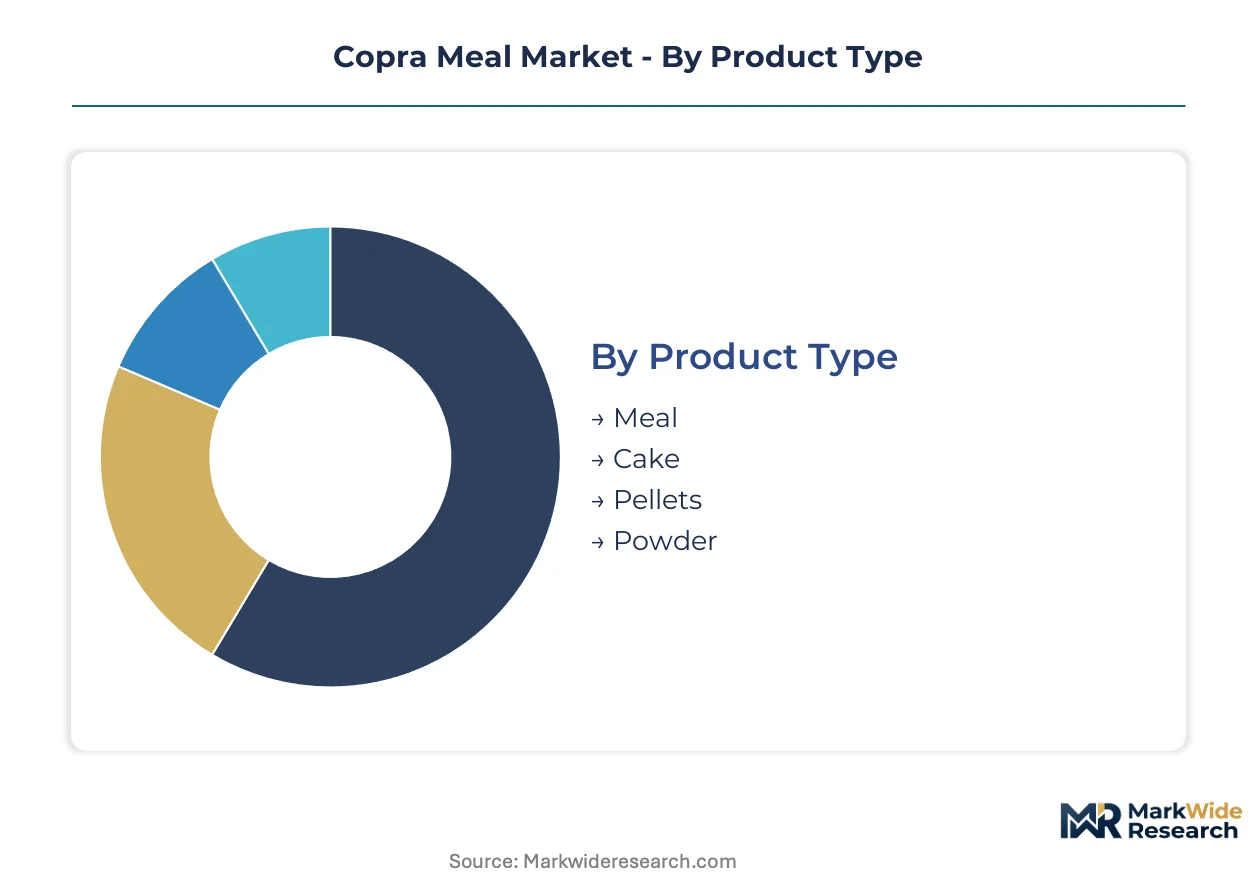
Copra meal segmentation reflects divergent processing intensities and end-use integration depths. Philippine crushing facilities calibrate output specifications to match feed mill automation requirements and regional agricultural waste valorization pathways.
Product Type:
Meal and pellet formats dominate automated handling systems, while cake and powder grades serve specialized nutrition and circular economy applications.
- Meal:Coarsely ground residual cake with 20-25% crude protein and 10-12% crude fiber content. Vietnamese and Thai compounders favor this grade for least-cost dairy ration formulations where mechanical flow properties align with legacy soybean meal handling infrastructure.
- Pellets:Densified meal fractions compressed to standard feed mill dimensions. Luzon-based integrated livestock operations specify this format to prevent bridging in pneumatic conveying systems and reduce dust exposure during automated batching.
- Cake:Unprocessed expeller-pressed slabs retaining higher residual oil. Indonesian artisanal crushers supply this grade to smallholder cooperatives for on-farm mixing.
- Powder:Finely milled fractions below 1mm particle size. Shrimp hatcheries in Vietnam's Mekong Delta specify this grade for larval starter diets.
Meal leads volumes today; powder is gaining share fastest.
Application:
Cost tier stratification separates commodity feed absorption from premium residue valorization channels.
- Animal Feed:Protein-energy supplementation for ruminant and monogastric formulations. Southeast Asian dairy cooperatives expand inclusion rates as FAO mycotoxin guidelines tighten compliance requirements for aflatoxin thresholds.
- Fertilizers:Organic soil amendment leveraging residual nitrogen and potassium. EU Green Deal bioeconomy incentives accelerate offtake from Philippine processors seeking circular economy certification.
- Food Products:Defatted flour fractions for gluten-free baking applications. Specialty mills in Metro Manila serve domestic health food distributors.
- Biofuels:Anaerobic digestion feedstock and biomass pellet inputs. Indonesian palm oil processors co-fire copra residues to meet renewable energy mandates.
Animal Feed anchors revenue today; Fertilizers show the steepest expansion trajectory.
Distribution Channel:
Customer type determines procurement modality, with volume scale dictating direct mill relationships versus intermediary dependence.
- Wholesale:Bulk tonnage transactions through agricultural commodity traders. Quezon Province crushing clusters transact primarily via this channel to serve regional feed compounders.
- Direct Sales:Named-account contracting between processors and integrated livestock operations. Tier-one Vietnamese nutrition firms negotiate quality-based pricing frameworks with Samar Coco Products Manufacturing Corp.
- Feed Stores:Bagged retail distribution to smallholder farmers. Provincial agricultural supply cooperatives in the Philippines' Bicol Region stock 25kg sacks for backyard poultry operations.
- Online Retail:E-commerce platforms connecting specialty organic fertilizer buyers with certified processors. Japanese home gardening distributors source through this channel.
Wholesale dominates tonnage today; Direct Sales is climbing the fastest.
End User:
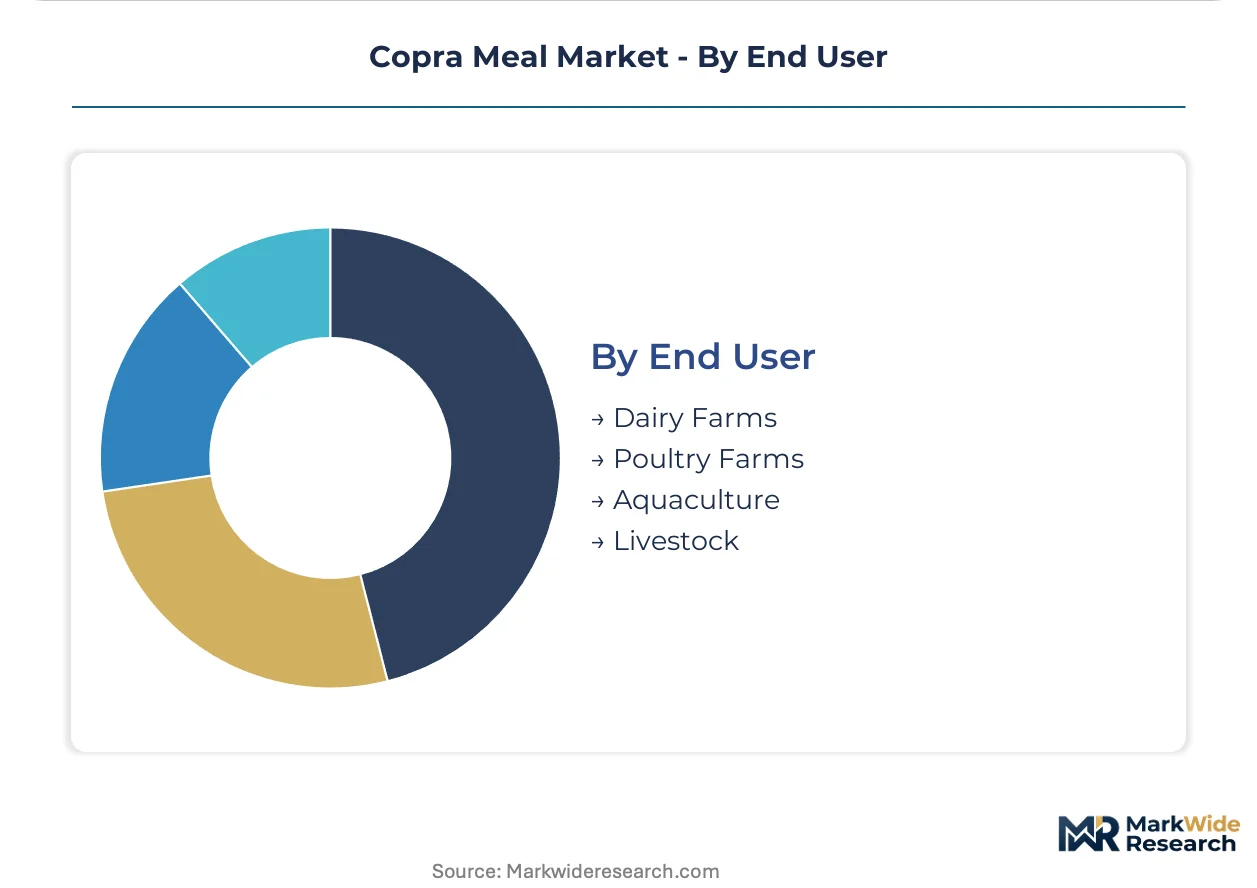
Geographic concentration of livestock production shapes demand patterns across archipelagic supply chains.
- Dairy Farms:High-yielding herd nutrition programs in Thailand's central plains specify expeller-pressed grades with enhanced oil retention for unified protein-energy supplementation.
- Poultry Farms:Layer and broiler operations throughout Indonesia's Java corridor absorb standard meal grades as cost-competitive protein alternatives to soybean meal.
- Livestock:Cattle fattening operations in the Philippines' Batangas Province utilize copra meal in backgrounding rations.
- Aquaculture:Marine hatchery and grow-out facilities. Shrimp farmers in Vietnam's Ca Mau Province trial powder-grade inclusion to displace fishmeal.
Dairy Farms lead absolute consumption today; Aquaculture is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quezon Province processing clusters anchor copra meal supply chains across Southeast Asia. Philippine crushing capacity expansion is shortening procurement distances for regional feed compounders. Indonesian and Vietnamese facilities are capturing secondary demand as coconut oil price volatility reshapes origin preferences.
Philippines
Dairy cooperatives in Batangas Province are expanding copra meal inclusion in high-yielding herd rations as FAO mycotoxin guidelines tighten compliance thresholds. The Bureau of Agriculture and Fisheries Standards enforces maximum aflatoxin limits that shape export eligibility for shipments to EU markets. Samar Coco Products Manufacturing Corp. leverages its Quezon-based crushing capacity to anchor Luzon supply chains serving Metro Manila integrated livestock operations.
Indonesia
Java corridor poultry farms absorb standard meal grades as cost-competitive protein alternatives to soybean meal in layer and broiler formulations. The national feed safety agency monitors mycotoxin thresholds for domestic compounders equivalent to Philippine standards. PT Indofood Sukses Makmur Tbk operates crushing facilities across archipelagic processing districts where laboratory infrastructure shortages delay export clearance timelines.
Vietnam
Shrimp hatcheries in Ca Mau Province trial powder-grade copra meal inclusion to displace fishmeal as marine protein costs intensify across Mekong Delta farming zones. Tier-one nutrition firms negotiate quality-based pricing frameworks directly with named crushing facilities. Direct mill-to-compounder contracting is displacing traditional broker-mediated procurement in Ho Chi Minh City feed manufacturing hubs.
Thailand
Central plains dairy operations specify expeller-pressed grades with enhanced oil retention for unified protein-energy supplementation in high-yielding herd nutrition programs. The Department of Livestock Development aligns domestic feed safety protocols with Codex Alimentarius standards. Bangkok-based compounders are adopting ISO 22000 certification requirements to capture price premiums from Japanese and South Korean buyers demanding documented safety systems.
India
Kerala and Karnataka coconut processing belts supply defatted flour fractions for domestic health food distributors serving gluten-free baking applications. FSSAI standards govern mycotoxin limits in feed-grade copra meal shipments interstate. Marico Limited and Ruchi Soya Industries Limited occupy positions within the specialty oilseed processing tier where circular economy residue valorization is absorbing secondary meal streams.
Copra Meal Market Vendor Landscape
Global majors compete with regional champions across quality verification and distribution reach in copra meal supply chains. The vendor base stratifies between integrated agricultural conglomerates with North American distribution networks and archipelagic crushing specialists with origin-direct procurement relationships. Three archetypes dominate: Philippine-Indonesian origin crushers with mechanical extraction capacity, multinational nutrition formulators with laboratory testing protocols, and diversified coconut oil processors with residue valorization capabilities. Capacity expansion at Quezon Province facilities and ISO 22000 certification investments at mid-sized Indonesian crushers represent the dominant competitive moves reshaping procurement relationships.
Within the archipelagic origin tier, Samar Coco Products Manufacturing Corp. and Tantuco Enterprises Inc. exemplify Philippine-based crushing specialists with Quezon Province facility concentrations. CIIF OMG occupies a position representing integrated coconut industry holdings with backward linkages to plantation supply bases. Among multinational nutrition formulators, ADM Animal Nutrition and Cargill, Incorporated anchor the quality-differentiated segment through laboratory-verified sourcing frameworks and North American distribution infrastructure for dairy nutrition applications.
| Leading Market Players |
|---|
| Samar Coco Products Manufacturing Corp. |
| ADM Animal Nutrition |
| Cargill, Incorporated |
| Tantuco Enterprises Inc. |
| Marico Limited |
| PT Indofood Sukses Makmur Tbk |
| CIIF OMG |
| PRIMA INDUSTRIES LTD. |
| Ruchi Soya Industries Limited |
| Others |
Supply Flow & Price Mechanics
Expeller-pressed extraction technology diffusion across Philippine and Indonesian crushing facilities is compressing processing costs while concentrating supply relationships around origin-direct procurement frameworks. This mechanical efficiency gain simultaneously reduces unit production economics and reinforces buyer dependence on Quezon Province and Java corridor processing clusters.
Pricing Analysis
Crude coconut oil futures fluctuations transmit directly to copra meal contract structures, forcing feed compounders to absorb margin volatility through buffer inventory costs. Price differentiation rests on ISO 22000 certification status and residual oil retention grades, with certified processors commanding premiums from Japanese and South Korean buyers. Cost compression in standard meal grades is intensifying because soybean meal substitution elasticity constrains pricing power. Smallholder cooperatives in Indonesia's outer islands exhibit highest price sensitivity, while EU dairy nutrition formulators demonstrate lowest sensitivity due to deforestation-free sourcing mandate compliance requirements.
Supply Chain Analysis
Inter-island freight costs and port congestion premiums structure procurement economics for archipelagic supply chains serving Southeast Asian feed manufacturing hubs. Raw material flows draw from Philippine Quezon Province, Indonesian Sulawesi and Java, and Indian Kerala processing belts, with coconut kernel quality varying by harvest season. Supply chain risk centers on typhoon disruption exposure across Philippine coastal crushing facilities. Distribution runs through wholesale commodity traders for regional compounders, while direct mill-to-compounder contracting gains share among tier-one Vietnamese and Thai nutrition firms.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Copra meal markets offer margin expansion pathways through certification-driven premium tier capture and mechanical extraction efficiency gains that compress per-unit processing costs. Feed safety compliance investments and circular economy residue valorization create defendable pricing power against commodity substitutes.
For Market Incumbents: Anchor procurement relationships through backward integration into Quezon Province crushing capacity and ISO 22000 certification investments at Indonesian facilities. Defend margin position against soybean meal substitution by locking multi-year offtake agreements with Vietnamese aquaculture hatcheries. Prioritize laboratory infrastructure deployment in remote Indonesian processing districts to clear export bottlenecks. For New Entrants and Emerging Players: Regional feed compounders in Vietnam's Mekong Delta represent the most penetrable channel partner type for powder-grade copra meal distribution. Target shrimp hatchery formulations in Ca Mau Province where fishmeal cost pressures intensify demand for marine protein alternatives. Enter through direct sales contracting with tier-one nutrition firms seeking quality-verified sourcing frameworks. For Investors and Strategic Acquirers: Roll-up economics work for mid-sized Indonesian crushers with HACCP certification gaps because laboratory infrastructure shortages create acquisition targets at discounted valuations. Five-to-ten-year viability hinges on EU deforestation-free sourcing mandate compliance penetration. Watch for Philippine Bureau of Agriculture and Fisheries Standards field inspection protocol expansions as inflection signal for export eligibility tightening.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22000 Certification Investment | Mid-sized Indonesian crushers capture Japanese and South Korean buyer premiums through documented safety systems. |
| Backward Integration into Crushing Capacity | ADM Animal Nutrition and Cargill secure origin-direct procurement relationships against coconut oil price volatility. |
| Powder Grade Production Expansion | Vietnamese shrimp hatcheries in Ca Mau Province displace fishmeal with finely milled copra meal fractions. |
| Laboratory Infrastructure Deployment | Remote Indonesian processing districts reduce export clearance delays through origin-point mycotoxin testing capacity. |
| EU Deforestation-Free Compliance Program | Philippine exporters maintain North European dairy nutrition market access through geolocation verification protocols. |
Methodological Framework
Coverage spans the Philippines, Indonesia, Vietnam, Thailand, and India, with primary inputs from each market through structured interviews with crushing facility operations managers, feed compounder procurement leads, dairy cooperative nutrition directors, aquaculture hatchery managers, and coconut oil processor residue traders. Secondary validation draws from Philippine Bureau of Agriculture and Fisheries Standards regulatory filings, Indonesian national feed safety agency guidelines, Vietnam Ministry of Agriculture and Rural Development trade statistics, FAO mycotoxin threshold documentation, and EU Green Deal bioeconomy framework disclosures. Bottom-up volume estimates from individual processing facilities triangulate against top-down demand assessments from regional feed manufacturing associations.
Granularity-level modeling disaggregates the analysis window by product type (meal, pellets, cake, powder), application (animal feed, fertilizers, biofuels), and end user (dairy farms, poultry farms, aquaculture). CAGRs derive from least-squares fitting of annual volume trajectories adjusted for coconut oil price elasticity coefficients and substitution cross-elasticities with soybean meal. Industry-specific forecast inputs include FAO mycotoxin guideline adoption timelines and EU deforestation-linked sourcing rule implementation phases.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to coconut oil futures volatility, typhoon frequency disruption patterns, and regulatory enforcement intensity across Philippine and Indonesian export jurisdictions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Asia-Pacific Ruminant Feed Market
Agricultural Commodities
Corn and Corn Starch Derivatives Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
Europe Feed Amino Acids Market
Agricultural Commodities
Vietnam Feed Concentrate and Basemix Market
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
Vietnam Compound Feed Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Cattle Feed Market
Agricultural Commodities
Growing Peat Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Soybean Derivatives Market
Agricultural Commodities
Peat Market
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market