
 Feed Yeast Market | 2026-2036
Feed Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Yeast Market Analysis
Subscription-based nutritional monitoring services is restructuring how feed yeast value gets captured, shifting revenue from bulk powder sales to ongoing diet optimization contracts. Alltech Inc. leverages its integrated gut health platforms to lock in multi-year livestock producer agreements. Lesaffre anchors European supply through specialized fermentation complexes in France and Belgium. Lallemand Animal Nutrition, Inc. competes on strain-specific probiotic-yeast combinations that command premium positioning in ruminant programs.
Feed yeast comprises Saccharomyces cerevisiae and related species cultivated through aerobic fermentation on molasses or grain-based substrates, then dried to specific viable cell counts for inclusion in compound feeds at 0.1-2.0% inclusion rates to improve fiber digestibility and gut microbiome stability. Active dry yeast dominates volume flows due to extended shelf stability and ease of blending into pelleted rations, while liquid yeast gains traction in large-scale aquaculture operations where on-farm dilution reduces handling costs. Nutritional yeast occupies the highest margin tier as specialty livestock producers seek beta-glucan and mannan-oligosaccharide enrichment for immune modulation.
The EU F-Gas Regulation and REACH framework constrain solvent and processing chemical inputs for yeast derivatives sold into European feed channels, while the FDA's Center for Veterinary Medicine oversees GRAS notifications for novel yeast strains entering US commercial rations. China's Ministry of Agriculture and Rural Affairs sets maximum allowable mycotoxin thresholds that effectively filter smaller fermentation operations from certified supply chains. Stakeholders must monitor evolving strain registration pathways and carbon intensity benchmarks that will determine which production geographies retain cost-competitive access to premium feed yeast segments.
Market Dynamics
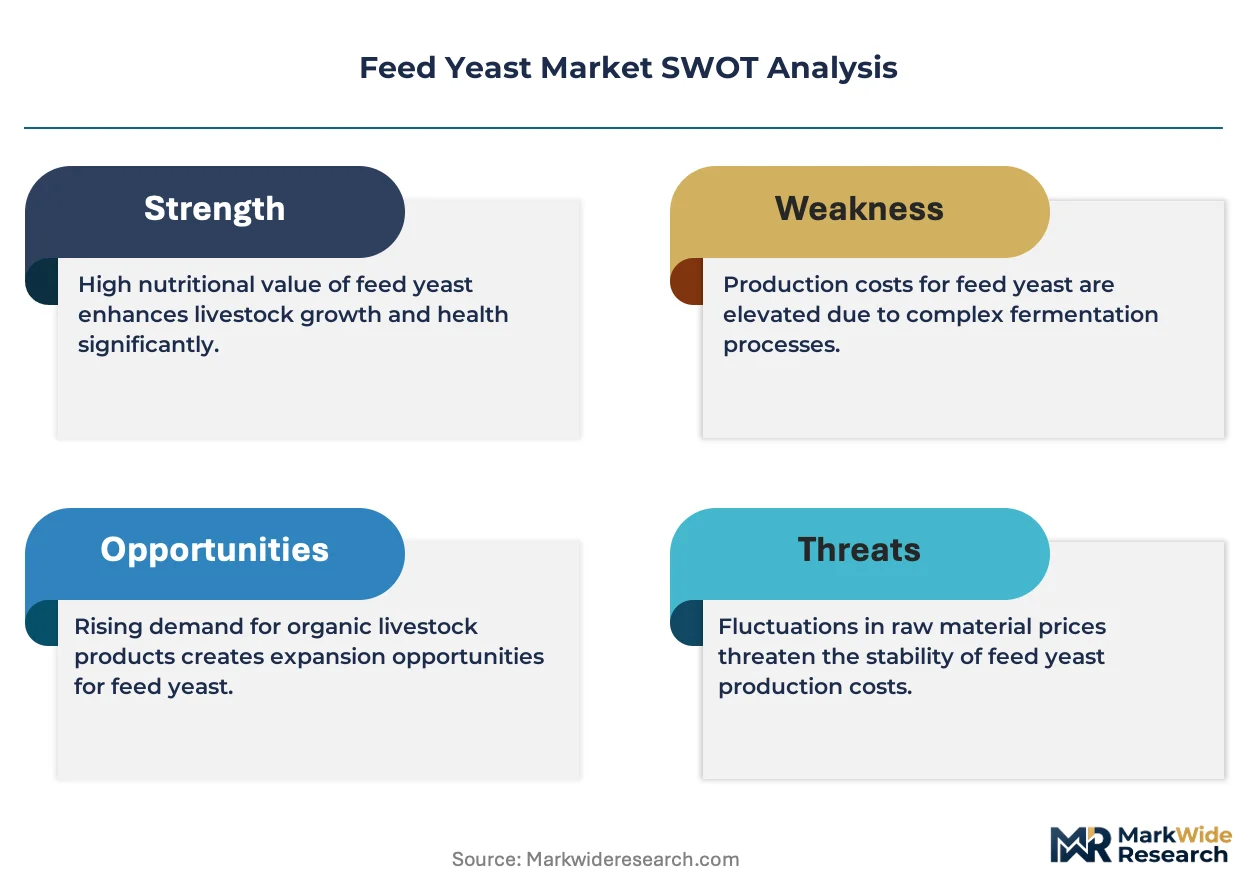
Fishmeal substitution mandates in aquaculture feed formulations are compressing substitution timelines and forcing fermentation capacity expansions across multiple geographies simultaneously.
Growth Catalysts
- Aquaculture feed substitution protocols:Fishmeal displacement targets in compound feed formulations are pulling Saccharomyces cerevisiae volumes into shrimp and salmon diets at accelerated inclusion rates.
- EU F-Gas Regulation compliance:Solvent recovery requirements for yeast derivative processing are filtering non-compliant fermentation operations from European supply chains, consolidating certified supplier positions.
- China's yeast protein promotion:The Ministry of Agriculture and Rural Affairs guidance on alternative protein inclusion in livestock rations is redirecting domestic molasses fermentation capacity toward feed-grade output.
Market Restraints
- Molasses input cost volatility:Sugar cane harvest fluctuations in Brazil and India transmit directly to substrate pricing, compressing margin stability for non-integrated fermentation operators.
- REACH framework chemical restrictions:Solvent and processing aid limitations for yeast cell wall derivative production add compliance overhead that smaller European facilities cannot absorb.
- Plant protein substitution threat:Pea and canola protein concentrate investments in aquaculture feed R&D divert formulation attention from yeast-derived alternatives in certain price-sensitive segments.
Strategic Opportunities
- Precision fermentation scale-up:Brazil's expanding sugar ethanol complex offers captive molasses supply for integrated yeast protein production serving Latin American livestock markets.
- Immune modulation application expansion:Beta-glucan enriched nutritional yeast for specialty poultry and swine producers commands formulation premiums in antibiotic-free certification programs.
- Carbon intensity benchmarking alignment:EU Green Deal farm-to-fork carbon accounting rules create competitive positioning for low-carbon intensity fermentation operations with renewable energy integration.
Industry Challenges
- Strain registration pathway complexity:FDA Center for Veterinary Medicine GRAS notification timelines for novel yeast strains extend commercialization cycles by 18-24 months.
- Fermentation specialist talent scarcity:Industrial microbiology and aerobic process engineering expertise concentrates with legacy suppliers, constraining new facility commissioning.
- On-farm dilution infrastructure requirements:Liquid yeast adoption in large-scale aquaculture demands capital investment in storage and dosing systems that smallholder operations cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Yeast Market |
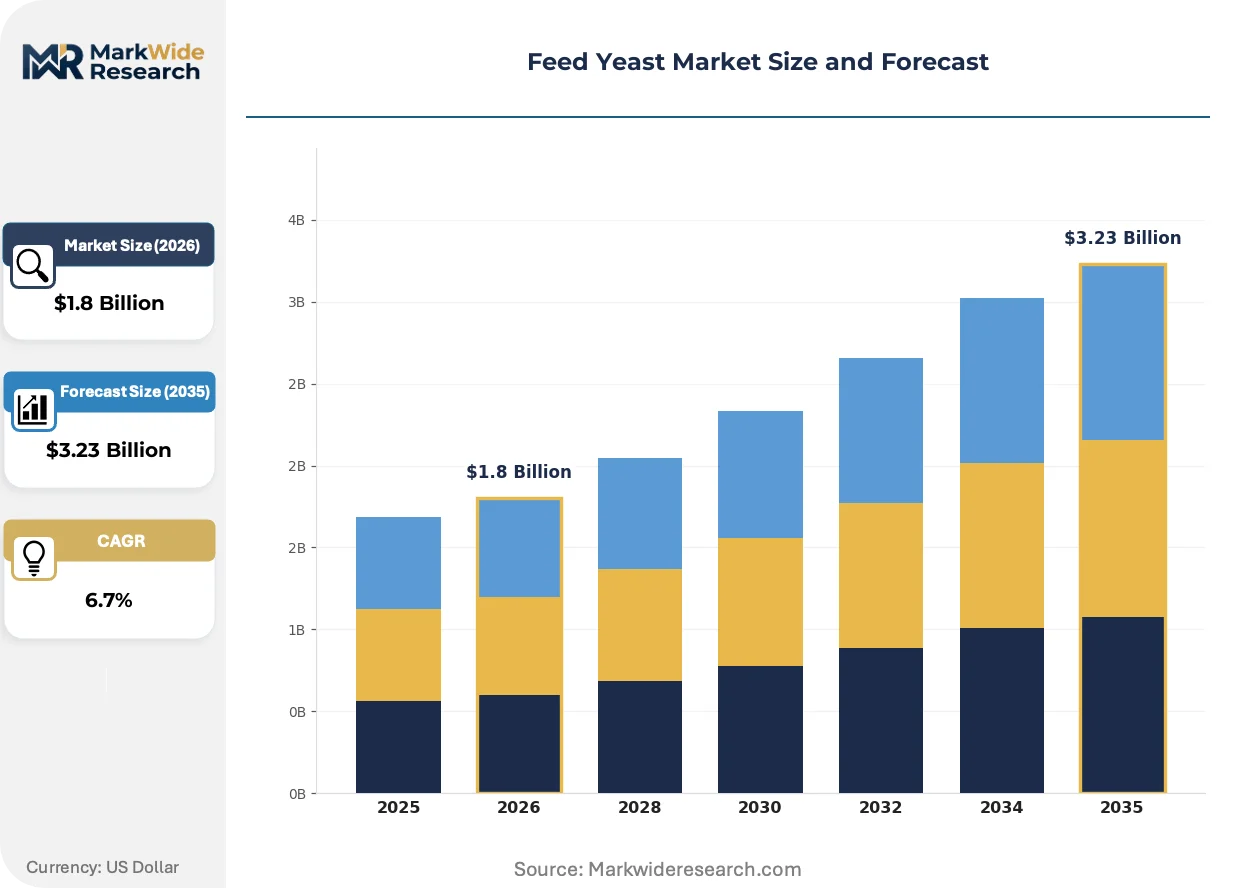
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Dry Yeast, Instant Yeast, Liquid Yeast, Nutritional Yeast Application: Poultry Feed, Ruminant Feed, Aquaculture Feed, Swine Feed Form: Powder, Granule, Pellets, Liquid End User: Farmers, Feed Manufacturers, Agribusiness, Livestock Producers |
| Companies Covered | Alltech Inc., Archer Daniels Midland Company, Lesaffre, Lallemand Animal Nutrition, Inc., Angel Yeast Co., Ltd, Cargill, Incorporated, Associated British Foods plc, Chr. Hansen A/S, DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Yeast Market Emerging Trajectories
Bioprocess intensification and regulatory carbon accounting are restructuring how feed yeast value gets captured, shifting competitive advantage toward integrated fermentation-energy complexes with strain-specific intellectual property.
Continuous fermentation monitoring through dissolved oxygen and biomass sensors is converging with automated nutrient feeding protocols to push viable cell counts beyond batch process limits. Large-scale aquaculture operations in Norway and Chile are piloting these systems to reduce on-farm yeast handling costs. The technology is converging with liquid yeast distribution models that bypass traditional dry yeast blending infrastructure entirely.
China's dual carbon goals are tightening energy intensity standards for industrial fermentation facilities, with the Ministry of Ecology and Environment (MEE) mandating renewable power quotas for new capacity approvals. Molasses-based yeast producers face retrofit requirements or geographic relocation to regions with grid decarbonization timelines. Facilities in Shandong and Guangdong provinces are responding with captive biogas generation from stillage residues.
Livestock producers are unbundling nutritional yeast purchases from compound feed contracts, establishing direct supply relationships with fermentation specialists for immune modulation ingredients. This disintermediation bypasses traditional feed mill intermediaries in North American and European ruminant programs. The pattern is most visible in organic dairy operations seeking beta-glucan certification for premium milk positioning.
Feed Yeast Market Segmentation
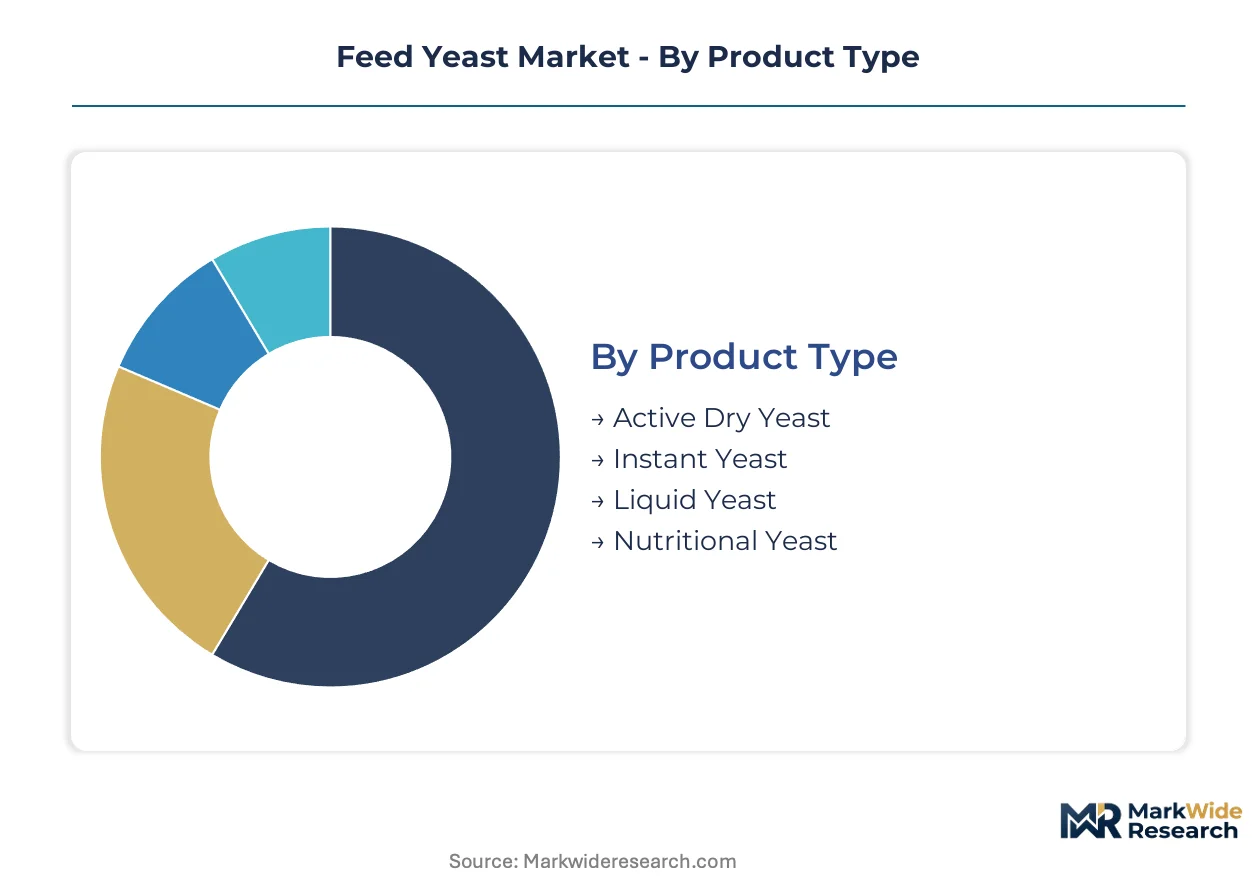
Feed yeast segmentation reflects divergent supply chain economics across preservation technologies, species-specific formulation requirements, and on-farm handling infrastructure. Product form and application targeting determine margin capture, with powder and liquid formats serving fundamentally different operational scales.
Product Type:
Upgrade cycles from active dry to nutritional yeast track livestock producer sophistication and certification program penetration.
- Active Dry Yeast:Dehydrated Saccharomyces cerevisiae with extended shelf stability and standardized viable cell counts, manufactured through batch fermentation followed by drum or fluidized bed drying. Poultry and swine compound feed mills in the US and Brazil concentrate procurement here, drawn by blending compatibility with pelleted rations and minimal cold chain requirements. The segment absorbs volume pressure from molasses cost volatility in major producing regions.
- Nutritional Yeast:Inactivated whole-cell yeast cultivated for elevated beta-glucan and mannan-oligosaccharide content, then pasteurized and dried for immune modulation applications. Specialty ruminant and organic dairy operations in France and Germany source directly from fermentation specialists, bypassing traditional feed mill intermediaries to secure antibiotic-free certification compliance. Premium positioning reflects strain-specific intellectual property and post-fermentation processing intensity.
- Instant Yeast:Rapid-rehydration dried yeast with reduced particle size for accelerated dissolution in liquid feed systems. Aquaculture hatcheries in Norway and Chile pilot adoption where on-farm mixing infrastructure supports immediate use protocols.
- Liquid Yeast:Non-dried fermentation broth with high viable cell density, distributed in bulk tanker configurations for on-farm dilution. Large-scale salmon and shrimp operations in Vietnam and Indonesia deploy capital-intensive storage and dosing systems to reduce per-unit handling costs.
Active dry yeast sits at the top of the volume ranking, with nutritional yeast climbing the fastest.
Application:
Cost tier differentiation separates commodity protein substitution from functional gut health targeting across livestock species.
- Aquaculture Feed:Fishmeal displacement protocols in shrimp and salmon diets pull Saccharomyces cerevisiae at inclusion rates exceeding traditional livestock applications. Norwegian and Chilean salmon producers integrate liquid yeast through continuous fermentation monitoring systems to optimize viable cell delivery. Regulatory pressure on marine ingredient sustainability accelerates formulation shifts.
- Ruminant Feed:Dairy and beef operations deploy yeast to stabilize rumen pH and fiber digestibility during high-grain feeding transitions. US and Brazilian feedlots concentrate demand where beta-glucan enriched nutritional yeast commands premiums in antibiotic-free certification programs. Direct supply relationships with fermentation specialists are disintermediating traditional compound feed channels.
- Poultry Feed:Broiler and layer operations prioritize active dry yeast for pelleted ration compatibility and extended storage in warm-climate distribution networks. Integration with coccidiosis management programs drives inclusion rate decisions.
- Swine Feed:Nursery and grower-finisher phases utilize yeast for gut microbiome stabilization during dietary transitions. Chinese commercial operations expand molasses fermentation capacity to serve domestic protein substitution mandates.
Aquaculture feed leads value concentration, while ruminant applications gain share fastest through premium nutritional yeast adoption.
Form:
Customer type determines handling infrastructure investment, separating integrated agribusiness from smallholder distribution economics.
- Powder:Fine particulate dried yeast with maximum surface area for rapid rehydration and homogeneous blending into mash feeds. Standard specification for poultry and swine compound feed manufacturers with automated batching systems.
- Liquid:Viable cell suspensions requiring refrigerated storage and precision dosing equipment. Aquaculture and large-scale dairy operations in Northern Europe and Southeast Asia absorb capital requirements for supply chain cost reduction.
- Granule:Agglomerated particles with controlled dissolution kinetics for ruminant total mixed rations. Dust reduction properties suit open-air feeding environments in Australian and Argentinian pasture systems.
- Pellets:Compressed yeast integrated with carrier substrates for direct feeding or minimal-processing inclusion. Niche application in smallholder poultry operations with limited mixing equipment.
Powder dominates manufacturing throughput, with liquid formats expanding most quickly in aquaculture integration.
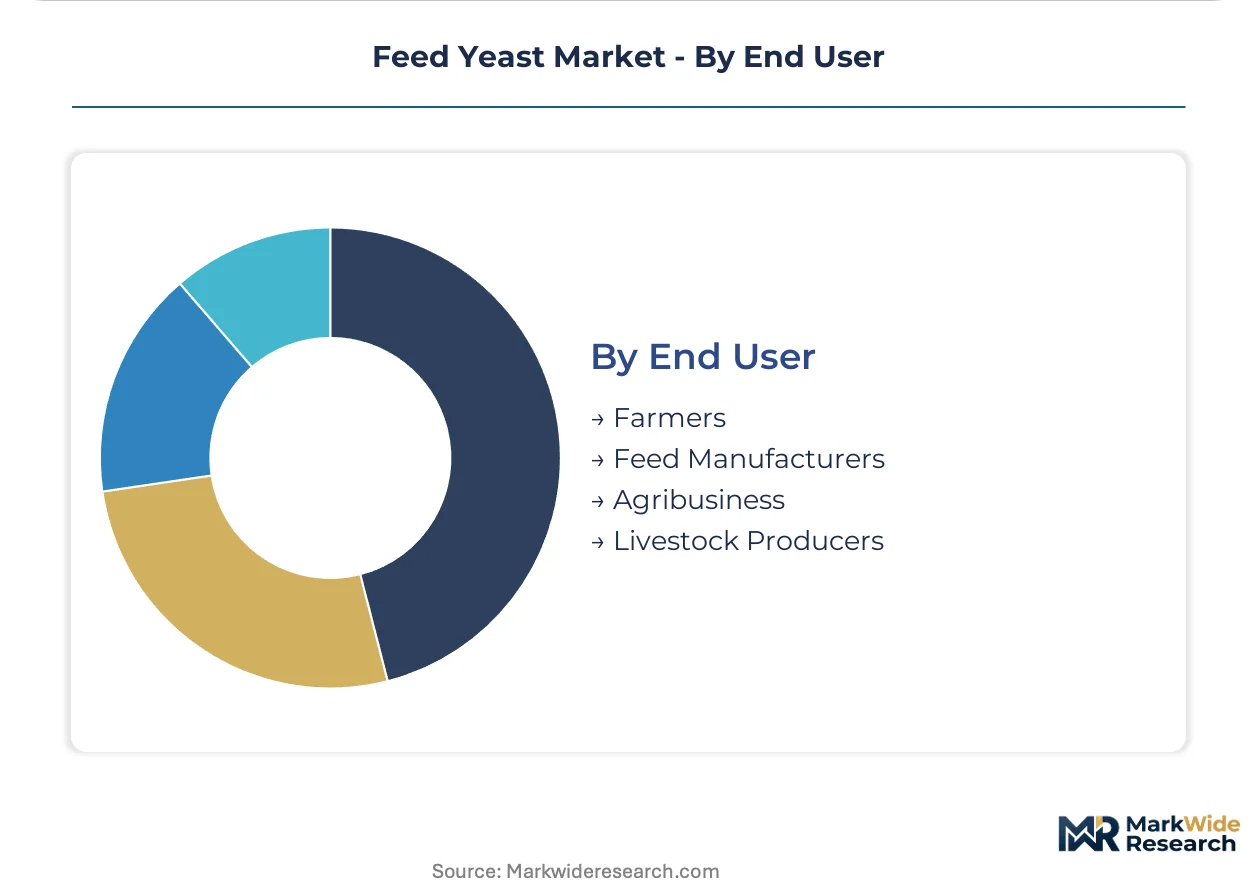
End User:
Supply concentration varies by procurement scale, with feed manufacturers consolidating volume and livestock producers capturing functional ingredient premiums.
- Feed Manufacturers:Compound feed mills integrate active dry yeast at 0.1-2.0% inclusion rates during pelleting operations, sourcing through long-term contracts with established fermentation suppliers. Brazilian and Chinese facilities prioritize molasses supply security in supplier selection.
- Livestock Producers:Specialty dairy and beef operations establish direct nutritional yeast procurement for immune modulation certification, particularly in organic and antibiotic-free market segments across North America and Western Europe.
- Agribusiness:Vertically integrated protein companies with captive feed milling capacity optimize yeast inclusion through in-house nutrition teams and precision feeding systems.
- Farmers:Smallholder poultry and swine operations access yeast through regional distributor networks, with price sensitivity favoring standard-grade active dry formulations over premium nutritional variants.
Feed manufacturers anchor volume procurement, with livestock producers driving margin expansion through direct specialty yeast sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting feed yeast fermentation capacity toward jurisdictions with lower carbon accounting burdens and subsidized molasses supply chains. Producers migrate to regions where compliance overhead and energy intensity standards create arbitrage opportunities for integrated operators.
China
Domestic aquaculture feed mills absorb expanding yeast protein volumes as the Ministry of Agriculture and Rural Affairs enforces alternative protein inclusion mandates. The Ministry of Ecology and Environment enforces renewable power quotas for new fermentation capacity approvals. Shandong and Guangdong province facilities retrofit with captive biogas generation from stillage residues to meet dual carbon goals.
United States
Ruminant feedlots and dairy operations drive nutritional yeast procurement for antibiotic-free certification programs. The FDA's Center for Veterinary Medicine oversees GRAS notification pathways for novel yeast strains entering commercial rations. Midwest compound feed manufacturers in Iowa and Illinois consolidate active dry yeast contracts through long-term supplier agreements.
Brazil
Integrated sugar-ethanol complexes offer captive molasses supply for yeast protein production serving Latin American livestock markets. ANVISA regulates feed additive safety assessments for imported yeast derivatives. São Paulo state fermentation facilities leverage proximity to cane processing infrastructure to reduce substrate logistics costs.
Germany
Specialty ruminant producers in Bavaria and Lower Saxony source beta-glucan enriched nutritional yeast directly from fermentation specialists. The EU F-Gas Regulation and REACH framework constrain solvent inputs for yeast cell wall derivative processing. Baden-Württemberg facilities absorb compliance overhead through scale advantages and integrated solvent recovery systems.
Norway
Salmon aquaculture operations deploy liquid yeast through continuous fermentation monitoring systems to optimize viable cell delivery. The country's national veterinary regulator enforces marine ingredient sustainability standards that accelerate fishmeal displacement. Coastal processing clusters around Bergen and Trondheim pilot automated nutrient feeding protocols for bioprocess intensification.
Feed Yeast Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in nutritional yeast contrasting fragmented supply for commodity active dry formulations. Three archetypes dominate: integrated fermentation-energy complexes with captive substrate supply, strain-specific probiotic-yeast specialists commanding premium positioning, and diversified agribusiness conglomerates leveraging feed distribution networks. Capacity expansion and direct supply relationship cultivation represent the dominant competitive moves, as producers bypass traditional feed mill intermediaries to capture immune modulation ingredient premiums.
Within the integrated fermentation tier, Lesaffre and Angel Yeast Co., Ltd anchor European and Asian supply respectively through specialized fermentation complexes. Lallemand Animal Nutrition, Inc. occupies a position among strain-specific specialists combining probiotic and yeast technologies for ruminant program differentiation. These three exemplify how geographic concentration of molasses supply and regulatory compliance capability determine competitive positioning across premium and standard product tiers.
| Leading Market Players |
|---|
| Alltech Inc. |
| Archer Daniels Midland Company |
| Lesaffre |
| Lallemand Animal Nutrition, Inc. |
| Angel Yeast Co., Ltd |
| Cargill, Incorporated |
| Associated British Foods plc |
| Chr. Hansen A/S |
| DSM |
| Others |
Supply Flow & Price Mechanics
Captive molasses supply through backward integration into sugar-ethanol complexes anchors both cost position and pricing power for Brazilian and Indian fermentation operators serving Latin American and Asian feed channels. This upstream control over substrate sourcing insulates integrated producers from sugar cane harvest volatility that compresses margins for non-integrated competitors dependent on spot molasses markets.
Pricing Analysis
Distributor margin compression in European feed channels intensifies as REACH compliance overhead filters smaller facilities from certified supply chains. Three-tier pricing structure across premium nutritional yeast, standard active dry formulations, and economy liquid variants tracks certification level and strain-specific intellectual property. Price differentiation hinges on immune modulation ingredient premiums in antibiotic-free dairy programs versus commodity protein substitution in aquaculture feed. Specialty ruminant producers in Germany and France exhibit lowest price sensitivity due to direct supply relationships with fermentation specialists, while smallholder poultry operations in Southeast Asia face acute cost pressure from molasses input volatility.
Supply Chain Analysis
Freight cost differentials between bulk liquid tanker distribution and dried powder container shipping reshape regional competitive boundaries for aquaculture and ruminant applications. Supply concentrates in Brazil, China, and France, with Brazilian facilities drawing from captive cane processing infrastructure and Chinese producers responding to Ministry of Ecology and Environment renewable power quotas. Raw material dependencies center on sugar cane molasses, grain-based fermentation substrates, and specialized nutrient feeds for strain cultivation. Single-source vulnerability runs through Brazilian molasses supply during El Niño harvest disruptions. Distribution runs through compound feed mill intermediaries for standard active dry yeast, with direct supplier-producer relationships capturing nutritional yeast premiums in organic certification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feed yeast fermentation capacity is migrating toward jurisdictions with subsidized molasses supply and lighter carbon accounting burdens, creating geographic-arbitrage returns for operators relocating from EU REACH-constrained facilities to Brazil's integrated sugar-ethanol corridor.
For Market Incumbents: Cement supply security through captive molasses offtake agreements with Brazilian and Indian sugar processors, insulating against substrate price spikes that threaten margin stability. Expand fermentation capacity in Shandong and Guangdong provinces to capture China's Ministry of Agriculture and Rural Affairs protein substitution mandates while retrofitting with biogas generation to meet Ministry of Ecology and Environment renewable energy quotas. Prioritize strain registration pathway investments to compress FDA Center for Veterinary Medicine GRAS notification timelines that currently extend commercialization cycles. For New Entrants and Emerging Players: Precision fermentation scale-up technology offers entry into immune modulation ingredient segments where beta-glucan enriched nutritional yeast commands formulation premiums in North American antibiotic-free certification programs. Target liquid yeast distribution for large-scale aquaculture operations in Vietnam and Indonesia, where on-farm dilution infrastructure requirements filter established competitors. Pursue direct supply relationships with specialty organic dairy producers, bypassing feed mill intermediaries that dominate standard active dry yeast channels. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap fermentation specialists with strain-specific intellectual property because regulatory compliance overhead and GRAS registration timelines create barriers that favor consolidated platforms with dedicated regulatory affairs capabilities. Focus acquisition screening on facilities with integrated solvent recovery systems and renewable energy sourcing that meet EU F-Gas Regulation and EU Green Deal carbon intensity benchmarks. Monitor fishmeal substitution mandate acceleration in Norwegian and Chilean salmon aquaculture as the signal indicating premium yeast protein demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Supply | Brazilian sugar-ethanol complexes reduce substrate logistics costs and insulate margin stability from harvest volatility. |
| Strain-Specific Probiotic-Yeast Combination Development | Lallemand's ruminant program differentiation commands premium positioning through intellectual property moats. |
| Captive Biogas Generation Installation | Shandong and Guangdong facilities meet China's MEE renewable power quotas while reducing energy cost exposure. |
| Direct Supply Relationship Cultivation | Organic dairy operations in France and Germany bypass feed mill intermediaries for immune modulation certification. |
| Liquid Yeast Distribution Infrastructure | Norwegian salmon operations deploy continuous fermentation monitoring to optimize viable cell delivery and reduce handling costs. |
Methodological Framework
Coverage spans China, Brazil, the United States, Germany, and Norway, with primary inputs from each market's fermentation specialists and downstream feed channel participants. The analysis combines interviews with plant managers at molasses-integrated facilities, procurement leads at compound feed manufacturers, regulatory affairs directors navigating FDA GRAS pathways, and technical R&D heads developing strain-specific applications. Secondary validation draws from EU F-Gas Regulation filings, REACH compliance disclosures, Chinese Ministry of Agriculture and Rural Affairs guidance documents, and Brazilian ANVISA feed additive safety assessments. Bottom-up capacity and production estimates triangulate against top-down demand modeling from aquaculture and livestock sector consumption data.
Rate-of-change decomposition separates volume growth drivers across product type tiers, application segments, and regional regulatory clusters. The analytical framework models segmentation dimensions including preservation technology, species-specific formulation requirements, end-user procurement scale, and carbon intensity benchmarking alignment. CAGRs derive from iterative reconciliation of supply-side capacity expansion announcements with demand-side inclusion rate assumptions in fishmeal substitution protocols and antibiotic-free certification programs. Industry-specific forecast inputs incorporate molasses price elasticity coefficients and fermentation energy intensity standards.
The model holds under stable regulatory compliance timelines and uninterrupted molasses supply from major producing regions; deviation in FDA GRAS notification duration or El Niño-driven Brazilian harvest shortfalls would shift capacity expansion trajectories and pricing power distributions. Forecasts reflect documented assumptions about strain registration pathway efficiency and renewable energy quota enforcement intensity. Stakeholders should weight assumptions against their own operating context and substrate sourcing security.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Roundwood Market
Agricultural Commodities
Corn Hydrolysate Market
Agricultural Commodities
Sod Peat Market
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
Bladderpod Oil Market
Agricultural Commodities
Corn and Corn Starch Derivatives Market
Agricultural Commodities
Feed Sucrose Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Market
Agricultural Commodities
North America Corn Glucose Market
Agricultural Commodities
Soybean Derivatives Market
Agricultural Commodities
Blood Meal Market