
 Cordial Drink Market | 2026-2036
Cordial Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Cordial Drink Market Analysis
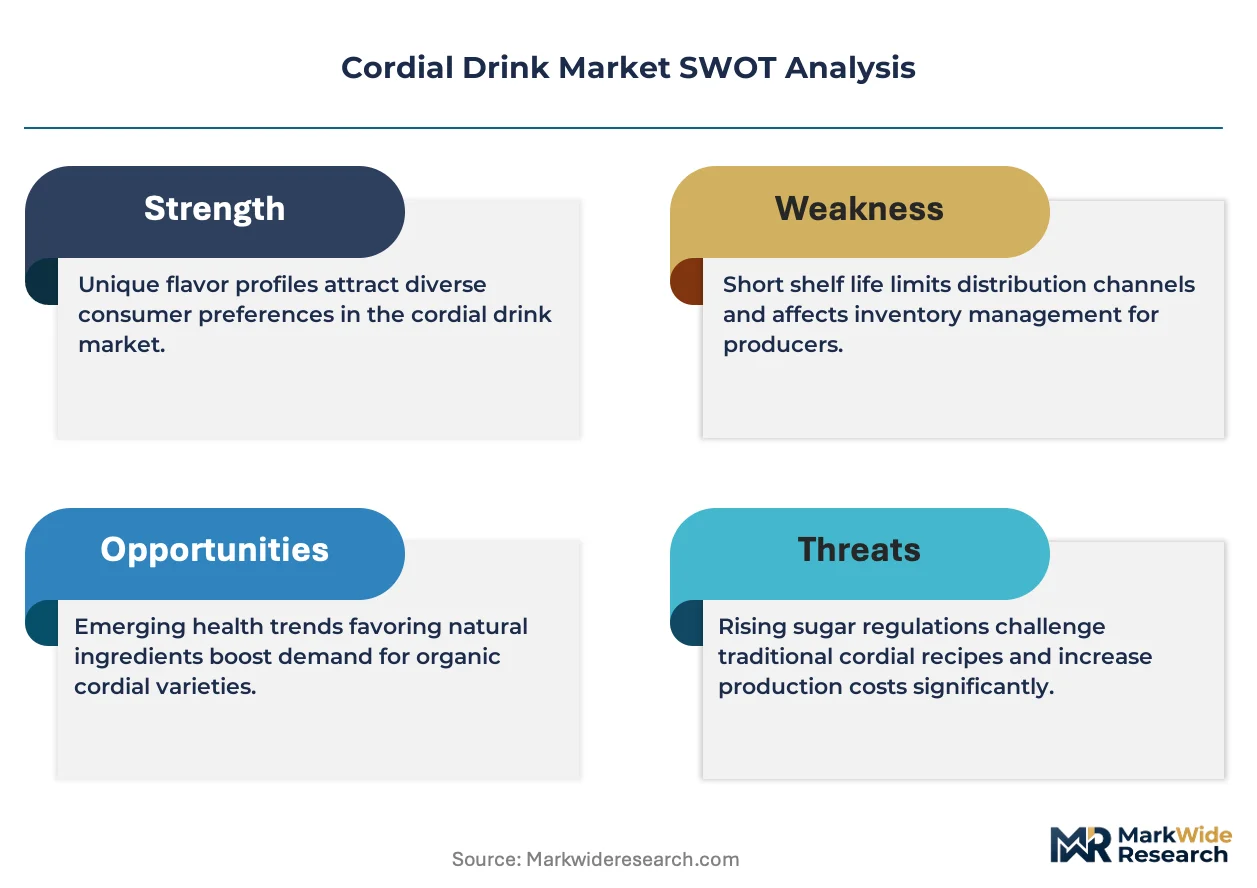
The gap between premium artisanal cordials and mass-market commodity concentrates is expanding in concrete terms of ingredient sourcing, retail pricing architecture, and channel placement. Britvic Plc anchors the mainstream UK segment through deep supermarket penetration and heritage brand equity. Monin Inc. differentiates through specialty foodservice channels with premium syrup positioning in cafes and cocktail bars. Nichols Plc competes in the mid-tier with regional flavor portfolios that leverage localized retail relationships.
Cordial drink denotes a non-alcoholic beverage concentrate, typically diluted with water at ratios between one-to-four and one-to-ten, containing fruit extracts, sweeteners, acidulants, and preservatives with shelf stability engineered through pasteurization or chemical preservation. Its primary commercial purpose centers on delivering flavored hydration at lower per-serve cost and transport weight than ready-to-drink alternatives. Fruit-based formulations occupy the mature volume core of the market, while sparkling cordials represent the fastest-growing structural segment as younger consumers migrate from conventional carbonates. Distribution through supermarkets captures the bulk of household purchasing, though online channels are deepening penetration in subscription-based repeat buying for premium and herbal variants.
FDA oversight of food additive safety and labeling requirements shapes product composition and market access for US-manufactured cordials, while EU REACH and F-Gas Regulation frameworks govern flavor chemical registrations and processing equipment emissions that affect production economics. The EU Green Deal's packaging waste directives are accelerating shifts toward concentrated formats that reduce plastic bottle counts per consumer serving. Stakeholders must monitor evolving sugar taxation regimes and natural claim enforcement standards as these regulatory vectors increasingly determine which product architectures sustain profitability versus face reformulation costs.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing plastic bottle counts per serving and forcing concentrated format innovation across manufacturing footprints. Reformulation costs from natural extract mandates are redistributing margin structures between heritage brands and private-label entrants.
Growth Catalysts
- EU F-Gas Regulation:Equipment emissions standards are accelerating investment in low-carbon pasteurization systems that reduce energy intensity in fruit processing facilities.
- Café channel expansion:Specialty coffee shops in London and Melbourne are building cordial-based signature beverage programs that elevate concentrate visibility among younger demographics.
- Natural acidulant substitution:Citric acid from fermented agricultural feedstock is displacing synthetic variants in clean-label formulations targeting German and French retail shelves.
Market Restraints
- Sugar taxation regimes:UK Soft Drinks Industry Levy and similar frameworks in Ireland and Portugal are compressing margins on traditional high-sugar squash formulations.
- Concentrate supply concentration:Blackcurrant and elderberry extract sourcing clusters in Eastern European processing facilities create weather-dependent input volatility.
- Carbonated substitute competition:Flavored sparkling water systems from SodaStream and competing countertop devices are capturing household dilution occasions.
Strategic Opportunities
- Subscription channel penetration:Direct-to-consumer platforms in the United Kingdom are capturing repeat purchasing for premium herbal variants with personalized flavor profiling.
- Functional ingredient convergence:Adaptogenic botanicals and nootropic compounds are creating new occasion-based positioning in Australian and New Zealand wellness retail.
- EU packaging waste directive tailwinds:Refillable glass concentrate formats qualify for extended producer responsibility credits in French and Belgian circular economy frameworks.
Industry Challenges
- Natural preservation expertise scarcity:Food technologists with pasteurization optimization skills for reduced-chemical stability are concentrated in legacy beverage manufacturing regions.
- Clean-label certification timelines:Organic and natural claim verification through Soil Association and EU organic frameworks extends new product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cordial Drink Market |
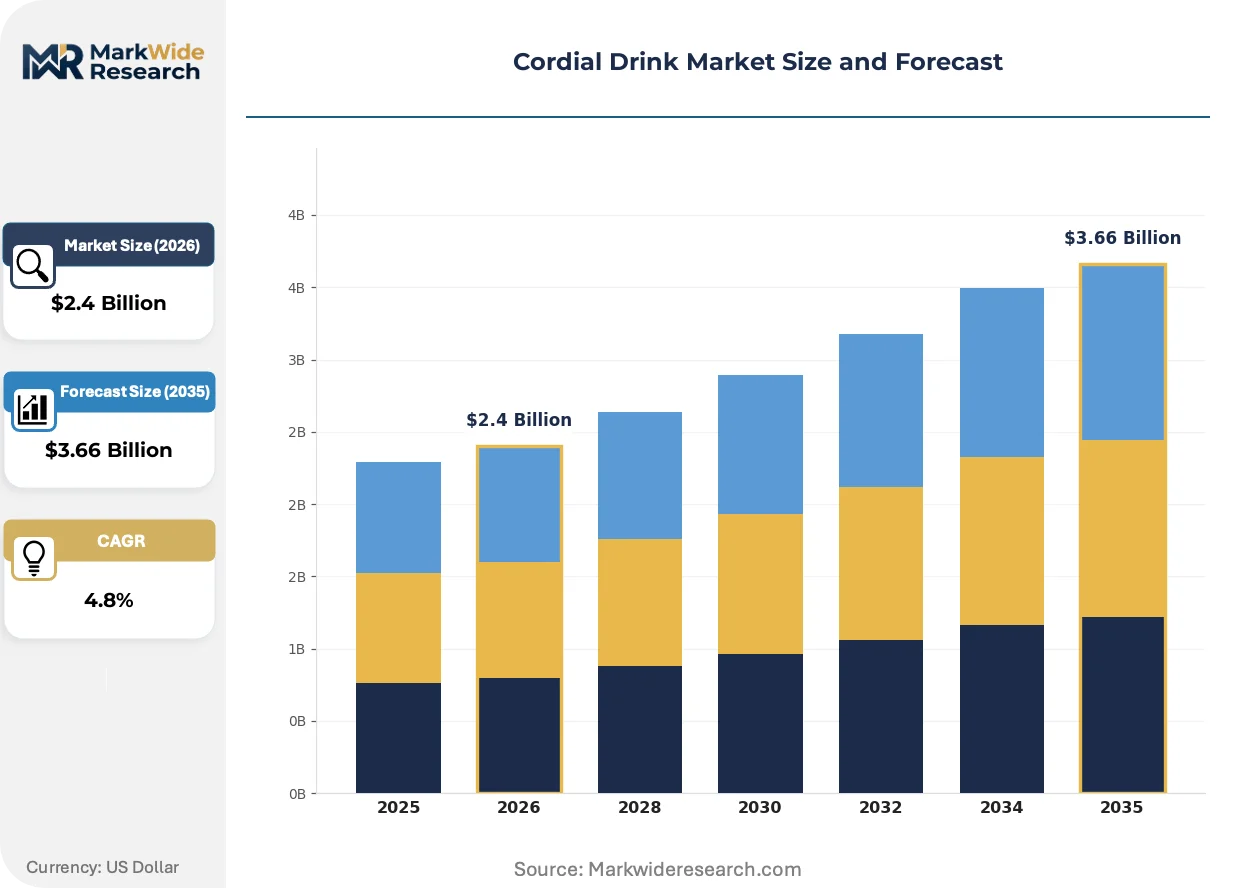
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit-Based, Herbal, Concentrated, Sparkling Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Stores Flavor Profile: Citrus, Berry, Tropical, Spiced End User: Households, Restaurants, Cafes, Catering Services |
| Companies Covered | Rasna Private Limited, PepsiCo Inc., Britvic Plc, Monin Inc., AG Barr Plc, The Coca-Cola Company, Nichols Plc, Asahi Beverages, Bickford's Australia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordial Drink Market Emerging Trajectories
Cold-pressed extraction methods and ambient-stable natural preservation systems are redrawing technical boundaries between premium artisanal and mass-market production economics. Regulatory packaging mandates and shifting hydration occasions are simultaneously compressing legacy formats and opening white space for functional positioning.
High-pressure processing technology is absorbing pasteurization duties previously handled by thermal treatment, preserving volatile aromatic compounds in citrus and berry concentrates. Premium cordial manufacturers in the United Kingdom and Australia are adopting HPP lines at scale, enabling shorter ingredient lists without sacrificing shelf stability. This shift is absorbing capital expenditure from flavor house R&D budgets and compressing the technical gap between small-batch and industrial production.
REACH chemical registration requirements for novel flavor compounds are extending approval timelines for synthetic alternatives and tilting formulation strategies toward GRAS-status natural extracts. ECHA documentation burdens are particularly acute for mid-tier manufacturers lacking dedicated regulatory affairs capacity. The United Kingdom and German markets are responding with accelerated partnerships between concentrate producers and established flavor houses that maintain pre-validated natural ingredient libraries.
Restaurant procurement is consolidating around single-source beverage programs that bundle cordial concentrates with dispensing equipment and staff training protocols. Group purchasing organizations in the United Kingdom hospitality sector are displacing fragmented supplier relationships with category management contracts. This concentration is most visible in London and Manchester metropolitan clusters where multi-site operators standardize across 15-40 unit estates.
Cordial Drink Market Segmentation
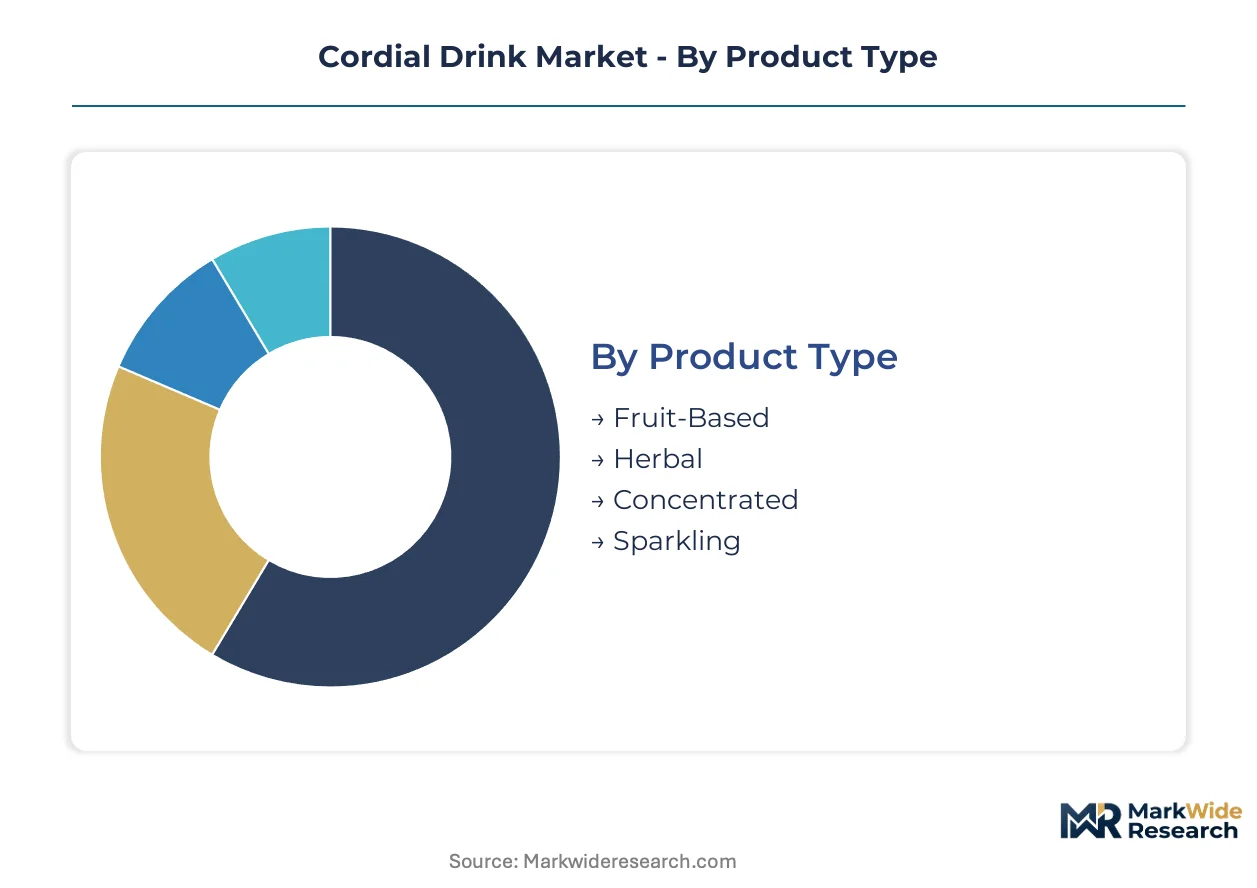
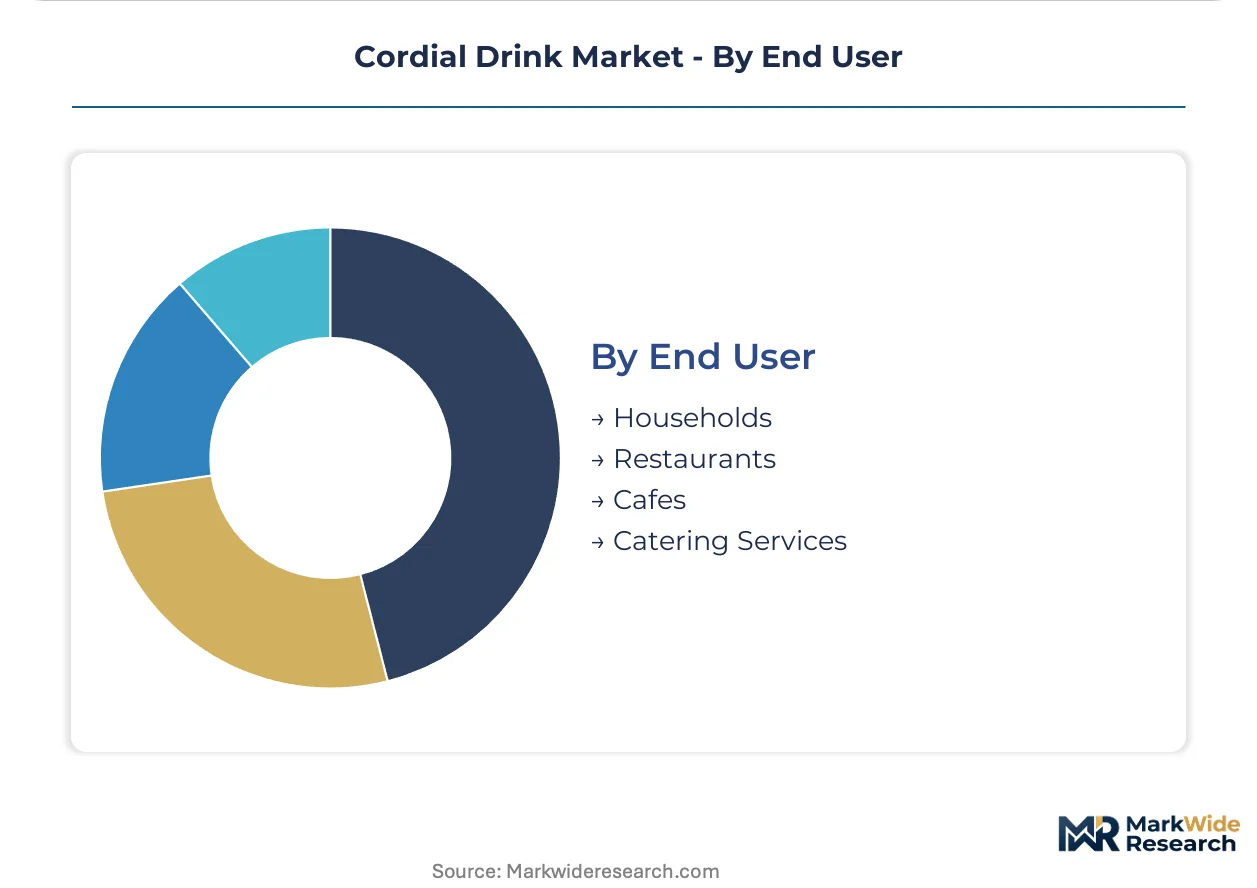
Cordial drink segmentation reveals divergent margin architectures across product formats and channel economics. Concentrated formats command premium shelf positioning in subscription channels while mass-market dilutables dominate supermarket volume throughput.
Product Type:
Volume concentrates in traditional dilutable formats while premium innovation clusters around carbonated and botanical variants.
- Fruit-Based:Formulations built on citrus, berry, and orchard fruit extracts constitute the mature volume core of household purchasing. UK supermarkets move these SKUs through high-velocity shelf placements where dilution ratios of one-to-four drive repeat restocking cycles.
- Herbal:Botanical infusions featuring elderflower, mint, and chamomile extracts target wellness-positioned consumers in Australian and New Zealand retail. These variants carry extended development timelines under Soil Association organic verification frameworks.
- Concentrated:Reduced-water formats minimize transport weight and packaging waste per serving, qualifying for EU Green Deal extended producer responsibility credits in French circular economy schemes.
- Sparkling:Carbonated cordials are gaining share fastest among younger demographics migrating from conventional soft drinks, with London and Melbourne cafes building signature beverage programs around these formats.
Mature deployment sits with Fruit-Based formulations. Newer deployment is concentrated in Sparkling variants.
Distribution Channel:
Channel selection determines margin capture and consumer relationship depth, with digital platforms disrupting legacy supermarket dominance.
- Supermarkets:Tesco, Sainsbury's, and Waitrose anchor household replenishment through heritage brand facings and promotional calendar integration. These channels absorb the bulk of volume but compress net margins through slotting fee structures and private-label substitution pressure.
- Online:Direct-to-consumer platforms capture repeat purchasing for premium herbal variants with personalized flavor profiling and subscription-based replenishment models.
- Convenience Stores:Impulse-oriented smaller formats serve immediate consumption occasions in transit hubs and petrol station forecourts.
- Specialty Stores:Delicatessens and farm shops curate artisanal cordial portfolios for gift-oriented purchasing and regional provenance signaling.
Volume leadership rests with Supermarkets. Margin expansion concentrates in Online channels.
Flavor Profile:
Flavor selection maps to occasion-based consumption patterns and seasonal demand cycles across retail and foodservice.
- Citrus:Lemon and orange concentrates dominate summer hydration occasions through dilution versatility and perceived refreshment intensity. Blackcurrant sourcing clusters in Eastern European processing facilities create input volatility for berry formulations.
- Berry:Blackcurrant, raspberry, and elderberry extracts anchor traditional UK squash consumption with deep household penetration.
- Tropical:Mango, passion fruit, and pineapple variants target younger demographics and multicultural household preferences in urban UK markets.
- Spiced:Ginger, cinnamon, and clove formulations occupy winter seasonal positioning and mixer applications in cocktail bars.
Established demand centers on Citrus and Berry profiles. Emerging positioning clusters around Spiced variants for mixology applications.
End User:
End-user segmentation separates household replenishment economics from foodservice procurement concentration.
- Households:Family-oriented purchasing drives volume through multi-liter bottle formats and dilution-based cost efficiency. UK households maintain weekly replenishment rhythms for traditional squash consumption.
- Restaurants:Group purchasing organizations in UK hospitality are consolidating supplier relationships around category management contracts bundling concentrates with dispensing equipment.
- Cafes:Specialty coffee shops in London and Melbourne metropolitan clusters are building cordial-based signature beverage programs that elevate concentrate visibility.
- Catering Services:Event and institutional foodservice procurement prioritizes ambient-stable concentrates with extended shelf life for inventory flexibility.
Volume concentration remains with Households. Premium positioning and innovation investment flows toward Cafes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London anchors the cordial drink industry's commercial gravity through its dense network of specialty cafes and restaurant procurement headquarters that set beverage program standards across the United Kingdom and export markets.
United Kingdom
Traditional squash consumption drives household replenishment rhythms through Tesco and Sainsbury's high-velocity shelf placements. The UK Soft Drinks Industry Levy compresses margins on high-sugar formulations while accelerating reformulation toward reduced-sugar variants. Britvic Plc and Nichols Plc maintain manufacturing footprints in the Midlands and North England that supply heritage brand distribution.
Germany
Clean-label demand from wellness-positioned consumers concentrates in Berlin and Hamburg metropolitan retail corridors. ECHA REACH documentation requirements for flavor compound registrations extend new product development timelines and favor partnerships with established flavor houses. Bavarian and Baden-Württemberg processing facilities specialize in natural acidulant fermentation from agricultural feedstock.
Australia
Specialty coffee shops in Melbourne and Sydney metropolitan clusters build cordial-based signature beverage programs that elevate concentrate visibility among younger demographics. TGA food additive oversight shapes import compliance for US and European concentrate suppliers. Asahi Beverages and Bickford's Australia anchor production capacity in Victoria and New South Wales.
France
EU Green Deal packaging waste directives accelerate refillable glass concentrate formats that qualify for extended producer responsibility credits in circular economy frameworks. ANSM natural claim enforcement standards pressure reformulation toward verified organic extracts. Paris and Lyon hospitality procurement consolidates around category management contracts bundling concentrates with dispensing equipment.
United States
FDA food additive safety and labeling requirements govern product composition for US-manufactured cordials accessing foodservice and retail channels. PepsiCo Inc. and The Coca-Cola Company leverage national beverage distribution networks that penetrate convenience store and supermarket channels. California and New York metropolitan markets concentrate premium and functional variant demand.
Cordial Drink Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered market structure that separates integrated concentrate manufacturers from brand licensors and private-label specialists. The vendor base fragments across three strategic archetypes: heritage brand owners with deep supermarket penetration, premium syrup specialists targeting foodservice channels, and regional flavor portfolio players leveraging localized retail relationships. Dominant competitive moves include portfolio diversification into functional botanical variants and strategic partnerships with flavor houses to compress clean-label certification timelines.
Within the heritage brand tier, Britvic Plc and Nichols Plc occupy positions that exemplify mainstream UK market anchoring through supermarket channel dominance and regional flavor portfolio depth. Monin Inc. represents the premium foodservice specialist archetype with positioning in cafes and cocktail bars that elevates concentrate visibility among younger demographics. Rasna Private Limited sits within the emerging market expansion archetype, leveraging private company structure to penetrate price-sensitive household segments in South Asian markets.
| Leading Market Players |
|---|
| Rasna Private Limited |
| PepsiCo Inc. |
| Britvic Plc |
| Monin Inc. |
| AG Barr Plc |
| The Coca-Cola Company |
| Nichols Plc |
| Asahi Beverages |
| Bickford's Australia |
| Others |
Supply Flow & Price Mechanics
Blackcurrant concentrate price indices from Eastern European processing facilities cascade through three-tier pricing structures across premium, standard, and economy levels, compressing margins on heritage formulations while concentrating margin capture in refillable glass formats qualifying for French extended producer responsibility credits.
Pricing Analysis
Dilution-to-yield ratios anchor value-based pricing, with premium artisanal variants commanding shelf positioning through one-to-ten concentration efficiency versus mass-market one-to-four dilutables. Certification grade under Soil Association organic frameworks and volume scale through supermarket promotional calendars drive price differentiation between tiers. Cost compression in high-sugar formulations intensifies because UK Soft Drinks Industry Levy exposure erodes legacy margin structures. Price-sensitive household replenishment segments in UK supermarkets absorb promotional pressure, while least-sensitive cafe channel buyers prioritize signature beverage program differentiation over per-liter cost.
Supply Chain Analysis
Refillable glass return flows through French and Belgian circular economy frameworks are compressing plastic bottle counts per serving and redirecting capital toward ambient-stable natural preservation infrastructure. Blackcurrant and elderberry extraction clusters in Poland and Bulgaria, combined with citrus processing concentration in Spain and Italy, create weather-dependent input volatility for berry formulations. Single-source vulnerability in Eastern European concentrate supply exposes manufacturers to frost damage and harvest variability. Distribution runs through supermarket replenishment rhythms in UK households, with direct-to-consumer subscription platforms deepening penetration for premium herbal variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cordial drink manufacturing is becoming a vertical-integration race, with upstream control over natural acidulant fermentation from agricultural feedstock emerging as the decisive cost lever separating sustainable margin structures from reformulation-burdened competitors.
For Market Incumbents: Deepen backward integration into blackcurrant and elderberry processing clusters in Poland and Bulgaria to offset weather-dependent input volatility threatening heritage squash formulations. Secure dedicated capacity at Bavarian natural acidulant fermentation facilities before REACH documentation burdens extend new product development timelines for mid-tier competitors lacking regulatory affairs capacity. For New Entrants and Emerging Players: Australian wellness retail buyers seeking adaptogenic botanical convergence represent the most penetrable white-space target, with TGA food additive oversight creating compliance moats against underprepared international suppliers. Melbourne and Sydney cafe channel procurement consolidation around category management contracts offers a bundled go-to-market angle combining concentrate supply with dispensing equipment and staff training protocols. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier regional flavor portfolio players in UK and German markets facing Soil Association certification timeline compression and sugar taxation margin erosion. Long-term viability across the projection horizon hinges on natural preservation expertise scarcity concentration in legacy beverage manufacturing regions. Monitor EU Green Deal packaging waste directive implementation velocity in France and Belgium as the inflection indicator for refillable glass format economics tipping toward mainstream adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Extract Processing | Captive supply of blackcurrant concentrate from Polish facilities insulates against Eastern European weather volatility. |
| Direct-to-Consumer Subscription Launch | Online channel penetration captures repeat purchasing for premium herbal variants with personalized flavor profiling. |
| High-Pressure Processing Capacity Addition | HPP technology adoption at UK and Australian scale preserves volatile aromatic compounds without thermal degradation. |
| Refillable Glass Format Transition | Extended producer responsibility credits in French circular economy frameworks offset packaging cost premiums. |
| Clean-Label Certification Investment | Soil Association organic verification accelerates partnership access with established flavor houses maintaining pre-validated libraries. |
Methodological Framework
Trade journals, customs records, and EU regulatory filings formed the secondary backbone, supplemented by primary interviews with beverage brand managers, supermarket category buyers, flavor house technical directors, and foodservice procurement leads at UK hospitality group purchasing organizations. Bottom-up and top-down triangulation validated volume estimates against Nielsen retail audit data and ECHA REACH registration databases.
Bottom-up modeling built category projections from individual SKU velocity through Tesco, Sainsbury's, and Waitrose shelf placements, while top-down analysis cross-checked against aggregate soft drinks industry levy revenue disclosures. Segmentation dimensions included product format concentration ratios, distribution channel margin structures, flavor profile occasion mapping, and end-user procurement concentration across household replenishment versus cafe signature programs. CAGRs derived from trend extrapolation of dilution occasion migration from carbonated soft drinks and natural claim enforcement acceleration.
Revisions become necessary when EU Green Deal packaging directive enforcement timelines accelerate, sugar taxation regimes expand beyond UK-Ireland-Portugal clusters, or blackcurrant harvest failures in Eastern Europe trigger concentrate supply shocks. Practitioners should monitor Soil Association certification queue lengths and HPP equipment manufacturer order backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Italy Alcohol E-Commerce Market
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Liquor Flavored Ice Cream Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Wine Destemmer Market
Alcoholic Beverages
Beer Glass Chillers Market
Alcoholic Beverages
Brazil Alcohol E-Commerce Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Mini Brew Fermenter Market
Alcoholic Beverages
Uganda Spirits Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Cider Market
Alcoholic Beverages
Europe Tequila Market