
 Australia and New Zealand Tequila Market | 2026-2036
Australia and New Zealand Tequila Market Size, Share, and Industry Trends Forecast 2026-2036
Australia and New Zealand Tequila Market Insights
Premium bar and restaurant pour revenue is reconfiguring margin pools across the Australia and New Zealand tequila value chain. Patrón Spirits Company leverages its agave sourcing discipline to sustain price authority in high-end Sydney venues. Jose Cuervo anchors volume throughput through broad off-trade distribution networks spanning both countries. Beam Suntory differentiates via aged expression portfolios that command shelf space in Melbourne's premium liquor retail.
Tequila denotes a distilled spirit manufactured exclusively from blue Weber agave in designated Mexican states, with alcohol content typically ranging between 35% and 55% ABV depending on classification and export destination. The spirit serves commercial beverage applications spanning neat consumption, cocktail base preparation, and luxury gifting across hospitality and retail channels. Blanco expressions lead volume throughput due to lower production cycle requirements and accessible price positioning, while Añejo and Extra Añejo categories capture disproportionate margin pools as aged stock accumulates scarcity value. On-Trade distribution channels concentrate premium pricing power in Melbourne and Auckland's cocktail-dense precincts, whereas Online Retail accelerates trial among customer segments outside major metropolitan cores.
FSANZ mandates strict country-of-origin labeling and alcohol content disclosure for all imported spirits entering Australian retail, while New Zealand's Commerce Commission enforces parallel standards under the Fair Trading Act. TGA border inspection protocols for beverage alcohol imports add compliance layers that filter smaller Mexican distillers from direct market access. Stakeholders must monitor evolving excise rate adjustments and biosecurity documentation requirements as both jurisdictions tighten traceability expectations for agave-based imports.
Market Dynamics
Premium on-trade venues in Sydney and Melbourne are reconfiguring tequila margin pools through cocktail-forward programming that elevates aged expressions above standard well pours. This demand concentration among metropolitan hospitality corridors is compressing wholesale pricing power while amplifying brand-building requirements for market entry.
Growth Catalysts
- FSANZ Labeling Alignment:Standardized country-of-origin disclosure requirements reduce information friction for Mexican distillers entering Australian retail channels.
- Cocktail Culture Maturation:Melbourne's bar-dense precincts generate pull for small-batch agave spirits through menu innovation and staff education programs.
- Biosecurity Protocol Streamlining:TGA inspection documentation digitization accelerates border clearance timelines for established import pipelines.
Market Restraints
- Agave Supply Concentration:Jalisco highland agave farming dominates raw material sourcing, exposing price volatility risk from Mexican climatic disruption.
- Excise Burden Structure:Australia's alcohol taxation framework imposes cost stacking that filters out sub-premium price positioning.
- Substitution Elasticity:Local gin and whisky categories capture trial budgets through domestic provenance marketing and shorter supply chains.
Strategic Opportunities
- Auckland Hospitality Expansion:New Zealand's cocktail venue density remains underdeveloped relative to Australian benchmarks, presenting first-mover positioning potential.
- Direct-to-Consumer Channel:Online retail platforms bypass traditional wholesale markups while reaching millennial buyers outside metropolitan cores.
- Aged Expression Scarcity Marketing:Extra Añejo stock accumulation enables limited-release programming that commands shelf space in premium liquor retail.
Industry Challenges
- Agave Agronomy Expertise Gap:Australian importers lack in-house capability to verify sustainable farming claims and terroir authenticity at origin.
- Compliance Documentation Burden:TGA biosecurity certification and FSANZ nutritional labeling create dual-track approval timelines that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia and New Zealand Tequila Market |
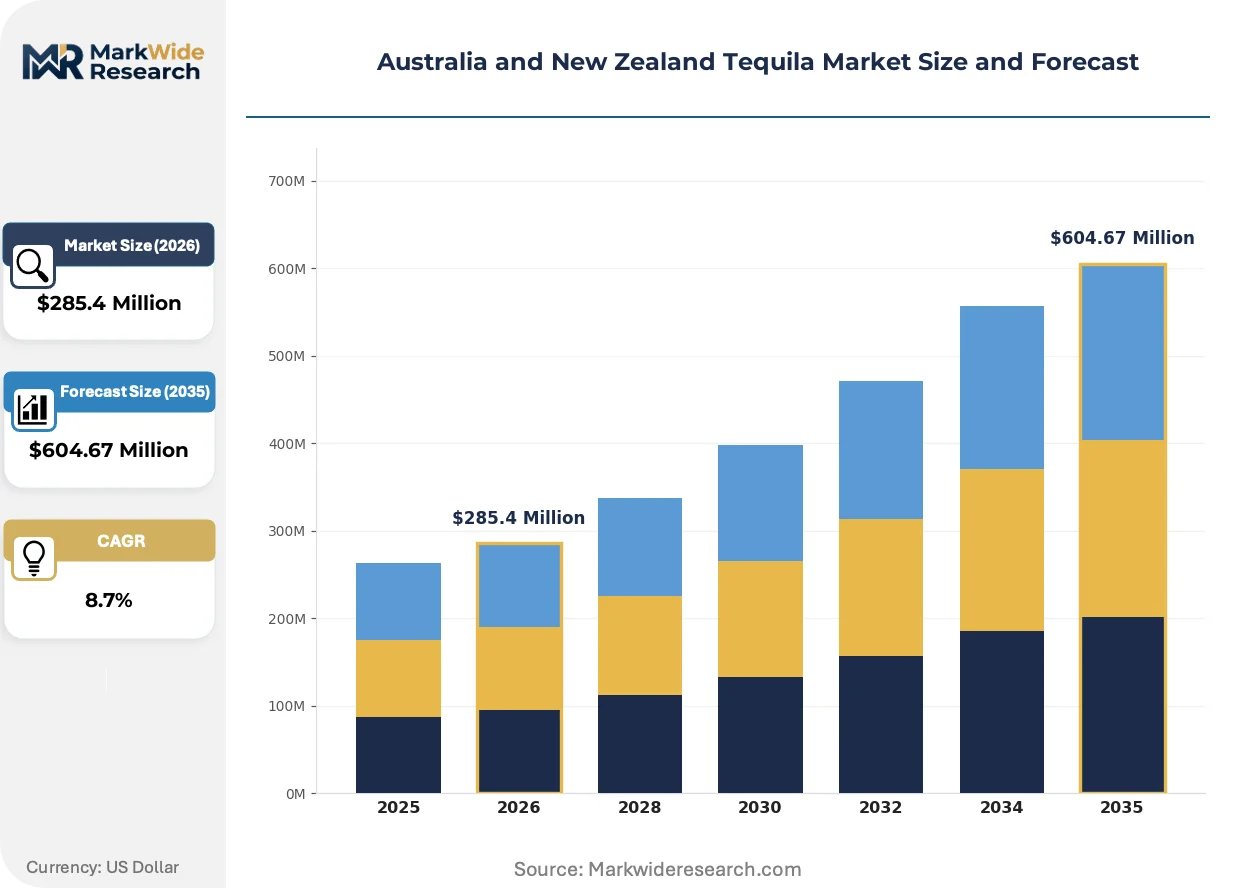
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blanco, Reposado, Añejo, Extra Añejo Distribution Channel: Online Retail, Off-Trade, On-Trade, Supermarkets Customer Type: Young Adults, Millennials, Luxury Buyers, Occasional Consumers Packaging Type: Glass Bottles, Plastic Bottles, Tetra Packs, Cans |
| Companies Covered | Don Julio, Herradura, Jose Cuervo, El Jimador, Casamigos, Patrón Spirits Company, Beam Suntory, Milagro Tequila, Sauza Tequila, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia and New Zealand Tequila Market Trends and Innovations
Craft production methods and transparency protocols are migrating from niche positioning to baseline market entry requirements across the Australia and New Zealand tequila category. These shifts compress margins for undifferentiated imports while rewarding sourcing investments.
Additive-free tequila certification is migrating from enthusiast forums to mainstream hospitality procurement criteria. Melbourne's premium bar operators now screen suppliers for diffuser-free production methods and estate-grown agave claims. This filtration is compressing volume opportunities for industrial-scale Mexican distillers while elevating price authority for verified craft producers.
FSANZ is tightening nutritional labeling disclosure for imported spirits, mandating standardized alcohol content presentation and allergen warnings. This regulatory friction forces Mexican exporters to reformulate packaging runs specifically for Australian compliance. Smaller distillers with limited production flexibility face disproportionate adaptation costs relative to volume throughput.
Buyer concentration among hospitality groups is consolidating procurement decisions across multi-venue portfolios. Sydney's large-format restaurant operators now negotiate master supply agreements that displace fragmented distributor relationships. This channel compression is most visible in New South Wales, where venue group buying power extracts preferential terms from import agents.
Australia and New Zealand Tequila Market Segmentation
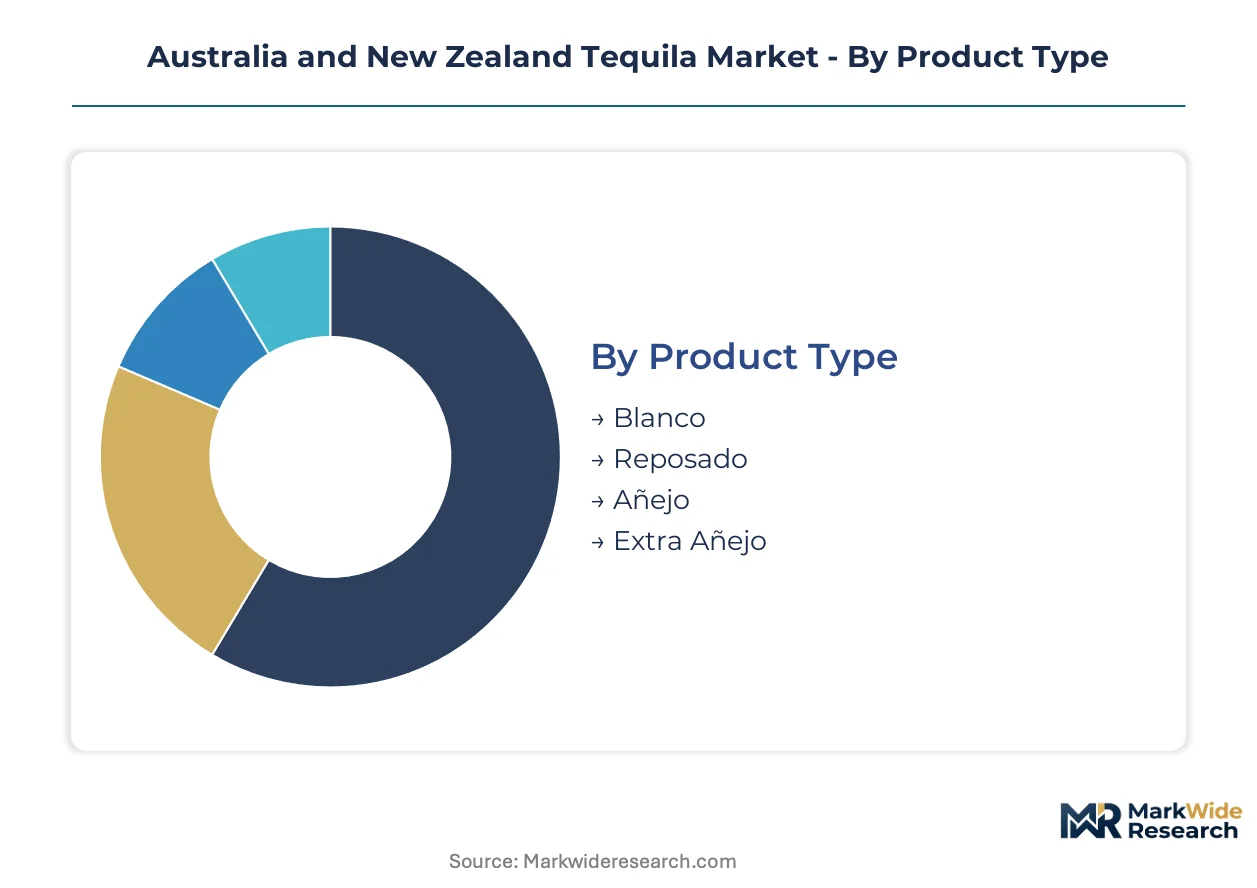
Segmentation patterns across the Australia and New Zealand tequila market reveal distinct service intensity requirements. Premium aged expressions demand sophisticated staff training and cellar management, while volume channels prioritize logistics efficiency and regulatory compliance documentation.
Product Type:
After-sales-service intensity varies sharply across agave aging tiers, with extended barrel programs requiring inventory financing and provenance verification support.
- Blanco:Unaged expressions bottled immediately after distillation preserve raw agave character with higher terpene content. Sydney's high-volume cocktail bars drive throughput here, though margin compression from excise stacking limits wholesale flexibility.
- Añejo:Oak-barrel aging between one and three years develops vanilla and caramel notes through lignin extraction. Melbourne's premium restaurant groups concentrate procurement for sipping programs, with scarcity positioning justifying elevated price architecture.
- Reposado:Two-month to one-year oak contact delivers intermediate complexity for mixed applications.
- Extra Añejo:Extended aging beyond three years commands ultra-premium positioning through stock accumulation.
Blanco holds the largest share; momentum sits with Añejo.
Distribution Channel:
Cost tier stratification separates capital-intensive on-trade programming from leaner digital direct-to-consumer models.
- On-Trade:Licensed venues including bars, restaurants, and hotels generate premium pricing power through staff education and menu integration. Auckland's emerging cocktail corridor presents first-mover positioning potential as venue density lags Australian benchmarks.
- Off-Trade:Independent liquor retailers and bottle shops capture discovery-oriented buyers through curated shelf placement. Melbourne's premium retail clusters favor aged expression portfolios with verified additive-free credentials.
- Online Retail:E-commerce platforms bypass traditional wholesale markups while reaching millennial segments outside metropolitan cores.
- Supermarkets:Mass retail chains anchor volume throughput for standard-tier Blanco through promotional pricing cycles.
On-Trade commands the margin pool; Online Retail is climbing the fastest.
Customer Type:
Volume concentration patterns track generational wealth accumulation and hospitality engagement frequency.
- Millennials:Urban professionals aged 28-43 drive premiumization through experiential consumption and brand story engagement. Sydney's hospitality corridors concentrate this segment's trial budgets, with TGA-compliant labeling transparency filtering purchase decisions.
- Luxury Buyers:High-net-worth individuals prioritize scarcity signaling and collector-grade provenance. Extra Añejo limited releases and single-estate bottlings capture disproportionate spend per occasion in private dining contexts.
- Young Adults:Entry-level legal-age consumers show price elasticity and format experimentation.
- Occasional Consumers:Infrequent purchasers respond to seasonal gifting cycles and promotional visibility.
Millennials anchor volume value; Luxury Buyers show the steepest expansion trajectory.
Packaging Type:
Margin structure and supply concentration diverge across material specifications and regulatory compliance burdens.
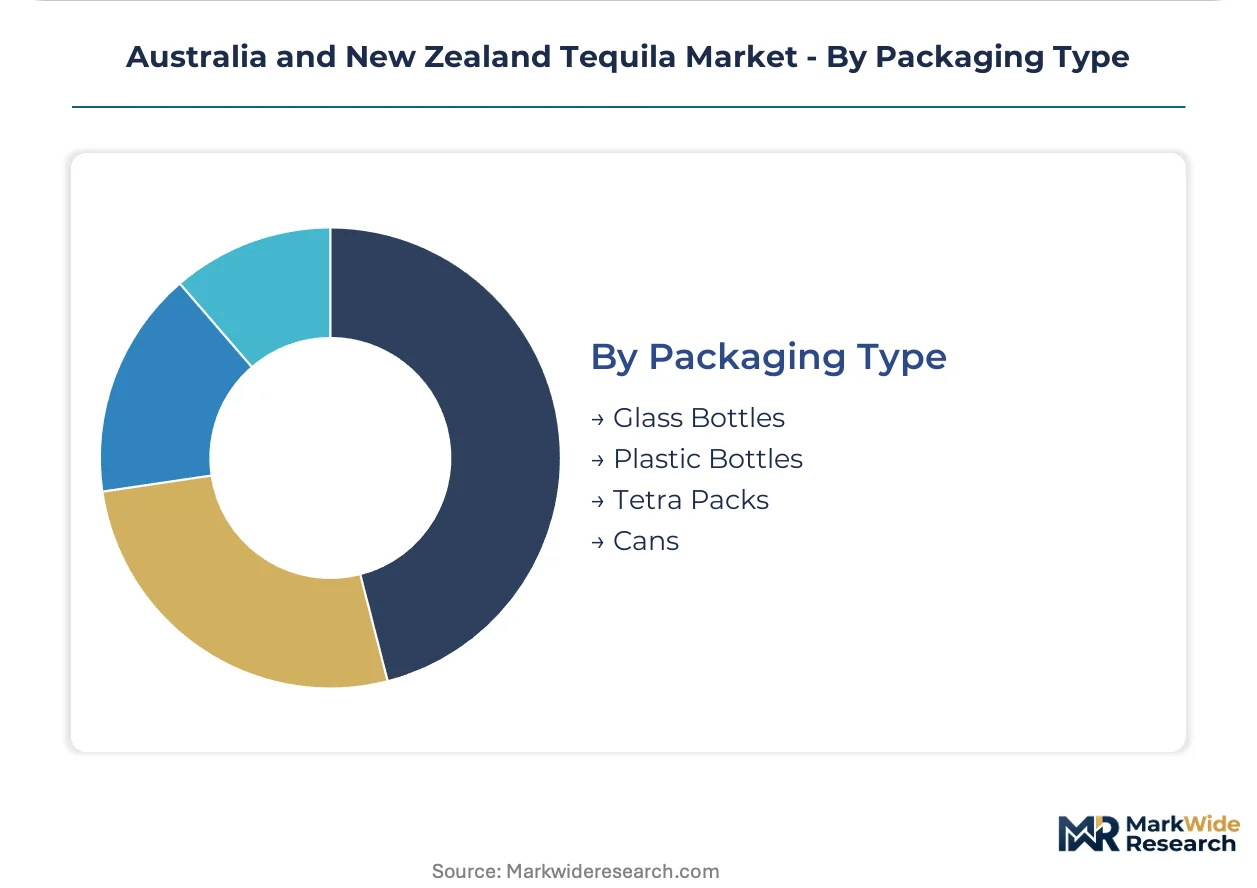
- Glass Bottles:Premium-grade flint and amber glass dominates aged expression presentation, with weight and closure quality signaling price tier. FSANZ labeling mandates require specific panel placement that constrains Mexican design standardization.
- Plastic Bottles:PET formats serve travel retail and outdoor event channels where breakage risk outweighs premium positioning requirements.
- Tetra Packs:Aseptic cartons occupy minimal shelf space in spirits retail, with regulatory barriers to alcohol content stability.
- Cans:Single-serve aluminum formats target festival and outdoor consumption occasions with portability advantages.
Glass Bottles dominate revenue contribution; Cans represent the emerging format with fastest uptake velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia dominates consumption volume through metropolitan hospitality corridors, while New Zealand exhibits steeper per-capita growth in premium aged expressions. This consumption-mix differential shapes distinct import strategies across the Tasman.
New South Wales
Sydney's cocktail-dense precincts in Surry Hills and the CBD concentrate demand for verified additive-free tequila. TGA border inspection protocols filter smaller Mexican distillers from direct warehouse access. The Inner West bar cluster sustains pull for small-batch agave spirits through staff education programs and menu integration.
Victoria
Melbourne's premium restaurant groups anchor procurement for Añejo sipping programs in the laneway hospitality corridor. FSANZ labeling mandates require specific alcohol content panel placement that constrains Mexican design standardization. South Yarra and Fitzroy retail clusters favor aged expression portfolios with estate-grown agave credentials.
Queensland
Brisbane's emerging rooftop bar scene generates trial budgets for Blanco cocktail bases among younger demographics. The state's liquor licensing framework imposes operational constraints on late-trade venues that compress on-trade programming hours. Gold Coast tourism corridors sustain off-trade volume through duty-free and travel retail channels.
New Zealand
Auckland's hospitality venue density remains underdeveloped relative to Australian benchmarks, presenting first-mover positioning potential for premium imports. The Commerce Commission enforces country-of-origin standards under the Fair Trading Act that parallel Australian disclosure requirements. Wellington's compact central city enables rapid venue-to-venue brand activation for craft agave entrants.
Australia and New Zealand Tequila Market Competitive Landscape
Capability concentration sits with heritage Mexican distillers possessing agave terroir verification and extended barrel programs; scale advantage sits with multinational spirits houses with established ANZ distribution infrastructure. The market structure tiers between authenticity-positioned craft entrants and volume-anchored legacy brands. Three archetypes dominate: estate-verified premium specialists, diversified spirits conglomerates with tequila portfolios, and celebrity-backed lifestyle brands. Competitive moves center on sourcing transparency certification and direct-to-consumer channel development.
Within the heritage distiller tier, Patrón Spirits Company and Herradura occupy positions defined by Jalisco highland agave provenance and additive-free production credentials. Beam Suntory sits within the diversified spirits conglomerate archetype, leveraging cross-category distribution relationships. Casamigos exemplifies the celebrity-backed lifestyle positioning that commands shelf space through brand narrative rather than traditional hospitality education investment.
| Leading Market Players |
|---|
| Don Julio |
| Herradura |
| Jose Cuervo |
| El Jimador |
| Casamigos |
| Patrón Spirits Company |
| Beam Suntory |
| Milagro Tequila |
| Sauza Tequila |
| Others |
Pricing and Supply Chain Analysis
Jalisco highland agave farming concentration exposes price volatility risk from Mexican climatic disruption, determining both premium-to-economy pricing spreads and the three-tier import pipeline structure spanning estate-verified distillers, contract-bottling networks, and industrial-scale exporters. TGA biosecurity certification and FSANZ labeling mandates impose compliance cost stacking that filters sub-premium positioning while amplifying scarcity value capture for verified additive-free producers.
Pricing Analysis
Long-term offtake agreements between Australian import agents and Jalisco estate distillers anchor premium-tier supply security, while spot-market purchasing dominates standard Blanco throughput. Three-tier pricing structure across premium, standard, and economy levels separates single-estate Extra Añejo releases from contract-bottled Reposado and industrial diffuser outputs. Cost compression in the standard tier intensifies because excise burden stacking and biosecurity documentation fees erode wholesale flexibility. Sydney hospitality groups show least price sensitivity through master supply agreements, whereas Queensland independent retailers exhibit highest elasticity to promotional cycles.
Supply Chain Analysis
Contract-bottling concentration among third-party Jalisco facilities serving non-estate brands holds capacity for standard-tier export volume. Geographic supply concentration centers on Mexico for blue Weber agave cultivation, with secondary processing nodes in Guadalajara metropolitan zone and tertiary packaging adaptation for Australian compliance in Sydney import warehouses. Raw material dependencies rest on highland agave piña, American white oak for barrel programs, and flint glass from domestic Mexican foundries. Single-source vulnerability runs through Jalisco highland terroir exclusivity. Distribution runs through licensed import agents holding TGA establishment registrations and FSANZ food importer accreditations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer concentration among Sydney and Melbourne hospitality groups is consolidating procurement decisions across multi-venue portfolios, shifting pricing power toward venue operators and compressing distributor margin pools. This fragmentation of supplier relationships into master agreements favors scale-backed incumbents with working capital depth.
For Market Incumbents: Harden additive-free certification protocols to defend shelf space against celebrity-backed lifestyle entrants lacking estate-verified credentials. Deepen backward integration into Jalisco highland agave farming through equity stakes or long-term planting contracts to secure raw material priority during climatic stress periods. Channel control investment in direct-to-consumer platforms bypasses wholesale markup compression from consolidated hospitality buyers. For New Entrants and Emerging Players: Auckland's underdeveloped cocktail venue density relative to Australian benchmarks represents the most penetrable entry point for craft agave specialists seeking first-mover positioning. Wellington's compact central city enables rapid venue-to-venue brand activation with minimal field marketing overhead. Online retail platforms targeting millennial segments outside Sydney and Melbourne metropolitan cores offer go-to-market angles that circumvent entrenched distributor relationships. For Investors and Strategic Acquirers: The market sits at a premiumization phase that favors estate-verified craft producers with barrel stock accumulation and additive-free certification already in place. Long-term viability across a five-to-ten-year window hinges on terroir authenticity verification and direct channel development rather than volume scale. Watch TGA biosecurity documentation digitization progress as the inflection signal for working capital efficiency gains among import-dependent business models.| Strategic Initiative | Industry Significance |
|---|---|
| Estate Agave Sourcing Verification | TGA-compliant provenance documentation unlocks premium on-trade access in Sydney and Melbourne corridors. |
| Additive-Free Certification Investment | Melbourne bar procurement criteria now screen suppliers for diffuser-free production methods and estate-grown claims. |
| Direct-to-Consumer Channel Launch | Online retail platforms bypass traditional wholesale markups while reaching millennial buyers outside metropolitan cores. |
| Extra Añejo Barrel Stock Accumulation | Limited-release programming commands shelf space in South Yarra and Fitzroy premium liquor retail clusters. |
| Auckland Hospitality Partnership Development | New Zealand's lagging venue density presents first-mover positioning potential before Australian saturation patterns replicate. |
Research Methodology
Initial hypotheses were tested against primary input from import agents holding TGA establishment registrations, procurement managers at Sydney hospitality groups, Melbourne premium liquor retail buyers, and Jalisco estate distiller export directors, and refined through secondary validation. Bottom-up and top-down triangulation combined trade customs data, FSANZ food importer accreditation records, and TGA border inspection disclosure patterns with Nielsen retail audit data and hospitality procurement database tracking.
Demand-supply-balance framing anchored the analytical approach across the analysis window, modeling segmentation dimensions spanning agave aging tier, distribution channel intensity, customer generational cohort, and packaging material specification. CAGRs were derived from volume trajectory reconciliation against value expansion patterns. Industry-specific forecast inputs included excise rate adjustment sensitivity and biosecurity documentation timeline compression assumptions.
Practitioners should monitor Jalisco highland agave planting cycle disruptions and TGA digitization rollout pace for early signals of supply constraint or clearance acceleration. Forecasts reflect assumptions regarding sustained premiumization pull from Melbourne and Sydney hospitality corridors. Quarterly review of import agent working capital stress indicators and FSANZ labeling enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Organic Wine Market
Alcoholic Beverages
F-Style Jugs Market
Alcoholic Beverages
Bright Beer Tank Market
Alcoholic Beverages
Brewing Supplies Market
Alcoholic Beverages
Global Beer Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Gin and Tonic Tea Market
Alcoholic Beverages
Rotels Market
Alcoholic Beverages
Moscato Wine Market
Alcoholic Beverages
Wine Filtering Machine Market
Alcoholic Beverages
Canada Wine Coolers Market
Alcoholic Beverages
Uganda Spirits Market
Alcoholic Beverages
Global TCD Alcohol DM Market
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
Global Bars and Nightclubs Market