
 Stove Top Moka Coffee Pot Market | 2026-2036
Stove Top Moka Coffee Pot Market Size, Share, and Industry Trends Forecast 2026-2036
Stove Top Moka Coffee Pot Market Insights
The capital-intensity gap between die-cast aluminum specialists and premium stainless-steel fabricators is rotating competitive advantage toward upstream metalworking capabilities. Bialetti leverages its historic Italian foundry infrastructure to sustain cost leadership in traditional aluminum models. Grosche anchors its position through ethical sourcing narratives that differentiate its stainless-steel lines in North American specialty channels. De'Longhi competes by extending its appliance brand equity into automated-compatible moka formats.
A stove top moka coffee pot brews espresso-strength coffee by passing pressurized steam through a tamped grounds chamber, typically operating at one to two bars pressure with aluminum or stainless-steel boiler construction. The device serves both ritual-driven home consumers and commercial cafes seeking manual extraction control without electrical dependency. Aluminum product types still occupy volume leadership due to thermal conductivity advantages, though stainless-steel variants are gaining fastest among health-conscious buyers wary of metal leaching. Family size configurations dominate revenue pools in Southern European households, while single-serve formats attract urban apartment dwellers through specialty stores and online retail channels.
EFSA food-contact material standards and EU REACH chemical restrictions shape allowable coatings and alloy compositions for European market access, while FDA indirect food additive regulations govern US import compliance. Italy's metalworking districts and China's Zhejiang casting clusters each navigate divergent national product safety frameworks that determine export eligibility. Stakeholders must monitor evolving nickel-release limits and emerging state-level right-to-repair legislation that could mandate spare-part availability across distribution channels.
Market Dynamics
The stove top moka coffee pot market faces intensifying pressure from EFSA's tightening nickel-release limits under food-contact material standards, which is forcing foundries to reformulate stainless-steel alloys and aluminum anodization processes ahead of compliance deadlines.
Growth Catalysts
- EU REACH chemical restrictions:Manufacturers investing in compliant coating technologies gain preferential access to German and Italian distribution networks.
- Specialty coffee home brewing:Urban consumers in Milan and Berlin drive replacement cycles for premium single-serve formats through dedicated retail channels.
- Aluminum thermal conductivity:Traditional die-cast construction retains cost-performance advantages for volume production in Piedmont metalworking clusters.
Market Restraints
- Raw material volatility:Nickel price swings squeeze stainless-steel fabricators in Germany's precision-engineering corridor.
- Supply concentration risk:Zhejiang casting clusters control upstream aluminum boiler production, creating single-source dependencies for European assemblers.
- Electric espresso substitution:Automated pump machines capture convenience-seeking households in North American metropolitan markets.
Strategic Opportunities
- Right-to-repair legislation:Emerging state-level mandates in California and New York will require spare-part availability, opening aftermarket revenue streams.
- Ethical sourcing certification:Fair-trade aluminum and conflict-free mineral traceability differentiate products in Canadian specialty channels.
- Induction compatibility:Hybrid base designs combining aluminum cores with stainless-steel interfaces address modern cooktop infrastructure in Japanese urban apartments.
Industry Challenges
- Metallurgical expertise scarcity:Foundries struggle to recruit technicians capable of managing EFSA-compliant alloy formulations.
- Certification timeline compression:Third-party laboratory testing for updated food-contact approvals creates 8-14 month product launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stove Top Moka Coffee Pot Market |
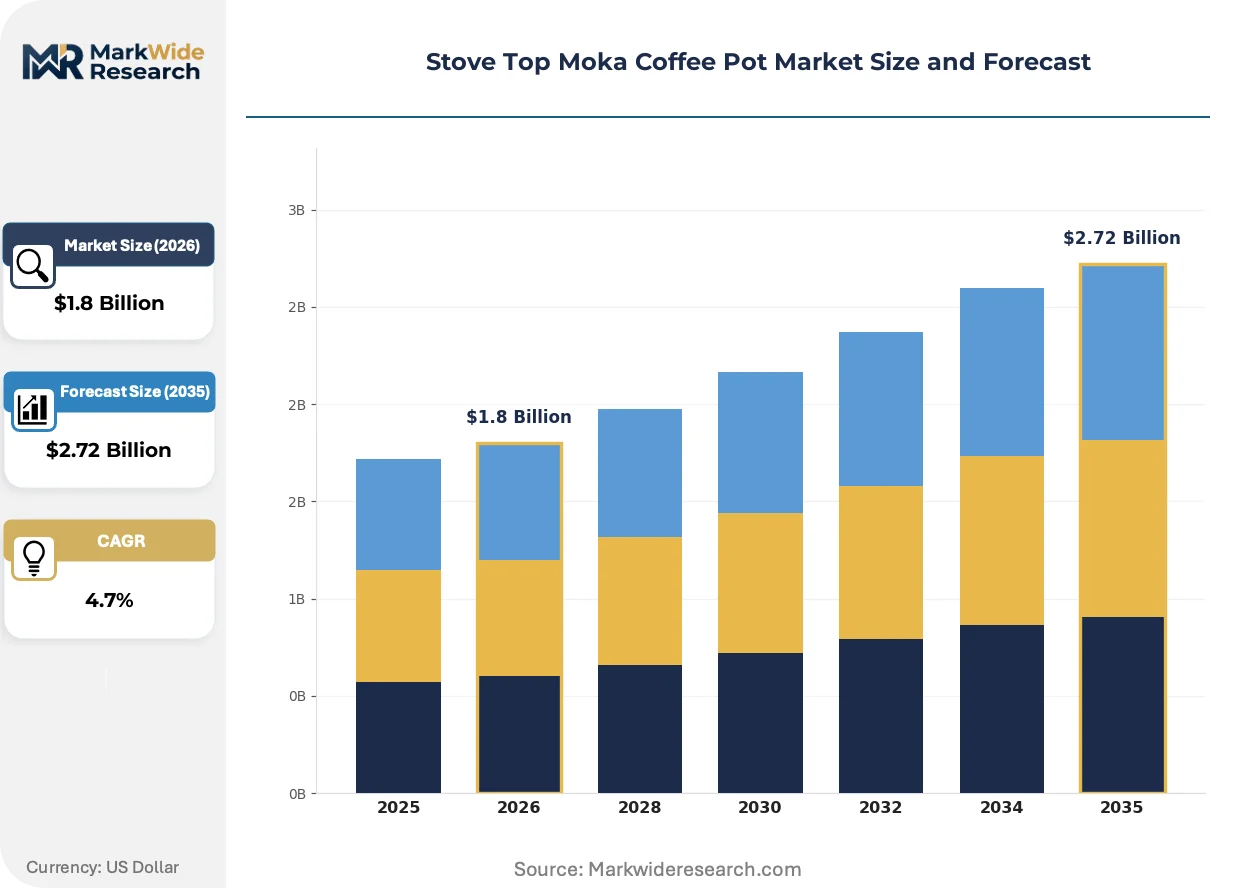
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Stainless Steel, Non-stick, Copper Size: Single Serve, Double Serve, Family Size, Travel Size End User: Home Consumers, Cafes, Restaurants, Offices Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Bialetti, Alessi, Alpha Coffee, De'Longhi, Grosche, LuxHaus, Primula, Zulay Kitchen, Cuisinox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stove Top Moka Coffee Pot Market Trends and Innovations
Material science advances and regulatory chemistry requirements are fragmenting traditional manufacturing approaches. Competitive advantage now flows to suppliers mastering compliant alloy engineering rather than assembly efficiency.
Stainless-steel composite construction is decomposing the historic aluminum monopoly in premium segments. Health-conscious buyers in Toronto and Vancouver now specify nickel-tested boilers, compressing demand for traditional die-cast formats and forcing Italian foundries to retool anodization lines or exit the upper price tier entirely.
EFSA's updated nickel-release testing protocols under food-contact material standards are reshaping allowable alloy compositions. Fabricators serving France and Spain must now certify every production batch through accredited laboratories, raising fixed compliance costs that disadvantage small-batch artisans against scaled German producers.
Direct-to-consumer subscription models are displacing wholesale dependency for specialty brands. Urban apartment dwellers in Seattle and Portland now receive scheduled gasket and filter replacements through automated replenishment platforms, eroding traditional retailer attachment rates and compressing customer acquisition costs for digital-native entrants.
Stove Top Moka Coffee Pot Market Segmentation
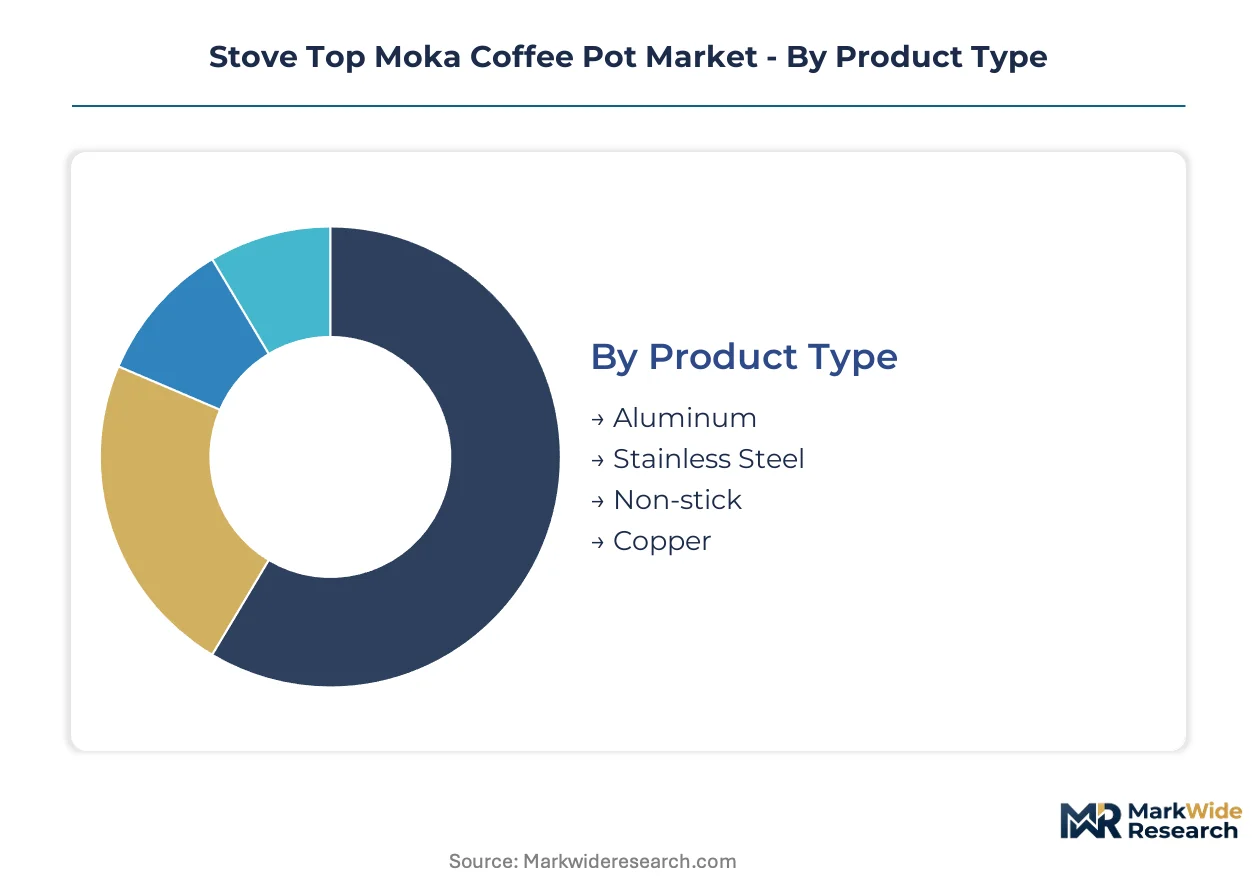
Material composition and thermal engineering specifications fragment manufacturing capabilities across distinct supplier ecosystems. Size configurations and channel access determine pricing power and replacement cycle frequency for each addressable cohort.
Product Type:
Margin pools concentrate in stainless-steel fabrication due to health-certification premiums and alloy complexity barriers that filter out commodity competitors.
- Aluminum:Die-cast construction leverages thermal conductivity coefficients of 205 W/m·K for rapid heat distribution. Traditional foundries in Italy's Piedmont region dominate volume production, though EFSA anodization standards now require batch-level certification that elevates fixed costs per production run.
- Stainless Steel:Austenitic 18/8 and 18/10 grades with nickel content below EFSA release thresholds command specialty channel placement. German precision-engineering corridors and North American ethical-sourcing narratives rotate demand toward nickel-tested boilers in Toronto and Vancouver metropolitan markets.
- Non-stick:Ceramic and PTFE-alternative coatings comply with EU REACH chemical restrictions on perfluorinated compounds. Coating durability limitations compress replacement cycles versus bare metal alternatives.
- Copper:Solid copper construction with tin-lined interiors serves aesthetic-driven collectors and professional barista training environments. Raw material costs and hand-finishing requirements restrict addressable volume.
Aluminum holds installed capacity across legacy Italian foundries. Stainless steel is rotating up the share rankings among health-conscious buyer cohorts.
Size:
Volume concentration sits with family configurations that anchor Southern European household penetration and gift-giving occasions.
- Single Serve:Compact 1-cup aluminum boilers target urban apartment dwellers with limited cooktop space. Seattle and Portland specialty retailers report fastest inventory turns for this format among millennial first-time buyers.
- Double Serve:2-cup stainless-steel variants balance portion flexibility with thermal mass efficiency. Berlin and Milan urban consumers drive replacement demand through dedicated coffee equipment boutiques.
- Family Size:6-cup and 9-cup die-cast aluminum dominates Italian and Spanish household penetration. Traditional morning ritual usage patterns sustain replacement cycles every 4-7 years.
- Travel Size:Collapsible or miniaturized formats for camping and RV applications occupy niche outdoor retail channels. Durability trade-offs limit mainstream adoption.
Family size captures the deepest installed base across Mediterranean markets. Single serve is climbing the fastest among North American urban apartment segments.
End User:
Commercial applications concentrate demand for induction-compatible hybrid construction and rapid-cycle durability specifications.
- Home Consumers:Ritual-driven brewing behavior sustains premium pricing for heritage brands. Replacement cycles correlate with household moves and kitchen renovation timelines.
- Cafes:Manual extraction control without electrical dependency appeals to third-wave coffee operators seeking theatrical service elements. Stainless-steel durability specifications dominate procurement criteria.
- Restaurants:Tableside service applications in Italian and French dining concepts favor polished aluminum aesthetics. Volume procurement runs through hospitality supply distributors.
- Offices:Break-room installations prioritize induction compatibility and automated safety features. Procurement consolidation through facility management vendors compresses margin realization.
Home consumers anchor volume demand across all material tiers. Cafes are gaining share fastest as specialty coffee culture extends into commercial preparation environments.
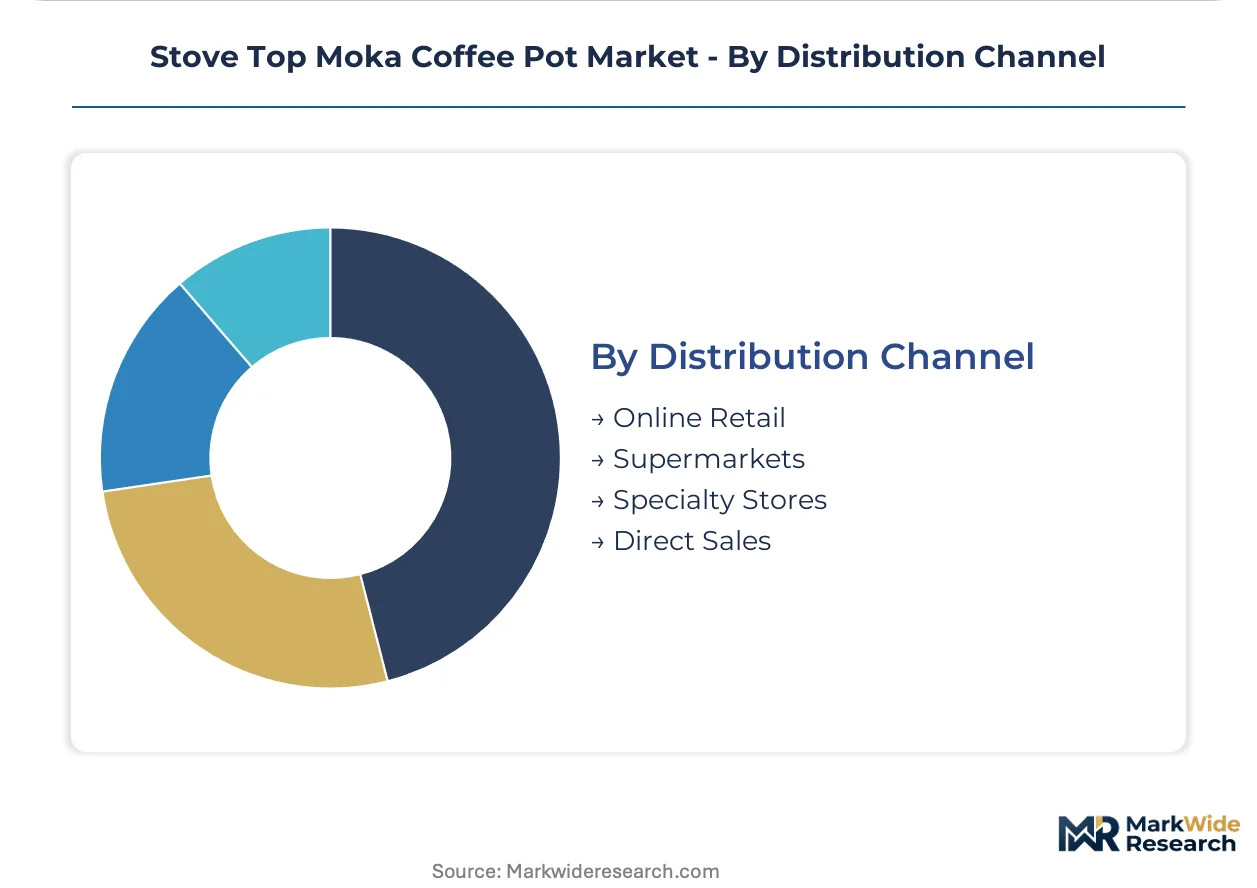
Distribution Channel:
Customer acquisition economics favor direct relationships that capture replacement part revenue and subscription replenishment streams.
- Online Retail:Amazon and direct-to-consumer platforms aggregate comparison shoppers and gift purchasers. Automated gasket and filter subscription models now displace traditional retailer attachment rates for digital-native entrants.
- Supermarkets:Mass-market aluminum formats occupy seasonal promotional slots and impulse purchase locations. Price transparency across competing brands compresses premium positioning opportunities.
- Specialty Stores:Curated selection and staff expertise justify stainless-steel premiums in Toronto, Vancouver, Seattle, and Portland retail corridors. In-store brewing demonstrations convert consideration to purchase.
- Direct Sales:Brand-owned flagship locations and pop-up installations in Milan and Berlin capture tourist and collector segments. Exclusive finishes and limited editions rotate through this channel.
Specialty stores hold the deepest engagement with premium stainless-steel buyers. Online retail is expanding most quickly as subscription replenishment platforms consolidate replacement part demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium stainless-steel fabricators in Germany command pricing power that aluminum foundries in Italy cannot match, creating a regional asymmetry that shapes competitive investment patterns across European metalworking corridors.
Italy
Heritage die-cast foundries in Piedmont sustain volume leadership through thermal conductivity advantages, though EFSA batch-certification requirements for anodized aluminum now elevate fixed costs per production run. Traditional morning ritual usage in Turin and Milan households drives replacement cycles every 4-7 years for family-size configurations.
Germany
Precision-engineering corridors in Bavaria and Baden-Württemberg specialize in nickel-tested austenitic grades that comply with tightened EFSA food-contact release thresholds. REACH chemical restrictions on alloy compositions force continuous metallurgical reformulation, concentrating technical expertise in Stuttgart and Nuremberg industrial clusters.
United States
Specialty coffee culture in Seattle and Portland accelerates demand for single-serve stainless-steel formats through dedicated retail channels. FDA indirect food additive regulations govern import compliance for European and Asian suppliers, while emerging right-to-repair legislation in California and New York mandates spare-part availability across distribution networks.
Canada
Health-conscious buyers in Toronto and Vancouver metropolitan markets specify nickel-tested boilers, compressing demand for traditional aluminum formats. Ethical sourcing certification and fair-trade aluminum traceability differentiate products in specialty channels, with Vancouver retailers reporting fastest inventory turns for premium stainless-steel lines.
China
Zhejiang casting clusters control upstream aluminum boiler production for global export, creating single-source dependencies for European assemblers. Domestic demand concentrates in Shanghai and Beijing urban apartments where compact formats address limited cooktop space, though national food-contact safety frameworks diverge from EFSA and FDA standards.
Stove Top Moka Coffee Pot Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting the vendor base across material specialization tiers. Italian heritage foundries anchor volume production through captive die-cast infrastructure, while German precision fabricators capture premium positioning via alloy engineering capabilities. Three archetypes dominate: aluminum thermal specialists, stainless-steel compliance leaders, and digital-native subscription platforms. Competitive moves concentrate on backward integration into foundry capacity and direct-to-consumer channel capture.
Among heritage Italian manufacturers, Bialetti exemplifies the aluminum volume archetype through its historic foundry infrastructure. German fabricators including Grosche occupy positions within the stainless-steel premium tier, leveraging compliance engineering for specialty channel placement. De'Longhi represents appliance-brand extension strategies that bridge automated and manual extraction formats.
| Leading Market Players |
|---|
| Bialetti |
| Alessi |
| Alpha Coffee |
| De'Longhi |
| Grosche |
| LuxHaus |
| Primula |
| Zulay Kitchen |
| Cuisinox |
| Others |
Pricing and Supply Chain Analysis
Eight-to-fourteen-month certification timelines for EFSA food-contact approvals concentrate pricing power with scaled German fabricators capable of absorbing fixed laboratory costs, while Italian foundries face margin compression from batch-level anodization testing requirements. This lead-time asymmetry rewards upstream metalworking investment over assembly efficiency.
Pricing Analysis
Customization-premium spreads of 40-60% separate configured-to-order nickel-tested stainless-steel boilers from standard aluminum die-cast formats. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and thermal conductivity specification, with EFSA-compliant alloy engineering commanding specialty channel placement. Pricing pressure stems from raw material volatility in nickel markets, squeezing stainless-steel fabricators. Home consumers in Southern Europe exhibit highest price sensitivity for replacement cycles, while North American specialty buyers accept premiums for ethical sourcing certification.
Supply Chain Analysis
Inventory cycles of 90-120 days for EFSA-certified alloy batches tether European assemblers to Zhejiang casting clusters for upstream aluminum boiler production. The supply chain draws from Italy's Piedmont foundries, Germany's precision-engineering corridors, and China's Zhejiang clusters for critical inputs including die-cast aluminum, austenitic stainless steel, and ceramic coating formulations. Single-source vulnerability concentrates in Chinese aluminum casting capacity. Distribution runs through hospitality supply distributors for commercial procurement and direct-to-consumer platforms for replacement part replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where EFSA alloy certification requirements create switching costs that lock in buyers with compliant suppliers.
For Market Incumbents: Shield market position through captive foundry capacity in Germany's precision-engineering corridors and exclusive distribution partnerships with specialty retailers in Toronto and Vancouver. Electric espresso substitution threatens traditional aluminum volume tiers. Backward integration into EFSA-accredited laboratory testing accelerates product launch timelines against certification-backlogged competitors. For New Entrants and Emerging Players: Subscription-based gasket and filter replenishment services represent the most penetrable service-layer gap, where heritage brands under-serve digital-native urban apartment dwellers in Seattle and Portland. Direct-to-consumer automation platforms capture replacement cycle revenue streams. Ethical sourcing certification for fair-trade aluminum provides differentiated go-to-market positioning in Canadian specialty channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across stainless-steel fabrication sub-segments as EFSA compliance engineering demands metallurgical expertise investment. Long-term viability favors scaled producers with captive alloy formulation capabilities over artisan assemblers. Acquisition targets should demonstrate accredited laboratory relationships and induction-compatible hybrid base patents. Monitor nickel price volatility as inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA-Compliant Alloy Engineering Investment | Batch-level certification capability secures preferential access to German and Italian distribution networks. |
| Direct-to-Consumer Subscription Launch | Automated replenishment platforms displace traditional retailer attachment rates for digital-native entrants. |
| Ethical Sourcing Certification Program | Fair-trade aluminum traceability differentiates products in Vancouver and Toronto specialty retail corridors. |
| Induction-Compatible Hybrid Base Development | Aluminum-core stainless-steel interfaces address modern cooktop infrastructure in Japanese urban apartments. |
| Backward Integration into Foundry Capacity | Captive die-cast infrastructure insulates against Zhejiang casting cluster supply concentration risk. |
Research Methodology
The analysis maps aluminum die-cast, stainless-steel fabrication, and hybrid induction-compatible sub-sectors, each validated through foundry operations managers, specialty retail buyers, and food-contact certification specialists. Primary interviews with procurement leads at hospitality supply distributors and channel partners at North American ethical-sourcing retailers combined with secondary validation from EFSA guidance documents, EU REACH chemical restriction updates, and customs trade data. Bottom-up production capacity estimates and top-down consumption pattern analysis enabled triangulation across modeling approaches.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled material composition, size configuration, end-user application, and distribution channel dimensions. CAGRs derived from replacement cycle frequency analysis, urban household formation rates, and specialty coffee equipment penetration curves. Nickel price volatility indices and EFSA compliance timeline compression served as industry-specific forecast inputs.
Underlying assumptions cover EFSA regulatory stability, specialty coffee culture persistence, and raw material supply continuity, with deviation risk concentrated in nickel-release limit revisions and right-to-repair legislative acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Pods Market
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
Latin America Coffee Market
Coffee
Espresso Powder Market
Coffee
Caffeine Market
Coffee
North America Coffee Market
Coffee
Green Coffee Extract Market
Coffee
Coffee Roaster Market
Coffee
Espresso Tamper Market
Coffee
Canned Coffee Market
Coffee
Green Coffee Bean Extract Market
Coffee
North America Specialty Coffee Market
Coffee
Coffee Cherry Market
Coffee
Sparkling Coffee Market
Coffee
Asia-Pacific Ready to Drink (RTD) Coffee Market
Coffee
Cold Brew Coffee Market