
 Countertop Ice Dispensers Market | 2026-2036
Countertop Ice Dispensers Market Size, Share, and Industry Trends Forecast 2026-2036
Countertop Ice Dispensers Market Outlook
The gap between premium stainless-steel units and commodity plastic-body dispensers is repositioning how distributors structure their portfolios. Whirlpool Corporation leverages its appliance ecosystem to bundle ice dispensers with broader kitchen equipment packages. Hoshizaki Corporation anchors the premium tier through commercial-grade stainless construction and extended service networks. Maxx Ice competes aggressively on price in the mid-market, sacrificing margin for volume placement in independent restaurants.
Countertop ice dispensers are self-contained refrigeration appliances that produce, store, and dispense ice cubes or nuggets through a frontal chute, typically operating between 115V and 220V with integrated water filtration and antimicrobial bin liners. Their primary commercial purpose is to provide sanitary, on-demand ice access in confined front-of-house environments where floor space is constrained. Portable dispensers lead volume in small-format cafes and mobile catering setups where installation flexibility outweighs daily throughput. Under-counter dispensers capture the fastest growth in bars and quick-service restaurants seeking to reclaim counter space while maintaining customer-facing ice access. Modular dispensers occupy the margin-rich tier in high-volume chains that pair separate ice makers with dedicated dispenser heads.
The EPA's ENERGY STAR program and the DOE's commercial refrigeration efficiency standards shape product development timelines and qualification costs for manufacturers selling into the United States. NSF International sanitation certification governs market access for food-contact equipment, while UL electrical safety listings remain non-negotiable for commercial insurance and health department approvals. Stakeholders must monitor how pending refrigerant phase-down rules under the AIM Act reshape compressor technology choices and retrofit economics across installed bases.
Market Dynamics
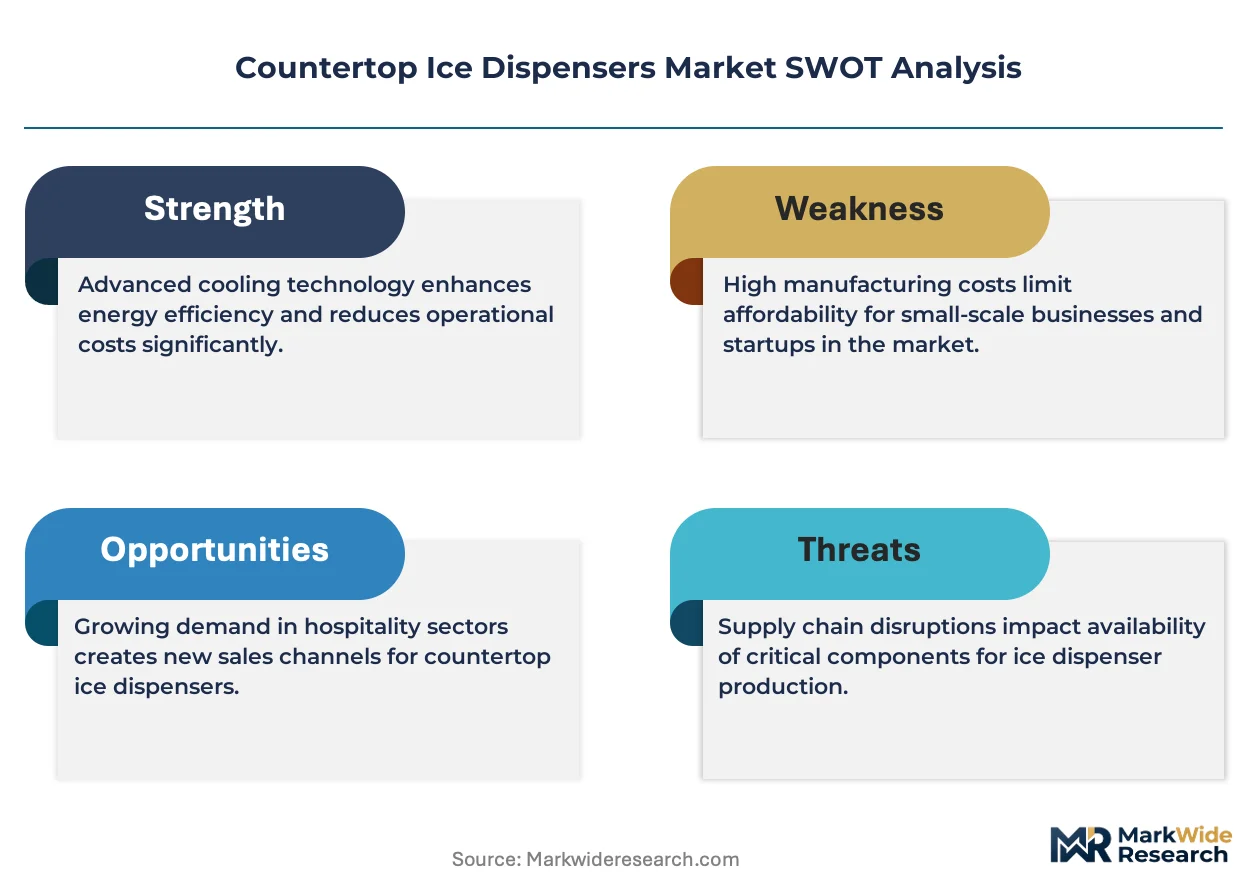
ENERGY STAR certification requirements from the EPA are forcing manufacturers to redesign compressor systems and insulation packages, compressing development timelines while raising qualification costs for commercial refrigeration equipment.
Growth Catalysts
- Quick-service restaurant expansion:Chains in the United States are shortening equipment refresh cycles to 5-7 years, replacing aging units with ENERGY STAR-qualified models to reduce operating costs and meet corporate sustainability targets.
- Urban foodservice corridor densification:High-traffic districts in Chicago, Los Angeles, and New York are driving demand for compact, front-of-house ice solutions where floor space commands premium lease rates.
- Refrigerant transition mandates:The AIM Act's hydrofluorocarbon phase-down rules are accelerating R-290 and CO₂ compressor adoption, creating replacement demand across installed bases as service economics shift.
Market Restraints
- Stainless steel price volatility:Commodity fluctuations for 304-grade stainless directly squeeze margins on premium commercial units, forcing mid-market manufacturers toward plastic-body alternatives.
- Certification timeline friction:NSF International sanitation testing and UL electrical safety listings require 4-6 month approval windows, delaying product launches and freezing inventory commitments.
- Water filtration infrastructure gaps:Independent restaurants in secondary markets lack consistent reverse-osmosis or carbon filtration systems, limiting dispenser performance and warranty coverage.
Strategic Opportunities
- Mobile catering penetration:Portable dispenser configurations are capturing volume in food trucks and event catering where 115V power access and installation flexibility outweigh daily throughput requirements.
- Under-counter space reclamation:Bars and quick-service restaurants are shifting dispenser placement below counter height, opening specification opportunities for compact, customer-facing chute designs.
- Modular system bundling:High-volume chains are decoupling ice production from dispensing, creating margin-rich opportunities for dedicated dispenser heads paired with remote ice makers.
Industry Challenges
- Refrigerant technician scarcity:The transition to flammable hydrocarbon and transcritical CO₂ systems requires specialized training that commercial service networks have not yet scaled.
- Legacy electrical infrastructure:Older buildings in dense urban cores lack 220V circuits or adequate amperage for high-capacity units, forcing expensive electrical upgrades or specification downgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Countertop Ice Dispensers Market |
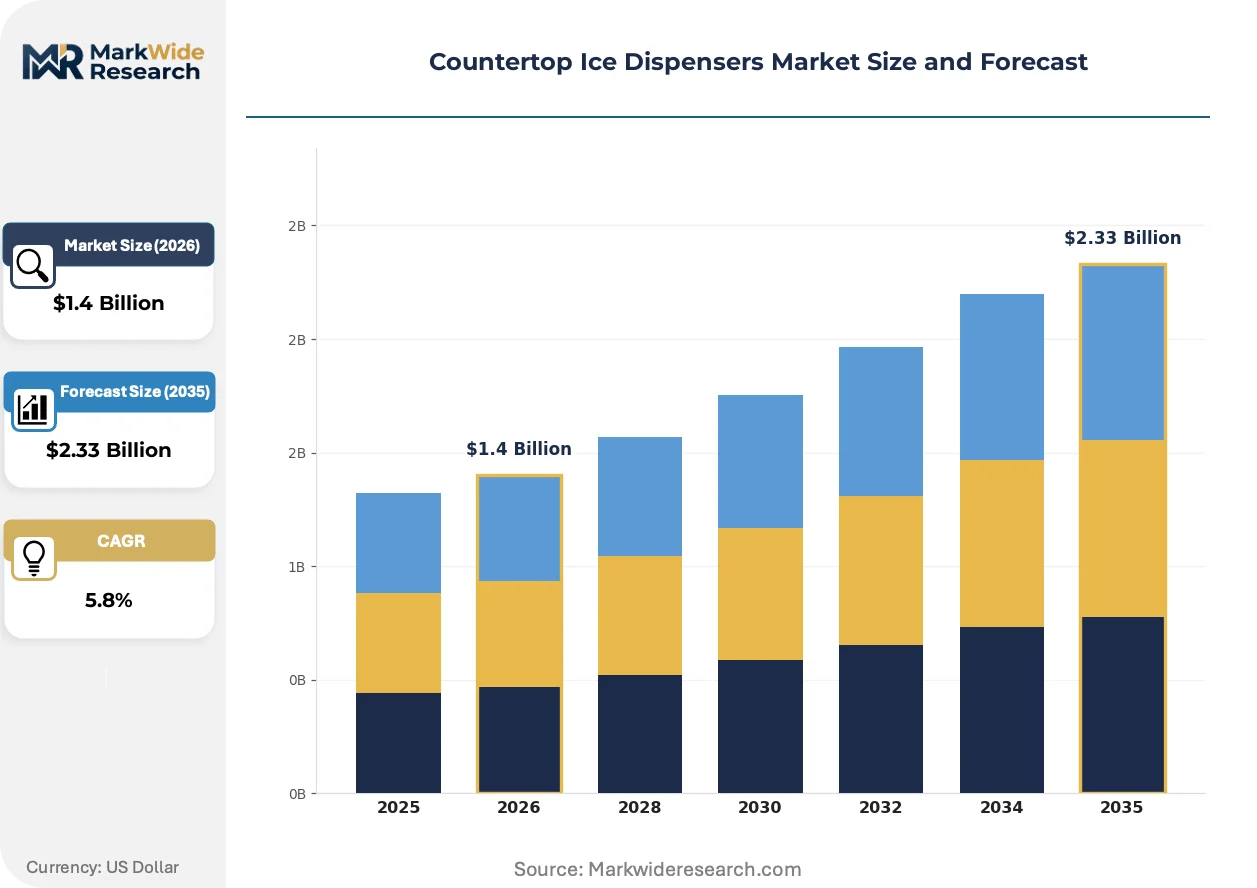
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Dispenser, Under-Counter Dispenser, Modular Dispenser, Gravity Dispenser End User: Restaurants, Cafes, Bars, Catering Services Installation Type: Freestanding, Countertop, Wall-Mounted, Built-In Capacity: Small (Less than 25 lbs), Medium (25-50 lbs), Large (51-100 lbs), Extra Large (over 100 lbs) |
| Companies Covered | GE Appliances, Whirlpool Corporation, NewAir Appliances, Frigidaire, Igloo, Whynter LLC, Maxx Ice, Summit Appliance, Hoshizaki Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Countertop Ice Dispensers Market Strategic Shifts
Antimicrobial bin liners and touchless dispensing interfaces are redefining sanitary performance standards, while connectivity modules enable remote diagnostics and predictive maintenance scheduling.
UV-C LED sterilization is integrating into ice storage zones to suppress biofilm formation without chemical treatment. Boutique hotel chains and healthcare foodservice operators are specifying these units at 15-20% price premiums. The technology is integrating real-time sanitation monitoring into lease and service contracts, compressing traditional maintenance intervals.
The EPA's ENERGY STAR Version 5.0 commercial refrigeration standards are tightening maximum daily energy consumption thresholds by 10-15% for compact equipment categories. Manufacturers must redesign insulation densities and compressor efficiency maps to maintain qualification. Small-format cafe and convenience store segments are responding fastest, as procurement specifications now mandate certified equipment.
Foodservice distributors are unbundling after-sales service from equipment sales, shifting toward subscription-based maintenance models with per-dispenser monthly fees. Independent restaurant buyers in the United States are adopting these contracts to transfer compressor and filtration failure risk. This restructuring is most visible in the Southeast and Southwest, where hard water conditions accelerate scale-related service calls.
Countertop Ice Dispensers Market Segmentation
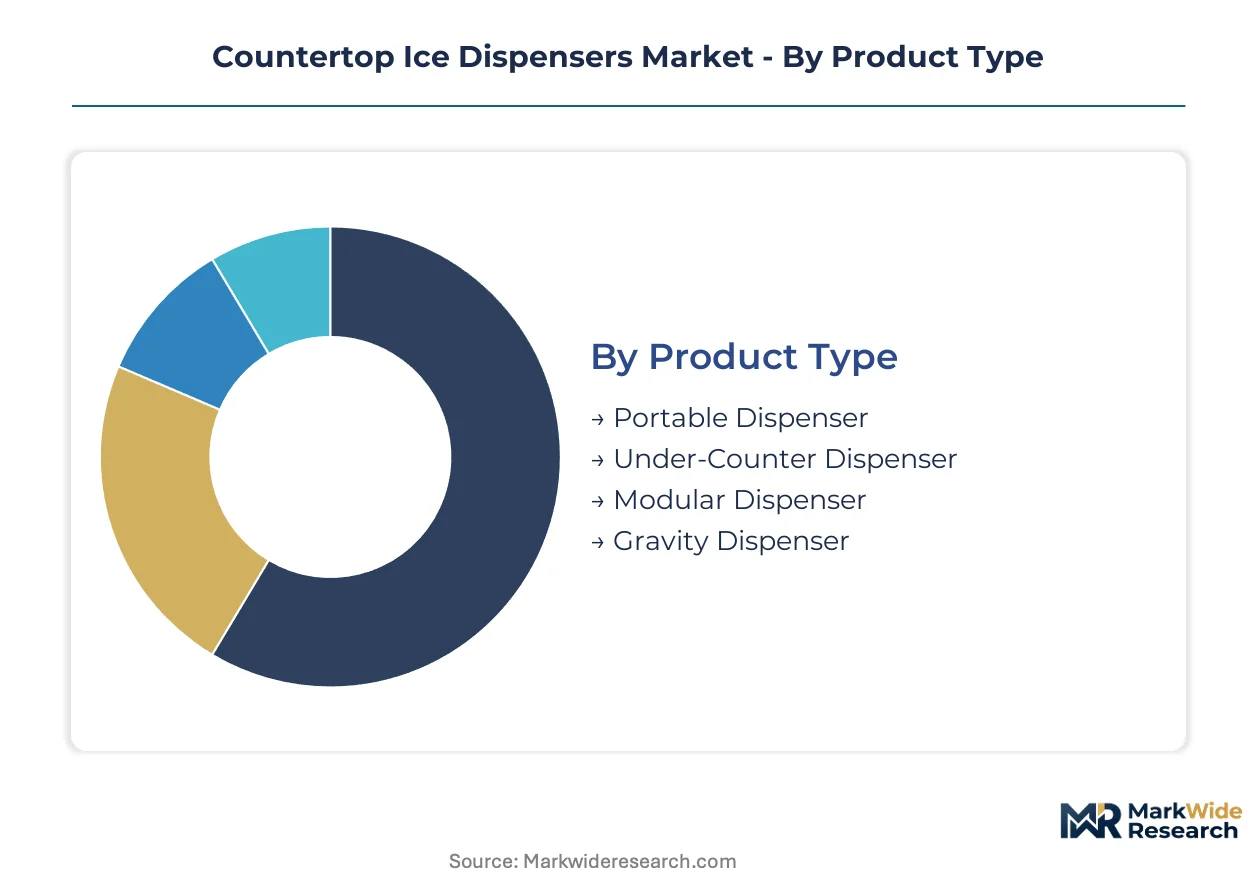
Equipment refresh cycles and space constraints create divergent specification requirements across commercial foodservice operations. Understanding how segments intersect reveals where procurement budgets concentrate and which configurations capture replacement demand.
Product Type:
Upgrade momentum varies sharply by how dispensers integrate with existing kitchen workflows and ventilation infrastructure.
- Portable Dispenser:Self-contained 115V units with integrated water reservoirs eliminate plumbing dependencies. Food trucks and event caterers in Chicago and Los Angeles specify these for rapid deployment where electrical access exists but permanent installation is impossible.
- Under-Counter Dispenser:Compact units with front-facing chutes reclaim counter surface while maintaining customer visibility. Bars and quick-service restaurants in high-rent urban corridors are standardizing on these configurations to maximize service area per square foot.
- Modular Dispenser:Dedicated dispenser heads paired with remote ice makers serve high-volume chains.
- Gravity Dispenser:Simple ice-drop mechanisms without powered augers suit low-throughput settings.
Volume placements concentrate in Under-Counter units; the faster expansion belongs to Portable configurations.
End User:
Procurement sophistication and replacement frequency separate institutional buyers from independent operators.
- Restaurants:Full-service and quick-service chains operate on 5-7 year refresh cycles mandated by corporate sustainability targets. The EPA's ENERGY STAR qualification now filters distributor catalogs before regional managers review specifications.
- Cafes:Boutique coffee chains prioritize compact footprints and antimicrobial surfaces. These operators accept 15-20% price premiums for UV-C LED sterilization and touchless interfaces that differentiate customer experience.
- Bars:High-volume beverage operations demand rapid ice recovery rates.
- Catering Services:Mobile and event-based foodservice drives demand for 115V flexibility.
Specification authority concentrates in chain Restaurants; Cafes are expanding their equipment budgets fastest.
Installation Type:
Building age and lease structure determine which mounting configurations are physically and economically viable.
- Freestanding:Castor-mounted units allow repositioning during service redesigns. Secondary market independents favor these where lease terms under five years discourage permanent modifications.
- Countertop:Traditional placement dominates existing installations. Replacement demand here is accelerating as pre-2020 units face refrigerant phase-down economics under the AIM Act.
- Wall-Mounted:Bracket-supported units free floor space entirely.
- Built-In:Custom cabinetry integration commands premium specification.
Current installed base skews Countertop; Wall-Mounted configurations are gaining specification share fastest.
Capacity:
Daily throughput requirements and peak demand patterns segment buyers across four distinct tiers.
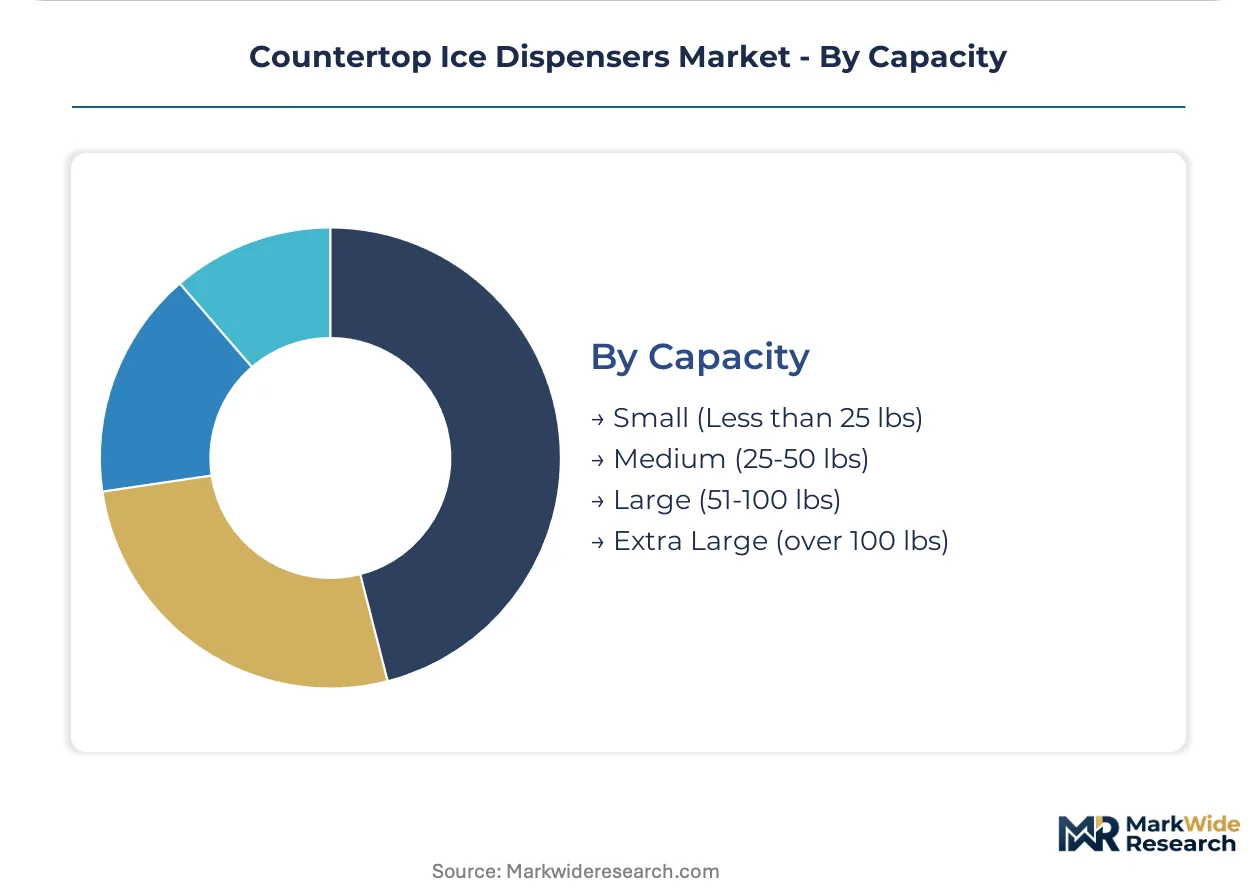
- Small (Less than 25 lbs):Compact units serve tasting rooms and micro-cafes with intermittent ice needs. These configurations prioritize energy efficiency over recovery speed to maintain ENERGY STAR qualification margins.
- Large (51-100 lbs):Mid-tier chains and independent restaurants with consistent lunch rushes specify this band. The segment balances capital cost against warranty coverage for compressor and filtration components.
- Medium (25-50 lbs):Boutique operators with moderate throughput dominate this tier.
- Extra Large (over 100 lbs):Stadium concessions and institutional foodservice require maximum output.
Procurement volume clusters in Large capacity; Small units are climbing the fastest as micro-format concepts multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago's high-traffic urban foodservice corridors concentrate replacement demand for ENERGY STAR-qualified countertop ice dispensers as quick-service chains refresh equipment on compressed 5-7 year cycles.
United States
Quick-service restaurant chains and boutique cafes drive specification authority across dense metropolitan markets. The EPA's ENERGY STAR Version 5.0 standards tighten daily energy consumption thresholds by 10-15% for compact commercial refrigeration. Los Angeles and New York foodservice operators prioritize under-counter configurations to reclaim premium counter space in high-rent districts.
Germany
Commercial kitchen equipment distributors emphasize modular dispenser heads paired with remote ice makers for high-volume institutional foodservice. The EU F-Gas Regulation accelerates hydrocarbon refrigerant transitions across installed bases. Bavaria's Munich-Stuttgart industrial corridor hosts precision stainless fabrication supplying premium-tier commercial refrigeration OEMs.
Japan
Compact countertop units serve micro-format cafes and convenience store chains with severe spatial constraints. METI energy efficiency labeling programs shape procurement specifications for commercial refrigeration equipment. Osaka's Kansai manufacturing belt produces antimicrobial bin liner technologies integrated into sanitary-focused dispenser designs.
United Kingdom
Independent restaurant operators and boutique hotel chains specify UV-C LED sterilization features at 15-20% price premiums. The UK's commercial refrigeration efficiency standards align with broader EU regulatory frameworks post-transition. London's dense urban foodservice corridors concentrate demand for space-efficient under-counter dispenser placements.
Australia
Mobile catering operators and event foodservice providers prioritize portable 115V dispenser configurations for rapid deployment flexibility. The country's national energy efficiency programs govern commercial refrigeration equipment procurement in institutional settings. Sydney and Melbourne's high-density hospitality districts drive replacement cycles for aging countertop installations.
Countertop Ice Dispensers Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a tiered market structure. The vendor base separates into integrated appliance conglomerates, specialized commercial refrigeration manufacturers, and regional fabrication specialists. Three archetypes dominate: ecosystem bundlers leveraging kitchen equipment portfolios, premium stainless-steel constructors anchoring extended service networks, and price-aggressive volume players sacrificing margin for placement. Competitive moves concentrate on ENERGY STAR qualification races and refrigerant transition readiness.
Among integrated appliance conglomerates, Whirlpool Corporation and GE Appliances represent ecosystem bundlers that leverage broader kitchen equipment portfolios to capture specification share. Hoshizaki Corporation occupies a position within the premium-tier commercial refrigeration archetype. Maxx Ice exemplifies the price-competitive volume strategy in mid-market independent restaurant channels.
| Leading Market Players |
|---|
| GE Appliances |
| Whirlpool Corporation |
| NewAir Appliances |
| Frigidaire |
| Igloo |
| Whynter LLC |
| Maxx Ice |
| Summit Appliance |
| Hoshizaki Corporation |
| Others |
Value Chain & Pricing Dynamics
304-grade stainless steel price volatility cascades through fabrication tiers, compressing margins on premium commercial units while forcing mid-market manufacturers toward plastic-body alternatives or reduced insulation densities. This commodity pressure reshapes how distributors structure tiered offerings across independent restaurant and chain procurement channels.
Pricing Analysis
ENERGY STAR qualification uptime anchors value-based pricing, with certified units commanding placement premiums in corporate sustainability-driven refresh cycles. Price differentiation separates NSF/UL dual-certified premium tiers from single-listed standard configurations and uncertified economy alternatives. Cost compression in the mid-market intensifies as Maxx Ice and similar volume players sacrifice margin for placement share. Independent restaurants in secondary markets exhibit highest price sensitivity, while boutique cafe chains accept 15-20% premiums for UV-C LED and touchless features.
Supply Chain Analysis
Domestic-content mandates in US federal procurement specifications are reshaping sourcing patterns for institutional foodservice channels. Manufacturing concentrates in China, Mexico, and the United States, with precision stainless fabrication anchored in Bavaria's industrial corridor. Compressor assemblies draw from Japanese and South Korean component specialists, while antimicrobial bin liner technologies feed from Osaka's Kansai manufacturing belt. Tariff exposure on Chinese-sourced refrigeration components creates single-source vulnerability for cost-optimized tier producers. Distribution runs through foodservice equipment distributors with bundled after-sales service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into compressor technology and refrigerant service networks is becoming the decisive competitive lever as the AIM Act phase-down reshapes installed-base economics. Players capturing upstream control over R-290 and CO₂ system deployment will dictate replacement cycle timing.
For Market Incumbents: Lock in extended service network coverage for hydrocarbon and transcritical CO₂ systems before technician scarcity hardens into structural constraint. Consolidate certification timelines by pre-qualifying insulation and compressor platforms across multiple ENERGY STAR revision cycles. The refrigerant transition threat demands backward integration into compressor technology or captive service partnerships.
For New Entrants and Emerging Players: Foodservice equipment leasing companies represent the most penetrable channel partner type for subscription-based maintenance models. Target mobile catering operators and event foodservice providers in the Southeast and Southwest where hard water conditions accelerate service call frequency. Penetrate through portable 115V configurations with bundled filtration replacement schedules.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional fabrication specialists with UL pre-certification and established distributor relationships in high-rent urban corridors. Long-term viability hinges on refrigerant transition readiness and ENERGY STAR Version 5.0 compliance positioning. Watch for compressor platform standardization announcements as the inflection signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | R-290 and CO₂ compressor adoption accelerates replacement demand across AIM Act-affected installed bases. |
| Service Network Expansion | Certified hydrocarbon technician training transfers compressor failure risk from operators to OEMs. |
| Subscription Maintenance Models | Per-dispenser monthly fees restructure independent restaurant procurement toward operational expenditure. |
| Antimicrobial Technology Integration | UV-C LED sterilization commands 15-20% price premiums in boutique hotel and healthcare channels. |
| Under-Counter Configuration Development | Space reclamation designs capture specification share in high-rent urban foodservice corridors. |
Study Parameters
Trade association filings, EPA ENERGY STAR certification databases, and customs import records formed the secondary backbone, cross-referenced against primary interviews with foodservice equipment distributors, commercial refrigeration OEM procurement directors, and NSF International certification engineers. Bottom-up and top-down triangulation validated shipment volumes and pricing tiers across portable, under-counter, and modular configurations.
Bottom-up modeling aggregated unit economics across capacity tiers and installation types, while top-down analysis tracked replacement cycle timing against regulatory milestone dates. Segmentation dimensions included product type, end-user category, installation configuration, and daily throughput capacity. CAGRs derived from equipment refresh cycle compression and refrigerant transition replacement economics. Forecast inputs incorporated ENERGY STAR Version 5.0 qualification timelines and AIM Act phase-down schedules.
Caveats apply where refrigerant technician training scale, stainless steel commodity spikes, or electrical infrastructure upgrade delays could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Ice Maker Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Autonomous One-Pot Cooking System Market
Food Service Equipment
Mobile Food Warmer Market
Food Service Equipment
Restaurant Equipment Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
Reach-In Refrigerators Market
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market