
 Beer Glass Chillers Market | 2026-2036
Beer Glass Chillers Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Glass Chillers Market Outlook
The gap between premium and commodity tiers is restructuring the competitive landscape for beer glass chillers. Thrill International leverages thermoelectric miniaturization to dominate high-end bar installations. Krowne anchors its position through stainless steel fabrication scale and North American channel control. Beverage Air competes on refrigeration reliability across mid-market restaurant chains.
Beer glass chillers are electromechanical or passive devices engineered to reduce serving vessel temperature to 0-4°C prior to pour, utilizing thermoelectric modules, compressor-based refrigeration, or conductive gel sleeves to eliminate surface condensation and preserve carbonation. Electric chillers with thermoelectric cores occupy the fastest-expanding margin pool as operators replace ice baths with precision-controlled units. Stainless steel construction leads material preference in commercial settings for durability compliance, while silicone sleeves gain traction in portable and home-use segments.
The FDA Food Code and NSF International standards govern commercial chiller sanitation and electrical safety in US foodservice environments, pushing manufacturers toward sealed-component designs. The EU F-Gas Regulation restricts refrigerant selections for compressor-based units sold in Europe, redirecting R&D toward hydrocarbon alternatives. Stakeholders must monitor evolving energy-efficiency thresholds and refrigerant phase-down schedules to anticipate compliance-driven product transitions.
Market Dynamics
Thermoelectric miniaturization is compressing equipment footprints while FDA Food Code updates on temperature control are mandating precision specifications that legacy ice baths cannot satisfy.
Growth Catalysts
- Craft brewery taproom expansion:United States craft breweries are installing rapid-cooling systems to differentiate pour quality and reduce operational ice dependency.
- EU F-Gas Regulation phase-down:Hydrocarbon refrigerant R&D is accelerating as compressor-based unit manufacturers redesign for compliance.
- Bavaria's beer culture premiumization:German hospitality operators are specifying stainless steel chiller installations to meet elevated consumer temperature expectations.
Market Restraints
- Copper and nickel price volatility:Thermoelectric module production faces input cost pressure from semiconductor metal commodity swings.
- Compressor refrigerant supply concentration:Hydrocarbon alternative sourcing clusters with limited European chemical processors.
- NSF certification timeline friction:Sealed-component validation for commercial foodservice creates 8-14 month market entry delays.
Strategic Opportunities
- India untapped hospitality infrastructure:Premium hotel and microbrewery buildouts lack chiller penetration versus Western benchmarks.
- Silicone sleeve portable segment:Home entertainer and outdoor event applications represent unaddressed demand outside commercial channels.
- Energy-efficiency incentive alignment:United States IRA commercial equipment deductions favor thermoelectric over compressor-based installations.
Industry Challenges
- Thermoelectric engineering talent scarcity:Peltier module design and thermal interface optimization skills concentrate with semiconductor industry employers.
- Legacy refrigeration technician retraining:Hydrocarbon refrigerant handling certification requirements are compressing qualified service network availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Glass Chillers Market |
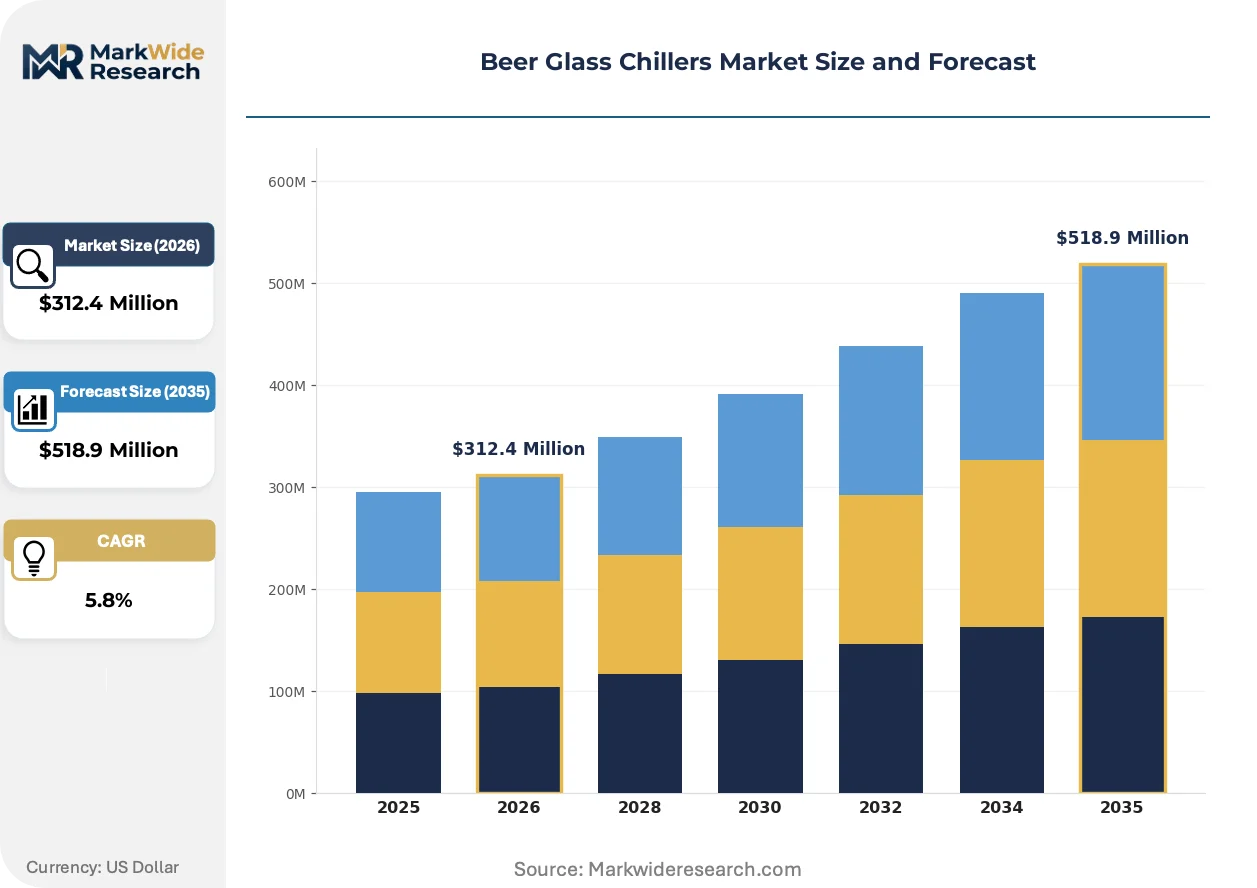
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Chillers, Ice Bucket Chillers, Refrigerated Glassware, Portable Chillers Material: Glass, Stainless Steel, Plastic, Silicone End User: Restaurants, Pubs, Home Use, Events Technology: Thermoelectric, Induction, Refrigeration, Passive Cooling |
| Companies Covered | Thrill International, Krowne, Beverage Air, TRUE, Williams, Vinotemp, Frucosol, SPEEDX, Frostte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Glass Chillers Market Strategic Shifts
Equipment intelligence and material substitution are converging to redefine performance benchmarks and compliance architecture across commercial and portable segments.
Thermoelectric cooling modules with solid-state Peltier cores are automating temperature precision previously requiring active compressor cycling. Craft brewery taprooms in the United States are adopting these units at accelerated pace to eliminate ice logistics. The technology is automating labor out of front-of-house beverage service while compressing equipment maintenance intervals.
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants are forcing compressor-based manufacturers toward hydrocarbon and CO₂ alternatives. This regulatory pressure is fragmenting product portfolios between sealed thermoelectric units and redesigned refrigeration architectures. German and Italian commercial kitchen equipment distributors report elongated procurement cycles as buyers evaluate compliance longevity.
After-sales service unbundling is emerging as craft brewery operators separate equipment purchase from maintenance contracts. Independent service technicians using mobile diagnostic tools are displacing manufacturer-authorized networks in North American metropolitan markets. This pattern is most visible in Denver and Portland taproom clusters where equipment density supports third-party specialization.
Beer Glass Chillers Market Segmentation
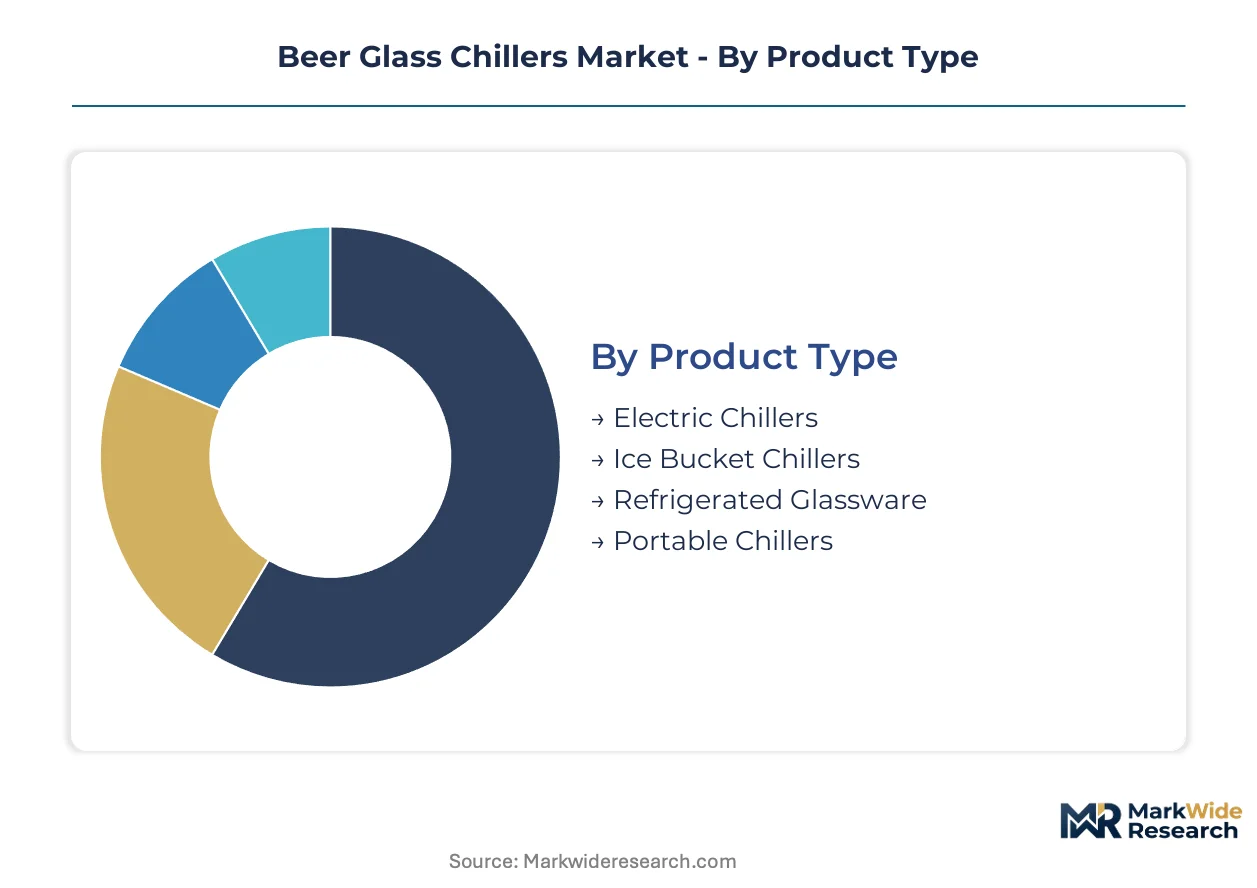
Equipment specification varies sharply across deployment contexts. Commercial operators prioritize sanitation compliance and throughput, while residential buyers trade precision for portability and price accessibility.
Product Type:
Cost tier separates precision-controlled installations from passive alternatives.
- Electric Chillers:Solid-state Peltier modules deliver 0-4°C precision without compressor maintenance. United States craft brewery taprooms are replacing ice baths with these units to satisfy FDA Food Code temperature documentation requirements.
- Ice Bucket Chillers:Passive conductive cooling through ice-water immersion remains prevalent in budget-constrained operations. Bavarian beer gardens specify these for outdoor service where electrical infrastructure is limited.
- Refrigerated Glassware:Compressor-based cabinet systems store pre-chilled glass inventory. These units face EU F-Gas Regulation redesign pressure as hydrocarbon refrigerant transitions elongate procurement cycles.
- Portable Chillers:Battery-powered or gel-pack units target mobile catering and outdoor events. The segment lacks penetration versus Western benchmarks in Indian hospitality infrastructure buildouts.
Volume sits with Ice Bucket Chillers; growth tilts toward Electric Chillers.
Material:
Application context dictates durability-versus-weight tradeoffs.
- Stainless Steel:NSF-certified fabrication dominates commercial foodservice for corrosion resistance and thermal conductivity. German hospitality operators specify these for premium chiller installations aligned with elevated consumer temperature expectations.
- Glass:Aesthetic transparency suits front-of-house display applications. The material's fragility restricts deployment in high-volume bar environments.
- Silicone:Flexible sleeves enable portable home entertainer applications outside commercial channels. The material gains traction in outdoor event segments where weight reduction is prioritized.
- Plastic:Polymer construction serves economy-tier residential and disposable event markets. Thermal performance lags metallic alternatives.
Commercial revenue concentrates in Stainless Steel; Silicone climbs fastest in residential expansion.
End User:
Customer type determines compliance burden and purchase frequency.
- Restaurants:Full-service operators require sealed-component designs satisfying NSF International validation timelines. These buyers separate equipment purchase from maintenance contracts in North American metropolitan markets.
- Pubs:High-throughput establishments prioritize rapid-cooling throughput over precision. Denver and Portland taproom clusters support third-party service technician specialization.
- Home Use:Residential buyers favor countertop footprint and noise reduction. The segment shows unaddressed demand for silicone sleeve portable formats.
- Events:Mobile catering operators value battery autonomy and rapid deployment. Indian premium hotel buildouts lack chiller penetration versus Western benchmarks.
Installed base favors Restaurants; Events demonstrates steepest expansion trajectory.
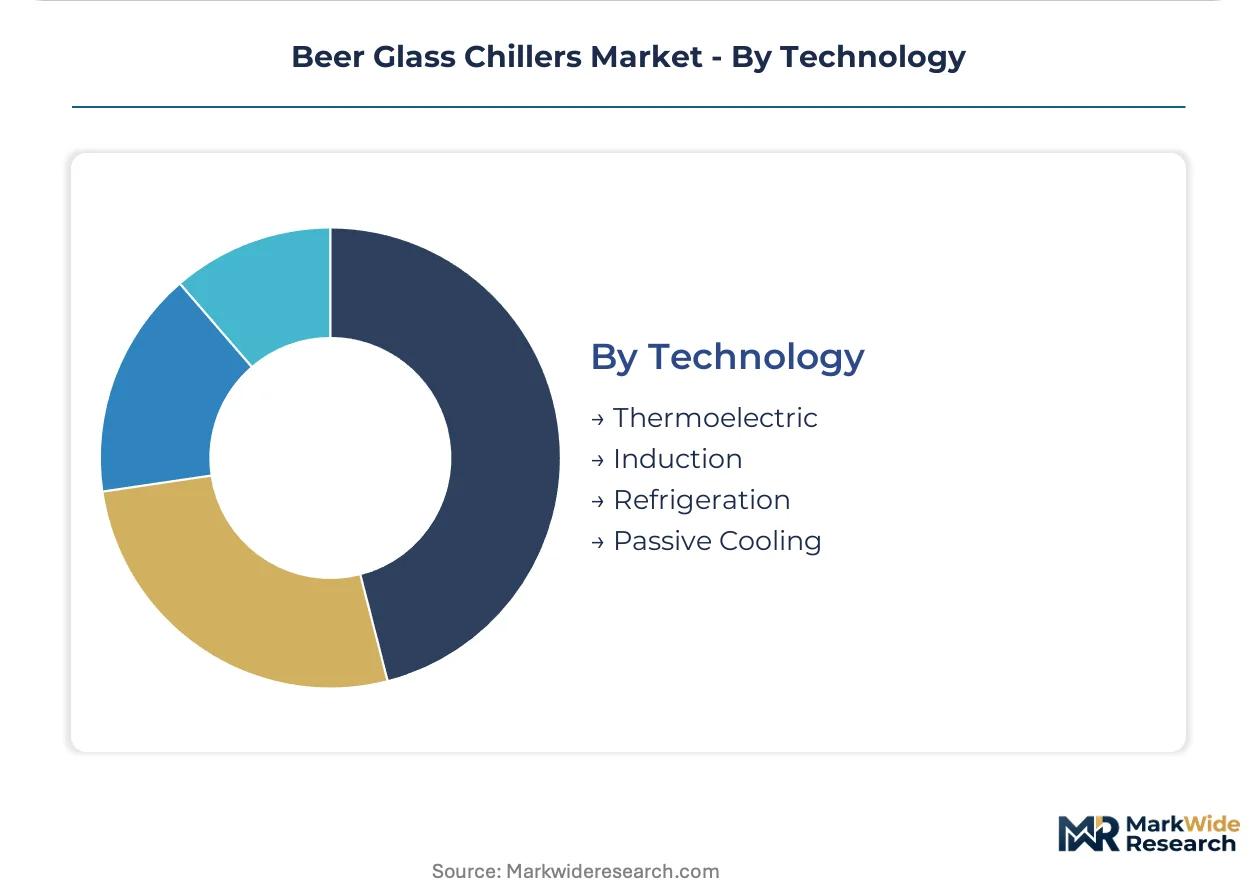
Technology:
Maturity gradient separates solid-state innovation from legacy refrigeration.
- Thermoelectric:Peltier module precision eliminates compressor maintenance and refrigerant compliance. United States IRA commercial equipment deductions favor these installations over compressor-based alternatives.
- Refrigeration:Vapor-compression systems face EU F-Gas Regulation phase-down pressure. Hydrocarbon alternative sourcing clusters with limited European chemical processors.
- Induction:Electromagnetic cooling remains nascent with concentrated engineering talent scarcity. Peltier module design skills concentrate with semiconductor industry employers.
- Passive Cooling:Gel sleeve and ice-based methods require no electrical infrastructure. These systems cannot satisfy FDA Food Code precision documentation requirements.
Refrigeration retains volume leadership; Thermoelectric gains share fastest on regulatory alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denver and Portland taproom clusters anchor North American craft brewery chiller density, with equipment specialization supporting third-party service technician networks that displace manufacturer-authorized maintenance contracts.
United States
Craft brewery taprooms in Colorado and Oregon drive rapid-cooling system installations to eliminate ice logistics and satisfy FDA Food Code temperature documentation requirements. The Inflation Reduction Act commercial equipment deductions favor thermoelectric installations over compressor-based alternatives. Denver metropolitan operators separate equipment purchase from maintenance contracts, enabling independent technician specialization.
Germany
Bavarian beer gardens and hospitality operators specify stainless steel chiller installations to meet elevated consumer temperature expectations in Munich and regional brewing centers. The EU F-Gas Regulation restricts hydrofluorocarbon refrigerants for compressor-based units, redirecting procurement toward thermoelectric alternatives. German commercial kitchen equipment distributors report elongated procurement cycles as buyers evaluate compliance longevity.
India
Premium hotel and microbrewery buildouts in Mumbai and Bangalore lack chiller penetration versus Western benchmarks, representing infrastructure gaps for portable and electric formats. The country's national food safety regulator mandates temperature control standards that precision equipment satisfies. Maharashtra and Karnataka hospitality clusters show accelerating specification of sealed-component designs for new construction.
United Kingdom
London and Manchester pub operators balance rapid-cooling throughput demands against energy-efficiency compliance thresholds. CE marking and post-Brexit UKCA certification requirements extend validation timelines for sealed-component commercial units. Southeast England distribution channels concentrate mid-market restaurant chain procurement.
Japan
Tokyo and Osaka hospitality venues prioritize countertop footprint reduction and noise attenuation in high-density commercial districts. METI energy-efficiency standards compress equipment specification windows for imported units. Kanto region hotel buildouts specify thermoelectric precision for premium service differentiation.
Beer Glass Chillers Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology sophistication and material specification tiers. The vendor base organizes around three strategic archetypes: thermoelectric miniaturization specialists, stainless steel fabrication scale operators, and refrigeration reliability incumbents. Consolidation pressure concentrates among mid-market compressor-based manufacturers facing EU F-Gas redesign costs. Dominant competitive moves include hydrocarbon refrigerant R&D acceleration and after-sales service unbundling to capture recurring revenue streams.
Within the thermoelectric specialization tier, Thrill International exemplifies premium-position engineering focused on solid-state precision. Krowne anchors North American channel control through fabrication scale and stainless steel supply chain proximity. Beverage Air occupies the mid-market reliability position across restaurant chain installations. These three companies represent distinct competitive vectors—technology leadership, manufacturing scale, and service network density—that structure rivalry across price-performance segments.
| Leading Market Players |
|---|
| Thrill International |
| Krowne |
| Beverage Air |
| TRUE |
| Williams |
| Vinotemp |
| Frucosol |
| SPEEDX |
| Frostte |
| Others |
Value Chain & Pricing Dynamics
Thermoelectric module copper and nickel feedstock traverses semiconductor-grade refinement in Japan and South Korea before reaching Peltier assembly houses, with purity premiums separating precision-controlled chiller tiers from commodity compressor alternatives downstream.
Pricing Analysis
Throughput-based pricing anchors commercial installations, where rapid-cooling capacity per hour determines contract value more than unit manufacturing cost. Three-tier pricing structure across premium thermoelectric, standard compressor, and economy ice-bucket levels separates NSF-certified sealed designs from open-basin alternatives. Pricing pressure stems from EU F-Gas Regulation compliance costs compressing margins on hydrocarbon redesigns. Restaurant chains exhibit highest price sensitivity due to volume procurement leverage, while craft brewery taprooms prioritize precision documentation over per-unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing for thermoelectric semiconductor substrates, constraining Peltier module availability during export quota fluctuations. Manufacturing concentrates in Germany, Italy, and the United States for stainless steel fabrication and final assembly. Raw material dependencies span nickel-bismuth-telluride thermoelectric compounds, hydrocarbon refrigerant alternatives, and NSF-certified silicone gaskets. Supply chain risk centers on regulatory restriction as EU F-Gas phase-downs elongate compressor-based procurement cycles. Distribution runs through commercial kitchen equipment distributors and direct craft brewery relationships in North American metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
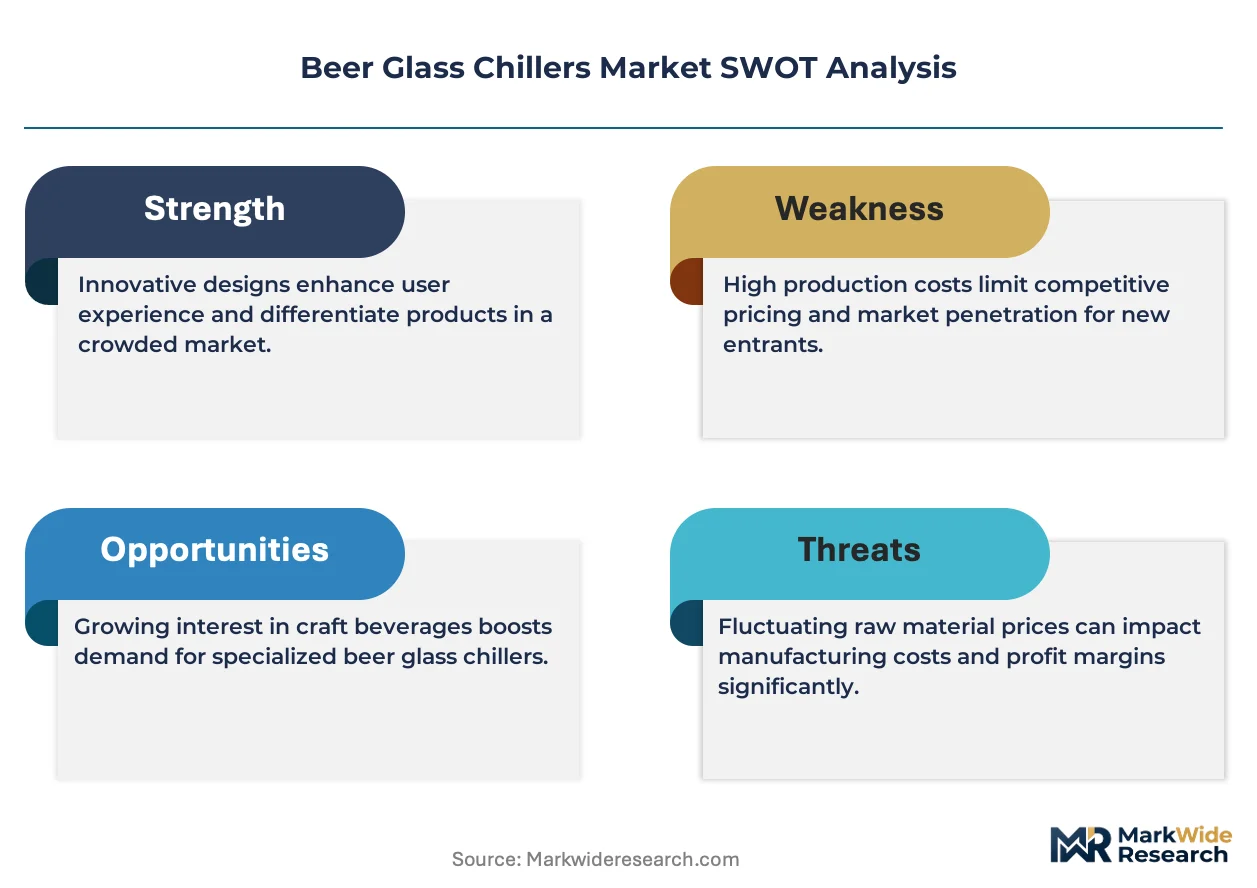
The beer glass chillers market is consolidating as EU F-Gas redesign costs force weaker compressor-based manufacturers toward exit or acquisition, compressing the competitive field around thermoelectric specialists and stainless steel fabricators with compliance-ready portfolios.
For Market Incumbents: Hedge refrigerant technology exposure by accelerating hydrocarbon R&D partnerships with European chemical processors while securing thermoelectric module supply agreements with Japanese semiconductor houses. Defend channel position in Denver and Portland taproom clusters through embedded service technician networks that displace third-party maintenance unbundling. Prioritize NSF certification pipeline investment to compress 8-14 month validation timelines.
For New Entrants and Emerging Players: Capture India's untapped premium hotel and microbrewery infrastructure in Mumbai and Bangalore where chiller penetration lags Western benchmarks. Target silicone sleeve portable formats for home entertainer segments outside commercial channels. Enter through FSSAI-compliant sealed-component designs that satisfy Maharashtra and Karnataka hospitality cluster specifications for new construction.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-market compressor manufacturers facing EU F-Gas transition costs in Italy and Germany. Long-term viability hinges on thermoelectric patent portfolios and stainless steel fabrication scale rather than refrigerant-dependent architectures. Watch hydrocarbon refrigerant approval velocity at ECHA as the inflection signal for compressor-based asset viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocarbon Refrigerant R&D Partnership | ECHA approval timelines determine compressor-based product survival in European markets. |
| Thermoelectric Module Supply Agreement | Japanese semiconductor house relationships secure Peltier core availability against rare earth quota volatility. |
| Embedded Service Technician Network | Denver and Portland taproom density supports third-party specialization displacing manufacturer-authorized maintenance. |
| Silicone Sleeve Portable Format Launch | Home entertainer segments outside commercial channels represent unaddressed demand in Western and Indian markets. |
| FSSAI Sealed-Component Certification | Maharashtra and Karnataka hospitality clusters specify precision temperature control for new premium hotel construction. |
Study Parameters
Independent corroboration across equipment distributor procurement managers, craft brewery operations directors, and commercial kitchen design consultants underwrites the qualitative findings. Primary fieldwork captured specification patterns at Denver, Portland, Munich, and Mumbai hospitality clusters. Secondary validation drew from FDA Food Code documentation, EU F-Gas Regulation filings, FSSAI technical standards, and NSF International certification databases. Bottom-up unit shipment analysis triangulated against top-down hospitality construction spend across the analysis window.
Rate-of-change decomposition separated volume growth from price-mix effects across product type, material grade, end-user segment, and technology architecture dimensions. CAGR derivation applied logistic diffusion curves to thermoelectric adoption patterns and replacement-cycle modeling to compressor-based installed base turnover. Industry-specific inputs included craft brewery taproom expansion permits, EU refrigerant phase-down schedules, and Indian premium hotel pipeline tracking.
The model holds under stable regulatory enforcement timelines and commodity input availability; deviation in rare earth export restrictions or accelerated F-Gas phase-downs would shift competitive positioning toward solid-state alternatives. Forecasts reflect documented assumptions on adoption curve steepness and replacement elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Commercial Wine Dispenser Market
Alcoholic Beverages
Spirits Miniatures Market
Alcoholic Beverages
Home Brewing Systems Market
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Global Distillation System Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Japan Beer Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Mexico Alcohol E-Commerce Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Cocktail Market
Alcoholic Beverages
Chardonnay Market
Alcoholic Beverages
Canada Alcohol E-Commerce Market
Alcoholic Beverages
India Tequila Market
Alcoholic Beverages
Russia Tequila Market